
 Smart Airport Construction Market | 2026-2036
Smart Airport Construction Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Airport Construction Market Analysis
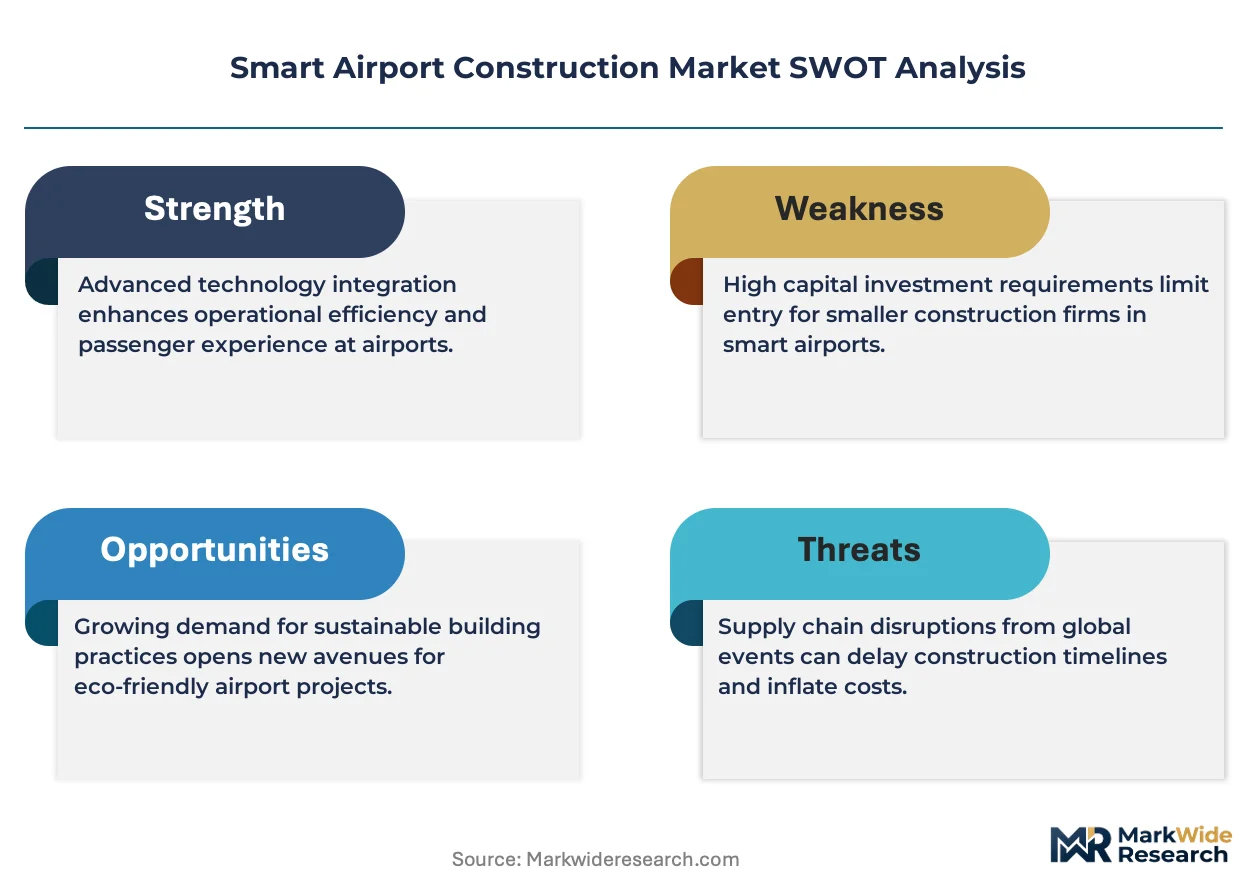
Project finance through availability-based concessions is reshaping competitive entry in smart airport construction, allowing technology integrators without heavy balance sheets to bid for long-term service contracts. Siemens AG leverages its digital building twin platforms to anchor large-scale terminal automation programs across multiple continents. Honeywell International Inc. competes through vertical control over fire safety, security, and energy management subsystems. Thales Group differentiates via biometric passenger flow and integrated command center solutions that reduce terminal congestion.
Smart airport construction encompasses the design, engineering, and build-out of passenger terminals, airside facilities, and ground infrastructure embedded with sensor networks, building automation protocols, and real-time data orchestration layers operating at latencies below 100 milliseconds for critical safety systems. The primary purpose is to synchronize aircraft turnaround, baggage handling, security screening, and retail operations through a unified digital backbone that reduces passenger processing time and energy intensity per enplanement. Terminal Development applications currently occupy the largest share of capital deployment as aging hubs in Europe and North America face capacity constraints. IoT Sensors and Energy Management technologies are recording the fastest expansion as airports pursue net-zero operational targets under tightening environmental compliance. Automated Systems retain premium margin pools due to the scarcity of integrators capable of certifying multi-vendor robotic baggage and autonomous ground vehicle fleets.
FAA certification requirements for airport surface detection systems, EU Green Deal building performance standards enforced through ECHA-linked procurement rules, and Saudi GACA smart airport mandates collectively determine which technology packages qualify for public funding or green bond issuance. Regulators in the US and Europe are converging on cybersecurity hardening of operational technology networks, creating new compliance costs for contractors lacking aviation-specific IT security credentials. Stakeholders must decide whether to build captive integration capabilities or partner with established aviation IT specialists as contract scopes shift from discrete construction to decade-long performance-based facility management.
Market Dynamics
Availability-based concession financing is restructuring competitive entry, allowing technology integrators without heavy balance sheets to capture long-term service contracts previously reserved for traditional construction conglomerates.
Growth Catalysts
- EU Green Deal building mandates:The EU Green Deal and F-Gas Regulation are compelling retrofits of legacy HVAC and lighting infrastructure across European hubs, creating sustained capital deployment in energy-efficient terminal systems.
- Saudi gigaproject acceleration:NEOM and Red Sea Airport developments are establishing new benchmarks for autonomous passenger processing and sustainable construction methods, concentrating demand in the Kingdom.
- Biometric passenger flow systems:Integrated command center solutions that reduce terminal congestion are gaining priority procurement status as capacity constraints intensify at aging North American and European hubs.
Market Restraints
- Aviation-specific IT security credential scarcity:Regulators in the US and Europe are converging on cybersecurity hardening of operational technology networks, creating new compliance barriers for contractors lacking specialized certifications.
- Multi-vendor robotic fleet integration bottlenecks:The scarcity of integrators capable of certifying autonomous baggage and ground vehicle fleets is constraining deployment timelines and inflating premium margins.
- Legacy system interoperability debt:Aging terminal infrastructure in Europe and North America requires expensive middleware layers to connect with modern sensor networks and building automation protocols.
Strategic Opportunities
- Net-zero operational targeting:IoT Sensors and Energy Management technologies are recording accelerated expansion as airports pursue decarbonization under tightening environmental compliance frameworks.
- Digital building twin convergence:The intersection of real-time data orchestration layers with predictive maintenance algorithms is opening decade-long performance-based facility management contracts.
- Middle East integrated terminal system adoption:Airport operators across the Gulf are accelerating procurement of fully unified digital backbones that synchronize aircraft turnaround, baggage handling, and security screening.
Industry Challenges
- Sub-100-millisecond latency engineering:Critical safety systems require specialized network architecture expertise that sits outside traditional construction contractor capabilities.
- FAA surface detection certification timelines:Extended approval cycles for airport surface detection systems are compressing project delivery windows and inflating working capital requirements.
- Cross-vendor robotic fleet harmonization:Integrating autonomous ground vehicles from multiple suppliers into unified command structures demands scarce systems engineering talent.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Airport Construction Market |
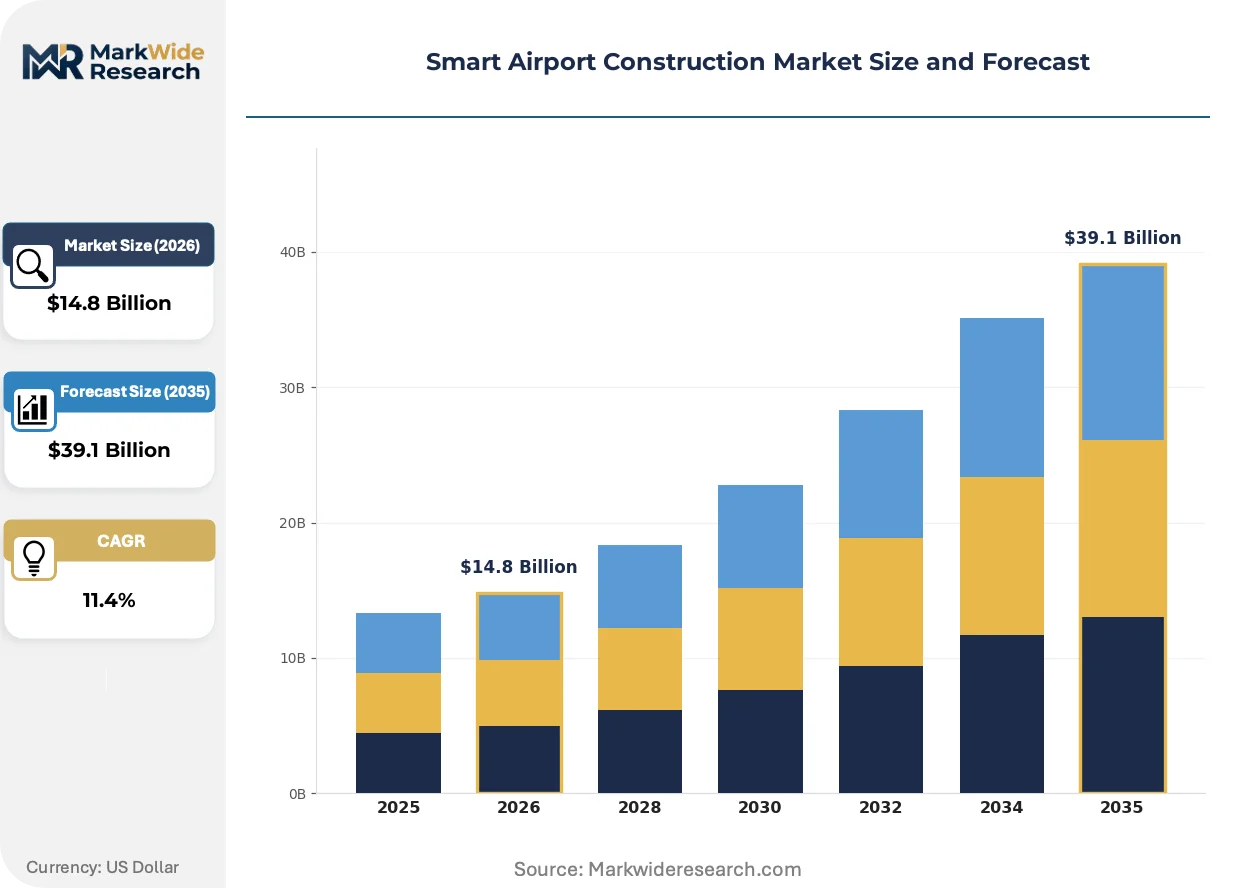
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.1 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Smart Lighting, IoT Sensors, Automated Systems, Energy Management End User: Aeronautical Authorities, Construction Firms, Airport Operators, Tech Integrators Application: Terminal Development, Runway Expansion, Parking Solutions, Security Enhancements Service Type: Consulting, Project Management, Design, Implementation |
| Companies Covered | Honeywell International Inc., Siemens AG, Thales Group, Cisco Systems, Inc., SITA, IBM Corporation, Amadeus IT Group, Raytheon Technologies Corporation, Collins Aerospace, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Airport Construction Market Emerging Trajectories
Digital twin architectures are replacing static building information models as the foundational layer for terminal automation, enabling predictive rather than reactive facility management across new and retrofit projects.
Edge computing nodes deployed throughout passenger terminals and airside facilities are rendering obsolete centralized server-room architectures that cannot meet sub-100-millisecond latency requirements for collision avoidance and emergency response systems. Airport operators in Saudi Arabia and the UAE are deploying these architectures at scale in greenfield developments. The shift is compressing vendor qualification criteria around real-time data processing capabilities rather than traditional mechanical and electrical contracting experience.
The EU F-Gas Regulation is banning refrigerants with high global warming potential from new airport HVAC installations, forcing equipment suppliers to accelerate heat pump and natural refrigerant system development. Contractors must now certify installation teams on ammonia and CO2-based systems previously rare in commercial aviation settings. German and French hub retrofits are experiencing the most acute compliance pressure, with procurement rules linked to ECHA enforcement mechanisms disqualifying conventional equipment packages.
Buyers are unbundling construction and decade-long performance obligations into separate contract lots, allowing technology integrators to compete for operational service layers without carrying heavy construction balance sheet requirements. This fragmentation is displacing traditional design-build-operate consortiums at major Middle Eastern and Asian hub expansions. Saudi GACA smart airport mandates explicitly favor this procurement structure, creating entry pathways for software and automation specialists previously excluded from capital-intensive terminal development.
Smart Airport Construction Market Segmentation
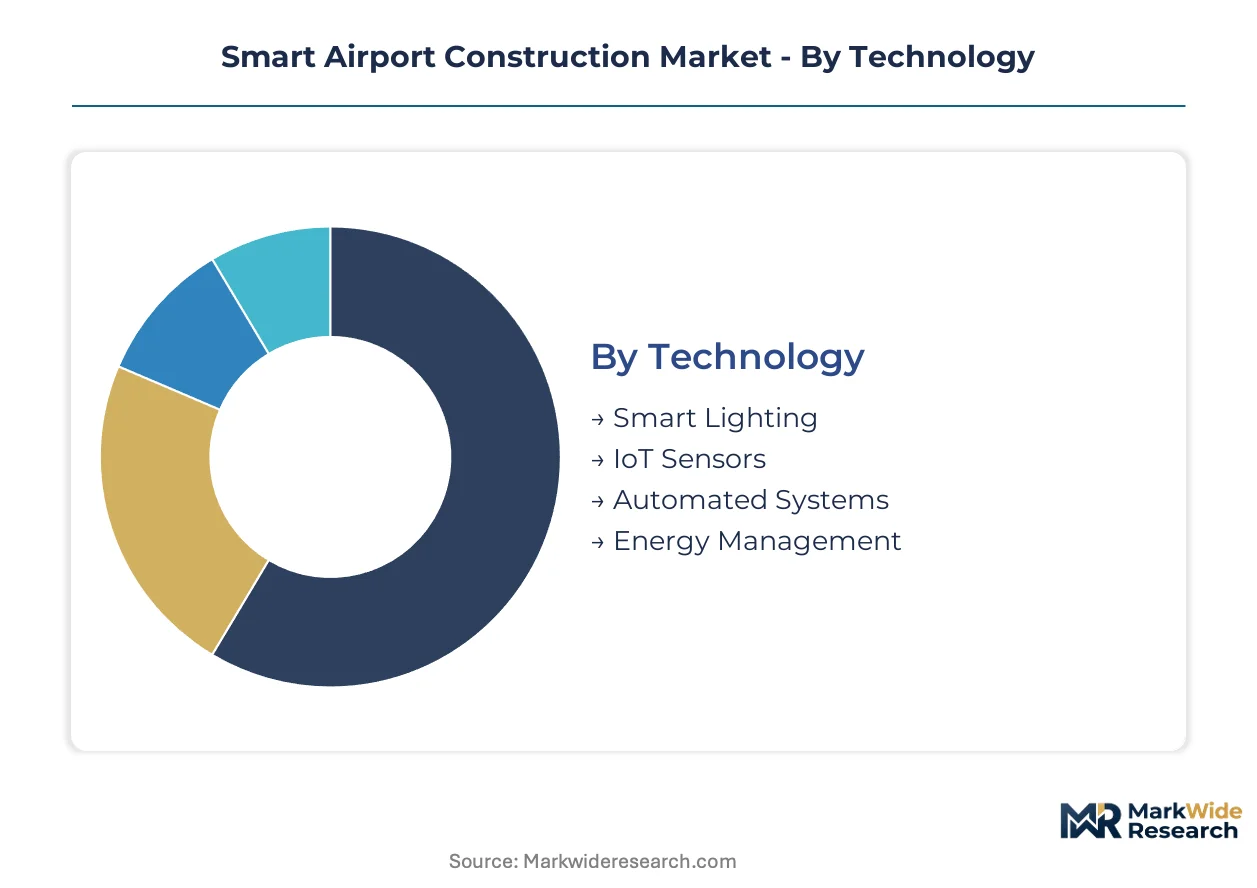
Smart airport construction demands precise segmentation to align capital deployment with regulatory mandates and operational technology requirements. Each dimension—technology, end user, application, and service type—shapes procurement structures and margin pools differently across greenfield and retrofit contexts.
Technology:
Technology selection determines latency performance, certification complexity, and long-term service revenue potential in terminal automation.
- IoT Sensors:Networks of environmental, occupancy, and asset-tracking devices feed real-time data orchestration layers. Saudi GACA mandates and EU Green Deal compliance are accelerating deployment in energy monitoring and predictive maintenance applications across new Middle Eastern hubs.
- Automated Systems:Robotic baggage handling, autonomous ground vehicles, and self-service passenger processing equipment require multi-vendor integration expertise. Scarcity of certified integrators sustains premium margins as airports in the UAE and Saudi Arabia scale greenfield autonomous fleets.
- Smart Lighting:LED arrays with daylight harvesting and occupancy-based dimming reduce terminal energy intensity. German and French hub retrofits prioritize these systems under ECHA-linked procurement rules.
- Energy Management:Building automation protocols coordinating HVAC, lighting, and on-site generation optimize consumption per enplanement. Heat pump and natural refrigerant configurations are displacing conventional systems under F-Gas Regulation deadlines.
Automated Systems command the established base. The steepest expansion runs through IoT Sensors.
End User:
End user type shapes contract scope, financing structure, and technology integration risk allocation.
- Airport Operators:Terminal owners procurement decade-long performance-based facility management contracts unbundled from construction. Saudi and UAE operators are accelerating adoption of fully integrated terminal systems with unified digital backbones.
- Tech Integrators:Software and automation specialists capture operational service layers through availability-based concessions without heavy construction balance sheets. FAA and EU cybersecurity hardening requirements favor established aviation IT credentials.
- Aeronautical Authorities:National regulators specify certification requirements for surface detection systems and operational technology network security. Extended approval cycles compress project delivery windows.
- Construction Firms:Traditional contractors face displacement as procurement fragments into separate construction and performance obligation lots. Middleware expertise for legacy system interoperability is becoming a defensive capability.
Airport Operators command the established base. Tech Integrators are climbing the fastest.
Application:
Application focus determines capital intensity, regulatory exposure, and passenger throughput optimization potential.
- Terminal Development:New-build and expansion projects embed sensor networks and building automation from foundation. Aging hubs in Germany, France, and the UK face capacity constraints driving retrofit demand.
- Security Enhancements:Biometric passenger flow systems and integrated command centers reduce congestion. FAA certification requirements for surface detection systems apply to adjacent airside security layers.
- Runway Expansion:Airside construction incorporates edge computing nodes for collision avoidance systems requiring sub-100-millisecond latency. Greenfield developments in Saudi Arabia deploy these architectures at scale.
- Parking Solutions:Automated guidance, EV charging infrastructure, and dynamic pricing systems extend terminal digital backbones to ground access. Integration with public transit smart payment networks is emerging.
Terminal Development commands the established base. Security Enhancements show the steepest expansion trajectory.
Service Type:
Service type segmentation reveals where value capture is shifting from discrete deliverables to continuous performance accountability.
- Implementation:Physical deployment of sensor networks, automation hardware, and digital infrastructure. Saudi GACA smart airport mandates explicitly favor procurement structures separating implementation from decade-long operations.
- Project Management:Coordination of multi-vendor robotic fleet harmonization and cross-disciplinary certification timelines. Working capital requirements inflate due to extended FAA approval cycles.
- Design:Digital twin architectures replacing static building information models as foundational layers. Predictive maintenance algorithms embedded from schematic stages.
- Consulting:Advisory on regulatory compliance including EU F-Gas Regulation, ECHA enforcement mechanisms, and cybersecurity hardening standards. Aviation-specific IT security credential scarcity creates bottleneck.
Implementation commands the established base. Project Management is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU Green Deal building performance standards and Saudi GACA smart airport mandates are redistributing capital deployment toward retrofit hubs in Western Europe and greenfield gigaprojects in the Gulf. National procurement rules now tie public funding eligibility to specific technology certification and decarbonization benchmarks.
United States
Aging terminal infrastructure at Hartsfield-Jackson Atlanta and Chicago O'Hare drives capacity-constrained retrofit demand. FAA certification requirements for airport surface detection systems compress project delivery timelines. Dallas-Fort Worth anchors autonomous ground vehicle pilot programs integrating multi-vendor robotic fleets.
Germany
Frankfurt and Munich hubs face acute ECHA-linked procurement pressure to retrofit legacy HVAC systems under F-Gas Regulation deadlines. Heat pump and natural refrigerant configurations displace conventional equipment packages. Berlin-Brandenburg serves as testbed for digital building twin architectures replacing static information models.
France
Charles de Gaulle and Orly airports prioritize biometric passenger flow systems to reduce terminal congestion. EU cybersecurity hardening standards for operational technology networks create compliance barriers for non-specialist contractors. Paris-Saclay cluster concentrates systems engineering talent for sub-100-millisecond latency safety networks.
Saudi Arabia
NEOM and Red Sea Airport developments establish benchmarks for autonomous passenger processing and sustainable construction. Saudi GACA mandates explicitly favor procurement structures separating implementation from decade-long performance obligations. Riyadh anchors integrated terminal system adoption with unified digital backbones.
United Arab Emirates
Dubai International and Abu Dhabi Zayed International accelerate edge computing node deployment for collision avoidance systems. Availability-based concession financing allows technology integrators to capture operational service layers without heavy construction balance sheets. Dubai South cluster concentrates predictive maintenance algorithm development.
Smart Airport Construction Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented procurement structures. Large-scale terminal automation programs favor integrators with digital building twin platforms and aviation-specific IT security credentials. Three archetypes dominate: diversified industrial conglomerates with building automation portfolios, aviation IT specialists with biometric and command center expertise, and network infrastructure providers with edge computing capabilities. Competitive moves center on decade-long performance-based facility management contracts and multi-vendor robotic fleet certification partnerships.
Within the diversified industrial tier, Honeywell International Inc. and Siemens AG exemplify channel-controlling positions anchored by vertical control over fire safety, security, and energy management subsystems. Thales Group occupies a specialist position representing biometric passenger flow and integrated command center capabilities. These three entities illustrate how procurement fragmentation into separate construction and performance obligation lots creates divergent pathways for market participation.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| Thales Group |
| Cisco Systems, Inc. |
| SITA |
| IBM Corporation |
| Amadeus IT Group |
| Raytheon Technologies Corporation |
| Collins Aerospace |
| Others |
Supply Flow & Price Mechanics
Dubai South's concentration of predictive maintenance algorithm developers compresses vendor margins for standardized sensor deployments while amplifying pricing power for integrators holding FAA cybersecurity credentials. Saudi GACA procurement rules separating implementation from decade-long performance obligations redistribute margin capture toward operational service layers.
Pricing Analysis
Certification level (FAA-grade cybersecurity credentials) creates the primary spread between premium integrators and commodity hardware suppliers. Project-based pricing dominates terminal automation contracts, though availability-based concessions are gaining share in Middle Eastern greenfield developments. Price differentiation rests on vertical control over fire safety subsystems and multi-vendor robotic fleet certification. Cost compression in standardized IoT sensor networks is intensifying because Saudi and UAE operators are unbundling procurement lots. Airport operators with captive technical teams exhibit lowest price sensitivity; traditional construction firms facing displacement show highest.
Supply Chain Analysis
Extended payment terms from Saudi sovereign wealth-backed gigaprojects strain working capital for European HVAC equipment suppliers. Component manufacturing concentrates in Germany, China, and South Korea. Supply chains draw from rare earth elements for sensor networks, advanced composites for airside infrastructure, and specialized refrigerants for F-Gas-compliant heat pump systems. Single-source vulnerability around FAA-certified cybersecurity modules poses structural risk. Distribution runs through EPC contractors with aviation authority relationships rather than open vendor markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement fragmentation across construction and operational service layers creates multiple entry points for specialists lacking traditional balance sheet scale. Unbundling of decade-long performance obligations from capital-intensive terminal build-outs generates niche capture opportunities.
For Market Incumbents: Entrench position through captive integration of biometric passenger flow systems with building automation protocols. Acquire middleware expertise for legacy system interoperability as defensive capability against tech integrators. Prioritize FAA cybersecurity credential maintenance as regulatory barriers tighten. For New Entrants and Emerging Players: Pursue white-space in European retrofit HVAC compliance under F-Gas Regulation deadlines where incumbent construction firms lack natural refrigerant certification. Target German and French hub energy management upgrades as most penetrable segment. Lead with digital building twin platforms rather than mechanical contracting credentials. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors aviation IT specialists with biometric command center capabilities over diversified industrial conglomerates. Five-to-ten year viability hinges on recurring revenue from performance-based facility management contracts. Watch for Saudi GACA mandate expansion beyond gigaprojects to existing hub retrofits as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Vendor Robotic Fleet Certification | FAA-credited integrators capture premium margins as autonomous baggage handling scales at UAE hubs. |
| Digital Building Twin Platform Integration | Predictive maintenance algorithms embedded from schematic stages displace reactive facility management. |
| Natural Refrigerant HVAC Transition | ECHA-linked procurement rules in Germany and France disqualify conventional equipment packages. |
| Availability-Based Concession Financing | Technology integrators without heavy construction balance sheets capture long-term service contracts. |
| Edge Computing Node Deployment | Sub-100-millisecond latency architectures render centralized server-room designs obsolete at Saudi greenfields. |
Methodological Framework
Cross-validation between primary interviews with airport operators and secondary validation through GACA procurement disclosures anchors the qualitative findings. Stakeholder consultations included terminal development executives, aviation IT security specialists, EPC contract managers, and energy systems engineers. Secondary sources comprised FAA certification databases, ECHA enforcement bulletins, Saudi sovereign project announcements, and EU Green Deal implementation trackers. Bottom-up project pipeline analysis and top-down regulatory mandate sizing were triangulated.
Calibration against historical deployment timelines at Frankfurt, Dubai International, and NEOM established trajectory parameters across the projection horizon. Segmentation dimensions modeled include technology type, end user archetype, application focus, and service delivery model. CAGRs were derived from capacity constraint intensity, regulatory deadline clustering, and sovereign project acceleration patterns. Industry-specific inputs included F-Gas Regulation compliance cost curves and biometric passenger flow adoption benchmarks.
Sensitivities concentrate around FAA certification timeline extensions, EU cybersecurity standard finalization, and Saudi gigaproject schedule adjustments. Forecasts reflect documented assumptions on regulatory enforcement intensity and sovereign capital commitment durability. Macroeconomic contraction, regulatory rollback, or autonomous vehicle safety incidents would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart Infrastructure
Smart Pipeline Networks Market
Smart Infrastructure
Global IoT in Construction Market
Smart Infrastructure
Smart Hydrants Market
Smart Infrastructure
Smart Concrete Market
Smart Infrastructure
Asia-Pacific Smart Building Market
Smart Infrastructure
Digital Twin-Enabled Structural Health Monitoring Test Platforms Market
Smart Infrastructure
Smart Infrastructure Market
Smart Infrastructure
Bridge and Tunnel Condition Assessment Sensor Networks and Test Platforms Market
Smart Infrastructure
US Smart Building Market
Smart Infrastructure
IoT in Commercial Construction Market
Smart Infrastructure
Infrastructure Solution Integration Service Market
Smart Infrastructure
Construction 4.0 Market
Smart Infrastructure
Big Data in Construction Market