
 Powered Screed Market | 2026-2036
Powered Screed Market Size, Share, and Industry Trends Forecast 2026-2036
Powered Screed Market Analytics
The EU Green Deal's construction equipment emissions benchmarks are restructuring procurement criteria across European commercial flooring. Wacker Neuson SE leverages its Munich engineering base to dominate electric-powered screed development. Allen Engineering Corporation anchors North American distribution through specialized contractor channels. Multiquip Inc. competes on manufacturing scale across gas-powered and hybrid product lines.
A powered sced is a mechanized concrete finishing device that employs vibrating blades, augers, or lasers to level and smooth freshly poured concrete surfaces, typically operating at frequencies between 3,000 and 6,000 vibrations per minute to achieve specified flatness tolerances. Its primary industrial purpose is to replace manual screeding in large-scale concrete pours, reducing labor requirements while improving surface regularity for subsequent flooring systems. Laser screeds command premium positioning in commercial flooring applications where F-number flatness specifications drive contractor selection, while handheld screeds sustain volume in residential segments constrained by project scale and equipment mobility. Ride-on screeds lead technology migration as contractors prioritize operator ergonomics and pour-speed consistency across warehouse and logistics facility builds.
The US Environmental Protection Agency's Tier 4 Final engine standards and the European Union's F-Gas Regulation jointly constrain gas-powered equipment configurations, compelling manufacturers to accelerate electric and hybrid platform development. China's Ministry of Ecology and Environment enforces national emissions standards for construction machinery that restrict diesel-powered imports while favoring domestic electric technology adoption. Stakeholders must monitor regulatory divergence across these three jurisdictions to anticipate certification costs and product line rationalization requirements.
Market Dynamics
Stringent emissions regulations across Germany, the United States, and China are forcing equipment manufacturers to reengineer powertrain architectures while maintaining the vibration frequencies and flatness tolerances that concrete contractors require.
Growth Catalysts
- EU Green Deal benchmarks:Germany's commercial flooring contractors face mandatory emissions reductions for construction equipment, accelerating procurement of electric ride-on screeds that satisfy F-number specifications.
- China's provincial highway programs:State infrastructure investment prioritizes mechanized concrete finishing across provincial networks, concentrating equipment deployment in transportation corridor development.
- Laser-guided precision technology:Warehouse and logistics facility developers specify laser screeds to achieve superflat tolerances required by automated material handling systems.
Market Restraints
- Battery energy density limitations:Current lithium-ion configurations constrain continuous operation time for electric screeds on large-scale pours, forcing hybrid interim solutions.
- Supply concentration in rare earth processing:Permanent magnet motor production depends on Chinese refining capacity, creating vulnerability in electric powertrain supply chains.
- EPA Tier 4 Final compliance costs:Gas-powered equipment manufacturers absorb certification and aftertreatment expenses that compress margins on entry-level product lines.
Strategic Opportunities
- India's infrastructure buildout:National highway expansion and smart city initiatives create first-mover advantage for screed manufacturers establishing local assembly or distribution partnerships.
- Equipment-as-a-service models:Rental channel expansion allows contractors to access laser screed capabilities without capital commitment, opening mid-tier contractor segments.
- Photovoltaic-integrated manufacturing:Solar-powered production facilities align with EU Green Deal supply chain disclosure requirements while reducing operational emissions intensity.
Industry Challenges
- Skilled operator scarcity:Laser screed operation requires certified training in grade control systems and vibration mechanics, constraining deployment speed in emerging markets.
- Cross-jurisdiction certification complexity:Manufacturers must navigate divergent EPA, EU F-Gas, and China MEE standards simultaneously, extending product development timelines.
- Legacy fleet integration friction:Contractors with substantial gas-powered equipment investments face sunk cost barriers when evaluating electric platform migration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Powered Screed Market |
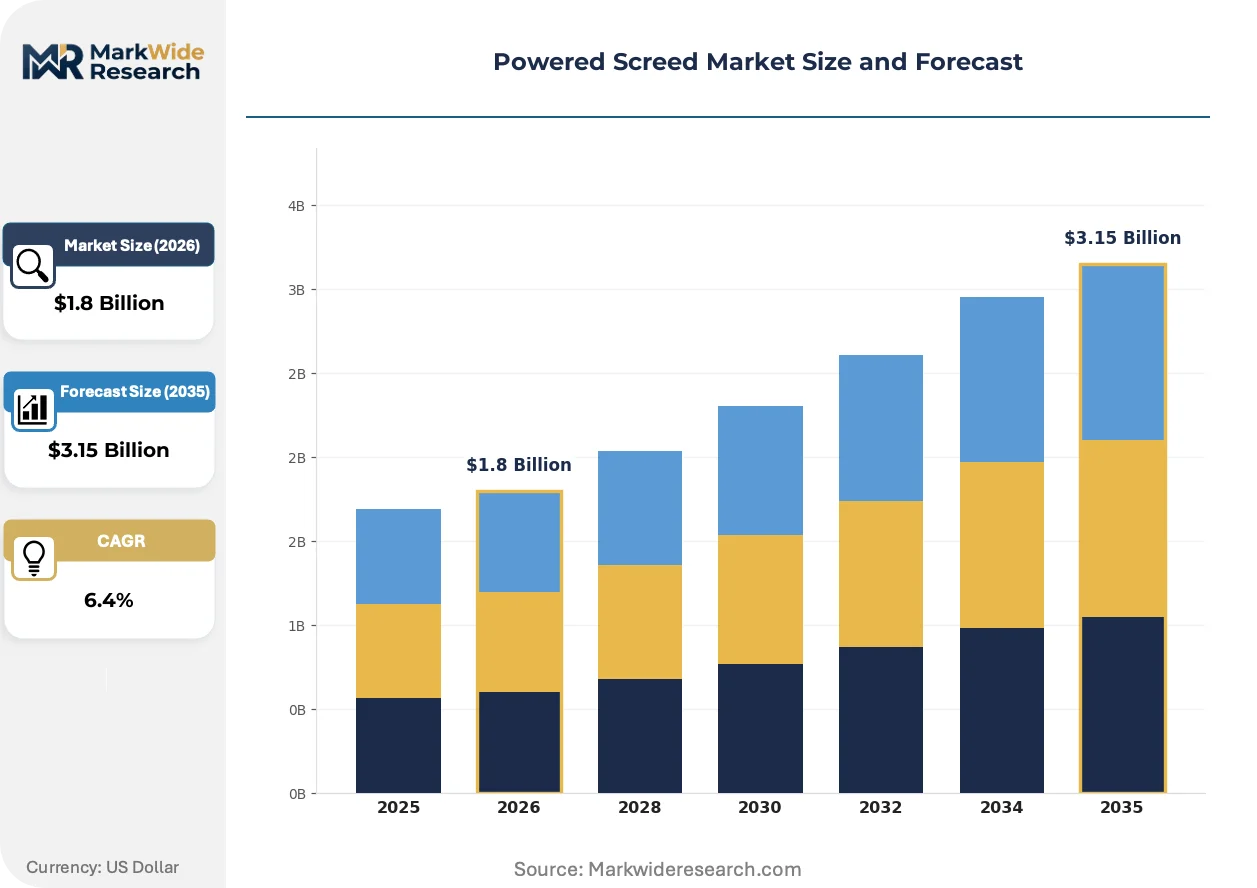
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Truss Screeds, Ride-On Screeds, Handheld Screeds, Laser Screeds Application: Residential Flooring, Commercial Flooring, Road Construction, Sports Facilities End User: Contractors, Construction Companies, DIY Enthusiasts, Government Projects Technology: Electric, Gas-Powered, Hybrid, Pneumatic |
| Companies Covered | Wacker Neuson SE, Allen Engineering Corporation, Multiquip Inc., MBW Inc., SOMERO Enterprises, Inc., Husqvarna AB, Marshalltown Company, Tomahawk Power, Ligchine International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Powered Screed Market Evolving Landscape
Electrification is reconfiguring competitive advantage around battery thermal management and power electronics, while regulatory pressure and procurement evolution reshape how equipment reaches end-users.
Battery-electric powertrains are electrifying the core value proposition of ride-on screeds. Logistics facility developers in the United States specify zero-emissions equipment for LEED certification compliance. This shift compresses the competitive window for gas-powered alternatives in commercial flooring segments.
Europe's F-Gas Regulation constrains refrigerant options in equipment climate control systems, compelling manufacturers to redesign operator cabin thermal management. The industrial consequence extends product engineering cycles by 12-18 months. Commercial flooring contractors in Germany and France now prioritize equipment with documented refrigerant compliance in procurement specifications.
Rental-first procurement is displacing direct equipment ownership among mid-tier concrete contractors. Specialized equipment distributors in Texas and Florida are consolidating screed fleets under centralized maintenance programs. This pattern concentrates purchasing influence with national rental chains rather than individual contractors.
Powered Screed Market Segmentation
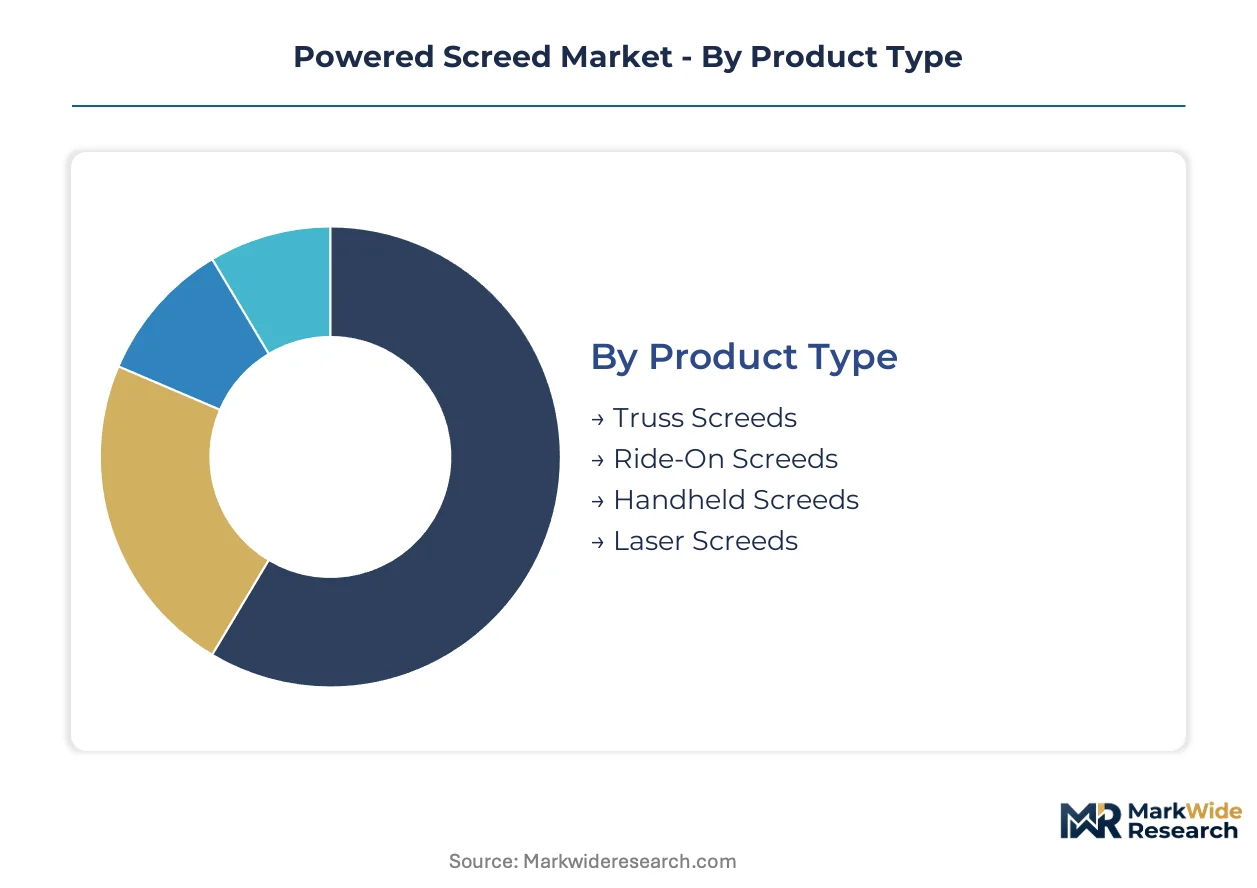
Powered screed procurement patterns diverge sharply across equipment mobility requirements, project scale thresholds, and emissions compliance obligations. Contractor selection criteria prioritize vibration frequency precision, operator ergonomics, and powertrain certification status.
Product Type:
Equipment mobility and pour-size economics differentiate buyer investment thresholds across commercial and residential segments.
- Ride-On Screeds:Self-propelled platforms with operator stations deliver continuous vibration across warehouse-scale pours exceeding 10,000 square feet. German commercial flooring contractors specify these units to satisfy EU Green Deal emissions benchmarks while maintaining F-number flatness specifications.
- Laser Screeds:Grade-control systems using rotating laser transmitters achieve superflat tolerances within ±3 millimeters over 30-meter spans. Logistics facility developers in the United States mandate these for automated material handling system compatibility.
- Truss Screeds:Engine-driven vibrating trusses span bridge decks and highway widths, favored by state transportation agencies for provincial highway networks.
- Handheld Screeds:Portable gasoline or battery units suit residential slabs and repair work where equipment transport costs exceed productivity gains.
Volume sits with ride-on configurations; growth tilts toward laser-guided precision platforms.
Application:
Surface tolerance specifications and project timelines reshape equipment deployment patterns across verticals.
- Commercial Flooring:Warehouse and distribution center builds demand superflat finishes for high-rack storage systems. LEED certification requirements in the United States accelerate zero-emissions equipment procurement for these developments.
- Road Construction:Provincial highway programs in China prioritize mechanized concrete finishing across transportation corridor networks, concentrating ride-on and truss screed deployment.
- Residential Flooring:Single-family and small multi-family projects sustain handheld screed volumes where pour sizes fall below equipment mobilization thresholds.
- Sports Facilities:Running tracks and court surfaces require specialized slope control and drainage grading, commanding premium laser screed configurations.
Commercial flooring commands equipment value; road construction drives unit expansion.
End User:
Capital access and technical capability stratify procurement behavior across customer types.
- Contractors:Specialized commercial flooring contractors in Germany and France now embed refrigerant compliance documentation into equipment specifications under F-Gas Regulation obligations.
- Construction Companies:General contractors with diversified project portfolios favor rental channel access to laser screed capabilities without capital commitment.
- Government Projects:State infrastructure agencies specify domestic equipment content and emissions certification status in public procurement tenders.
- DIY Enthusiasts:Residential owner-builders represent minimal volume, constrained by equipment cost and operational training requirements.
Construction companies concentrate fleet ownership; contractors represent the steepest expansion trajectory through rental penetration.
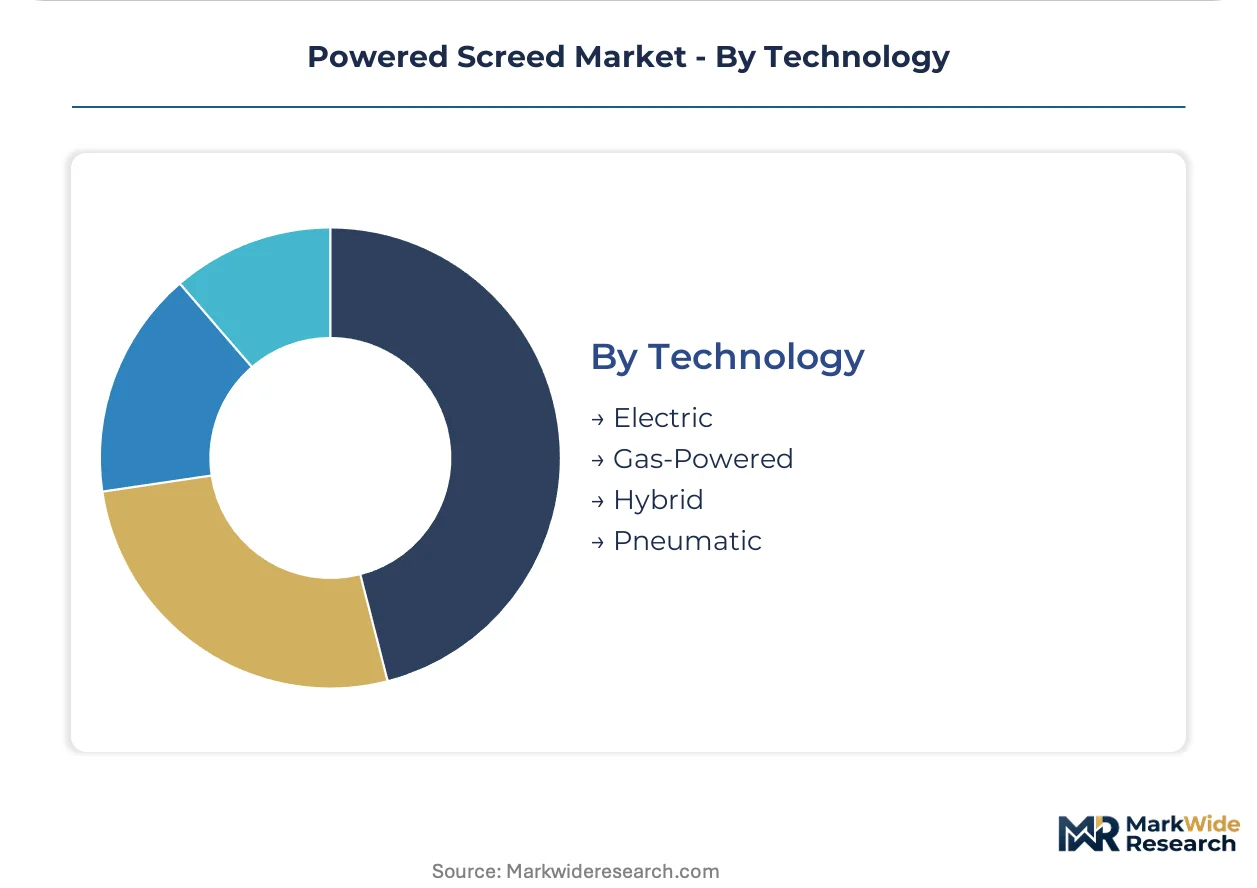
Technology:
Powertrain architecture selection increasingly hinges on jurisdiction-specific emissions enforcement rather than performance differentiation.
- Electric:Battery-electric platforms with thermal management systems support 4-6 hour continuous operation windows. EPA Tier 4 Final compliance costs and EU Green Deal benchmarks compress the competitive window for alternatives in commercial segments.
- Hybrid:Range-extender configurations bridge battery energy density limitations on large-scale pours, serving as interim solutions for contractors evaluating full electrification.
- Gas-Powered:Gasoline and propane units sustain market presence in regions with limited charging infrastructure and among contractors with legacy fleet investments.
- Pneumatic:Compressed-air systems serve niche explosive-environment applications where spark ignition risks prohibit combustion or electric motors.
Gas-powered retains installed base; electric platforms gain share fastest on regulatory momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of powered screed components while Germany and the United States absorb premium equipment imports. This production-consumption divide shapes regional competitive dynamics and regulatory compliance requirements across jurisdictions.
United States
Warehouse construction in Dallas-Fort Worth and Phoenix drives laser screed deployment for superflat flooring specifications. EPA Tier 4 Final standards compel manufacturers to integrate exhaust aftertreatment systems into gas-powered units. Texas-based rental chains consolidate fleet purchasing power, shifting procurement influence away from individual contractors.
Germany
Commercial flooring contractors in Munich and Stuttgart expand electric ride-on screed adoption to meet EU Green Deal emissions benchmarks. The F-Gas Regulation mandates refrigerant compliance documentation in equipment specifications. Bavarian engineering clusters anchor development of battery thermal management systems for extended operation windows.
China
State-led provincial highway programs concentrate mechanized concrete finishing demand across transportation corridor networks. The Ministry of Ecology and Environment enforces national emissions standards that restrict diesel-powered imports while favoring domestic electric technology. Yangtze River Delta manufacturing bases supply permanent magnet motors for powertrain assembly.
India
National highway expansion and smart city initiatives create equipment demand in Maharashtra and Gujarat. The Bureau of Indian Standards certifies construction machinery for public procurement eligibility. Delhi-NCR contractors face air quality regulations that accelerate interest in electric platform trials.
Japan
Prefabricated construction methods in Kanto and Kansai regions sustain demand for precision concrete finishing equipment. METI efficiency standards guide powertrain development toward hybrid configurations. Osaka-based distributors specialize in compact laser screeds for constrained urban job sites.
Powered Screed Market Competitive Landscape
The competitive structure tilts toward engineering-specialized manufacturers with established regulatory certification capabilities. Market concentration remains moderate, with distinct tiering between premium precision-equipment developers and scale-oriented volume producers. Two strategic archetypes dominate: Munich-based engineering houses with electric platform leadership, and North American distributors with rental channel penetration. Competitive moves center on powertrain reengineering for emissions compliance and fleet consolidation through rental partnerships.
Among Germany-based engineering specialists, Wacker Neuson SE exemplifies the electric-development archetype through its Munich engineering base. Allen Engineering Corporation and Multiquip Inc. represent North American market presence, with the former anchoring specialized contractor distribution and the latter occupying a position across gas-powered and hybrid product lines. These three companies illustrate the geographic and technological stratification shaping procurement decisions.
| Leading Market Players |
|---|
| Wacker Neuson SE |
| Allen Engineering Corporation |
| Multiquip Inc. |
| MBW Inc. |
| SOMERO Enterprises, Inc. |
| Husqvarna AB |
| Marshalltown Company |
| Tomahawk Power |
| Ligchine International |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap specialists in Germany and Japan anchor premium pricing discipline through captive engineering capabilities, while their reliance on Yangtze River Delta component sourcing exposes margin structures to rare earth processing bottlenecks and MEE emissions certification delays.
Pricing Analysis
Margin tightening in electric ride-on configurations reflects battery thermal management system costs and Tier 4 Final aftertreatment expenses. Three-tier pricing structure across laser-guided precision, hybrid interim, and gas-powered economy levels separates F-number certified contractors from residential handheld buyers. Price differentiation traces to EPA and EU emissions certification tiers plus after-sales service bundling. Commercial flooring contractors in Germany exhibit lowest price sensitivity due to Green Deal compliance mandates; residential DIY segments in India face acute cost compression.
Supply Chain Analysis
China's domestic-content requirements for public procurement tenders reshape sourcing patterns for permanent magnet motors and lithium-ion cells. Manufacturing concentrates in China, Germany, and the United States for final assembly, while component sourcing draws from South Korea for power electronics and Japan for precision sensors. Raw material dependencies rest on Chinese rare earth refining, German steel forging, and South Korean battery chemistry. Single-source vulnerability in neodymium processing threatens electric powertrain scaling. Distribution runs through specialized equipment rental chains in Texas and Florida, consolidating fleet purchasing away from individual contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Permanent magnet motor supply constraints prop pricing power for manufacturers with secured rare earth offtake, as battery energy density limitations sustain hybrid platform relevance.
For Market Incumbents: Acquire certified training infrastructure to lock in laser screed operator pipelines against skilled labor scarcity. Secure backward integration into battery thermal management assembly to defend margins from power electronics cost spikes. Prioritize F-Gas Regulation compliance documentation for German and French procurement specifications. For New Entrants and Emerging Players: Equipment-as-a-service digital platforms offer lowest customer acquisition friction in India's Maharashtra and Gujarat highway corridors. Target state transportation agencies with domestic-content-compliant truss screed offerings. Pursue rental channel partnerships rather than direct contractor sales to bypass capital barrier friction. For Investors and Strategic Acquirers: Distressed-cycle entries favor electric-platform engineering specialists with Yangtze River Delta manufacturing partnerships. Long-term viability centers on powertrain reengineering capabilities across the 5-10 year emissions compliance window. Monitor EPA Tier 5 pre-rulemaking signals as inflection indicator for gas-powered asset stranding risk.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery Thermal Management | Captive production of power electronics reduces exposure to South Korean semiconductor supply volatility. |
| Rental Channel Partnership Expansion | Texas-based fleet consolidators concentrate procurement influence for mid-tier contractor access. |
| Photovoltaic-Integrated Manufacturing | Solar-powered production facilities satisfy EU Green Deal supply chain disclosure requirements. |
| Certified Operator Training Program Development | Laser screed grade-control certification addresses skilled labor scarcity constraining deployment speed. |
| Domestic Assembly Partnership in India | Maharashtra and Gujarat local content positioning unlocks Bureau of Indian Standards procurement eligibility. |
Research Methodology
Independent corroboration across equipment distributor interviews, state transportation agency procurement officers, and commercial flooring contractor maintenance directors underwrites the qualitative findings. Primary fieldwork engaged rental fleet managers, OEM procurement teams at Wacker Neuson and Multiquip, and aftermarket service heads across Germany, the United States, and China. Secondary validation drew from EPA Tier 4 Final certification databases, EU F-Gas Regulation compliance registries, and China MEE construction machinery emissions filings. Bottom-up unit deployment tracking and top-down infrastructure investment flow analysis triangulate market sizing.
Rate-of-change decomposition across the projection horizon segments volume by product mobility tier, powertrain architecture, and end-use application intensity. Modeled dimensions include ride-on versus handheld configurations, electric-hybrid-gas technology splits, and commercial flooring versus road construction demand patterns. CAGRs derive from infrastructure investment pipeline analysis and equipment replacement cycle modeling. Forecast inputs incorporate provincial highway program commitments in China and warehouse construction permitting velocity in Dallas-Fort Worth and Phoenix.
The model holds under sustained emissions enforcement intensity and lithium-ion cost decline curves; deviation in rare earth export restrictions or battery chemistry breakthroughs would shift powertrain adoption timelines. Forecasts reflect documented assumptions on regulatory phase-in schedules and contractor fleet turnover rates. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Trenchers Market
Construction Equipment
Italy Construction Equipment Market
Construction Equipment
Static Crane Market
Construction Equipment
Demolition Vessels Market
Construction Equipment
South Korea Heavy Construction Equipment Rental Market
Construction Equipment
Mortar Testing Equipment Market
Construction Equipment
Laser Cladding Equipment Market
Construction Equipment
North America Mini and Midi Horizontal Directional Drilling Market
Construction Equipment
Europe Construction Machinery Rental Market
Construction Equipment
Hydraulic Spreader Market
Construction Equipment
Global Concrete Curing Equipment Market
Construction Equipment
Snow Removal Market
Construction Equipment
Demolition Equipment Market
Construction Equipment
Europe Excavator and Loaders Market
Construction Equipment
Construction Equipment Attachments Market
Construction Equipment
Spray Washer Market