
 Aerial Work Platform (AWP) Market | 2026-2036
Aerial Work Platform (AWP) Market Size, Share, and Industry Trends Forecast 2026-2036
Aerial Work Platform (AWP) Market Analysis
The capital-intensity divergence between full-line manufacturers and regional assemblers is unwinding competitive stability across the AWP supply base. JLG Industries leverages integrated boom and scissor manufacturing to sustain pricing power in North American rental channels. Haulotte Group anchors its position through European engineering certification depth and specialized rough-terrain portfolios. Sinoboom competes aggressively on electric scissor lift cost structures while navigating export compliance complexity.
An aerial work platform is a mobile elevating device with a work platform and controls at the platform level, typically extending vertically to heights between 20 and 185 feet depending on configuration, designed to position personnel and tools at elevated work sites. Boom lift configurations articulate or telescope to reach over obstacles, while scissor lifts provide strictly vertical elevation through linked folding supports for applications requiring heavy platform loads. Electric technology leads in indoor warehousing and telecommunications maintenance segments where zero-emission operation and reduced noise footprint align with facility requirements. Hydraulic systems still dominate outdoor construction deployments where power density and rough-terrain capability outweigh energy efficiency priorities.
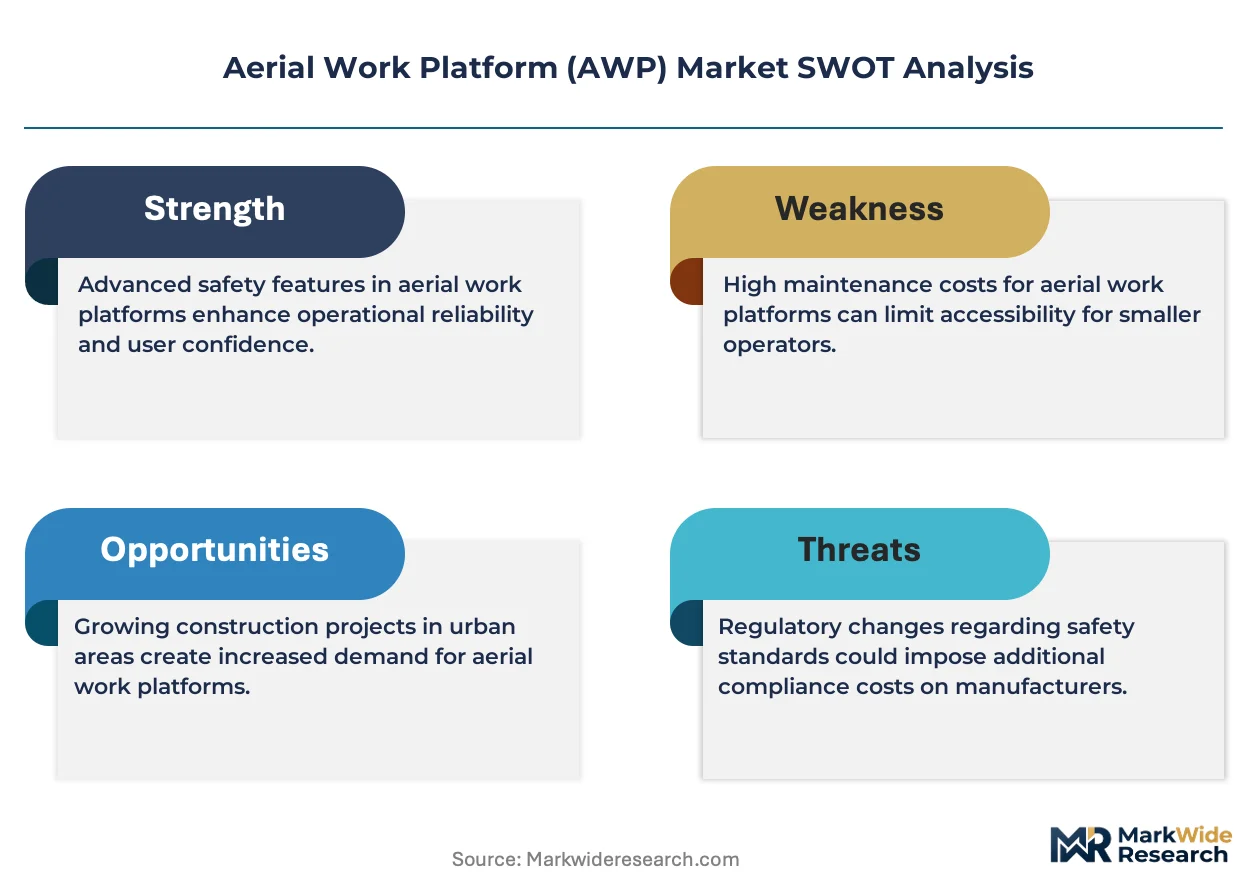
ANSI A92 standards govern design, safe use, and training requirements for AWPs in the United States, while EN 280 certification mandates structural calculations and stability testing for European market access. OSHA inspection protocols and the EU Machinery Directive together elevate compliance costs for manufacturers serving both jurisdictions. Fleet managers must weigh total cost of ownership against electrification timelines as rental channels face tightening carbon disclosure expectations.
Market Dynamics
Electrification mandates from fleet operators are compressing diesel equipment replacement cycles and forcing manufacturers to reconfigure powertrain supply chains around lithium-ion cell sourcing.
Growth Catalysts
- ANSI A92.20 Design Standards:Updated stability and load-sensing requirements in the United States are accelerating fleet turnover toward compliant models. Rental networks are retiring pre-2020 equipment ahead of enforcement timelines.
- Utility-Scale Solar Deployment:Photovoltaic installation crews in Texas and California are absorbing boom lift capacity for module placement at height. Project pipelines are extending equipment utilization seasons.
- Telecommunications Infrastructure:5G small cell and macro tower buildouts are creating sustained demand for compact electric scissors in urban right-of-way work. Tower maintenance contracts are shifting toward multi-year fleet leases.
Market Restraints
- Steel and Aluminum Input Volatility:Boom fabrication costs fluctuate with commodity indexes, compressing margin visibility for mid-tier assemblers. Tariff exposure on Chinese structural steel adds procurement uncertainty.
- Battery Cell Supply Concentration:Cylindrical lithium-ion production concentrates in East Asian cell makers, creating single-source risk for electric scissor lift OEMs. Cell qualification cycles extend platform development timelines.
- EN 280 Certification Friction:European structural testing requirements impose 12-18 month validation periods for new boom geometries. Smaller manufacturers lack capital to maintain parallel certification tracks.
Strategic Opportunities
- India Construction Equipment Formalization:Organized rental penetration remains below 15% in Indian metropolitan construction. Equipment-as-a-service models can capture unbanked contractor demand.
- Hybrid Powertrain Convergence:Diesel-electric architectures for rough-terrain booms address emission zones without range anxiety. Dual-power platforms open municipal and infrastructure segments.
- OSHA Silica Exposure Rules:Tighter dust suppression mandates in concrete and masonry work are elevating enclosed platform demand. Positive-pressure cabs represent attachable retrofit revenue.
Industry Challenges
- Mechatronics Technician Scarcity:Electric platform diagnostics require blended mechanical-hydraulic-electrical skill sets. Vocational pipelines are not producing certified repair specialists at replacement rates.
- IP Licensing in Load Sensing:Proprietary tilt and overload algorithms from major OEMs create patent thickets. Regional manufacturers face litigation exposure when developing independent safety systems.
- Legacy Fleet Integration:Telematics retrofits for pre-2015 diesel units encounter CAN bus incompatibility. Rental networks must maintain dual maintenance protocols during transition periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Aerial Work Platform (AWP) Market |
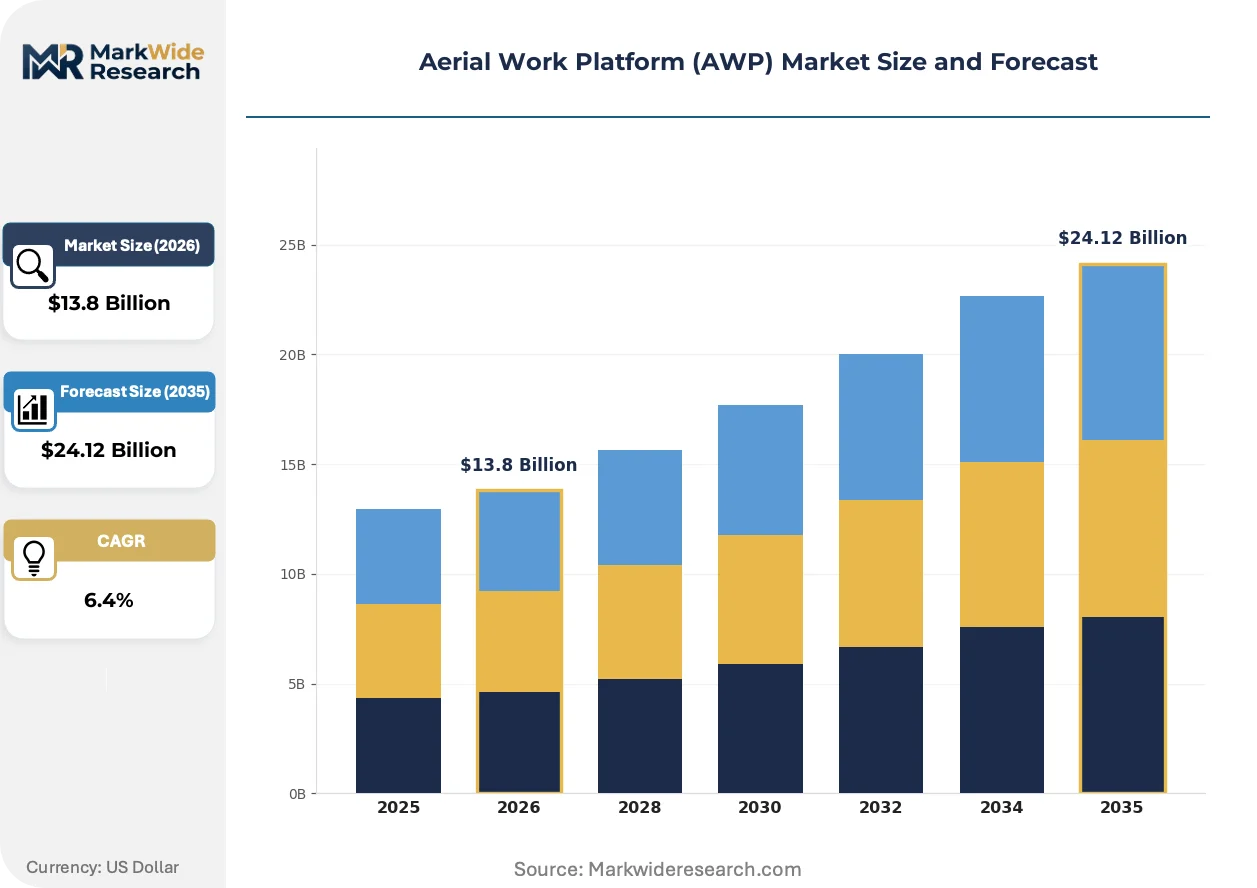
| Market Size in 2026 | $13.8 Billion |
| Market Size in 2035 | $24.12 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Scissor Lift, Boom Lift, Vertical Mast Lift, Trailer-Mounted Lift End User: Construction, Maintenance, Warehousing, Telecommunications Deployment: Rental, Purchase, Lease, Financing Technology: Electric, Hydraulic, Pneumatic, Hybrid |
| Companies Covered | JLG Industries, Terex Corporation, Haulotte Group, Dinolift OY, Manitou Group, Skyjack, Aichi Corporation, Oshkosh Corporation, Sinoboom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Aerial Work Platform (AWP) Market Emerging Trajectories
Autonomous positioning systems and predictive maintenance architectures are redefining equipment uptime guarantees. Manufacturers are embedding sensor networks to shift from asset sales to availability contracting.
Lithium iron phosphate battery packs are fragmenting the electric scissor lift segment by enabling rapid opportunity charging at construction sites. Warehouse operators in the United States are adopting fast-charge infrastructure to eliminate battery swap labor. The technology is fragmenting procurement patterns as buyers separate fleet electrification timelines from full site power upgrades.
EU Machinery Directive amendments are mandating real-time stability monitoring and automatic envelope control for all new AWPs sold in member states. Manufacturers must integrate load moment indicators and tilt sensors as standard equipment. The directive is compressing development cycles for European engineering teams while creating compliance export requirements for non-EU suppliers.
Rental channel consolidation is compressing fleet decision authority into fewer procurement desks. National rental networks in the United States are standardizing platform specifications across hundreds of branches. This concentration is forcing OEMs to absorb longer payment terms and bundled service obligations in exchange for volume commitments.
Aerial Work Platform (AWP) Market Segmentation
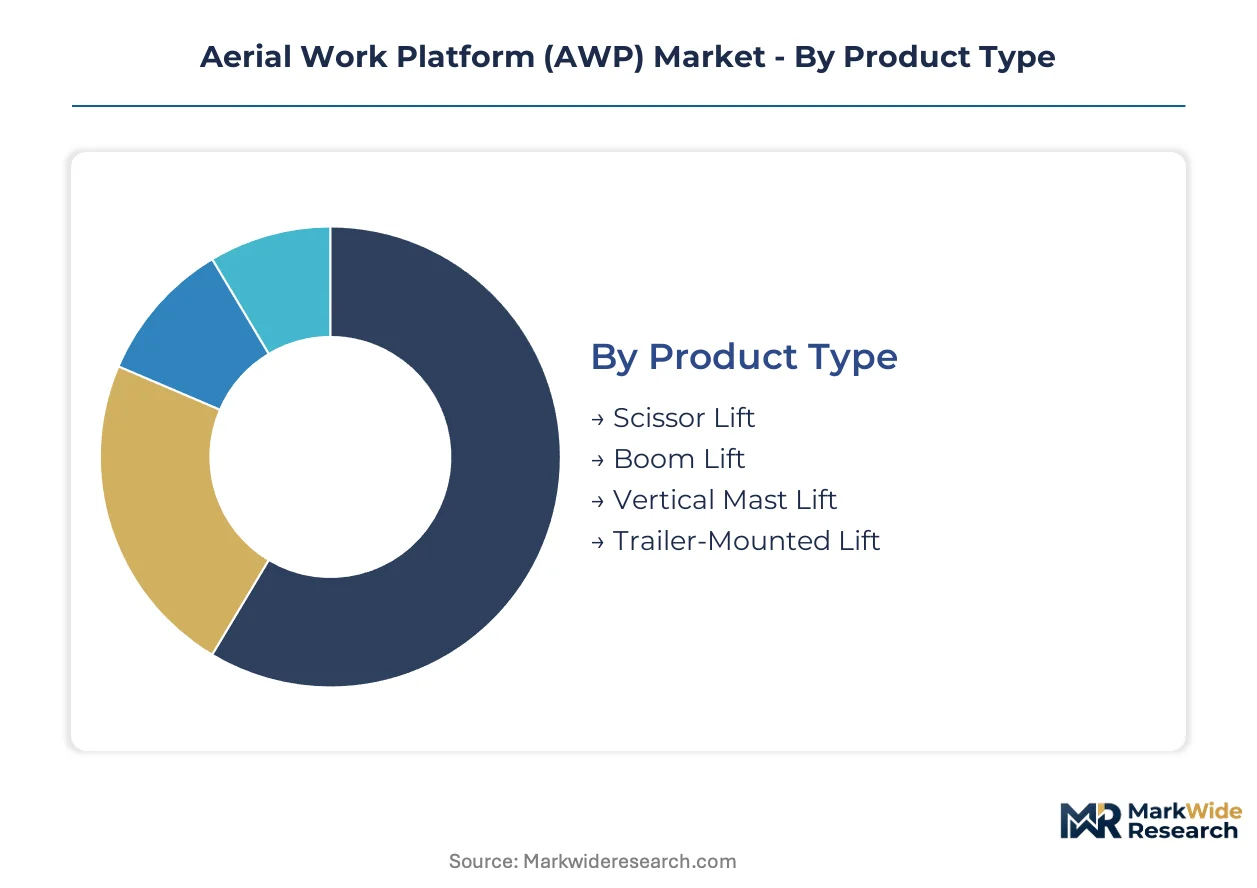
AWP procurement patterns diverge sharply across equipment configurations and ownership models. Fleet operators optimize total cost of ownership differently depending on application intensity, site access constraints, and capital deployment preferences.
Product Type:
Margin pools concentrate in boom lift configurations where engineering complexity and safety certification depth sustain pricing premiums. Scissor lifts compete on manufacturing scale and battery integration speed.
- Scissor Lift:Linked folding support structures deliver strictly vertical elevation with heavy platform load capacity. Warehouse operators in the United States are absorbing electric scissor capacity for fulfillment center maintenance where zero-emission operation aligns with ESG disclosure requirements.
- Boom Lift:Articulating and telescoping configurations extend horizontal and vertical reach over obstacles. Utility-scale solar crews in Texas and California are locking multi-year boom leases for photovoltaic module placement at height, extending seasonal utilization windows.
- Vertical Mast Lift:Compact single-mast designs navigate narrow aisle widths in retail and facility maintenance. Telecom contractors favor these units for 5G small cell installations in dense urban right-of-way constraints.
- Trailer-Mounted Lift:Towable platforms serve intermittent height access for municipal and event infrastructure. Landscaping and tree care contractors in seasonal markets favor rental procurement for peak demand absorption.
Boom lift holds installed capacity. Scissor lift is rotating up the share rankings.
End User:
Application intensity varies by sector capital cycle timing and regulatory exposure. Construction dominates unit volume while telecommunications drives fleet modernization velocity.
- Construction:General contracting and specialty trades deploy mixed fleets across rough-terrain and slab applications. Commercial building contractors face OSHA silica exposure rules elevating enclosed platform specifications for concrete and masonry work.
- Maintenance:Facility management and industrial plant services require rapid mobilization for intermittent height access. Manufacturing sites are adopting predictive maintenance architectures to shift from ownership to availability contracting.
- Warehousing:E-commerce fulfillment networks operate electric scissors on multi-shift schedules with opportunity charging infrastructure. Fast-charge lithium iron phosphate packs are eliminating battery swap labor costs.
- Telecommunications:Tower maintenance and 5G deployment crews demand compact electric units with extended duty cycles. Macro tower buildouts are compressing replacement cycles across national rental networks.
Construction commands current fleet share. Telecommunications is gaining share fastest.
Deployment:
Capital deployment preferences split between balance sheet ownership and operational flexibility. Rental channel consolidation is compressing decision authority into fewer procurement desks.
- Rental:National networks standardize specifications across hundreds of branches, forcing OEMs to absorb extended payment terms. Fleet managers weigh telematics integration and bundled service obligations against volume commitments.
- Purchase:Large contractors with predictable utilization profiles capture depreciation benefits and customization control. Utility-scale solar developers favor ownership for multi-year project pipelines.
- Lease:Operating leases preserve capital for mid-tier contractors facing interest rate volatility. Municipal infrastructure departments favor lease structures for budget predictability.
- Financing:Equipment finance companies structure residual value guarantees around secondary market liquidity. Credit availability fluctuates with construction lending cycles.
Rental dominates transaction volume. Purchase is climbing the fastest among capital deployment modes.
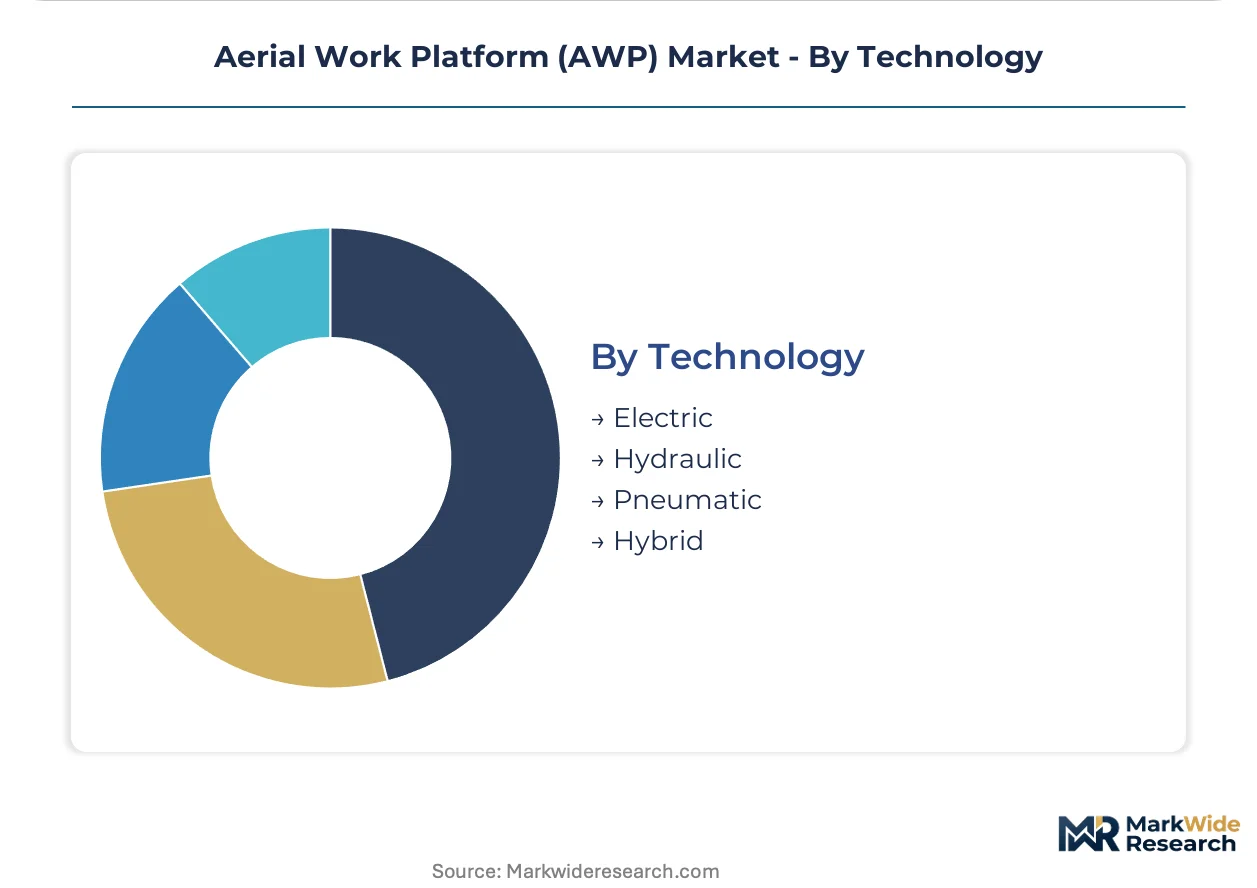
Technology:
Powertrain selection hinges on duty cycle intensity, site emission constraints, and charging infrastructure availability. Electrification mandates are reconfiguring manufacturer supply chains around lithium-ion cell sourcing.
- Electric:Battery-powered platforms eliminate emissions and noise for indoor warehousing and urban telecommunications work. Lithium iron phosphate chemistry enables rapid opportunity charging at construction sites without full power upgrades.
- Hydraulic:Diesel-hydraulic systems retain dominance in outdoor construction where power density and rough-terrain capability outweigh efficiency priorities. ANSI A92.20 stability requirements are accelerating fleet turnover toward compliant hydraulic models.
- Pneumatic:Compressed air systems serve explosive atmosphere applications in chemical and petrochemical facilities. Specialized rental fleets maintain these units for confined space entry protocols.
- Hybrid:Diesel-electric architectures address emission zones without range anxiety for municipal and infrastructure segments. Dual-power platforms open bridge maintenance and rail corridor applications.
Hydraulic retains installed base dominance. Electric is expanding most quickly across procurement specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in the United States where utility-scale solar and 5G deployments compress fleet availability, while European markets absorb certification cost premiums through EN 280 compliance timelines. Rental channel consolidation in North America extracts longer payment terms from manufacturers, contrasting with fragmented contractor bases in emerging economies that resist standardization premiums.
United States
Utility-scale solar installations in Texas and California absorb boom lift capacity for photovoltaic module placement at height, extending equipment utilization seasons beyond traditional construction cycles. OSHA silica exposure rules mandate enclosed platform specifications for concrete and masonry work, elevating equipment complexity requirements. The Southeast corridor from Florida to Georgia hosts expanding rental network branches standardizing electric scissor specifications across multi-state territories.
Germany
Industrial facility maintenance drives demand for compact electric units with predictive maintenance architectures, shifting procurement from ownership to availability contracting. The EU Machinery Directive mandates real-time stability monitoring and automatic envelope control for all new AWPs, compressing development cycles for engineering teams. The Baden-Württemberg cluster anchors rough-terrain boom engineering with specialized certification depth for export markets.
China
Domestic construction formalization accelerates organized rental penetration in tier-one cities, creating equipment-as-a-service opportunities for unbanked contractor segments. GB standards and MIIT regulations govern structural safety and emission requirements for aerial platform manufacturing. The Yangtze River Delta concentration supports lithium-ion cell supply chain integration for electric scissor lift cost structures.
India
Metropolitan construction in Mumbai and Delhi drives unmet demand for organized rental services below 15% current penetration rates. The Central Electricity Authority and Bureau of Indian Standards impose evolving safety certification requirements for imported equipment. The Gujarat industrial corridor attracts assembly operations targeting price-sensitive contractor segments with localized fabrication.
United Arab Emirates
Expo infrastructure legacy and continued tourism development sustain demand for trailer-mounted and vertical mast units in facility maintenance applications. The country's national construction regulator enforces equipment safety protocols aligned with international standards for high-rise work. Dubai's logistics hub position facilitates re-export of certified units to Middle East and African markets.
Aerial Work Platform (AWP) Market Vendor Landscape
Concentration sits with full-line manufacturers commanding integrated boom and scissor production capabilities that sustain pricing power in consolidated rental channels. Mid-tier regional assemblers compete on manufacturing scale and battery integration speed while navigating export compliance complexity. Three archetypes define competitive positioning: integrated full-line manufacturers, European engineering specialists with certification depth, and Asian scale players leveraging electric platform cost structures. Dominant competitive moves include strategic partnerships for lithium-ion cell sourcing and portfolio diversification into hybrid powertrain architectures.
Within the integrated manufacturer tier, JLG Industries and Terex Corporation exemplify North American full-line positioning with captive boom and scissor fabrication capabilities. Haulotte Group anchors the European specialist archetype through engineering certification depth and rough-terrain portfolio concentration. Among Asian scale players, Sinoboom occupies a position competing aggressively on electric scissor lift cost structures while navigating complex export compliance requirements across multiple jurisdictions.
| Leading Market Players |
|---|
| JLG Industries |
| Terex Corporation |
| Haulotte Group |
| Dinolift OY |
| Manitou Group |
| Skyjack |
| Aichi Corporation |
| Oshkosh Corporation |
| Sinoboom |
| Others |
Supply Flow & Price Mechanics
Lithium-ion cell substitution for lead-acid battery packs is redrawing supplier geography toward East Asian cathode material hubs while compressing electric scissor lift pricing premiums against hydraulic equivalents. Fleet operators now weigh total cost of ownership calculations that embed charging infrastructure capital against diesel fuel volatility, forcing manufacturers to absorb cell qualification delays into margin structures.
Pricing Analysis
Configured-to-order pricing for rough-terrain booms with EN 280 certification depth commands substantial premiums over standard slab scissor configurations sold through rental channels. Three-tier pricing structure across premium, standard, and economy levels reflects ANSI A92.20 compliance status, lithium-ion integration speed, and bundled telematics service obligations. Cost compression in mid-tier electric scissors is intensifying because Sinoboom's aggressive cost structures force incumbent repositioning. Municipal lease customers exhibit highest price sensitivity; utility-scale solar developers with multi-year project pipelines show lowest.
Supply Chain Analysis
Inbound logistics costs from Shanghai to Los Angeles port congestion have elevated landed costs for Chinese structural steel and aluminum boom extrusions, compressing margin visibility for regional assemblers. Cylindrical lithium-ion cell production concentrates in China, South Korea, and Japan, drawing from cobalt sulfate feedstocks anchored in the Democratic Republic of Congo and Indonesian nickel laterites. Single-source vulnerability concentrates in East Asian cell maker qualification cycles that extend platform development timelines. Distribution runs through consolidated national rental networks that extract extended payment terms and bundled service obligations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Electrification mandates fragmenting procurement timelines across rental, purchase, and lease channels create white-space openings for specialized service providers and hybrid powertrain innovators.
For Market Incumbents: Secure captive lithium-ion cell sourcing through strategic partnerships with CATL or LG Energy Solution to defend margin position against supply concentration risk. Deepen ANSI A92.20 and EN 280 certification investment to maintain pricing power as rental networks consolidate procurement authority. For New Entrants and Emerging Players: Telematics retrofit and predictive maintenance service layers remain under-served by full-line manufacturers focused on unit sales. Target Indian metropolitan construction equipment-as-a-service models where organized rental penetration sits below fifteen percent. Pursue municipal infrastructure lease structures for budget-predictable revenue anchoring. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional assemblers lacking capital to maintain parallel EN 280 and ANSI certification tracks. Five-to-ten year viability hinges on electrification transition execution rather than hydraulic legacy maintenance. Watch lithium iron phosphate cell cost curves as inflection indicator for electric platform economic tipping points.| Strategic Initiative | Industry Significance |
|---|---|
| Lithium-Ion Cell Supply Agreement | CATL or LG Energy Solution partnerships secure cathode material access for electric scissor cost structures. |
| Hybrid Powertrain Development | Diesel-electric architectures open municipal bridge maintenance and rail corridor emission-zone applications. |
| Predictive Maintenance Platform Launch | Sensor-network embedding shifts rental channels from asset sales to availability contracting models. |
| India Equipment-as-a-Service Expansion | Unbanked contractor segments in Mumbai and Delhi absorb organized rental formalization. |
| EN 280 Certification Acceleration | European structural testing depth sustains boom lift pricing premiums against Asian scale competition. |
Methodological Framework
The analysis maps boom lift, scissor lift, vertical mast, and trailer-mounted configurations, each validated through fleet managers at national rental networks, OEM procurement directors, and aftermarket service heads. Primary interviews with maintenance directors at utility-scale solar developers and telecommunications tower contractors combined with secondary validation from OSHA enforcement data, EU Machinery Directive amendments, and SEC 10-K filings from listed equipment manufacturers. Bottom-up unit shipment modeling and top-down value triangulation cross-checked against customs records for steel and aluminum structural inputs.
Consistency checks validated volume and value outputs against rental fleet utilization surveys and lithium-ion cell import trajectories across the analysis window. Segmentation dimensions modeled include product type, end-use sector, deployment mode, and powertrain technology. CAGRs derived from equipment replacement cycle acceleration tied to ANSI A92.20 enforcement timelines and utility-scale solar pipeline extensions. Forecast inputs incorporated telematics penetration rates and fast-charge infrastructure deployment patterns.
Forecasts assume regulatory continuity in OSHA silica exposure enforcement and EU Machinery Directive stability monitoring mandates; material policy shifts would require re-modeling. Commodity price volatility in steel and aluminum, alongside cell supply concentration disruptions, represent specific revision risks. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Construction Equipment
Escalator Cleaning Machine Market
Construction Equipment
Stud Welding Machine Market
Construction Equipment
Laser Welding Equipment Market
Construction Equipment
China Fire Sprinklers Market
Construction Equipment
Construction Pump Market
Construction Equipment
Dock Door Market
Construction Equipment
Log Splitters Rental Market
Construction Equipment
Solar Pile Driving Equipment Market
Construction Equipment
Cutter Suction Dredger (CSD) Market
Construction Equipment
Trailer Winch Market
Construction Equipment
Metal Rollforming System Market
Construction Equipment
Hose End Sprayers Market
Construction Equipment
Tower Crane Market
Construction Equipment
Asia-Pacific Road Marking Machine Market
Construction Equipment
Australia Mobile Cranes Rental Market
Construction Equipment
Global Airport Snow Removal Vehicles and Equipment Market