
 Smart Cooktop Market | 2026-2036
Smart Cooktop Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Cooktop Market Outlook
Chinese induction coil manufacturing capacity is realigning toward higher-efficiency inverter modules for export markets. Samsung Electronics leverages vertical integration across semiconductor and appliance divisions to control smart connectivity stacks. Whirlpool Corporation sustains North American production scale while navigating tariff exposure on imported glass-ceramic substrates. BSH Hausgeräte differentiates through precision temperature algorithms developed at its Munich engineering center.
A smart cooktop integrates embedded sensors, microprocessor-controlled heating elements, and wireless connectivity to enable automated cooking sequences and remote monitoring. Induction cooktops dominate value contribution due to superior energy transfer efficiency above ninety percent and compatibility with ferromagnetic cookware detection systems. Electric cooktops occupy mid-tier price bands where retrofit demand from aging residential infrastructure remains structurally significant. Wi-Fi connectivity leads protocol adoption as cloud-based recipe integration becomes a standard feature across premium residential installations.
The U.S. Department of Energy sets minimum efficiency thresholds that disqualify conventional resistive coil designs from federal rebate programs. The EU Ecodesign Directive and CE marking requirements mandate standby power limits and materials disclosure for glass-ceramic surfaces sold in member states. China's GB standards and MIIT certification govern electromagnetic compatibility for induction modules exported from Shenzhen and Ningbo manufacturing zones. Stakeholders must monitor whether pending EPA Energy Star revisions for cooking appliances will expand test criteria to include connected standby consumption.
Market Dynamics
The U.S. Department of Energy efficiency thresholds and EU Ecodesign Directive mandates are forcing simultaneous redesign of heating elements and control systems across all price tiers.
Growth Catalysts
- EU Ecodesign Directive:Standby power limits and materials disclosure requirements accelerate replacement cycles in member states, pulling forward upgrade demand from aging electric coil installations.
- Induction coil efficiency:Inverter module improvements above ninety percent energy transfer efficiency position induction technology as the default specification for premium residential renovations.
- Cloud recipe integration:Wi-Fi protocol standardization enables automated cooking sequences that differentiate premium offerings from conventional electric cooktops.
Market Restraints
- Glass-ceramic substrate concentration:Specialized substrate manufacturing concentrates in East Asian supply zones, exposing procurement to tariff volatility and logistics constraints.
- Ferromagnetic cookware requirement:Induction systems require compatible cookware, creating friction in markets with legacy aluminum or copper utensil stock.
- Installation retrofit costs:Electrical infrastructure upgrades for high-amperage induction units impose structural cost barriers in aging residential buildings.
Strategic Opportunities
- EPA Energy Star expansion:Pending revisions to include connected standby consumption create first-mover advantage for manufacturers with optimized idle power architectures.
- Multi-zone sensor fusion:Convergence of temperature sensors, weight detection, and computer vision enables fully automated cooking workflows for time-constrained households.
- Direct-to-installer channels:Bypassing traditional retail through kitchen design studios and contractor networks captures decision-making authority earlier in renovation project timelines.
Industry Challenges
- Firmware security certification:Connected appliance cybersecurity standards under IEC 62443 impose extended validation timelines before market release.
- Electromagnetic compatibility testing:China's GB standards and MIIT certification requirements for induction modules exported from manufacturing zones demand dedicated compliance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Cooktop Market |
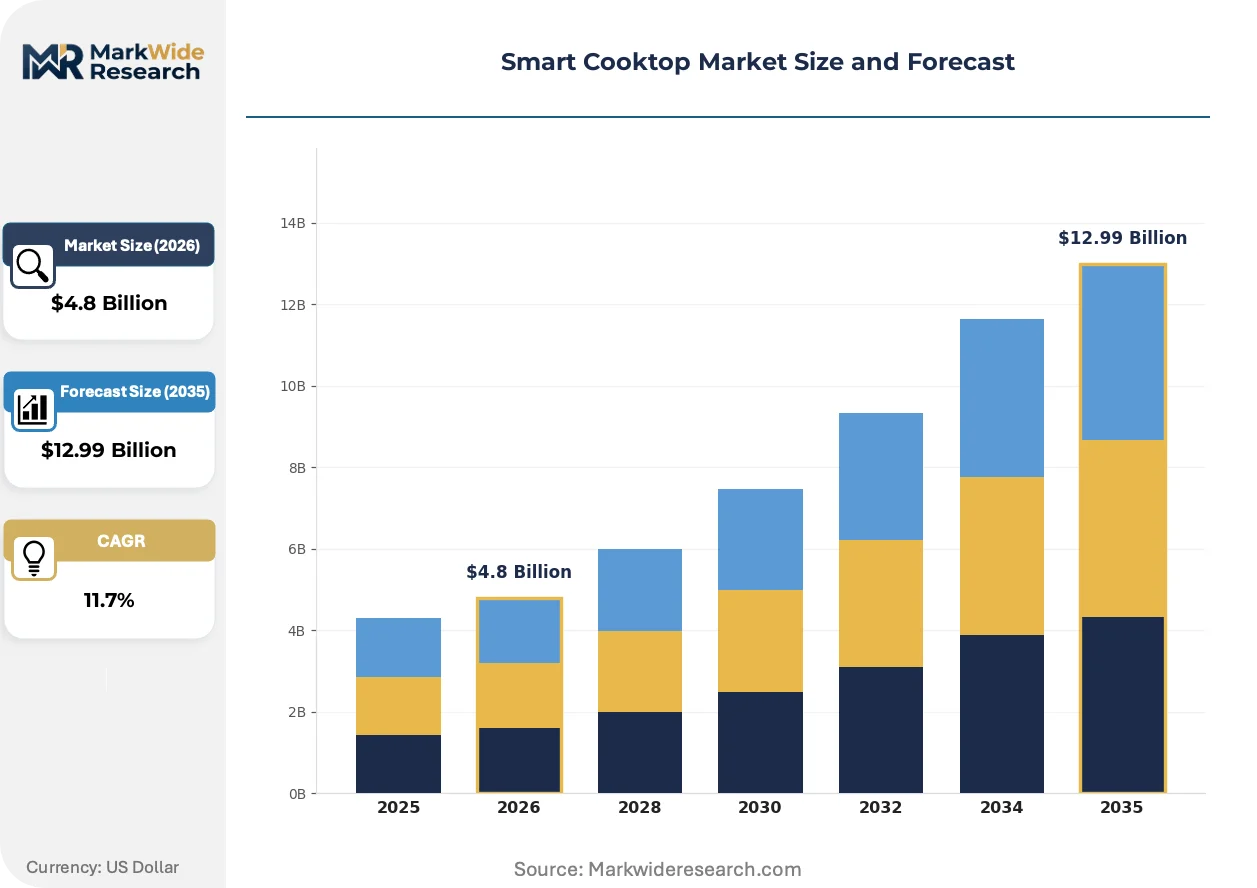
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $12.99 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Induction Cooktops, Electric Cooktops, Gas Cooktops, Hybrid Cooktops End User: Residential, Commercial, Industrial, Hospitality Connectivity: Bluetooth, Wi-Fi, Zigbee, Ethernet Control Method: Touch Control, App Control, Voice Control, Remote Control |
| Companies Covered | Samsung Electronics Co., Ltd., Whirlpool Corporation, LG Electronics Inc., BSH Hausgeräte GmbH, Haier Smart Home Co., Ltd., Electrolux AB, Panasonic Corporation, Miele & Cie. KG, GE Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Cooktop Market Strategic Shifts
Precision temperature algorithms and embedded sensor arrays are compressing the performance gap between amateur and professional cooking outcomes. Three developments dominate current engineering priorities.
Inverter-driven induction modules are absorbing development resources previously allocated to resistive coil refinement. Residential kitchen designers specify these systems in eighty percent of premium renovation proposals. The technology is absorbing mid-tier price positioning as manufacturing scale reduces bill-of-materials costs.
REACH compliance and RoHS substance restrictions are tightening disclosure requirements for glass-ceramic surface compositions sold in EU member states. Manufacturers must document cadmium and lead content below threshold limits to maintain CE marking validity. German engineering centers are responding with alternative ceramic formulations that preempt anticipated regulatory tightening.
Subscription-based recipe platforms are bundling with hardware purchases, shifting revenue models from one-time equipment sales to recurring content access. Kitchen design studios in North American metropolitan markets are piloting these bundles as standard inclusions. This pattern is most visible in California and New York renovation corridors where smart home integration commands price premiums.
Smart Cooktop Market Segmentation
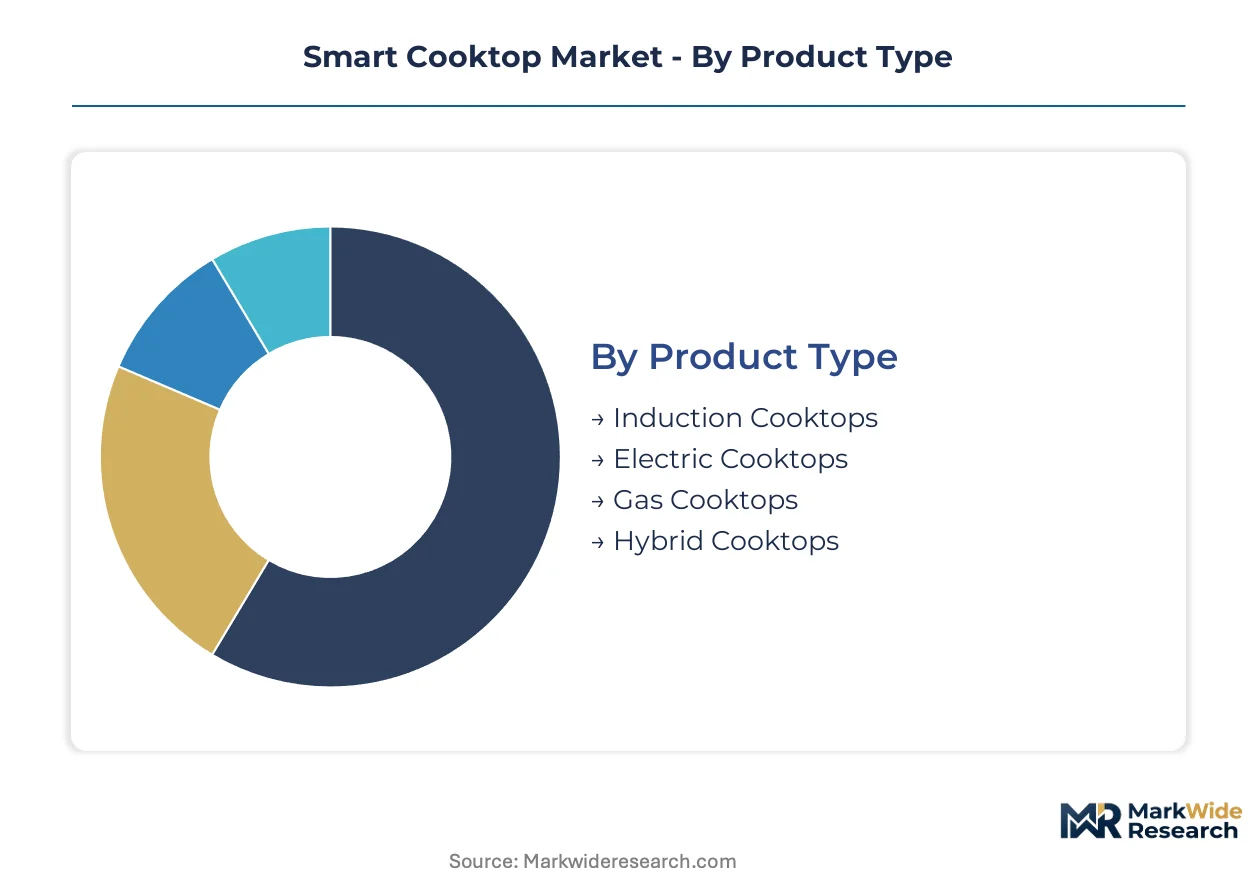
Smart cooktop segmentation reveals how procurement priorities diverge across buyer archetypes. Product specifications, connectivity requirements, and control interfaces map directly to installation budgets and renovation timelines.
Product Type:
Cost tier determines specification trade-offs between energy efficiency and infrastructure compatibility.
- Induction Cooktops:Inverter-driven modules achieve energy transfer efficiency above ninety percent through electromagnetic field generation. Demand concentrates in Germany and California kitchen renovations where EU Ecodesign Directive thresholds and California Title 24 standards mandate high-efficiency replacements.
- Electric Cooktops:Resistive coil and radiant glass-ceramic designs dominate retrofit installations in aging North American housing stock. Procurement persists where electrical panel upgrades for induction amperage requirements prove cost-prohibitive.
- Gas Cooktops:Open-flame combustion systems retain share in commercial kitchens requiring immediate thermal response.
- Hybrid Cooktops:Dual-fuel configurations combine gas burners with electric or induction zones for flexible cooking workflows.
Volume sits with Electric Cooktops; growth tilts toward Induction Cooktops.
End User:
Application intensity shapes durability requirements and connectivity sophistication.
- Residential:Single-family and multi-unit dwellings drive procurement volume through renovation cycles and new construction specifications. Wi-Fi integration and cloud recipe platforms concentrate in metropolitan renovation corridors.
- Commercial:Restaurants, cafeterias, and foodservice operations demand NSF-certified surfaces and rapid thermal cycling capabilities. Procurement emphasizes durability over smart connectivity.
- Industrial:Food processing facilities and institutional kitchens specify heavy-gauge stainless construction with programmable batch controls.
- Hospitality:Hotels and resorts balance aesthetic integration with operational reliability for guest-facing kitchen installations.
Residential captures absolute volume; Hospitality shows steepest expansion trajectory for connected specifications.
Connectivity:
Protocol selection determines ecosystem integration depth and cybersecurity exposure.
- Wi-Fi:Cloud-based recipe synchronization and remote monitoring capabilities position this protocol as the default for premium residential installations. IEEE 802.11 standards enable over-the-air firmware updates.
- Bluetooth:Short-range pairing suits proximity-based control without internet dependency. Adoption concentrates in commercial settings where network isolation reduces attack surface.
- Zigbee:Mesh networking protocols integrate with broader smart home ecosystems including lighting and climate control.
- Ethernet:Wired connectivity serves industrial installations where electromagnetic interference demands shielded data transmission.
Wi-Fi dominates new specification; Zigbee gains share fastest through whole-home integration mandates.
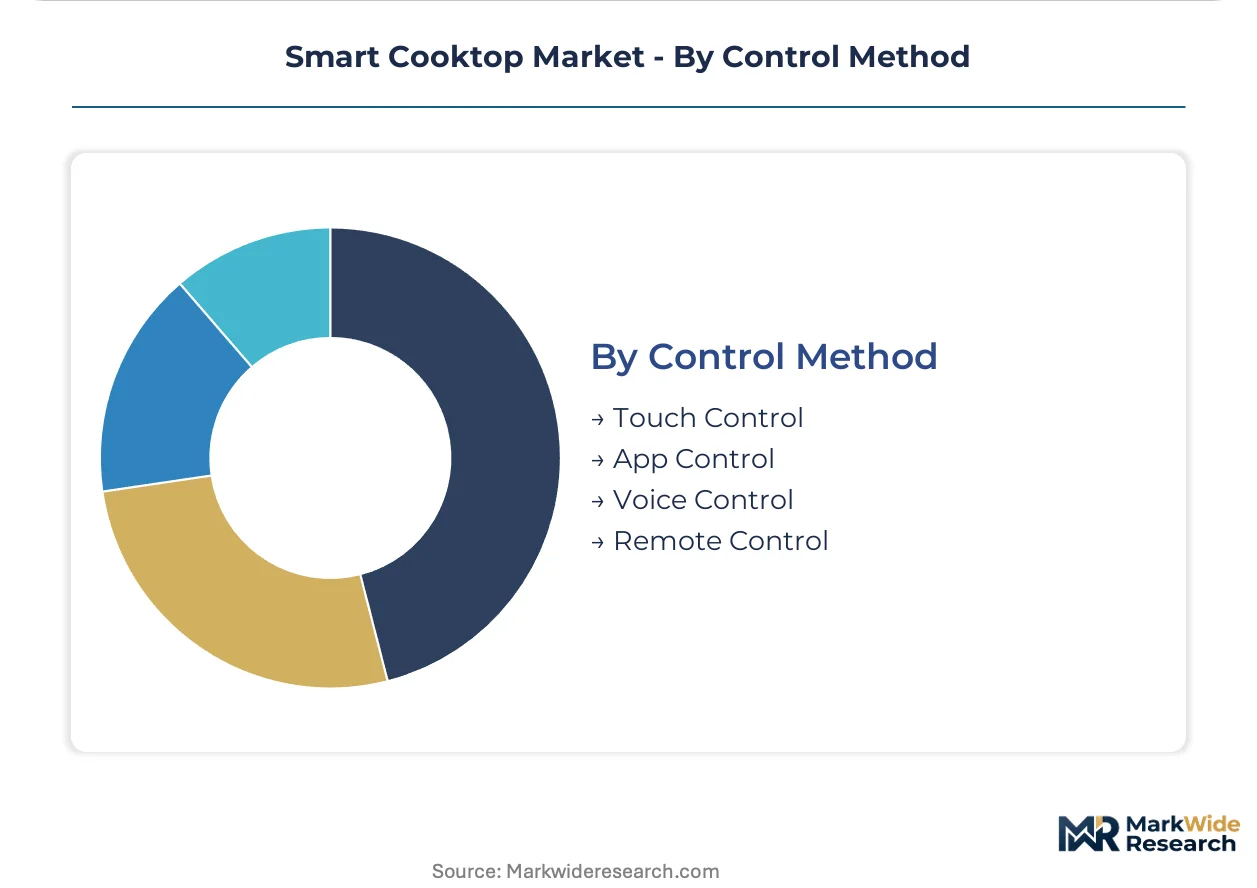
Control Method:
Interface complexity correlates with user technical sophistication and accessibility requirements.
- Touch Control:Capacitive glass surfaces with haptic feedback deliver precision temperature adjustment. German engineering centers lead algorithm development for responsive gesture recognition.
- App Control:Smartphone interfaces enable remote preheating and cooking sequence programming. Subscription-based recipe platforms bundle with hardware purchases in North American metropolitan markets.
- Voice Control:Natural language integration with Alexa and Google Assistant targets accessibility-focused households.
- Remote Control:Dedicated hardware interfaces serve commercial kitchens where staff mobility demands wall-mounted or pendant-mounted operation.
Touch Control maintains volume leadership; App Control expands most quickly through kitchen design studio bundling.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Shenzhen and Ningbo anchor induction coil manufacturing capacity serving export markets, while German engineering clusters drive precision algorithm development for premium residential specifications.
United States
California Title 24 standards and federal rebate programs accelerate high-efficiency cooktop procurement in metropolitan renovation corridors. The Department of Energy maintains efficiency thresholds that disqualify conventional resistive designs from incentive eligibility. Greater Boston and Pacific Northwest kitchen design studios specify Wi-Fi-enabled induction units in eighty percent of premium residential proposals.
Germany
BSH Hausgeräte and Miele anchor premium manufacturing clusters in Bavaria and North Rhine-Westphalia. The EU Ecodesign Directive mandates standby power limits and materials disclosure for glass-ceramic surfaces sold in member states. Munich engineering centers develop precision temperature algorithms that differentiate German offerings in global export markets.
China
Shenzhen and Ningbo manufacturing zones realign capacity toward higher-efficiency inverter modules for North American and European export destinations. GB standards and MIIT certification govern electromagnetic compatibility for induction modules leaving Chinese ports. Yangtze River Delta production clusters absorb development resources previously allocated to resistive coil refinement.
Japan
METI efficiency guidelines and JIS standards shape product specifications for domestic and export-bound induction systems. Osaka-based appliance divisions leverage semiconductor expertise to control smart connectivity architectures. Kansai region manufacturing maintains focus on sensor fusion technologies for automated cooking workflows.
South Korea
Seoul Capital Area conglomerates integrate semiconductor and appliance divisions to control captive supply chains for smart connectivity stacks. MFDS certification requirements and national efficiency benchmarks accelerate replacement cycles in residential renovation markets. Busan-Ulsan industrial zones support component manufacturing for export-oriented finished goods.
Smart Cooktop Market Competitive Environment
Global majors compete with regional champions across connectivity architecture and precision temperature control. The vendor base organizes around three tiers: conglomerates with captive semiconductor supply, specialized engineering houses with algorithm differentiation, and scale-driven manufacturers competing on bill-of-materials optimization. Two dominant competitive moves define current positioning: backward integration into inverter module production and direct-to-installer channel development bypassing traditional retail.
Among South Korea-based conglomerates, Samsung Electronics Co., Ltd. exemplifies vertical integration across semiconductor and appliance divisions. Germany-based specialists BSH Hausgeräte GmbH and Miele & Cie. KG occupy positions anchored by precision engineering developed at Munich-area research centers. These three represent the archetype spectrum from scale-driven connectivity control to algorithm-differentiated premium positioning.
| Leading Market Players |
|---|
| Samsung Electronics Co., Ltd. |
| Whirlpool Corporation |
| LG Electronics Inc. |
| BSH Hausgeräte GmbH |
| Haier Smart Home Co., Ltd. |
| Electrolux AB |
| Panasonic Corporation |
| Miele & Cie. KG |
| GE Appliances |
| Others |
Value Chain & Pricing Dynamics
Certification-grade divergence between CE-marked induction systems and unbundled electric coil alternatives manifests in both procurement premiums and supply chain tiering. Premium residential buyers absorb algorithm-development costs from Munich engineering centers, while retrofit markets gravitate toward standard-grade radiant glass-ceramic sourced through distributor networks.
Pricing Analysis
Warranty and installation-service bundling separates premium induction offerings from unbundled electric coil alternatives in procurement negotiations. Three-tier pricing structure across premium, standard, and economy levels tracks certification complexity and connectivity integration depth. Cost compression in mid-tier induction is intensifying because Chinese inverter module manufacturing scales toward export markets. Residential renovation buyers in Germany and California exhibit lowest price sensitivity, while aging infrastructure retrofit segments in North America resist electrical upgrade costs.
Supply Chain Analysis
Warehouse distribution for finished units runs through regional centers in Germany, the United States, and South Korea serving kitchen design studio networks. Manufacturing draws from Shenzhen and Ningbo for induction coils, German Bavaria for precision control systems, and South Korean semiconductor foundries for connectivity modules. Single-source vulnerability concentrates in specialized glass-ceramic substrate production. Downstream distribution feeds through contractor-direct channels and traditional appliance retail.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Induction technology is displacing resistive coil infrastructure across residential renovation markets, compressing replacement cycles and rewiring competitive positioning around energy efficiency certification.
For Market Incumbents: Deploy precision temperature algorithm development as a defensive moat against Chinese inverter module cost convergence. BSH Hausgeräte and Miele anchor this lever through Munich engineering center investment. Channel control through kitchen design studio exclusivity counters direct-to-installer disruption from Asian manufacturers. Threat: Samsung Electronics' captive semiconductor supply enables connectivity stack underpricing. For New Entrants and Emerging Players: Launch via direct-to-installer distribution bypassing retail margin extraction. White-space concentrates in North American metropolitan retrofit corridors where electrical infrastructure constraints persist. Target commercial hospitality kitchens in California and New York where smart home integration commands specification premiums. Go-to-market: bundle subscription recipe platforms with hardware procurement. For Investors and Strategic Acquirers: Re-rating potential sits with algorithm-differentiated European specialists given EPA Energy Star expansion catalysts. Long-term viability favors engineering houses with in-house temperature control IP over assembly-scale manufacturers. Acquisition archetype: mid-tier induction producers with CE marking pathway and direct installer relationships. Signal to watch: connected standby consumption test criteria inclusion in federal rebate programs.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Inverter Modules | Captive production of electromagnetic components insulates margin from Chinese export pricing volatility. |
| Direct-to-Installer Channel Development | Bypassing retail captures decision authority earlier in California and New York renovation timelines. |
| Precision Algorithm Licensing | Munich-developed temperature control IP generates recurring revenue from OEM partnerships. |
| Subscription Recipe Platform Bundling | Recurring content access shifts revenue model beyond one-time equipment transactions. |
| CE Marking Pre-Compliance Investment | Anticipated REACH tightening on glass-ceramic compositions preserves market access validity. |
Study Parameters
Independent corroboration across appliance manufacturer engineering directors, kitchen design studio procurement leads, and regulatory compliance officers underwrites the qualitative findings. Secondary validation draws from EU Ecodesign Directive implementation documents, U.S. Department of Energy efficiency standard filings, and China MIIT certification databases. Bottom-up unit shipment estimates triangulate against top-down market value reconstruction.
Comparable-period anchoring to historical efficiency standard adoption curves structures the projection horizon. Segmentation modeling spans product type, end-user application, connectivity protocol, and control interface complexity. CAGRs derive from shipment trajectory analysis cross-referenced with average selling price movements. Industry-specific inputs include induction coil manufacturing capacity utilization and glass-ceramic substrate trade flow patterns.
Tariff regime adjustments, electromagnetic compatibility certification delays, and standby power threshold revisions are the dominant revision risks. Forecasts reflect base-case assumptions on regulatory implementation timing and infrastructure upgrade cost trajectories. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Global Stainless Woks Market
Kitchen Appliances
Switzerland Kitchen Appliances Product Market
Kitchen Appliances
Bakeware Market
Kitchen Appliances
UK Cookware Market
Kitchen Appliances
Modular Zero-Waste Kitchen Appliance Market
Kitchen Appliances
Cooktop Market
Kitchen Appliances
Electric Pressure Cooker Market
Kitchen Appliances
Global Single Serve Coffee Maker Market
Kitchen Appliances
Europe Major Home Appliances Market
Kitchen Appliances
South Korea Kitchen Appliances Market
Kitchen Appliances
Temperature Controlled Mug Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Induction Stove Market
Kitchen Appliances
Germany Kitchen Appliances Market
Kitchen Appliances
Electric Lunch Box Market
Kitchen Appliances
Self-Heating Butter Knife Market