
 Built-In Kitchen Appliances Market | 2026-2036
Built-In Kitchen Appliances Market Size, Share, and Industry Trends Forecast 2026-2036
Built-In Kitchen Appliances Market Analysis
The EU Ecodesign Framework is broadening the cost-of-entry calculus for built-in appliance manufacturers targeting European markets. Bosch leverages its captive motor and compressor production to absorb compliance costs without outsourcing. Samsung anchors its position through vertical control over semiconductor and display supply for smart oven interfaces. Miele specializes in super-premium segments where energy-label thresholds function as brand validators rather than cost burdens.
Built-in kitchen appliances comprise factory-integrated cooking, cooling, cleaning, and heating equipment designed for permanent cabinet enclosure, typically operating at 220-240V with standardized cutout dimensions. These systems serve residential and commercial food preparation environments where space optimization and aesthetic continuity drive specification decisions. Ovens and dishwashers command the deepest margin pools as replacement cycles compress and smart connectivity becomes standard. Energy-efficient technology segments are pulling ahead of conventional alternatives as utility rebates and building codes harden efficiency floors. The residential end-user channel generates the highest absolute volume, though hospitality procurement concentrates purchasing power and demands extended service contracts.
The US Department of Energy maintains separate test procedures for built-in versus freestanding cooking equipment, creating dual certification burdens for manufacturers serving both categories. China's GB standards and the EU's Ecodesign Directive together shape the baseline efficiency architecture that most global production lines must accommodate. Stakeholders must monitor whether emerging material disclosure requirements in European markets will cascade into supply-chain requalification costs for stainless steel and insulation components.
Market Dynamics
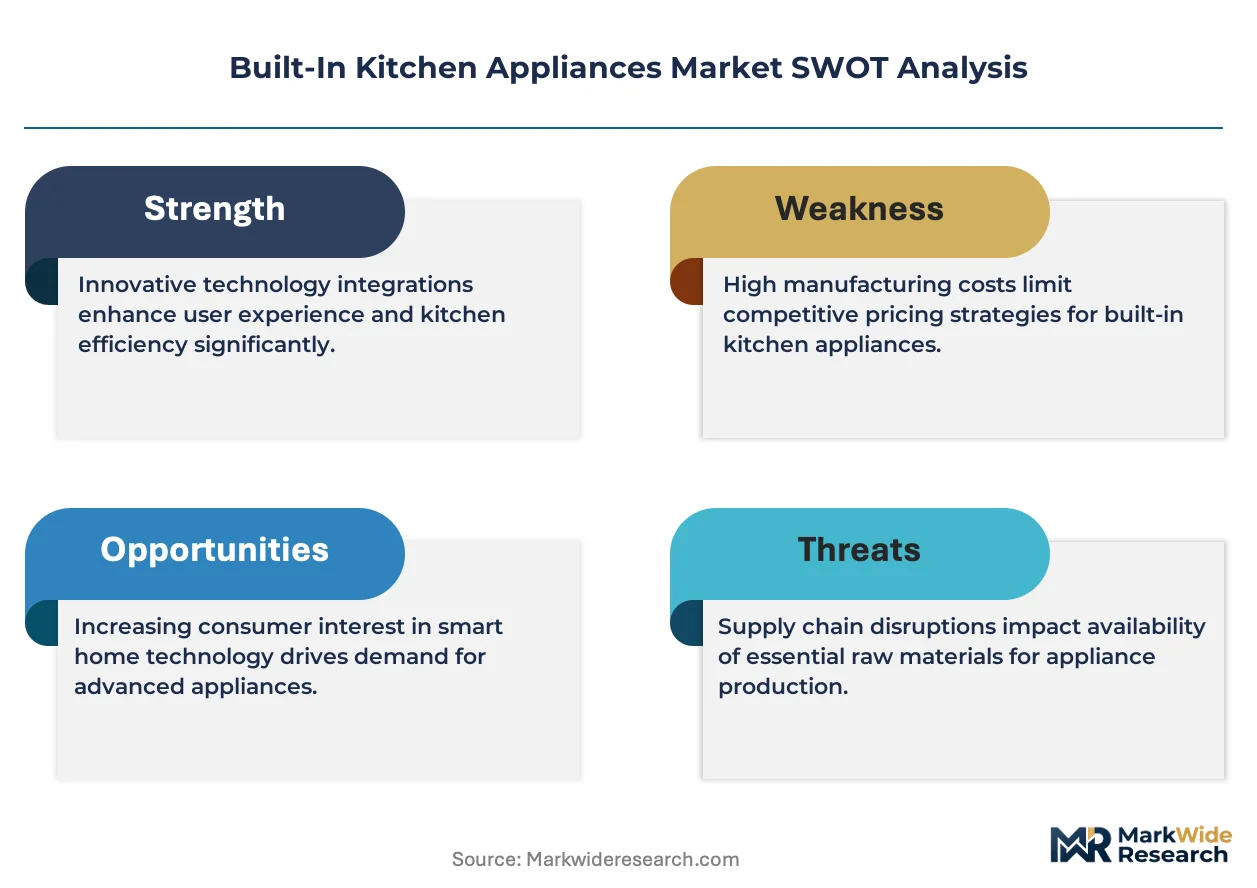
The EU Ecodesign Framework is compressing replacement cycles while simultaneously raising manufacturing cost floors, forcing specification decisions toward integrated smart systems that bundle energy compliance with connectivity premiums.
Growth Catalysts
- EU Ecodesign Directive:Tightening minimum efficiency thresholds for ovens and dishwashers are accelerating upgrade demand in Germany's premium housing corridors around Munich and Stuttgart.
- Connected appliance packages:Residential developers in suburban North America are specifying factory-integrated smart kitchen ecosystems as standard in new construction.
- Semiconductor-enabled interfaces:Touch-display convergence with cooking controls is electrifying consumer willingness to pay for premium built-in configurations.
Market Restraints
- Stainless steel and insulation supply chains:Emerging material disclosure requirements in European markets threaten cascading requalification costs for thermal components.
- Dual certification architecture:The US Department of Energy maintains separate test procedures for built-in versus freestanding cooking equipment, fragmenting production line economics.
- China GB standards alignment:Baseline efficiency requirements under China's national standards create design lock-in that limits product architecture flexibility for export markets.
Strategic Opportunities
- Utility rebate programs:Energy-efficient technology segments are pulling ahead as building codes harden efficiency floors and municipal incentives concentrate demand.
- Hospitality procurement consolidation:Extended service contract bundling creates purchasing power concentration among hotel and restaurant chains seeking lifecycle cost certainty.
- Induction cooking convergence:Electrification mandates in residential building codes are creating white space for full-kitchen induction packages that replace gas infrastructure.
Industry Challenges
- Embedded systems engineering talent:Smart connectivity integration requires firmware and IoT security capabilities that appliance manufacturers historically outsourced.
- Legacy kitchen footprint incompatibility:Standardized 220-240V cutout dimensions limit retrofit flexibility when upgrading from conventional to connected appliance generations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Built-In Kitchen Appliances Market |
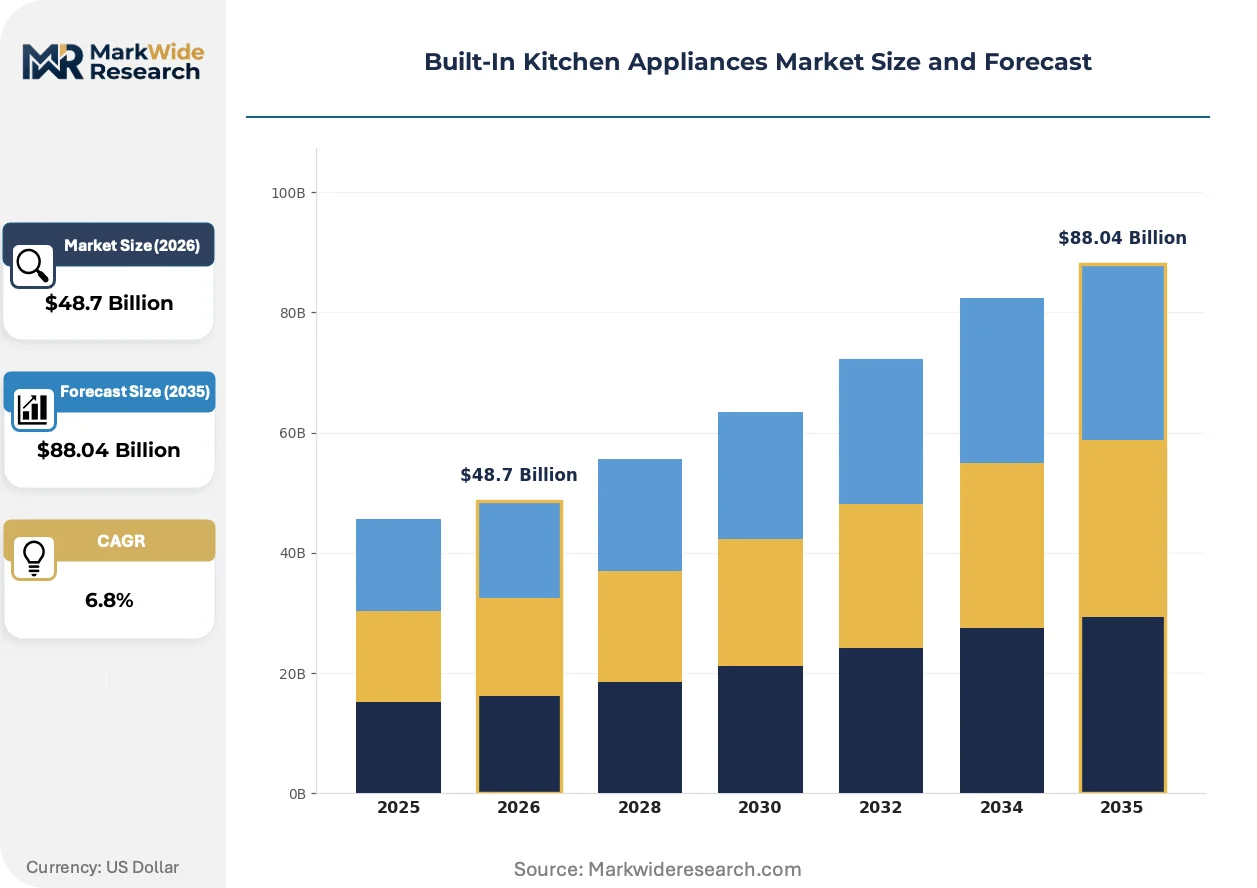
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ovens, Dishwashers, Refrigerators, Microwaves Technology: Smart Technology, Energy-Efficient, Induction, Conventional End User: Residential, Commercial, Hospitality, Real Estate Installation Type: New Construction, Remodeling, Renovation, Retrofit |
| Companies Covered | LG, Electrolux, Bosch, Haier, Miele, Siemens, Samsung, Gaggenau, Whirlpool, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Built-In Kitchen Appliances Market Emerging Trajectories
Electrification of cooking surfaces is converging with semiconductor-driven interface layers, compressing the boundary between thermal engineering and consumer electronics.
Induction coil technology is electrifying residential cooking infrastructure. High-end residential developers in Germany and the Netherlands are specifying full-induction kitchens as standard. This shift is compressing demand for traditional radiant and gas cooking surfaces while expanding power electronics content per appliance unit.
The EU F-Gas Regulation is tightening refrigerant containment requirements for built-in cooling appliances. Manufacturers must redesign compressor architectures and sealing systems to accommodate lower-GWP alternatives. Premium built-in refrigerator lines targeting Scandinavian markets are responding with propane-isobutane blend transitions ahead of mandate timelines.
Builder-direct specification is displacing retail channel influence in new residential construction. North American production homebuilders are consolidating appliance procurement through national distribution agreements that bypass traditional dealer networks. This concentration is most visible in Arizona, Texas, and Florida master-planned communities where design centers bundle appliance packages with mortgage financing.
Built-In Kitchen Appliances Market Segmentation
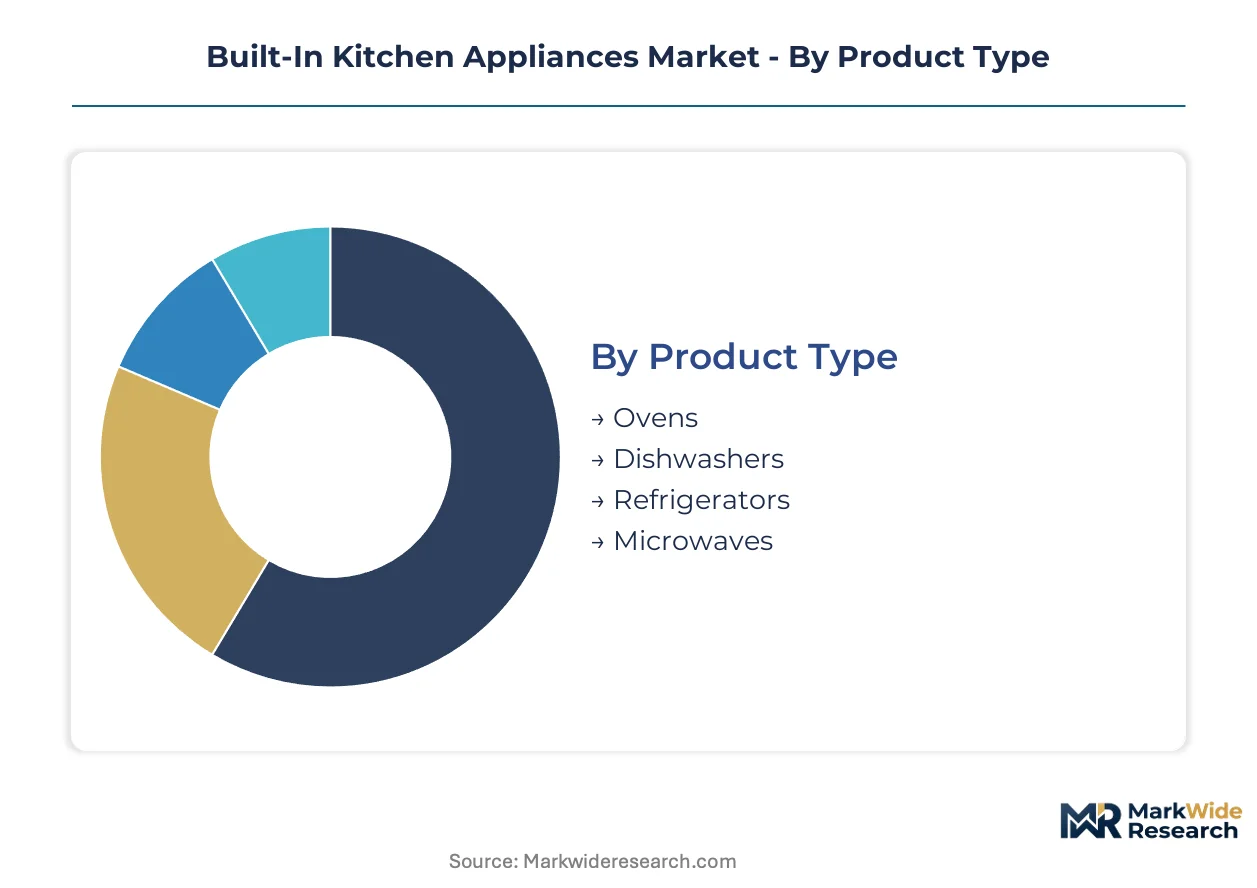
Segmentation in built-in kitchen appliances reveals how integration depth, energy compliance tiers, and specification channels fragment demand. Manufacturers must align product architectures with distinct margin pools and certification burdens across each dimension.
Product Type:
Integration depth varies sharply—ovens and dishwashers anchor permanent cabinet enclosures while refrigerators and microwaves accommodate more modular replacement pathways.
- Ovens:Factory-integrated thermal systems with standardized 220-240V cutouts and semiconductor-enabled touch interfaces. Demand clusters in Germany's premium housing corridors around Munich and Stuttgart where EU Ecodesign thresholds accelerate replacement cycles.
- Dishwashers:Built-in cleaning equipment with captive water connections and energy-label compliance architecture. North American suburban developers specify these as standard in connected appliance packages for new residential construction.
- Refrigerators:Cabinet-enclosed cooling systems with compressor and sealing systems redesigned for lower-GWP refrigerant blends under EU F-Gas Regulation timelines.
- Microwaves:Compact built-in units with standardized dimensions allowing retrofit flexibility where full kitchen reconfiguration is cost-prohibitive.
Volume placements concentrate in Ovens; the faster expansion belongs to Dishwashers.
Technology:
Cost tier stratification separates premium smart systems from compliance-driven efficiency upgrades and legacy conventional alternatives.
- Smart Technology:IoT-enabled appliances with firmware-integrated cooking controls and display convergence. Semiconductor supply constraints and embedded systems engineering scarcity limit manufacturer participation.
- Energy-Efficient:Products engineered to exceed baseline efficiency thresholds under EU Ecodesign and China GB standards. Utility rebate programs in municipal jurisdictions harden demand concentration.
- Induction:Electrified cooking surfaces replacing gas infrastructure under residential building code mandates. Full-kitchen induction packages gain traction with high-end developers in Germany and the Netherlands.
- Conventional:Legacy radiant and gas cooking surfaces facing demand compression as electrification mandates expand and replacement cycles shorten.
Shipments stratify across Energy-Efficient and Conventional tiers; Induction climbs the fastest as building codes eliminate gas infrastructure.
End User:
Application context dictates service contract structures, procurement concentration, and aesthetic specification intensity.
- Residential:Individual homeowners and multifamily occupants prioritizing space optimization and aesthetic continuity with cabinet systems. Highest absolute volume channel with fragmented purchasing power.
- Commercial:Restaurant and foodservice operations demanding durability cycles and rapid service response. Extended service contract bundling concentrates purchasing power among chain operators.
- Hospitality:Hotel procurement functions seeking lifecycle cost certainty through national distribution agreements. Brand standards enforcement drives specification consistency across properties.
- Real Estate:Production homebuilders and residential developers bundling appliance packages with mortgage financing. North American builder-direct specification in Arizona, Texas, and Florida master-planned communities bypasses traditional dealer networks.
Absolute volume concentrates in Residential; Hospitality procurement delivers the steepest expansion trajectory through service contract bundling.
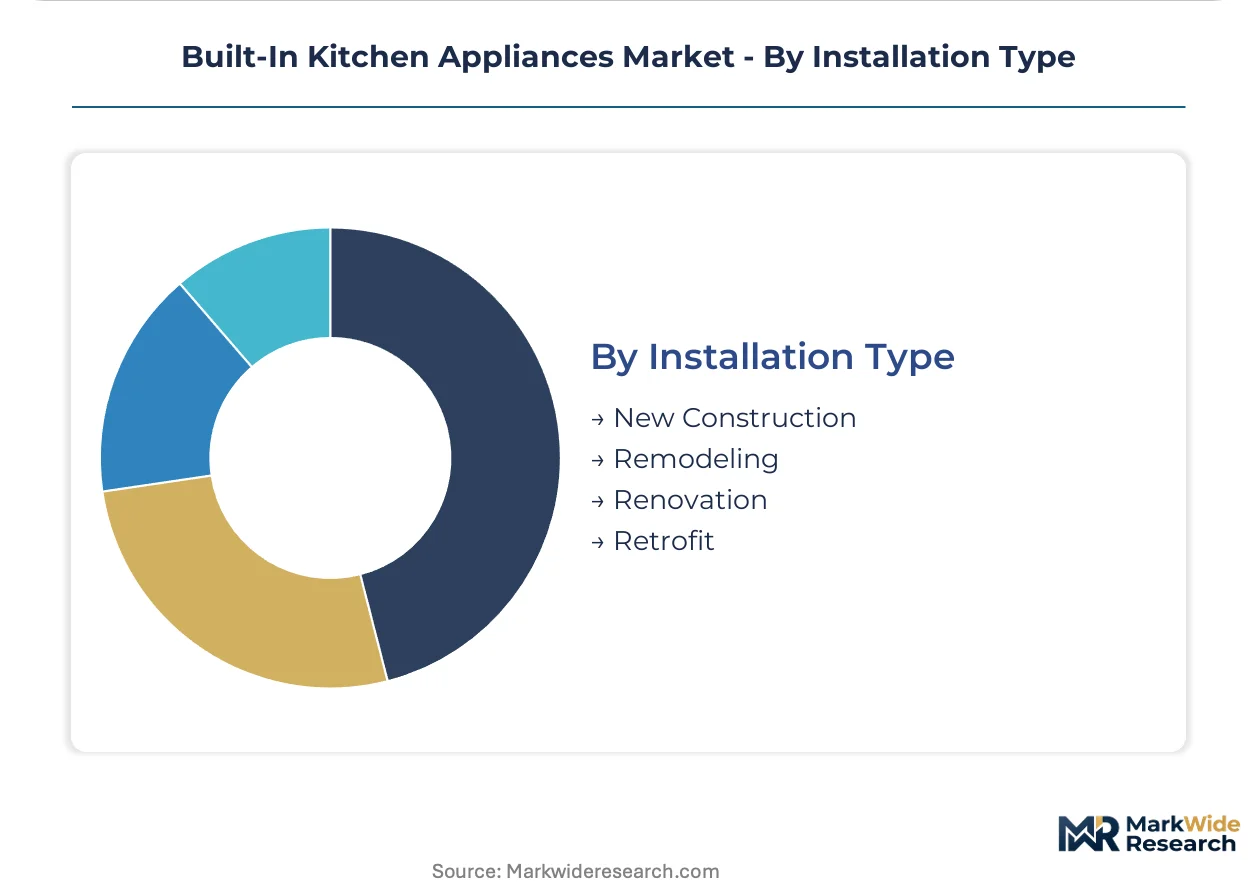
Installation Type:
Customer type and project phase determine specification authority, margin capture, and retrofit constraint severity.
- New Construction:Builder-direct procurement with design-center bundling and national distribution agreements. Standardized cutout dimensions enable factory-integrated smart kitchen ecosystems.
- Remodeling:Partial kitchen reconfiguration preserving existing cabinet footprints while upgrading core appliances. Power electronics and interface layers drive premium willingness-to-pay.
- Renovation:Comprehensive kitchen reconstruction allowing full appliance replacement and infrastructure modernization. Induction cooking convergence creates white space for electrification package sales.
- Retrofit:Appliance replacement within legacy 220-240V cutout dimensions limiting smart connectivity integration without cabinet modification.
Project flow concentrates in New Construction; Renovation activity is expanding most quickly as housing stock ages and electrification mandates intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free trade zones in Southeast Asia and Mexico's IMMEX program are drawing component assembly for export markets. Subsidized industrial parks in China's interior provinces compete with Eastern European special economic zones for final-assembly investment. These tax-advantaged locations concentrate production serving premium housing corridors in developed economies.
United States
Suburban master-planned communities in Arizona, Texas, and Florida drive builder-direct procurement of connected appliance packages. The Department of Energy maintains separate test procedures for built-in versus freestanding equipment, fragmenting certification burdens. Atlanta and Dallas housing corridors concentrate specification activity where national distribution agreements bypass traditional dealer networks.
Germany
Premium housing developments around Munich and Stuttgart accelerate replacement cycles under tightening EU Ecodesign thresholds. The F-Gas Regulation forces refrigerant transitions in built-in cooling appliances ahead of mandate timelines. Bavaria's industrial corridor anchors captive motor and compressor production serving compliance-driven efficiency upgrades.
China
GB standards alignment creates design lock-in limiting product architecture flexibility for export markets. The MIIT oversees national efficiency benchmarks that shape baseline production specifications. Yangtze River Delta manufacturing clusters supply semiconductor-enabled interfaces for smart oven convergence.
Netherlands
High-end residential developers specify full-induction kitchens as standard under electrification mandates. The national building code eliminates gas infrastructure in new construction, expanding power electronics content per unit. Randstad urban corridors concentrate demand for factory-integrated smart kitchen ecosystems.
Japan
METI efficiency programs drive premium-tier specification in compact urban housing formats. JIS standards govern cutout dimensions and voltage compatibility for retrofit-constrained installations. Tokyo and Osaka metropolitan areas concentrate replacement demand where legacy footprint incompatibility limits smart connectivity integration.
Built-In Kitchen Appliances Market Vendor Landscape
German producers anchor the premium-engineering tier; Korean and Chinese fabricators hold scale-driven positions in smart connectivity and cost-optimized segments. The vendor base stratifies across three structural archetypes: captive-component manufacturers absorbing compliance costs internally, semiconductor-integrated specialists controlling display and interface supply, and super-premium brands where regulatory thresholds validate positioning. Consolidation pressure runs through M&A activity targeting IoT firmware capabilities and strategic partnerships securing extended service contract channels.
Within the captive-supply archetype, Bosch and Siemens exemplify backward integration into motors and compressors that contains Ecodesign compliance costs. Samsung occupies a position bridging semiconductor control with appliance-scale manufacturing. Miele anchors the super-premium tier where energy-label thresholds function as brand validators rather than cost burdens.
| Leading Market Players |
|---|
| LG |
| Electrolux |
| Bosch |
| Haier |
| Miele |
| Siemens |
| Samsung |
| Gaggenau |
| Whirlpool |
| Others |
Supply Flow & Price Mechanics
Stainless steel coil indices from the Yangtze River Delta and European hot-rolled steel benchmarks cascade through built-in appliance manufacturing into three distinct pricing tiers, with premium smart systems capturing connectivity premiums while compliance-driven efficiency upgrades absorb margin compression from refrigerant and motor redesigns.
Pricing Analysis
Lead-time-driven pricing stratification rewards builder-direct procurement with volume discounts while spot inventory clearance commands steep markdowns. Three-tier pricing structure across premium smart, standard efficient, and economy conventional levels separates Miele's super-premium positioning from Samsung's semiconductor-integrated mid-tier and Haier's cost-optimized base offerings. Pricing pressure stems from EU Ecodesign compliance costs and F-Gas refrigerant transitions compressing margins in cooling segments. Real estate developers exhibit lowest price sensitivity through bundled mortgage financing, while individual retail retrofit buyers face highest sticker shock from cabinet modification requirements.
Supply Chain Analysis
Workforce availability constraints in China's Jiangsu and Zhejiang provinces, alongside skilled technician shortages in Mexico's Baja California corridor, are reshaping component assembly location decisions. Manufacturing concentrates in China, Germany, and Mexico with component flows drawing from Taiwan's semiconductor foundries and South Korea's display panel producers. Raw material dependencies rest on nickel-alloy stainless steels, rare-earth magnets for compressor motors, and copper winding stock. Single-source vulnerability in semiconductor-enabled touch controllers threatens production continuity. Distribution runs through national builder-direct agreements bypassing traditional dealer networks in North American suburban markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The built-in kitchen appliances market is becoming a vertical-integration race where captive motor, compressor, and semiconductor production determines who absorbs regulatory compliance costs without outsourcing margin.
For Market Incumbents: Lock in captive supply of motors and compressors to contain Ecodesign cost absorption, while securing long-term semiconductor allocation agreements for smart interface production. Threat from induction cooking mandates in Germany and the Netherlands accelerates demand for power electronics capabilities that traditional thermal engineering teams lack. Channel control through national distribution agreements with production homebuilders in Arizona, Texas, and Florida defends volume positions against retail erosion. For New Entrants and Emerging Players: Direct-to-builder digital specification platforms offer white-space entry around hospitality procurement consolidation, where extended service contract bundling concentrates purchasing power among hotel chains seeking lifecycle cost certainty. The most penetrable segment sits in commercial foodservice operations demanding rapid service response outside incumbent warranty networks. Target induction retrofit packages in aging European housing stock where gas infrastructure elimination creates replacement demand without new construction volume requirements. For Investors and Strategic Acquirers: Distressed-cycle entries favor IoT firmware specialists with appliance integration capabilities in Germany's Bavarian industrial corridor, where Ecodesign compliance investments have strained mid-tier engineering resources. Long-term viability hinges on semiconductor interface control and refrigerant transition readiness across the next decade. Watch for inflection signals in utility rebate program expansion rates, which concentrate demand for energy-efficient technology segments and validate premium pricing power.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Motors and Compressors | Bosch's captive production absorbs EU Ecodesign compliance costs without outsourcing margin to suppliers. |
| Semiconductor Supply Agreement for Smart Interfaces | Samsung's vertical control over display and chip supply secures allocation priority during foundry constraints. |
| Builder-Direct National Distribution Partnership | Production homebuilders in Arizona, Texas, and Florida bypass dealer networks to capture bundled financing premiums. |
| Refrigerant Transition Engineering Investment | Propane-isobutane blend redesigns under EU F-Gas Regulation timelines open premium positioning in Scandinavian markets. |
| Extended Service Contract Channel Development | Hospitality procurement consolidation among hotel chains creates lifecycle revenue streams beyond unit sales. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, while primary interviews with appliance manufacturing executives, residential development procurement directors, hospitality facility managers, and semiconductor supply chain specialists provided operational validation. Secondary sources included EU Ecodesign Directive implementation reports, US Department of Energy certification databases, China MIIT efficiency benchmark disclosures, and builder-direct distribution agreement filings. Bottom-up shipment data from component suppliers reconciled against top-down demand estimates from housing construction permits and replacement cycle modeling.
Data-stream reconciliation across product type, technology tier, end-user channel, and installation phase segmentation generated volume and value outputs over the projection horizon. CAGRs derived from historical replacement cycle compression rates, electrification mandate adoption curves, and smart connectivity penetration trajectories. Industry-specific forecast inputs incorporated EU F-Gas Regulation compliance timelines and North American utility rebate program expansion patterns.
Inputs from trade associations and regulatory bodies were available through the study window; gaps in real-time semiconductor allocation data and builder-direct contract terms introduce uncertainty bands around smart technology segment projections. Forecasts reflect assumptions regarding electrification mandate enforcement consistency and refrigerant transition engineering timelines. A small set of named triggers—utility rebate program expansion, F-Gas Regulation acceleration, and semiconductor supply normalization—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Capsule Coffee Machines Market
Kitchen Appliances
Europe Air Fryers Market
Kitchen Appliances
Global Portable Blenders Market
Kitchen Appliances
US Induction Cookware Market
Kitchen Appliances
Asia Pacific Household Electric Grills Market
Kitchen Appliances
Residential Hobs Market
Kitchen Appliances
Mexico Kitchen Appliances Products Market
Kitchen Appliances
Cake Pans Market
Kitchen Appliances
Portable Sandwich Maker Market
Kitchen Appliances
Smart Induction Cooktop Market
Kitchen Appliances
Luxury Kitchen Appliances Market
Kitchen Appliances
Pressure Cooker Market
Kitchen Appliances
Air Fryer Accessories Market
Kitchen Appliances
Europe Household Side by Side Refrigerator Market
Kitchen Appliances
Tabletop Kitchen Products Market
Kitchen Appliances
Europe Small Kitchen Appliances Market