
 Cooktop Market | 2026-2036
Cooktop Market Size, Share, and Industry Trends Forecast 2026-2036
Cooktop Market Analysis
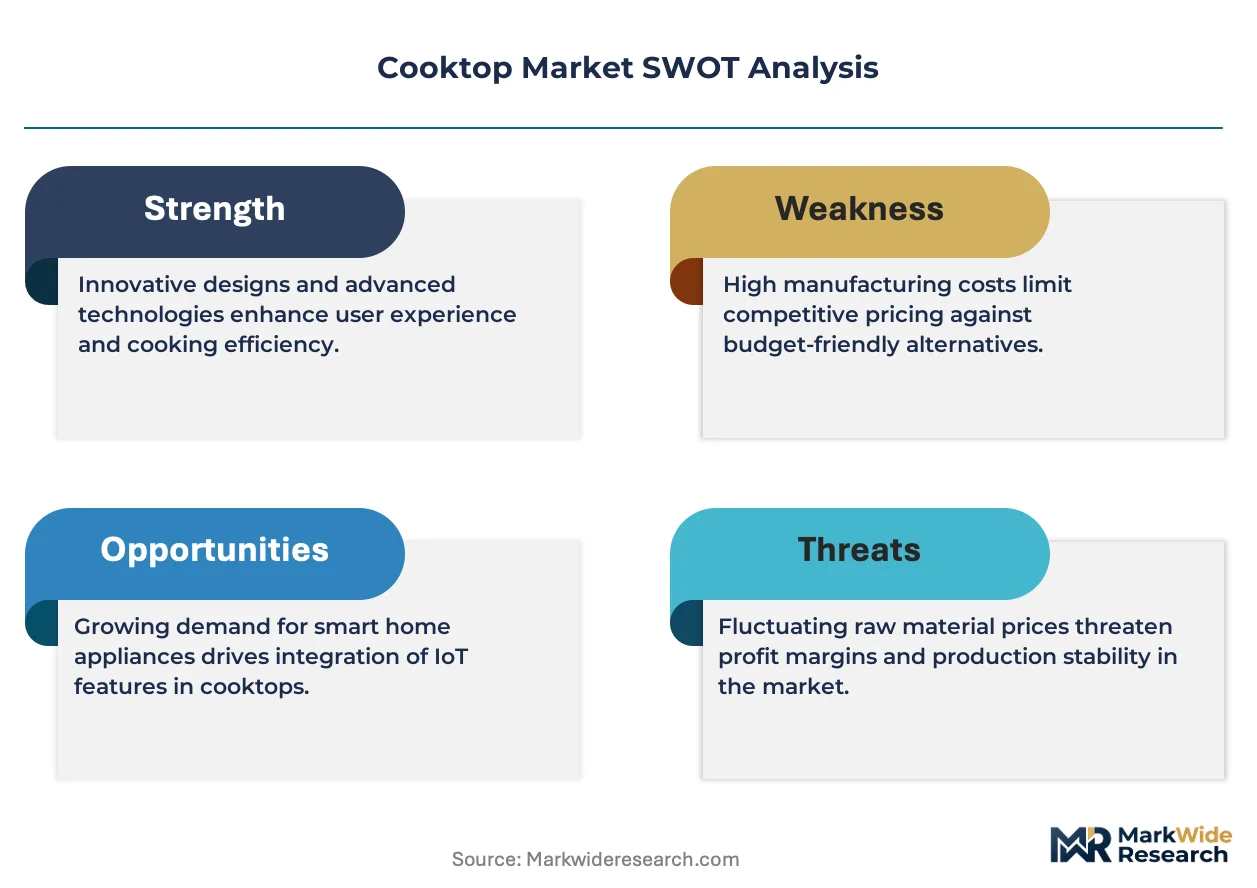
Project finance for smart kitchen ecosystems is narrowing the competitive field to manufacturers with balance-sheet depth. BSH Hausgeräte GmbH leverages captive financing programs to anchor premium induction lines in European markets. Whirlpool Corporation sustains volume competitiveness through manufacturing scale across North American plants. Samsung Electronics differentiates via smart technology integration that extends software monetization beyond hardware margins.
A cooktop is a flat heating appliance installed into kitchen countertops, typically employing resistive electric coils, sealed gas burners, or electromagnetic induction coils beneath a ceramic glass surface to transfer thermal energy directly to cookware. Induction cooktops achieve efficiency rates above 80% by generating heat within the vessel itself rather than the cooking surface. Electric segments occupy the largest installed base globally, while induction categories represent the fastest-growing margin pool as energy codes tighten. Smart technology integration commands premium positioning, though knob control variants retain dominance in commercial kitchens where durability outweighs connectivity demands.
EPA ENERGY STAR specifications in the United States and EU Ecodesign requirements collectively reshape product development priorities toward efficiency benchmarking and standby power reduction. China's GB standards and NMPA-aligned safety certifications govern electromagnetic compatibility thresholds for induction systems entering domestic channels. Stakeholders must monitor regulatory divergence between efficiency-first European frameworks and performance-oriented North American testing protocols when allocating R&D budgets across regional portfolios.
Market Dynamics
The EU Ecodesign Directive is compressing gas cooktop replacement cycles across member states, forcing manufacturers to reallocate production capacity toward electromagnetic induction platforms ahead of hardware obsolescence mandates.
Growth Catalysts
- EU Ecodesign Directive:Tightening efficiency thresholds in Germany, France, and Italy are accelerating gas-to-electric transitions in residential kitchen renovations.
- Induction coil efficiency:Electromagnetic heating platforms achieve thermal transfer rates above 80%, reducing household energy consumption and utility bills.
- Urban kitchen renovation cycles:China's tier-one cities are compressing appliance replacement timelines as property turnover accelerates in Beijing and Shanghai.
Market Restraints
- Copper and ferrite magnet cost volatility:Input price swings for induction coil materials compress margin stability for mid-tier manufacturers.
- Electrical infrastructure gaps:Rural and aging urban grids in parts of Eastern Europe and South Asia limit induction adoption despite regulatory pressure.
- Gas distribution network lock-in:Existing pipeline infrastructure in the Netherlands and UK creates switching friction for households.
Strategic Opportunities
- India's electrification push:Rural household connectivity expansion under the Saubhagya scheme opens first-time appliance markets for basic induction units.
- Smart kitchen ecosystem convergence:Integration of cooktops with voice-assistant platforms and recipe applications creates software monetization layers beyond hardware sales.
- Commercial kitchen retrofit demand:Food service operators in Singapore and Dubai are replacing gas lines with induction banks to meet indoor air quality codes.
Industry Challenges
- Electromagnetic compatibility certification:NMPA-aligned safety testing in China and FCC Part 18 compliance in the United States create divergent approval timelines.
- Skilled installation technician shortages:Induction unit deployment requires certified electrical work, constraining rollout velocity in markets with thin contractor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cooktop Market |
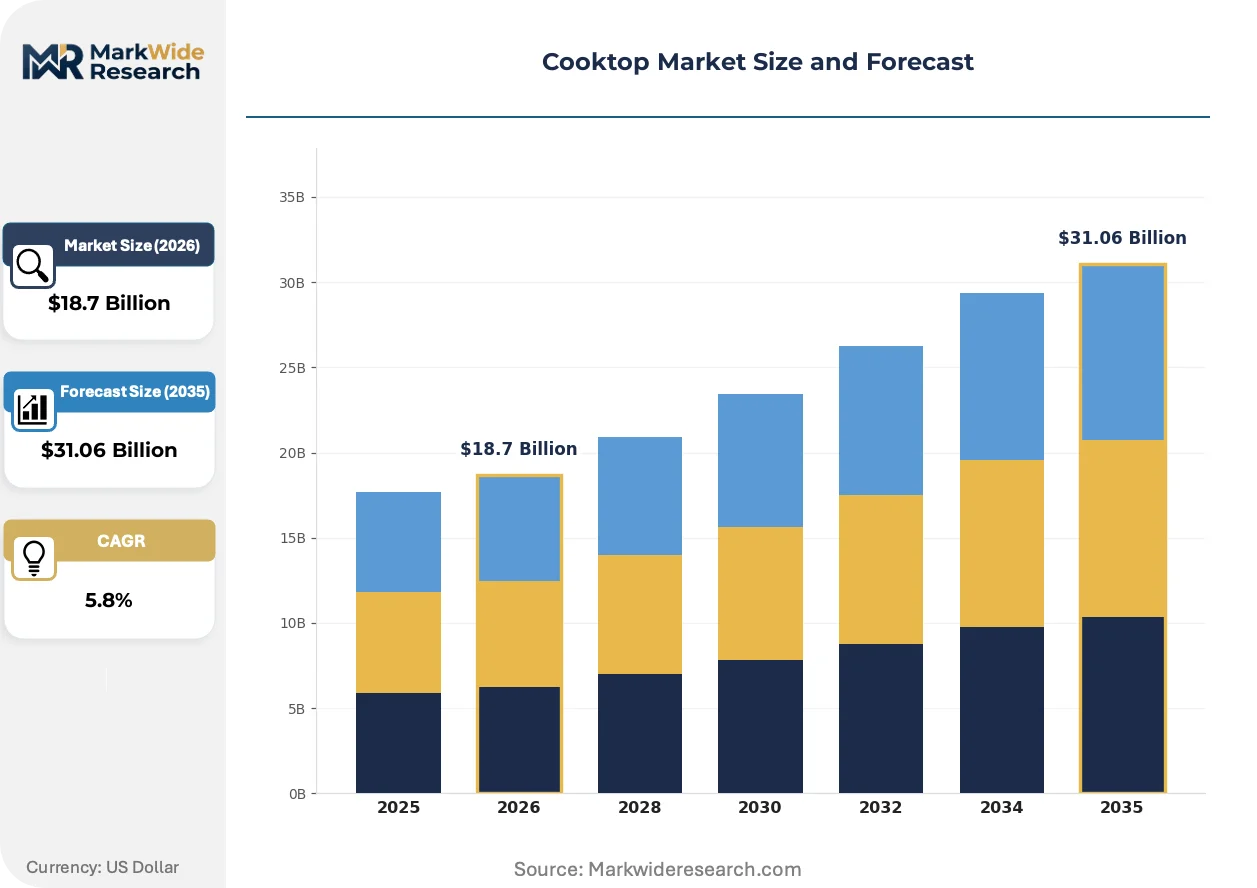
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Gas, Induction, Hybrid Technology: Touch Control, Knob Control, Smart Technology, Built-in End User: Residential, Commercial, Hospitality, Institutional Size: 30-inch, 36-inch, 24-inch, 48-inch |
| Companies Covered | BSH Hausgeräte GmbH, Miele & Cie. KG, Whirlpool Corporation, Electrolux AB, Samsung Electronics, LG Electronics, Haier, Panasonic Holdings Corporation, Smeg S.p.A, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cooktop Market Emerging Trajectories
Product development trajectories center on efficiency benchmarking, connectivity integration, and material substitution as regulatory thresholds tighten and end-use expectations shift toward seamless kitchen ecosystems.
Induction coil technology is hybridizing with traditional resistive elements in flexible-zone cooktops that automatically detect cookware placement and size. Residential builders in suburban US developments are specifying these hybrid platforms to satisfy buyer demand for gas-like responsiveness with electric compliance. This convergence is compressing the pure gas cooktop installed base in new construction while expanding the addressable market for premium electric lines.
EPA ENERGY STAR specifications in the United States are mandating standby power reduction below one watt, forcing firmware and power-management redesigns across induction product lines. Manufacturers serving the North American market are re-engineering control boards and display systems to meet these thresholds. The specification most heavily affects entry-level electric coil segments where cost-engineered designs previously ignored phantom load.
Builder procurement patterns are consolidating around smart-home platform compatibility as a non-negotiable specification. Large-scale residential developers in Germany and California are requiring cooktop-to-hub connectivity as standard, displacing knob-control variants in premium tract housing. This specification cascade is most visible in master-planned communities where technology integration serves as a marketing differentiator against competing developments.
Cooktop Market Segmentation
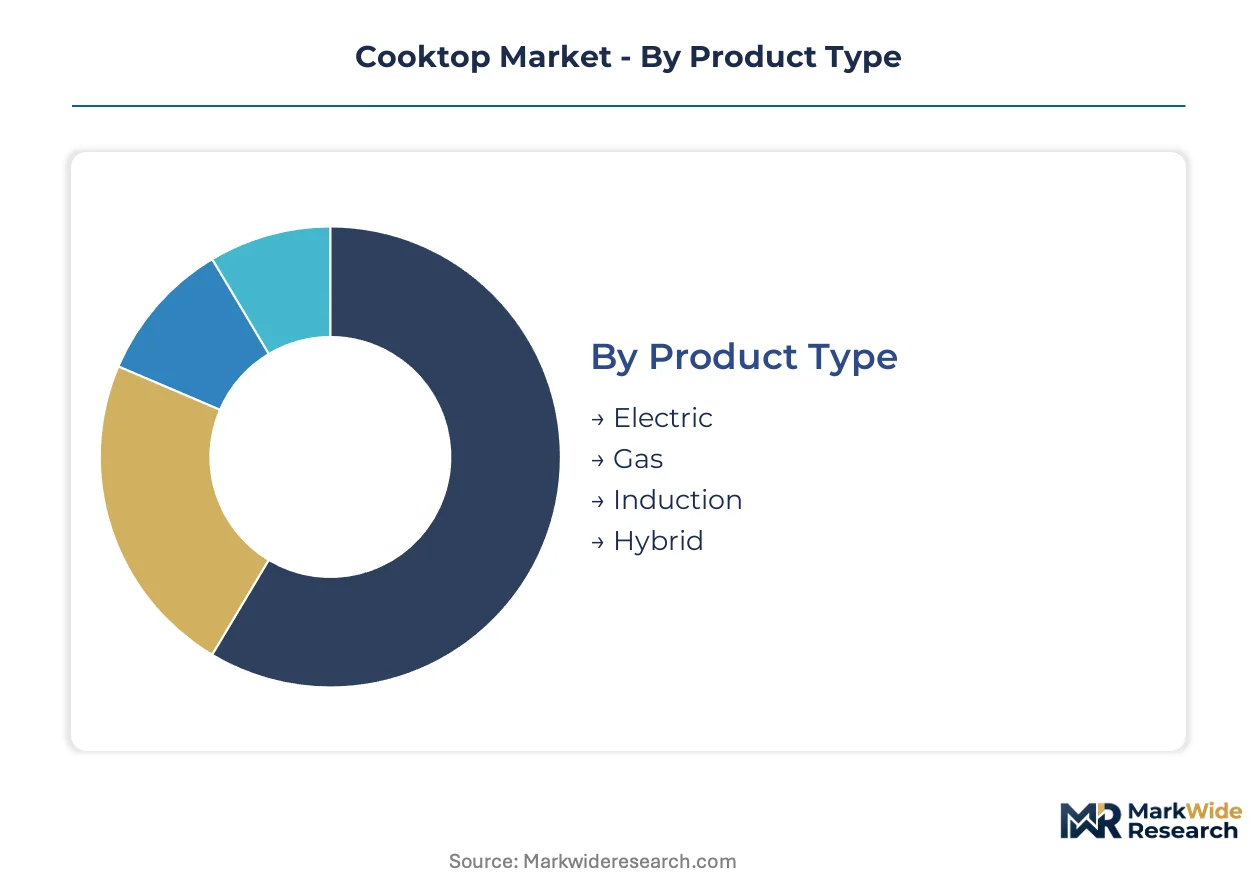
Cooktop segmentation reveals divergent technology adoption curves across residential renovation cycles and commercial retrofit mandates. Product architecture choices directly constrain installation requirements, energy compliance pathways, and margin capture potential for manufacturers.
Product Type:
Residential kitchens span a spectrum from legacy gas infrastructure to code-driven electric conversion, with efficiency benchmarks and grid readiness dictating platform selection.
- Electric:Resistive coil and smooth-top radiant elements constitute the largest installed base globally. Demand concentrates in North American suburban housing stock where 240V infrastructure is standard and replacement cycles align with kitchen renovation timelines.
- Induction:Electromagnetic coil systems achieve thermal efficiency above 80% by generating heat within cookware rather than the surface. EU member states are compressing replacement cycles as Ecodesign Directive thresholds tighten, while China's tier-one cities accelerate adoption amid urban kitchen renovation booms in Beijing and Shanghai.
- Gas:Sealed burner systems retain dominance in markets with established pipeline distribution networks. The Netherlands and UK face switching friction from existing infrastructure lock-in despite regulatory pressure.
- Hybrid:Dual-fuel configurations combining gas burners with electric ovens face declining specification rates as all-electric building codes proliferate across California and German federal states.
Established volume favors Electric; emerging adoption favors Induction.
Technology:
Control interfaces differentiate price tiers and determine smart ecosystem integration depth for builder specifications and consumer replacement decisions.
- Knob Control:Mechanical dial interfaces dominate commercial kitchen specifications where durability and intuitive operation outweigh connectivity demands. Food service operators in Singapore and Dubai prioritize reliability over digital features when retrofitting induction banks for indoor air quality compliance.
- Smart Technology:WiFi-enabled platforms with voice-assistant integration and recipe application connectivity command premium positioning. Large-scale residential developers in Germany and California require cooktop-to-hub compatibility as standard in master-planned communities.
- Touch Control:Capacitive glass interfaces bridge analog reliability with modern aesthetics. Mid-tier residential renovations in China's tier-two cities favor these systems for cost-conscious kitchen upgrades.
- Built-in:Seamless countertop integration with downdraft ventilation or modular cooking suites targets luxury kitchen specifications. Custom home builders in suburban US developments specify these for buyer differentiation.
Knob Control anchors commercial durability requirements; Smart Technology captures residential premiumization.
End User:
Application environments impose divergent performance, certification, and lifecycle cost thresholds that reshape product development priorities.
- Residential:Single-family and multi-family housing units drive replacement demand through renovation cycles. China's urban property turnover accelerates appliance refresh timelines in Beijing and Shanghai.
- Commercial:Restaurants, catering operations, and food service establishments prioritize throughput and ventilation compliance. Operators in Singapore and Dubai are replacing gas lines with induction banks to meet indoor air quality codes.
- Hospitality:Hotel and resort kitchen specifications balance guest-facing aesthetics with back-of-house durability. Luxury properties in Dubai specify smart-enabled platforms for guest room service integration.
- Institutional:Schools, hospitals, and government facilities emphasize total cost of ownership and safety certification. India's Saubhagya electrification scheme opens first-time appliance markets for basic induction units in rural institutional kitchens.
Residential segments dominate unit volumes; Commercial retrofits are expanding most quickly.
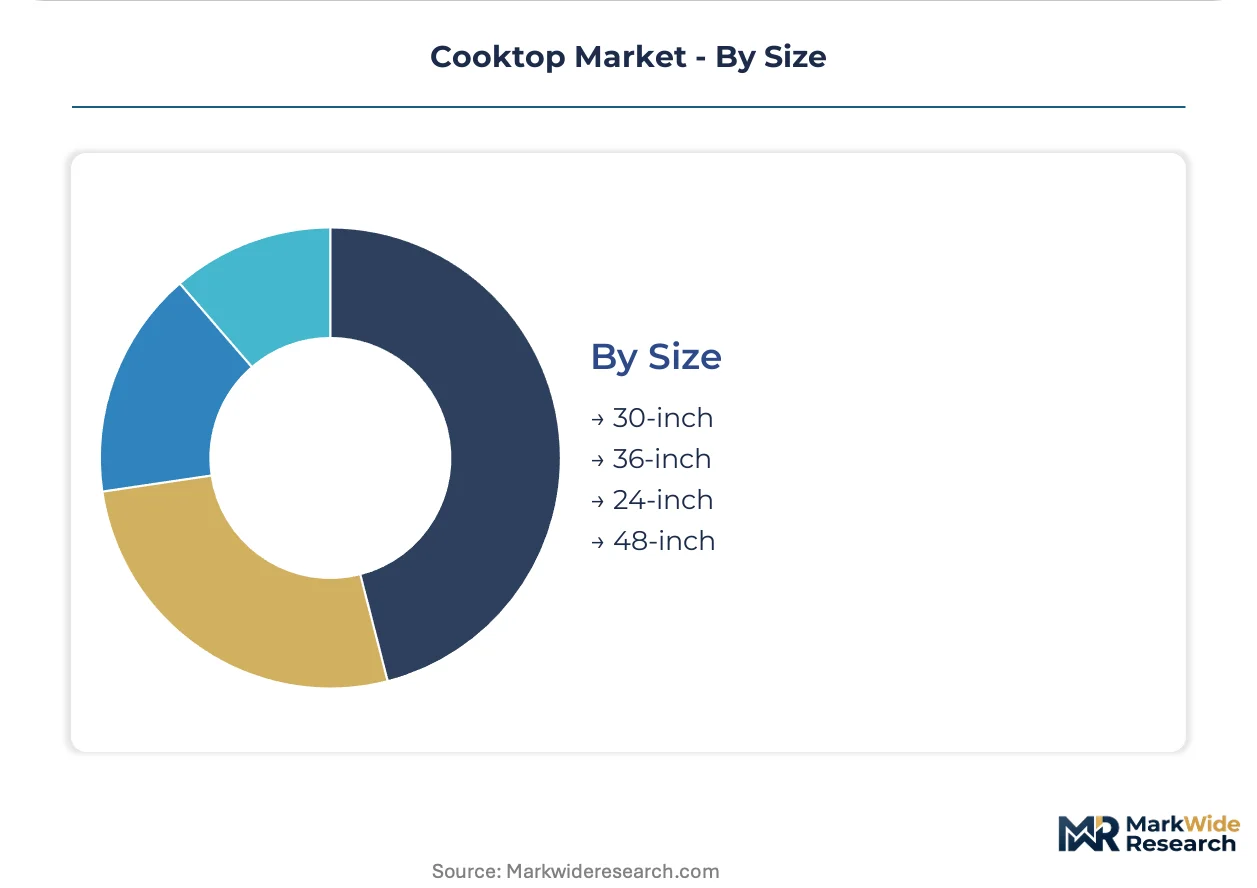
Size:
Dimensional specifications align with kitchen footprint constraints, cooking behavior patterns, and regional housing stock characteristics.
- 30-inch:Standard North American residential width fits legacy cabinet cutouts and replacement cycles. Suburban US developments specify this format for move-up buyer segments.
- 36-inch:Upscale residential and small commercial installations accommodate multiple cooking zones. Custom home builders in California specify these for premium tract housing differentiation.
- 24-inch:Compact formats serve urban apartments, auxiliary kitchens, and European housing stock with smaller footprints. China's tier-one city renovations favor these for space-constrained units.
- 48-inch:Professional-grade widths target luxury residential and commercial high-throughput applications. Hospitality specifications in Dubai integrate these into open-kitchen designs.
30-inch formats anchor replacement demand; 36-inch specifications gain share fastest in premium residential construction.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Residential builders and urban renovators concentrate demand across distinct regulatory environments. National efficiency codes and electrification timelines reshape procurement patterns in each major market.
United States
Suburban developers specify induction units for new tract housing as California and New York tighten building electrification codes. The EPA ENERGY STAR program mandates standby power below one watt, forcing control board redesigns. Dallas-Fort Worth metro builders anchor premium electric line demand in the Sun Belt.
Germany
Federal states accelerate gas-to-electric kitchen conversions ahead of federal efficiency mandates. The EU Ecodesign Directive compresses replacement cycles for legacy gas installations. Munich and Stuttgart industrial clusters concentrate premium induction manufacturing for European distribution.
China
Beijing and Shanghai property turnover accelerates appliance refresh timelines in tier-one cities. NMPA-aligned GB standards govern electromagnetic compatibility thresholds for domestic induction systems. Yangtze River Delta manufacturing bases supply both domestic channels and export markets.
India
Rural household connectivity expansion under the Saubhagya scheme opens first-time appliance markets for basic induction units. BIS certification requirements standardize safety testing for electromagnetic systems entering domestic channels. Maharashtra and Gujarat industrial corridors concentrate assembly operations for price-sensitive segments.
United Arab Emirates
Hospitality developers in Dubai specify smart-enabled platforms for guest-facing kitchen integration. MOHAP safety frameworks align with international electromagnetic compatibility standards. Dubai Design District clusters anchor luxury specification demand for open-kitchen hospitality concepts.
Cooktop Market Vendor Landscape
Channel-controlling players compete with product-specialist players across divergent technology-integration vectors. The vendor base stratifies into three tiers: captive-financing premium manufacturers, scale-driven volume producers, and smart-technology integrators. Consolidation pressures favor balance-sheet depth for project finance qualification. Dominant competitive moves include manufacturing footprint reallocation toward induction platforms and smart-home ecosystem partnerships.
Within the captive-financing tier, BSH Hausgeräte GmbH and Miele & Cie. KG exemplify European-origin manufacturers leveraging balance-sheet capacity to anchor premium positioning. At the scale-driven end, Whirlpool Corporation occupies a position reflecting North American manufacturing concentration. Samsung Electronics represents the smart-technology integration archetype, with software monetization extending beyond hardware margins.
| Leading Market Players |
|---|
| BSH Hausgeräte GmbH |
| Miele & Cie. KG |
| Whirlpool Corporation |
| Electrolux AB |
| Samsung Electronics |
| LG Electronics |
| Haier |
| Panasonic Holdings Corporation |
| Smeg S.p.A |
| Others |
Supply Flow & Price Mechanics
Copper and ferrite magnet cost volatility determines both pricing tier spreads and supply chain shape across induction cooktop manufacturing, compressing margin stability for mid-tier producers while forcing premium manufacturers toward captive material sourcing and long-term offtake agreements.
Pricing Analysis
Cost-plus contracts with London Metal Exchange copper indexation dominate procurement between coil manufacturers and appliance assemblers. Three-tier pricing structure across premium, standard, and economy levels separates ENERGY STAR-certified induction platforms from basic radiant electric units and entry-level gas alternatives. Pricing pressure stems from ferrite magnet supply constraints in China's Yangtze River Delta manufacturing bases. Residential renovation buyers exhibit highest price sensitivity, while hospitality developers in Dubai demonstrate lowest sensitivity due to total-cost-of-ownership procurement frameworks.
Supply Chain Analysis
Supply-chain finance facilities extended by Yangtze River Delta component suppliers to appliance assemblers compress working capital cycles and lock in volume commitments. Manufacturing concentrates in China, Germany, and Mexico for regional market access. Raw material dependencies center on copper winding wire, ferrite ceramic magnets, and tempered glass-ceramic substrates. Single-source vulnerability runs through Chinese ferrite magnet production. Distribution runs through builder-direct specification channels for new construction and big-box retail for replacement demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among large-scale residential developers and hospitality procurement consortia, compressing vendor margins and favoring manufacturers with project finance capacity.
For Market Incumbents: Harden induction platform positioning against gas-to-electric regulatory mandates by securing Ecodesign Directive pre-certification pipelines. Deepen backward integration into ferrite magnet production to offset raw material volatility. Anchor specification relationships with California and German federal state builder consortia before efficiency mandates tighten further. For New Entrants and Emerging Players: India's rural electrification corridors under Saubhagya scheme implementation represent the most penetrable entry point for basic induction units priced below premium European lines. Southeast Asian commercial kitchen retrofit demand in Singapore and Vietnam offers secondary white-space targeting. Pursue distributor partnership models with established electrical contractor networks rather than direct retail buildout. For Investors and Strategic Acquirers: The market sits at a regulatory-acceleration phase that favors balance-sheet-heavy manufacturers with captive financing programs. Long-term viability hinges on smart-ecosystem integration depth rather than pure hardware scale. Acquisition targets should demonstrate NMPA-aligned certification infrastructure for China market access. Monitor EU member state implementation timelines for Ecodesign Directive gas phase-out schedules as inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Induction Platform Manufacturing Scale-Up | Reallocates capacity toward Ecodesign-compliant production ahead of hardware obsolescence mandates. |
| Smart Home Ecosystem Partnership | Integrates cooktop connectivity with voice-assistant platforms for software monetization beyond hardware. |
| Captive Ferrite Magnet Sourcing | Secures upstream control over coil core materials subject to price volatility and supply constraint. |
| Regional Certification Investment | Establishes NMPA-aligned testing infrastructure for electromagnetic compatibility in China channels. |
| Project Finance Program Expansion | Enables specification capture with builder-developers consolidating procurement around technology-integrated platforms. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with residential developers, commercial kitchen operators, electrical contractors, and appliance procurement managers at hospitality groups. Secondary validation drew from EPA ENERGY STAR certification databases, EU Ecodesign Directive implementation notices, NMPA electromagnetic compatibility filings, and customs trade records for copper and ferrite magnet flows. Bottom-up unit shipment estimates triangulated against top-down construction permit and renovation spend data.
Calibration against historical replacement cycle data and regulatory implementation timelines anchored growth trajectory assumptions across the projection horizon. Segmentation dimensions modeled include product type, control interface technology, end-use application, and regional regulatory cluster. CAGRs were derived from segment-level demand elasticity analysis and efficiency mandate penetration curves. Forecast inputs incorporated builder specification surveys and commercial retrofit pipeline tracking.
Practitioners should monitor EU member state Ecodesign enforcement acceleration and China property turnover velocity for early signals of demand inflection. Forecasts reflect assumptions regarding regulatory implementation consistency and material cost stabilization. Macroeconomic deviation, tariff regime shifts, or grid infrastructure shortfalls would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Kitchen Chimney Market
Kitchen Appliances
Kitchen Knife Market
Kitchen Appliances
Sandwich Maker Market
Kitchen Appliances
Popcorn Makers Market
Kitchen Appliances
Residential Induction Cooktops Market
Kitchen Appliances
Self-Heating Butter Knife Market
Kitchen Appliances
Toaster Market
Kitchen Appliances
Russia Household Electric Grill Market
Kitchen Appliances
Smart Connectivity Kitchen Appliances Market
Kitchen Appliances
Germany Kitchen Appliances Market
Kitchen Appliances
Air Fryer Accessories Market
Kitchen Appliances
Commercial Induction Cooktops Market
Kitchen Appliances
Malaysia Smart Kitchen Appliances Market
Kitchen Appliances
Smart Kitchen Appliances Market
Kitchen Appliances
Electric Hobs Market
Kitchen Appliances
Household Bread Machine Market