
 Bakeware Market | 2026-2036
Bakeware Market Size, Share, and Industry Trends Forecast 2026-2036
Bakeware Market Analysis
REACH compliance is realigning the cost-of-entry calculus for bakeware manufacturers targeting European distribution. Kaiser Bakeware leverages its German engineering heritage to sustain premium positioning in aluminized steel formats. Groupe SEB anchors multi-brand portfolios across cookware sets and specialty baking formats. Nordic Ware differentiates through proprietary bundt pan geometries that dominate seasonal demand cycles in North American retail channels.
Bakeware encompasses oven-safe containers and tools engineered from materials such as aluminized steel with silicone-based non-stick coatings, designed to withstand thermal cycling between 450°F and 550°F for bread, pastry, and confectionery preparation. The primary commercial purpose centers on heat distribution uniformity and food release performance across residential and foodservice environments. Aluminum bakeware retains volume leadership due to thermal conductivity advantages, yet silicone formats are capturing margin pools among home bakers seeking collapsible storage and dishwasher compatibility. Professional chefs and restaurants concentrate demand toward heavy-gauge aluminized steel and stoneware for thermal mass retention during high-volume service windows.
The US FDA regulates direct food contact surfaces under 21 CFR 177, while the EU ECHA enforces REACH substance restrictions on heavy metal migration from ceramic glazes and silicone curing agents. Germany's BIS-equivalent LGA and LFGB testing protocols further shape product approval timelines for imported bakeware. Stakeholders must monitor evolving state-level PFAS restrictions in California and New York, as these precede broader federal action and will force material reformulation decisions across silicone and conventional non-stick coating supply chains.
Market Dynamics
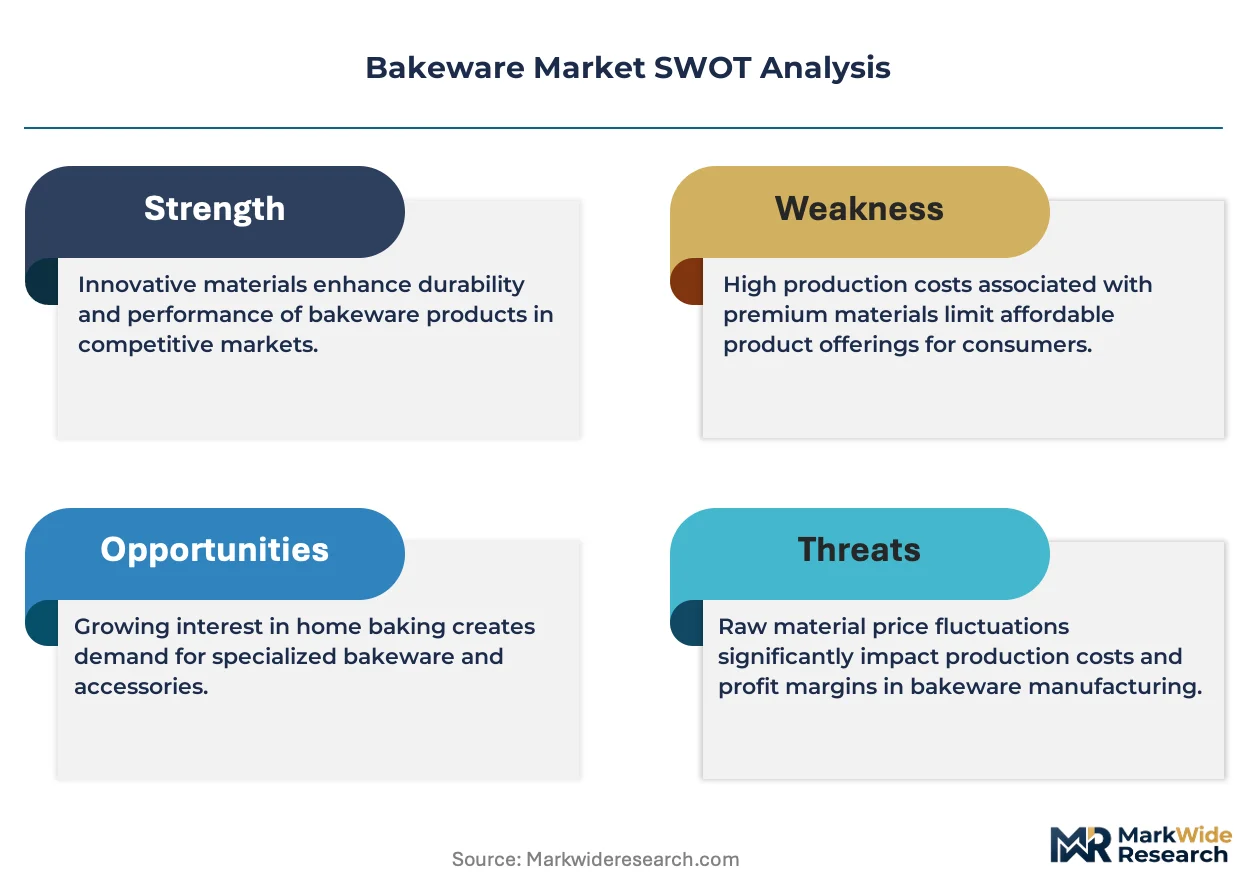
REACH substance restrictions and state-level PFAS bans are forcing material reformulation across silicone and non-stick coating supply chains, compressing approval timelines and elevating certification costs for manufacturers targeting European and North American distribution.
Growth Catalysts
- EU F-Gas Regulation:Phase-down mandates for fluorinated greenhouse gases are accelerating migration toward water-based and ceramic non-stick alternatives in commercial bakeware production.
- Foodservice expansion:Cloud kitchen proliferation and ghost bakery concepts are driving replenishment cycles for heavy-gauge aluminized steel sheet pans and specialty molds.
- Silicone curing advances:Platinum-catalyzed liquid injection molding is reducing cycle times for complex geometries, enabling cost-competitive production of collapsible storage formats.
Market Restraints
- Aluminum price volatility:LME aluminum fluctuations and energy cost spikes at smelters are compressing margins for rolled sheet and extruded rim products.
- Coating supply concentration:Sol-gel ceramic and PTFE-alternative formulation expertise clusters among a limited set of European and Japanese chemical suppliers.
- Thermal mass limitations:Silicone formats lack the heat retention required for artisan bread crust development, restricting penetration in professional sourdough and viennoiserie segments.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for specialty steel and coated metal products are attracting contract manufacturing investment for export-oriented bakeware.
- Induction compatibility:Ferritic stainless steel and steel-cored aluminum laminates address the 40% of European households with induction cooktops requiring oven-to-stovetop transitions.
- Direct-to-baker subscription:Curated quarterly mold and tool releases bypass retail slotting fees while capturing lifetime value from committed home baking enthusiasts.
Industry Challenges
- Laboratory testing backlog:LFGB and FDA migration studies for novel coating chemistries face 12-18 month queues at accredited facilities, delaying product launches.
- Legacy coating line retooling:Conversion from solvent-based to aqueous deposition systems requires seven-figure capital commitments with uncertain payback periods.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bakeware Market |
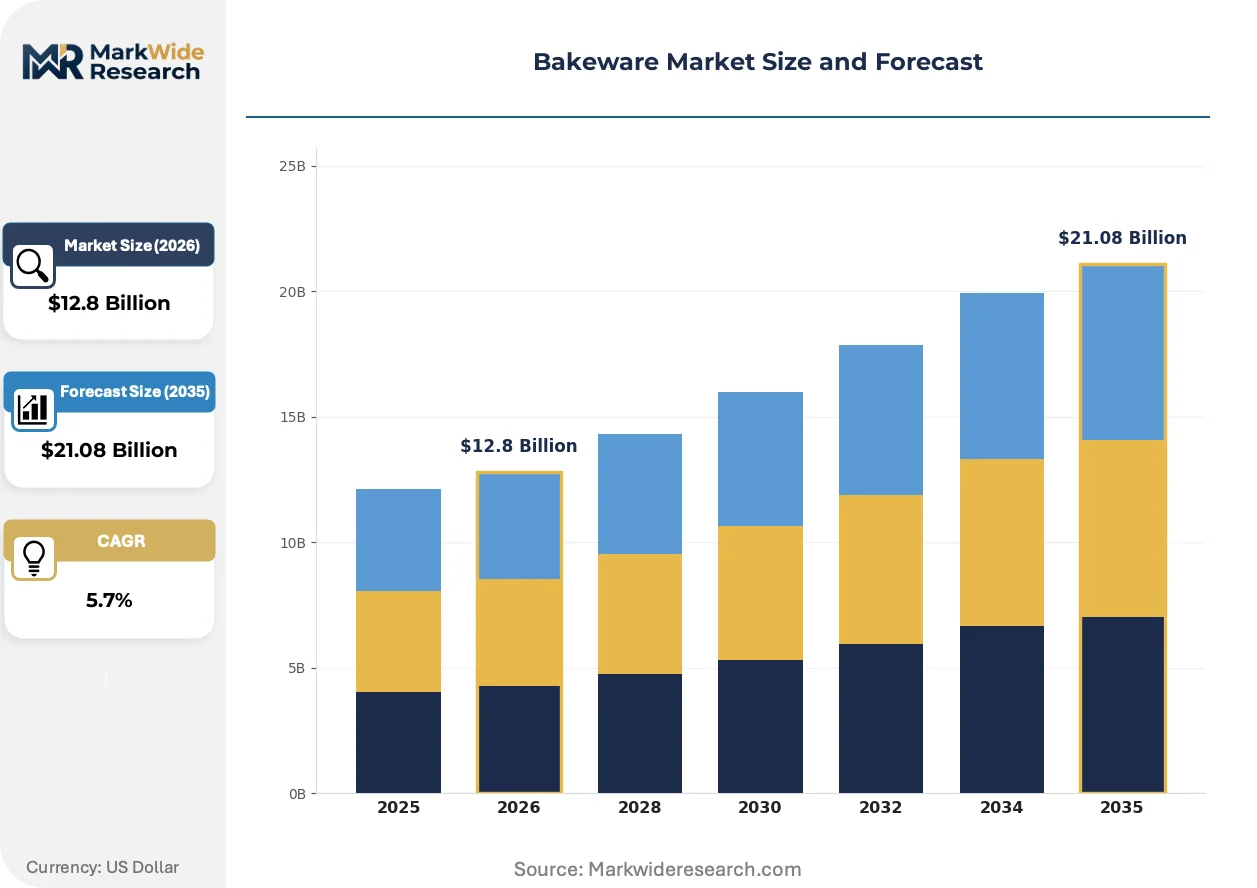
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $21.08 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cookware Sets, Baking Sheets, Muffin Tins, Loaf Pans Material: Silicone, Aluminum, Glass, Stoneware End User: Home Bakers, Professional Chefs, Restaurants, Catering Services Distribution Channel: Online Retail, Supermarkets, Specialty Stores, Wholesale Distributors |
| Companies Covered | Kaiser Bakeware, USA Pan, Groupe SEB, Le Creuset, Calphalon, Newell Brands, Nordic Ware, Wilton Brands, Meyer Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bakeware Market Emerging Trajectories
Material science convergence and regulatory chemistry bans are compressing traditional coating hierarchies while digital-native brands bypass incumbent retail gatekeepers through direct channels.
Hybrid ceramic-silicone composites are unifying the thermal conductivity of aluminized steel substrates with the release properties and dishwasher tolerance of elastomer surfaces. Premium home bakers and boutique commercial operations are piloting these laminates for intricate bundt and madeleine geometries. The technology is unifying previously separate manufacturing lines, enabling single-facility production of metal-core and pure silicone formats.
ECHA REACH Annex XVII amendments restricting per- and polyfluoroalkyl substances are eliminating long-chain fluoropolymer coatings from EU-bound bakeware by 2025. Manufacturers are accelerating sol-gel ceramic and short-chain fluorinated alternatives through migration testing protocols. German importers and domestic producers face the steepest compliance curves given the country's concentration of specialty baking culture and premium equipment expectations.
Bakers are consolidating purchases through vertical specialty retailers and brand-direct storefronts rather than general merchandise big-box channels. Sur La Table, King Arthur Baking, and direct-to-consumer launches from established manufacturers are capturing share from mass-market housewares departments. This pattern is most pronounced in coastal US metropolitan markets and German urban centers where enthusiast communities concentrate and price sensitivity for provenance and performance runs lower.
Bakeware Market Segmentation
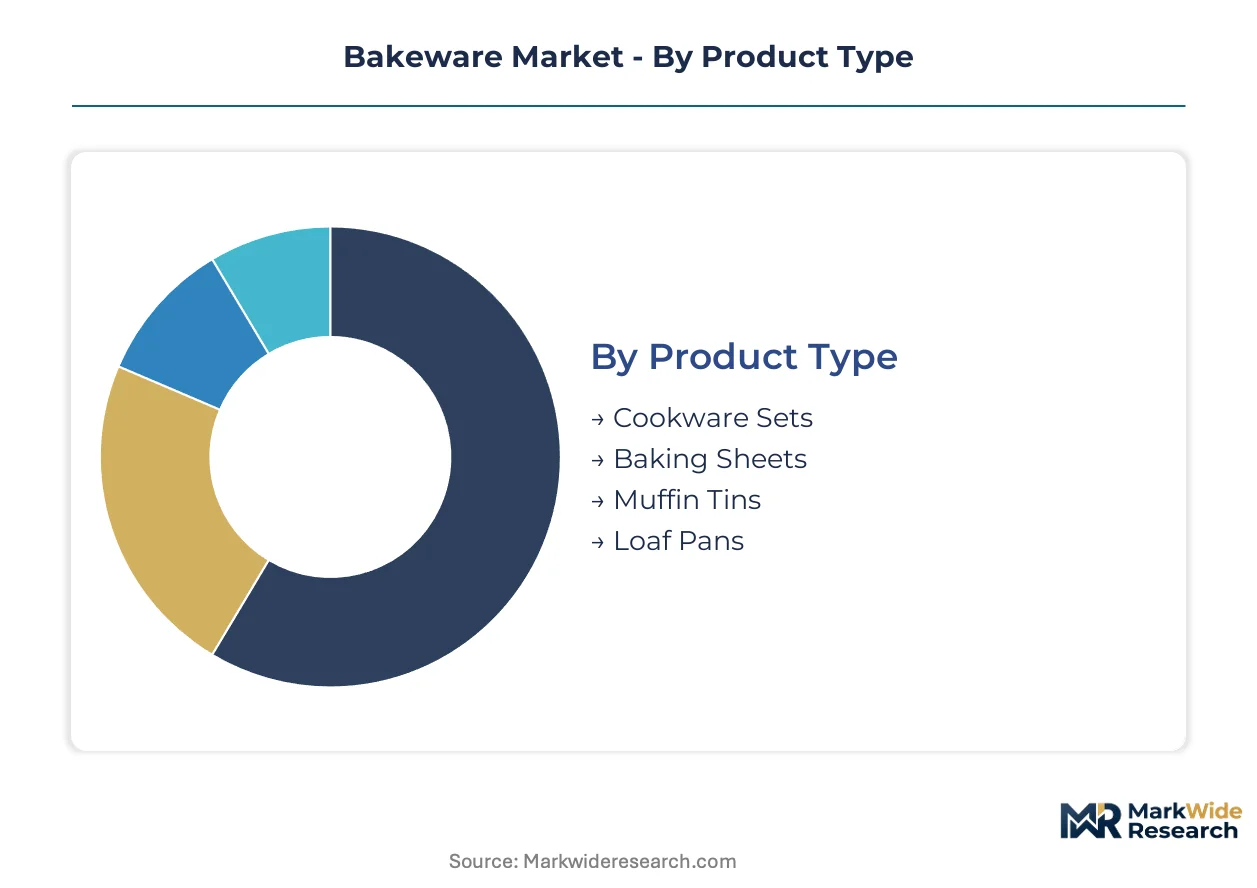
Bakeware segmentation reveals divergent certification burdens across material categories and end-use applications. Professional foodservice formats trigger FDA 21 CFR 177 and EU ECHA REACH migration testing, while residential silicone products face lighter conformity requirements.
Product Type:
FDA 21 CFR 177 governs direct food contact surfaces for all formats, with ECHA REACH Annex XVII adding heavy metal restrictions on ceramic glazes in loaf pans and muffin tins. German LFGB protocols impose additional sensory testing for baking sheets entering commercial kitchens.
- Baking Sheets:Heavy-gauge aluminized steel construction withstands 450°F to 550°F thermal cycling in cloud kitchen operations. Demand concentrates in North American ghost bakery facilities seeking rapid heat recovery during high-volume service windows.
- Cookware Sets:Curated collections bundling multiple formats for residential enthusiasts. German and French consumers prioritize induction-compatible bases requiring ferritic stainless steel or steel-cored aluminum laminates.
- Muffin Tins:Platinum-catalyzed silicone formats dominate collapsible storage segments.
- Loaf Pans:Stoneware variants retain thermal mass for artisan bread crust development.
Leading the category by volume: Baking Sheets. Growing fastest: Cookware Sets.
Material:
Cost tier stratification separates premium ceramic-silicone laminates from commodity aluminum extrusions. Raw material volatility at LME smelters compresses margins on rolled sheet products while silicone curing advances reduce cycle times for complex geometries.
- Aluminum:Thermal conductivity leadership sustains volume dominance across bread and pastry applications. Professional chefs in commercial bakeries specify heavy-gauge formats for uniform heat distribution during viennoiserie production.
- Silicone:Platinum-catalyzed liquid injection molding enables collapsible formats with dishwasher compatibility. Home bakers in coastal US metropolitan markets drive demand for storage-efficient designs.
- Stoneware:Thermal mass retention suits sourdough crust development despite weight penalties.
- Glass:Borosilicate formats address visibility preferences in residential convection ovens.
Aluminum leads by installed base. Silicone climbs the fastest on curing technology advances.
End User:
Application intensity dictates coating durability requirements and replacement frequency. Foodservice environments demand sol-gel ceramic or short-chain fluorinated alternatives as ECHA REACH eliminates long-chain fluoropolymers.
- Professional Chefs:Commercial kitchens specify heavy-gauge aluminized steel with thermal mass retention for high-volume service. Cloud kitchen proliferation accelerates replenishment cycles for sheet pans and specialty molds.
- Restaurants:Front-of-house presentation requirements drive premium stoneware and ceramic-silicone composite adoption. German urban centers concentrate demand for provenance-verified equipment.
- Home Bakers:Enthusiast segments prioritize collapsible silicone and dishwasher compatibility.
- Catering Services:Mobile operations favor lightweight aluminum formats for transport efficiency.
Professional Chefs anchor volume. Home Bakers gain share fastest through direct-to-consumer subscription channels.
Distribution Channel:
Customer type fragmentation separates enthusiast communities from price-sensitive mass-market purchasers. Vertical specialty retailers capture committed bakers while mass merchandisers serve replacement demand.
- Specialty Stores:Sur La Table and King Arthur Baking curate performance-verified formats for enthusiast communities. Coastal US metropolitan markets and German urban centers concentrate foot traffic for provenance-driven purchases.
- Online Retail:Direct-to-consumer launches bypass retail slotting fees while capturing lifetime value through subscription models. Quarterly mold releases target committed home baking enthusiasts.
- Supermarkets:Mass-market housewares departments serve emergency replacement demand.
- Wholesale Distributors:Foodservice supply chains aggregate volume for restaurant and catering procurement.
Specialty Stores lead by margin per transaction. Online Retail expands most quickly on digital-native brand launches.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Production-Linked Incentive scheme for specialty steel and coated metal products is attracting contract manufacturing investment for export-oriented bakeware production. This tax-incentive zone is reshaping regional supply chain configurations as manufacturers seek cost-competitive bases for aluminized steel formats.
Germany
German consumers prioritize durable, non-toxic baking equipment with provenance verification. The country's BfR and LFGB testing protocols impose additional sensory testing requirements on imported bakeware entering commercial kitchens. Bavaria and Baden-Württemberg concentrate specialty steel fabrication clusters serving premium cookware demand.
United States
California and New York state-level PFAS restrictions are forcing material reformulation decisions across silicone and conventional non-stick coating supply chains. The FDA regulates direct food contact surfaces under 21 CFR 177. Ghost bakery proliferation in coastal metropolitan markets accelerates replenishment cycles for heavy-gauge sheet pans.
China
Domestic demand for borosilicate glass and ceramic-silicone composite formats is expanding alongside export manufacturing. The country's national standards body oversees GB standards for food contact materials. Yangtze River Delta manufacturing clusters supply rolled aluminum and platinum-catalyzed silicone curing capacity for international brands.
India
Specialty steel and coated metal production incentives are drawing contract manufacturing investment from export-oriented bakeware brands. The Bureau of Indian Standards certifies domestic food contact materials. Gujarat and Maharashtra industrial corridors host emerging fabrication facilities targeting European and North American distribution.
France
Front-of-house presentation requirements in restaurant segments drive premium stoneware and ceramic-silicone composite adoption. The country's national food safety agency enforces EU REACH compliance on heavy metal migration from ceramic glazes. Paris and Lyon urban centers concentrate demand for provenance-verified equipment among professional chefs.
Bakeware Market Vendor Landscape
Diversified conglomerates compete with focused pure-play specialists across material tiers and distribution channels. The vendor base organizes around three strategic archetypes: heritage European engineering houses, North American direct-to-consumer digital brands, and Asian contract manufacturers scaling through production incentives. Consolidation pressure is concentrating coating formulation expertise among limited European and Japanese chemical suppliers. Dominant competitive moves include portfolio diversification into hybrid ceramic-silicone composites and backward integration into specialty steel supply.
Within the heritage engineering tier, Kaiser Bakeware occupies a position exemplifying German manufacturing pedigree in aluminized steel formats. Groupe SEB anchors a multi-brand portfolio spanning cookware sets and specialty baking equipment. Nordic Ware represents the design-differentiation archetype through proprietary bundt pan geometries that dominate seasonal demand cycles in North American retail channels.
| Leading Market Players |
|---|
| Kaiser Bakeware |
| USA Pan |
| Groupe SEB |
| Le Creuset |
| Calphalon |
| Newell Brands |
| Nordic Ware |
| Wilton Brands |
| Meyer Corporation |
| Others |
Supply Flow & Price Mechanics
Platinum-catalyzed liquid injection molding is compressing silicone bakeware production economics while simultaneously redrawing supplier concentration maps as Asian contract manufacturers capture scale advantages from curing technology advances.
Pricing Analysis
Short lead-time premiums command pricing power in commercial bakeware procurement as ghost kitchen operators prioritize rapid sheet pan replenishment over unit cost minimization. Three-tier pricing structure across premium, standard, and economy levels separates sol-gel ceramic-coated formats from conventional PTFE alternatives and uncoated aluminum commodity products. Price differentiation hinges on REACH certification tier and thermal cycling durability ratings. Cost compression in standard-tier aluminized steel is intensifying because LME aluminum volatility feeds directly into rolled sheet input costs. Mass-market retail buyers exhibit highest price sensitivity, while German commercial kitchen procurement teams prioritize LFGB-compliant provenance over unit economics.
Supply Chain Analysis
Direct-to-specialty-retailer channels handle enthusiast-grade demand from Sur La Table and King Arthur Baking, while wholesale distributors aggregate foodservice volume for restaurant procurement. Manufacturing concentrates in China, Germany, and India as Yangtze River Delta clusters supply rolled aluminum capacity, Bavarian fabricators serve premium European demand, and Gujarat facilities exploit PLI scheme incentives for export-oriented production. Raw material dependencies rest on LME aluminum ingot, platinum-group catalysts for silicone curing, and sol-gel ceramic precursor chemicals. Single-source vulnerability concentrates in Japanese and European coating formulation suppliers. Distribution runs through vertically integrated brand-direct storefronts and specialty retail partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bakeware sector is navigating a coating chemistry transition as ECHA REACH Annex XVII eliminates long-chain fluoropolymers and sol-gel ceramics displace legacy PTFE formulations.
For Market Incumbents: Acquire coating formulation expertise through targeted capability purchases in sol-gel ceramic and short-chain fluorinated alternatives. Secure captive supply of platinum-group catalysts to insulate silicone production from precious metal volatility. Backward integration into heavy-gauge aluminized steel rolling capacity in India protects margin structure against LME price swings. Defensive patent filings around hybrid ceramic-silicone laminate geometries will constrain new entrant design freedom. For New Entrants and Emerging Players: California and New York state-level PFAS restrictions open a window for ceramic-coated formats to displace incumbent PTFE-dependent portfolios in North American distribution. Target direct-to-consumer subscription models for home baking enthusiasts, where quarterly curated mold releases bypass retail slotting fee structures. White-space penetration concentrates in induction-compatible ferritic stainless steel formats for European households. Go-to-market execution should anchor on vertical specialty retail partnerships with provenance-forward positioning. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified housewares conglomerates seeking coating chemistry capabilities. Five-to-ten year viability favors manufacturers with in-house sol-gel formulation expertise and LFGB certification infrastructure already operational. Acquisition target archetype: mid-cap German or Japanese specialists with established commercial kitchen relationships and REACH-compliant product pipelines. Watch ECHA migration testing queue lengths as an inflection signal—backlogs exceeding eighteen months indicate regulatory friction that will favor incumbent certification holders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Steel Supply | Captive aluminized steel rolling capacity in India insulates margins from LME volatility. |
| Sol-Gel Ceramic Coating Scale-Up | REACH-compliant alternatives capture share as ECHA eliminates long-chain fluoropolymer formats. |
| Direct-to-Consumer Subscription Launch | Quarterly mold releases bypass retail slotting fees while capturing lifetime enthusiast value. |
| LFGB Certification Infrastructure Investment | German commercial kitchen access requires sensory testing capabilities that create importer moats. |
| Hybrid Ceramic-Silicone Composite Development | Unified laminates merge thermal conductivity with dishwasher tolerance for premium home segments. |
Methodological Framework
Independent corroboration across primary interviews with commercial bakery procurement directors, coating chemistry R&D leads, and specialty retail category buyers, combined with secondary validation from FDA 21 CFR 177 filings, ECHA REACH Annex XVII amendments, and LME aluminum futures data, underwrites the qualitative findings. Bottom-up demand modeling from end-use segments triangulates against top-down market sizing from trade flow analysis.
Comparable-period anchoring to historical regulatory implementation timelines shaped the forecast window construction. Segmentation modeling spans material category, end-use intensity, and distribution channel format across the projection horizon. CAGRs derive from regression analysis against aluminum price elasticity and coating substitution rates. Forecast inputs include platinum-group metal spot trends and cloud kitchen facility opening trajectories.
The model assumes a particular technology adoption path; alternative pathways for sol-gel ceramic penetration would alter the outlook if migration testing bottlenecks resolve faster than baseline assumptions. Forecasts reflect documented assumptions regarding ECHA enforcement stringency and state-level PFAS restriction diffusion. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Electric Pizza Oven Market
Kitchen Appliances
Commercial Countertop Ranges Market
Kitchen Appliances
Cotton Candy Maker Market
Kitchen Appliances
Household Coffee Machine Market
Kitchen Appliances
Garlic Press Market
Kitchen Appliances
United Kingdom Kitchen Appliances Market
Kitchen Appliances
Range Cooker Market
Kitchen Appliances
Electric Corkscrew Market
Kitchen Appliances
Switzerland Kitchen Appliances Product Market
Kitchen Appliances
Middle East Electric Vegetable Chopper Market
Kitchen Appliances
Europe Small Kitchen Appliances Market
Kitchen Appliances
Hand-Held Mixer Market
Kitchen Appliances
Kitchen Chimney Market
Kitchen Appliances
On-The-Go Pots Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Pressure Cooker Market