
 Temperature Controlled Mug Market | 2026-2036
Temperature Controlled Mug Market Size, Share, and Industry Trends Forecast 2026-2036
Temperature Controlled Mug Market Analysis
Subscription-based leasing for workplace beverage hardware is rewriting competitive entry barriers for temperature controlled mug vendors. Ember Technologies leverages direct-to-enterprise contracts to sustain recurring revenue streams beyond unit sales. Zojirushi Corporation anchors its position through precision thermal engineering heritage that commands premium positioning in Japanese and North American channels. Yeti Holdings competes through ruggedized brand equity that extends into outdoor and professional use cases with minimal technology complexity.
Temperature controlled mugs integrate heating elements, lithium-ion power cells, and digital sensors to maintain beverages within user-specified thermal ranges, typically between 120°F and 145°F, for extended durations. The primary commercial purpose centers on eliminating temperature decay during prolonged consumption intervals in office, travel, and residential environments. Smart mugs and app-controlled technology segments capture disproportionate margin pools as software-enabled personalization commands pricing premiums over passive insulated alternatives. Electric mugs with embedded battery systems represent the fastest-expanding category, though sensor technology integration across all product tiers is maturing rapidly as component costs decline.
FCC certification governs radio frequency emissions from Bluetooth-enabled units in the United States, while CE marking and RoHS compliance structure European market access for electronic beverage containers. Japan's METI enforces battery safety and energy efficiency standards that shape product development priorities for manufacturers targeting that market. Stakeholders must monitor evolving lithium-ion transportation regulations and right-to-repair legislative momentum that could mandate modular battery designs and reshape warranty cost structures across all major sales channels.
Market Dynamics
Workplace beverage culture has permanently shifted toward hybrid consumption patterns, forcing hardware vendors to restructure pricing and distribution around recurring enterprise contracts rather than one-time consumer transactions.
Growth Catalysts
- FCC Certification Pathway:United States radio frequency compliance for Bluetooth-enabled units creates a defensible quality signal that enterprise buyers use to filter vendor shortlists, accelerating premium segment consolidation.
- Corporate Procurement Consolidation:Fortune 500 procurement teams now bundle smart mugs into broader workplace amenity contracts, creating volume commitments that stabilize manufacturer cash flows across seasonal demand cycles.
- Lithium-Ion Energy Density Gains:Battery chemistry improvements extend heating duration without expanding form factor, enabling thinner industrial designs that penetrate premium travel and commuter segments previously blocked by bulk constraints.
Market Restraints
- Raw Material Concentration:Rare earth element processing for heating coils concentrates in Chinese supply chains, exposing margin stability to geopolitical friction and export licensing volatility.
- RoHS Compliance Costs:European hazardous substance restrictions impose testing and documentation burdens that disproportionately burden smaller vendors lacking dedicated regulatory affairs functions.
- Passive Insulation Substitution:Vacuum-insulated stainless steel alternatives from established houseware brands capture price-sensitive demand with zero electronics failure risk and minimal warranty exposure.
Strategic Opportunities
- German Commercial Real Estate Integration:Smart building developers in Frankfurt and Munich are specifying connected beverage hardware as tenant amenity differentiators, creating specification-driven demand independent of retail channels.
- Right-to-Repair Tailwinds:Emerging European legislative momentum toward modular battery mandates would advantage vendors with pre-engineered swap architectures, potentially rewriting warranty cost structures industry-wide.
- Sensor-Platform Convergence:Integration of hydration tracking and caffeine monitoring algorithms creates software subscription potential that extends customer lifetime value beyond hardware depreciation cycles.
Industry Challenges
- Cross-Functional Talent Scarcity:Vendors struggle to recruit engineers fluent in both thermal physics and mobile application architecture, slowing firmware iteration cycles and delaying app-store certification timelines.
- Certification Pipeline Bottlenecks:METI battery safety testing in Japan and FCC equipment authorization in the United States face backlogs that extend product launch windows by six to twelve months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Temperature Controlled Mug Market |
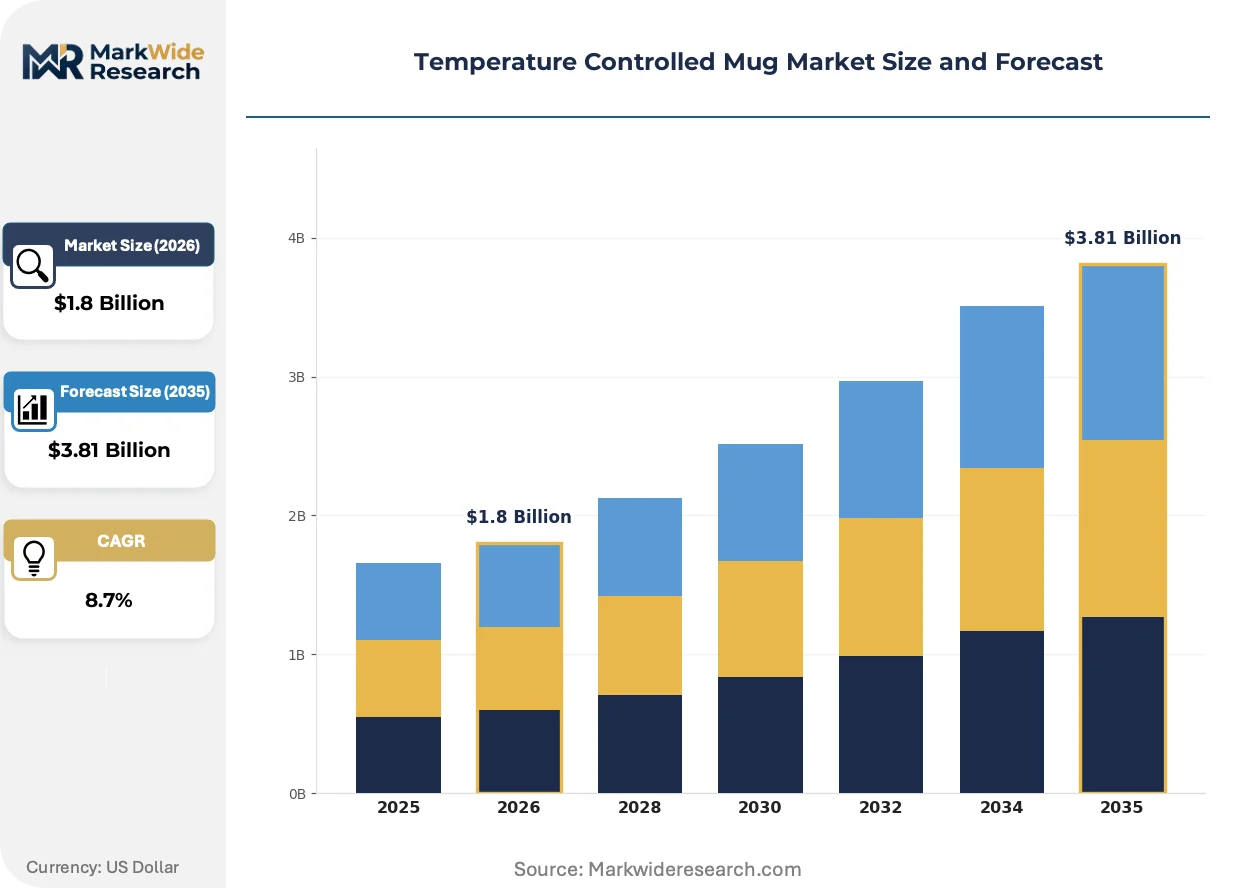
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Mugs, Electric Mugs, Insulated Mugs, Temperature Regulating Cups End User: Home Users, Office Workers, Travelers, Coffee Enthusiasts Technology: Bluetooth Enabled, App Controlled, Sensor Technology, Battery Operated Distribution Channel: Online Retail, Specialty Stores, Department Stores, Direct Sales |
| Companies Covered | Thermos, OHOM, Ember Technologies, Muggo, Yecup, Yeti Holdings, Zojirushi Corporation, Contigo Brands, Cauldryn, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Temperature Controlled Mug Market Emerging Trajectories
Component miniaturization and software-defined thermal management are converging to compress hardware differentiation cycles, forcing vendors to compete on data-enabled services rather than heating performance alone.
Induction heating coil arrays are collapsing the traditional trade-off between power efficiency and temperature precision. Enterprise procurement teams in the United States and Germany are specifying induction-based units for executive floor deployments where consistent performance overrides upfront cost considerations. This architecture is collapsing the addressable market for resistive heating elements in premium tiers.
Japan's METI has tightened energy efficiency standards for battery-powered appliances, requiring standby power draw reductions that force firmware re-architecture and component re-qualification. Manufacturers targeting Japanese distribution must redesign power management integrated circuits and resubmit for JIS certification, compressing margin structures for products already in market. Domestic vendors with existing METI relationships are accelerating certification timelines to capture stranded competitor inventory.
Enterprise beverage service contracts are displacing individual unit ownership in North American technology and professional services firms. Facilities management providers are bundling temperature controlled hardware into managed pantry services, transferring capital expenditure burden to operating budgets and demanding vendor financing flexibility. This shift is most visible in Seattle, Austin, and Toronto where hybrid workforce density supports per-seat pricing models.
Temperature Controlled Mug Market Segmentation
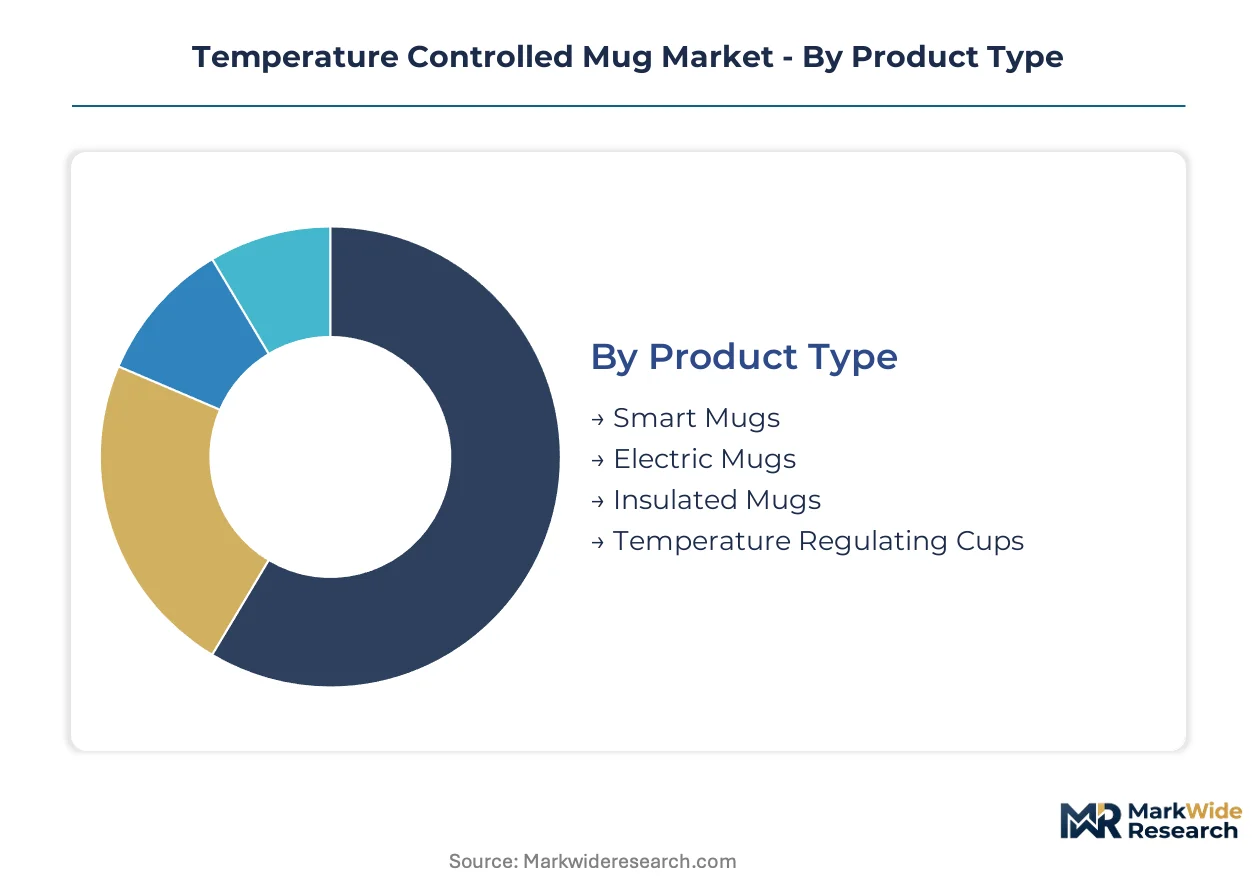
Temperature controlled mug segmentation reveals how hardware capabilities, user contexts, and channel economics fragment addressable demand. Vendors must align R&D roadmaps and inventory deployment against these dimensional splits to avoid margin erosion from product-market mismatches.
Product Type:
Cost tier differentiation separates passive thermal retention from active powered systems, with premium pricing attaching to electronic complexity and software integration.
- Smart Mugs:Bluetooth-connected vessels with embedded heating elements and lithium-ion power cells enable app-directed temperature maintenance between 120°F and 145°F. Enterprise procurement teams in the United States specify these for hybrid workplace deployments where beverage consistency signals amenity investment. FCC certification requirements for radio frequency emissions create vendor qualification barriers that concentrate contract awards.
- Electric Mugs:Corded or battery-powered units with resistive or induction heating coils provide active temperature management without connectivity features. German commercial real estate developers specify induction-based electric mugs for executive floor installations where power efficiency overrides upfront hardware costs. METI energy efficiency standards in Japan force firmware re-architecture for battery-operated variants targeting that market.
- Insulated Mugs:Vacuum-sealed stainless steel construction delivers passive thermal retention through material physics alone. Price-sensitive consumers in mass retail channels favor these for zero electronics failure risk and minimal warranty exposure.
- Temperature Regulating Cups:Phase-change material linings or thermal mass designs moderate beverage temperature without external power. Travel segments in commuter corridors adopt these for weight advantages over battery-equipped alternatives.
Smart mugs hold installed capacity. Electric mugs are rotating up the share rankings.
End User:
Application context determines performance specifications, with workplace and mobility use cases demanding divergent form factor and power autonomy trade-offs.
- Home Users:Residential consumption prioritizes countertop aesthetics and multi-beverage compatibility over travel durability. Kitchen technology adoption in the United States and Japan sustains premium pricing for connected units with voice assistant integration.
- Office Workers:Hybrid workforce beverage culture has permanently shifted procurement patterns toward enterprise-managed hardware. Facilities management providers in Seattle, Austin, and Toronto bundle temperature controlled mugs into managed pantry services with per-seat pricing models.
- Travelers:Commuter and aviation contexts demand spill-resistant sealing, TSA-compliant battery configurations, and compact form factors. Lithium-ion transportation regulations constrain product design for this segment across United States and European distribution channels.
- Coffee Enthusiasts:Precision temperature control for specialty brewing methods commands enthusiast pricing. App-enabled profiles for pour-over, French press, and espresso extraction temperatures capture margin pools in specialty retail channels.
Office workers represent the fastest-expanding trajectory. Home users anchor current revenue concentration.
Technology:
Maturity gradients across connectivity, control interface, sensing, and power architecture create distinct competitive arenas with diverging certification burdens.
- Bluetooth Enabled:Radio frequency modules enable smartphone pairing for remote temperature adjustment and firmware updates. FCC equipment authorization backlogs in the United States extend product launch windows by six to twelve months for vendors lacking established regulatory relationships.
- App Controlled:iOS and Android applications deliver scheduling, hydration tracking, and caffeine monitoring functionality. Subscription revenue potential from software services extends customer lifetime value beyond hardware depreciation cycles for vendors with platform development capabilities.
- Sensor Technology:Thermistors, infrared detectors, and accelerometers enable adaptive heating and spill detection. Component cost declines are maturing sensor integration across all product tiers, compressing differentiation cycles.
- Battery Operated:Lithium-ion cell integration enables cordless operation with heating duration tied to energy density gains. RoHS compliance costs for European hazardous substance restrictions disproportionately burden smaller vendors lacking dedicated regulatory affairs functions.
Sensor technology holds installed capacity. App controlled systems are rotating up the share rankings.
Distribution Channel:
Customer type and purchase context fragmentation across digital, specialty, mass retail, and vendor-direct channels shapes margin capture and brand positioning economics.
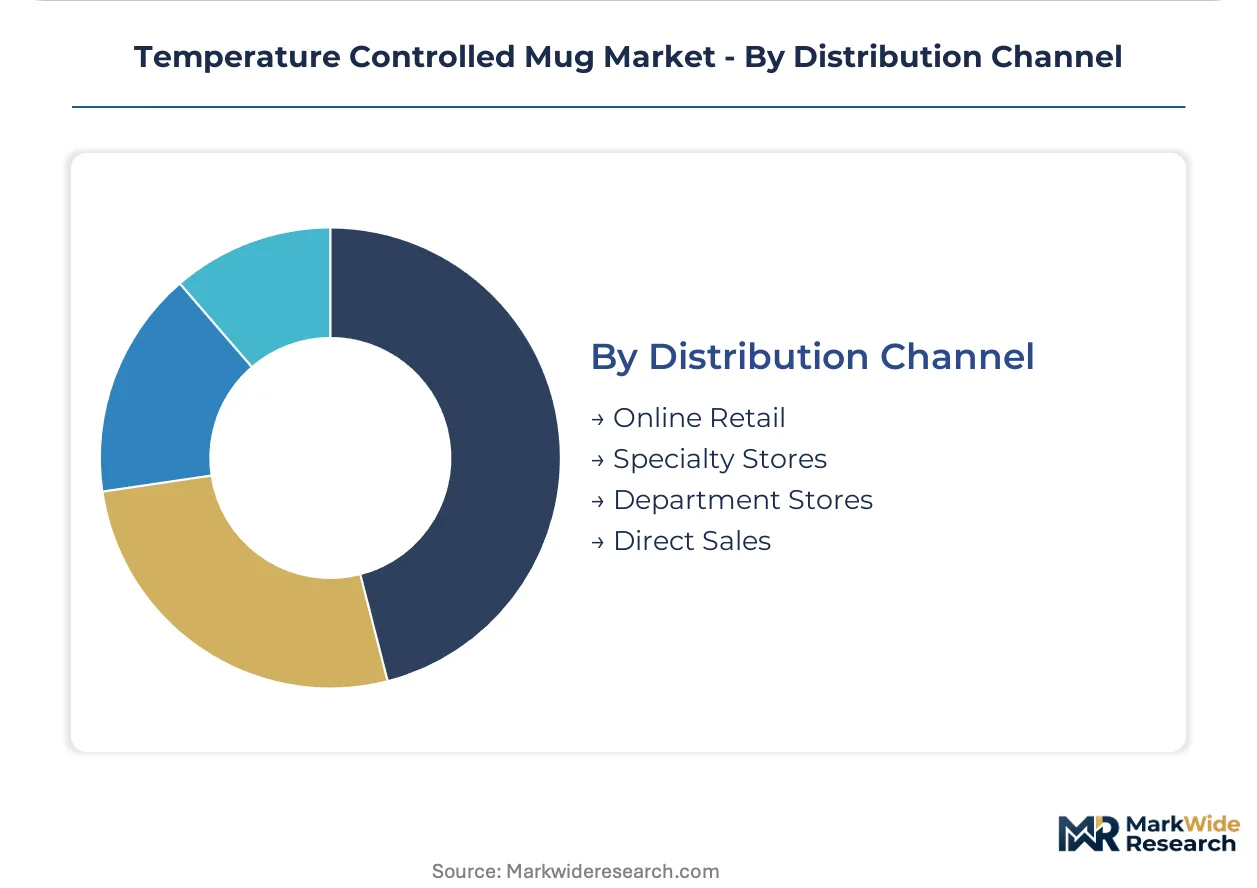
- Online Retail:Amazon and direct-to-consumer platforms enable specification comparison and review-driven selection. Enterprise buyers in North American technology firms bypass retail entirely through vendor-direct procurement portals.
- Specialty Stores:Williams Sonoma, Sur La Table, and regional kitchenware boutiques provide tactile evaluation and staff consultation. Coffee enthusiasts in urban clusters pay premium markups for hands-on assessment of build quality and thermal performance.
- Department Stores:Macy's, Nordstrom, and comparable mass retail anchors deliver seasonal gift market exposure with compressed margins and inventory risk transfer to vendors.
- Direct Sales:Vendor-controlled channels capture full margin and customer relationship data. Ember Technologies leverages direct-to-enterprise contracts to sustain recurring revenue streams beyond unit sales in Fortune 500 deployment programs.
Online retail holds installed capacity. Direct sales are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Enterprise procurement teams in the United States, Germany, and Japan concentrate the bulk of premium temperature controlled mug demand. Hybrid workplace beverage culture and commercial real estate integration are reshaping geographic deployment patterns.
United States
Fortune 500 facilities management providers bundle smart mugs into managed pantry services across Seattle, Austin, and Toronto corridors. FCC certification requirements for Bluetooth-enabled units create vendor qualification barriers that enterprise buyers use to filter shortlists. Corporate procurement consolidation in technology and professional services sectors drives specification-driven demand independent of retail channels.
Germany
Commercial real estate developers in Frankfurt and Munich specify connected beverage hardware as tenant amenity differentiators. CE marking and RoHS compliance structure market access for electronic beverage containers, imposing testing burdens that favor established regulatory affairs functions. Induction-based electric mug deployments on executive floors prioritize power efficiency over upfront hardware costs.
Japan
METI energy efficiency standards for battery-powered appliances force firmware re-architecture and component re-qualification for manufacturers targeting distribution. Precision thermal engineering heritage commands sustained premium positioning in domestic and North American channels. Domestic vendors with existing regulator relationships accelerate certification timelines to capture stranded competitor inventory.
United Kingdom
Specialty retail channels in London and Southeast England sustain premium markups for tactile evaluation of build quality. GDPR compliance shapes data handling for app-connected units entering European distribution. Managed workplace services in financial services clusters are piloting per-seat hardware leasing models.
Canada
Hybrid workforce density in Toronto supports vendor-direct procurement portals that bypass traditional retail entirely. Health Canada and PMRA frameworks influence product safety documentation for cross-border enterprise contracts. Pacific Northwest technology corridor spillover creates specification alignment with United States procurement standards.
Temperature Controlled Mug Market Vendor Landscape
Channel-controlling players compete with product-specialist players across fragmented tier structures. The vendor base spans heritage thermal engineering houses, ruggedized outdoor brands, and connected hardware startups. Three archetypes dominate: precision thermal specialists, ruggedized lifestyle brands, and software-enabled platform vendors. Strategic moves center on direct-to-enterprise contract structures and firmware-platform convergence.
Within the heritage engineering tier, Zojirushi Corporation and Thermos occupy positions anchored by decades of thermal physics specialization. Yeti Holdings exemplifies the ruggedized lifestyle archetype, extending brand equity into professional use cases with minimal electronics complexity. Ember Technologies represents the software-enabled platform vector, leveraging recurring revenue architectures beyond unit sales. These three anchors illustrate how thermal performance, brand durability, and data services fragment competitive positioning.
| Leading Market Players |
|---|
| Thermos |
| OHOM |
| Ember Technologies |
| Muggo |
| Yecup |
| Yeti Holdings |
| Zojirushi Corporation |
| Contigo Brands |
| Cauldryn |
| Others |
Supply Flow & Price Mechanics
Rare earth element export licensing volatility from Chinese processing facilities determines both premium-to-economy pricing spreads and supplier geographic diversification imperatives. Battery chemistry cost indexation in lithium-ion supply contracts forces vendors to absorb margin compression or pass through to enterprise procurement teams.
Pricing Analysis
Cost-plus contracts with lithium carbonate indexation dominate supplier agreements for battery-equipped smart mugs. Three-tier pricing structure across premium, standard, and economy levels separates FCC-certified Bluetooth units from basic electric models and passive insulated alternatives. Cost compression in the mid-tier intensifies because RoHS compliance documentation burdens disproportionately burden smaller vendors. Enterprise buyers in the United States exhibit lowest price sensitivity, while mass retail channels in Europe anchor demand at economy tiers.
Supply Chain Analysis
Tariff exposure between China and the United States dominates sourcing decisions for heating coil arrays and lithium-ion cells. Manufacturing concentrates in China, South Korea, and Japan for battery cells, with rare earth processing anchored in Chinese facilities. Component sourcing draws from Taiwanese semiconductor foundries for power management integrated circuits and German sensor specialists for precision thermistors. Single-source vulnerability in rare earth magnet supply creates specification risk for induction heating architectures. Distribution runs through vendor-direct enterprise portals and Amazon-led online retail with minimal wholesale intermediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where FCC certification backlogs and METI battery safety relationships create regulatory entrenchment that protects established vendor positions.
For Market Incumbents: Pre-empt modular battery architecture deployment before right-to-repair mandates crystallize in European legislation. Deepen firmware-platform integration to raise switching costs for enterprise procurement teams evaluating vendor consolidation. Accelerate METI relationship investment to capture stranded competitor inventory during re-certification windows. For New Entrants and Emerging Players: Pursue Canadian enterprise procurement portals in Toronto where hybrid workforce density supports per-seat pricing models with minimal incumbent saturation. Target German commercial real estate specification channels where smart building developers seek connected beverage hardware as tenant amenities. Lead with induction heating efficiency claims to bypass resistive heating patent thickets. For Investors and Strategic Acquirers: European right-to-repair legislative momentum reshapes the acquisition landscape toward vendors with pre-engineered battery swap architectures. Five-to-ten year viability hinges on software subscription revenue attachment rates exceeding hardware depreciation cycles. Signal to monitor: FCC equipment authorization backlog durations as proxy for competitive entry velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Battery Architecture Development | Right-to-repair compliance in European markets rewrites warranty cost structures for prepared vendors. |
| Direct-to-Enterprise Contract Expansion | Fortune 500 facilities management bundling in Seattle and Austin stabilizes recurring revenue beyond seasonal retail cycles. |
| Induction Heating Platform Migration | Power efficiency gains collapse resistive heating differentiation in premium tiers where German developers specify performance. |
| FCC Certification Relationship Investment | Equipment authorization backlog navigation accelerates product launch windows against competitors lacking regulatory affairs scale. |
| Sensor-Platform Convergence | Hydration tracking and caffeine monitoring algorithms extend customer lifetime value through software subscription attachment. |
Methodological Framework
Operator-level perspectives from facilities management procurement directors, thermal hardware engineering leads, enterprise channel sales heads, and lithium-ion supply chain managers anchored the qualitative base. Primary interview findings cross-referenced against FCC equipment authorization databases, METI battery safety filings, customs trade records for rare earth element flows, and SEC disclosures from publicly traded houseware vendors. Bottom-up unit shipment estimates triangulated against top-down enterprise contract value analysis.
Scenario-bracketing around regulatory acceleration and battery chemistry cost trajectories structured the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, end-user application context, connectivity technology level, and distribution channel structure. CAGRs derived from regression against historical enterprise procurement cycle data and lithium-ion energy density improvement curves. Forecast inputs incorporated RoHS compliance cost inflation assumptions and right-to-repair legislative probability weights.
The forecast holds incumbent behavior within observed patterns; aggressive modular battery standardization moves by Chinese contract manufacturers would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Global Single Serve Coffee Maker Market
Kitchen Appliances
Pressure Cooker Market
Kitchen Appliances
Australia Kitchen Appliances Market
Kitchen Appliances
China Mixer Grinder Market
Kitchen Appliances
Italy Kitchen Appliances Market
Kitchen Appliances
Germany Kitchen Appliances Market
Kitchen Appliances
India Mixer Grinder Market
Kitchen Appliances
US Smart Oven Market
Kitchen Appliances
Asia Pacific Household Electric Grills Market
Kitchen Appliances
Residential Cooking Grills Market
Kitchen Appliances
Electric Lunch Box Market
Kitchen Appliances
Global Smart Ovens Market
Kitchen Appliances
Smart Kitchen Appliances Market
Kitchen Appliances
Garlic Press Market
Kitchen Appliances
Hand-Held Mixer Market
Kitchen Appliances
Russia Household Electric Grill Market