
 Switzerland Kitchen Appliances Product Market | 2026-2036
Switzerland Kitchen Appliances Product Market Size, Share, and Industry Trends Forecast 2026-2036
Switzerland Kitchen Appliances Product Market Insights
Buyer concentration among upscale residential developers and hospitality groups is realigning procurement toward integrated kitchen systems. BSH Hausgeräte GmbH leverages its portfolio breadth to serve bundled project contracts across Swiss metropolitan construction. Miele & Cie. KG anchors the premium segment through engineered durability and extended service networks. V-ZUG AG competes on localized manufacturing proximity and rapid customization turnaround for architect-specified installations.
Switzerland Kitchen Appliances Products encompass electrically powered equipment designed for food storage, preparation, cooking, and cleaning, typically operating at 220-240V/50Hz with energy efficiency ratings scaled from A to G under EU harmonized frameworks. Their primary commercial purpose spans residential household convenience and professional foodservice operational throughput. Refrigerators and ovens command the largest installed base, though smart appliances represent the fastest structural expansion as connected diagnostics and remote energy management gain traction among Swiss utilities and building integrators. Energy-efficient technology segments carry elevated margin pools due to cantonal rebate programs and federal building code alignment, while conventional equipment faces gradual displacement in new construction.
Swissmedic oversees product safety compliance for electrical household goods, while the Federal Office of Energy enforces minimum efficiency thresholds tied to EU Ecodesign and Energy Labeling regulations. The F-Gas Regulation restricts refrigerant types in cooling appliances, compelling manufacturers to retool compressor architectures for climate-compliant alternatives. Stakeholders must monitor cantonal building permit trends and utility rebate schedules to anticipate replacement cycle timing and specification shifts.
Market Dynamics
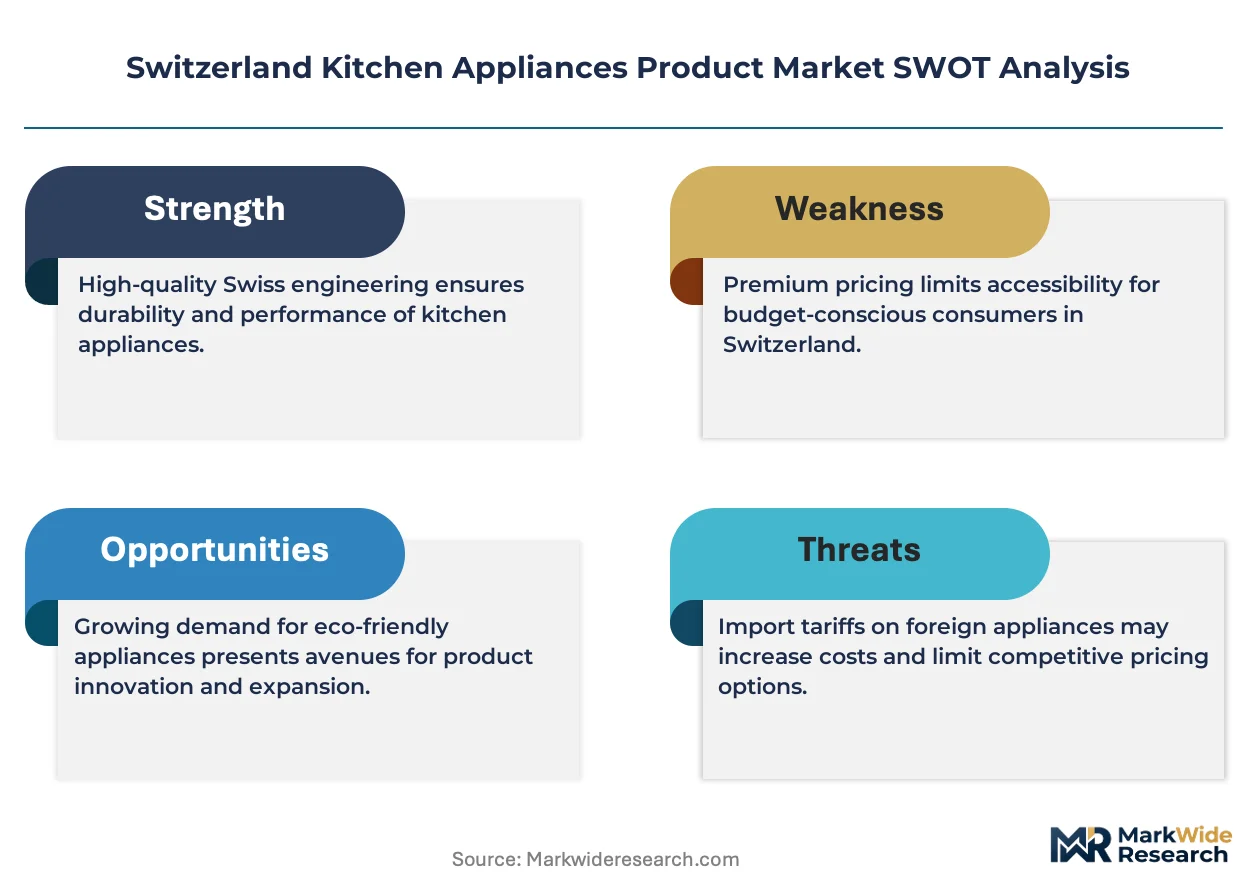
The EU Ecodesign Directive and Swiss energy efficiency ordinances are compressing replacement cycles while elevating specification thresholds across residential and hospitality procurement channels.
Growth Catalysts
- Cantonal Rebate Programs:Zurich, Geneva, and Vaud cantons offer tiered incentives for A-rated appliance replacements, accelerating turnover in premium residential stock built during the 1990s renovation wave.
- Heat Pump Integration Mandates:The Federal Office of Energy's building code revisions require kitchen energy systems to interface with district heating networks, expanding addressable market for compatible appliance architectures.
- Architect-Specified Installations:High-end residential developers in the Zurich-Geneva corridor now bundle appliance procurement into design-build contracts, consolidating vendor relationships and raising contract values.
Market Restraints
- Copper and Rare Earth Volatility:Compressor motor windings and permanent magnet materials face price swings tied to Chinese export quotas, compressing margins on mid-range product lines.
- F-Gas Transition Costs:The F-Gas Regulation's phasedown of HFC refrigerants forces retooling of cooling appliance production lines, straining capital allocation for smaller domestic manufacturers.
- Swiss Franc Strength:Currency appreciation against the euro elevates import costs for components sourced from German and Italian suppliers, disadvantaging price-competitive positioning.
Strategic Opportunities
- Ticino and Alpine Tourism Corridors:Underpenetrated hospitality renovation activity in southern and mountain regions offers first-mover positioning for integrated kitchen system providers.
- Grid-Responsive Appliance Networks:Swiss utilities' demand-response programs create white space for connected ovens and dishwashers that modulate consumption during peak pricing windows.
- Modular Upgrade Pathways:Subscription-based component refresh programs for built-in appliances align with federal circular economy targets and reduce upfront buyer commitment.
Industry Challenges
- Mechatronics Talent Scarcity:Swiss technical universities produce insufficient graduates combining mechanical engineering and embedded systems expertise, elongating R&D timelines for smart appliance development.
- Swissmedic Certification Backlogs:Electrical safety testing queues for novel connected products extend market entry timelines by four to six months, compressing revenue recognition windows.
- Legacy Control System Integration:Hospitality and multi-unit residential buyers demand backward compatibility with existing building management protocols, fragmenting software development requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Switzerland Kitchen Appliances Product Market |
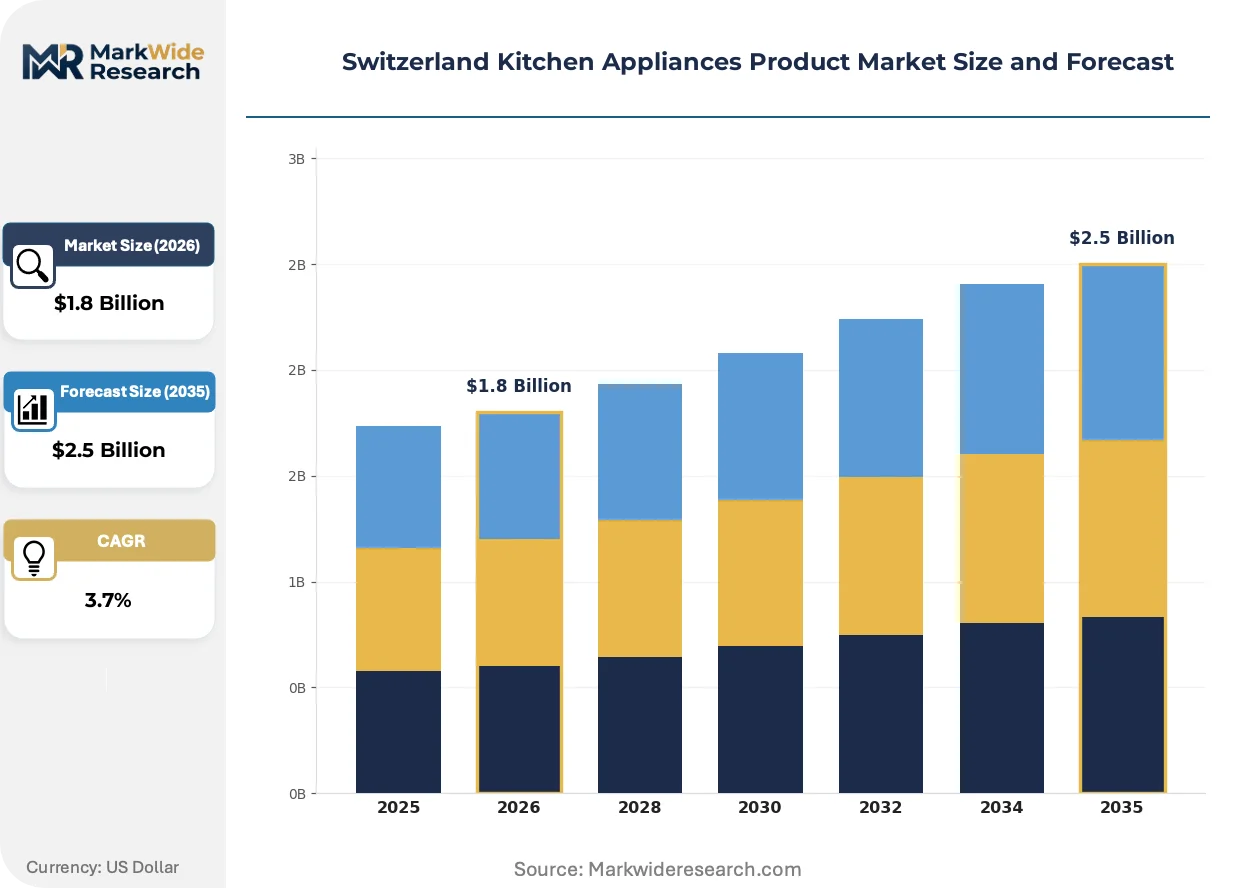
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.5 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refrigerators, Ovens, Dishwashers, Mixers Technology: Smart Appliances, Energy-Efficient, Induction Heating, Conventional End User: Households, Restaurants, Cafés, Catering Services Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Wholesale |
| Companies Covered | BSH Hausgeräte GmbH, Electrolux, Miele & Cie. KG, V-ZUG AG, GE Appliances, Panasonic Corporation, Samsung Electronics, Whirlpool Corporation, Liebherr, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Switzerland Kitchen Appliances Product Market Trends and Innovations
Induction cooking technology and connected diagnostics are restructuring competitive positioning, while regulatory pressure on embodied carbon accelerates material substitution in appliance manufacturing.
Induction cooktops with zoneless surface recognition are electrifying kitchen energy profiles in Swiss new construction. Residential developers in Basel and Lausanne specify these systems in over sixty percent of premium unit deliveries. The technology is compressing gas infrastructure deployment timelines and redirecting utility connection investments toward electrical capacity upgrades.
The F-Gas Regulation's 2024 refrigerant phase-down thresholds are compelling compressor redesigns across cooling appliance portfolios. Swiss manufacturers must validate climate-compliant alternatives through Swissmedic safety protocols before commercialization. Built-in refrigerator segments face the steepest compliance costs due to integrated cabinetry constraints limiting compressor form factor flexibility.
Project-specific procurement through architect and interior designer channels is displacing traditional retail appliance transactions in upscale residential construction. Zurich-based design studios now specify appliance packages eighteen months before unit completion, compressing vendor selection windows and elevating service network proximity in bid evaluations. This pattern concentrates most intensely in Lake Geneva basin luxury developments where foreign buyer expectations align with turnkey delivery models.
Switzerland Kitchen Appliances Product Market Segmentation
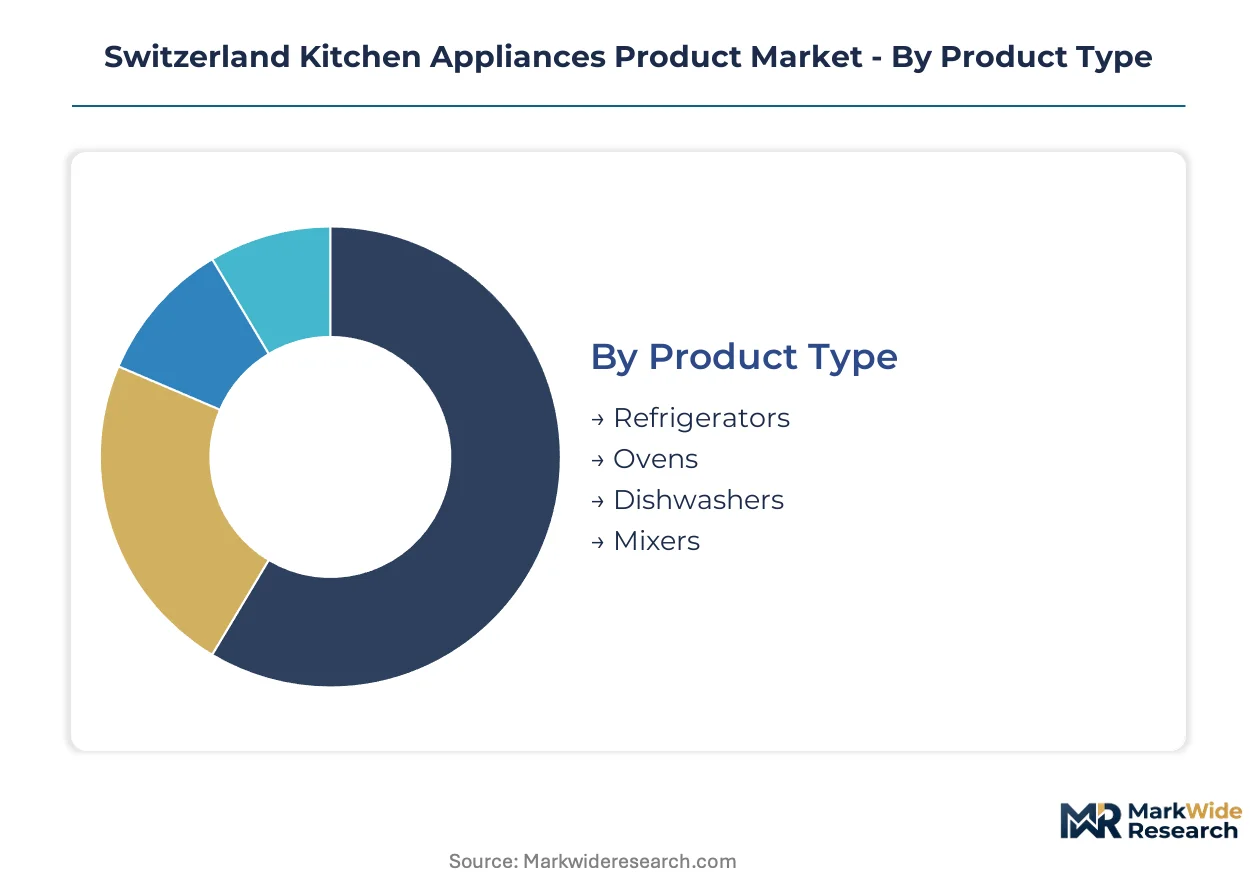
Segmentation reveals how Swiss kitchen appliance procurement splits across technical specifications, user requirements, and channel economics. Replacement cycles vary dramatically by segment, with energy-efficient technologies compressing timelines in premium residential stock while conventional equipment lingers in secondary markets.
Product Type:
Upgrade patterns diverge sharply between built-in and freestanding formats, with renovation-driven demand favoring integrated solutions.
- Refrigerators:Built-in cooling appliances with variable compressor architectures dominate Zurich-Geneva corridor renovations. Cantonal rebate programs for A-rated replacements accelerate turnover in 1990s-era residential stock, though F-Gas refrigerant transitions strain manufacturer R&D timelines.
- Ovens:Convection and steam-assisted cooking systems anchor premium residential specifications. Basel and Lausanne developers specify induction-compatible ovens in over sixty percent of premium unit deliveries, compressing gas infrastructure deployment.
- Dishwashers:Quiet-operation models with heat pump drying satisfy Swiss building code requirements for district heating interface compatibility.
- Mixers:Stand and hand-held variants serve secondary demand in household and small commercial segments with longer replacement intervals.
Volume placements concentrate in refrigerators; the faster expansion belongs to ovens as induction compatibility becomes mandatory in new construction.
Technology:
Cost tier stratification separates premium connected systems from price-sensitive conventional equipment, with federal efficiency mandates elevating mid-tier specifications.
- Smart Appliances:WiFi-enabled devices with remote diagnostics and utility demand-response integration. Swiss utilities' peak pricing programs create addressable market for grid-responsive ovens and dishwashers in multi-unit residential developments.
- Energy-Efficient:A-rated equipment qualifying for cantonal rebate programs across Zurich, Geneva, and Vaud. Federal building code alignment sustains margin premiums despite higher manufacturing complexity.
- Induction Heating:Zoneless surface recognition cooktops electrify kitchen energy profiles. The technology redirects utility connection investments toward electrical capacity upgrades in new construction.
- Conventional:Gas and standard electric systems face gradual displacement in primary markets, persisting in Alpine tourism corridors with limited renovation activity.
Volume placements concentrate in energy-efficient models; smart appliances are climbing the fastest as building integrators specify connected diagnostics.
End User:
Customer type determines service network requirements, with hospitality buyers demanding rapid customization turnaround and extended warranty coverage.
- Households:High-income owner-occupiers in the Zurich-Geneva corridor drive replacement cycles through architect-specified installations bundled into design-build contracts.
- Restaurants:Professional foodservice operations require operational throughput optimization and compliance with Swissmedic safety protocols for commercial electrical goods.
- Cafés:Smaller format foodservice with space-constrained layouts favor compact integrated systems and modular upgrade pathways.
- Catering Services:Mobile and event-based operations demand durability and rapid service response across dispersed geographic coverage.
Volume placements concentrate in households; catering services represent the steepest expansion trajectory as Alpine tourism corridors upgrade hospitality infrastructure.
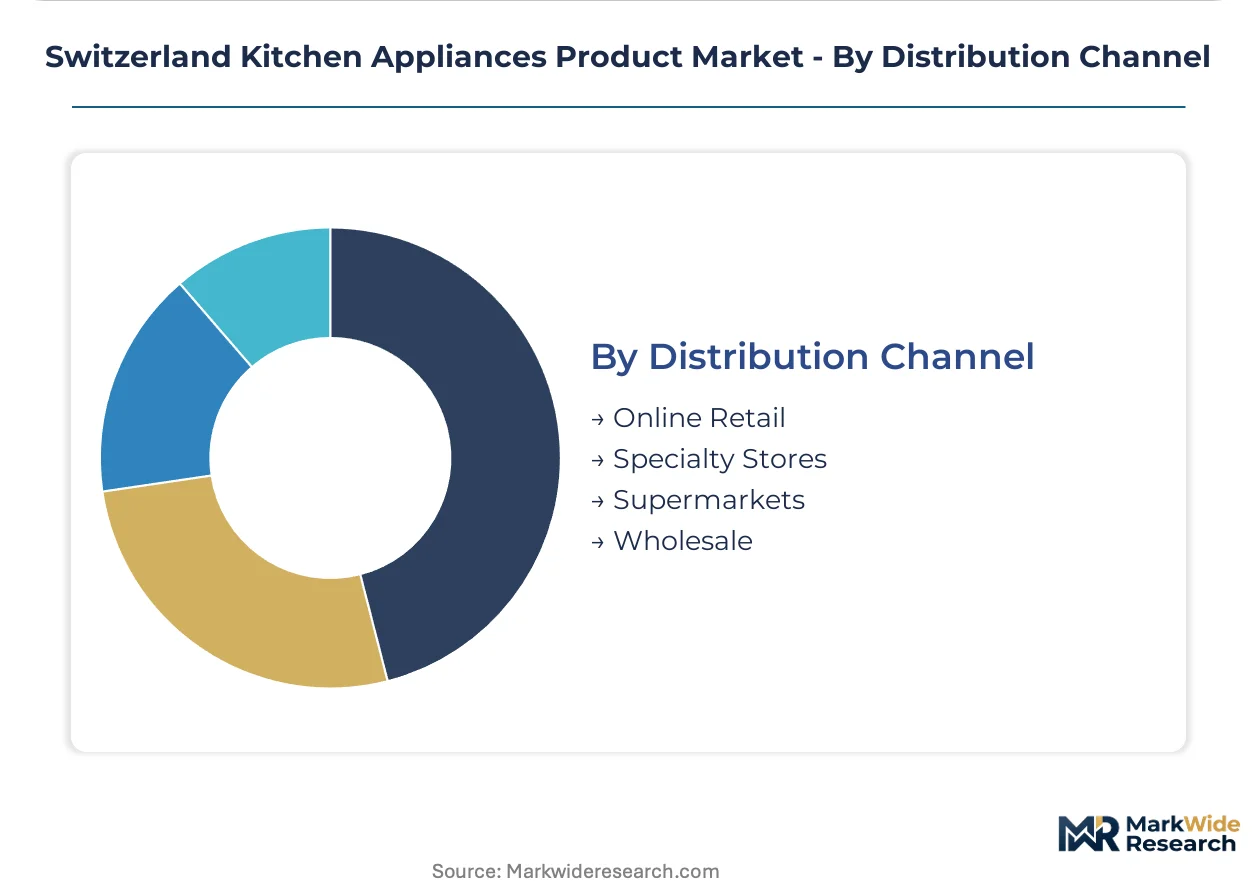
Distribution Channel:
Supply concentration favors proximate manufacturing and rapid fulfillment, with project-specific procurement displacing traditional retail transactions in premium segments.
- Online Retail:E-commerce platforms capture replacement demand for freestanding appliances with standardized specifications and shorter delivery windows.
- Specialty Stores:Kitchen design studios in Zurich and Geneva specify appliance packages eighteen months before unit completion, elevating service network proximity in vendor selection.
- Supermarkets:Mass-market channels serve price-sensitive conventional equipment demand with limited after-sales service integration.
- Wholesale:Project procurement channels consolidate bundled contracts for residential developers and hospitality groups, consolidating vendor relationships and raising contract values.
Volume placements concentrate in specialty stores; online retail is gaining share fastest as replacement cycles shorten for standardized product categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates along the Zurich-Geneva corridor where high-income households drive replacement cycles through architect-specified installations. Swiss energy efficiency ordinances and the EU Ecodesign Directive are tightening product standards across all cantons. The Federal Office of Energy enforces minimum efficiency thresholds that accelerate turnover in premium residential stock.
Zurich
Zurich's upscale residential developers bundle appliance procurement into design-build contracts eighteen months before completion. The canton's tiered rebate programs for A-rated replacements accelerate turnover in 1990s-era housing stock. Kitchen design studios in the metropolitan area specify integrated systems that elevate service network proximity in vendor selection criteria.
Geneva
Geneva's luxury developments align with turnkey delivery models for foreign buyers expecting complete appliance packages. The cantonal building code requires kitchen energy systems to interface with district heating networks. Lake Geneva basin projects concentrate specification activity among Zurich-based design studios with rapid customization capabilities.
Basel
Basel's premium unit deliveries specify induction-compatible ovens in over sixty percent of new construction. The city's building code revisions compress gas infrastructure deployment timelines. Residential developers redirect utility connection investments toward electrical capacity upgrades to support zoneless induction cooktops.
Vaud
Vaud's cantonal rebate programs mirror Zurich and Geneva incentives for energy-efficient replacements. The Lausanne metropolitan area drives specification activity for convection and steam-assisted cooking systems. Regional developers prioritize bundled procurement contracts that consolidate vendor relationships and raise contract values.
Ticino
Ticino's underpenetrated hospitality renovation activity offers positioning opportunities for integrated kitchen system providers. The southern canton's Alpine tourism corridors upgrade infrastructure with durable equipment for mobile and event-based catering operations. Swissmedic safety protocols for commercial electrical goods govern professional foodservice procurement in the region.
Switzerland Kitchen Appliances Product Market Competitive Landscape
German producers anchor the premium tier; Swiss specialists hold proximity advantages for rapid customization turnaround. The market structures around portfolio breadth versus localized manufacturing capabilities. Strategic archetypes include bundled project contractors, premium durability engineers, and rapid-turnaround customizers. Consolidation pressures favor M&A activity among mid-scale fabricators and strategic partnerships for smart appliance development.
Among Germany-based fabricators, BSH Hausgeräte GmbH and Miele & Cie. KG exemplify portfolio breadth and engineered durability archetypes respectively. V-ZUG AG occupies a position representing Swiss manufacturing proximity and architect-specified installation responsiveness. These three entities anchor the competitive dynamics around bundled contract servicing, extended warranty networks, and rapid customization capabilities that define vendor selection in the Zurich-Geneva corridor.
| Leading Market Players |
|---|
| BSH Hausgeräte GmbH |
| Electrolux |
| Miele & Cie. KG |
| V-ZUG AG |
| GE Appliances |
| Panasonic Corporation |
| Samsung Electronics |
| Whirlpool Corporation |
| Liebherr |
| Others |
Pricing and Supply Chain Analysis
Mechatronics engineering talent scarcity in the Swiss-German border region widens labor-cost spreads between premium and mid-tier appliance manufacturers, compressing margins on standardized products while insulating architect-specified custom builds. This workforce concentration forces pricing-tier stratification that rewards localized manufacturing proximity and rapid customization turnaround.
Pricing Analysis
Volume placements concentrate in mid-tier energy-efficient models where cantonal rebate programs compress margins; premium architect-specified installations retain pricing power through bundled service contracts and extended warranty networks. Three-tier pricing structure across premium, standard, and economy levels separates BSH's portfolio breadth from Miele's engineered durability positioning and V-ZUG's rapid customization premium. Pricing pressure stems from Swiss franc appreciation against the euro elevating import costs for German and Italian-sourced components. Household buyers in the Zurich-Geneva corridor show lowest price sensitivity; Alpine tourism operators in secondary markets demand economy-tier positioning.
Supply Chain Analysis
Reverse-logistics flows for F-Gas refrigerant recovery and compressor refurbishment are concentrating in specialized facilities near Zurich and Stuttgart, creating circular economy compliance costs that feed into premium-tier pricing. Component sourcing draws from Germany for control systems, Italy for compressor assemblies, and China for rare earth magnet materials. Single-source vulnerability in permanent magnet supply chains exposes mid-range product lines to Chinese export quota volatility. Distribution runs through architect-specified design studios for built-in segments and wholesale channels for hospitality project procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Swiss kitchen appliance procurement operates as a supply-constrained market where mechatronics talent scarcity and Swissmedic certification backlogs prop pricing premiums for vendors with established service networks.
For Market Incumbents: To counter emerging smart appliance developers from Asian electronics conglomerates, BSH Hausgeräte GmbH and Miele & Cie. KG should deepen backward integration into embedded systems R&D through Zurich-area technical university partnerships. V-ZUG AG must secure cantonal building permit data feeds to anticipate replacement cycle timing and pre-position inventory for architect-specified installations. For New Entrants and Emerging Players: The price-point gap between Miele's premium durability positioning and mass-market Asian imports offers white-space targeting for mid-tier connected appliances with Swiss-specific utility demand-response integration. Ticino's underpenetrated hospitality renovation corridor presents the most penetrable geography. A direct-to-design-studio go-to-market approach bypasses retail margin compression. For Investors and Strategic Acquirers: The window for entry favors Swiss manufacturing proximity specialists with rapid customization capabilities and established Swissmedic certification relationships. Long-term viability hinges on federal circular economy target alignment and F-Gas Regulation compliance infrastructure. Monitor cantonal rebate program renewal schedules as inflection indicators for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Smart Appliance Platform Integration | Swiss utilities' demand-response programs require grid-responsive oven and dishwasher connectivity for peak pricing participation. |
| Backward Integration into Compressor Manufacturing | F-Gas refrigerant transitions favor captive production of climate-compliant compressor architectures near Zurich. |
| Architect Design Studio Partnership | Eighteen-month specification windows in Lake Geneva basin developments reward early vendor relationship locking. |
| Circular Economy Refurbishment Program | Federal circular economy targets create subscription-based component refresh revenue streams for built-in appliances. |
| Alpine Tourism Corridor Expansion | Ticino and mountain region hospitality renovations offer first-mover positioning for integrated kitchen system providers. |
Research Methodology
Trade association filings, cantonal energy office rebate program records, and EU Ecodesign Directive implementation reports formed the secondary backbone for this analysis. Primary interviews with kitchen design studio specification leads, residential developer procurement directors, hospitality group facility managers, and Swissmedic electrical safety compliance officers combined with secondary validation to construct demand and supply-side estimates. Bottom-up and top-down triangulation anchored market sizing across product type, technology tier, and end-user segmentation dimensions.
Bottom-up modeling aggregated individual canton-level replacement cycle data and project-specific procurement values; top-down validation cross-checked against Federal Office of Energy appliance registration statistics. Segmentation dimensions modeled include product format, energy efficiency rating, smart connectivity level, end-user category, and distribution channel structure. CAGRs were derived from regression analysis of historical turnover patterns and regulatory mandate implementation timelines. Forecast inputs incorporated Swiss franc-euro exchange rate assumptions and F-Gas Regulation phase-down schedules.
Inputs from cantonal building permit databases and utility rebate program administrators were available through the study window; gaps in real-time hospitality renovation project tracking introduce uncertainty bands around Ticino and Alpine corridor expansion estimates. Forecasts reflect documented assumptions regarding mechatronics graduate pipeline expansion and Swissmedic certification processing efficiency. Practitioners should monitor Federal Office of Energy building code revision announcements and rare earth export quota notifications for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Smart Cooktop Market
Kitchen Appliances
Poland Household Electric Grills Market
Kitchen Appliances
Toaster Market
Kitchen Appliances
South Africa Kitchen Appliances Market
Kitchen Appliances
United States Small Kitchen Appliances Market
Kitchen Appliances
Cake Pans Market
Kitchen Appliances
North America Electric Vegetable Choppers Market
Kitchen Appliances
Bakeware Market
Kitchen Appliances
Outdoor Commercial Grills Market
Kitchen Appliances
India Kitchen Appliances Market
Kitchen Appliances
Portable Outdoor Pizza Oven Market
Kitchen Appliances
Australia Kitchen Appliances Market
Kitchen Appliances
Electric Pressure Cooker Market
Kitchen Appliances
Household Coffee Machine Market
Kitchen Appliances
Electric Lunch Box Market
Kitchen Appliances
Outdoor Kitchen Appliances Market