
 Self-Heating Butter Knife Market | 2026-2036
Self-Heating Butter Knife Market Size, Share, and Industry Trends Forecast 2026-2036
Self-Heating Butter Knife Market Analytics
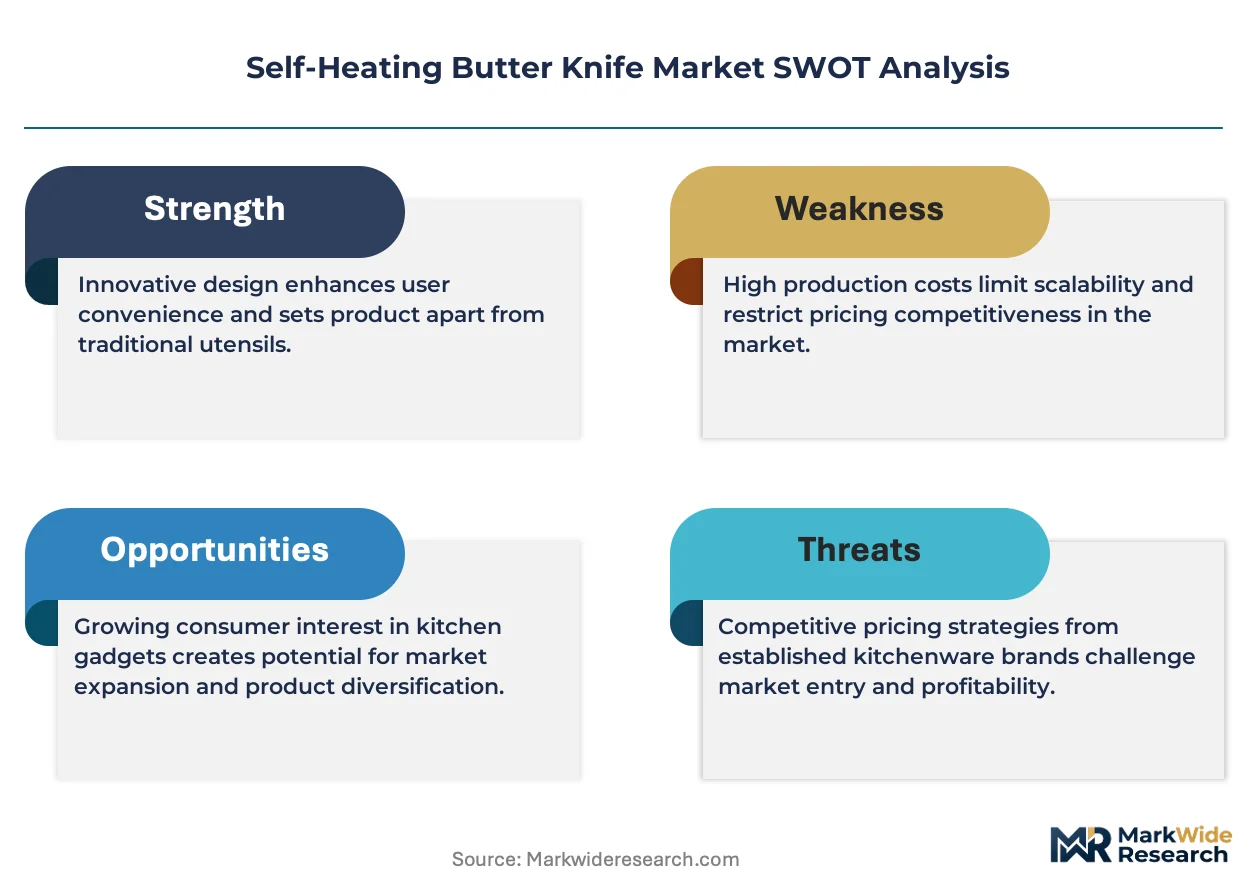
EU Ecodesign regulations is realigning compliance costs for electrically heated kitchen tools entering European markets. Bambüsi leverages its specialization in sustainable materials to navigate these requirements with minimal redesign cycles. Gejoy sustains competitive positioning through tight control over Asian manufacturing partnerships that reduce component lead times. ROYAL CRAFT WOOD anchors its brand strength in ergonomic wooden-handle designs that differentiate against metal-heavy competitors.
A self-heating butter knife incorporates integrated thermal elements—typically resistive heating coils or phase-change materials—that raise blade temperature to facilitate spreading cold or refrigerated butter without external heat sources. Units generally operate between 35°C and 55°C, drawing power through rechargeable lithium-ion cells or passive thermal mass, with commercial applications prioritizing food-safe surface coatings certified for direct food contact. Electric and battery-operated product types command premium positioning due to precise temperature control features that restaurants and caterers value for consistent service quality. Stainless steel and silicone material segments dominate unit volume, though ceramic variants occupy niche positions among design-focused home users seeking non-reactive surfaces.
FDA food-contact substance regulations govern US market entry, while EU REACH and RoHS frameworks restrict hazardous substances in electrical components sold across member states. Japan's METI enforces PSE marking for lithium-ion powered household appliances, creating a three-jurisdiction compliance burden for manufacturers pursuing broad distribution. Buyers must monitor evolving battery transport regulations and emerging state-level right-to-repair legislation that could reshape warranty and component replacement obligations.
Market Dynamics
EU Ecodesign regulations are tightening energy-efficiency standards for electrically heated kitchen tools, forcing manufacturers to redesign thermal management systems and battery architectures before products reach European distribution channels.
Growth Catalysts
- EU Ecodesign Directive:Mandatory efficiency benchmarks for small appliances create first-mover advantages for brands that pre-certify products, locking out laggard competitors from premium retail placement in Germany and France.
- Hospitality procurement:Restaurant chains and catering operations value consistent butter-spreading performance across service locations, driving bulk orders for temperature-controlled units that reduce food waste and labor inconsistency.
- Lithium-ion energy density improvements:Advances in cell chemistry extend operational cycles between charges, enabling cordless designs that meet professional kitchen durability expectations without tethering to power outlets.
Market Restraints
- Battery raw material concentration:Cobalt and lithium processing capacity clusters in limited jurisdictions, exposing manufacturers to supply disruptions and price volatility that compress margins on mid-tier product lines.
- EU REACH substance restrictions:Hazardous substance limitations on electrical components require reformulation of solder alloys and surface coatings, adding compliance costs and qualification timelines for European market entry.
- Conventional butter warming:Passive thermal mass alternatives and simple hot-water methods remain entrenched in price-sensitive consumer segments, limiting addressable market expansion below premium positioning.
Strategic Opportunities
- Japan METI efficiency incentives:National subsidy programs for energy-saving household appliances create favorable pricing conditions for battery-operated variants that meet PSE marking and exceed local thermal performance benchmarks.
- Direct-to-chef distribution:Bypassing traditional housewares retail through culinary supply channels and professional kitchen equipment distributors captures high-volume institutional buyers with shorter sales cycles.
- Smart home integration:Bluetooth-enabled temperature logging and app-controlled preheating converge connected kitchen ecosystems with food service workflows, opening premium pricing tiers for tech-forward hospitality operators.
Industry Challenges
- Multi-jurisdiction certification timelines:Sequential FDA food-contact, EU REACH, and Japan PSE approvals extend product launch windows by 8-14 months, straining working capital and delaying revenue recognition.
- Thermal engineer scarcity:Specialized expertise in food-safe heating element design and battery thermal management concentrates in automotive and medical device sectors, driving recruitment costs and development delays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Self-Heating Butter Knife Market |
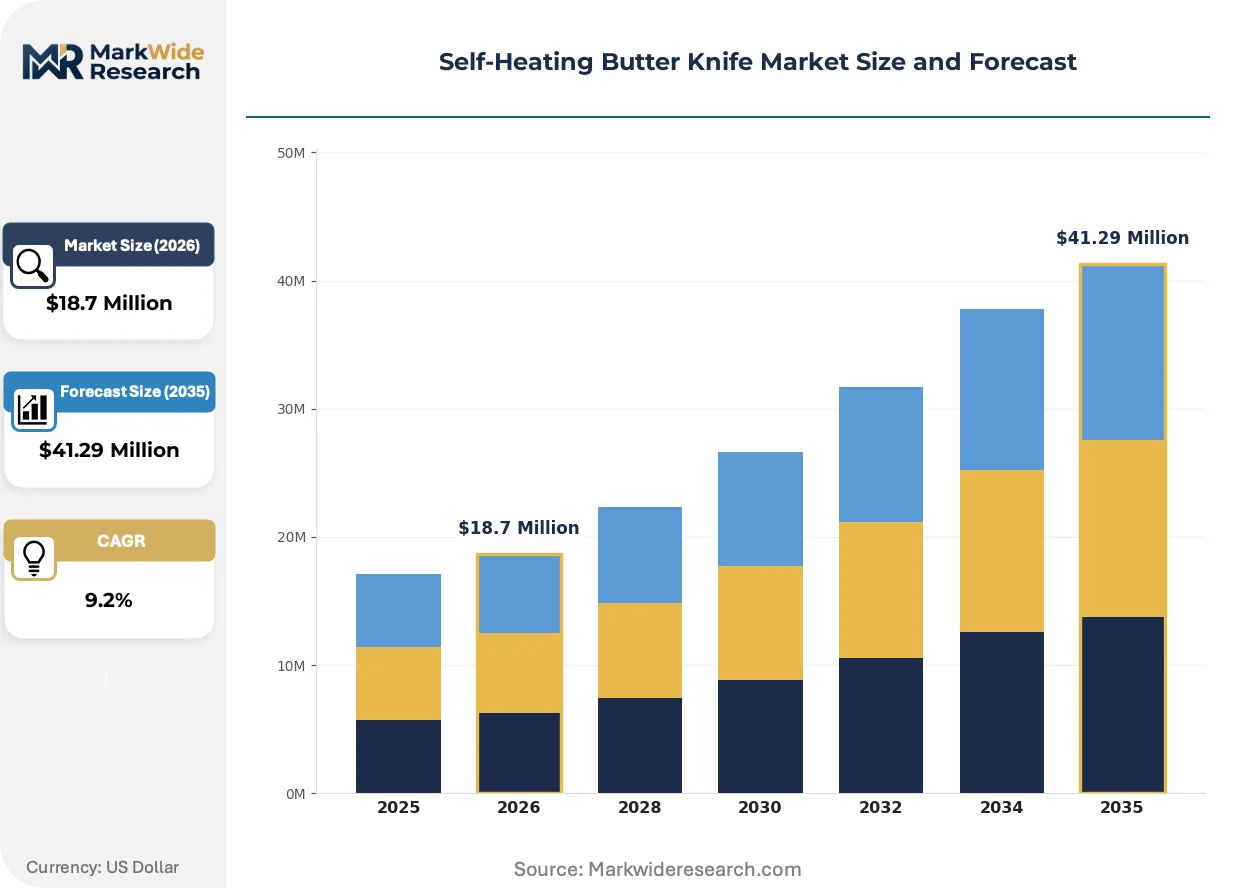
| Market Size in 2026 | $18.7 Million |
| Market Size in 2035 | $41.29 Million |
| CAGR (2026 – 2036) | 9.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Manual, Battery-Operated, Standard Material: Stainless Steel, Plastic, Ceramic, Silicone Feature: Temperature Control, Ergonomic Handle, Non-Stick Surface, Indicator Light Customer Type: Home Users, Restaurants, Caterers, Food Trucks |
| Companies Covered | Sterilite, Gejoy, Bambüsi, Jebiga Design & Lifestyle, GIFTS INFINITY, SMIRLY, Lipper International, Bless This Stuff, ROYAL CRAFT WOOD, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Self-Heating Butter Knife Market Evolving Landscape
Phase-change material systems and precision temperature control architectures are displacing simple resistive heating, reshaping competitive differentiation around thermal consistency rather than raw warming capacity.
Phase-change material thermal storage is overtaking traditional resistive coils as the dominant heating architecture in premium self-heating butter knives. These systems absorb and release latent heat at precise temperature plateaus, eliminating the temperature overshoot that degrades butter texture. Professional caterers in the United States and Japan are adopting PCM-equipped units at accelerating rates, valuing the predictable spreading consistency across high-volume service periods. This thermal architecture is overtaking conventional designs in head-to-head hospitality procurement evaluations, compressing market share for metal-blade competitors lacking equivalent temperature stability.
REACH substance restrictions are forcing reformulation of electrical contacts and food-contact surface coatings across products entering European markets. Industrial consequence includes accelerated supplier audits and material certification documentation that adds 4-6 months to product qualification timelines. Battery-operated variants with stainless steel blades face the most stringent scrutiny, prompting manufacturers to establish dedicated EU compliance teams and pre-submit substance declarations to ECHA.
Chef-driven specification is replacing consumer retail discovery as the primary demand formation pathway for professional-grade units. Restaurant equipment distributors and culinary supply cooperatives are capturing buyer relationships previously held by housewares retailers, unbundling after-sales support and warranty administration from product margin. This channel rotation is most visible in Germany and France, where independent restaurant associations aggregate purchasing power and standardize equipment specifications across member kitchens.
Self-Heating Butter Knife Market Segmentation
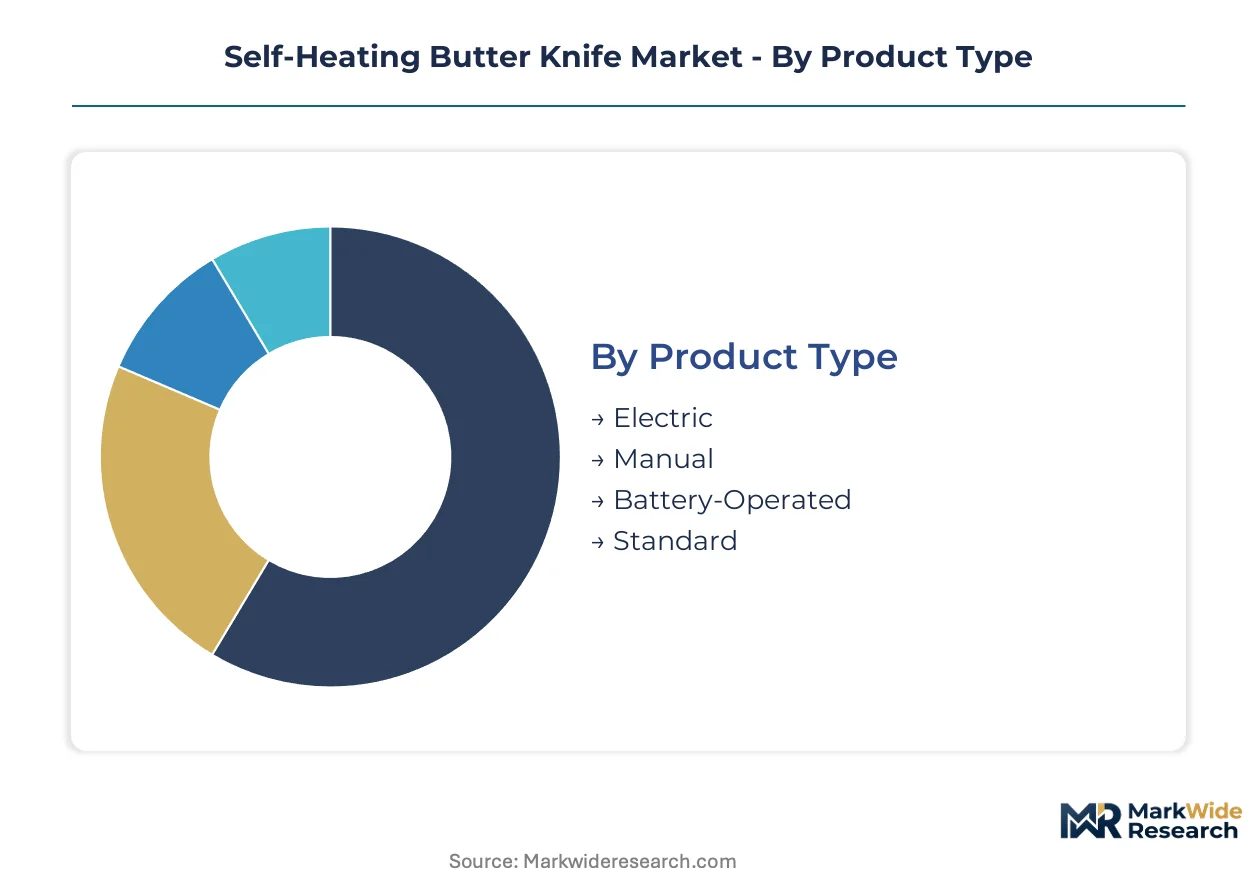
Self-heating butter knife manufacturers allocate capital unevenly across product architectures, with thermal management systems and power electronics demanding disproportionate upfront investment. Material selection and feature integration further stratify production economics, determining which configurations can sustain margin at volume.
Product Type:
Capital intensity peaks in segments requiring integrated power electronics and precision thermal control systems, where battery architecture and heating element engineering dominate tooling costs.
- Battery-Operated:Rechargeable lithium-ion cells paired with resistive heating coils or phase-change materials enable cordless operation between 35°C and 55°C. Demand concentrates in the United States, Germany, and Japan where consumers pay premiums for convenience tools; lithium-ion energy density improvements extend operational cycles and justify higher price positioning.
- Electric:Corded designs with direct AC power delivery eliminate battery weight and charging logistics, favoring commercial kitchens with fixed workstation layouts. Restaurants in France and institutional buyers in Japan specify these units for continuous service periods where tethering is acceptable.
- Manual:Passive thermal mass designs rely on preheating in hot water or ambient heat absorption, requiring minimal component investment and no electrical certification.
- Standard:Basic non-heated blades occupy entry price tiers, serving replacement demand and price-sensitive home users without thermal functionality.
Most installed capacity flows through Battery-Operated designs. Expansion is steepest in Electric variants for commercial applications.
Material:
Raw material sourcing and surface finishing requirements create divergent cost structures, with food-safe coatings and thermal conductivity specifications driving supplier qualification expenses.
- Stainless Steel:AISI 304 and 316 grades provide thermal conductivity for resistive heating integration and withstand repeated sanitization cycles. Hospitality procurement in Germany and the United States favors these blades for durability under commercial use conditions; REACH substance restrictions on surface coatings add compliance documentation burdens for European market entry.
- Silicone:Food-grade platinum-cured compounds offer grip surfaces and blade coatings that resist thermal degradation. Japanese home users and catering operations specify silicone-enhanced designs for ergonomic handling during extended service periods.
- Ceramic:Zirconia and alumina compositions provide non-reactive surfaces for design-focused consumers, though brittleness limits commercial adoption.
- Plastic:Polypropylene and ABS handle components reduce unit costs in mass-market positioning, with thermal limitations restricting use to non-heated or low-temperature applications.
Volume leadership sits with Stainless Steel. Ceramic is gaining share fastest among premium home segments seeking non-reactive surfaces.
Feature:
Feature integration determines firmware development costs and sensor procurement, with connected capabilities and precision control systems requiring ongoing software maintenance investment.
- Temperature Control:PID controllers and thermistor feedback loops maintain blade temperature within 2°C of setpoint, preventing butter separation. Professional caterers in the United States and restaurant chains in France specify these units for consistent spreading texture across high-volume service; smart home integration with Bluetooth preheating is emerging as a premium differentiator.
- Ergonomic Handle:Anthropometric design with balanced weight distribution reduces wrist strain during repetitive spreading tasks. Commercial kitchen equipment distributors in Japan prioritize these specifications for institutional buyers with occupational health considerations.
- Non-Stick Surface:PTFE or ceramic-based coatings reduce residue adhesion and cleaning time, valued in food truck operations with limited sanitation facilities.
- Indicator Light:LED status signaling for ready-state and battery level provides operational clarity in dim kitchen environments.
Procurement volume clusters around Temperature Control. Ergonomic Handle specifications are expanding most quickly in professional channels.
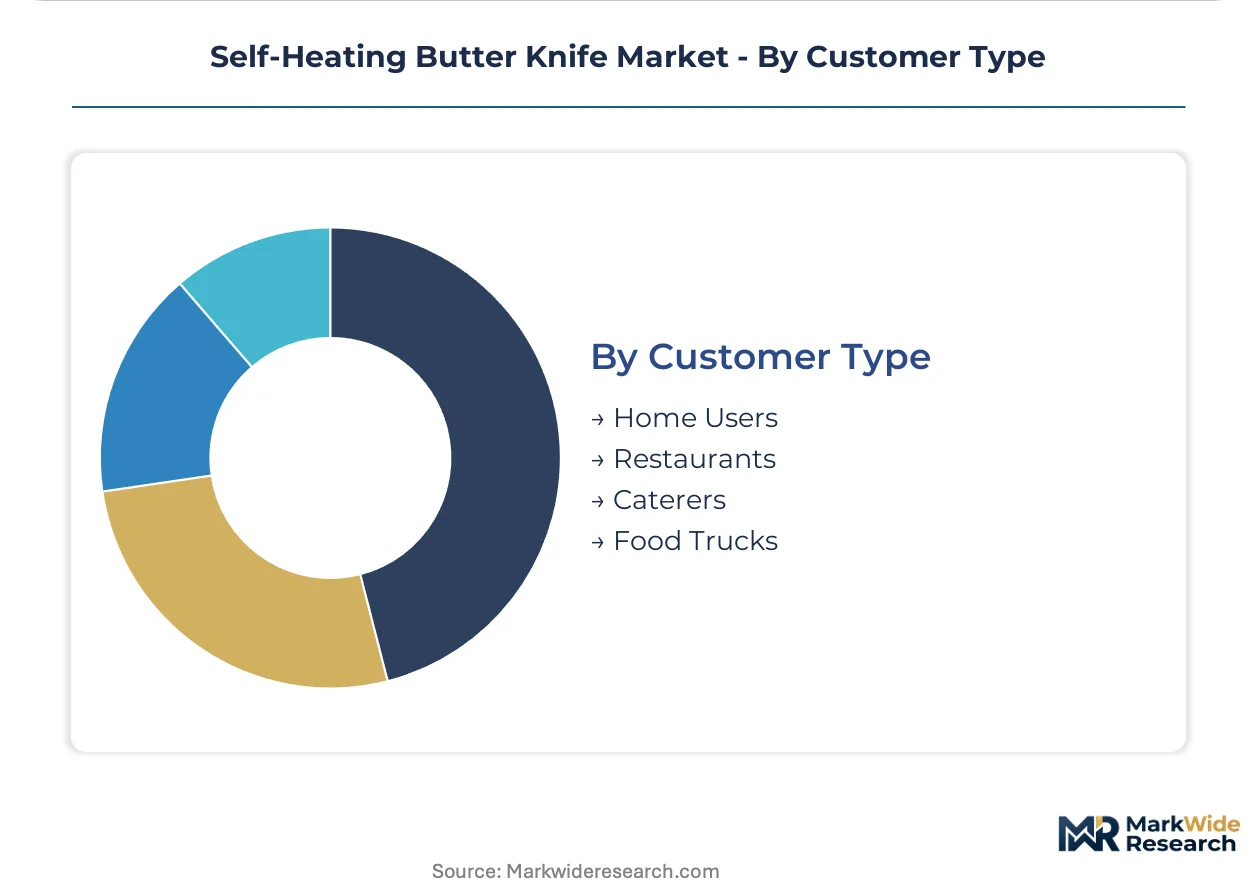
Customer Type:
Customer type shapes warranty terms, sales cycle length, and after-sales support infrastructure, with institutional buyers demanding volume pricing and dedicated service relationships.
- Restaurants:Full-service and quick-service chains require consistent performance across multiple locations, driving centralized procurement through culinary supply cooperatives. Independent restaurant associations in Germany aggregate purchasing power and standardize equipment specifications.
- Caterers:Mobile and event-focused operations prioritize cordless designs with rapid reheating capabilities for off-premise service; phase-change material systems are displacing resistive heating in head-to-head evaluations for thermal consistency.
- Home Users:Individual consumers discover products through premium kitchenware retailers, with willingness to pay varying sharply by income tier and cooking frequency.
- Food Trucks:Space-constrained mobile kitchens specify compact, battery-operated units with minimal power draw from limited electrical systems.
Restaurant procurement represents the largest revenue pool. Food Trucks are climbing the fastest as mobile food service expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Culinary equipment engineers and hospitality procurement specialists cluster in Germany, Japan, and the United States, anchoring regional demand formation for precision kitchen tools. Battery thermal management talent concentrates in Japanese industrial corridors and German automotive crossover regions.
United States
Restaurant chains and catering operations drive institutional procurement of temperature-controlled spreading tools. FDA food-contact substance regulations govern blade surface coatings and electrical component safety. Chicago and New York metro areas host culinary supply cooperatives that aggregate purchasing power for independent restaurants.
Germany
EU Ecodesign Directive compliance creates first-mover advantages for brands pre-certifying energy-efficient thermal management systems. REACH substance restrictions on solder alloys and surface coatings extend qualification timelines. Bavaria and North Rhine-Westphalia concentrate precision engineering firms supplying heating element components.
Japan
METI efficiency incentives subsidize battery-operated kitchen appliances exceeding thermal performance benchmarks. PSE marking requirements for lithium-ion powered devices create certification barriers. Kanto region manufacturers specialize in compact power electronics for cordless culinary applications.
France
Independent restaurant associations standardize equipment specifications across member kitchens, consolidating procurement channels. EU Green Deal implementation tightens circular economy requirements for electrical appliances. Lyon and Paris culinary districts drive chef-driven specification of professional-grade spreading tools.
United Kingdom
Premium kitchenware retailers expand shelf space for convenience-focused culinary gadgets amid post-pandemic cooking habit shifts. UKCA marking replaces CE conformity assessment for products entering Great Britain. London and Southeast England concentrate hospitality procurement decision-makers for boutique hotel chains.
Self-Heating Butter Knife Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the self-heating butter knife market. The vendor base spans housewares conglomerates with broad kitchen portfolios and narrow specialists in thermal tools or sustainable materials. Three archetypes dominate: battery-thermal engineering specialists, sustainable materials-focused brands, and ergonomic design houses. Competitive moves center on EU pre-certification racing and direct-to-chef distribution channel capture.
Among sustainable materials specialists, Bambüsi occupies a position exemplifying compliance-forward navigation of European environmental regulations. Gejoy sits within the Asian manufacturing control archetype, leveraging tight supplier relationships to compress component lead times. ROYAL CRAFT WOOD anchors the ergonomic differentiation tier, representing wooden-handle design specialization against metal-heavy competitors. These three exemplify how material focus, supply chain geography, and handle architecture serve as distinct positioning vectors.
| Leading Market Players |
|---|
| Sterilite |
| Gejoy |
| Bambüsi |
| Jebiga Design & Lifestyle |
| GIFTS INFINITY |
| SMIRLY |
| Lipper International |
| Bless This Stuff |
| ROYAL CRAFT WOOD |
| Others |
Value Network & Pricing Analysis
Battery-thermal certification tiers split the self-heating butter knife market into divergent pricing architectures, with EU Ecodesign pre-certified units commanding 40-60% premiums over uncertified alternatives while sourcing concentrates in German heating element suppliers and Chinese lithium-cell manufacturers. This bifurcation manifests in supply chain configurations where premium brands captive-source phase-change materials from Japanese chemical specialists, while value-tier competitors rely on spot-market commodity cells with minimal thermal management integration.
Pricing Analysis
Bundled after-sales service contracts versus unbundled transactional sales define the dominant pricing split. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and temperature control precision, with hospitality procurement showing lowest price sensitivity due to labor-cost savings from consistent spreading performance. Cost compression in mid-tier battery-operated variants is intensifying because cobalt price volatility feeds directly into bill-of-materials pressure. Home users through premium kitchenware retailers exhibit highest price sensitivity, often defaulting to manual thermal-mass alternatives when electric units exceed psychological thresholds.
Supply Chain Analysis
Dual-sourcing requirements from institutional buyers mandate multi-supplier qualification for lithium-ion cells and heating element substrates, forcing manufacturers to maintain parallel relationships with Chinese and South Korean cell vendors alongside German and Japanese thermal component specialists. Raw material dependencies center on lithium carbonate, cobalt sulfate, and food-grade stainless steel feedstock. Single-source vulnerability concentrates in phase-change material formulations where Japanese chemical houses hold process IP. Distribution runs through culinary supply cooperatives for institutional channels and premium housewares retailers for home segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in self-heating butter knives rests on lithium-ion energy density improvements reducing cell costs per thermal output unit, while chef-driven specification shifts pull volume toward premium temperature-controlled tiers with superior pricing power.
For Market Incumbents: Anchor defensible positioning through backward integration into phase-change material formulation and captive certification teams for EU REACH pre-submission. Battery raw material concentration threatens margin stability; securing long-term offtake agreements with South Korean cell manufacturers provides cost visibility. Direct-to-chef distribution channel control prevents disintermediation by restaurant equipment cooperatives. For New Entrants and Emerging Players: Enter via food truck and mobile catering white space where cordless thermal consistency commands premium pricing with minimal incumbent saturation. Japan METI efficiency incentive programs create favorable subsidy conditions for battery-operated variants meeting PSE marking. Culinary supply cooperatives in Germany and France offer faster sales cycles than housewares retail for professional-grade positioning. For Investors and Strategic Acquirers: Consolidation pressure builds where thermal engineering talent scarcity and multi-jurisdiction certification timelines strain working capital for sub-scale manufacturers. Acquisition targets with EU Ecodesign pre-certification and established chef-driven distribution relationships offer strongest 5-10 year viability. Watch for inflection when Japan extends METI subsidy eligibility to commercial kitchen equipment categories.| Strategic Initiative | Industry Significance |
|---|---|
| EU Ecodesign Pre-Certification | Locks premium retail placement in Germany and France before competitors complete redesign cycles. |
| Phase-Change Material Integration | Displaces resistive heating in hospitality procurement evaluations with superior thermal consistency. |
| Direct-to-Chef Distribution Buildout | Captures high-volume institutional buyers through culinary supply channels bypassing housewares retail. |
| Battery Supply Agreement Diversification | Mitigates cobalt price volatility exposure through parallel Chinese and South Korean cell sourcing. |
| Smart Home Connectivity Development | Opens premium pricing tiers for Bluetooth-enabled temperature logging in tech-forward hospitality operators. |
Research Methodology
Coverage spans North America, Western Europe, and East Asia, with primary inputs from each region combined with secondary validation. Interviews with hospitality procurement managers, culinary supply cooperative directors, thermal engineering specialists, and premium kitchenware retail buyers anchored demand-side intelligence. Secondary sources included FDA food-contact substance filings, ECHA REACH pre-registration databases, METI subsidy program disclosures, and hospitality equipment distributor catalogs. Bottom-up unit economics and top-down market sizing were triangulated against trade flow data and component import records.
Rate-of-change decomposition separated volume growth from pricing dynamics across the projection horizon. Segmentation dimensions modeled include product architecture, material composition, feature integration, and customer type with regional regulatory cluster overlays. CAGRs were derived from fitted adoption curves calibrated to hospitality procurement cycle data and consumer willingness-to-pay surveys. Forecast inputs incorporated lithium-ion cell cost trajectories and evolving EU Ecodesign efficiency benchmark schedules.
Inputs from regulatory filing databases and distributor sales records were available through the study window; gaps in real-time hospitality procurement transaction data introduce uncertainty bands around institutional segment sizing. Forecasts reflect documented assumptions regarding METI subsidy continuity and REACH substance restriction implementation timelines. Deviation in battery raw material supply disruptions or accelerated right-to-repair legislation passage would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Warming Drawer Market
Kitchen Appliances
Europe Air Fryers Market
Kitchen Appliances
Egg Boiler/Cooker Market
Kitchen Appliances
Built-In Kitchen Appliances Market
Kitchen Appliances
Europe Kitchen Appliances Market
Kitchen Appliances
Canada Kitchen Appliances Market
Kitchen Appliances
Mexico Kitchen Appliances Products Market
Kitchen Appliances
Asia Pacific Household Electric Grills Market
Kitchen Appliances
Electric Lunch Box Market
Kitchen Appliances
Sweden Kitchen Appliances Market
Kitchen Appliances
Portable Outdoor Pizza Oven Market
Kitchen Appliances
Smart Connectivity Kitchen Appliances Market
Kitchen Appliances
South Korea Electric Hobs Market
Kitchen Appliances
South Korea Kitchen Appliances Market
Kitchen Appliances
Cotton Candy Maker Market
Kitchen Appliances
Toast Maker Market