
 Mexico Cookware Market | 2026-2036
Mexico Cookware Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Cookware Market Insights
The Mexico cookware market is rebalancing as premium stainless steel and copper collections pull away from commodity aluminum and basic nonstick offerings. Grupo Vasconia dominates domestic manufacturing through its vertically integrated foundry operations in Mexico. Tramontina leverages Brazilian scale to compete aggressively on cast iron and tri-ply lines. Meyer Corporation anchors the premium import tier through specialty retail partnerships.
Cookware encompasses vessels and containers fabricated from metals, ceramics, or composites, engineered to withstand thermal cycling between 150°C and 300°C while maintaining food contact safety under repeated use. Stainless steel segments lead volume, while copper and ceramic-coated lines capture expanding margin pools in professional kitchens. Residential cooking applications sustain the broadest base, though catering services and outdoor cooking represent the fastest-growing demand channels as Mexican hospitality formats diversify.
PROFECO enforces labeling and consumer protection standards, while NOM-251-SSA1-2009 governs food contact material hygiene, and Mexico's evolving alignment with FDA import protocols shapes cross-border product flows. Stakeholders must monitor regulatory convergence between Mexican standards and U.S. food safety frameworks to anticipate compliance costs and market access conditions.
Market Dynamics
PROFECO enforcement of labeling standards and NOM-251-SSA1-2009 food contact material rules are compressing informal import channels while redirecting procurement toward certified domestic and cross-border suppliers with verified compliance documentation.
Growth Catalysts
- Metropolitan kitchen modernization:Households in Mexico City, Guadalajara, and Monterrey are replacing basic aluminum vessels with stainless steel and ceramic-coated collections as disposable incomes rise and cooking media exposure expands.
- PROFECO transparency mandates:Mandatory origin labeling and thermal performance disclosure requirements are advantaging compliant manufacturers who can document foundry-to-retail traceability.
- Catering services expansion:Restaurant groups and institutional foodservice operators are building central commissaries that require standardized, high-durability cookware inventories.
Market Restraints
- Aluminum price volatility:Raw material input swings compress margin stability for commodity-grade producers dependent on primary metal sourcing.
- Import channel fragmentation:Unregulated cross-border flows through informal logistics corridors undercut certified product pricing and distort competitive benchmarking.
- Copper thermal conductivity limits:Professional kitchen demand for rapid heat response faces supply constraints from limited domestic smelting capacity and import dependency.
Strategic Opportunities
- Querétaro and Bajío manufacturing corridor:Industrial park development and automotive supplier spillover skills create foundry expansion potential outside saturated central Mexico.
- Induction compatibility retrofit:Ceramic induction base technology convergence with traditional vessel geometries opens replacement cycles in electrifying residential kitchens.
- Specialty retail partnerships:Department store kitchen concept boutiques and chef-branded shop-in-shop formats are displacing traditional mass-market distribution for premium collections.
Industry Challenges
- Food contact certification timelines:NOM-251-SSA1-2009 laboratory testing and PROFECO registration procedures create six-to-nine month product launch delays.
- Foundry workforce specialization:Precision casting for tri-ply and copper-core construction requires skills scarce in legacy aluminum cookware manufacturing regions.
- Legacy distributor integration:Traditional wholesale channels resist inventory transparency and point-of-sale data sharing required by modern trade partners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Cookware Market |
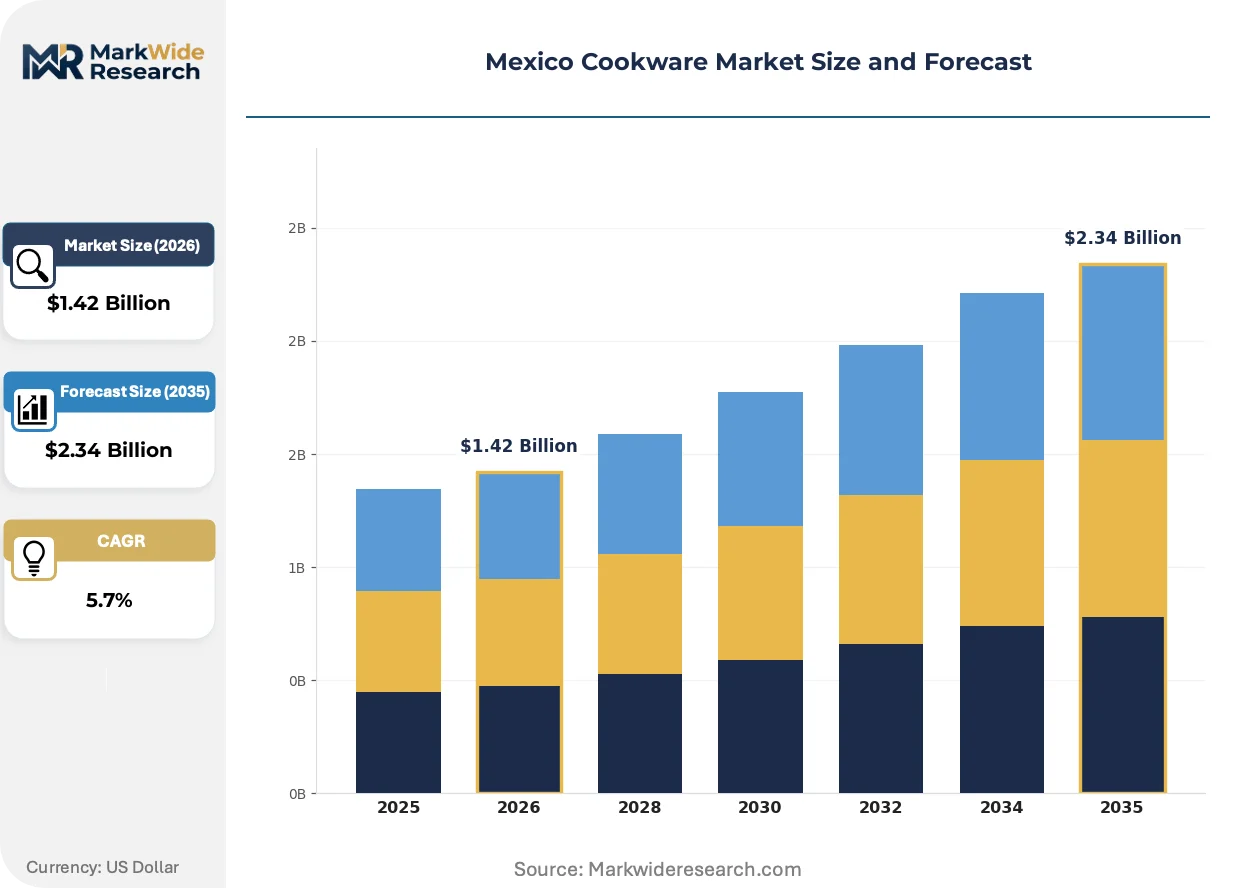
| Market Size in 2026 | $1.42 Billion |
| Market Size in 2035 | $2.34 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pots, Pans, Bakeware, Cookware Sets Material: Stainless Steel, Nonstick Coating, Cast Iron, Copper Application: Residential Cooking, Professional Kitchens, Outdoor Cooking, Catering Services Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Direct Sales |
| Companies Covered | Meyer Corporation, TTK Prestige, Grupo Vasconia (Vasconia Brands), SCANPAN, Fissler, Tramontina, Newell Brands, The Vollrath Company, Groupe SEB, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Cookware Market Trends and Innovations
Ceramic nonstick coating chemistry, induction base retrofitting, and compliance-driven supply chain documentation are converging to reshape product specifications and procurement criteria across Mexican residential and commercial kitchens.
Advanced ceramic-reinforced PTFE-free coatings are absorbing thermal shock requirements previously met by seasoned cast iron or heavy-gauge aluminum. Residential buyers in Mexico City and Monterrey are adopting these surfaces at accelerating replacement cycles. The technology is absorbing market share from traditional nonstick while compressing price premiums for entry-level stainless steel.
NOM-251-SSA1-2009 hygiene standard updates are mandating migration testing documentation for all food contact surfaces. Importers and domestic manufacturers must now submit laboratory certification for heavy metal leaching and thermal degradation resistance. Professional kitchen segments are responding fastest, with restaurant groups centralizing procurement through pre-approved vendor lists.
Direct-to-consumer digital channels are fragmenting traditional wholesale dominance in cookware distribution. Specialty retailers and brand-owned e-commerce platforms are capturing urban household purchases previously routed through department store intermediaries. This pattern concentrates in Mexico City metropolitan zone, where logistics infrastructure supports rapid fulfillment of bulky kitchen goods.
Mexico Cookware Market Segmentation
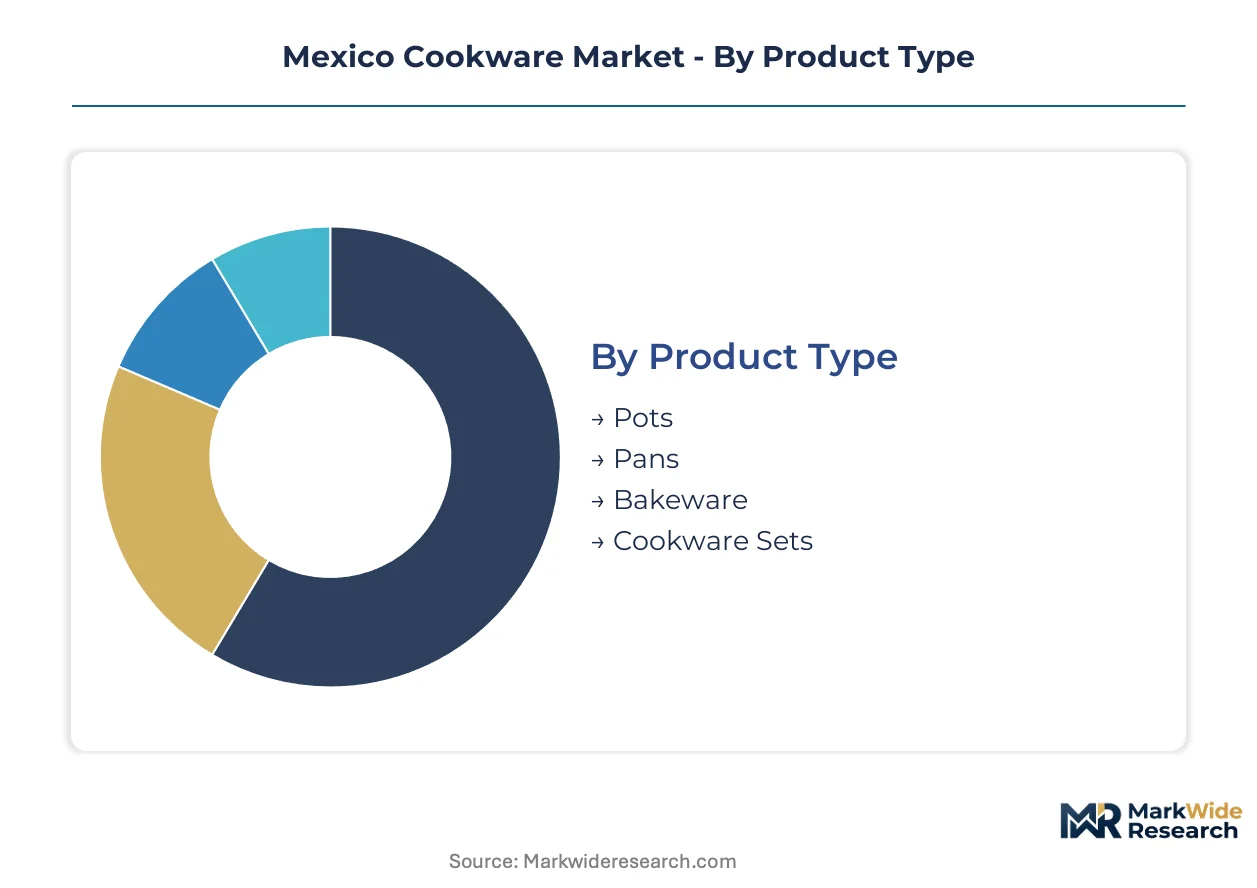
Cookware segmentation in Mexico tracks divergent supply chain configurations across material grades and distribution tiers. Manufacturers align production capabilities with distinct compliance burdens and thermal performance specifications demanded by each segment cluster.
Product Type:
Supply concentration tilts toward high-volume vessel categories where Mexican foundries achieve scale economies against Brazilian and Asian imports.
- Pots:Stockpots and saucepans fabricated from rolled stainless steel or spun aluminum dominate residential replenishment cycles. Demand concentrates in Mexico City metropolitan households upgrading from basic aluminum to tri-ply construction as cooking program visibility expands through digital media.
- Pans:Skillets and sauté vessels absorb the broadest manufacturing capacity across Grupo Vasconia's foundry network. Guadalajara residential buyers drive specification shifts toward ceramic-coated surfaces compatible with induction cooktops spreading through new apartment construction.
- Bakeware:Sheet pans, cake molds, and roasting trays in aluminized steel or ceramic-coated formats serve specialized baking segments. Commercial bakery commissaries in Monterrey corridor represent the primary volume anchor.
- Cookware Sets:Coordinated collections of five to twelve pieces bundle margin across matched vessel geometries. Department store promotional cycles and wedding registry channels sustain this segment's revenue concentration.
Today's leader: Pans. Tomorrow's challenger: Cookware Sets.
Material:
Cost tier stratification separates commodity aluminum producers from certified stainless steel fabricators bearing NOM-251-SSA1-2009 documentation burdens.
- Stainless Steel:Austenitic 304 and 430 grades with aluminum or copper disc bases deliver corrosion resistance for professional kitchen duty cycles. Restaurant group procurement centralization in Mexico City and Monterrey favors suppliers with verified heavy metal migration testing.
- Cast Iron:Pre-seasoned or enameled vessels from Brazilian and domestic foundries retain thermal mass for slow-cooking applications. Outdoor cooking expansion across northern Mexico states drives replacement demand.
- Nonstick Coating:PTFE-based and ceramic-reinforced surfaces reduce oil requirements for health-conscious residential segments. PROFECO labeling mandates on coating composition and temperature limits reshape import sourcing patterns.
- Copper:Solid or clad constructions with tin or stainless steel lining deliver superior thermal conductivity for precision cooking. Limited domestic smelting capacity constrains supply, concentrating procurement through specialized importers serving professional kitchens.
Stainless Steel captures current volume leadership. Copper presents the steepest expansion trajectory as professional kitchen specifications tighten.
Application:
Volume distribution favors residential channels while margin pools concentrate in commercial segments demanding durability certification and replacement part availability.
- Residential Cooking:Household meal preparation sustains the broadest base across all material tiers. Metropolitan kitchen modernization in Mexico City, Guadalajara, and Monterrey drives upgrade cycles from basic aluminum to premium collections.
- Professional Kitchens:Restaurant, hotel, and institutional foodservice operations require standardized inventories with thermal performance documentation. Central commissary construction by multi-unit restaurant groups concentrates procurement through approved vendor lists.
- Outdoor Cooking:Grilling, camping, and patio applications favor cast iron and heavy-gauge carbon steel constructions. Northern Mexico climate and recreational cooking culture support specialty retailer placement.
- Catering Services:Event and institutional foodservice operators build portable equipment inventories for off-premise execution. Volume procurement runs through foodservice distributors rather than retail channels.
Residential Cooking anchors current demand. Catering Services are gaining share fastest as Mexican hospitality formats diversify beyond traditional restaurant models.
Distribution Channel:
Customer type fragmentation separates price-sensitive mass-market buyers from specification-driven professional purchasers.
- Specialty Stores:Kitchen concept boutiques and chef-branded shop-in-shop formats deliver premium positioning with staff expertise. Palacio de Hierro and Liverpool department store networks dominate this channel in metropolitan corridors.
- Supermarkets:Mass-market retail chains move commodity-grade aluminum and basic nonstick through promotional pricing. Walmart México and Soriana capture volume from price-sensitive household replenishment.
- Online Retail:Brand-owned platforms and marketplace listings fragment traditional wholesale dominance. Mexico City logistics infrastructure supports rapid fulfillment of bulky kitchen goods with return complexity.
- Direct Sales:Catalog, television shopping, and manufacturer-direct channels serve rural and small-town markets outside specialty retail coverage. Demonstration-based selling justifies premium positioning for innovative coatings.
Specialty Stores defend margin leadership. Online Retail presents the most aggressive challenger to established channel structures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mexico outpaces Brazil in cookware regulatory stringency while lagging in domestic copper smelting capacity, creating divergent import dependency profiles across Latin America's two largest markets.
Mexico City Metro
Household kitchen modernization drives stainless steel and ceramic-coated vessel upgrades in Polanco and Condesa residential zones. PROFECO labeling mandates enforce origin disclosure and thermal performance documentation at point-of-sale. The Santa Fe industrial corridor hosts Grupo Vasconia's vertically integrated foundry operations serving domestic and export demand.
Nuevo León
Monterrey's restaurant group central commissaries standardize procurement through approved vendor lists demanding NOM-251-SSA1-2009 certification. The state's proximity to Texas border logistics accelerates FDA-aligned import protocols for premium collections. Apodaca manufacturing parks attract automotive supplier spillover skills into precision metal fabrication.
Jalisco
Guadalajara residential buyers shift toward induction-compatible ceramic surfaces as new apartment construction electrifies cooking infrastructure. Tlaquepaque and Tonalá artisan foundries retain traditional copper vessel craftsmanship for specialty hospitality segments. Lake Chapala retirement communities sustain demand for mid-tier cookware sets through registry and gift channels.
Bajío Region
Querétaro industrial park development creates foundry expansion potential outside saturated central Mexico supply chains. Automotive tier-one supplier capabilities in San Luis Potosí transfer into precision casting for tri-ply construction. León's leather and footwear manufacturing base diversifies into metalworking skills pools for cookware component fabrication.
Northern Border States
Cross-border retail arbitrage from Texas distorts pricing benchmarks in Tijuana and Ciudad Juárez mass-market channels. Chihuahua and Coahuila outdoor cooking culture sustains cast iron demand through specialty retailer placement. Matamoros logistics corridors channel informal import flows that PROFECO enforcement actions increasingly intercept.
Mexico Cookware Market Competitive Landscape
Top-tier vendors anchor premium stainless steel and copper-core collections, while mid-tier domestic fabricators compete on aluminum volume and basic nonstick replenishment cycles. The market structure tilts toward consolidation among foundry-integrated manufacturers with verified NOM-251-SSA1-2009 documentation capabilities. Three strategic archetypes dominate: vertically integrated domestic producers with captive raw material sourcing, Brazilian scale players leveraging Mercosur logistics advantages, and Asian import specialists navigating PROFECO compliance bottlenecks. Competitive moves concentrate on backward integration into precision casting capabilities and specialty retail partnership exclusivity.
Within the domestic integrated tier, Grupo Vasconia exemplifies foundry-to-retail vertical control over aluminum and stainless steel supply chains. Among import-positioned specialists, Meyer Corporation occupies the premium-tier vector through department store concept boutique placement. Tramontina represents Brazilian scale competition on cast iron and tri-ply lines, leveraging regional trade architecture for cost positioning against Asian alternatives.
| Leading Market Players |
|---|
| Meyer Corporation |
| TTK Prestige |
| Grupo Vasconia (Vasconia Brands) |
| SCANPAN |
| Fissler |
| Tramontina |
| Newell Brands |
| The Vollrath Company |
| Groupe SEB |
| Others |
Pricing and Supply Chain Analysis
Aluminum LME spot volatility cascades through Mexican cookware supply chains, compressing margin pools for commodity-grade producers while amplifying pricing power for foundry-integrated manufacturers with captive raw material sourcing. Grupo Vasconia's vertical control over aluminum and stainless steel inputs insulates its pricing tiers from import-dependent competitors exposed to currency and tariff fluctuations.
Pricing Analysis
Capacity additions in Querétaro and Bajío manufacturing corridors are reshaping price floors for mid-tier stainless steel collections. Three-tier pricing structure across premium, standard, and economy levels separates NOM-251-SSA1-2009 certified professional-grade vessels from basic aluminum commodity replenishment. Cost compression in economy tiers is intensifying because informal import channels undercut certified product positioning. Mass-market supermarket buyers exhibit highest price sensitivity, while restaurant group procurement through approved vendor lists prioritizes thermal performance documentation over unit cost.
Supply Chain Analysis
NOM-251-SSA1-2009 laboratory certification requirements are gating supplier qualification timelines and compressing eligible vendor pools. Primary fabrication concentrates in Mexico, Brazil, and China, with Mexican foundries leveraging proximity advantages for PROFECO-compliant rapid replenishment. Raw material sourcing draws from Chilean copper cathode, Brazilian iron ore, and domestic aluminum scrap recovery streams. Single-source vulnerability in copper smelting capacity creates procurement bottlenecks for professional kitchen segments demanding clad-core construction. Distribution runs through specialty retail boutiques in metropolitan corridors and foodservice distributors for commercial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mexico's cookware market operates as a regulatory compounder where PROFECO enforcement actions and NOM-251-SSA1-2009 compliance documentation are accelerating vendor consolidation and advantaging certified domestic manufacturers.
For Market Incumbents: Anticipate margin compression from Brazilian scale players by deepening backward integration into precision casting capabilities for tri-ply and copper-core construction. Lock in specialty retail partnership exclusivity with Palacio de Hierro and Liverpool department store networks before channel fragmentation accelerates. Certification investment in foundry-to-retail traceability systems represents the critical defensive lever against informal import displacement. For New Entrants and Emerging Players: Central commissary procurement officers at multi-unit restaurant groups represent an underserved buyer archetype bypassed by traditional retail-focused entrants. Specialty hospitality segments in Tlaquepaque and Tonalá artisan corridors offer white-space positioning for copper craftsmanship differentiation. Direct-to-commercial distribution bypassing wholesale intermediaries captures procurement centralization momentum in Monterrey and Mexico City foodservice clusters. For Investors and Strategic Acquirers: Asymmetric upside sits with foundry-integrated mid-cap specialists possessing verified NOM-251-SSA1-2009 documentation capabilities and automotive supplier spillover precision metalworking skills. Long-term viability hinges on regulatory convergence between Mexican standards and FDA import protocols tightening cross-border product flows. Watch for PROFECO enforcement action intensity in Matamoros and Tijuana logistics corridors as the inflection signal for informal channel compression velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precision Casting | Captures margin pools in tri-ply construction for professional kitchen segments. |
| NOM-251-SSA1-2009 Certification Investment | Unlocks restaurant group procurement through approved vendor list eligibility. |
| Specialty Retail Partnership Exclusivity | Secures premium positioning in Palacio de Hierro and Liverpool concept boutiques. |
| Induction Base Retrofit Technology Launch | Addresses electrification trends in Guadalajara and Mexico City residential construction. |
| Querétaro Manufacturing Corridor Expansion | Leverages automotive supplier spillover skills outside saturated central Mexico supply chains. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary fieldwork with foundry operations managers, procurement leads at restaurant groups, category buyers at Liverpool and Palacio de Hierro, and regulatory affairs specialists at PROFECO with secondary validation. Secondary sources included Mexican customs trade records, SEC 10-K filings of listed cookware manufacturers, PROFECO enforcement action databases, and NOM-251-SSA1-2009 laboratory certification registries. Bottom-up vessel volume estimates and top-down market value assessments were cross-referenced for convergence.
Comparable historical periods anchored the projection framework against pre-pandemic baseline demand patterns and post-regulatory enforcement structural shifts across the analysis window. Segmentation modeling tracked material grade tiers, application channels spanning residential through professional kitchen, and distribution format evolution from wholesale through direct-to-consumer. CAGRs were derived from regression analysis against macroeconomic indicators and foundry capacity utilization rates, with aluminum LME price trajectories and PROFECO enforcement intensity scored as scenario-weighted inputs.
Underlying measurement precision varies by segment; stainless steel and copper-certified professional-grade categories carry tighter precision than informal aluminum commodity flows. Forecasts reflect documented assumptions on regulatory enforcement continuity and raw material price regime stability. Deviation in PROFECO inspection intensity or NOM-251-SSA1-2009 laboratory testing backlog duration would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Household Items
Soap Tablet Market
Household Items
Plastic Bathtub Market
Household Items
Smart Connected Water Purifier Market
Household Items
Car Air Freshener Market
Household Items
Portable Air Humidifier and Dehumidifier Market
Household Items
Underwear Disinfection Dryers Market
Household Items
Hydralight Lanterns Market
Household Items
North America Glassware Market
Household Items
Stainless Steel Water Bottles Market
Household Items
Stainless Steel Toilet Paper Dispenser Market
Household Items
Shower Heads and Systems Market
Household Items
MENA POU Water Purifiers Market
Household Items
Remote Control Holder Market
Household Items
Global Disposable Toilet Seat Covers Market
Household Items
Russia Residential Water Heaters Market
Household Items
Smart Drying Racks Market