
 Global Single Serve Coffee Maker Market | 2026-2036
Global Single Serve Coffee Maker Market Size, Share, and Industry Trends Forecast 2026-2036
Global Single Serve Coffee Maker Market Outlook
Multi-source component procurement is restructuring supply economics for single serve coffee maker manufacturers. Keurig Dr Pepper leverages captive pod ecosystems to lock in recurring revenue streams. Nestlé Nespresso SA anchors its position through direct-to-consumer subscription models and proprietary capsule architecture. De'Longhi competes by extending its manufacturing scale across European and Asian assembly plants.
A single serve coffee maker is an appliance engineered to brew one individualized portion of coffee using sealed pods, capsules, or loose grounds through pressurized extraction or gravity-fed dripping, typically operating at temperatures between 195°F and 205°F and pressures up to 19 bar for espresso variants. Pod machines dominate unit shipments due to lower entry price points and broader retail availability, while capsule systems concentrate margin pools through proprietary format lock-in. Espresso technology commands premium positioning in commercial settings where extraction consistency determines repeat purchase behavior.
The US FDA governs food-contact materials in brew chambers and water reservoirs, while the EU Ecodesign Directive mandates standby power limits and recyclability disclosures for appliances sold in member states. Japan's METI enforces electrical safety standards that shape product certification timelines for Asian market entry. Stakeholders must monitor how extended producer responsibility frameworks in France and Germany redefine cost allocation for end-of-life capsule collection infrastructure.
Market Dynamics
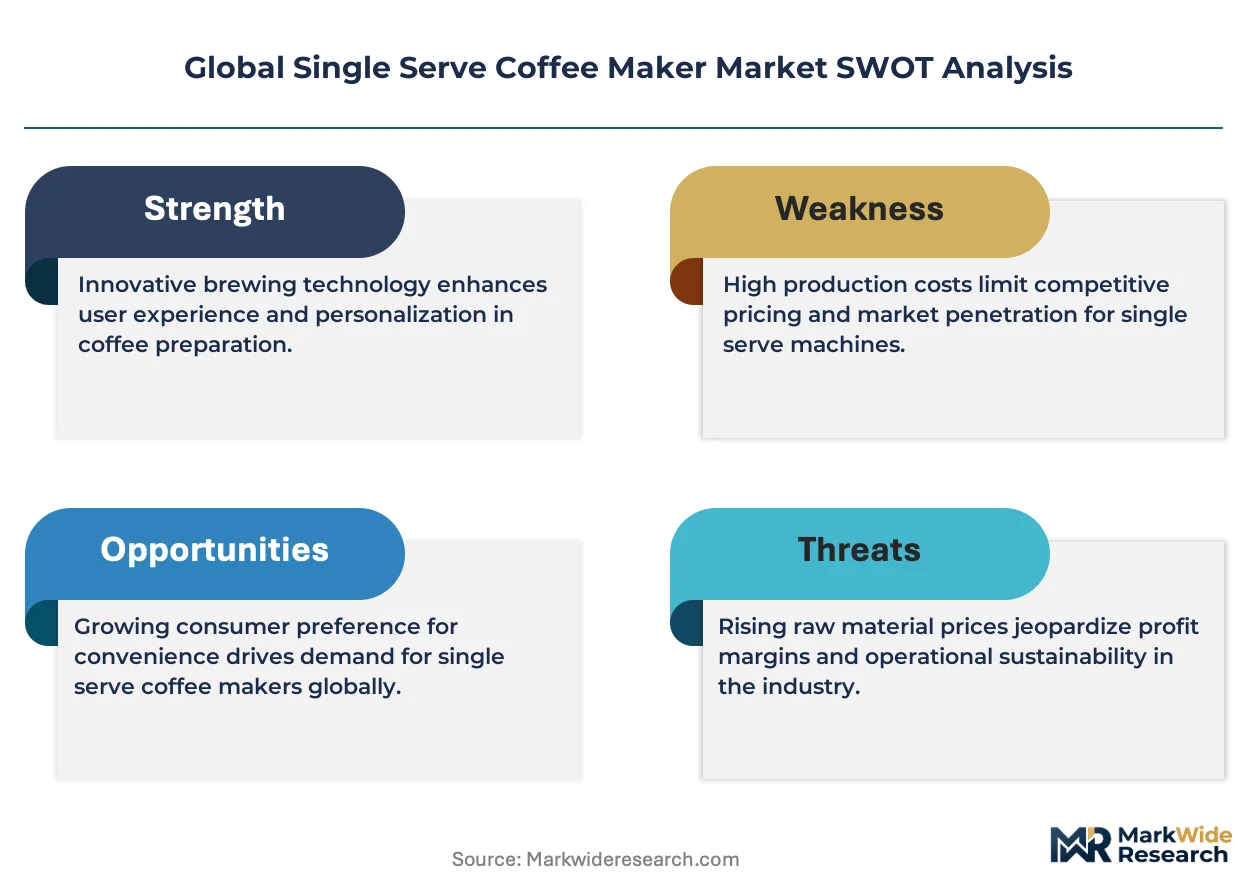
Proprietary pod ecosystems and captive consumables are restructuring profit pools away from hardware margins toward recurring revenue streams. The Ecodesign Directive's standby power mandates are forcing redesign cycles that favor manufacturers with integrated European assembly footprints.
Growth Catalysts
- Quick-service restaurant penetration:Chains in the United States deploy single-serve systems for portion consistency and labor reduction during peak morning hours.
- Extended producer responsibility frameworks:France and Germany mandate producer-funded capsule collection infrastructure, creating competitive moats for compliant manufacturers.
- Pressurized extraction advancement:19-bar espresso variants capture commercial settings where extraction consistency drives repeat purchase behavior.
Market Restraints
- Aluminum capsule input volatility:Primary aluminum price swings compress margin stability for premium capsule producers dependent on barrier-layer metallization.
- East Asian PCB concentration:Control board fabrication clusters in Taiwan and South Korea expose supply timelines to regional logistics disruptions.
- Biodegradable material performance gap:PLA and paper-based alternatives fail to match oxygen barrier properties of conventional multi-layer capsules, limiting shelf-life extension.
Strategic Opportunities
- Indian hospitality expansion:Mid-tier hotel chains in Mumbai and Bangalore represent unsaturated demand for consistent in-room beverage systems.
- Direct-to-consumer subscription models:Proprietary capsule architectures enable recurring revenue capture bypassing traditional retail markup structures.
- IoT-enabled predictive maintenance:Connected brewers in corporate breakrooms reduce service dispatch frequency through automated fault detection.
Industry Challenges
- Food-contact material certification timelines:FDA 21 CFR compliance for new brew chamber polymers extends product launch windows by 8-14 months.
- Legacy system integration friction:Commercial clients with existing water line infrastructure face retrofit complexity when upgrading to plumbed-capable units.
- Specialized field service technician scarcity:High-pressure pump and thermoblock repair expertise concentrates with authorized service networks, limiting third-party maintenance competition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Single Serve Coffee Maker Market |
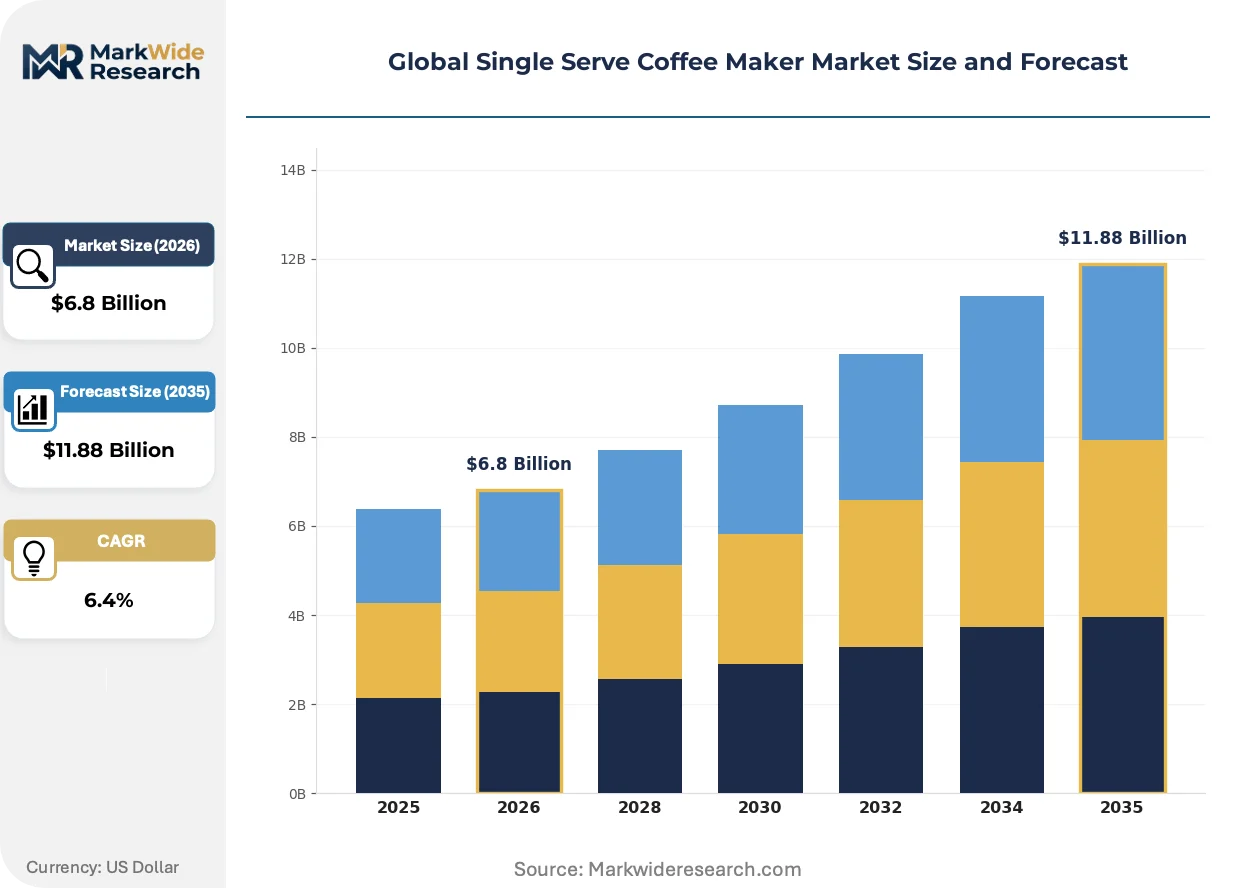
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $11.88 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Cup Machine, Pod Machine, Capsule Machine, Ground Coffee Machine Technology: Brewing Technology, Espresso Technology, Drip Technology, Cold Brew Technology End User: Residential, Commercial, Office, Hospitality Distribution Channel: Online Retail, Specialty Stores, Supermarkets, Others |
| Companies Covered | Keurig Dr Pepper, Nestlé Nespresso SA, De'Longhi, JURA Elektroapparate AG, Hamilton Beach Brands, BUNN, Sunbeam Products, LUIGI LAVAZZA SPA, Krups, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Single Serve Coffee Maker Market Strategic Shifts
Component miniaturization and connected diagnostics are compressing form factors while expanding remote monitoring capabilities across installed bases. These shifts favor manufacturers with software-hardware integration competency over pure appliance assemblers.
Precision temperature profiling is rewriting extraction control architectures. Boutique coffee chains in Melbourne and Copenhagen adopt PID-enabled brewers that adjust thermal curves by origin roast profile. This capability is compressing the performance gap between automated systems and manual pour-over methods in premium positioning.
EU Ecodesign Directive standby power limits are forcing firmware redesigns that trade rapid-start convenience against phantom load reduction. Manufacturers serving German and French distribution channels must recertify existing platforms to sub-0.5-watt idle consumption thresholds. The compliance burden falls heaviest on value-tier producers lacking dedicated European engineering centers.
Corporate procurement departments are consolidating vendor relationships through master service agreements that bundle equipment, consumables, and technical support. Facility management providers in the United States negotiate multi-location contracts that displace single-site purchasing autonomy. This concentration shifts bargaining power toward buyers with scale and compresses margins for regional distributors.
Global Single Serve Coffee Maker Market Segmentation
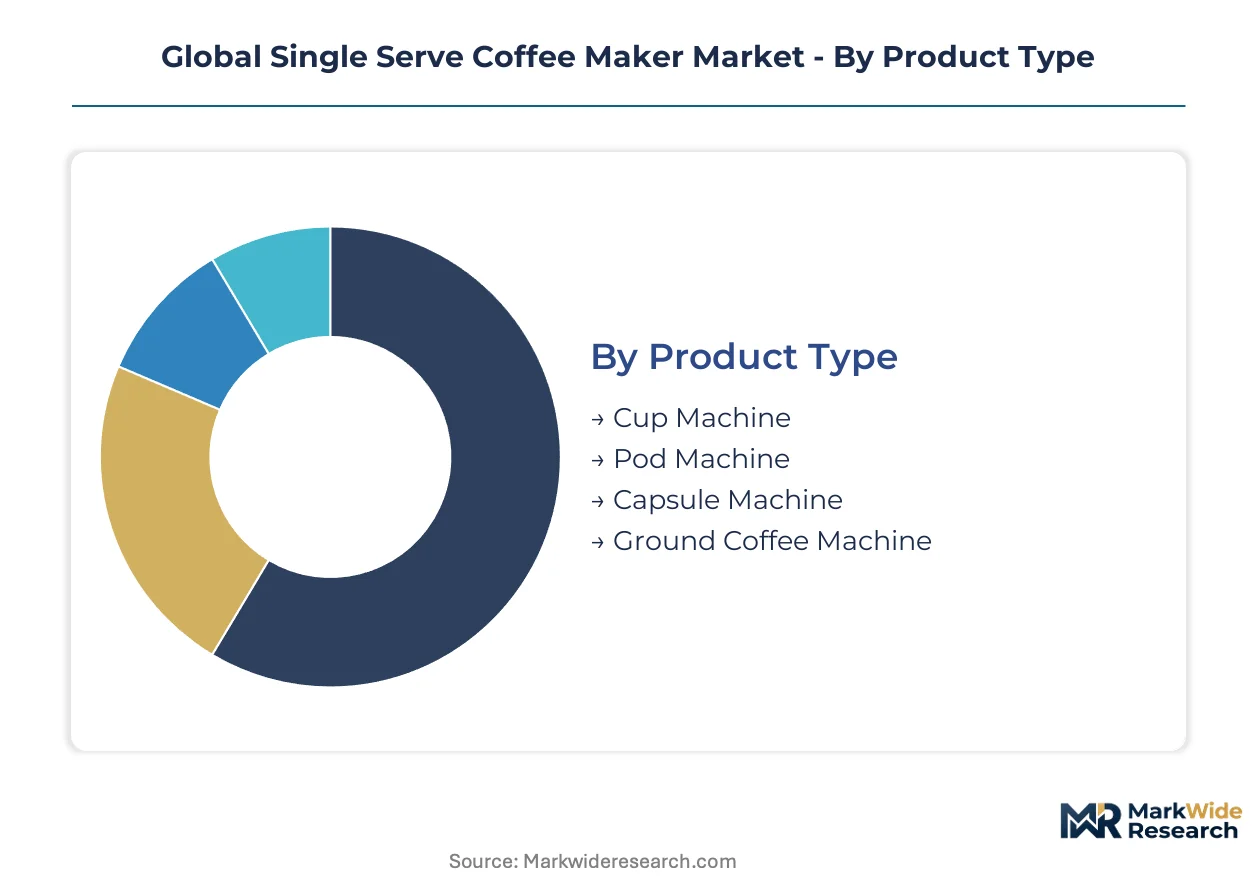
Segmentation in the single serve coffee maker market reveals how proprietary formats, extraction methods, and procurement channels partition profit pools. Manufacturers configure product portfolios around format lock-in potential and recurring consumable attachment rates.
Product Type:
Standardization dominates at the entry level while proprietary ecosystems capture premium positioning across this category.
- Pod Machine:Lower price points and broad retail availability drive mass-market penetration. Quick-service restaurants in the United States deploy these systems for morning rush efficiency and portion consistency. Expansion is steepest in commercial foodservice where labor reduction justifies equipment investment.
- Capsule Machine:Proprietary format architecture enables recurring revenue capture through captive consumables. European hospitality chains favor these systems for extraction reliability and brand differentiation in guest rooms. Most installed capacity flows through this segment.
- Cup Machine:Paper-based filtration appeals to sustainability-focused procurement departments in corporate campuses.
- Ground Coffee Machine:Flexibility in bean sourcing attracts specialty coffee enthusiasts and independent cafes.
Pod and capsule formats together concentrate manufacturing investment due to consumable attachment economics.
Technology:
Pressure requirements and thermal control precision stratify production costs and service complexity across extraction methods.
- Espresso Technology:19-bar pump systems deliver extraction consistency that commands premium positioning in boutique coffee chains. Melbourne and Copenhagen operators adopt PID-enabled thermal profiling to narrow the performance gap against manual methods.
- Brewing Technology:Pressurized extraction at moderate pressures balances speed and quality for office breakroom deployments.
- Drip Technology:Gravity-fed systems dominate residential entry points where simplicity overrides extraction nuance.
- Cold Brew Technology:Extended steeping cycles address growing demand for low-acidity beverages in wellness-oriented hospitality concepts.
Commercial settings favor espresso and brewing technologies for throughput reliability, while residential demand clusters at drip price points.
End User:
Volume scale and service intensity diverge sharply between private consumption and institutional procurement.
- Hospitality:Mid-tier hotel chains in Mumbai and Bangalore represent unsaturated demand for in-room beverage consistency. Property management companies negotiate master service agreements bundling equipment, consumables, and technical support.
- Commercial:Quick-service restaurant chains prioritize rapid-start capabilities and minimal training requirements for hourly staff.
- Office:Corporate procurement departments consolidate vendor relationships through multi-location contracts that displace single-site purchasing autonomy.
- Residential:Countertop footprint constraints and aesthetic integration drive form factor innovation.
Hospitality and commercial segments together anchor equipment margins through service contract attachment, while residential volume sustains consumable replenishment economics.
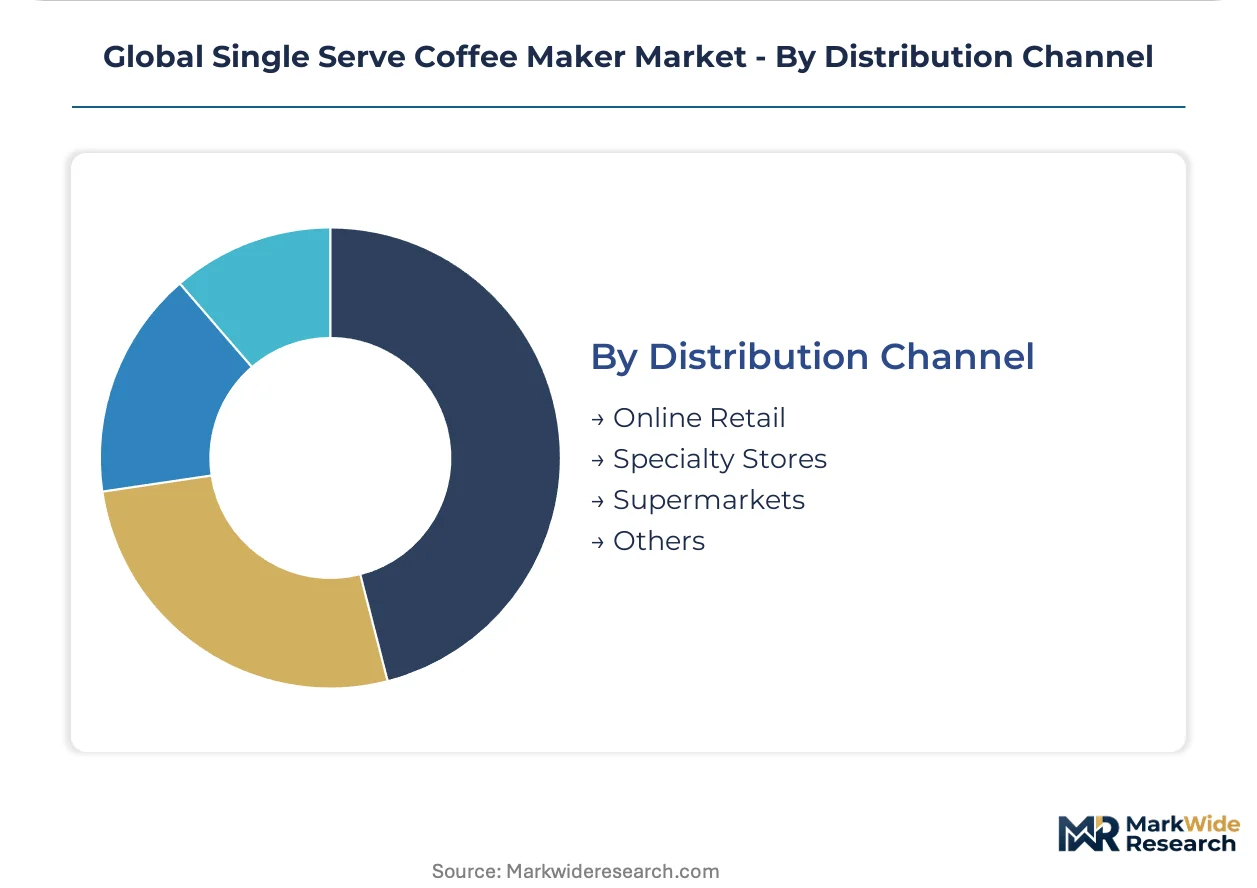
Distribution Channel:
Channel selection determines margin retention and customer relationship depth for manufacturers and intermediaries alike.
- Online Retail:Direct-to-consumer subscription models bypass traditional retail markup structures and capture recurring revenue through proprietary capsule architectures.
- Specialty Stores:Hands-on demonstration and staff expertise support premium positioning for espresso technology variants.
- Supermarkets:Mass-market pod and capsule replenishment concentrates purchase frequency in grocery basket economics.
- Others:Foodservice distributors and facility management providers serve institutional procurement with bundled equipment and consumable contracts.
Online and specialty channels together expand fastest as manufacturers seek direct customer relationships, though supermarkets retain volume dominance in consumable replenishment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States quick-service restaurants deploy single-serve systems for morning rush efficiency and portion consistency. The hospitality sector in Germany and France faces Ecodesign Directive compliance deadlines for standby power reduction. Industrial clusters in Milan, Shenzhen, and Bangalore concentrate manufacturing and procurement negotiations.
United States
Quick-service restaurant chains prioritize rapid-start capabilities and minimal training requirements for hourly staff. The FDA governs food-contact materials in brew chambers and water reservoirs through 21 CFR compliance frameworks. Corporate procurement departments in Chicago and Dallas consolidate vendor relationships through multi-location master service agreements.
Germany
Mid-tier hotel chains negotiate bundled equipment and consumable contracts for in-room beverage consistency. Extended producer responsibility frameworks mandate producer-funded capsule collection infrastructure through national implementation. Engineering centers in Munich and Stuttgart drive firmware redesigns for sub-0.5-watt idle consumption thresholds.
France
Boutique coffee chains in Paris adopt PID-enabled thermal profiling to narrow performance gaps against manual pour-over methods. ANSM and environmental regulators enforce recyclability disclosures and end-of-life collection cost allocation. Manufacturing facilities near Lyon optimize assembly footprints for EU Ecodesign Directive recertification cycles.
Japan
Corporate breakrooms demand connected brewers with automated fault detection for reduced service dispatch frequency. METI electrical safety standards shape product certification timelines for domestic market entry. Precision temperature profiling adoption concentrates in Tokyo and Osaka specialty coffee segments.
India
Mid-tier hotel chains in Mumbai and Bangalore represent unsaturated demand for consistent in-room beverage systems. BIS standards and state-level procurement policies influence equipment specification for hospitality projects. Facility management providers in Hyderabad and Chennai expand technical service networks for commercial installations.
Global Single Serve Coffee Maker Market Competitive Environment
Global majors compete with regional champions across proprietary format ecosystems and captive consumable economics. The vendor base stratifies into consolidated platform owners, diversified appliance manufacturers, and specialized commercial equipment fabricators. Three archetypes dominate: ecosystem-locked players monetizing recurring pod revenue, scale-driven assemblers competing on manufacturing efficiency, and premium specialists commanding positioning through extraction technology. Competitive moves concentrate on backward integration into capsule metallization and geographic expansion through master service agreements with multi-location facility managers.
Among ecosystem-locked platform owners, Keurig Dr Pepper and Nestlé Nespresso SA exemplify the recurring revenue archetype through proprietary pod architectures. De'Longhi occupies a position representing diversified appliance manufacturers extending assembly scale across European and Asian plants. These three anchors illustrate how format lock-in potential and consumable attachment rates partition strategic positioning.
| Leading Market Players |
|---|
| Keurig Dr Pepper |
| Nestlé Nespresso SA |
| De'Longhi |
| JURA Elektroapparate AG |
| Hamilton Beach Brands |
| BUNN |
| Sunbeam Products |
| LUIGI LAVAZZA SPA |
| Krups |
| Others |
Value Chain & Pricing Dynamics
Quick-service restaurant procurement consolidation in the United States anchors the dominant contract-based pricing model, with multi-location master service agreements compressing spot-market premiums for equipment and bundled consumables.
Pricing Analysis
Aluminum input cost pass-through volatility compresses margin stability for premium capsule producers tethered to barrier-layer metallization supply. Three-tier pricing structure across premium espresso systems, standard pod machines, and economy drip variants segments buyers by extraction technology and service bundling. Cost compression in the value tier intensifies because Ecodesign Directive recertification burdens fall heaviest on producers lacking dedicated European engineering centers. Corporate procurement departments exhibit lowest price sensitivity due to total-cost-of-ownership framing, while independent cafes face acute pressure from consumable attachment rates.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan and South Korea for control board PCB fabrication, exposing assembly timelines to regional logistics disruptions. Manufacturing draws from Chinese aluminum rolling mills for capsule metallization, Italian pump component specialists for 19-bar espresso systems, and Malaysian plastic injection molding for housing assemblies. Commodity price volatility in primary aluminum feeds margin instability for proprietary format producers. Distribution runs through foodservice distributors and facility management providers serving institutional procurement with bundled equipment and consumable contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with the EU Ecodesign Directive's sub-0.5-watt standby mandates forcing redesign cycles that favor compliant incumbents with integrated European assembly footprints.
For Market Incumbents: Acquire captive capsule metallization capacity to defend against aluminum input volatility and secure barrier-layer supply continuity. Consolidate technical service networks in Germany and France to capture extended producer responsibility framework compliance rents, while proprietary format lock-in protects against private-label pod erosion.
For New Entrants and Emerging Players: Capture mid-tier hotel chain procurement in Mumbai and Bangalore through master service agreements bundling equipment, consumables, and preventive maintenance. White-space concentration in Indian hospitality in-room systems offers penetrable demand, with direct-to-consumer subscription models providing a go-to-market angle bypassing retail markup structures.
For Investors and Strategic Acquirers: Diversified appliance manufacturers with multi-continental assembly footprints are the most active acquirer in this space, seeking software-hardware integration competency. Long-term viability hinges on recurring consumable economics rather than hardware shipment volume. Signal to monitor: firmware-enabled predictive maintenance adoption rates in corporate breakroom installed bases as an inflection indicator for service contract attachment potential.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Capsule Metallization | Captive aluminum barrier-layer supply secures margin stability against LME price swings. |
| Direct-to-Consumer Subscription Launch | Proprietary format lock-in bypasses supermarket retail markup and captures recurring revenue. |
| IoT-Enabled Predictive Maintenance Rollout | Connected diagnostics in corporate breakrooms reduce service dispatch frequency and deepen account stickiness. |
| Ecodesign Directive Compliance Recertification | Sub-0.5-watt idle consumption firmware redesigns open German and French distribution channels. |
| Master Service Agreement Expansion | Multi-location contracts with US facility management providers consolidate vendor relationships and displace regional distributors. |
Study Parameters
Bottom-up hospitality and commercial procurement modeling reconciled against top-down manufacturing capacity tracking forms the analytical core of this study. Primary interviews with equipment procurement managers at mid-tier hotel chains, category buyers at quick-service restaurant headquarters, facility management provider executives, and aftermarket service network operators combined with secondary validation from SEC 10-K filings, EU Ecodesign Directive implementation reports, FDA 21 CFR food-contact material registrations, and customs trade data for aluminum and electronic component flows.
Historical trendline analysis of installed base growth, consumable replenishment velocity, and equipment replacement cycles informed projection parameters across the modeling period. Segmentation dimensions modeled include product format architecture, extraction technology pressure tier, end-use procurement channel, and regional regulatory compliance cluster. CAGRs were derived from slope analysis of volume and value trajectories, with forecast inputs incorporating Ecodesign Directive recertification timelines and extended producer responsibility framework implementation schedules.
Aluminum price volatility, logistics disruption in East Asian PCB fabrication clusters, and biodegradable material performance gaps are the dominant revision risks that could alter trajectory assumptions. Forecasts reflect documented analytical frameworks and data sources. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Kitchen Appliances
Digital BBQ Tongs and Thermometer Market
Kitchen Appliances
Electric Lunch Box Market
Kitchen Appliances
Asia Pacific Electric Vegetable Choppers Market
Kitchen Appliances
Brazil Kitchen Appliances Market
Kitchen Appliances
North America Electric Vegetable Choppers Market
Kitchen Appliances
Global Portable Blenders Market
Kitchen Appliances
US Smart Oven Market
Kitchen Appliances
Cake Pans Market
Kitchen Appliances
Poland Household Electric Grills Market
Kitchen Appliances
US Induction Cookware Market
Kitchen Appliances
Kitchen Appliances Market
Kitchen Appliances
Europe Kitchen Appliances Market
Kitchen Appliances
Canada Kitchen Appliances Market
Kitchen Appliances
Commercial Induction Cooktops Market
Kitchen Appliances
Electric Countertop Griddles Market
Kitchen Appliances
Hand-Held Mixer Market