
 Smart City Kiosk Deployment Market | 2026-2036
Smart City Kiosk Deployment Market Size, Share, and Industry Trends Forecast 2026-2036
Smart City Kiosk Deployment Market Analytics
The smart city kiosk market is rebalancing between premium interactive systems with edge computing and commodity static displays with basic connectivity. CIVIQ Smartscapes leverages vertical integration across hardware and cloud software to command higher-margin municipal contracts. Soofa, Inc. anchors its position in solar-powered outdoor units for transit agencies, while NEC Corporation dominates large-format LED-integrated installations in Asian metropolitan pilots.
Smart city kiosk deployment encompasses networked, self-service terminals installed in public rights-of-way, typically featuring touchscreen interfaces, environmental housings rated to IP54 or higher, and real-time backhaul via cellular or fiber connectivity for delivering information, transactions, or civic services. Information dispensing applications lead current installed base volumes due to transit agency modernization cycles, while IoT connectivity and NFC-enabled payment integration represent the fastest-expanding technology segments as cities consolidate fragmented vendor ecosystems. Software development and content management services capture disproportionate margin pools relative to installation, reflecting recurring revenue stickiness and municipal demand for remote fleet management dashboards.
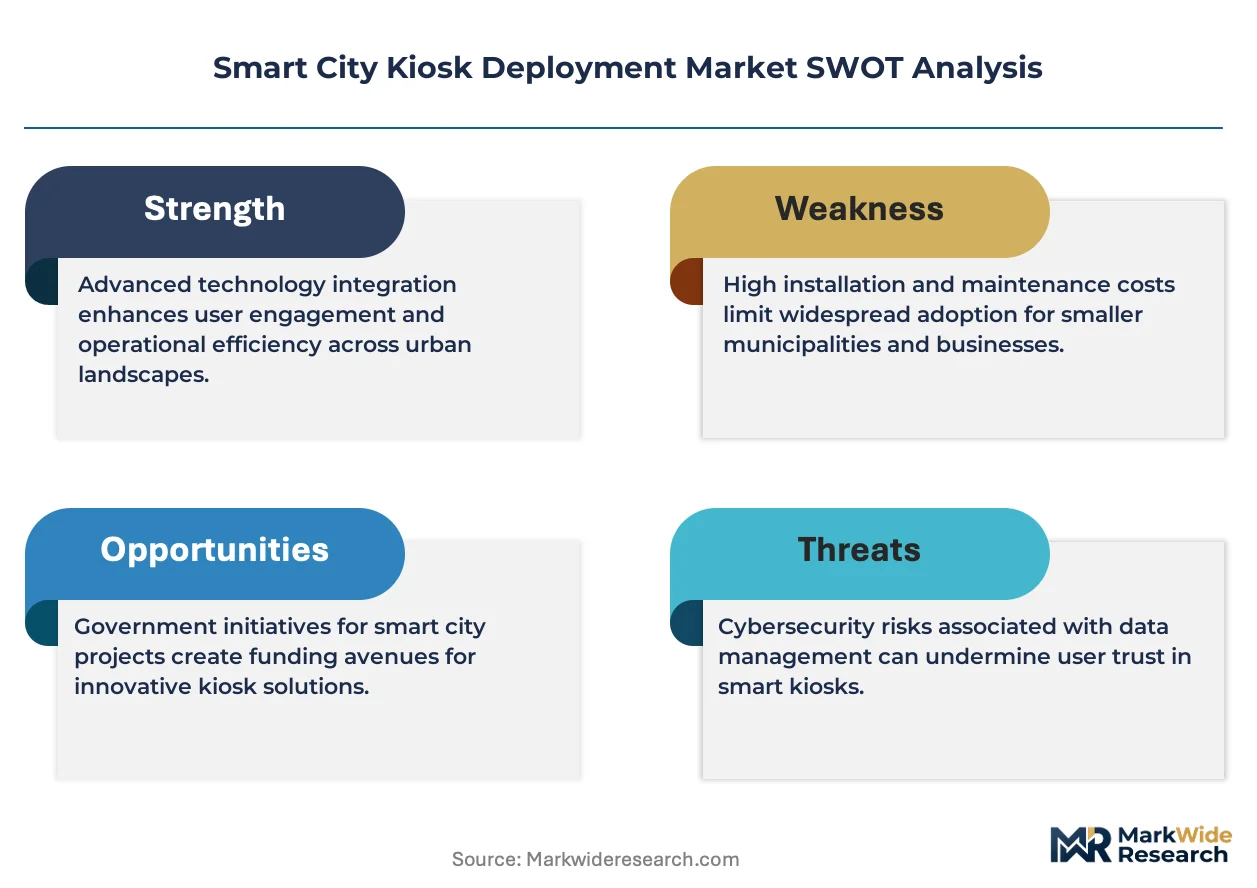
FCC Part 15 emissions standards govern radio-frequency modules in US deployments, while the EU AI Act and GDPR impose algorithmic transparency and biometric data restrictions on facial recognition-enabled kiosks across European member states. Japan's METI promotes JIS-compliant interoperability frameworks that reduce vendor lock-in for municipal procurement. Stakeholders must weigh compliance investment against functional differentiation as regulatory fragmentation intensifies across deployment geographies.
Market Dynamics
Transportation authorities in Germany, the United Kingdom, and Canada are consolidating fragmented kiosk vendor ecosystems into unified fleet management platforms, compressing procurement cycles and elevating software recurring revenue above hardware margins.
Growth Catalysts
- EU AI Act compliance mandates:Algorithmic transparency requirements for facial recognition-enabled terminals are accelerating replacement cycles across European municipal networks.
- NFC payment integration:Contactless transaction capabilities in transit hubs are expanding average revenue per kiosk through fare collection commissions.
- Edge computing architectures:Real-time processing at the terminal level reduces backhaul latency for emergency alert systems and dynamic wayfinding.
Market Restraints
- Semiconductor supply concentration:Touch controller and cellular modem sourcing remains concentrated among Taiwanese and South Korean foundries, exposing deployment timelines to foundry allocation volatility.
- GDPR biometric restrictions:Facial recognition data collection limitations impose architectural constraints on audience analytics modules, forcing hardware redesigns.
- LCD panel input cost exposure:Large-format display glass pricing fluctuates with Chinese glass substrate capacity, pressuring margin structures on premium LED-integrated installations.
Strategic Opportunities
- India smart city mission:Municipal corporations in Pune, Surat, and Ahmedabad are issuing tenders for interoperable transit-information terminals with localized language support.
- Solar-powered outdoor units:Photovoltaic-integrated housings with battery backup enable off-grid deployment in parks and waterfront corridors without trenching for power.
- 5G private network convergence:Integration with campus-wide private cellular networks allows kiosks to serve as fixed wireless access points for surrounding IoT sensor grids.
Industry Challenges
- Cybersecurity certification timelines:Common Criteria EAL4+ evaluation for payment-enabled terminals extends product launch schedules by 8-14 months.
- Legacy transit system integration:API compatibility with decades-old central dispatch software requires custom middleware development for each municipal authority.
- Field technician skill scarcity:Combined competencies in IP networking, electrical safety, and physical security hardware installation concentrate among specialized contractor pools.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart City Kiosk Deployment Market |
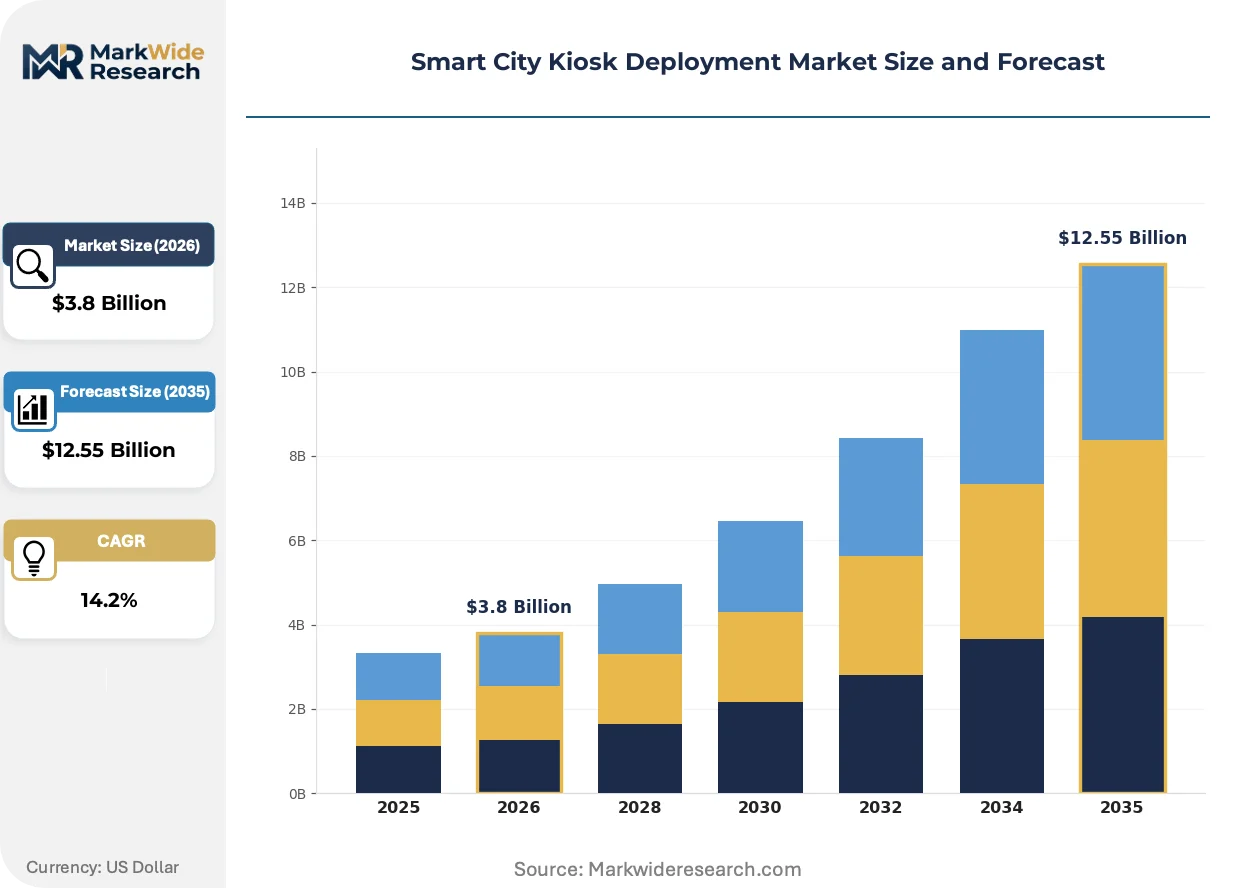
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Information Dispensing, Ticketing, Advertising, Public Services Service Type: Installation, Maintenance, Software Development, Content Management End User: Government, Transportation Authorities, Retailers, Educational Institutions Technology: Touchscreen, IoT Connectivity, NFC, Solar Power |
| Companies Covered | CIVIQ Smartscapes LLC, Smart City Media, Soofa, Inc., Verizon Communications Inc., OLEA Kiosks Inc., Intel Corporation, NEC Corporation, Panasonic, Diebold Nixdorf, Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart City Kiosk Deployment Market Evolving Landscape
Edge-native processing architectures and modular hardware platforms are displacing monolithic kiosk designs, enabling municipal operators to upgrade compute and connectivity without full terminal replacement.
Computer vision modules with on-device inference are rewriting how transit agencies deploy passenger flow analytics. Transport for London and Metrolinx in Toronto are piloting these systems for real-time platform crowding alerts. The technology is compressing the data architecture from cloud-dependent pipelines to localized decision loops that function during network outages.
The EU AI Act's risk classification framework for biometric identification systems is forcing architectural pivots in European deployments. Terminal manufacturers must now document algorithmic training data provenance and maintain human-in-the-loop override capabilities. German municipal procurement offices are embedding these compliance requirements into technical specifications ahead of formal enforcement deadlines.
Subscription-based fleet management platforms are displacing perpetual-license software models in North American transit authority RFPs. Chicago Transit Authority and Vancouver's TransLink have shifted to per-terminal monthly fees covering remote monitoring, content updates, and cybersecurity patching. This restructures vendor cash flows toward predictable recurring revenue and extends contract durations.
Smart City Kiosk Deployment Market Segmentation
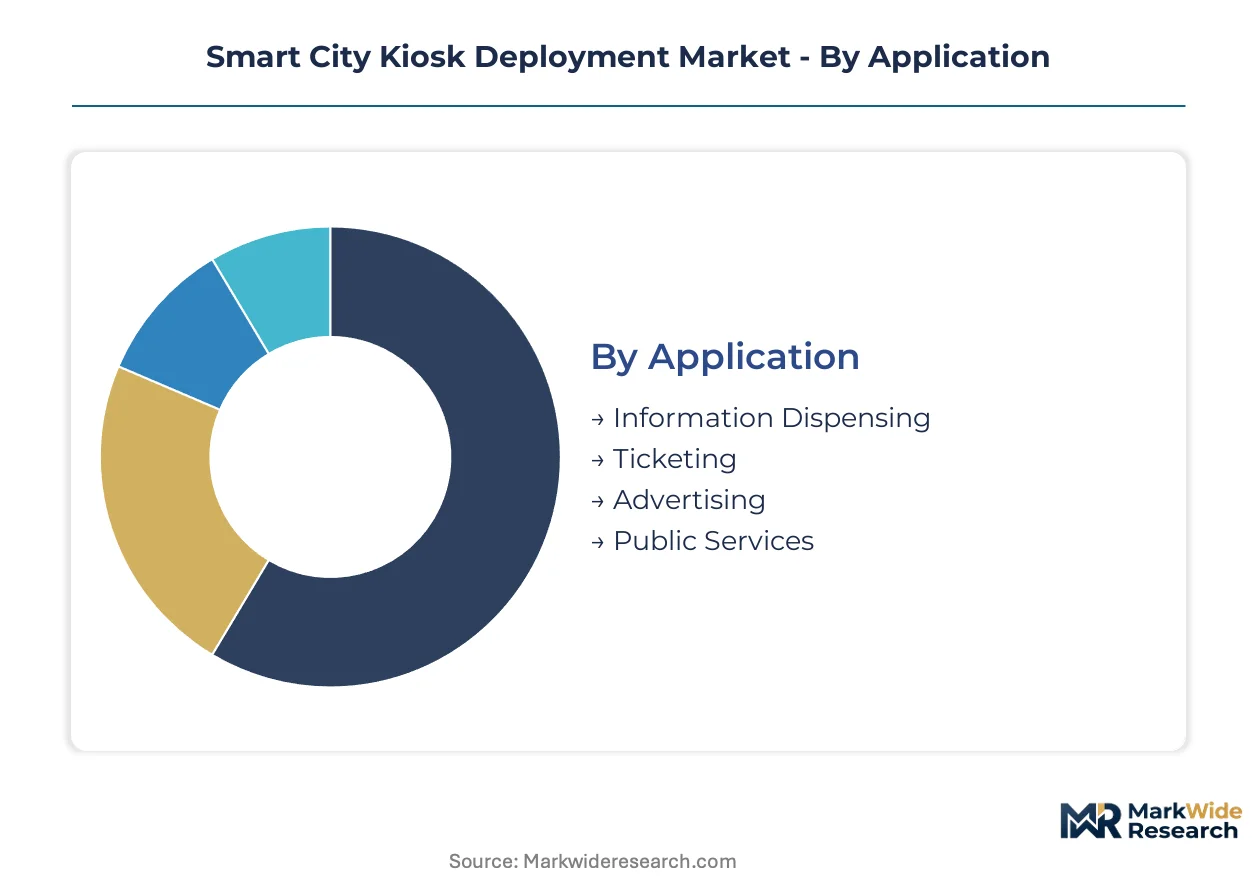
Smart city kiosk procurement patterns diverge sharply between high-volume transit information terminals and premium interactive systems with biometric capabilities. Understanding these segment boundaries clarifies where software recurring revenue accumulates versus hardware margin compression.
Application:
Volume deployment concentrates in transit information terminals, while premium pricing attaches to advertising-integrated and public service platforms with payment capabilities.
- Information Dispensing:Static and interactive displays delivering real-time transit schedules, wayfinding, and municipal alerts. Transportation authorities in Germany and Canada dominate procurement volumes as legacy analog signage replacement cycles accelerate.
- Ticketing:Fare collection terminals with NFC payment integration and account-based ticketing backhaul. Contactless transaction capabilities expand average revenue per unit through commission structures, with Transport for London and Metrolinx Toronto driving specification standards.
- Advertising:Large-format LED-integrated units with audience analytics modules. GDPR biometric restrictions in Europe constrain facial recognition deployment, compressing addressable inventory in member states.
- Public Services:Multi-function terminals integrating permit applications, bill payment, and emergency alert activation. Municipal governments in Pune and Ahmedabad issue tenders requiring localized language support under India's smart city mission.
Mature deployment sits with Information Dispensing. Newer deployment is concentrated in Public Services.
Service Type:
Margin pools shift toward recurring software and content management as municipal procurement consolidates fragmented vendor ecosystems into unified fleet management platforms.
- Installation:Site preparation, electrical trenching, network backhaul provisioning, and physical security anchoring. Field technician skill scarcity in IP networking and electrical safety concentrates specialized contractor pools in North American and European urban corridors.
- Maintenance:Preventive servicing, component replacement, and environmental housing refurbishment. Subscription-based models displace break-fix arrangements in Chicago Transit Authority and Vancouver TransLink contracts.
- Software Development:Custom middleware for legacy transit system API compatibility, remote monitoring dashboards, and cybersecurity patching. Common Criteria EAL4+ evaluation for payment-enabled terminals extends development timelines.
- Content Management:Remote fleet management platforms with real-time template updates and multilingual publishing workflows. Per-terminal monthly fees restructure vendor cash flows toward predictable recurring revenue.
Installation and Maintenance capture volume revenue. Software Development and Content Management are climbing the fastest.
End User:
Government and transportation authority procurement dominates installed base, while retail and educational pilots test interoperability frameworks before scaled deployment.
- Government:Municipal offices deploying multi-service terminals for permit processing, tax payment, and civic engagement. EU AI Act compliance mandates reshape technical specifications ahead of enforcement deadlines.
- Transportation Authorities:Transit agencies modernizing passenger information systems with real-time crowding alerts and dynamic wayfinding. Edge computing architectures reduce backhaul latency for emergency systems.
- Retailers:Outdoor shopping districts and transit-adjacent commercial corridors deploying wayfinding-integrated advertising units. Solar-powered outdoor housings enable off-grid installation without electrical trenching.
- Educational Institutions:University campuses testing 5G private network convergence with kiosks serving as fixed wireless access points for IoT sensor grids.
Transportation Authorities anchor current volume. Educational Institutions represent the steepest expansion trajectory.
Technology:
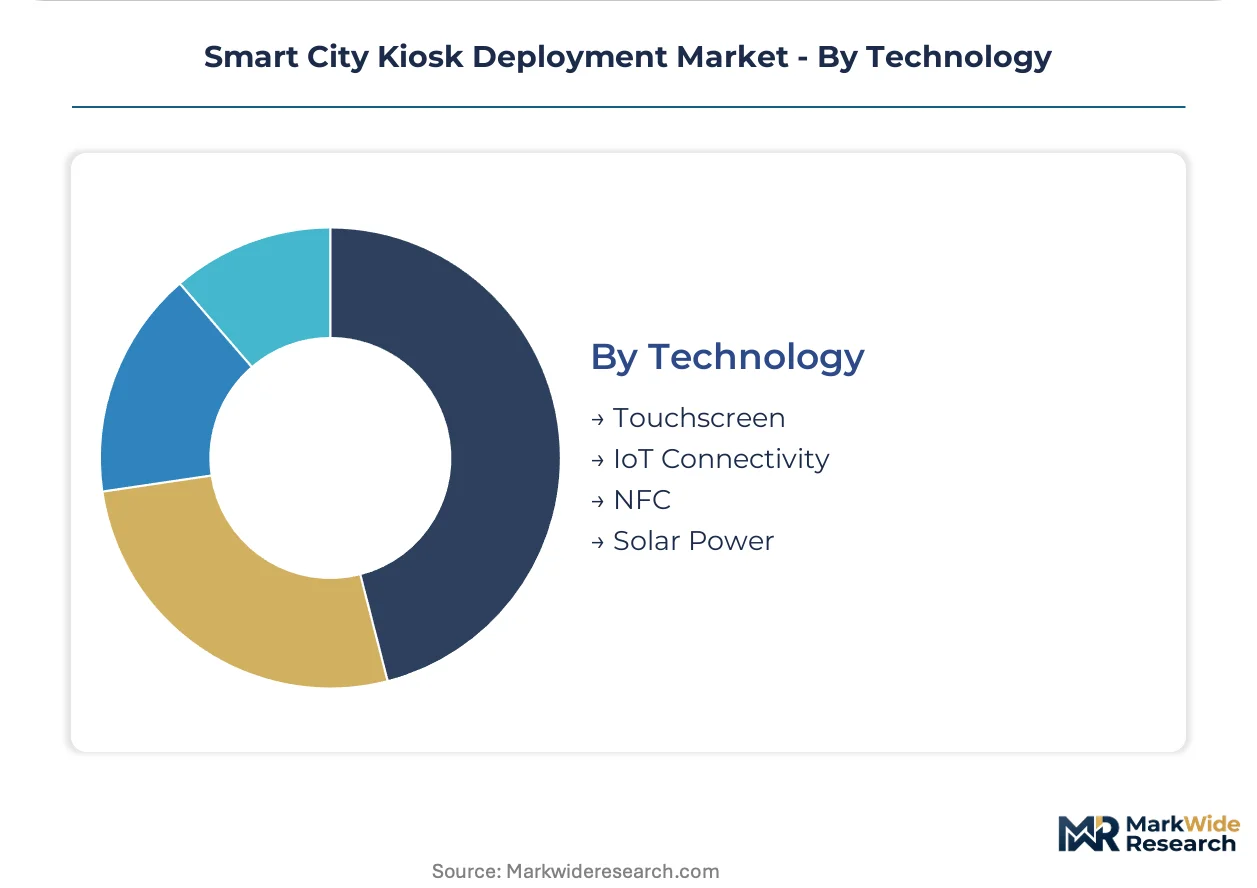
Touchscreen and IoT connectivity form the baseline specification, while NFC and solar power differentiate premium configurations for specific deployment contexts.
- Touchscreen:Projected capacitive and infrared touch controllers rated for outdoor environmental exposure. Taiwanese and South Korean foundry concentration exposes deployment timelines to semiconductor allocation volatility.
- IoT Connectivity:Cellular and fiber backhaul modules enabling real-time data exchange with central management platforms. FCC Part 15 emissions standards govern radio-frequency modules in US deployments.
- NFC:Contactless payment and identity verification readers integrated with fare collection and access control systems. Commission structures from transaction processing expand unit economics in transit hub concentrations.
- Solar Power:Photovoltaic-integrated housings with battery backup for off-grid parks and waterfront corridors. Soofa anchors market position in this configuration for North American transit agencies.
Touchscreen and IoT Connectivity constitute mature baseline specifications. Solar Power is gaining share fastest among technology differentiators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Transportation authorities in German metropolitan clusters like Berlin-Brandenburg and the Rhine-Ruhr corridor drive the densest kiosk deployment density worldwide, with municipal procurement offices embedding EU AI Act compliance into technical specifications ahead of formal enforcement deadlines.
Germany
The KBA and federal procurement offices mandate interoperable urban infrastructure standards that reduce vendor lock-in. Municipal governments in Hamburg and Munich prioritize unified fleet management platforms over fragmented point solutions. The Rhine-Ruhr corridor concentrates Europe's largest installed base of transit-information terminals with real-time crowding analytics.
United States
FCC Part 15 emissions standards govern radio-frequency modules while transportation authorities in Chicago and New York modernize passenger information systems. The Chicago Transit Authority shifted to subscription-based fleet management platforms with per-terminal monthly fees. California transit agencies test solar-powered outdoor units in parks and waterfront corridors without electrical trenching.
United Kingdom
Transport for London pilots computer vision modules with on-device inference for platform crowding alerts, compressing data architectures from cloud-dependent pipelines to localized decision loops. GDPR biometric restrictions constrain facial recognition deployment in advertising-integrated units. Manchester and Birmingham municipal authorities consolidate fragmented vendor ecosystems into unified procurement frameworks.
India
The national smart city mission drives tender issuance from municipal corporations in Pune, Surat, and Ahmedabad for interoperable transit-information terminals with localized language support. BIS compliance frameworks shape hardware specifications for outdoor environmental housings. Maharashtra and Gujarat sub-regions concentrate pilot deployments of multi-function public service terminals integrating permit applications and bill payment.
Canada
Metrolinx in Toronto drives specification standards for NFC-enabled fare collection terminals with account-based ticketing backhaul. Health Canada and PMRA frameworks intersect with municipal procurement for units deployed in transit-adjacent public health contexts. Vancouver's TransLink shifted to subscription-based fleet management covering remote monitoring and cybersecurity patching.
Smart City Kiosk Deployment Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across hardware fabrication and cloud software layers. The vendor base organizes into three strategic archetypes: vertically integrated infrastructure specialists controlling captive manufacturing, solar-powered outdoor unit purveyors serving off-grid deployment contexts, and telecommunications carriers leveraging network assets for connectivity provisioning. Dominant competitive moves include backward integration into touch controller and cellular modem sourcing, plus geographic expansion through municipal authority relationship cultivation.
Among North American infrastructure specialists, CIVIQ Smartscapes LLC and Soofa, Inc. occupy distinct positioning vectors within the competitive structure. CIVIQ Smartscapes exemplifies the vertically integrated archetype with unified hardware and cloud software control. Soofa, Inc. anchors the solar-powered outdoor configuration segment for transit agency deployments. Verizon Communications Inc. represents telecommunications carrier leverage of network infrastructure for kiosk backhaul provisioning. NEC Corporation and Panasonic sit within the Asian metropolitan pilot ecosystem for large-format LED-integrated installations.
| Leading Market Players |
|---|
| CIVIQ Smartscapes LLC |
| Smart City Media |
| Soofa, Inc. |
| Verizon Communications Inc. |
| OLEA Kiosks Inc. |
| Intel Corporation |
| NEC Corporation |
| Panasonic |
| Diebold Nixdorf, Incorporated |
| Others |
Value Network & Pricing Analysis
Backward integration into touch controller and cellular modem sourcing anchors both supply security and margin control for kiosk manufacturers bidding on municipal fleet contracts. CIVIQ Smartscapes and NEC Corporation leverage captive manufacturing to buffer against foundry allocation volatility while commanding premium pricing on EU AI Act-compliant terminals.
Pricing Analysis
Value-based pricing anchored to uptime guarantees and fleet management dashboard functionality dominates municipal procurement. Three-tier pricing structure across premium interactive systems with edge computing, standard touchscreen terminals, and commodity static displays separates vendors by software recurring revenue potential. Pricing pressure stems from LCD panel input cost exposure to Chinese glass substrate capacity fluctuations. Transportation authorities exhibit highest price sensitivity on hardware procurement, while software development and content management services face lower negotiation pressure due to specialized skill scarcity.
Supply Chain Analysis
Freight cost escalation on large-format display glass from Chinese manufacturing hubs to European and North American assembly plants compresses margins on premium LED-integrated installations. Touch controller and cellular modem sourcing concentrates in Taiwan and South Korea, creating single-source vulnerability for deployment timelines. Raw material dependencies include projected capacitive sensor arrays, IP54-rated environmental housings, and photovoltaic-integrated battery systems. Distribution runs through specialized contractor pools with combined IP networking and electrical safety competencies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The smart city kiosk market functions as a vertical-integration race where control over edge computing modules and cloud software layers determines contract capture. Players pursuing backward integration into semiconductor sourcing gain procurement cycle advantages.
For Market Incumbents: Extend subscription-based fleet management platform penetration to lock in recurring revenue before municipal procurement consolidation completes. Defend against solar-powered outdoor unit specialists by integrating photovoltaic housings into standard product lines. Prioritize EU AI Act compliance documentation to preempt German municipal technical specification requirements.
For New Entrants and Emerging Players: Begin with interoperable transit-information terminals for India's smart city mission in Pune, Surat, and Ahmedabad where localized language support requirements fragment incumbent advantage. Target educational institution pilots for 5G private network convergence applications. Pursue partnership-based go-to-market models with telecommunications carriers leveraging existing network infrastructure assets.
For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by telecommunications carriers seeking vertical integration into fixed wireless access point deployment. Long-term viability hinges on software recurring revenue stickiness rather than hardware shipment volumes. Monitor NFC payment integration penetration in transit hubs as inflection indicator for fare collection commission economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Touch Controllers | Reduces exposure to Taiwanese foundry allocation volatility for transit agency contracts. |
| EU AI Act Compliance Certification | Unlocks German municipal procurement where algorithmic transparency mandates reshape specifications. |
| Solar-Powered Housing Integration | Enables off-grid deployment in California parks and waterfront corridors without trenching costs. |
| 5G Private Network Convergence | Positions kiosks as fixed wireless access points for university campus IoT sensor grids. |
| Subscription Fleet Management Platform | Restructures vendor cash flows toward predictable recurring revenue with extended contract durations. |
Research Methodology
Document review covered municipal procurement databases, transit authority RFP filings, and regulatory compliance frameworks, complemented by interviews with kiosk fleet operations managers, municipal IT procurement officers, and cellular modem sourcing specialists. Secondary validation drew from FCC Part 15 emissions filings, EU AI Act implementation guidance, and BIS hardware specification documents. Bottom-up unit deployment estimates triangulated against top-down municipal budget allocation data.
Installed base projections and revenue forecasts emerged from segment-level modeling across application type, service tier, end-user category, and technology configuration throughout the forecast period. CAGRs derived from historical deployment velocity in Germany, United States, and India adjusted for regulatory compliance timeline acceleration and semiconductor supply constraints. Industry-specific inputs included transit agency modernization cycle phasing and solar-powered unit adoption curves in off-grid deployment contexts.
Underlying measurement precision varies by segment; information dispensing and touchscreen baseline specifications carry tighter precision than emerging solar power and 5G convergence applications. Forecasts reflect assumptions regarding EU AI Act enforcement timing and foundry capacity allocation stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
India Smart City Market
Smart City Technology
Smart City Framework Market
Smart City Technology
Global Smart/Connected Street Lights Market
Smart City Technology
Global Smart City Market
Smart City Technology
US Smart Cities Market
Smart City Technology
Saudi Arabia Smart Cities Market
Smart City Technology
Smart Space Market
Smart City Technology
Smart Parcel Locker Market
Smart City Technology
Smart Signaling Market
Smart City Technology
Global Smart City ICT Infrastructure Market
Smart City Technology
Smart Street Lights Market
Smart City Technology
Smart Mailbox Market
Smart City Technology
Smart Shade Device Market
Smart City Technology
City Data Platform Market
Smart City Technology
Smart Parcel Delivery Locker Market
Smart City Technology
Smart City Kiosk Market