
 Global Smart City ICT Infrastructure Market | 2026-2036
Global Smart City ICT Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart City ICT Infrastructure Market Outlook
Premium fiber-optic backbones and commodity wireless mesh networks is decoupling as procurement teams split capital between latency-critical and cost-sensitive workloads. Siemens leverages its factory automation heritage to anchor smart grid deployments across German industrial zones. Huawei Technologies Co., Ltd. competes on 5G small-cell density for intelligent transport corridors in Middle Eastern city-states. Cisco Systems, Inc. controls the enterprise edge with software-defined networking stacks purpose-built for municipal data centers.
Global Smart City ICT Infrastructure encompasses the integrated hardware, software, and communication layers that collect, transmit, and process urban data across energy, mobility, water, and public safety systems, typically operating on sub-10 millisecond latency thresholds for real-time control loops. Smart Grid and Intelligent Transport Systems occupy the largest capital allocation pools, while AI and Big Data Analytics segments capture disproportionate R&D spend as cities prioritize predictive maintenance over reactive service models. IoT sensor networks sustain the fastest volume expansion, though Cloud Computing margins concentrate among hyperscale providers with dedicated sovereign cloud offerings.
The EU AI Act, GDPR, and CE marking frameworks constrain algorithmic transparency and data residency for platform vendors serving European municipalities. The EPA and FCC in the United States enforce emissions and spectrum rules that shape hardware specifications for smart lighting and connected vehicle infrastructure. Stakeholders must monitor divergence between sovereign data localization mandates and the technical architectures of multinational cloud providers.
Market Dynamics
Municipal procurement teams now split capital between latency-critical fiber backbones and cost-sensitive wireless mesh networks, creating divergent vendor ecosystems for real-time control versus bulk data transmission workloads.
Growth Catalysts
- MIIT Dual Carbon Mandates:China's Ministry of Industry and Information Technology carbon neutrality targets accelerate smart grid deployments in provincial capitals and intelligent transport corridors in Yangtze River Delta city clusters.
- EU AI Act Compliance:Algorithmic transparency requirements for urban data platforms drive replacement cycles in European municipalities, favoring vendors with documented explainability frameworks and edge-processing architectures.
- 5G Small-Cell Density:Middle Eastern city-states prioritize ultra-dense radio access networks for connected vehicle infrastructure, with transport authorities specifying sub-5 millisecond handover thresholds for autonomous shuttle routes.
Market Restraints
- Rare Earth Supply Concentration:Permanent magnet dependencies for IoT sensor motors and wind turbine generators concentrate in Chinese processing facilities, exposing non-domestic grid operators to export quota volatility.
- GDPR Data Residency Friction:European municipalities face 18-24 month procurement delays when evaluating multinational cloud providers against sovereign data localization requirements and cross-border transfer mechanism adequacy.
- Legacy SCADA Incompatibility:Decades-old industrial control protocols in water and energy distribution systems resist API-based integration with modern analytics platforms, forcing costly protocol gateway deployments.
Strategic Opportunities
- Indian Smart Cities Mission:The Ministry of Housing and Urban Affairs' 100-city program underfunds integrated ICT infrastructure, creating white space for private operators to finance, build, and operate municipal data centers on concession contracts.
- Digital Twin Convergence:Real-time sensor fusion with Building Information Modeling and geospatial systems enables predictive maintenance for underground utility networks, compressing emergency response windows from hours to minutes.
- US IRA Clean Energy Credits:Inflation Reduction Act production tax credits for grid modernization hardware reduce effective capex burdens for municipal utilities deploying advanced metering infrastructure and distributed energy resource management systems.
Industry Challenges
- Edge Computing Talent Scarcity:Municipal IT departments lack embedded systems engineers capable of configuring Kubernetes clusters on ruggedized field hardware, forcing reliance on vendor-managed service contracts with 40% markup structures.
- Interoperability Certification Backlogs:CE marking and FCC equipment authorization queues for IoT devices extend 8-14 months, delaying pilot-to-scale transitions for smart lighting and environmental sensor networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart City ICT Infrastructure Market |
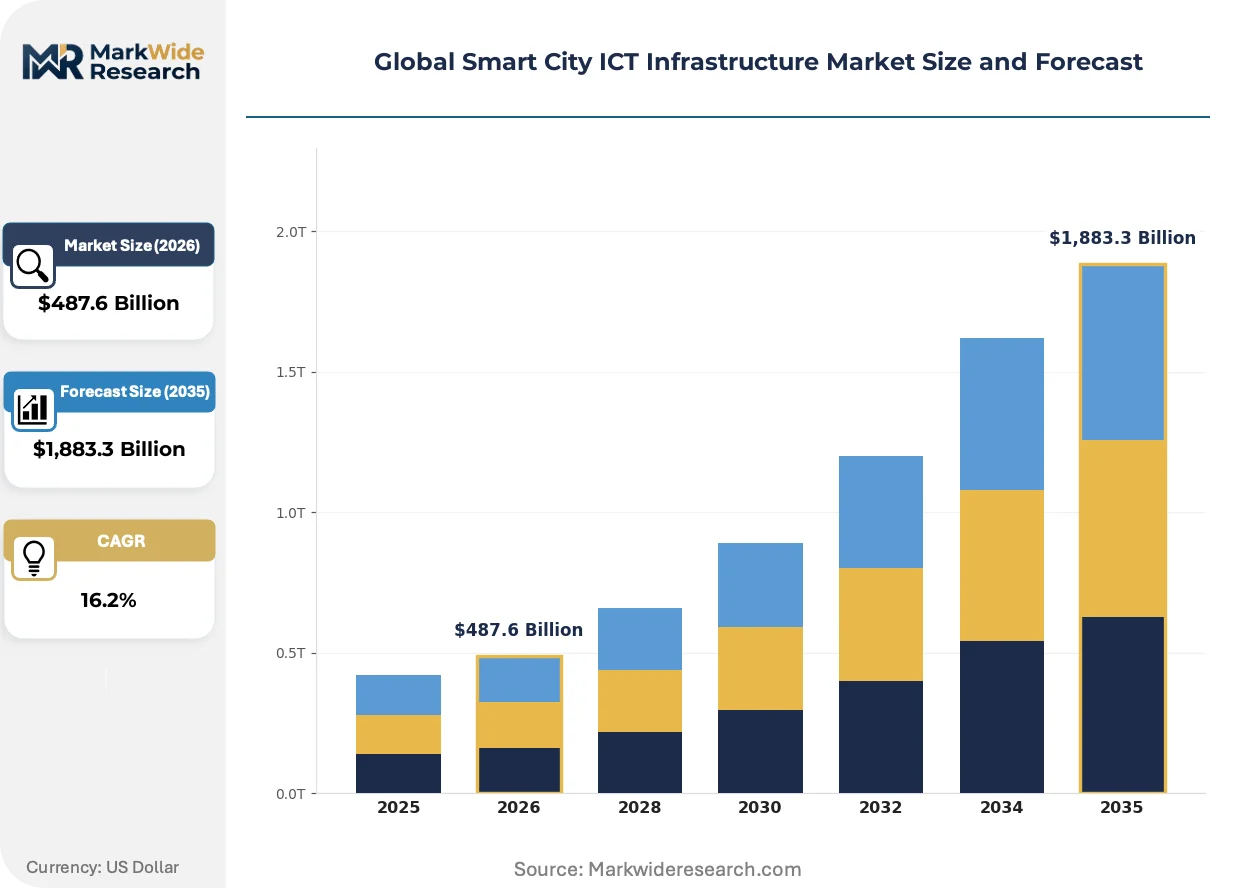
| Market Size in 2026 | $487.6 Billion |
| Market Size in 2035 | $1,883.3 Billion |
| CAGR (2026 – 2036) | 16.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Grid, Intelligent Transport Systems, Smart Water Management, Smart Lighting Technology: IoT, AI, Cloud Computing, Big Data Analytics End User: Cities, Government Agencies, Utility Providers, Transport Authorities Application: Traffic Management, Waste Management, Energy Efficiency, Public Safety |
| Companies Covered | Siemens, Schneider Electric, Cisco Systems, Inc., Hitachi, Ltd., Honeywell International Inc., Huawei Technologies Co., Ltd., Microsoft Corporation, Verizon Communications, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart City ICT Infrastructure Market Strategic Shifts
Edge-native processing architectures are displacing cloud-centric designs as latency requirements tighten for autonomous mobility and grid stabilization applications, while regulatory pressure on algorithmic accountability accelerates investment in explainable AI tooling.
Digital twin platforms integrating real-time IoT telemetry with 3D geospatial visualization is rewriting how transport authorities model traffic flow and utilities simulate pipe network stress. German industrial zones and Singapore's Land Transport Authority deploy these systems for scenario planning. The technology compresses infrastructure planning cycles from multi-year studies to iterative simulation sprints.
The EU AI Act's risk classification framework for critical infrastructure algorithms imposes conformity assessment burdens on predictive maintenance software vendors. High-risk system providers must maintain technical documentation and human oversight protocols. European city procurement teams now embed these compliance checkpoints into RFP evaluation criteria, disadvantaging lean software entrants.
Municipal buyers increasingly unbundle hardware procurement from long-term service contracts, treating sensors and edge devices as commodity purchases while competitively tendering analytics and maintenance separately. This pattern is most visible in North American water utility digitization programs, where cities source LoRaWAN endpoints through cooperative purchasing agreements but negotiate data platform subscriptions directly.
Global Smart City ICT Infrastructure Market Segmentation
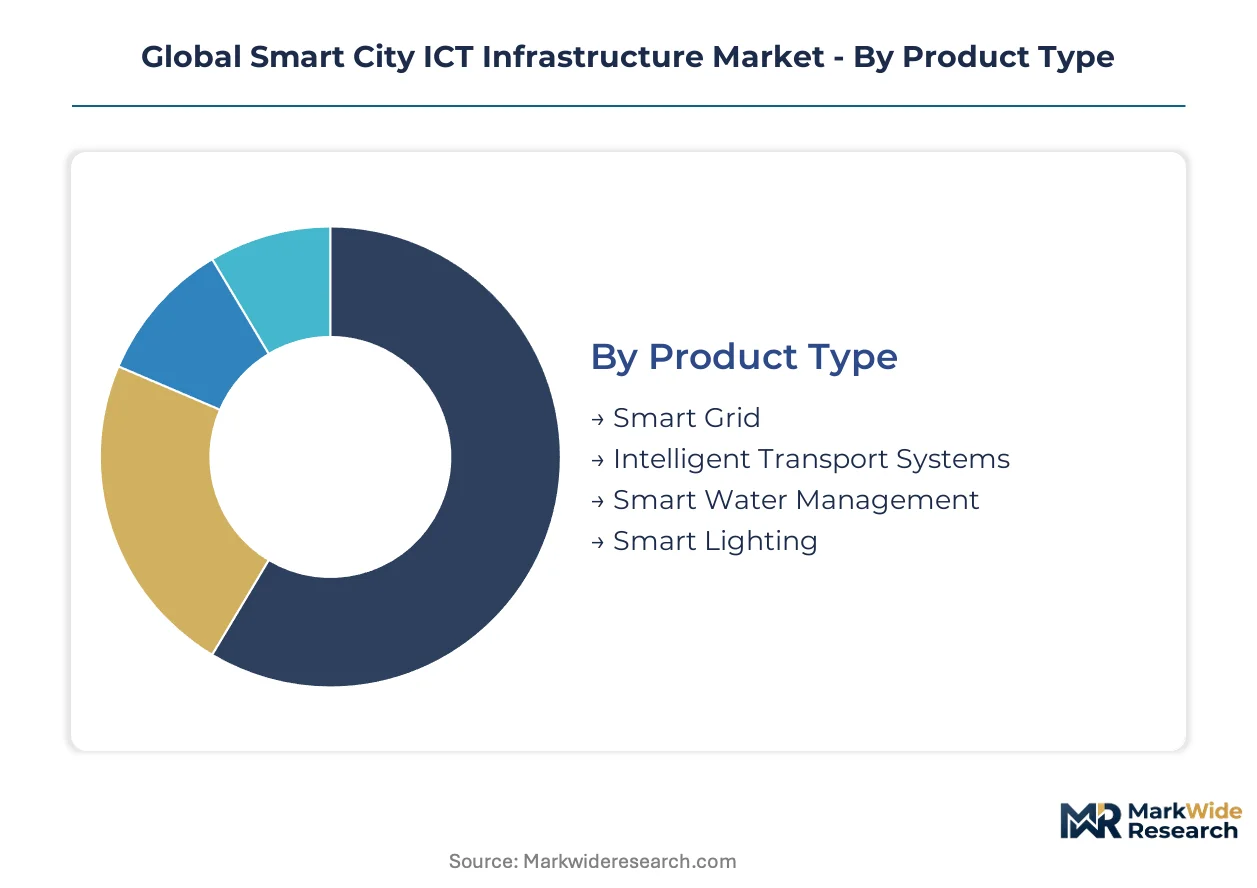
Municipal procurement cycles for smart city infrastructure operate on staggered replacement timelines, with energy and mobility systems commanding earlier upgrade waves than environmental and lighting assets. Understanding segment-specific refresh rates enables vendors to align R&D roadmaps with predictable budget windows.
Product Type:
Replacement cycles diverge sharply across urban infrastructure categories, with grid and transport assets requiring 7-10 year upgrades versus 12-15 year cycles for water and lighting systems.
- Smart Grid:Advanced metering infrastructure and distributed energy resource management systems form the backbone of utility digitization. China's provincial capitals under MIIT dual carbon mandates deploy these systems fastest, though rare earth magnet dependencies in transformer equipment create supply vulnerability.
- Intelligent Transport Systems:Connected vehicle infrastructure, traffic signal optimization, and autonomous shuttle corridors demand sub-5 millisecond latency architectures. Middle Eastern city-states specify ultra-dense 5G small-cell networks for these deployments, with transport authorities mandating stringent handover thresholds.
- Smart Water Management:Leak detection sensors and pressure monitoring networks address non-revenue water losses in aging distribution systems.
- Smart Lighting:LED conversion programs with integrated environmental sensing provide the entry point for many municipal digitization initiatives.
Volume placements concentrate in Smart Grid; the faster expansion belongs to Intelligent Transport Systems.
Technology:
Cost tiering separates premium edge-native processing stacks from commodity cloud subscriptions, with municipal buyers unbundling hardware procurement from analytics services.
- IoT:Sensor networks for environmental monitoring, asset tracking, and predictive maintenance sustain the steepest volume expansion. LoRaWAN and NB-IoT protocols dominate European deployments under GDPR data minimization constraints, while cellular IoT accelerates in Asian industrial zones.
- AI:Predictive maintenance algorithms and traffic flow optimization engines capture disproportionate R&D investment. EU AI Act risk classifications impose conformity assessment burdens on high-risk system vendors, embedding documentation requirements into procurement criteria.
- Cloud Computing:Sovereign cloud offerings from hyperscale providers address data residency mandates in regulated markets.
- Big Data Analytics:Urban data platform subscriptions increasingly compete separately from hardware procurement.
Hardware volume concentrates in IoT; AI platforms are climbing the fastest.
End User:
Customer type determines contract structure, with utility providers favoring long-term service agreements and transport authorities preferring performance-based procurement.
- Cities:Integrated master planning across energy, mobility, and public safety domains requires centralized data platforms. Singapore's municipal government anchors this segment with unified procurement for traffic management and grid modernization.
- Government Agencies:National smart city missions in India and standard-setting bodies in Germany shape technical specifications and funding mechanisms for sub-municipal deployments.
- Utility Providers:Grid operators and water utilities prioritize SCADA replacement and AMI rollout with defined ROI thresholds.
- Transport Authorities:Sub-national bodies manage corridor-specific intelligent transport investments with distinct latency requirements.
Contract value concentrates with Cities; Government Agencies are gaining share fastest.
Application:
Maturity curves separate established traffic management deployments from emerging waste and safety analytics, with energy efficiency bridging both phases.
- Traffic Management:Real-time signal optimization and congestion pricing systems represent the most deployed use case. German industrial zones and Singapore's Land Transport Authority deploy digital twin platforms for scenario planning, compressing infrastructure studies from multi-year cycles to iterative sprints.
- Energy Efficiency:Building automation and district heating optimization span commercial and residential building stocks. US municipal utilities leverage IRA production tax credits to reduce effective capex burdens for advanced metering infrastructure.
- Waste Management:Fill-level sensors and route optimization algorithms address collection efficiency in dense urban cores.
- Public Safety:Video analytics and emergency response coordination platforms face stringent algorithmic accountability requirements.
Deployment scale concentrates in Traffic Management; Public Safety is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's Land Transport Authority anchors global smart city deployment velocity with integrated traffic management platforms built on IoT sensor networks and edge computing architectures.
China
Provincial capitals under MIIT dual carbon mandates deploy smart grid infrastructure fastest, with Yangtze River Delta city clusters driving intelligent transport corridor investments. The Ministry of Industry and Information Technology enforces carbon neutrality targets that accelerate municipal digitization timelines. Shenzhen and Shanghai concentrate 5G small-cell density deployments for autonomous shuttle networks.
Germany
Industrial zones in Bavaria and North Rhine-Westphalia anchor smart grid modernization through factory automation heritage integration. The EU AI Act and GDPR compliance requirements shape procurement standards for urban data platforms across municipal governments. Siemens leverages its automation legacy to anchor deployments across German industrial corridors.
United States
Municipal utilities leverage IRA production tax credits to reduce effective capex burdens for advanced metering infrastructure rollout. The EPA and FCC enforce emissions and spectrum rules that shape hardware specifications for smart lighting and connected vehicle infrastructure. California and Texas utilities concentrate distributed energy resource management system deployments.
United Arab Emirates
Transport authorities in Dubai and Abu Dhabi specify ultra-dense 5G small-cell networks for connected vehicle infrastructure with sub-5 millisecond handover thresholds. MOHAP and federal telecom regulators mandate data localization for critical infrastructure platforms. Dubai's Roads and Transport Authority pilots autonomous shuttle corridors with stringent latency architectures.
India
The Ministry of Housing and Urban Affairs' 100-city Smart Cities Mission underfunds integrated ICT infrastructure, creating white space for private operators. CEA and TRAI regulations shape technical specifications for municipal data center deployments. Maharashtra and Karnataka state capitals concentrate concession-based municipal data center financing models.
Global Smart City ICT Infrastructure Market Competitive Environment
Premium-margin players sit above commodity-margin players across latency-tier specialization, with fiber-backbone vendors commanding higher service attach rates than wireless mesh hardware suppliers. The vendor ecosystem splits between integrated platform providers and component specialists. Three archetypes dominate: industrial automation heritage firms, telecom infrastructure incumbents, and hyperscale cloud operators. Consolidation pressure concentrates among edge computing software layers, while hardware procurement unbundling accelerates competitive tendering for analytics subscriptions.
Within the industrial automation tier, Siemens and Schneider Electric exemplify platform-integrated positioning, while Cisco Systems, Inc. anchors enterprise edge control with software-defined networking stacks purpose-built for municipal data centers. Huawei Technologies Co., Ltd. occupies a position in 5G small-cell density competition for intelligent transport corridors. These three entities represent divergent strategic anchors: factory automation heritage, enterprise networking dominance, and telecom infrastructure scale.
| Leading Market Players |
|---|
| Siemens |
| Schneider Electric |
| Cisco Systems, Inc. |
| Hitachi, Ltd. |
| Honeywell International Inc. |
| Huawei Technologies Co., Ltd. |
| Microsoft Corporation |
| Verizon Communications |
| IBM Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive edge-computing production by Siemens and Huawei anchors premium pricing power for sub-5 millisecond latency stacks, while outsourced wireless mesh hardware feeds commoditization pressure in cost-sensitive municipal sensor deployments. This integration divergence splits vendor margins between service-attach-rich fiber backbone contracts and volume-driven LoRaWAN endpoint supply.
Pricing Analysis
Value-based pricing tied to traffic throughput uptime dominates intelligent transport procurements, with Middle Eastern transport authorities paying premiums for sub-5 millisecond handover guarantees. Three-tier pricing structure across premium edge-native, standard cloud-hybrid, and economy wireless mesh levels reflects certification grade differentiation under EU AI Act conformity requirements. Cost compression in wireless sensor tiers is intensifying because unbundled hardware procurement treats LoRaWAN endpoints as commodity purchases. Municipal utilities show least price sensitivity for grid modernization with IRA credit offsets, while Indian smart city missions exhibit highest sensitivity due to underfunded integrated ICT budgets.
Supply Chain Analysis
Direct-to-municipal channels handle hyperscale smart grid deployments, while systems integrators intermediate fragmented transport authority procurements. Permanent magnet processing concentrates in China, South Korea, and Japan, with rare earth dependencies for IoT sensor motors drawing from Chinese export quota systems. 5G small-cell radio units, edge servers, and fiber-optic cable constitute the core component stack. Single-source vulnerability in Chinese rare earth processing exposes non-domestic grid operators to supply disruption. Distribution runs through vendor-managed service contracts with 40% markup structures where municipal IT departments lack embedded systems engineering capacity.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
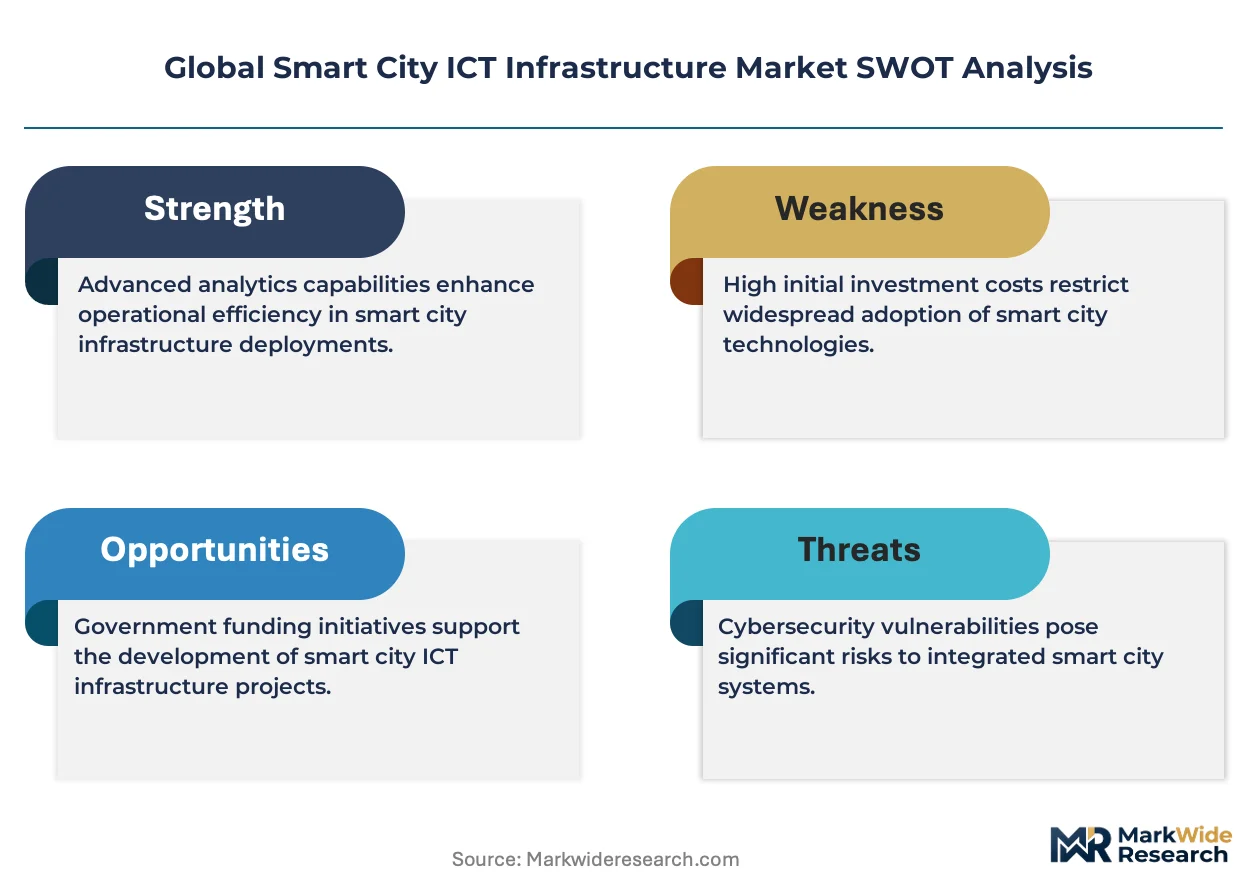
Consolidation pressure concentrates among edge computing software layers as interoperability certification backlogs and talent scarcity force weaker analytics vendors toward acquisition or exit. EU AI Act documentation requirements embed compliance burdens that disadvantage lean software entrants lacking conformity assessment resources.
For Market Incumbents: To counter unbundled procurement patterns, Siemens and Cisco should deepen captive production of Kubernetes-configured ruggedized field hardware, reducing reliance on 40% markup service contracts. Anchor smart grid deployments through backward integration into transformer equipment with documented rare earth magnet sourcing alternatives, insulating municipal utility clients from Chinese export quota volatility.
For New Entrants and Emerging Players: Launch via concession-based municipal data center financing in Maharashtra and Karnataka state capitals, where India's Smart Cities Mission underfunding creates white space for private build-operate-transfer models. Target explainable AI tooling for EU municipalities facing 18-24 month procurement delays, embedding algorithmic transparency documentation as a first-mover compliance advantage.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap edge computing specialists with sovereign cloud certifications and documented EU AI Act conformity frameworks. Long-term viability favors vendors with dual exposure to MIIT-mandated Chinese provincial deployments and IRA-credit-backed US utility modernization. Watch CEA and TRAI regulatory finalization in India as the inflection signal for concession contract standardization.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-Native Platform Integration | Displacement of cloud-centric designs tightens latency for autonomous mobility under MIIT dual carbon mandates. |
| Sovereign Cloud Certification | GDPR data residency compliance reduces 18-24 month procurement friction for European municipal buyers. |
| Digital Twin Convergence | Real-time sensor fusion with BIM compresses emergency response windows for Singapore Land Transport Authority. |
| Backward Integration into Rare Earth Processing | Captive magnet supply insulates transformer equipment from Chinese export quota volatility. |
| Concession-Based Municipal Data Center Financing | Private build-operate-transfer models address underfunding gaps in India's 100-city Smart Cities Mission. |
Study Parameters
Document review covered SEC 10-K filings from network equipment vendors, EU AI Act technical documentation, and MIIT dual carbon policy frameworks, complemented by interviews with municipal CIOs, transport authority procurement leads, and edge computing systems integrators. Bottom-up triangulation validated smart grid deployment volumes against top-down provincial capital budget allocations across China, Germany, and the United States.
Cross-reference of historical replacement cycle data against expert panel inputs shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type refresh rates, technology cost tiers, end-user contract structures, and application maturity curves. CAGRs derived from iterative convergence of utility AMI rollout trajectories, 5G small-cell density specifications, and sovereign cloud adoption patterns.
Regulatory finalization delays, rare earth supply disruptions, and municipal budget reallocation are the dominant revision risks to base-case infrastructure deployment assumptions. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
India Smart City Market
Smart City Technology
Smart Parking Meters Market
Smart City Technology
City Data Platform Market
Smart City Technology
UAE Smart Furniture Market
Smart City Technology
Singapore ICT Market
Smart City Technology
US Smart Cities Market
Smart City Technology
Global Smart Hubs Market
Smart City Technology
Smart Mailbox Market
Smart City Technology
Smart City Platform Market
Smart City Technology
Smart Parcel Locker Market
Smart City Technology
Smart Shade Device Market
Smart City Technology
Smart City Kiosk Deployment Market
Smart City Technology
Smart Communities Market
Smart City Technology
Saudi Arabia Smart Cities Market
Smart City Technology
Global Smart Pole Market
Smart City Technology
Global Smart Ticketing Market