
 Global Smart/Connected Street Lights Market | 2026-2036
Global Smart/Connected Street Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smart/Connected Street Lights Market Foresight
The divergence between premium and commodity tiers is hardening in the Global Smart/Connected Street Lights Market. Signify leverages its in-house LED chip fabrication to control margins at the high end, while Telensa competes on narrowband IoT specialization for cost-sensitive municipal tenders. Acuity Brands anchors its position through deep North American channel relationships and ANSI-compliant control systems.
Smart/connected street lights integrate solid-state LED engines with embedded sensors, wireless transceivers, and centralized management platforms to enable remote dimming, outage detection, and environmental data collection. The primary commercial purpose is reducing municipal energy expenditure while generating real-time urban data streams. LED deployments dominate installed base economics due to lumen-per-watt superiority and declining phosphor costs, while cloud-based technology architectures capture expanding margin pools as cities consolidate vendor management platforms. Smart Cities as a deployment model is concentrating procurement volume, though Public Infrastructure retains the longest replacement cycles.
The EU Green Deal and F-Gas Regulation constrain legacy high-intensity discharge retrofits across member states, while China's GB standards and MIIT IoT security mandates shape product certification requirements for export-oriented manufacturers. The US Department of Transportation's MUTCD compliance framework and FAA obstruction lighting rules create additional specification layers for interstate corridor projects. Stakeholders must weigh interoperability standards against vendor lock-in risks as procurement shifts toward outcome-based service contracts.
Market Dynamics
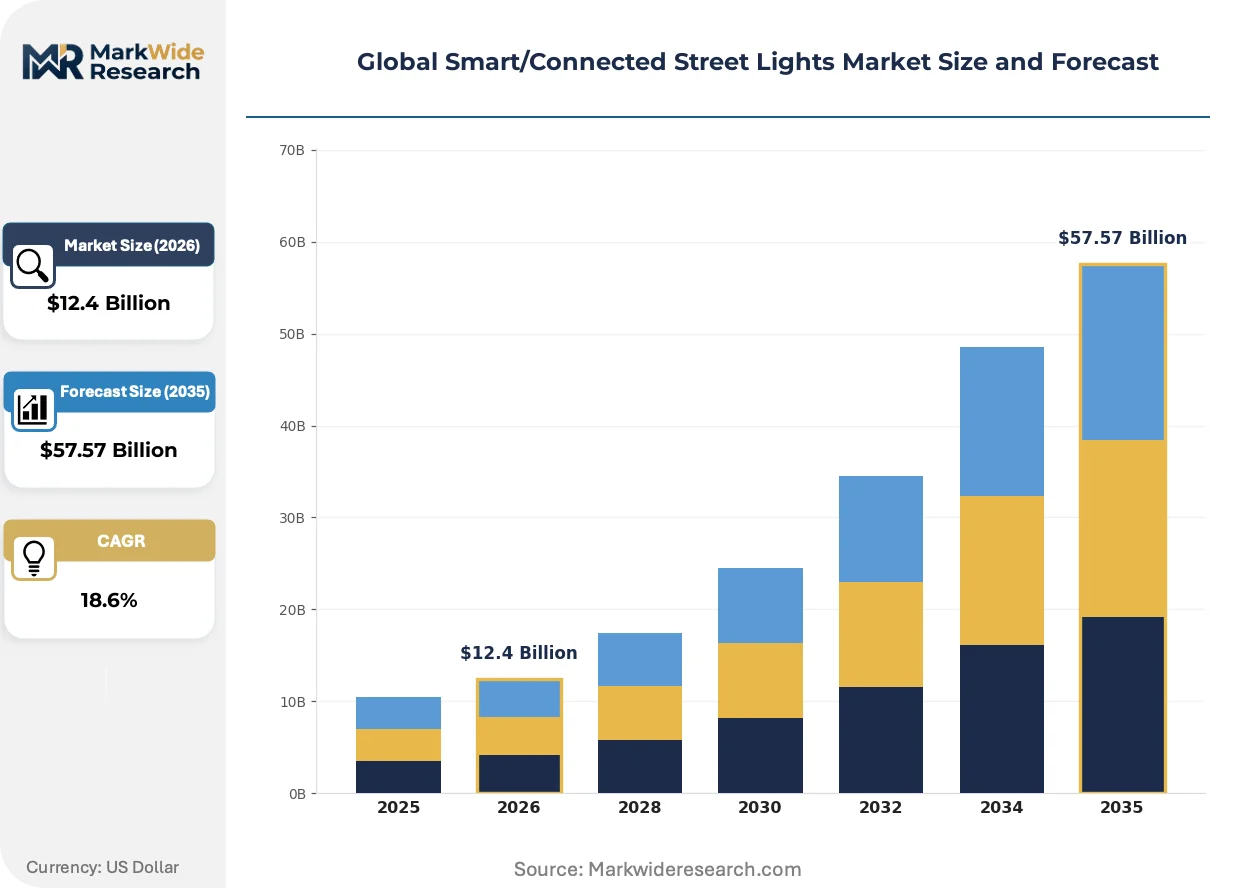
Municipal procurement consolidation around networked LED retrofits is compressing vendor margins while elevating platform-scale winners. The shift from fixture sales to multi-year service contracts favors suppliers with captive cloud infrastructure and embedded financing capabilities.
Growth Catalysts
- EU Green Deal decarbonization mandates:Binding national targets force legacy high-intensity discharge replacements across member states, creating standardized tender volumes for connected luminaire vendors.
- China's MIIT IoT security certification:Mandatory GB standards for networked infrastructure accelerate domestic procurement while raising export compliance barriers for foreign manufacturers.
- Edge computing convergence:Embedded AI accelerators in street-level nodes enable real-time traffic analytics and public safety applications, expanding addressable use cases beyond illumination.
Market Restraints
- Phosphor and rare earth input volatility:LED phosphor supply concentrates in Chinese processing facilities, exposing fixture manufacturers to price swings and export quota risks.
- Narrowband spectrum fragmentation:Incompatible LoRa, NB-IoT, and proprietary mesh protocols across municipal deployments force redundant hardware SKUs and inflate inventory carrying costs.
- F-Gas Regulation retrofit friction:EU constraints on legacy high-intensity discharge lamp disposal extend project timelines and raise compliance overhead for public works departments.
Strategic Opportunities
- India's Smart Cities Mission:Centralized AMRUT funding for 100 urban clusters creates concentrated demand for integrated lighting-management platforms with localized manufacturing incentives.
- LiDAR-sensor fusion:Combining optical cameras with ranging sensors in unified street-mounted enclosures opens autonomous vehicle infrastructure and pedestrian safety monitoring revenue streams.
- US IRA clean energy tax credits:Municipal deployment subsidies under the Inflation Reduction Act reduce payback periods for networked retrofits in budget-constrained mid-sized cities.
Industry Challenges
- Cyber-physical systems engineering scarcity:Municipal IT departments lack personnel trained in OT/IT convergence, delaying pilot-to-scale transitions and inflating implementation consulting costs.
- Legacy electromechanical control integration:Decades-old photocell and relay infrastructure in established cities requires expensive gateway hardware to achieve centralized management visibility.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smart/Connected Street Lights Market |
| Market Size in 2026 | $12.4 Billion |
| Market Size in 2035 | $57.57 Billion |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Solar, Hybrid, Traditional Deployment Model: Public Infrastructure, Commercial Sites, Residential Areas, Smart Cities Technology: IoT, Wireless, Cloud-Based, Automated Application: Traffic Management, Public Safety, Smart Waste Management, Environmental Monitoring |
| Companies Covered | Signify, Schneider Electric, Itron, Acuity Brands, Schreder, Telensa, Osram, Eaton, GE Current, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smart/Connected Street Lights Market Shifts & Advancements
Silicon carbide power electronics and ambient light harvesting are compressing energy consumption benchmarks while enabling sensor-dense node architectures. These hardware advances are reshaping competitive differentiation around computational density rather than lumen output alone.
GaN-on-silicon LED drivers are electrifying fixture efficiency curves by cutting switching losses and thermal management overhead. Tier-one smart city clusters in China and Germany are specifying these subsystems for new-build corridors, compressing total cost of ownership calculations against legacy silicon alternatives.
REACH substance restrictions and RoHS amendments are forcing phosphor reformulation and solder alloy substitutions across European supply chains. Manufacturers serving EU tenders must recertify luminaire assemblies, with outdoor-rated products facing the most complex material compliance timelines.
Performance-based service contracting is displacing capital purchase models in Dutch and Danish municipal procurement. Cities now pay lumen-hours delivered rather than fixtures installed, transferring asset ownership and maintenance liability to vendor consortia while demanding guaranteed uptime SLAs.
Global Smart/Connected Street Lights Market Segmentation
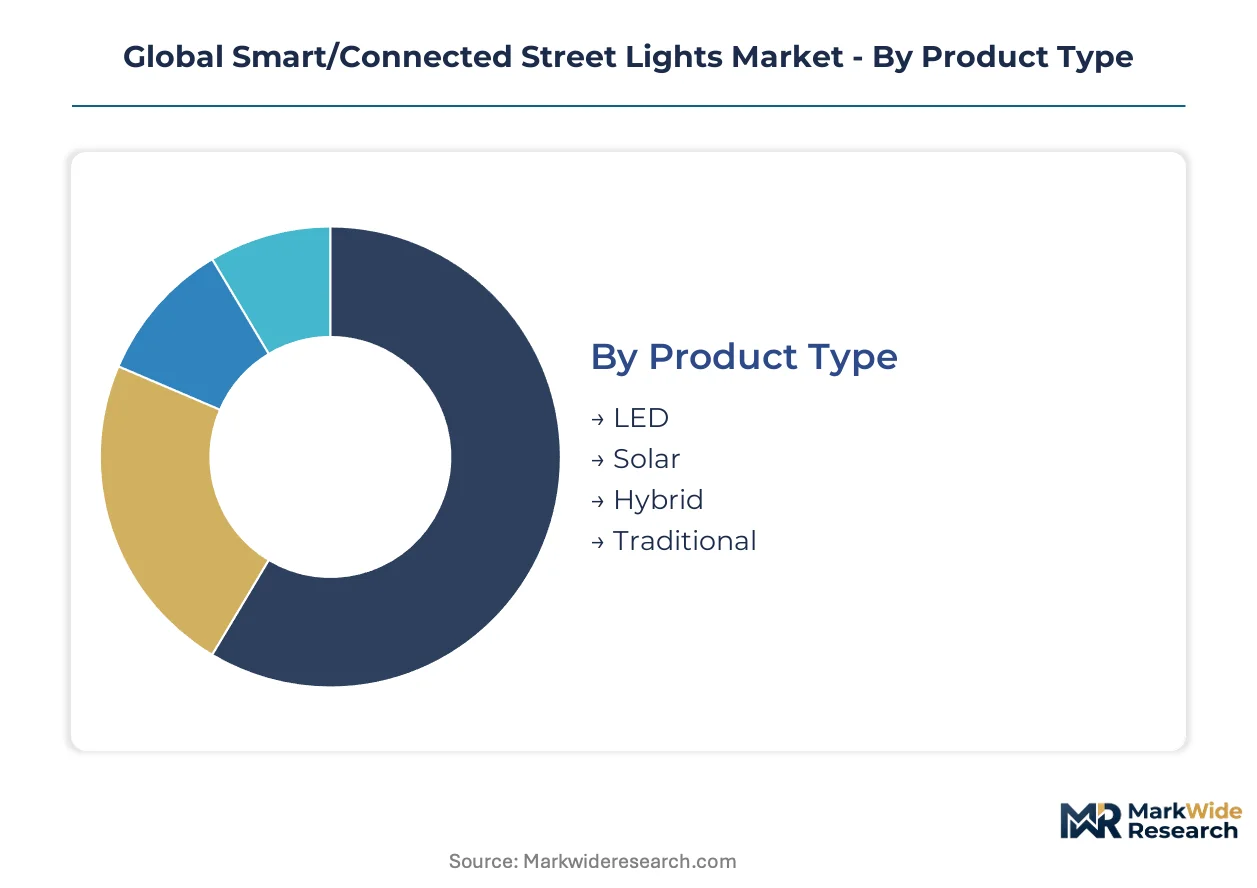
Segmentation in the Global Smart/Connected Street Lights Market reveals how capital allocation, regulatory pressure, and data monetization potential concentrate vendor priorities. Product choices dictate upfront infrastructure spend, while deployment models determine contract structure and payback horizons.
Product Type:
LED retrofits demand the heaviest capital outlays due to luminaire replacement, pole reinforcement, and control system integration across municipal portfolios.
- LED:Solid-state semiconductor engines deliver 130-150 lumens per watt with 50,000-hour rated lifespans. Procurement concentrates in Germany's federal highway programs and China's tier-one smart city clusters where energy efficiency mandates enforce minimum efficacy standards.
- Solar:Photovoltaic-integrated fixtures eliminate grid connection costs for remote corridors and island municipalities. Deployment accelerates across India's AMRUT-funded urban clusters and sub-Saharan African capitals where grid reliability remains intermittent and diesel backup costs are prohibitive.
- Hybrid:Grid-tied solar with battery buffering balances autonomy with reliability for critical infrastructure routes.
- Traditional:High-pressure sodium and metal halide legacy stock persists in budget-constrained secondary cities.
Most installed capacity flows through LED. Expansion is steepest in Solar.
Deployment Model:
Contract duration and financing complexity vary sharply across deployment models, with Smart Cities demanding 10-15 year service agreements versus transactional fixture sales in Residential Areas.
- Public Infrastructure:Federal and state highway departments specify ANSI-compliant control systems with NEMA socket interfaces. Procurement aggregates around the US Department of Transportation's MUTCD corridor upgrades and China's Ministry of Transport expressway digitization programs.
- Smart Cities:Integrated platform contracts bundle illumination with traffic analytics, air quality sensing, and public WiFi. Volume concentrates in China's MIIT-certified city clusters, the Netherlands' performance-based lumen-hour contracts, and Singapore's Punggol Digital District pilot.
- Commercial Sites:Retail parks and logistics hubs prioritize motion-activated dimming for liability reduction.
- Residential Areas:Homeowner association deployments favor low-cost photocell replacements over networked controls.
Platform-scale vendors capture margin in Smart Cities. Public Infrastructure retains the longest replacement cycles.
Technology:
Interoperability requirements fragment technology procurement, with Cloud-Based architectures capturing recurring revenue streams while IoT hardware faces protocol standardization pressures.
- Cloud-Based:Centralized management platforms aggregate telemetry from thousands of nodes for predictive maintenance and energy optimization. Adoption concentrates in Denmark's municipal consortia and California's regional energy districts where outcome-based contracting transfers operational risk to vendors.
- IoT:Embedded sensors and narrowband transceivers enable real-time outage detection and environmental data collection. Deployment accelerates under China's MIIT IoT security mandates and India's Smart Cities Mission specifications requiring domestic certification.
- Wireless:LoRa and NB-IoT protocols dominate where cellular coverage is uneven or subscription costs are prohibitive.
- Automated:AI-driven dimming algorithms adjust output based on traffic flow and ambient conditions without human intervention.
Recurring revenue concentrates in Cloud-Based. Hardware volume flows through IoT.
Application:
Data monetization potential determines application prioritization, with Traffic Management and Public Safety offering the clearest paths to ancillary revenue beyond illumination.
- Traffic Management:Optical and LiDAR sensors embedded in street enclosures feed real-time flow data to municipal traffic centers. Procurement clusters in Germany's KBA-connected autobahn digitization pilots and Singapore's autonomous vehicle testing zones where infrastructure-to-vehicle communication is mandatory.
- Public Safety:Gunshot detection, crowd analytics, and emergency call integration transform lighting assets into surveillance networks. Deployment concentrates in Chicago's Array of Things expansion and Rio de Janeiro's favela electrification programs.
- Environmental Monitoring:Particulate matter and noise sensors support EPA and EEA air quality compliance reporting.
- Smart Waste Management:Fill-level sensors in adjacent bins trigger optimized collection routing.
Municipal budgets prioritize Traffic Management. Public Safety is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in smart city infrastructure concentrate in Germany's Ruhr Valley, China's Yangtze River Delta, and the US research triangle, anchoring regional deployment capacity.
United States
Federal highway digitization programs and IRA clean energy tax credits drive municipal retrofit demand. The Department of Transportation's MUTCD compliance framework shapes procurement specifications for interstate corridor projects. Chicago's Array of Things expansion and California's regional energy districts concentrate platform-scale deployments.
Germany
Federal autobahn electrification and municipal energy efficiency mandates accelerate networked luminaire procurement. The KBA-connected vehicle infrastructure standards and EU Green Deal binding targets enforce minimum efficacy requirements. The Ruhr Valley industrial corridor and Bavaria's smart city pilots anchor high-specification tender volumes.
China
Tier-one smart city clusters in the Yangtze River Delta and Pearl River Delta dominate centralized procurement volumes. MIIT IoT security certification and GB standards for networked infrastructure raise export compliance barriers while accelerating domestic deployment. Beijing-Tianjin-Hebei and Sichuan-Chongqing regions concentrate manufacturing and pilot programs.
Netherlands
Performance-based lumen-hour contracting models displace capital purchase frameworks in municipal procurement. The EU Green Deal decarbonization mandates and REACH substance restrictions force phosphor reformulation across supply chains. Amsterdam and Rotterdam metropolitan consortia transfer asset ownership to vendor consortia under guaranteed uptime SLAs.
India
Centralized AMRUT funding for urban clusters creates concentrated demand for integrated lighting-management platforms. The Smart Cities Mission specifications require domestic certification while PLI scheme incentives support localized manufacturing. Maharashtra and Gujarat industrial corridors concentrate deployment, with Delhi-NCR and Bangalore anchoring platform integration pilots.
Global Smart/Connected Street Lights Market Competitive Landscape
Top-tier vendors anchor platform-scale service contracts, while mid-tier specialists compete on narrowband IoT specialization and regional tender access. The vendor base stratifies across captive cloud infrastructure owners, component-integrated fixture manufacturers, and narrowband protocol specialists. Two dominant competitive moves are emerging: vertical integration into LED chip fabrication to control input costs, and strategic partnerships with municipal financing consortia to capture multi-year service contracts.
Within the premium-tier vector, Signify and Acuity Brands occupy positions as archetypal platform-scale vendors with deep channel relationships, while Telensa exemplifies the narrowband IoT specialization archetype competing on cost-sensitive municipal tenders. These three companies represent the structural divergence between margin-protected high-end positioning and volume-driven standard-tier competition.
| Leading Market Players |
|---|
| Signify |
| Schneider Electric |
| Itron |
| Acuity Brands |
| Schreder |
| Telensa |
| Osram |
| Eaton |
| GE Current |
| Others |
Supply & Pricing Matrix
LED phosphor and rare earth processing costs anchor fixture manufacturing economics, flowing from Chinese extraction facilities through tier-one smart city tenders in the Yangtze River Delta to municipal procurement platforms in Germany and the Netherlands, with pricing power concentrating at the phosphor reformulation stage under REACH substance restrictions.
Pricing Analysis
The bundled-vs-unbundled service split separates capital purchase models in Residential Areas from performance-based lumen-hour contracts in Dutch and Danish municipal procurement. Pricing stratifies across premium, standard, and economy tiers based on MIIT IoT security certification status and captive cloud infrastructure ownership. Cost compression in the standard tier is intensifying because narrowband protocol fragmentation forces redundant hardware SKUs. Mid-sized cities in budget-constrained markets exhibit the highest price sensitivity, while tier-one smart city clusters prioritize guaranteed uptime SLAs over unit economics.
Supply Chain Analysis
Freight cost volatility from Chinese processing facilities to European assembly plants shapes inventory positioning strategies for fixture manufacturers serving EU Green Deal-mandated retrofits. Geographic supply concentrates in China for LED phosphors and rare earth elements, in Germany for silicon carbide power electronics, and in Taiwan for GaN-on-silicon substrates. Raw material dependencies rest on yttrium-aluminum-garnet phosphors, neodymium magnets, and high-purity silicon wafers. Single-source vulnerability concentrates in Chinese rare earth export quotas. Distribution runs through municipal procurement platforms and federal highway department tender aggregators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU Green Deal decarbonization mandates accelerate replacement cycles against China's MIIT certification barriers that raise export compliance costs for foreign manufacturers.
For Market Incumbents: To counter narrowband IoT specialization by cost-focused competitors, deepen backward integration into LED chip fabrication to control phosphor input costs, and expand captive cloud infrastructure ownership to capture multi-year service contract margins in Dutch performance-based procurement. For New Entrants and Emerging Players: Launch via India's AMRUT-funded Smart Cities Mission tenders where domestic certification requirements and PLI scheme incentives create protected demand pools for localized manufacturing, targeting sub-Saharan African capitals with solar-integrated fixtures where grid reliability gaps persist. For Investors and Strategic Acquirers: Consolidation pressure builds where municipal IT departments lack OT/IT convergence expertise, inflating implementation consulting costs and delaying pilot-to-scale transitions. Long-term viability centers on platform-scale vendors with embedded financing capabilities. The signal to watch is the share of procurement volume shifting from transactional fixture sales to guaranteed uptime SLAs under vendor consortia ownership.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into LED Chip Fabrication | Captive phosphor supply insulates margins from Chinese export quota volatility under MIIT oversight. |
| Performance-Based Service Contracting | Dutch lumen-hour models transfer asset ownership to vendors while locking in guaranteed uptime SLAs. |
| MIIT IoT Security Certification Investment | GB standards compliance opens tier-one Chinese smart city clusters while raising barriers for uncertified competitors. |
| LiDAR-Sensor Fusion Platform Development | Unified street-mounted enclosures capture autonomous vehicle infrastructure revenue in Singapore and Germany. |
| AMRUT-Funded Localized Manufacturing | PLI scheme incentives anchor production in Maharashtra and Gujarat to serve India's Smart Cities Mission. |
Research Methodology
Bottom-up municipal deployment modeling reconciled against top-down LED fixture production tracking forms the analytical core of this study. Primary interviews with municipal procurement officers, smart city platform engineers, federal highway planning directors, and narrowband IoT protocol specialists combined with secondary validation from EU Green Deal implementation reports, MIIT GB standard filings, USDOT MUTCD corridor upgrade databases, and AMRUT funding disbursement records. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map LED phosphor costs, narrowband transceiver pricing, and cloud platform subscription revenues across product type, deployment model, technology architecture, and application segmentation dimensions. CAGRs derive from fitted growth curves applied to municipal retrofit pipelines and smart city platform adoption rates. Forecast inputs incorporate EU F-Gas Regulation compliance timelines and China's dual carbon goals for infrastructure electrification.
Forecast precision tightens around the base case; tail outcomes carry wider variance under rare earth export quota disruptions or narrowband spectrum fragmentation intensification. Forecasts reflect documented assumptions about municipal budget continuity and certification harmonization progress. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
Smart City Platform Market
Smart City Technology
City Data Platform Market
Smart City Technology
Smart Shade Device Market
Smart City Technology
Saudi Arabia Smart Cities Market
Smart City Technology
India Smart City Market
Smart City Technology
Outdoor LED Smart Lighting Solution Market
Smart City Technology
Global Smart City Market
Smart City Technology
UAE Smart Furniture Market
Smart City Technology
Smart City Kiosk Market
Smart City Technology
Smart Communities Market
Smart City Technology
Smart Parcel Locker Market
Smart City Technology
Smart Parking Meters Market
Smart City Technology
Singapore ICT Market
Smart City Technology
Global Smart Pole Market
Smart City Technology
US Smart Cities Market
Smart City Technology
Smart Mailbox Market