
 Smart City Kiosk Market | 2026-2036
Smart City Kiosk Market Size, Share, and Industry Trends Forecast 2026-2036
Smart City Kiosk Market Analytics
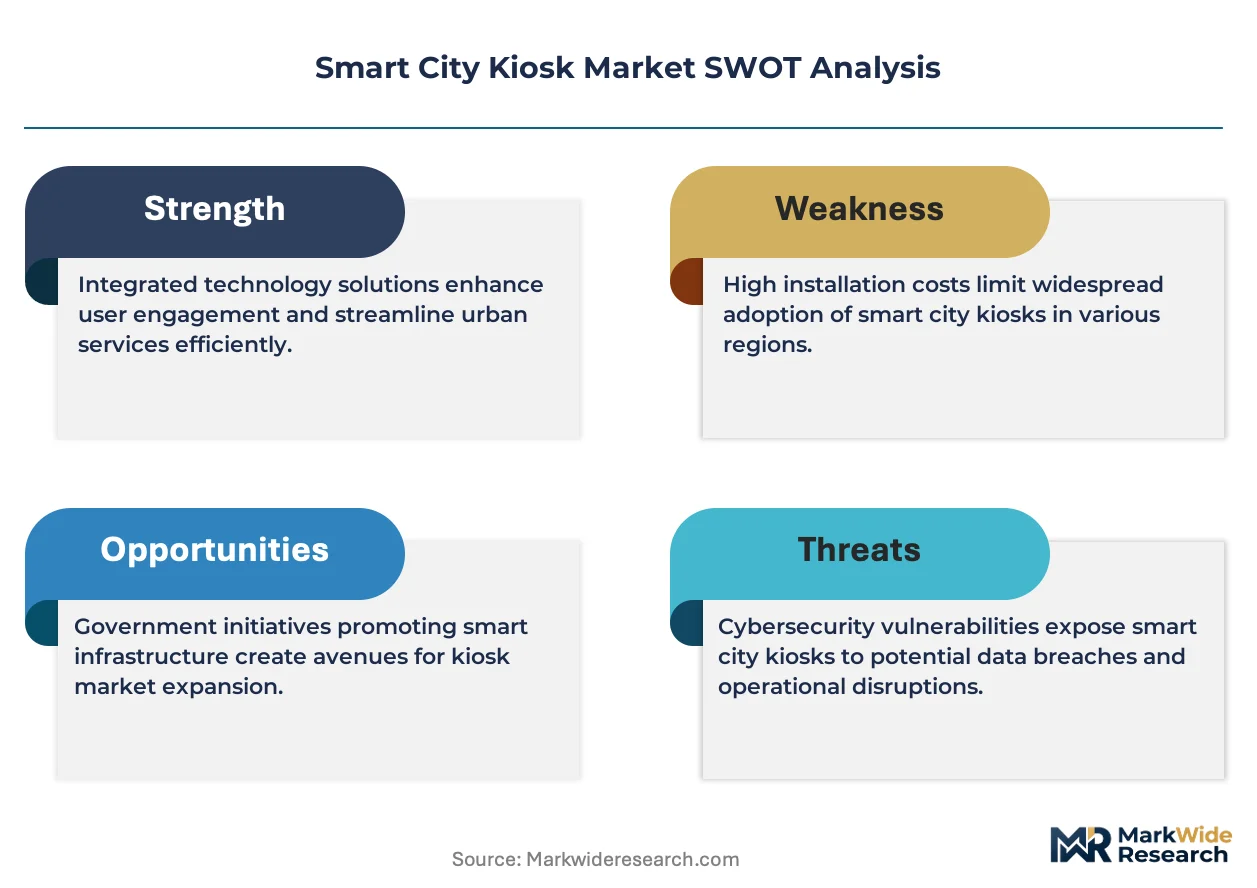
Outdoor-rated IP65 enclosure standards are reorganizing procurement criteria across the smart city kiosk landscape. CIVIQ Smartscapes LLC leverages its vertical integration into enclosure fabrication and display assembly to sustain cost advantages on large municipal contracts. Intel Corporation anchors the semiconductor layer with edge-computing chipsets purpose-built for kiosk AI workloads. Soofa Inc. differentiates through solar-powered deployments that reduce grid dependency in parks and pedestrian zones.
A smart city kiosk is a networked, self-service terminal installed in public spaces, typically integrating touchscreen interfaces, payment modules, environmental sensors, and wireless connectivity within weather-hardened housings ranging from 32-inch to 75-inch display formats. These units process real-time information dissemination, transit ticketing, and civic service transactions without staffed intervention. Interactive kiosks command the largest installed base among product types due to their versatility across wayfinding and service delivery applications, while solar-powered technology represents the fastest-expanding configuration as cities prioritize carbon-neutral infrastructure. Payment kiosks concentrate margin pools where transit agencies demand PCI-DSS compliant encryption and contactless reader integration.
The Federal Communications Commission governs wireless emissions and connectivity certification for kiosk deployments across the United States, while the EU AI Act imposes algorithmic transparency mandates on facial recognition and behavioral analytics modules. The European Accessibility Act further shapes hardware design by requiring screen-reader compatibility and tactile interface standards. Stakeholders must weigh regulatory divergence between jurisdictions when selecting sensor architectures and data-processing locations.
Market Dynamics
Municipal procurement departments are consolidating vendor pools around full-service contracts that bundle hardware, software, and maintenance, compressing margins for component-only suppliers and rewarding vertically integrated kiosk manufacturers with captive fabrication capabilities.
Growth Catalysts
- Transit authority modernization mandates:Urban transportation agencies in Germany, Japan, and the United Arab Emirates are replacing legacy ticketing infrastructure with contactless-enabled kiosks to reduce cash handling costs and accelerate passenger throughput.
- EU AI Act compliance deadlines:Algorithmic transparency requirements for facial recognition modules are accelerating replacement cycles as cities retire non-compliant units ahead of enforcement phases.
- Solar photovoltaic integration:Declining panel costs and improved battery density are enabling off-grid deployments in parks, waterfronts, and remote transit stops previously unreachable by electrical infrastructure.
Market Restraints
- Semiconductor supply concentration:Edge-computing chipsets for AI workloads depend on concentrated foundry capacity in East Asia, creating lead time volatility for kiosk manufacturers without buffer inventory.
- GDPR data localization costs:The European Union's data residency requirements force operators to deploy regional cloud infrastructure or on-premise processing, adding capex per deployment.
- Smartphone substitution:Transit apps with integrated ticketing are reducing passenger reliance on physical kiosks for basic transactions, pressuring unit economics in high-mobile-penetration cities.
Strategic Opportunities
- Carbon-neutral infrastructure mandates:The EU Green Deal's public procurement rules favor solar-powered kiosks with embodied carbon disclosures, creating preference premiums for manufacturers with lifecycle certification.
- Wayfinding in aging urban centers:Historic districts in Italy, Spain, and Portugal lack underground fiber and electrical capacity, creating demand for cellular-connected, battery-backed units with minimal civil works.
- Convergence of environmental sensing and digital signage:Kiosks combining air quality monitoring, noise detection, and real-time transit data are capturing expanded municipal budgets previously siloed across departments.
Industry Challenges
- Multi-jurisdiction certification timelines:Manufacturers face sequential FCC, CE marking, and national telecom approvals for wireless modules, stretching product launch schedules by 8-14 months.
- Legacy transit system integration:Proprietary protocols from incumbent fare collection vendors block seamless API connections, requiring expensive middleware development for each municipal deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart City Kiosk Market |
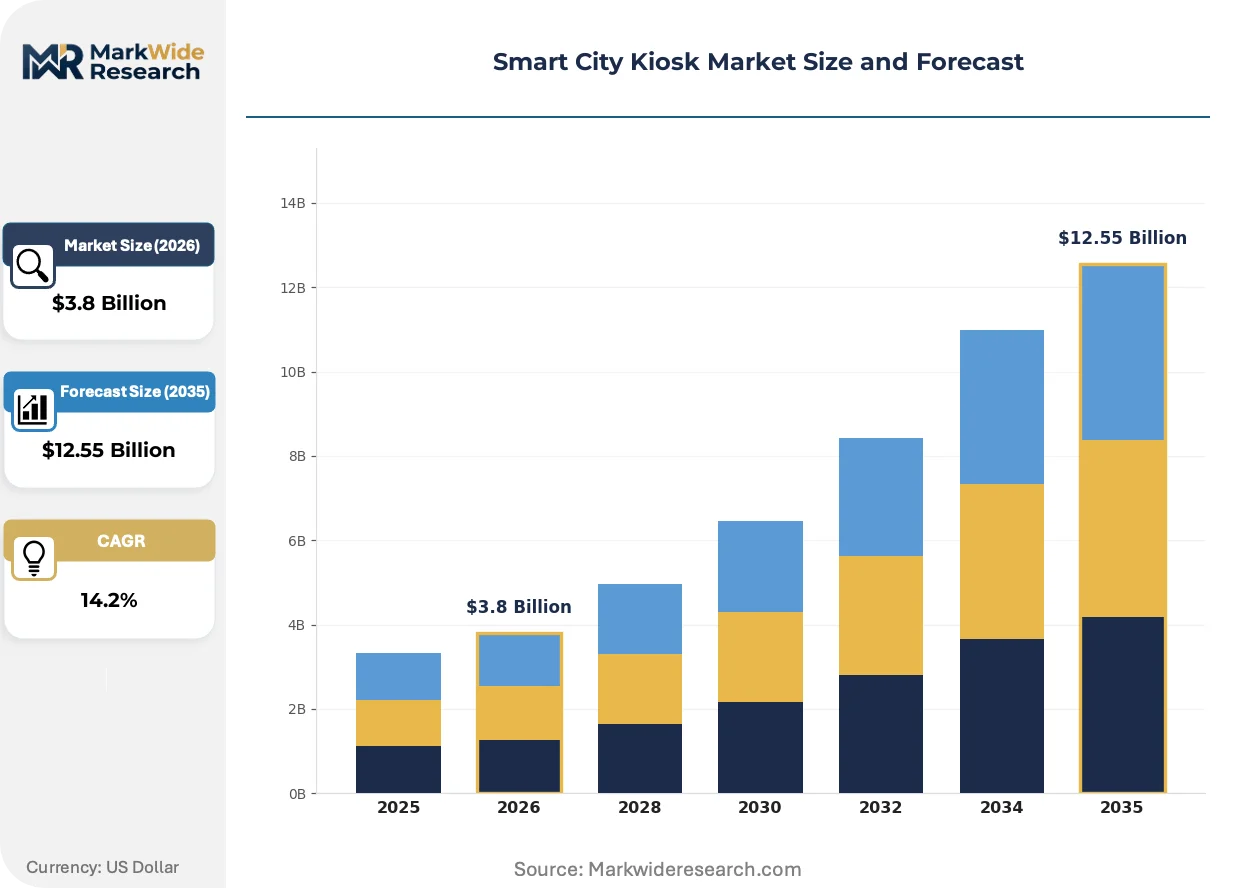
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
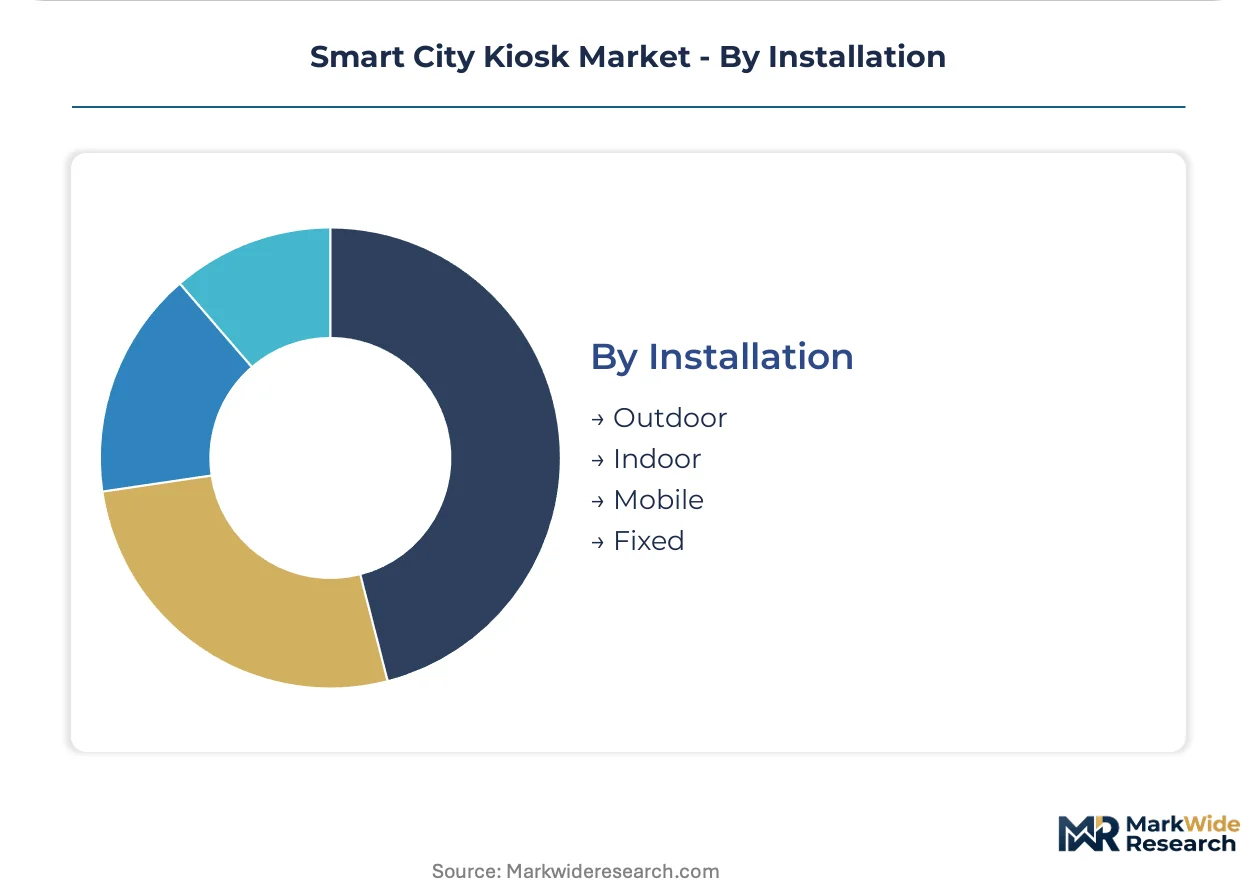
| Segmentation | Product Type: Information Kiosks, Interactive Kiosks, Payment Kiosks, Directory Kiosks Technology: Touchscreen, RFID, IoT Connectivity, Solar Powered End User: Municipalities, Transportation Centers, Tourist Attractions, Universities Installation: Outdoor, Indoor, Mobile, Fixed |
| Companies Covered | CIVIQ Smartscapes LLC, Smart City Media, Soofa Inc., OLEA Kiosks Inc., Verizon Communications Inc., Intel Corporation, Ferrograph Ltd., smartLINK, Peerless A.V., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart City Kiosk Market Evolving Landscape
Hardware architectures are fragmenting between premium edge-AI configurations and stripped-down cloud-dependent units, while regulatory pressure on data processing locations is forcing redesigns of sensor-to-cloud pathways.
Computer vision modules for crowd analytics and passenger counting are bifurcating the installed base. Transit agencies with high passenger volumes are deploying GPU-accelerated edge units for real-time processing, while smaller municipalities adopt lightweight camera-to-cloud architectures that offload computation. This split is compressing margins on mid-range configurations that lack differentiation against either extreme.
REACH restrictions on persistent organic pollutants are reshaping enclosure material specifications across European deployments. Manufacturers are substituting halogen-free flame retardants and recycled aluminum alloys for conventional ABS housings, adding 12-18% to bill-of-materials costs. German and French procurement offices are now embedding these material standards into technical specifications, effectively screening out Asian suppliers without EU-based fabrication.
Service contracting is unbundling from hardware purchase in North American municipal procurement. Chicago, Los Angeles, and Toronto transit authorities are separating 10-year maintenance agreements from initial capital outlays, forcing manufacturers to price recurring revenue streams independently and compete against third-party field service specialists. This shift favors vendors with established technician networks over pure-play hardware exporters.
Smart City Kiosk Market Segmentation
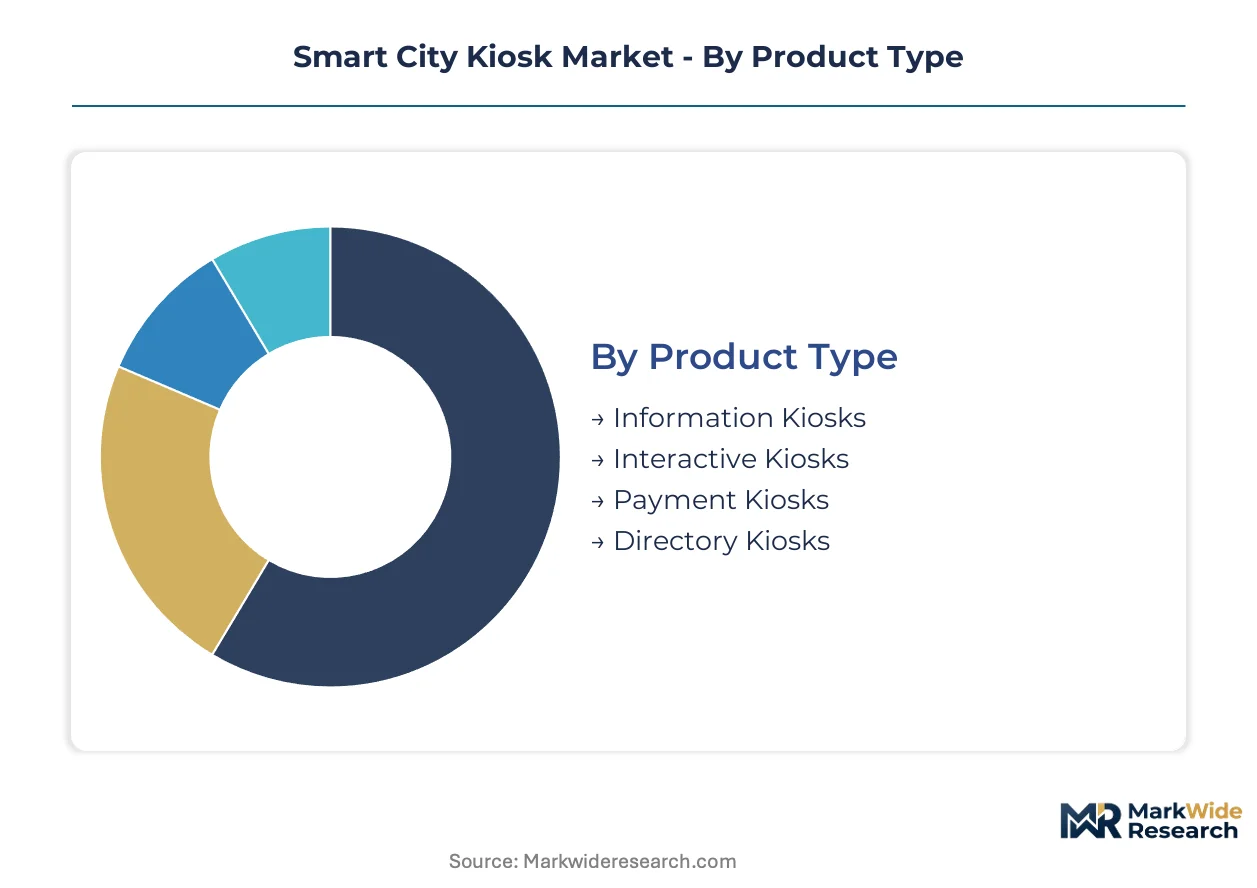
Smart city kiosk procurement channels vary sharply by segment, with transit authorities favoring bundled payment-enabled units while parks departments source solar configurations through sustainability offices. Understanding these channel dynamics helps vendors align sales coverage and service models to buyer decision-making structures.
Product Type:
Payment kiosks and interactive units dominate municipal RFPs, while information and directory configurations flow through separate procurement channels with distinct margin profiles.
- Interactive Kiosks:These units integrate touchscreen interfaces, wayfinding software, and multi-language support within weather-hardened enclosures. Demand concentrates in German and Japanese transit hubs where passenger throughput requirements drive specifications for 55-inch to 75-inch display formats and real-time transit API integration.
- Payment Kiosks:PCI-DSS compliant terminals with contactless readers and encrypted PIN pads process transit ticketing and civic service transactions. UAE transportation authorities are consolidating vendor pools around these units to reduce cash handling costs and accelerate passenger flow through metro and bus terminals.
- Information Kiosks:Static or lightly interactive displays for public service announcements and emergency alerts.
- Directory Kiosks:Wayfinding-focused units mapping building interiors or district layouts, common in Japanese commercial districts and UAE mall complexes.
By volume, interactive kiosks lead. By growth pace, payment kiosks are ahead.
Technology:
Cost tiers separate premium edge-AI configurations from stripped-down cloud-dependent architectures, with solar-powered units commanding sustainability premiums in EU public procurement.
- Solar Powered:Photovoltaic panels paired with lithium battery storage enable off-grid deployment in parks, waterfronts, and remote transit stops. The EU Green Deal's procurement rules favor these configurations with embodied carbon disclosures, creating preference premiums for manufacturers with lifecycle certification.
- Touchscreen:Capacitive and infrared touch layers ranging from 32-inch to 75-inch formats serve as the baseline interface standard across all product types.
- IoT Connectivity:Cellular and mesh networking modules transmit sensor data and enable remote management, critical for historic Italian and Portuguese districts lacking underground fiber infrastructure.
- RFID:Near-field communication readers support transit card validation and access control integration.
Touchscreen technology anchors installed base volumes. Solar-powered configurations are expanding most quickly as carbon-neutral mandates harden.
End User:
Application requirements drive specification divergence, with transportation centers demanding 24/7 uptime guarantees while universities prioritize flexible content management platforms.
- Transportation Centers:Metro, rail, and bus terminals in Germany, Japan, and the UAE require payment integration, real-time arrival data, and passenger counting analytics. These deployments face the strictest uptime SLA requirements and shortest replacement cycles driven by EU AI Act compliance deadlines.
- Municipalities:City governments deploy mixed-use kiosks combining transit ticketing, wayfinding, and environmental sensing across downtown cores and public squares.
- Tourist Attractions:Museums, monuments, and cultural sites in Italy, Spain, and Portugal favor battery-backed cellular units to minimize civil works in protected historic zones.
- Universities:Campus deployments emphasize flexible digital signage and event promotion over payment functionality, with shorter procurement cycles and lower technical barriers.
Transportation centers generate the highest revenue per unit. Municipalities are scaling fastest as bundled service contracts consolidate vendor relationships.
Installation:
Geography and infrastructure availability determine installation type selection, with outdoor and mobile units requiring IP65 enclosures and cellular backhaul in underserved locations.
- Outdoor:IP65-rated enclosures withstand temperature extremes, moisture, and particulate exposure in streetscapes and transit platforms. REACH restrictions on persistent organic pollutants are reshaping material specifications across European deployments, with German and French procurement offices embedding halogen-free flame retardant standards.
- Fixed:Permanently anchored installations with hardwired power and fiber connectivity dominate high-traffic transportation centers.
- Indoor:Climate-controlled environments in transit terminals, malls, and civic buildings allow lighter enclosure specifications.
- Mobile:Trailer-mounted or relocatable units serve temporary events, construction zones, and emergency response scenarios.
Fixed outdoor installations hold the largest installed base. Mobile configurations are climbing the fastest as event-driven and emergency-use cases multiply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across procurement environments, with municipal transit authorities in Germany and Japan demanding premium specifications while UAE agencies prioritize rapid deployment over customization. Cost-conscious municipalities in Southern Europe favor solar-powered configurations that minimize civil infrastructure spending.
Germany
Federal transit modernization programs and stringent EU AI Act compliance deadlines drive replacement of legacy ticketing infrastructure. The Bundesamt für Sicherheit in der Informationstechnik shapes cybersecurity certification requirements for payment modules. Procurement concentrates in Bavaria and North Rhine-Westphalia, where Munich and Cologne transit authorities bundle 10-year service contracts with hardware purchases.
United Arab Emirates
Metro and bus terminal expansions in Dubai and Abu Dhabi prioritize contactless passenger throughput over deep customization. The Telecommunications and Digital Government Regulatory Authority governs wireless connectivity certification for outdoor deployments. Dubai's Roads and Transport Authority leads regional consolidation, standardizing kiosk specifications across emirate-level contracts to accelerate rollout timelines.
Japan
JR East and Tokyo Metro replacement cycles favor 55-inch to 75-inch interactive formats with real-time transit API integration. The Ministry of Economy, Trade and Industry promotes edge-AI chipsets through industrial technology grants. Osaka and Nagoya clusters concentrate manufacturing partnerships, with Kansai-based fabricators supplying enclosure assemblies for domestic transit authorities.
Italy
Historic district constraints in Rome, Florence, and Venice drive demand for cellular-connected, battery-backed units requiring minimal excavation. The Garante per la Protezione dei Dati Personali enforces GDPR data localization for facial recognition modules. Procurement flows through regional sustainability offices in Tuscany and Lazio, prioritizing solar configurations with embodied carbon disclosures under EU Green Deal procurement rules.
United States
Chicago, Los Angeles, and Toronto transit authorities separate maintenance agreements from capital purchases, compressing hardware margins. The Federal Communications Commission certifies wireless emissions for streetscape deployments. Municipal procurement in California and Texas increasingly favors full-service contracts that bundle software, hardware, and field service networks.
Smart City Kiosk Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the smart city kiosk landscape. Vertically integrated manufacturers with captive enclosure fabrication capture premium municipal contracts, while component specialists compete on price for standardized transit deployments. Three archetypes dominate: full-service integrators bundling hardware and decade-long maintenance, semiconductor suppliers anchoring the edge-AI layer, and solar-power specialists targeting carbon-neutral procurement mandates. Competitive moves concentrate on strategic partnerships for transit system integration and geographic expansion through regional fabrication licensing.
Among US-based technology providers, CIVIQ Smartscapes LLC and Soofa Inc. occupy distinct positioning archetypes, with the former representing vertical integration into enclosure and display manufacturing and the latter exemplifying solar-powered deployment specialization. Intel Corporation anchors the semiconductor tier as a supplier of edge-computing chipsets rather than a kiosk systems competitor. Verizon Communications Inc. sits within the connectivity infrastructure layer, leveraging cellular network assets for deployments in fiber-constrained locations.
| Leading Market Players |
|---|
| CIVIQ Smartscapes LLC |
| Smart City Media |
| Soofa Inc. |
| OLEA Kiosks Inc. |
| Verizon Communications Inc. |
| Intel Corporation |
| Ferrograph Ltd. |
| smartLINK |
| Peerless A.V. |
| Others |
Value Network & Pricing Analysis
Twenty-four-week lead times for edge-computing chipsets from East Asian foundries concentrate pricing power among kiosk manufacturers with buffer inventory, while procurement officers in Germany and Japan leverage long-term service bundling to compress hardware margins. This dynamic rewards backward integration into enclosure fabrication and penalizes component-only suppliers lacking captive supply chains.
Pricing Analysis
Decade-long maintenance agreements now drive lifetime value more than initial hardware sales, with Chicago and Toronto transit authorities separating these contracts from capital purchases. Three-tier pricing structure across premium edge-AI, standard cloud-dependent, and economy stripped-down configurations stratifies by processing capability and certification grade. Cost compression in mid-range units is intensifying because GPU-accelerated edge configurations and lightweight camera-to-cloud architectures squeeze undifferentiated alternatives. Municipalities in Southern Europe exhibit highest price sensitivity due to constrained infrastructure budgets, while German transit authorities accept premium pricing for BSI-certified cybersecurity modules.
Supply Chain Analysis
Container availability on Asia-Europe trade lanes shapes inbound logistics costs for lithium battery cells and photovoltaic panels destined for solar-powered kiosk assembly. Semiconductor fabrication concentrates in Taiwan and South Korea, while aluminum alloy enclosure stamping localizes in Germany and China. Bill-of-materials exposure rests on halogen-free flame retardants subject to REACH restrictions and recycled aluminum alloys. Single-source vulnerability in edge-AI chipsets creates lead time volatility for manufacturers without strategic inventory positions. Distribution runs through municipal procurement departments consolidating vendor pools around full-service contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach revenue layers are expanding faster than hardware sales as North American transit authorities unbundle maintenance agreements from capital purchases, transforming vendor economics toward recurring income streams.
For Market Incumbents: Shield market position by deepening backward integration into enclosure fabrication to capture EU Green Deal procurement premiums for embodied carbon disclosures, and accelerate certification investment for EU AI Act compliance ahead of enforcement phases. Smartphone substitution threats from transit apps pressure unit economics in high-mobile-penetration cities, making captive technician networks the critical defensive lever against third-party field service specialists. For New Entrants and Emerging Players: Differentiate on solar-powered deployment specialization to access carbon-neutral infrastructure mandates in Italy, Spain, and Portugal where historic district constraints block conventional electrical infrastructure. White-space concentration sits in cellular-connected, battery-backed units for fiber-constrained locations, with sustainability offices in Tuscany and Lazio offering the most penetrable procurement channel. Go-to-market execution should target regional sustainability certification partnerships rather than competing head-to-head for bundled transit contracts. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because municipal procurement consolidation around full-service contracts generates decade-long maintenance income streams with high renewal rates. Acquisition targets should display established field service networks and lifecycle certification capabilities under EU Green Deal frameworks. The signal to watch is enforcement timeline clarity for EU AI Act algorithmic transparency mandates, which will trigger replacement cycles for non-compliant facial recognition modules.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Enclosure Fabrication | Captures EU Green Deal preference premiums for embodied carbon disclosures in German and French procurement. |
| Certification Investment for EU AI Act Compliance | Accelerates replacement cycle capture as cities retire non-compliant facial recognition modules ahead of deadlines. |
| Field Service Network Expansion | Secures recurring revenue separation from hardware sales in Chicago, Los Angeles, and Toronto transit authorities. |
| Solar Photovoltaic Supply Agreement | Locks in lithium battery and panel sourcing for off-grid deployments in Italian and Portuguese historic districts. |
| Transit System Integration Partnership | Overcomes proprietary protocol barriers from incumbent fare collection vendors through middleware co-development. |
Research Methodology
A spread of perspectives from municipal procurement officers, transit authority technology directors, kiosk manufacturer product managers, and semiconductor supply chain specialists converged on the working assumptions underlying this analysis. Primary fieldwork combined structured interviews with secondary validation against FCC certification databases, EU procurement portal records, and customs trade data for aluminum alloy and photovoltaic panel flows. Bottom-up unit deployment tracking across German, Japanese, and UAE transit authorities triangulated against top-down market sizing from enclosure fabrication capacity and edge-computing chipset shipment data.
Segmentation dimensions modeled include product type, technology configuration, end-user application, and installation environment across the projection horizon. CAGRs derived from weighted least-squares fitting to historical deployment trajectories, adjusted for regulatory inflection points including EU AI Act compliance deadlines and EU Green Deal procurement rule implementations. Forecast inputs incorporated foundry capacity utilization rates for AI-optimized chipsets and municipal budget allocation patterns for carbon-neutral infrastructure.
Material uncertainties — semiconductor supply disruption, GDPR data localization enforcement intensity, smartphone substitution acceleration — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding transit authority modernization timelines and solar photovoltaic cost curves. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
Smart City Framework Market
Smart City Technology
Smart City Platform Market
Smart City Technology
Smart Parking Meters Market
Smart City Technology
City Data Platform Market
Smart City Technology
Smart Mailbox Market
Smart City Technology
UAE Smart Furniture Market
Smart City Technology
Outdoor LED Smart Lighting Solution Market
Smart City Technology
Smart Communities Market
Smart City Technology
India Smart City Market
Smart City Technology
Smart Parcel Locker Market
Smart City Technology
Global Smart/Connected Street Lights Market
Smart City Technology
Smart Package Lockers Market
Smart City Technology
Smart Ticketing Solutions Market
Smart City Technology
Smart Shade Device Market
Smart City Technology
Global Smart City ICT Infrastructure Market
Smart City Technology
E-Governance Market