
 India Smart City Market | 2026-2036
India Smart City Market Size, Share, and Industry Trends Forecast 2026-2036
India Smart City Market Foresight
A capital-intensity divergence between systems integrators and hardware specialists is bifurcating competitive dynamics across the India Smart City Market. TCS sustains dominance in command center deployments through its institutional relationships with state urban development departments. Cisco Systems anchors network infrastructure layers across multiple smart city projects, leveraging its edge-to-core connectivity portfolio. Siemens competes on energy management systems, specializing in grid automation for municipal power utilities.
Smart city infrastructure encompasses integrated urban systems that combine IoT sensors, cloud computing platforms, and AI analytics to optimize municipal service delivery, typically operating through centralized data fabrics that process real-time inputs from traffic, energy, and environmental monitoring endpoints. Smart lighting and traffic management systems represent mature deployment categories with established procurement frameworks, while AI analytics and environmental monitoring applications capture expanding budget allocations as cities prioritize predictive governance models. Cloud computing infrastructure underpins scaling architectures, though edge computing investments are gaining traction among private developers seeking reduced latency for public safety applications.
The Ministry of Housing and Urban Affairs Smart Cities Mission establishes project sanctioning protocols, while BIS standards govern interoperability specifications for IoT devices deployed across municipal networks. State-level urban development authorities layer additional compliance requirements onto environmental monitoring and waste management implementations. Stakeholders must track evolving data localization mandates and procurement preference shifts toward domestic technology providers as policy frameworks mature.
Market Dynamics
Municipal corporations in Surat and Pune are driving adoption of integrated command centers, creating a bifurcation between systems integrators and hardware specialists as procurement frameworks mature under the Smart Cities Mission.
Growth Catalysts
- Smart Cities Mission mandate:The Ministry of Housing and Urban Affairs mandates area-based development, channeling central funding toward transport management and energy efficiency applications in tier-two cities.
- IoT sensor deployment:Real-time traffic, energy, and environmental monitoring endpoints are expanding municipal data fabrics, enabling predictive governance models across urban infrastructure.
- Tier-two city concentration:Demand concentrates in cities like Indore, Bhopal, and Coimbatore as state urban development authorities prioritize integrated urban systems outside metro hubs.
Market Restraints
- Capital intensity for hardware:Edge computing investments for public safety applications require substantial upfront expenditure, limiting private developer participation.
- Data localization compliance:Evolving mandates from the Ministry of Electronics and Information Technology create procurement friction for cloud-dependent architectures.
- Interoperability gaps:BIS standards for IoT devices remain partially implemented, fragmenting device ecosystems across municipal networks.
Strategic Opportunities
- Environmental monitoring expansion:AI analytics for air quality and waste management capture expanding budget allocations as cities prioritize predictive capabilities.
- Domestic technology preference:Procurement shifts toward Indian technology providers under the PLI scheme create openings for local systems integrators.
- Edge-to-core convergence:Integration of edge computing with centralized cloud platforms enables reduced-latency public safety applications for private developers.
Industry Challenges
- Integration complexity with legacy municipal systems:Command centers must interface with decades-old traffic signal and power grid infrastructure, extending deployment timelines.
- Skill scarcity in AI analytics:Municipal corporations lack personnel trained in machine learning model deployment for real-time urban data processing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Smart City Market |
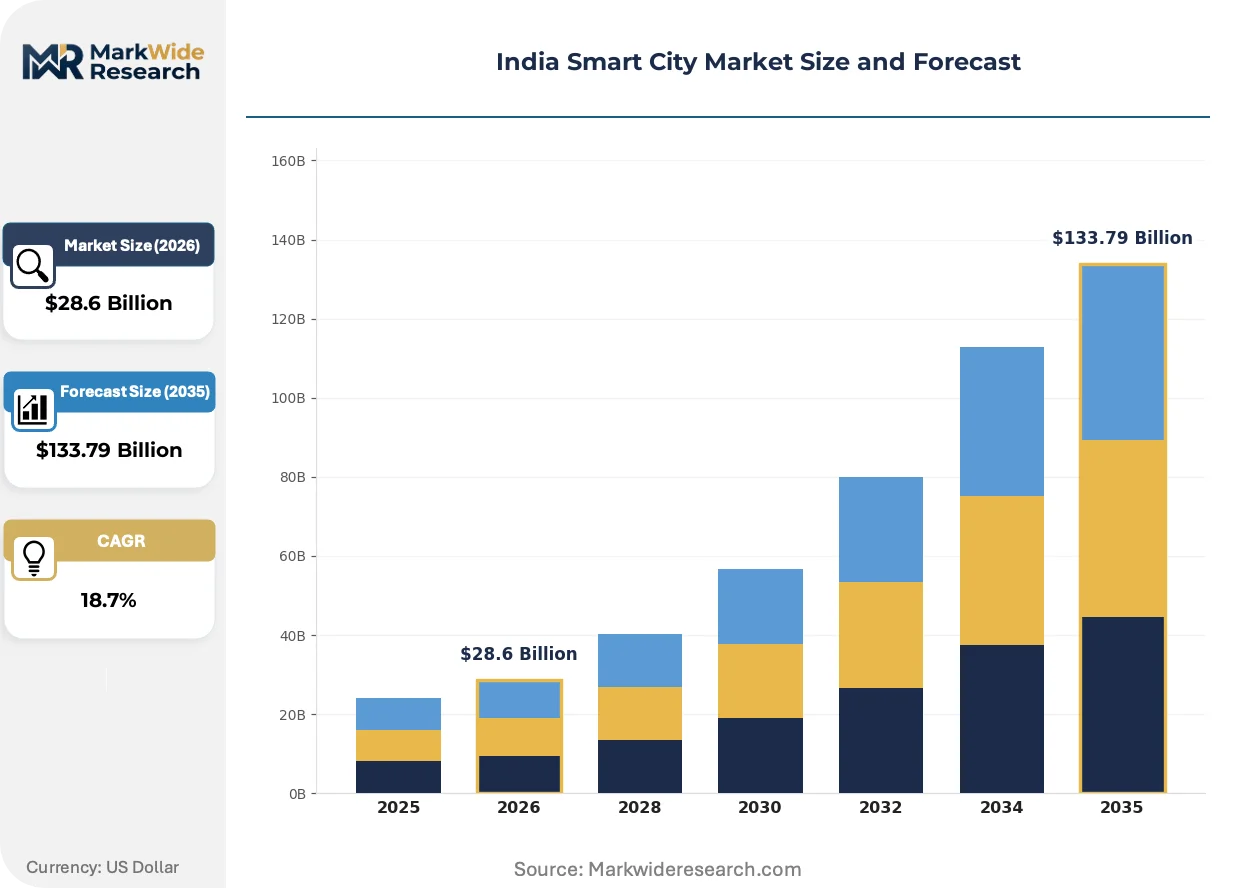
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $133.79 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smart Lighting, Waste Management Solutions, Smart Grid, Traffic Management Systems Technology: IoT, Cloud Computing, AI Analytics, Big Data End User: Municipal Corporations, Private Developers, Government Agencies, Citizens Application: Public Safety, Transport Management, Energy Efficiency, Environmental Monitoring |
| Companies Covered | NEC Corporation, TCS (Tata Consultancy Services), Cisco Systems, Wipro, Infosys, Microsoft, Hitachi, Quantela, Siemens, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Smart City Market Shifts & Advancements
Edge computing architectures are gaining traction among private developers, while regulatory pressure on data localization and domestic procurement is reshaping technology sourcing patterns across municipal projects.
AI-driven predictive analytics is supplanting rule-based traffic management systems in command center deployments. Municipal corporations in Surat and Pune are adopting machine learning models for congestion forecasting at accelerated procurement cycles. This shift is compressing vendor selection criteria toward demonstrated algorithmic performance rather than hardware specifications.
BIS interoperability standards for IoT devices are tightening compliance timelines for municipal network deployments. The Ministry of Housing and Urban Affairs is layering additional certification requirements onto environmental monitoring implementations. Smart lighting and waste management vendors are restructuring product roadmaps to accommodate staggered compliance deadlines across state-level urban development authorities.
Outcome-based service contracts are displacing capital expenditure models for smart lighting and traffic management systems. Municipal corporations in tier-two cities are contracting integrated operations and maintenance agreements spanning 10-15 year horizons. This pattern is most visible in Karnataka and Tamil Nadu, where state urban development authorities have issued template concession frameworks.
India Smart City Market Segmentation
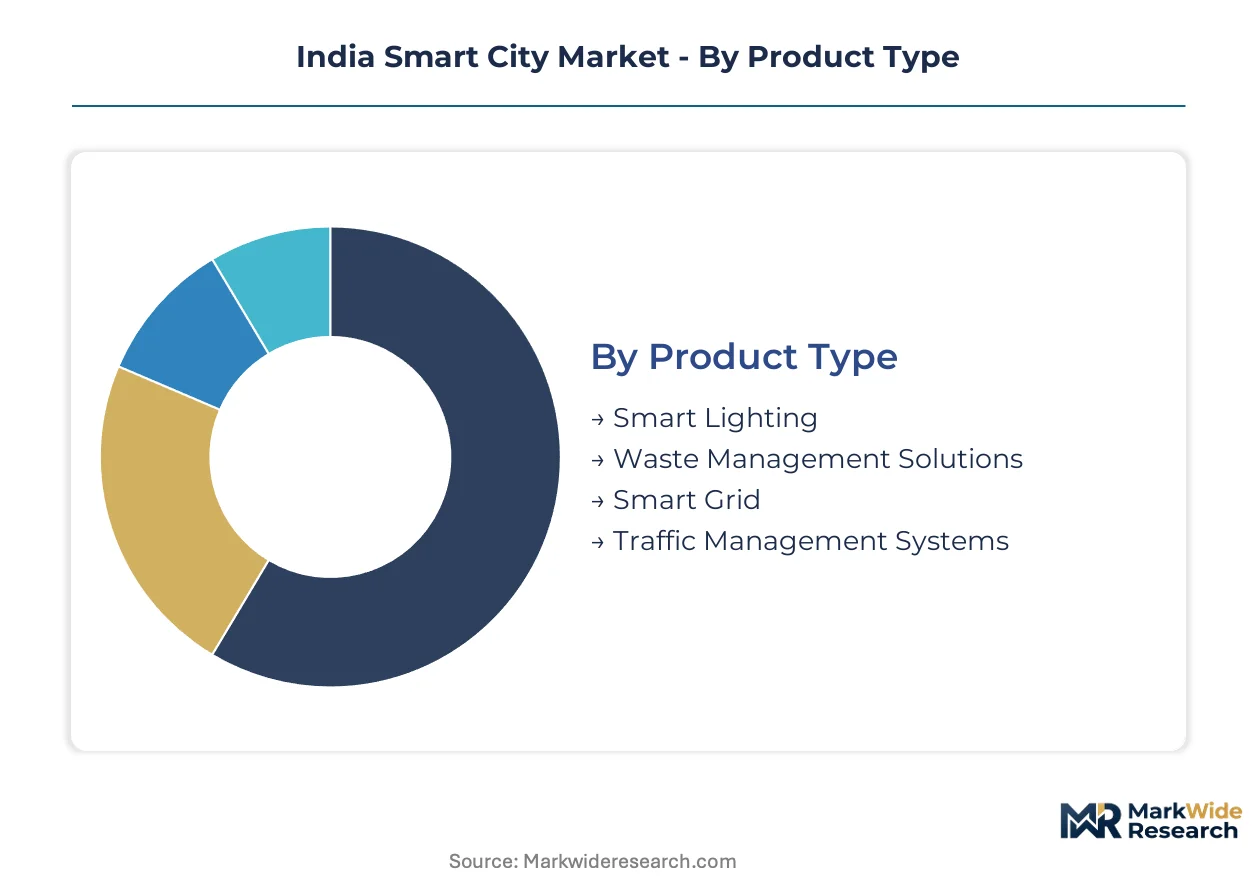
Smart city procurement in India fragments across four intersecting dimensions, with technology choices and end-user governance models determining deployment architectures. BIS certification requirements and Smart Cities Mission funding protocols create divergent compliance burdens across each category, reshaping vendor qualification criteria.
Product Type:
BIS interoperability standards impose tiered certification timelines, with environmental monitoring hardware facing accelerated compliance deadlines under Ministry of Housing and Urban Affairs directives.
- Smart Lighting:LED-based street illumination with embedded IoT controllers enables remote dimming and fault detection. Municipal corporations in Karnataka and Tamil Nadu favor 10-15 year operations contracts, displacing capital expenditure models.
- Traffic Management Systems:AI-driven signal optimization and congestion forecasting platforms process real-time vehicle flow data. Surat and Pune command centers prioritize machine learning procurement over hardware specifications.
- Smart Grid:Grid automation systems for municipal power utilities integrate distributed energy resources.
- Waste Management Solutions:Sensor-equipped collection logistics and route optimization platforms.
Established volume favors Smart Lighting; emerging adoption favors Traffic Management Systems.
Technology:
Data localization mandates from the Ministry of Electronics and Information Technology stratify cloud architecture choices, with edge deployments gaining traction for latency-sensitive public safety applications.
- IoT:Sensor networks for traffic, energy, and environmental endpoints form the foundational data layer. Tier-two cities concentrate deployment in Indore, Bhopal, and Coimbatore as state urban development authorities expand municipal data fabrics.
- AI Analytics:Predictive models for congestion forecasting and air quality monitoring capture expanding budget allocations. Skill scarcity in machine learning deployment constrains municipal adoption timelines.
- Cloud Computing:Centralized platforms underpin scaling architectures across command centers.
- Big Data:Aggregation frameworks for multi-source urban data processing and historical trend analysis.
Cloud Computing anchors current procurement; AI Analytics is climbing the fastest as predictive governance models mature.
End User:
Procurement authority fragmentation across central, state, and municipal tiers creates divergent vendor engagement protocols, with private developers facing higher capital intensity thresholds.
- Municipal Corporations:Primary procurement agents under Smart Cities Mission area-based development mandates. Surat and Pune drive integrated command center adoption through institutional relationships with systems integrators.
- Private Developers:Edge computing investors seeking reduced-latency architectures for public safety applications face substantial upfront expenditure requirements.
- Government Agencies:State urban development authorities layer compliance requirements onto environmental monitoring implementations.
- Citizens:End beneficiaries of service delivery optimization, with limited direct procurement involvement.
Municipal Corporations dominate current deployment; Private Developers represent the steepest expansion trajectory as concession frameworks mature.
Application:
Smart Cities Mission funding channels concentrate on transport and energy verticals, while environmental monitoring captures incremental allocations under tightening BIS certification timelines.
- Transport Management:Real-time traffic optimization and multimodal transit integration systems. Tier-two city demand concentrates procurement volume outside metro hubs.
- Energy Efficiency:Grid automation and demand-response platforms for municipal power utilities. Siemens competes through specialized relationships with state electricity boards.
- Public Safety:Video analytics and emergency response coordination systems.
- Environmental Monitoring:Air quality sensors and waste tracking platforms face staggered compliance deadlines across state-level urban development authorities.
Transport Management commands established budgets; Environmental Monitoring is gaining share fastest under predictive governance prioritization.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity varies sharply across Indian states, with Gujarat and Maharashtra showing lowest price sensitivity for integrated command centers while eastern states prioritize cost-optimized single-point solutions under tighter fiscal constraints.
Maharashtra
Mumbai and Pune municipal corporations drive premium-tier procurement for AI-enabled traffic management and integrated operations centers. The state urban development department layers Smart Cities Mission compliance requirements onto environmental monitoring implementations. Thane and Nagpur are expanding smart grid pilots through Maharashtra State Electricity Distribution Company partnerships.
Gujarat
Surat Municipal Corporation anchors western India's most advanced command center deployment with real-time waste tracking and congestion forecasting systems. Gujarat's state-level urban development authority fast-tracks BIS certification for IoT vendors under its digital infrastructure roadmap. Ahmedabad and Vadodara are replicating Surat's integrated operations framework with 10-15 year concession contracts.
Karnataka
Bengaluru's municipal corporation faces acute pressure to expand beyond its IT corridor into peripheral wards with smart lighting and air quality monitoring networks. The Karnataka state government has issued template concession frameworks for outcome-based service contracts. Mysuru and Hubballi-Dharwad concentrate tier-two city demand outside the capital metro.
Tamil Nadu
Chennai Corporation prioritizes flood-resilient environmental monitoring and stormwater sensor networks following cyclone vulnerability assessments. Tamil Nadu's urban development authority mandates domestic technology provider preferences under revised procurement guidelines. Coimbatore and Madurai are emerging as tier-two deployment hubs for transport management systems.
Telangana
Hyderabad's municipal corporation leverages its technology sector density to pilot edge computing architectures for public safety video analytics. The state electronics and IT department enforces data localization requirements for cloud-dependent smart city platforms. Warangal and Karimnagar represent expanding tier-two markets under the Smart Cities Mission area-based development mandate.
India Smart City Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with full-stack systems integrators commanding premium positioning against hardware-focused component suppliers. The upper tier captures multi-year command center contracts through institutional relationships with state urban development departments. Below them, network infrastructure specialists and energy management vendors compete on technical specifications and BIS compliance timelines. Dominant competitive moves include strategic partnerships between global technology providers and domestic systems integrators, plus portfolio diversification into adjacent municipal software verticals.
Within the integrated systems tier, TCS and Wipro exemplify full-service positioning through their established urban development department relationships. Cisco Systems anchors network infrastructure supply across multiple state-level deployments. Siemens occupies a specialized position in grid automation and energy management systems for municipal power utilities.
| Leading Market Players |
|---|
| NEC Corporation |
| TCS (Tata Consultancy Services) |
| Cisco Systems |
| Wipro |
| Infosys |
| Microsoft |
| Hitachi |
| Quantela |
| Siemens |
| Others |
Supply & Pricing Matrix
Ninety-day component lead times for edge computing hardware compress procurement windows for municipal systems integrators, concentrating pricing power with domestic IoT vendors holding BIS-certified inventory buffers while tier-two city corporations absorb freight premiums from fragmented supplier networks.
Pricing Analysis
Extended service and operations contracts spanning 10-15 years drive lifetime value capture for integrated command center deployments. Three-tier pricing structure across premium, standard, and economy levels separates TCS-led full-stack implementations from hardware-only suppliers and white-label component vendors. Cost compression in sensor hardware intensifies as Chinese and Taiwanese manufacturers expand direct municipal sales channels. Private developers show highest price sensitivity due to upfront edge computing capital requirements, while Gujarat and Maharashtra municipal corporations absorb premium tiers for demonstrated algorithmic performance.
Supply Chain Analysis
Semiconductor fabrication chokepoints in Taiwan and South Korea constrain IoT controller availability for smart lighting and traffic signal deployments. Component sourcing draws from China for LED assemblies, Germany for industrial automation controllers, and domestic Indian foundries for BIS-certified edge devices. Single-source vulnerability concentrates in advanced AI chipsets for command center analytics. Distribution runs through state urban development authority tender processes with Siemens, Cisco, and TCS maintaining approved vendor status across multiple jurisdictions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The India Smart City Market rewards vendors possessing scarce machine learning deployment capabilities alongside institutional relationships with state urban development departments, creating acquisition premiums for full-stack systems integrators over hardware specialists.
For Market Incumbents: Compound institutional positioning through deeper integration with Maharashtra and Gujarat state electricity boards, defending against emerging domestic challengers leveraging PLI scheme procurement preferences. Prioritize captive AI analytics talent pipelines to offset municipal skill scarcity constraining project timelines. For New Entrants and Emerging Players: Lead with environmental monitoring specialization targeting Karnataka and Tamil Nadu tier-two cities where BIS compliance deadlines create vendor qualification gaps. Establish partnership routes with Quantela or Hitachi for command center integration credibility rather than direct municipal bidding. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across edge computing infrastructure sub-segments as latency requirements harden for public safety applications. Target acquisition profiles favor domestic systems integrators with demonstrated Smart Cities Mission project completion records. Monitor PLI scheme domestic content threshold adjustments as inflection signals for foreign technology provider displacement.| Strategic Initiative | Industry Significance |
|---|---|
| AI Analytics Talent Acquisition | Machine learning deployment expertise unlocks premium command center contracts in Surat and Pune. |
| BIS Certification Pre-Investment | Early compliance with Ministry of Housing and Urban Affairs timelines secures environmental monitoring procurement eligibility. |
| State Electricity Board Partnership | Siemens demonstrates grid automation positioning through Maharashtra State Electricity Distribution Company relationships. |
| Outcome-Based Contract Structuring | Karnataka and Tamil Nadu template frameworks shift municipal procurement from capex to 10-15 year service agreements. |
| Edge-to-Cloud Architecture Integration | Cisco Systems anchors network infrastructure layers enabling reduced-latency public safety applications for private developers. |
Research Methodology
Desk research of Ministry of Housing and Urban Affairs project sanctioning records, BIS certification databases, and state urban development authority tender documents preceded structured interviews with municipal corporation CTOs, systems integration project managers, state electricity board planning officers, and IoT hardware procurement leads. Secondary validation drew from Smart Cities Mission progress reports, TRAI infrastructure disclosures, and PLI scheme administrative filings. Bottom-up project pipeline enumeration triangulated against top-down central funding allocation analysis.
Variance decomposition across the projection horizon isolates volume drivers by technology segment, end-user governance tier, and application vertical. Modeled dimensions span product type, technology layer, procurement authority, and use case with specific treatment of tier-two city expansion patterns. CAGRs derive from logistic adoption curve fitting against municipal budget allocation trajectories, with edge computing investment intensity and AI analytics penetration serving as primary forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained Smart Cities Mission central funding continuity or accelerated BIS compliance enforcement would require recalibration. Forecasts reflect documented assumptions regarding municipal procurement cycle durations and domestic technology preference trajectory. Practitioners should keep alternative scenarios live as data localization mandate implementation timelines and PLI scheme eligibility criteria evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
Smart Shade Device Market
Smart City Technology
UAE Smart Furniture Market
Smart City Technology
Smart Mailbox Market
Smart City Technology
Outdoor LED Smart Lighting Solution Market
Smart City Technology
Smart City Framework Market
Smart City Technology
Singapore ICT Market
Smart City Technology
Smart City Kiosk Deployment Market
Smart City Technology
US Smart Cities Market
Smart City Technology
Smart Ticketing Solutions Market
Smart City Technology
Global Smart/Connected Street Lights Market
Smart City Technology
Smart Space Market
Smart City Technology
Global Smart City Market
Smart City Technology
E-Governance Market
Smart City Technology
Global Smart Pole Market
Smart City Technology
Smart Street Lights Market
Smart City Technology
Smart City Platform Market