
 US Smart Cities Market | 2026-2036
US Smart Cities Market Size, Share, and Industry Trends Forecast 2026-2036
US Smart Cities Market Insights
The US smart cities sector is pivoting around a widening gap between premium integrated platforms and commodity point solutions. Cisco Systems leverages its networking heritage to dominate secure municipal backbone deployments. IBM anchors large-scale data analytics contracts with state-level agencies. Siemens competes through deep specialization in building automation and energy optimization systems.
Smart cities denote urban environments instrumented with networked sensors, edge computing nodes, and centralized analytics platforms that optimize resource allocation across transportation, energy, water, and public safety systems. IoT Solutions form the foundational connectivity layer, while Artificial Intelligence processes real-time telemetry to predict infrastructure failures before they cascade. Cloud Computing deployments now outpace on-premises installations among mid-sized municipalities seeking operational flexibility without capital intensity. Public Safety applications command premium pricing due to stringent reliability requirements and federal interoperability mandates.
The National Institute of Standards and Technology publishes cybersecurity frameworks that shape procurement specifications for critical infrastructure. The Federal Communications Commission governs spectrum allocation for connected vehicle and sensor networks, directly constraining deployment timelines. The Department of Transportation coordinates with the Cybersecurity and Infrastructure Security Agency to harmonize physical and digital resilience standards. Stakeholders must track evolving federal funding mechanics and state-level data sovereignty legislation to anticipate procurement rhythm shifts.
Market Dynamics
The Infrastructure Investment and Jobs Act is compressing procurement timelines for digitized urban corridors, forcing municipal agencies to accelerate vendor selection while federal funding windows remain open.
Growth Catalysts
- Federal Funding Windows:The Infrastructure Investment and Jobs Act channels capital toward connected infrastructure deployments, with state DOTs racing to obligate funds before authorization sunsets.
- Grid Modernization Convergence:Legacy electrical infrastructure in California, Texas, and New York metropolitan areas requires simultaneous sensor overlay and edge computing integration.
- C-V2X Spectrum Allocation:FCC rulings on 5.9 GHz band reconfiguration enable vehicle-to-infrastructure communication pilots that drive roadside unit procurement.
Market Restraints
- Municipal Bond Capacity Constraints:Rising interest rates compress debt-financed project scopes, forcing mid-sized cities to defer integrated platform deployments in favor of isolated point solutions.
- Semiconductor Supply Concentration:Edge computing hardware remains exposed to foundry capacity bottlenecks concentrated in East Asian manufacturing nodes.
- Interoperability Standards Fragmentation:Competing protocols between NIST cybersecurity frameworks and state-level data sovereignty statutes create procurement specification conflicts.
Strategic Opportunities
- Mid-Sized Municipalities:Cities between 100,000 and 500,000 residents remain undersupplied with integrated platforms, presenting white space for cloud-native deployments without legacy system baggage.
- Water-Wastewater Integration:Smart metering convergence with leak detection AI represents an emerging application vertical with distinct procurement channels from transportation-focused vendors.
- Inflation Reduction Act Incentives:Clean energy tax credits for municipal building retrofits accelerate demand for Siemens-style building automation and energy optimization systems.
Industry Challenges
- Cybersecurity Workforce Scarcity:CISA workforce development programs have not closed gaps in municipal IT security staffing, leaving agencies dependent on vendor-managed security services.
- Legacy SCADA Integration:Water and energy utilities face execution risk when overlaying IP-connected sensors atop decades-old industrial control systems with proprietary communication stacks.
- Interagency Coordination Friction:Department of Transportation timelines for connected vehicle corridors frequently misalign with FCC spectrum deployment schedules and state-level data governance reviews.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Smart Cities Market |
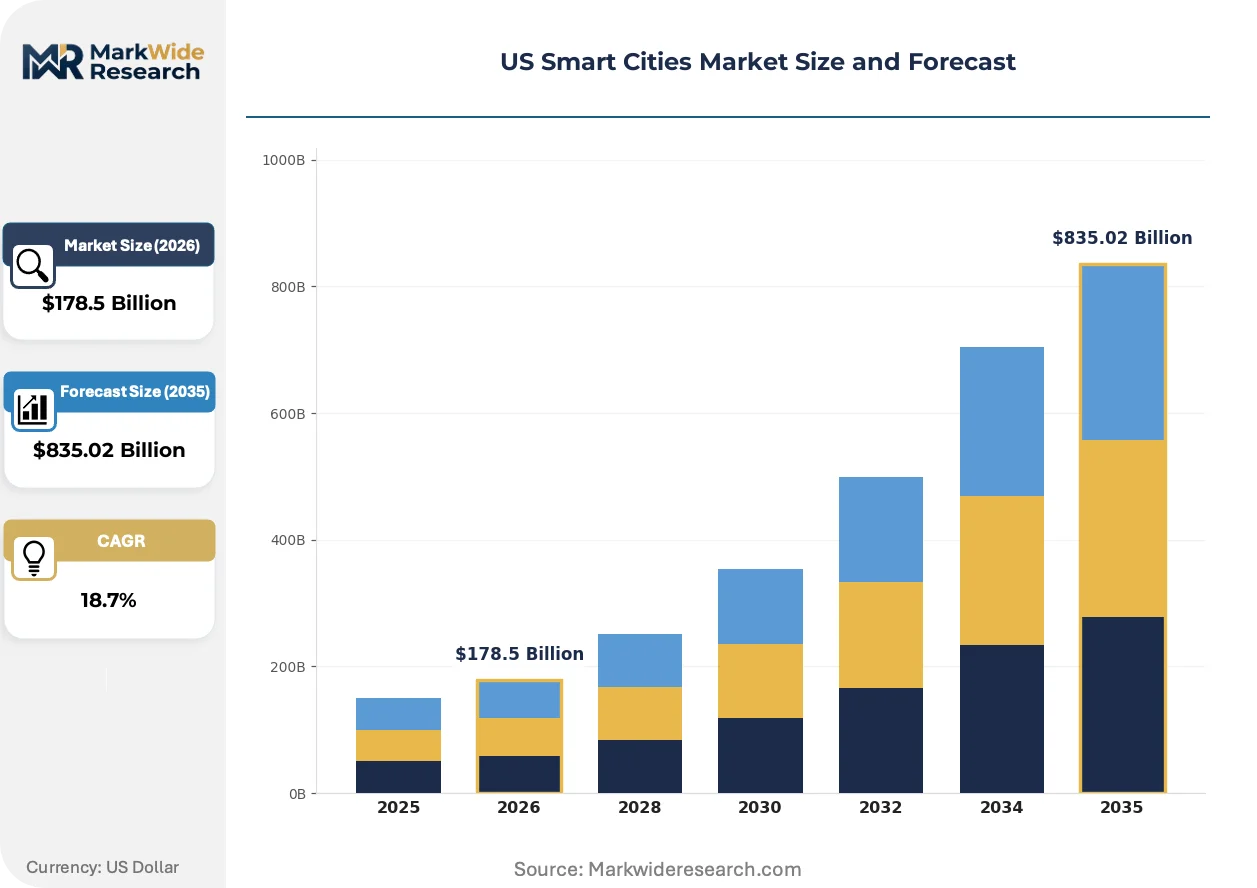
| Market Size in 2026 | $178.5 Billion |
| Market Size in 2035 | $835.02 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT Solutions, Cloud Computing, Artificial Intelligence, Big Data Analytics Application: Traffic Management, Waste Management, Energy Management, Public Safety End User: Civic Bodies, Government Agencies, Private Sector, Utilities Deployment: On-Premises, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | Cisco Systems, IBM, Microsoft, Siemens, Honeywell International, Schneider Electric, Intel, Oracle, General Electric, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Smart Cities Market Trends and Innovations
Edge AI inference is redistributing computational load from centralized cloud architectures toward street-level nodes, altering vendor competitive positions and procurement evaluation criteria.
Digital twin platforms are rewriting how transportation agencies simulate corridor performance before capital deployment. State DOTs in Texas and California are adopting these tools for congestion pricing design. The technology is compressing traditional engineering study timelines from 18 months to 90-day digital iteration cycles.
The FCC's 5.9 GHz band reconfiguration order mandates backward-compatible roadside unit upgrades for any municipality receiving federal connected vehicle grants. Equipment vendors must now certify dual-mode DSRC-C-V2X hardware. California and Michigan transportation authorities are advancing pilot corridors under the revised spectrum rules.
Municipal procurement teams are consolidating vendor relationships around outcome-based service level agreements rather than capital equipment purchases. Mid-sized cities in the Southwest are leading this transition, substituting annual subscription commitments for upfront infrastructure investments. The shift favors Cisco and IBM with existing managed service capabilities over hardware-centric competitors.
US Smart Cities Market Segmentation
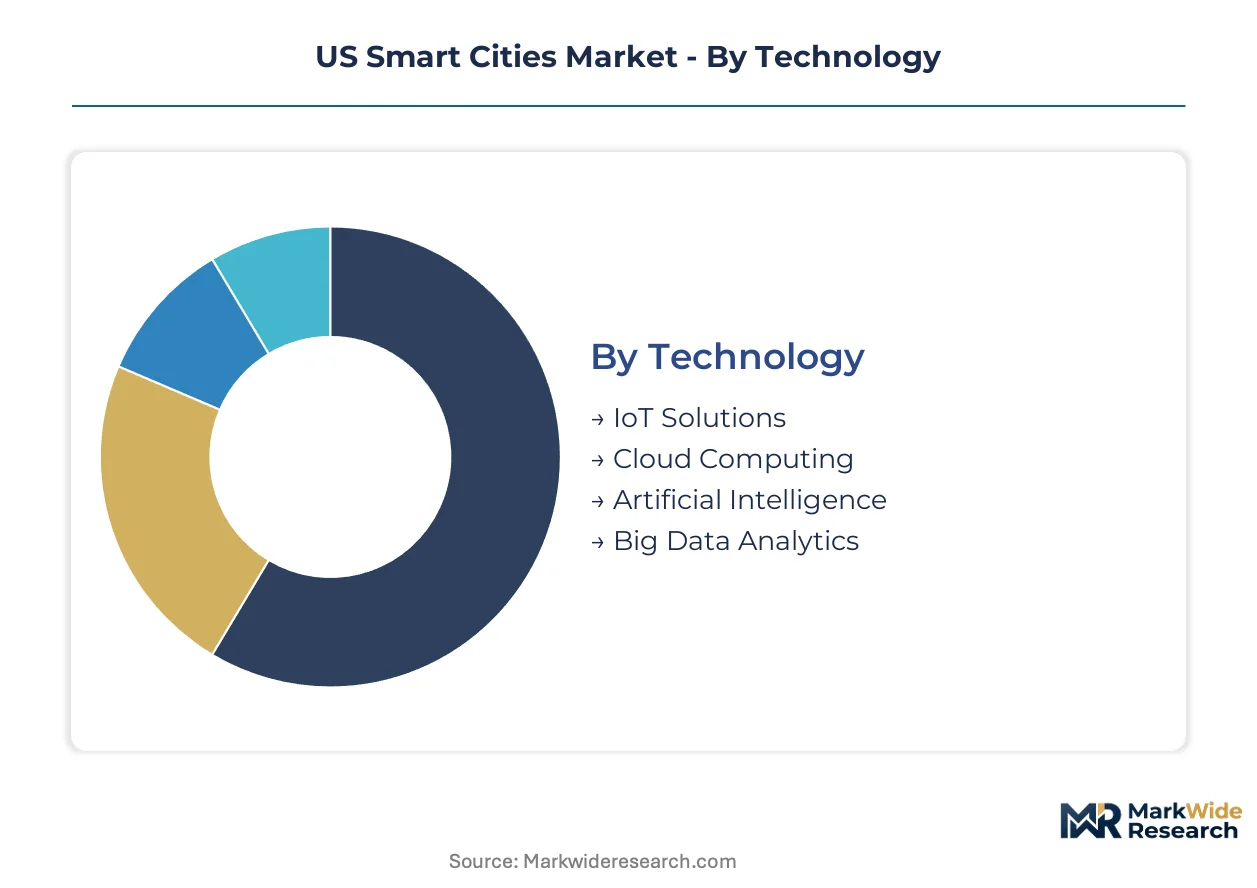
US Smart Cities Market segmentation reveals how procurement priorities diverge between legacy infrastructure overlays and greenfield digital deployments. Municipal buyers evaluate technology stacks against integration complexity, operational sovereignty requirements, and federal funding eligibility criteria.
Technology:
Purchasing decisions pivot on interoperability thresholds with existing municipal IT architectures and cybersecurity certification requirements under NIST frameworks.
- IoT Solutions:Networked sensor arrays and connectivity gateways form the physical instrumentation layer for urban infrastructure. California metropolitan transit authorities are deploying these at scale along digitized corridors where federal IIJA funding mandates interoperable device certification.
- Cloud Computing:Centralized compute and storage resources delivered via subscription models eliminate capital intensity for mid-sized municipalities. Texas and Arizona cities between 100,000 and 500,000 residents are adopting these deployments fastest as they bypass legacy on-premises infrastructure entirely.
- Artificial Intelligence:Machine learning models process telemetry streams for predictive maintenance and resource optimization.
- Big Data Analytics:Aggregation platforms synthesize multi-source urban data for operational dashboards and long-term planning.
Volume sits with IoT Solutions; growth tilts toward Cloud Computing.
Application:
Functional priorities reflect federal funding allocation patterns and measurable outcome metrics that satisfy municipal procurement oversight.
- Traffic Management:Intelligent signal control, congestion pricing systems, and connected vehicle corridor infrastructure. State DOTs in Texas and California are concentrating investment here where C-V2X spectrum rulings from the FCC enable vehicle-to-infrastructure communication pilots.
- Public Safety:Emergency response optimization, gunshot detection, and critical communication networks with stringent reliability mandates. New York metropolitan agencies command premium pricing for these deployments due to federal interoperability requirements and CISA resilience standards.
- Energy Management:Grid modernization, building automation, and distributed energy resource integration.
- Waste Management:Route optimization, fill-level monitoring, and collection fleet telematics.
Procurement momentum clusters in Traffic Management; Public Safety claims the steepest expansion trajectory as federal security funding accelerates.
End User:
Contracting authority and funding mechanisms determine vendor engagement models and solution architecture requirements.
- Civic Bodies:City councils and mayoral offices with consolidated procurement authority over multiple infrastructure domains. These stakeholders in California, Texas, and New York metropolitan areas are driving integrated platform adoption where legacy grid modernization converges with mobility investments.
- Government Agencies:State-level departments of transportation and environmental quality with specialized technical staff. Federal IIJA funding windows are compressing their vendor selection timelines for connected corridor deployments.
- Utilities:Investor-owned and municipal electric, water, and gas distribution operators.
- Private Sector:Commercial developers and facility operators pursuing smart building certifications.
Contract value concentrates with Civic Bodies; Government Agencies are gaining share fastest as federal funding flows through state administrative channels.
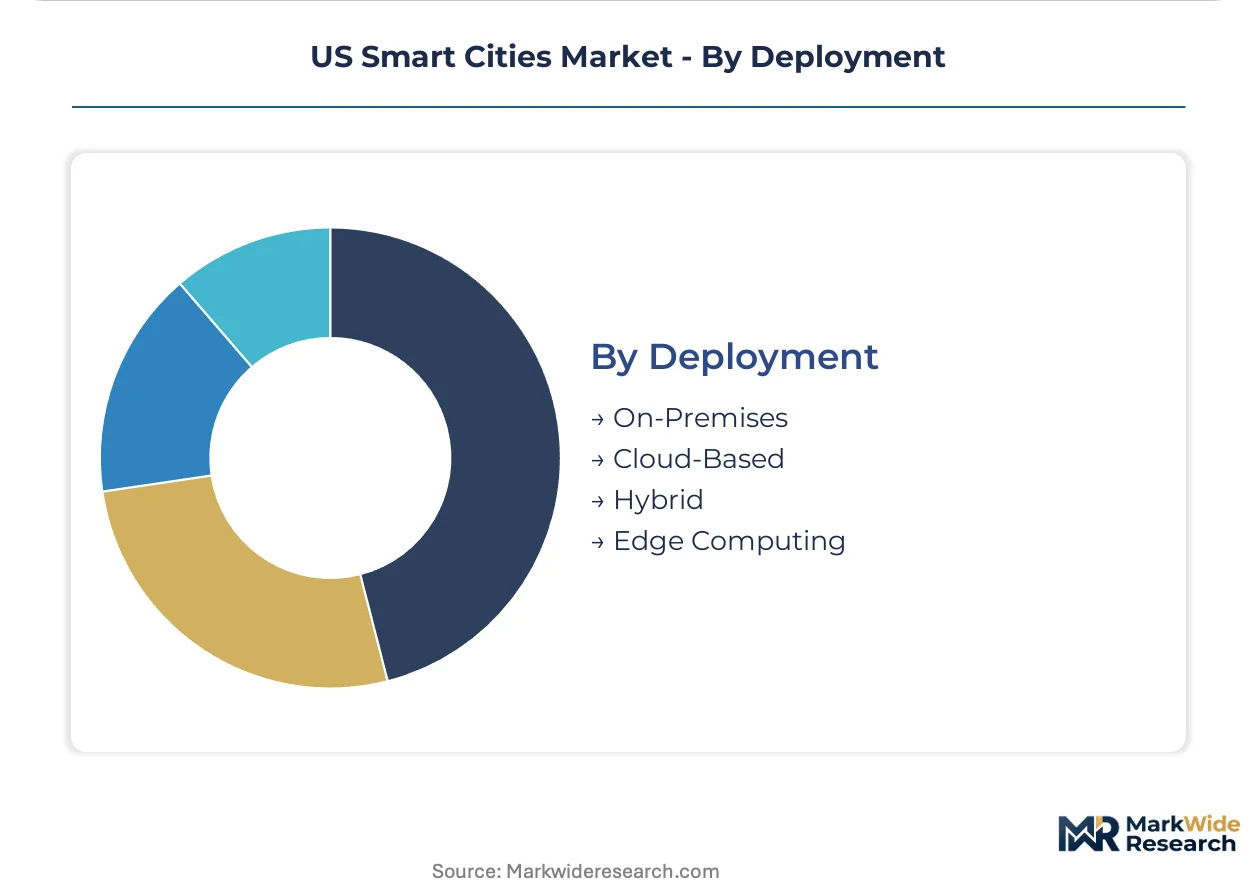
Deployment:
Architecture choices reflect data sovereignty concerns, latency requirements, and workforce technical capacity constraints.
- Edge Computing:Distributed processing nodes at street level reduce bandwidth costs and enable sub-second response times for safety-critical applications. California and Michigan transportation authorities are specifying these for connected vehicle corridors under FCC 5.9 GHz reconfiguration mandates.
- Cloud-Based:Fully off-premises deployments with vendor-managed infrastructure and security operations. Southwestern mid-sized cities are consolidating procurement around these models, substituting annual subscriptions for capital equipment purchases.
- Hybrid:Split architectures retaining sensitive workloads on-premises while bursting to cloud resources.
- On-Premises:Self-managed infrastructure with direct operational control over data and security policies.
Adoption currently favors Cloud-Based; Edge Computing is climbing the fastest as latency-sensitive transportation applications proliferate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The San Francisco Bay Area anchors smart city infrastructure deployment through its convergence of venture capital, utility modernization mandates, and connected vehicle pilot corridors. Federal IIJA funding has accelerated procurement timelines across California metropolitan transit authorities. State-level data sovereignty legislation in Texas and New York creates divergent compliance architectures for multi-jurisdictional vendors.
California
Metropolitan transit authorities in Los Angeles and San Francisco are deploying C-V2X roadside units under FCC 5.9 GHz reconfiguration mandates. The California Public Utilities Commission enforces grid modernization timelines that synchronize with utility procurement cycles. Silicon Valley technology clusters supply edge computing hardware to municipal agencies digitizing urban corridors.
Texas
Dallas-Fort Worth and Houston metropolitan areas are consolidating vendor relationships around outcome-based service agreements for traffic management systems. The Texas Department of Transportation compresses vendor selection timelines to obligate federal IIJA funds before authorization windows close. Austin's municipal utility pilots smart metering convergence with leak detection AI for water-wastewater integration.
New York
The New York metropolitan area commands premium pricing for public safety deployments due to federal interoperability mandates and CISA resilience standards. State environmental quality departments coordinate with municipal IT agencies on cybersecurity framework compliance. Buffalo and Rochester mid-sized municipalities adopt cloud-native platforms to bypass legacy infrastructure constraints.
Illinois
Chicago's Department of Transportation advances connected vehicle corridor pilots alongside legacy grid sensor overlay projects. The Illinois Commerce Commission governs utility rate cases that fund smart meter deployments. Peoria and Rockford cities between 100,000 and 500,000 residents represent white space for integrated platform vendors seeking cloud subscription models.
Michigan
Detroit's automotive industry heritage accelerates vehicle-to-infrastructure communication testing under revised FCC spectrum rules. The Michigan Department of Transportation coordinates with federal agencies on physical and digital resilience standard harmonization. Ann Arbor's municipal utility faces execution risk integrating IP-connected sensors atop decades-old SCADA industrial control systems.
US Smart Cities Market Competitive Landscape
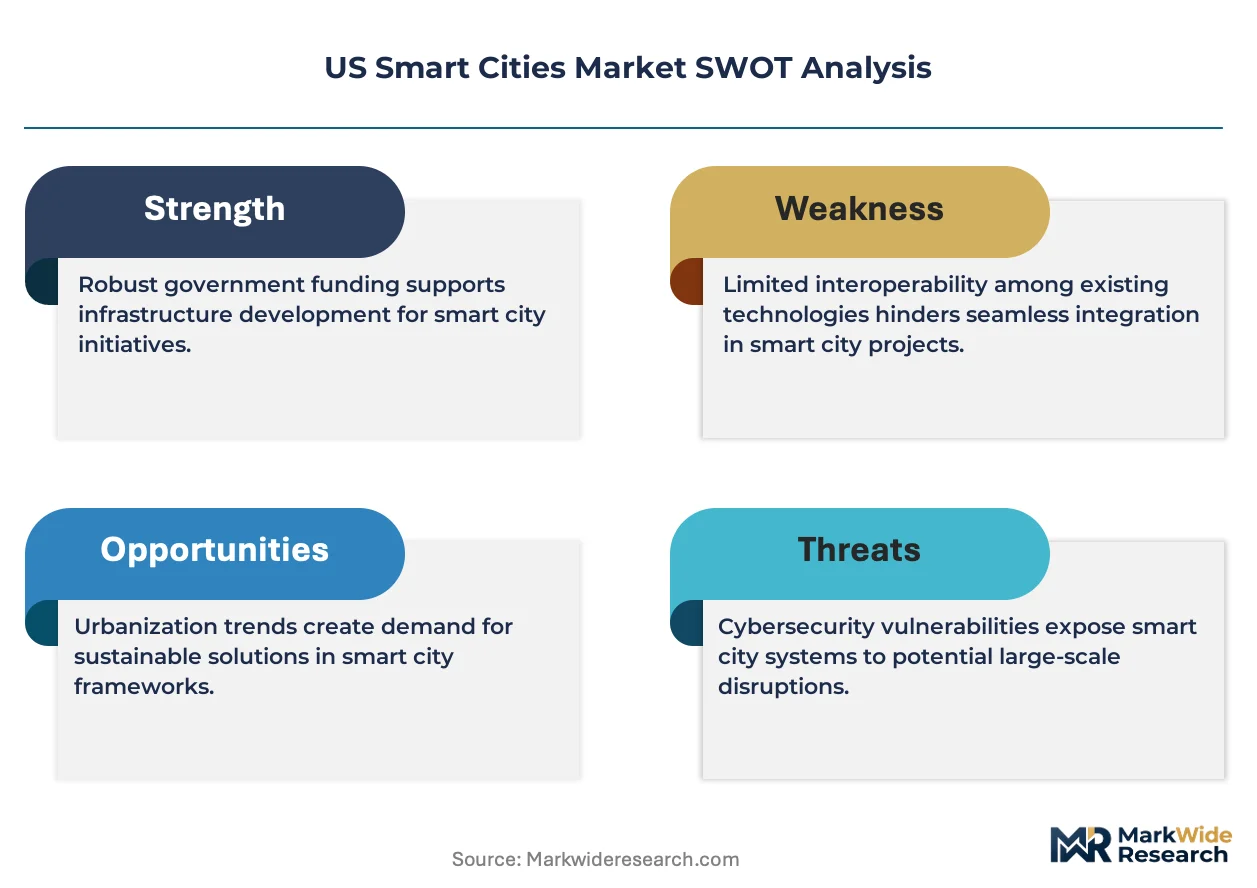
Premium-margin players sit above commodity-margin players across integration complexity and cybersecurity certification depth. The vendor base stratifies between networking heritage specialists, data analytics contractors, and building automation pure-plays. Three archetypes dominate: secure municipal backbone deployers, state-level analytics integrators, and energy optimization specialists. Competitive moves concentrate on strategic partnerships for federal funding access and portfolio diversification into water-wastewater verticals.
Within the networking infrastructure tier, Cisco Systems exemplifies secure municipal backbone deployment archetypes through its dominance of interoperable device certification programs. IBM anchors the state-level data analytics contracting vector alongside Oracle's cloud-native municipal subscriptions. Siemens occupies a position within building automation and energy optimization systems, competing through deep specialization in utility-facing retrofit incentives. These three companies represent distinct capability concentrations that shape procurement evaluation criteria across transportation, public safety, and energy management application verticals.
| Leading Market Players |
|---|
| Cisco Systems |
| IBM |
| Microsoft |
| Siemens |
| Honeywell International |
| Schneider Electric |
| Intel |
| Oracle |
| General Electric |
| Others |
Pricing and Supply Chain Analysis
Municipal procurement consolidation around outcome-based service agreements is forcing equipment vendors to absorb hardware costs into multi-year subscription models, compressing upfront margins while extending revenue recognition timelines. This shift favors Cisco and IBM with established managed service infrastructures over hardware-centric competitors lacking operational scale.
Pricing Analysis
Value-based pricing anchored to uptime guarantees and traffic throughput metrics dominates municipal backbone contracts, with Cisco commanding premium positioning through NIST cybersecurity certification depth. Price differentiation separates Federal Communications Commission-certified roadside units from uncertified commodity hardware, while California and Texas metropolitan agencies show lowest price sensitivity due to Infrastructure Investment and Jobs Act funding buffers. Cost compression in edge computing hardware is intensifying because semiconductor foundry bottlenecks constrain supply elasticity.
Supply Chain Analysis
Federal Communications Commission and NIST certification requirements gate vendor qualification, with roadside unit manufacturers requiring dual-mode DSRC-C-V2X hardware validation before procurement eligibility. Component sourcing draws from Taiwan and South Korea for edge computing semiconductors, with Mexico and Vietnam supplying enclosure and assembly fabrication. Single-source vulnerability concentrates in advanced sensor foundries. Distribution runs through systems integrators holding state-level contracting vehicles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The US smart cities sector is transitioning from capital-intensive infrastructure sales toward cloud-native service models, with edge AI inference displacing centralized cloud architectures as the dominant computational paradigm.
For Market Incumbents: Deepen vertical integration into edge computing hardware to secure foundry allocation priority against semiconductor supply concentration. Fortify NIST cybersecurity certification pipelines to maintain procurement specification influence as federal interoperability mandates tighten. Counter Oracle's cloud-native subscription momentum by embedding operational technology expertise into municipal staff augmentation contracts. For New Entrants and Emerging Players: Capture water-wastewater integration opportunities in mid-sized Southwestern municipalities where leak detection AI remains undersupplied relative to transportation-focused incumbents. Prioritize Austin and Phoenix metropolitan utilities with pilot-to-scale procurement pathways distinct from state DOT contracting channels. Lead with annual subscription commitments that substitute for deferred capital bond issuances. For Investors and Strategic Acquirers: The window for entry favors building automation specialists with Inflation Reduction Act incentive alignment and utility-facing retrofit expertise. Long-term viability hinges on portfolio diversification across transportation, energy, and water verticals rather than single-application concentration. Watch C-V2X pilot corridor conversion rates as the inflection signal for roadside unit demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Consolidates vendor relationships around outcome-based service agreements that displace capital equipment purchases. |
| Certification Investment | NIST cybersecurity framework alignment secures procurement specification influence for critical infrastructure deployments. |
| Geographic Expansion | Mid-sized municipalities between 100,000 and 500,000 residents offer white space for cloud-native bypass of legacy constraints. |
| Strategic Partnership | Systems integrators with state-level contracting vehicles accelerate federal funding window capture. |
| Acquisition of Specialist Firm | Water-wastewater AI capabilities diversify revenue beyond transportation-dominated incumbent portfolios. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted among municipal IT directors, state DOT procurement officers, utility planning leads, and systems integration specialists. Federal Communications Commission rulemaking dockets, NIST cybersecurity framework publications, Infrastructure Investment and Jobs Act funding disclosures, and state-level data sovereignty legislation formed the documentary foundation. Bottom-up municipal deployment tracking reconciled with top-down federal appropriation analysis.
Data-stream reconciliation across technology adoption curves, federal funding obligation timelines, and vendor contract announcements shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include deployment architecture, application vertical, end-user contracting authority, and geographic regulatory cluster. CAGRs derived from municipal procurement pipeline velocity and federal authorization sunset schedules, with edge computing hardware pricing and cloud subscription penetration as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to FCC spectrum reconfiguration timing and semiconductor supply normalization. Forecasts reflect assumptions regarding federal funding continuity and municipal bond market capacity. A model refresh is warranted upon material change in Infrastructure Investment and Jobs Act reauthorization prospects.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
Smart Communities Market
Smart City Technology
Global Smart City ICT Infrastructure Market
Smart City Technology
Smart Parcel Locker Market
Smart City Technology
City Data Platform Market
Smart City Technology
Smart City Platform Market
Smart City Technology
Smart City Kiosk Deployment Market
Smart City Technology
Singapore ICT Market
Smart City Technology
Smart Street Lights Market
Smart City Technology
India Smart City Market
Smart City Technology
Smart Ticketing Solutions Market
Smart City Technology
Smart Signaling Market
Smart City Technology
Outdoor LED Smart Lighting Solution Market
Smart City Technology
Smart Mailbox Market
Smart City Technology
Global Smart Pole Market
Smart City Technology
Smart Shade Device Market
Smart City Technology
Smart Parking Meters Market