
 Smart Space Market | 2026-2036
Smart Space Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Space Market Intelligence
The WELL Building Standard certification is reorganizing competitive dynamics by setting stringent criteria for human health in built environments. Siemens AG leverages its extensive building automation portfolio to meet these complex requirements. Schneider Electric SE competes on its EcoStruxure platform for integrated energy management and sustainability reporting. Cisco Systems Inc differentiates through its secure networking infrastructure, which underpins reliable data exchange in connected spaces.
A smart space is a physical environment where IoT sensors and connected devices collect real-time data to automate and optimize operations. These systems use analytics platforms to improve resource management, from energy consumption to spatial utilization. Energy Optimization solutions are a primary driver for adoption across all applications. While commercial buildings form the largest user base, co-working spaces and specialized hospitality environments represent the fastest-growing application segments due to their focus on user experience.
Data privacy regulations like Europe's GDPR directly influence solution design, requiring robust consent management and data anonymization features. In the United States, building energy codes such as California's Title 24 mandate efficiency levels that drive investment in smart controls. These regulatory frameworks compel vendors to build compliance into their core architectures. The central challenge for providers is to deliver seamless user experiences while navigating this complex and fragmented global regulatory environment.
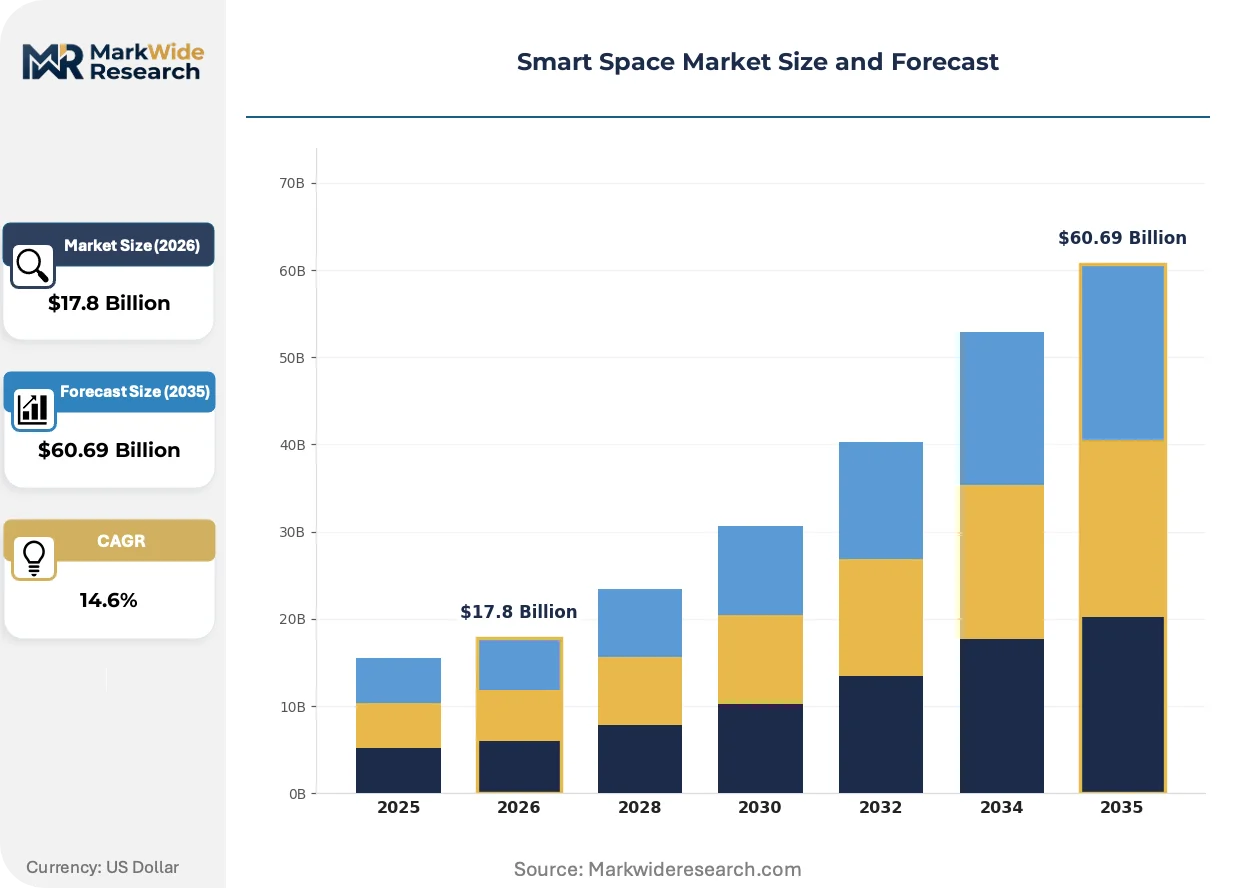
Market Dynamics
The convergence of corporate sustainability goals and stringent energy regulations is the central force defining the smart space market. This pressure compels building owners and operators to invest in IoT-driven solutions for transparent energy management and operational efficiency.
Growth Catalysts
- Energy Efficiency Mandates:Regulations like the EU's Corporate Sustainability Reporting Directive (CSRD) and California's Title 24 compel enterprises to adopt transparent energy monitoring and reduction technologies, directly stimulating solution sales.
- IoT and AI Proliferation:The declining cost of sensors and the increasing sophistication of AI-powered analytics platforms make it economically viable for commercial buildings to deploy systems for energy optimization and predictive maintenance.
- Focus on Occupant Experience:The hospitality and corporate real estate sectors are leveraging smart space technology to create healthier, more productive environments, using data to personalize lighting, climate, and space utilization for occupants.
Market Restraints
- High Initial Investment:The significant capital expenditure required to retrofit older buildings with sensors, actuators, and modern network infrastructure presents a major barrier to adoption for many property owners.
- System Interoperability:A lack of standardization among vendor ecosystems creates proprietary data silos, making it difficult to integrate different building systems like HVAC, lighting, and security into a single cohesive platform.
- Data Privacy Concerns:The extensive data collection on occupant behavior and space utilization raises significant privacy issues, requiring solution designs that comply with strict regulations like Europe's GDPR.
Strategic Opportunities
- Digital Twin Integration:Creating virtual models of physical buildings offers a significant opportunity for predictive analytics, enabling simulation of energy strategies and remote management of facility operations before physical implementation.
- Emerging Economies:Rapid urbanization and new construction in regions like the Middle East and Southeast Asia, particularly in smart city projects, provide a fertile ground for deploying integrated smart space solutions from the ground up.
- Edge Computing:Deploying computation closer to the data source via edge devices reduces latency and reliance on cloud connectivity, enabling faster real-time control and enhanced data security for sensitive building operations.
Industry Challenges
- Talent Scarcity:The market faces a shortage of professionals with hybrid expertise in facility management, IT networking, and data analytics, which is critical for deploying and managing complex smart space systems.
- Legacy System Integration:Integrating modern IoT platforms with aging, non-IP-based building automation systems (BAS) is a complex and costly technical challenge that can delay or derail implementation projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Space Market |
| Market Size in 2026 | $17.8 Billion |
| Market Size in 2035 | $60.69 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premises, Hybrid, Edge Computing Solution: Space Management, Occupancy Analytics, Security & Surveillance, Energy Optimization, Workplace Experience Application: Commercial Buildings, Educational Institutes, Government Facilities, Co-Working Spaces, Hospitality Environments End User: Facility Managers, Real Estate Developers, Corporate Enterprises, Property Management Firms |
| Companies Covered | Cisco Systems Inc, Adappt Intelligence Inc, Oracle Corporation, ICONICS Inc, Spacewell, ABB Ltd, Envoy, Schneider Electric SE, Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Space Market Strategic Shifts & Innovations
The market is shifting from reactive building automation to predictive, AI-driven environments. This evolution prioritizes not just efficiency but also occupant well-being and regulatory compliance, making intelligence an integral component of the built environment's value proposition.
AI-powered analytics platforms provide real-time insights into energy consumption and building operations. Commercial real estate owners and large corporations are the primary adopters, seeking to reduce operating costs and meet sustainability targets. This technology is displacing older, rule-based building management systems that lack the capability for dynamic optimization or predictive fault detection.
Mandatory disclosure rules are becoming a significant factor in technology adoption. The EU's CSRD, for example, requires large firms to report on their environmental impact, including building energy usage. This regulation directly impacts facility management across Europe, compelling investment in auditable smart platforms to ensure accurate and compliant sustainability reporting.
A notable behavioral change involves the move away from large, one-time capital purchases toward subscription-based service models. This "Space-as-a-Service" approach disrupts the traditional sales cycle for building controls, with providers now offering bundled solutions that include hardware, software, and continuous analytics. This trend is especially visible within the agile co-working sector and among corporate tenants in North American metropolitan areas.
Smart Space Market Segmentation
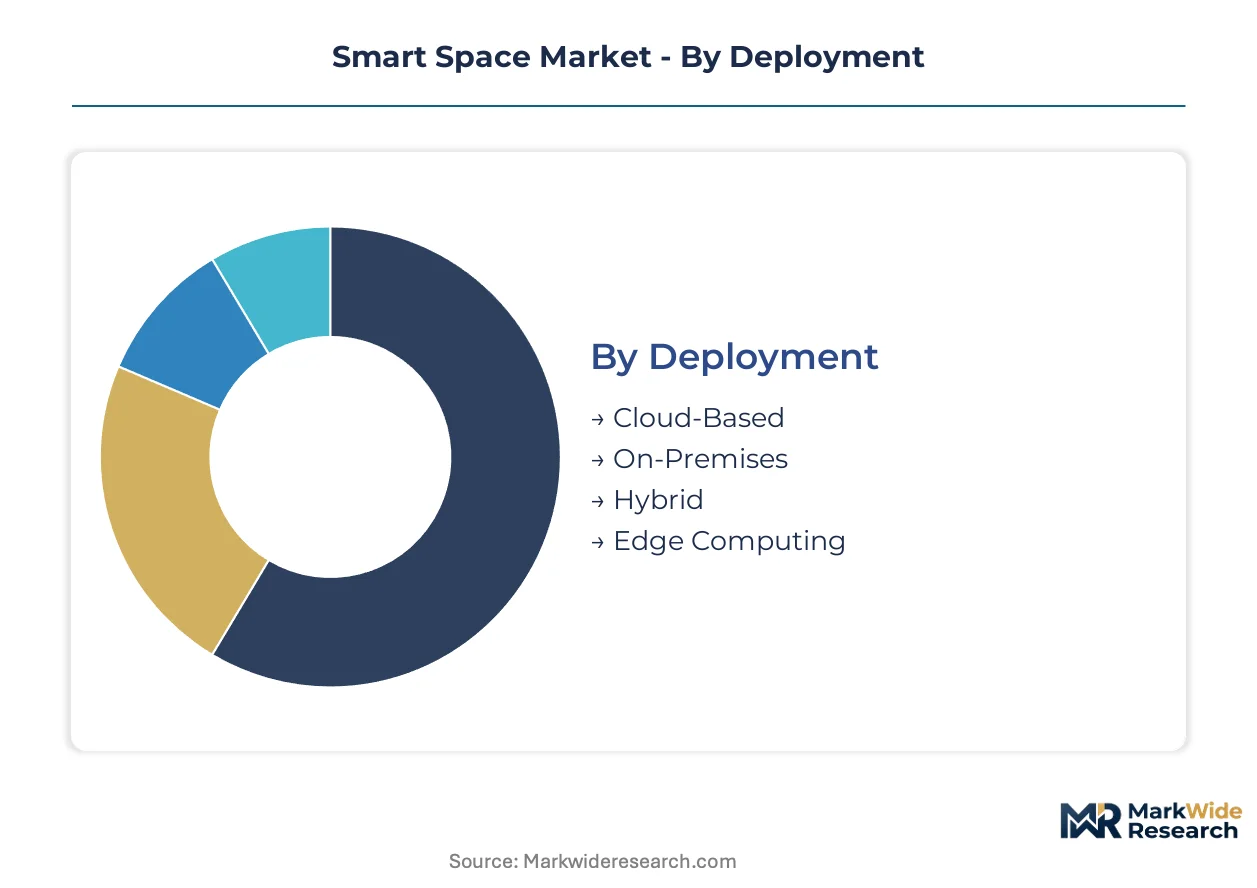
The Smart Space Market categorizes its offerings to address diverse operational needs and deployment preferences across various end-user environments. This segmentation helps solution providers tailor their technologies, from energy management platforms to occupancy analytics tools, for specific client requirements and regulatory landscapes.
Deployment:
Smart space solutions reach customers through distinct deployment models that influence data handling and infrastructure requirements.
- Cloud-Based:These solutions host software and data on remote servers, offering scalability and accessibility from any internet-connected device. Demand concentrates in corporate enterprises and property management firms seeking reduced upfront IT costs and continuous software updates.
- Edge Computing:Processing data closer to the source, often within the building itself, minimizes latency and enhances data security for time-sensitive operations. This model is gaining traction in critical infrastructure and secure government facilities in countries like Germany and the United States.
- On-Premises:Software and infrastructure are installed and managed directly on the client's physical site, providing maximum control over data and customization. Educational institutes and government facilities often prefer this model for enhanced security protocols.
- Hybrid:This model combines elements of both cloud-based and on-premises deployments, allowing organizations to maintain sensitive data locally while leveraging cloud services for scalability. Property management firms utilize hybrid setups for flexible data management.
By volume, Cloud-Based solutions lead. By growth pace, Edge Computing is ahead.
Solution:
The market's solution offerings are defined by their functional capabilities, addressing specific operational challenges within connected environments.
- Energy Optimization:These solutions utilize IoT sensors and AI analytics to monitor and reduce energy consumption across HVAC, lighting, and other building systems. Commercial buildings and corporate enterprises in Europe, driven by CSRD mandates, are primary adopters for cost savings and sustainability reporting.
- Workplace Experience:Platforms designed to enhance occupant comfort and productivity through personalized climate control, smart lighting, and space booking systems. Co-working spaces and hospitality environments in Singapore and North American metropolitan areas are rapidly deploying these solutions to attract and retain tenants.
- Space Management:Tools that track and analyze space utilization patterns, helping organizations optimize floor plans, manage desk assignments, and improve facility efficiency. Real estate developers and large corporate campuses leverage these systems for strategic planning.
- Occupancy Analytics:Systems that detect and count occupants, providing real-time data on foot traffic, density, and usage patterns for safety and operational insights. Retail environments and public facilities use this technology for crowd management.
- Security & Surveillance:Integrated systems featuring smart cameras, access control, and alarm monitoring, leveraging AI for anomaly detection and proactive threat identification. Government facilities and critical infrastructure prioritize these advanced security measures.
Energy Optimization solutions generate the largest share of demand. Workplace Experience solutions are climbing the fastest.
Application:
Smart space technologies find implementation across various physical environments, each presenting unique demands and use cases for automation and data analytics.
- Commercial Buildings:These structures represent the largest user base, deploying smart systems for energy efficiency, operational cost reduction, and tenant satisfaction. Large office complexes in urban centers like London and New York heavily invest in comprehensive smart solutions.
- Co-Working Spaces:These flexible environments leverage smart technologies to enhance user experience, optimize space utilization, and manage shared resources efficiently. This segment in North America and Southeast Asia is experiencing the steepest expansion trajectory.
- Hospitality Environments:Hotels and resorts implement smart solutions for personalized guest experiences, energy management in guest rooms, and streamlined operational workflows. Luxury hotel chains in Dubai and Paris integrate these systems for competitive advantage.
- Educational Institutes:Universities and schools deploy smart systems for energy management, campus security, and optimizing classroom utilization. Public and private schools in the United States incorporate these technologies for safer and more efficient learning environments.
- Government Facilities:Public sector buildings utilize smart technologies for enhanced security, energy conservation, and efficient facility management, often driven by government mandates. Municipal buildings in Nordic countries adopt these solutions for public sector efficiency.
Commercial Buildings account for the highest volume of deployments. Co-Working Spaces are gaining share fastest.
End User:
The adoption of smart space solutions is driven by distinct organizational roles and strategic objectives within the built environment sector.
- Corporate Enterprises:Large businesses invest in smart spaces to improve operational efficiency, reduce energy consumption, and meet corporate sustainability goals. Multinational corporations in Europe and the United States are significant adopters due to regulatory pressures like the CSRD.
- Real Estate Developers:These entities integrate smart technologies into new construction projects to enhance building value, attract tenants, and future-proof their properties. Developers in emerging economies like Singapore and the UAE prioritize smart infrastructure from the ground up.
- Facility Managers:Professionals responsible for building operations deploy smart solutions to streamline maintenance, optimize resource allocation, and ensure occupant comfort. They use these systems for proactive issue resolution and predictive maintenance across various building types.
- Property Management Firms:These companies manage portfolios of commercial and residential properties, using smart technologies to enhance tenant services, monitor building performance, and drive operational savings across multiple sites. They seek integrated platforms for remote oversight.
Corporate Enterprises represent the largest end-user segment by investment. Real Estate Developers show the most dynamic adoption patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulations like the EU's CSRD and California's Title 24 are compelling building owners to invest in smart space solutions. These mandates drive transparent energy monitoring and operational efficiency across diverse geographies. Technologically advanced urban centers globally prioritize smart infrastructure development.
United States
Demand for smart spaces in the United States is driven by significant corporate investment in operational efficiency and occupant experience. Building energy codes such as California's Title 24 mandate efficiency levels, spurring technology adoption. Major metropolitan areas like New York and San Francisco are seeing rapid deployment of smart building systems in commercial real estate.
Germany
Germany's smart space market focuses on energy optimization and compliance with stringent environmental regulations. The EU's CSRD directly influences facility management, requiring auditable platforms for sustainability reporting. Industrial hubs in Bavaria and North Rhine-Westphalia are integrating advanced IoT solutions for predictive maintenance and resource management.
Singapore
Singapore prioritizes smart infrastructure development, positioning itself as a leader in integrated urban solutions. Government initiatives like the Smart Nation program encourage the adoption of advanced building management systems. The city-state's new construction projects across Marina Bay are deploying comprehensive smart space technologies from the ground up.
China
China's rapid urbanization and extensive smart city projects are fueling demand for smart space technologies. National policies promoting green buildings and energy conservation incentivize the deployment of IoT-driven solutions. Major tech centers like Shenzhen and Shanghai are hubs for integrating AI-powered analytics into large-scale commercial and residential developments.
Smart Space Market Key Industry Players
Listed leaders compete with private specialists across the smart space technology and service delivery spectrum. The market exhibits a tiered structure, with established industrial conglomerates alongside agile software providers. Strategic archetypes include integrated solution providers, specialized software developers, and infrastructure hardware manufacturers. Companies pursue portfolio diversification and strategic partnerships to expand their market reach.
Within the integrated solution provider archetype, Siemens AG and Schneider Electric SE exemplify large industrial players leveraging extensive building automation portfolios. These companies offer comprehensive platforms that span hardware, software, and services, addressing complex client requirements. Cisco Systems Inc, meanwhile, anchors the secure networking infrastructure segment, providing the critical backbone for reliable data exchange in connected environments.
| Leading Market Players |
|---|
| Cisco Systems Inc |
| Adappt Intelligence Inc |
| Oracle Corporation |
| ICONICS Inc |
| Spacewell |
| ABB Ltd |
| Envoy |
| Schneider Electric SE |
| Siemens AG |
| Others |
Cost & Logistics Intelligence
Economies of scale in smart sensor manufacturing and AI software development shape both supply concentration and the eventual price floors for integrated solutions. This dynamic influences how vendors structure their offerings and compete within the Smart Space Market.
Pricing Analysis
WELL Building Standard certification creates the primary spread in pricing for smart space solutions, reflecting enhanced health and productivity features. Pricing models increasingly adopt a subscription-based "Space-as-a-Service" approach, bundling hardware, software, and continuous analytics. Price differentiation also stems from customization levels required for complex legacy system integrations. Pricing softness stems from increasing competition among solution providers and the commoditization of basic IoT components. Corporate enterprises and hospitality environments are less price-sensitive for advanced, certified solutions, while educational institutes often prioritize cost-effectiveness.
Supply Chain Analysis
Long lead times for specialized IoT sensors and embedded processors influence project timelines and inventory management for smart space deployments. The supply chain for core components concentrates in countries like China for sensor manufacturing, Germany for industrial automation controls, and the United States for advanced AI platforms. Raw material dependencies include rare earth elements for sensors and specialized semiconductors for AI processors. Logistics chokepoints present a structural risk, potentially delaying hardware delivery. Distribution primarily occurs through direct sales channels for large-scale corporate and government projects, complemented by channel partners for smaller commercial buildings and co-working spaces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Space Market is experiencing a cyclical recovery, driven by renewed corporate investment in operational efficiency and occupant well-being initiatives. This resurgence creates strategic imperatives for all market participants.
For Market Incumbents:Fortify core platform capabilities through continuous R&D in AI analytics and edge computing to maintain a technological lead. Acquire specialized software firms to integrate niche functionalities, addressing the threat from agile software providers. Enhance service offerings around data privacy compliance, particularly for GDPR-sensitive clients. Leverage extensive building automation portfolios to offer comprehensive, integrated solutions, reducing deployment friction for clients.
For New Entrants and Emerging Players:Integration complexity for legacy building automation systems presents a significant service-layer gap for new entrants. Target specialized hospitality environments or smaller educational institutes with tailored, easy-to-deploy solutions. The co-working sector in North American metropolitan areas and Southeast Asia represents a penetrable segment for agile offerings. A subscription-based "Space-as-a-Service" go-to-market angle can lower upfront costs and accelerate adoption among these users.
For Investors and Strategic Acquirers:Mid-cycle technology positioning favors integrated platform providers capable of delivering end-to-end smart space solutions, offering long-term viability in real estate asset management. Acquisition targets should include software developers specializing in AI analytics, digital twin integration, or robust edge computing solutions. A signal to watch for inflection is the widespread adoption of standardized interoperability protocols, which would streamline integration and expand market reach.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Siemens AG can strengthen its comprehensive building automation portfolio through enhanced software integration. |
| AI Analytics Development | Schneider Electric SE can improve predictive maintenance capabilities with advanced AI-driven insights. |
| Edge Computing Investment | Cisco Systems Inc can reduce latency and enhance data security for critical building operations in Germany. |
| Strategic Partnerships | Property management firms can offer more flexible and comprehensive smart solutions to diverse clients. |
| Subscription Model Expansion | The co-working sector can access advanced smart space technologies with lower initial capital expenditure. |
Research Approach
Initial hypotheses were tested against primary input from facility managers, corporate real estate executives, and IoT platform engineers, then refined through iterative feedback. This primary research was triangulated with extensive secondary data from EU CSRD reports, California Title 24 compliance documents, smart city project disclosures, and technology vendor whitepapers. A combination of bottom-up and top-down approaches ensured comprehensive market sizing and validation across various segments.
Variance decomposition across solution types, deployment models, applications, and end-users formed the basis of the quantitative forecast framework. CAGRs were derived by projecting demand drivers, technology adoption rates, and regulatory impacts across the analysis window. Key industry-specific forecast inputs included building energy consumption data, IoT sensor deployment rates, and new construction project pipelines in urban centers.
Forecasts assume regulatory continuity in the EU, United States, and Singapore; material policy shifts would require re-modeling the market trajectory. Risk factors such as rapid technological obsolescence or unforeseen data privacy legislation could alter demand patterns. Outputs are directional rather than precise point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
US Smart Cities Market
Smart City Technology
Smart City Kiosk Market
Smart City Technology
India Smart City Market
Smart City Technology
City Data Platform Market
Smart City Technology
E-Governance Market
Smart City Technology
Global Smart Pole Market
Smart City Technology
Global Smart Hubs Market
Smart City Technology
Global Smart City ICT Infrastructure Market
Smart City Technology
Smart City Platform Market
Smart City Technology
Global Smart City Market
Smart City Technology
Singapore ICT Market
Smart City Technology
Smart Shade Device Market
Smart City Technology
Smart Signaling Market
Smart City Technology
Smart Parcel Locker Market
Smart City Technology
Smart Street Lights Market
Smart City Technology
Smart Ticketing Solutions Market