
 Saudi Arabia Smart Cities Market | 2026-2036
Saudi Arabia Smart Cities Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Smart Cities Market Insights
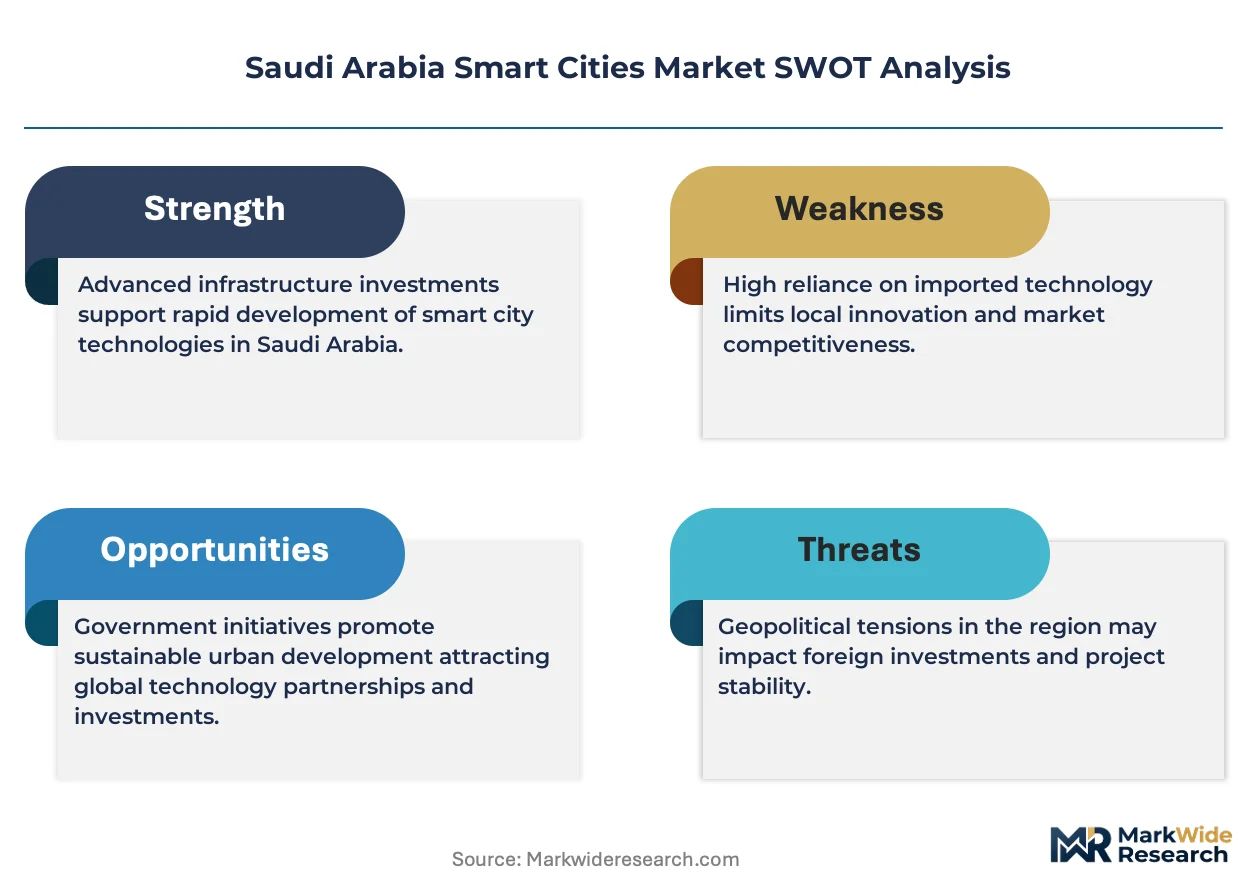
Multi-source procurement for digital infrastructure is decoupling from traditional single-vendor IT contracts across Saudi municipal projects. Huawei Technologies Co., Ltd. leverages its 5G-to-cloud stack to anchor large-scale deployment contracts in the Kingdom. Schneider Electric SE competes on energy-management integration, while Cisco Systems Inc. specializes in secure network backbones for critical urban systems.
A smart city integrates IoT sensors, edge computing nodes, and centralized data platforms to optimize energy distribution, traffic flows, and public safety across urban environments. Artificial Intelligence and Big Data segments lead current investment, with IoT platform deployment widening as sensor costs decline and connectivity standards stabilize. Traffic Management and Energy Management applications command the deepest margin pools, reflecting the capital intensity of retrofitting legacy grids and road networks with real-time orchestration layers.
SFDA guidelines on data privacy, MOHAP cybersecurity frameworks, and Saudi Communications and Information Technology Commission spectrum allocations collectively shape vendor eligibility and system interoperability requirements. Compliance with these standards determines market access for foreign technology providers and influences local partnership structures. Stakeholders must track evolving procurement mandates under Vision 2030 giga-projects to anticipate which service-type contracts—consulting, implementation, or long-term maintenance—will absorb the next wave of capital allocation.
Market Dynamics
Government procurement reforms under Vision 2030 are decoupling municipal digital infrastructure from legacy single-vendor IT contracts, fragmenting supplier bases and accelerating technology refresh cycles across Saudi urban redevelopment projects.
Growth Catalysts
- Vision 2030 mandates:National transformation programs prioritize smart infrastructure deployment in giga-projects, channeling sovereign capital toward integrated IoT platforms and centralized command centers.
- IoT sensor cost compression:Declining hardware prices enable denser edge-node networks across traffic grids and utility distribution systems, expanding real-time monitoring coverage.
- NEOM construction timelines:The linear city's phased buildout creates concentrated demand windows for integrated smart systems, pulling forward vendor qualification and localization requirements.
Market Restraints
- Semiconductor supply concentration:Reliance on East Asian foundries for edge-computing chipsets exposes deployment schedules to geopolitical disruption and allocation bottlenecks.
- Cybersecurity compliance friction:NCA and MOHAP certification timelines extend vendor onboarding by 8-14 months, compressing project windows and inflating pre-qualification costs.
- Legacy grid retrofit capital intensity:Existing municipal infrastructure requires parallel-run orchestration layers, doubling effective deployment expenditure versus greenfield sites.
Strategic Opportunities
- Secondary city penetration:Jeddah, Dammam, and Abha lag Riyadh in smart infrastructure density, presenting first-mover advantages for integrated platform vendors.
- AI-energy convergence:Machine learning-driven demand forecasting is converging with distributed solar microgrids, creating predictive load-balancing service contracts.
- SFDA data-governance frameworks:Emerging health-data interoperability standards open municipal-health system integration, expanding platform addressable market into telemedicine infrastructure.
Industry Challenges
- Localization workforce gaps:Saudi Vision 2030 Saudization targets collide with scarce domestic expertise in edge-computing architecture and cybersecurity operations.
- Multi-vendor integration complexity:Fragmented procurement across Huawei, Schneider, and Cisco stacks creates API incompatibility and data-sovereignty conflicts in unified command centers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Smart Cities Market |
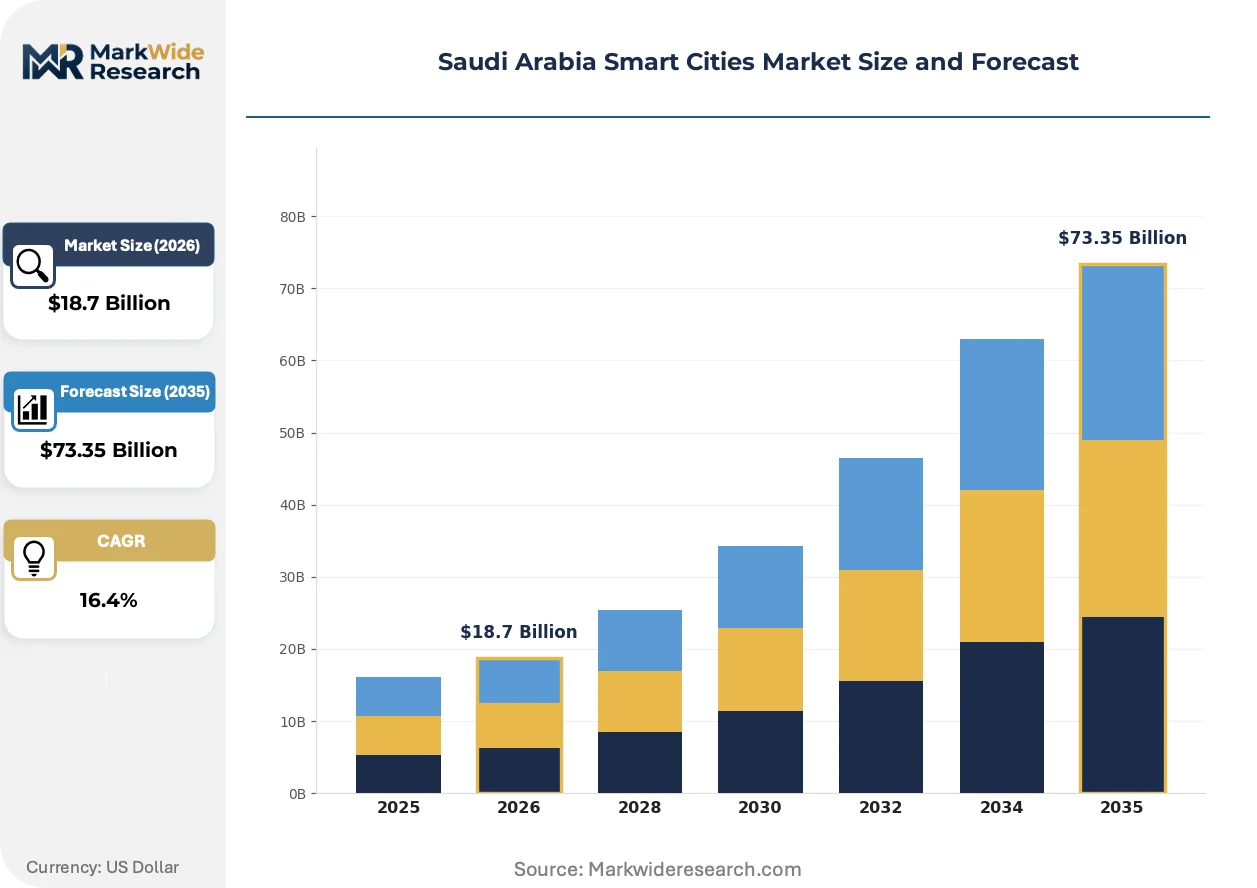
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, Cloud Computing, Big Data, Artificial Intelligence Application: Traffic Management, Waste Management, Energy Management, Security Systems End User: Government, Private Sector, Residents, Businesses Service Type: Consulting, Implementation, Maintenance, Integration |
| Companies Covered | Huawei Technologies Co., Ltd., Ericsson, Cisco Systems Inc., General Electric, Intel Corporation, Microsoft Corporation, AT&T, Inc., Schneider Electric SE, IBM Corporation, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Smart Cities Market Trends and Innovations
Edge-to-cloud orchestration architectures are displacing centralized data-lake models across municipal deployments, compressing latency for safety-critical applications while complicating vendor interoperability standards.
Digital twin platforms for urban infrastructure are converging with real-time sensor feeds from traffic, energy, and water systems. Riyadh Municipality and NEOM developers are deploying these systems at full-city scale rather than pilot zones. The technology is converging with predictive maintenance algorithms, shifting capital allocation from reactive repair toward preemptive asset replacement.
Saudi Communications and Information Technology Commission spectrum reallocations for private 5G networks are enabling dedicated municipal bandwidth slices. Industrial consequence includes bypassing public carrier dependency for critical infrastructure. Smart port and logistics zone operators in King Abdullah Economic City are securing these allocations fastest, insulating operations from congestion in commercial networks.
Outcome-based service contracting is displacing capital-purchase models for smart infrastructure. Municipal buyers now demand guaranteed uptime and efficiency metrics rather than hardware ownership. Riyadh and NEOM procurement frameworks embody this shift most visibly, with payment tied to operational performance rather than installation milestones.
Saudi Arabia Smart Cities Market Segmentation
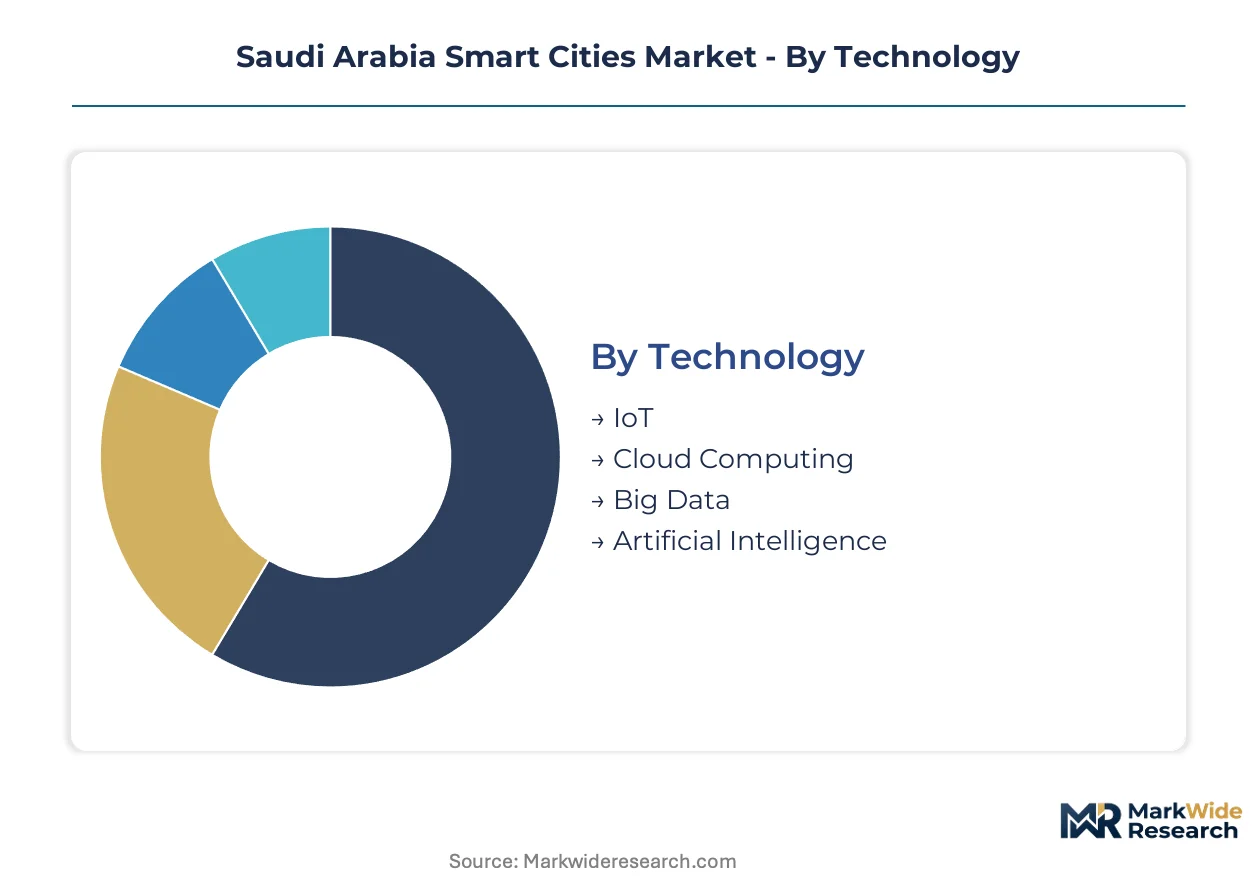
Smart city procurement in Saudi Arabia fragments across technology stacks, application domains, and service delivery models. Understanding these divisions reveals where sovereign capital concentrates and which vendor capabilities unlock contract access.
Technology:
Volume deployment concentrates in connectivity infrastructure, while premium margins attach to intelligence layers.
- Artificial Intelligence:Machine learning models optimize traffic prediction, energy load forecasting, and anomaly detection across municipal command centers. Riyadh Municipality and NEOM developers deploy computer vision for public safety and predictive maintenance, with demand accelerating as edge-computing latency thresholds tighten.
- Big Data:Centralized data platforms aggregate sensor feeds from traffic grids, utility networks, and environmental monitors into unified dashboards. Procurement in NEOM and King Abdullah Economic City prioritizes real-time analytics engines that correlate multi-source inputs for operational decision-making.
- IoT:Sensor networks for environmental monitoring, asset tracking, and infrastructure health monitoring form the physical layer of smart city architectures.
- Cloud Computing:Distributed storage and compute resources enable scalable processing of municipal data workloads without captive data center investment.
Mature deployment sits with IoT sensor networks. Newer deployment is concentrated in Artificial Intelligence inference engines.
Application:
Capital intensity varies sharply between greenfield installations and legacy retrofits.
- Energy Management:Smart grid orchestration layers integrate distributed solar microgrids, demand-response systems, and predictive load balancing across municipal power distribution. NEOM's linear city design embeds these systems from foundation, while Riyadh faces retrofit complexity with parallel-run requirements.
- Traffic Management:Adaptive signal control, congestion prediction algorithms, and connected vehicle infrastructure coordinate urban mobility. The Riyadh Metro integration and NEOM's autonomous mobility zones concentrate demand for real-time traffic orchestration platforms.
- Security Systems:Video analytics, access control, and emergency response coordination protect critical infrastructure and public spaces.
- Waste Management:Sensor-equipped bins, route optimization algorithms, and automated collection scheduling reduce municipal logistics costs.
Legacy grid constraints burden Energy Management retrofits. Steepest expansion trajectory belongs to Traffic Management as autonomous vehicle corridors multiply.
End User:
Sovereign buyers dominate procurement volume, but operational risk transfer shapes contract structures.
- Government:Municipal authorities, ministries, and giga-project developers specify platform requirements, allocate sovereign capital, and enforce localization mandates under Vision 2030. Riyadh Municipality, NEOM Company, and the Royal Commission for Al-Ula represent the deepest procurement pools.
- Private Sector:Real estate developers, logistics operators, and industrial zone managers purchase smart infrastructure as competitive differentiation. King Abdullah Economic City port operators deploy private 5G networks and digital twin platforms independent of municipal timelines.
- Residents:Citizen-facing applications for utility billing, transit payments, and service requests generate data inputs while demanding interoperability with government platforms.
- Businesses:Commercial tenants in smart districts consume building automation, energy optimization, and connectivity services as bundled amenities.
Contract standardization concentrates with Government buyers. Customization requirements expand most quickly in Private Sector deployments.
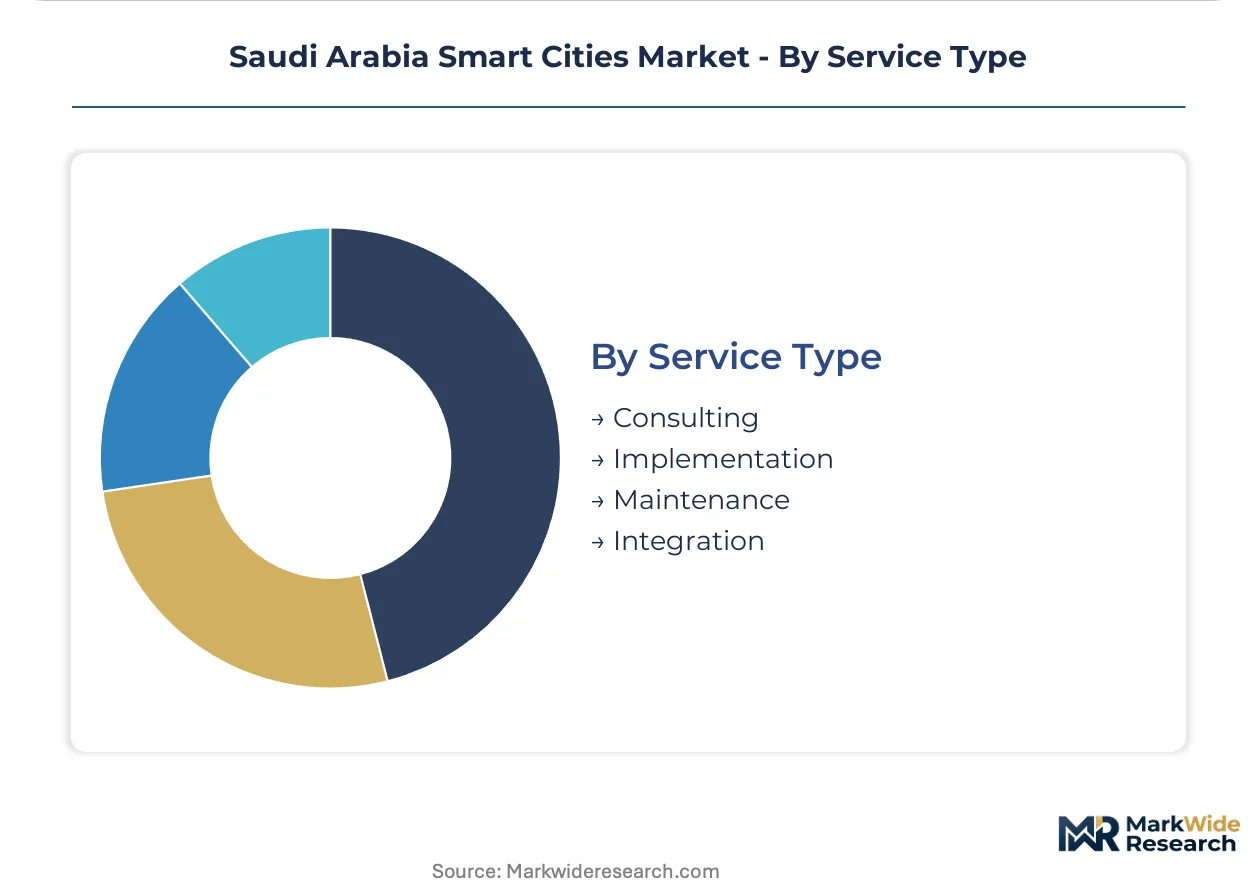
Service Type:
Revenue recognition shifts from milestone-based installation to performance-guaranteed operations.
- Implementation:System integration, hardware deployment, and software configuration deliver functional infrastructure. NEOM and Riyadh procurement frameworks now tie implementation payments to operational acceptance criteria rather than installation completion.
- Maintenance:Long-term service contracts guarantee uptime, security patching, and hardware refresh cycles. Outcome-based pricing with efficiency guarantees displaces fixed-fee arrangements in municipal tenders.
- Consulting:Strategy definition, vendor selection, and regulatory compliance advisory precede capital deployment.
- Integration:API development and multi-vendor stack harmonization resolve interoperability gaps between Huawei, Schneider, and Cisco deployments.
Margin compression hits Consulting as procurement standardizes. Maintenance contracts extending to 10-15 year terms capture the fastest-growing revenue pool.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Smart city investment concentrates in Riyadh and the NEOM corridor, with secondary metros emerging as procurement frameworks mature. Vision 2030 mandates channel sovereign capital toward integrated command centers and IoT backbone deployment.
Riyadh
The capital anchors national smart infrastructure deployment through the Riyadh Metro integration and municipal command center buildout. The Saudi Communications and Information Technology Commission allocates private 5G spectrum for critical urban systems. King Abdullah Financial District hosts dense sensor networks for traffic orchestration and energy load balancing.
Eastern Province
Industrial zone operators in Dammam and Jubail deploy private networks for port automation and logistics optimization. The Ministry of Municipal and Rural Affairs and Housing mandates interoperability standards for new district developments. King Abdullah Economic City advances digital twin platforms for maritime and supply chain infrastructure.
Western Region
Jeddah's coastal redevelopment drives demand for flood monitoring and coastal resilience systems alongside conventional smart city stacks. The National Water Company integrates sensor networks for distribution leak detection. The Jeddah Economic City development embeds building automation and microgrid orchestration from foundation.
NEOM Northwest
The linear city's phased construction creates concentrated procurement windows for autonomous mobility corridors and integrated utility platforms. NEOM Company enforces localization requirements that reshape vendor partnership structures. THE LINE and Oxagon developments deploy city-scale digital twins rather than pilot-zone implementations.
Saudi Arabia Smart Cities Market Competitive Landscape
Strategic partnerships dominate the current landscape as foreign technology providers align with local entities to meet Saudization and localization mandates. The supplier base fragments across three distinct capability stacks rather than consolidating around end-to-end platforms. Chinese infrastructure vendors, European energy specialists, and North American network security firms represent the primary strategic archetypes. Joint ventures and technology licensing agreements outpace outright acquisitions as the preferred market entry mechanism.
Within the infrastructure stack, Huawei Technologies Co., Ltd. and Ericsson occupy positions shaped by 5G-to-cloud integration capabilities. Cisco Systems Inc. anchors the secure networking tier alongside Schneider Electric SE, which exemplifies the energy-management specialization vector. These four entities collectively represent the vendor mix most frequently qualified for giga-project procurement frameworks.
| Leading Market Players |
|---|
| Huawei Technologies Co., Ltd. |
| Ericsson |
| Cisco Systems Inc. |
| General Electric |
| Intel Corporation |
| Microsoft Corporation |
| AT&T, Inc. |
| Schneider Electric SE |
| IBM Corporation |
| Others |
Pricing and Supply Chain Analysis
Scarce edge-computing architects in Riyadh and the Eastern Province widen labor-cost spreads between premium-tier system integrators and economy-focused hardware resellers. This workforce concentration compresses margins at the mid-market tier while pushing sovereign buyers toward bundled service contracts that internalize technical risk.
Pricing Analysis
Warranty and long-term maintenance bundling separates qualified vendors from commodity hardware suppliers in municipal procurement frameworks. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth under NCA cybersecurity mandates and Saudization compliance tiers. Cost compression in the economy tier is intensifying because sensor commoditization erodes hardware margins faster than software value-adds accumulate. Government buyers at NEOM and Riyadh Municipality demonstrate lowest price sensitivity due to sovereign capital availability, while private-sector real estate developers in secondary cities negotiate hardest on upfront capital expenditure.
Supply Chain Analysis
Freight cost volatility from East Asian semiconductor hubs through Jeddah Islamic Port inflates landed costs for edge-computing chipsets and 5G infrastructure components. Manufacturing concentration in China, South Korea, and Taiwan feeds the Kingdom's deployment timelines for IoT sensors, network equipment, and centralized data platforms. Single-source vulnerability around advanced node semiconductors exposes NEOM construction phases to allocation rationing during geopolitical stress. Distribution runs through authorized local partners holding CITC import licenses, with direct vendor relationships reserved for giga-project developers meeting minimum contract thresholds.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Edge-computing talent scarcity props pricing power for qualified system integrators, constraining rapid scale-up by unproven entrants. This supply-constrained dynamic favors incumbents with captive workforce development pipelines.
For Market Incumbents: Acquire specialized cybersecurity certification capabilities to preempt NCA compliance bottlenecks that delay competitor onboarding. Deepen backward integration into localized software development to offset Saudization workforce gaps and defend margin position against emerging Chinese platform vendors undercutting on bundled hardware-software pricing. For New Entrants and Emerging Players: The premium-to-economy price-point gap in AI-powered traffic management systems offers entry leverage for mid-tier vendors with modular, API-first architectures. Target Abha and Dammam municipal authorities where procurement standardization lags Riyadh and first-mover qualification windows remain open. Lead with outcome-based pilot contracts that transfer operational risk from cash-constrained secondary-city buyers. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated platform vendors given NEOM's phased construction pulling forward multi-year service contract visibility. Acquisition focus should center on Saudi-registered system integrators holding active CITC and NCA certifications. Monitor King Abdullah Economic City port operator procurement announcements as inflection signals for private 5G network demand scaling beyond sovereign projects.| Strategic Initiative | Industry Significance |
|---|---|
| Localization Joint Venture Formation | Saudization mandates under Vision 2030 require foreign vendors to transfer operational control to Saudi-registered entities. |
| Outcome-Based Service Contracting | Riyadh Municipality and NEOM now tie vendor payments to guaranteed uptime and efficiency metrics rather than installation milestones. |
| Edge-to-Cloud Platform Integration | Latency-sensitive safety applications favor distributed architectures over centralized data-lake models in municipal deployments. |
| Private 5G Spectrum Acquisition | CITC allocations for dedicated municipal bandwidth bypass public carrier dependency in critical infrastructure zones. |
| Cybersecurity Certification Pre-Investment | NCA and MOHAP compliance timelines extend vendor onboarding by 8-14 months, creating first-mover advantages for pre-qualified suppliers. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with smart city project directors, CITC licensing officers, municipal procurement managers, and systems integration engineers cross-validated deployment timelines and contract structures. Saudi Customs import records, CITC spectrum allocation databases, and Vision 2030 giga-project disclosure documents supplemented bottom-up vendor qualification tracking with top-down capital flow estimates.
Reconciliation of hardware shipment data, sovereign budget allocations, and vendor contract announcements shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include technology stack tier, application domain, end-user archetype, and service delivery model. CAGRs were derived from curve-fitting historical deployment velocities against announced giga-project completion targets, with explicit modeling of NCA certification bottlenecks and semiconductor supply constraints as dampening inputs.
Inputs from CITC, NCA, and municipal procurement offices were available through the study window; gaps in real-time contract value disclosure introduce uncertainty bands around vendor market share estimates. Forecasts reflect documented assumptions regarding NEOM construction phasing, Saudization enforcement intensity, and East Asian semiconductor supply stability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
Global Smart/Connected Street Lights Market
Smart City Technology
Smart Parking Meters Market
Smart City Technology
Smart Ticketing Solutions Market
Smart City Technology
Global Smart City ICT Infrastructure Market
Smart City Technology
Smart Parcel Locker Market
Smart City Technology
Global Smart Pole Market
Smart City Technology
Global Smart Hubs Market
Smart City Technology
Smart City Kiosk Market
Smart City Technology
Smart City Kiosk Deployment Market
Smart City Technology
Smart Package Lockers Market
Smart City Technology
Smart Street Lights Market
Smart City Technology
Smart City Platform Market
Smart City Technology
City Data Platform Market
Smart City Technology
UAE Smart Furniture Market
Smart City Technology
India Smart City Market
Smart City Technology
Smart Mailbox Market