
 Smart Parcel Locker Market | 2026-2036
Smart Parcel Locker Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Parcel Locker Market Intelligence
Chinese steel and electronics clusters is repositioning smart locker chassis production toward higher-grade, weather-resistant alloys. Cleveron leverages its Estonian engineering base to dominate cold-climate outdoor locker specifications. Parcel Pending by Quadient anchors its position through retail integration partnerships across British and French supermarket chains. DHL competes on last-mile density, operating proprietary locker networks that bypass third-party infrastructure.
A smart parcel locker is a networked, self-service storage unit equipped with electronic access control, typically featuring IoT sensors, cloud-connected management software, and modular cell configurations ranging from small envelope slots to large parcel bays. These systems automate secure handoff between logistics providers and recipients, eliminating failed delivery attempts and reducing courier redelivery costs. Outdoor lockers lead volume deployment due to their 24/7 accessibility and minimal real estate overhead, while modular locker systems represent the fastest-growing product type as operators reconfigure cell arrays to match shifting parcel size distributions. Cloud-based management technology concentrates margin pools through recurring software subscriptions and remote diagnostics, displacing simpler on-premise access models.
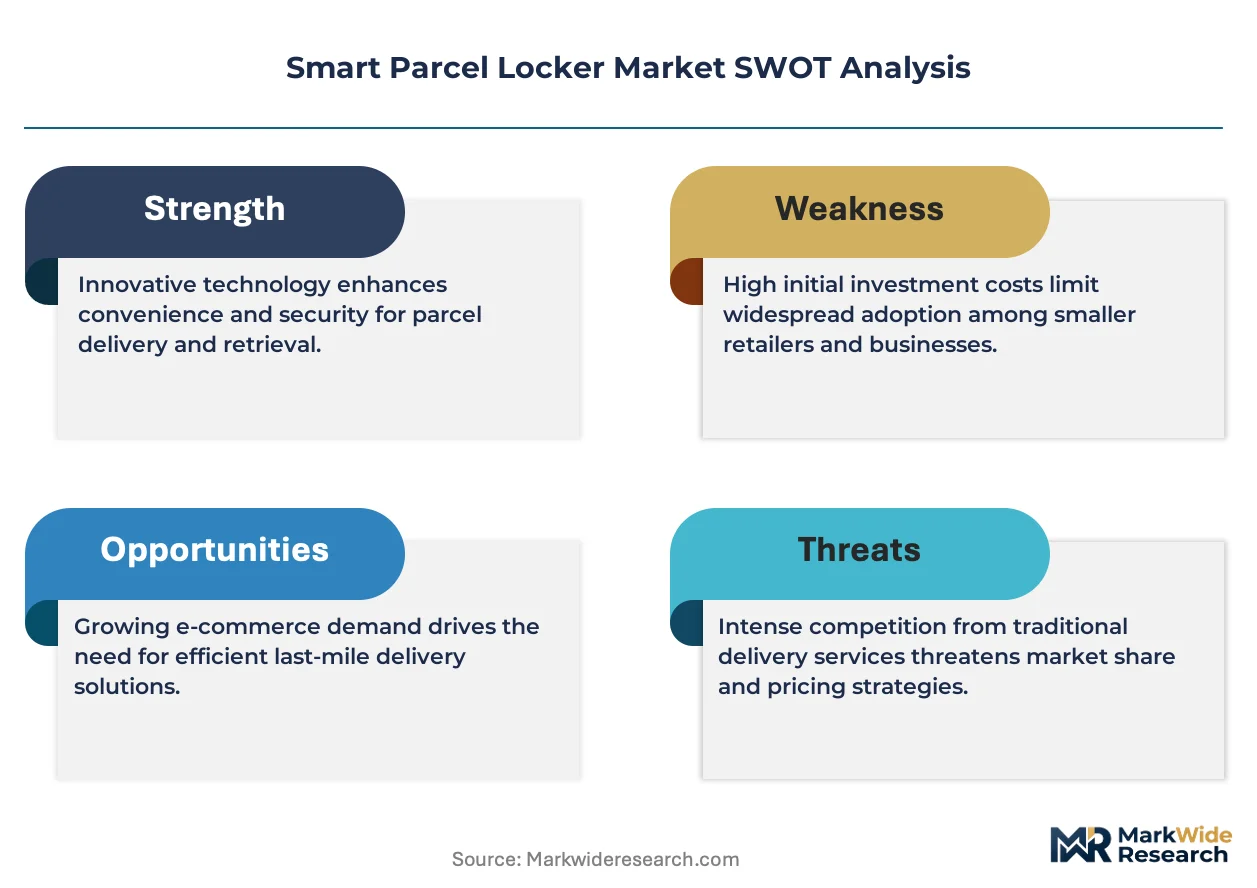
FCC certification governs wireless communication modules in US-deployed units, while CE marking and the EU AI Act shape automated access and data handling protocols across European installations. GDPR compliance adds cost complexity to cloud-based management platforms processing recipient identity and delivery data. Stakeholders must weigh hardware durability standards against software interoperability requirements as carrier-neutral networks displace single-operator locker estates.
Market Dynamics
Carrier-neutral locker networks are displacing single-operator estates as logistics providers seek interoperability and urban real estate efficiency.
Growth Catalysts
- E-commerce fulfillment density:Online retailers deploy lockers at apartment complexes and transit hubs to eliminate failed delivery attempts. Germany's dense urban networks accelerate this deployment pattern.
- EU Green Deal mandates:The framework pushes logistics operators toward low-carbon last-mile infrastructure. Smart lockers reduce courier vehicle kilometers through consolidated drop points.
- Cloud-based management platforms:IoT-connected software enables remote diagnostics and recurring subscription revenue. Operators favor these over simpler on-premise access models.
Market Restraints
- Steel alloy input volatility:Weather-resistant chassis alloys face price swings from Chinese production clusters. This squeezes hardware margins for outdoor locker specifications.
- GDPR compliance cost complexity:Cloud platforms processing recipient identity data incur legal and technical overhead. European operators bear disproportionate compliance burdens.
- Real estate access constraints:Prime urban locations command premium lease terms. Municipal zoning in dense cities limits 24/7 outdoor installation permits.
Strategic Opportunities
- Modular cell reconfiguration:Operators retrofit locker arrays to match shifting parcel size distributions. This flexibility captures oversized e-commerce volumes.
- Retail integration partnerships:Supermarket chains host lockers as foot traffic drivers. British and French grocery networks expand pilot programs.
- CE marking convergence with EU AI Act:Automated access protocols gain regulatory clarity. Manufacturers align biometric and sensor systems to unified standards.
Industry Challenges
- FCC certification timelines:Wireless communication modules in US-deployed units face lengthy approval cycles. Hardware launches stall on electromagnetic compliance testing.
- Legacy carrier system integration:Neutral locker networks must interface with proprietary DHL, FedEx, and national post operator APIs. Middleware development consumes engineering resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Parcel Locker Market |
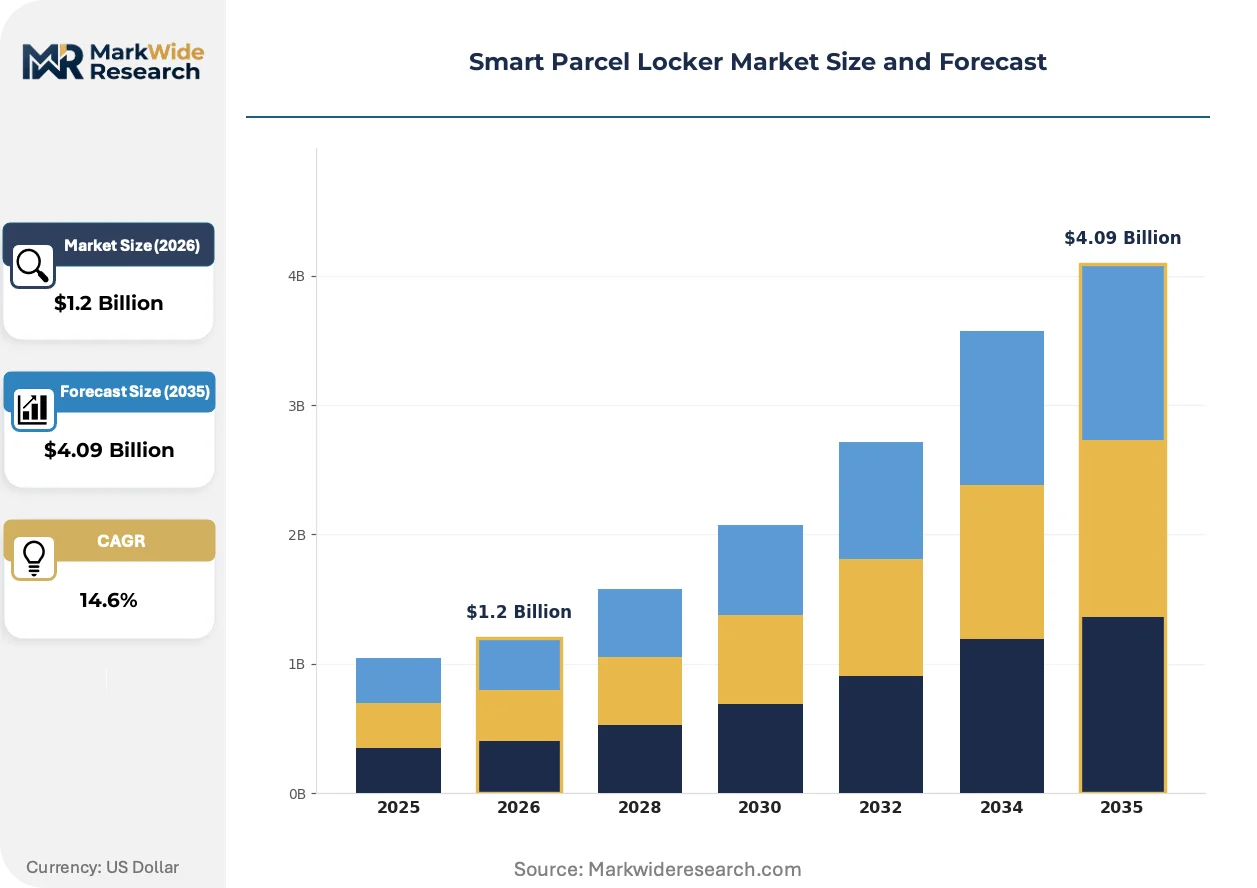
| Market Size in 2026 | $1.2 Billion |
| Market Size in 2035 | $4.09 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Indoor Lockers, Outdoor Lockers, Modular Lockers, Smart Locker Systems Deployment: Self-Service Systems, Smart Community Solutions, Retail Integrations, Last-Mile Delivery End User: E-commerce Retailers, Logistics Providers, Urban Communities, Universities Technology: IoT Integration, Cloud-Based Management, Mobile App Access, Real-Time Tracking |
| Companies Covered | Cleveron, XBP Global, Velocity Smart Technology, Smartbox Group, Locker4Rent, Parcel Pending by Quadient, Omnic, DHL, InPost, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Parcel Locker Market Strategic Shifts & Innovations
Solar-powered locker units with integrated battery storage are reshaping deployment economics for off-grid locations and sustainability commitments.
Photovoltaic roof panels paired with lithium-ion battery packs are electrifying outdoor locker energy autonomy. Logistics operators in sun-belt regions adopt these units to eliminate grid connection costs. The technology is electrifying remote deployment feasibility while compressing payback periods for rural last-mile nodes.
The EU AI Act imposes transparency requirements on automated access systems using biometric or behavioral verification. Locker manufacturers must document algorithmic decision logic for regulatory audits. Cold-climate specifications in Estonia and Nordic markets face additional scrutiny on facial recognition data retention protocols.
Buyer procurement is consolidating around carrier-agnostic network access rather than single-operator locker subscriptions. Third-party logistics providers negotiate multi-carrier API access as a standard contract term. This preference shift concentrates purchasing power among large e-commerce platforms in Germany and the Netherlands.
Smart Parcel Locker Market Segmentation
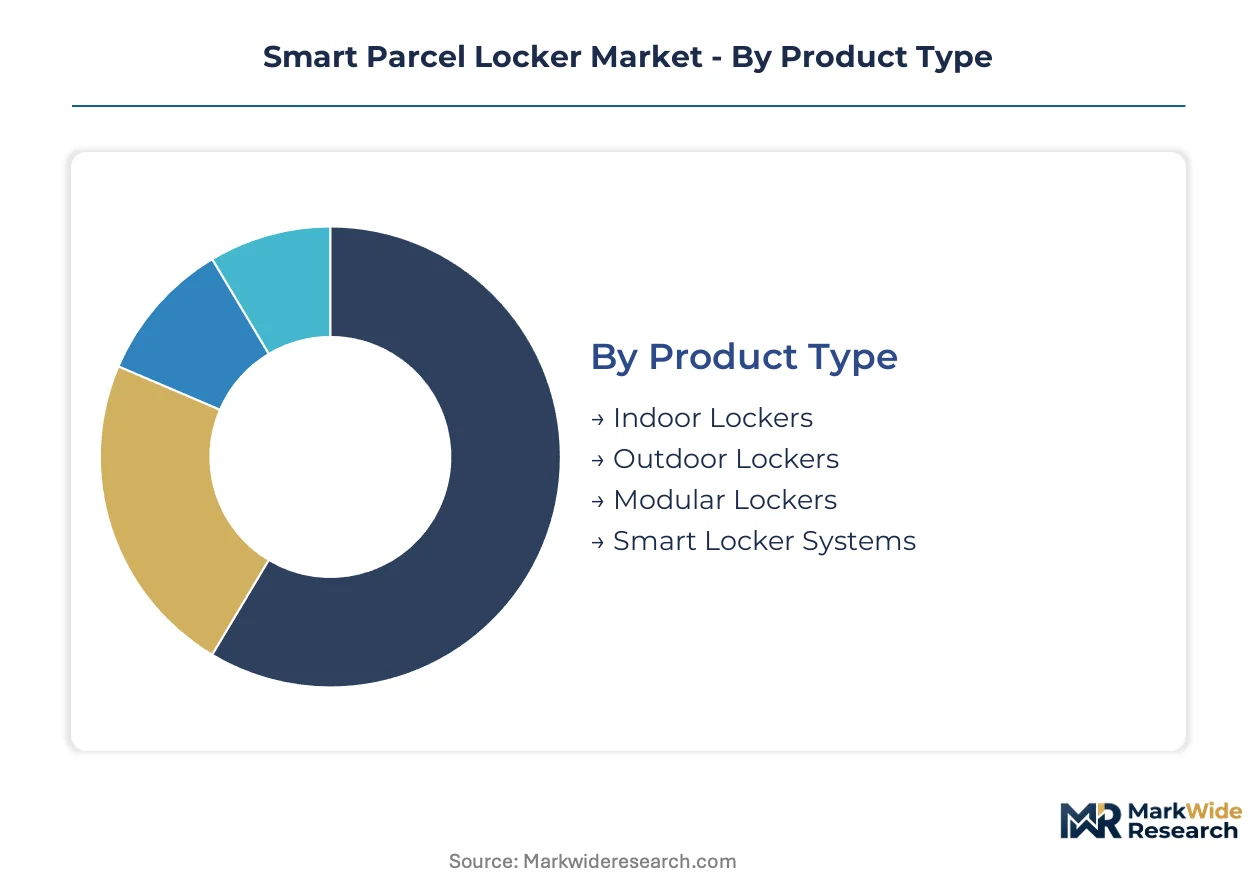
Smart parcel locker segmentation reveals how hardware durability, software architecture, and deployment context determine procurement patterns. Operators select product configurations based on real estate constraints, carrier interoperability requirements, and recipient access preferences.
Product Type:
Integration depth separates standalone outdoor installations from embedded indoor systems requiring building infrastructure coordination.
- Indoor Lockers:Climate-controlled units with reduced weatherproofing specifications integrate into apartment lobbies and retail backrooms. German residential developers specify these for new-build logistics rooms to minimize outdoor footprint.
- Outdoor Lockers:Weather-resistant chassis with IP-rated enclosures and heating elements enable 24/7 street-level deployment. Nordic operators prioritize these for year-round accessibility despite snow load and temperature cycling.
- Modular Lockers:Cell arrays reconfigure to match parcel size distributions without full hardware replacement.
- Smart Locker Systems:Turnkey platforms bundle hardware, software, and maintenance under unified service contracts.
Outdoor Lockers lead volumes today; Modular Lockers are gaining share fastest.
Deployment:
Cost tier separates capital-intensive infrastructure builds from operational expenditure models favoring third-party hosting.
- Self-Service Systems:Standalone terminals with minimal staff intervention reduce operating overhead. British supermarket chains deploy these in parking lots to capture foot traffic without interior floor space commitment.
- Smart Community Solutions:Multi-tenant networks serve residential complexes with shared access protocols. French property managers favor these to consolidate carrier deliveries into single logistics points.
- Retail Integrations:Locker banks embedded within store footprints drive cross-shopping behavior.
- Last-Mile Delivery:Carrier-operated nodes optimize courier route density.
Retail Integrations lead volumes today; Smart Community Solutions are climbing the fastest.
End User:
Application focus distinguishes volume-driven logistics operators from experience-focused residential developers.
- E-commerce Retailers:Platform operators deploy proprietary networks to control fulfillment branding and return logistics. German online marketplaces anchor the largest captive locker estates in Europe.
- Logistics Providers:DHL and national post operators build density to bypass third-party infrastructure access fees.
- Urban Communities:Municipal procurement emphasizes carrier-neutral access and public space integration.
- Universities:Campus operators prioritize centralized distribution to reduce dormitory mailroom staffing.
Logistics Providers lead volumes today; E-commerce Retailers are expanding most quickly.
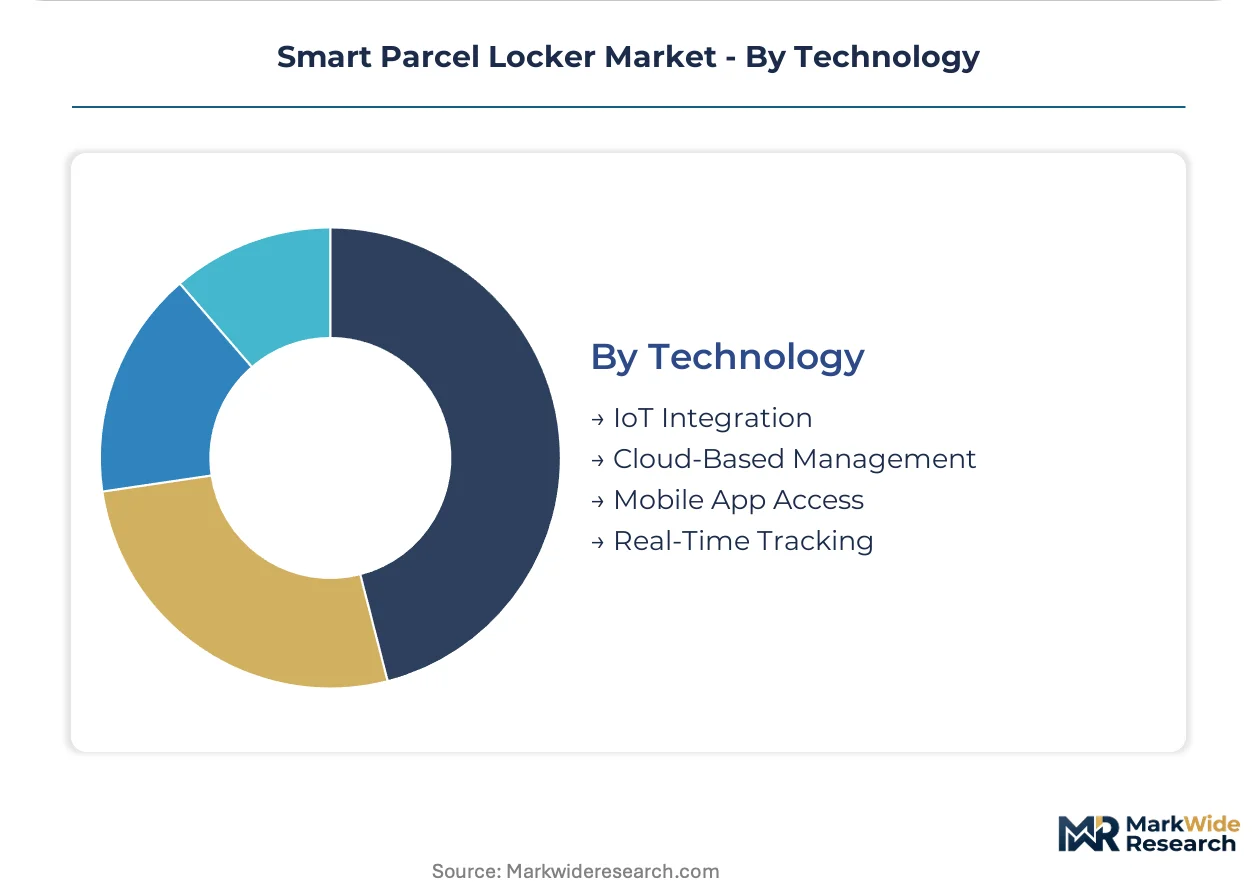
Technology:
Margin concentration favors recurring software revenue over one-time hardware sales.
- IoT Integration:Sensor networks monitor door status, temperature, and occupancy for predictive maintenance. Estonian manufacturers embed these modules to support remote diagnostics across dispersed Nordic installations.
- Cloud-Based Management:Centralized platforms enable real-time reconfiguration and subscription billing. GDPR compliance costs burden European operators processing recipient identity data.
- Mobile App Access:Smartphone authentication replaces PIN codes and QR scanning.
- Real-Time Tracking:Parcel location visibility integrates with carrier dispatch systems.
Cloud-Based Management leads volumes today; IoT Integration shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory divergence between GDPR-heavy European markets and lighter-touch Asian jurisdictions is shifting smart locker software development toward modular compliance architectures. Hardware production migrates toward steel and electronics clusters where weather-resistant alloy specifications align with cold-climate deployment demand.
Germany
Dense urban logistics networks and carrier-neutral procurement policies accelerate locker deployment across residential and retail nodes. The EU Green Deal mandates low-carbon last-mile infrastructure, consolidating drop-point networks to reduce courier vehicle kilometers. North Rhine-Westphalia hosts the continent's densest locker concentration, with DHL operating proprietary estates that bypass third-party access fees.
United States
E-commerce fulfillment density drives apartment complex and transit hub installations to eliminate failed delivery attempts. FCC certification timelines for wireless communication modules stall hardware launches on electromagnetic compliance testing. The Southeast sun-belt corridor adopts solar-powered units with integrated battery storage to eliminate grid connection costs for rural last-mile nodes.
China
Steel and electronics clusters reposition chassis production toward higher-grade, weather-resistant alloys for export specifications. National dual carbon goals push logistics operators toward energy-efficient delivery infrastructure standards. The Yangtze River Delta manufacturing belt concentrates smart locker component supply, with Shenzhen-based producers anchoring IoT module integration.
Estonia
Cold-climate engineering specialization dominates outdoor locker specifications for Nordic and Baltic deployment. GDPR compliance cost complexity burdens cloud-based management platforms processing recipient identity data. Tallinn anchors engineering development for facial recognition data retention protocols under EU AI Act transparency requirements.
United Kingdom
Retail integration partnerships with supermarket chains drive foot traffic through parking lot locker banks. CE marking convergence with automated access standards gains regulatory clarity for biometric sensor systems. Greater London concentrates carrier-neutral network procurement, with third-party logistics providers negotiating multi-carrier API access as standard contract terms.
Smart Parcel Locker Market Key Industry Players
Chinese producers anchor one tier; European specialists hold another through cold-climate engineering differentiation. The vendor base splits between scale-driven logistics operators building captive networks and modular hardware fabricators serving carrier-neutral deployments. Three archetypes dominate: proprietary carrier networks, retail-integrated platform providers, and component-specialist chassis manufacturers. Competitive moves concentrate on retail partnership expansion and solar-battery hardware differentiation.
Within the retail-integrated tier, Parcel Pending by Quadient and Smartbox Group exemplify supermarket-hosted deployment models. Cleveron occupies a position among cold-climate engineering specialists, with its Estonian base supporting Nordic specification dominance. DHL anchors the proprietary carrier network archetype, operating captive locker estates that bypass third-party infrastructure access entirely.
| Leading Market Players |
|---|
| Cleveron |
| XBP Global |
| Velocity Smart Technology |
| Smartbox Group |
| Locker4Rent |
| Parcel Pending by Quadient |
| Omnic |
| DHL |
| InPost |
| Others |
Cost & Logistics Intelligence
Carrier-neutral procurement mandates from German e-commerce platforms are forcing chassis manufacturers toward standardized, multi-carrier compatible designs that compress hardware margins while elevating software subscription premiums.
Pricing Analysis
Distributor margins on outdoor locker hardware have compressed as Chinese steel clusters compete on weather-resistant alloy specifications. Pricing stratifies across CE-marked biometric tiers, FCC-certified wireless modules, and basic PIN-code access systems, with cloud-based management platforms capturing recurring SaaS premiums. Cost compression in cold-climate specifications intensifies as Estonian engineering specialists defend Nordic market positions. Municipal buyers in dense urban zones exhibit highest price sensitivity, while logistics operators prioritize interoperability over unit cost.
Supply Chain Analysis
Workforce availability in Yangtze River Delta electronics clusters and Shenzhen IoT module facilities anchors smart locker component supply. Chassis production draws from Chinese steel alloy capacity, Estonian cold-climate engineering specialization, and German final assembly integration. Single-source vulnerability concentrates in lithium-ion battery packs for solar-powered units. Distribution runs through carrier-neutral network operators and retail integration partners rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in smart parcel lockers hinges on software subscription capture and modular cell reconfiguration services that offset hardware commoditization pressures.
For Market Incumbents: Anchor cloud-based management platform dominance through GDPR-compliant data architectures that neutralize compliance cost burdens on European operators. Defend against emerging retail integration specialists by deepening carrier-neutral API standardization. Prioritize backward integration into solar-battery power systems for off-grid deployment economics. For New Entrants and Emerging Players: Enter via white-space opportunities in French and British supermarket parking lot deployments where foot traffic conversion remains underexploited. Target smart community solutions in North Rhine-Westphalia residential developments where carrier-neutral procurement policies favor new network operators. Pursue white-label hardware supply to e-commerce platforms seeking captive locker branding control. For Investors and Strategic Acquirers: Asymmetric upside sits with modular hardware fabricators possessing CE marking convergence capabilities under EU AI Act transparency requirements. Five-to-ten year viability favors specialists integrating biometric access with automated retail fulfillment workflows. Monitor solar-powered locker adoption rates in US Southeast sun-belt corridors as inflection signal for rural last-mile node economics.| Strategic Initiative | Industry Significance |
|---|---|
| Carrier-Neutral API Standardization | DHL proprietary network bypass creates interoperability demand from German logistics operators. |
| Solar-Battery Hardware Integration | Photovoltaic roof panels eliminate grid connection costs for US Southeast rural deployments. |
| Retail Integration Partnership | British and French supermarket chains convert parking lot space into foot traffic drivers. |
| GDPR-Compliant Cloud Platform | EU AI Act transparency requirements burden competitors without Estonian engineering bases. |
| Modular Cell Reconfiguration Service | Parcel size distribution shifts in e-commerce drive retrofit demand without full replacement. |
Research Approach
Direct dialogue with logistics procurement directors, smart locker OEM engineering leads, retail integration partnership managers, and EU regulatory compliance officers grounded qualitative findings. Secondary validation drew from carrier network deployment disclosures, CE marking certification databases, FCC equipment authorization filings, and municipal zoning permit records. Bottom-up unit economics triangulated against top-down market sizing across hardware, software, and service revenue streams.
Top-down macroeconomic drivers combined with bottom-up carrier deployment density metrics across the projection horizon. Segmentation modeling incorporated product type durability tiers, deployment model capital intensity, end-user procurement centralization, and technology stack margin concentration. CAGRs derived from logistic operator capex cycle analysis and e-commerce fulfillment infrastructure buildout trajectories. Solar-battery adoption curves and GDPR compliance cost trajectories informed regional divergence assumptions.
Inputs from carrier network operators and retail chain procurement committees were available through the study window; gaps in proprietary DHL and InPost deployment economics introduce uncertainty bands around proprietary network estimates. Forecasts assume sustained EU Green Deal enforcement and stable Chinese steel alloy input availability. Material deviation in FCC certification timeline delays or municipal zoning permit restrictions warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
Smart Parcel Delivery Locker Market
Smart City Technology
Smart Parking Meters Market
Smart City Technology
Global Smart Hubs Market
Smart City Technology
Smart City Framework Market
Smart City Technology
City Data Platform Market
Smart City Technology
Global Smart Ticketing Market
Smart City Technology
Saudi Arabia Smart Cities Market
Smart City Technology
Smart Street Lights Market
Smart City Technology
Smart City Kiosk Market
Smart City Technology
Smart City Kiosk Deployment Market
Smart City Technology
Singapore ICT Market
Smart City Technology
Global Smart Pole Market
Smart City Technology
Global Smart City Market
Smart City Technology
Smart Shade Device Market
Smart City Technology
India Smart City Market
Smart City Technology
Smart Ticketing Solutions Market