
 Smart Street Lights Market | 2026-2036
Smart Street Lights Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Street Lights Market Outlook
Embedded systems engineering talent is rotating toward urban IoT platforms, unlocking design velocity for networked luminaires. Signify leverages its Amsterdam-based R&D campus to sustain proprietary light-management protocols across European deployments. Acuity Brands anchors North American municipal contracts through vertical integration into LED driver manufacturing. Telensa competes on narrowband RF mesh density, dominating utility-scale streetlight networks in the United Kingdom.
Smart street lights are networked luminaire assemblies integrating solid-state lighting, environmental sensors, and two-way communication modules to enable remote dimming, fault detection, and data collection for urban analytics. The primary commercial purpose is reducing municipal energy expenditure while generating real-time operational intelligence for traffic, air quality, and public safety applications. LED product type occupies the dominant revenue share due to retrofit economics and lumen-per-watt superiority over legacy sodium vapor. IoT technology leads growth velocity as municipalities demand edge-computing capability and API interoperability with broader urban digital twins. Installation via retrofit commands the largest project pipeline, since existing pole infrastructure minimizes civil works cost and permitting burden.
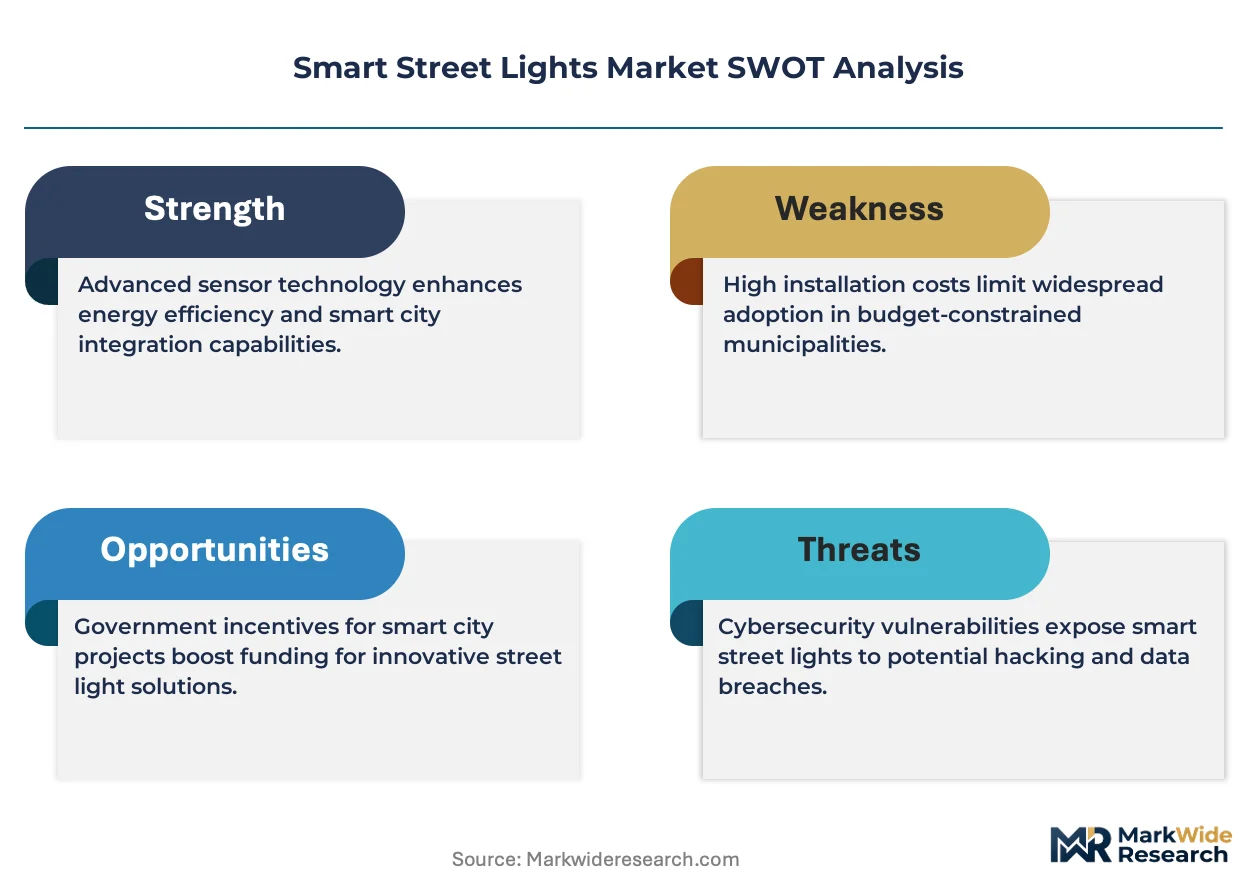
The Federal Communications Commission shapes spectrum allocation for streetlight-mounted small cells and IoT backhaul in the United States, while the EU Green Deal and associated CSRD reporting obligations pressure municipalities to document carbon reduction from lighting upgrades. India's Bureau of Energy Efficiency mandates minimum performance standards for LED street lighting under its domestic labeling program, constraining import eligibility. Stakeholders must monitor how evolving cybersecurity certification requirements for critical infrastructure IoT will reshape vendor qualification timelines and procurement specifications.
Market Dynamics
Municipal procurement cycles are compressing as legacy sodium vapor infrastructure reaches end-of-life simultaneously across multiple continents, forcing cities to choose between one-for-one LED retrofits and full IoT-enabled platform deployments.
Growth Catalysts
- EU Green Deal CSRD reporting:European municipalities must document carbon reduction from lighting upgrades, accelerating replacement timelines and favoring connected systems with embedded metering.
- India Smart Cities Mission:Central government funding mandates intelligent infrastructure in 100 urban centers, creating standardized procurement templates for networked luminaires.
- Edge computing capability:On-pole processing power enables real-time traffic and air quality analytics without cloud dependency, expanding the addressable use case beyond illumination.
Market Restraints
- Semiconductor supply concentration:LED driver ICs and RF communication modules depend on concentrated East Asian foundry capacity, exposing project timelines to single-source vulnerability.
- Copper and aluminum price volatility:Pole-mounted enclosures and heat sinks consume significant base metal tonnage, compressing margins when commodity markets spike.
- Legacy electrical codes:Municipal permitting departments in older US cities enforce arcane streetlight wiring standards that conflict with modern low-voltage IoT architectures.
Strategic Opportunities
- Indonesia's 100 Smart Cities initiative:Jakarta and Surabaya are piloting integrated urban platforms where streetlight networks serve as the primary IoT backbone for flood monitoring and traffic management.
- Small cell densification:5G network operators seek neutral-host pole infrastructure, creating recurring lease revenue streams for municipalities that deploy multi-tenant capable luminaires.
- EU F-Gas Regulation phase-down:Restrictions on high-GWP refrigerants in outdoor equipment indirectly favor solid-state lighting thermal management solutions over legacy systems requiring active cooling.
Industry Challenges
- Embedded firmware security certification:Critical infrastructure IoT cybersecurity standards are proliferating without harmonization, forcing vendors to pursue redundant country-specific approvals.
- Interoperability protocol fragmentation:Proprietary light-management systems from dominant vendors resist integration with third-party urban digital twin platforms, locking municipalities into single-source dependencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Street Lights Market |
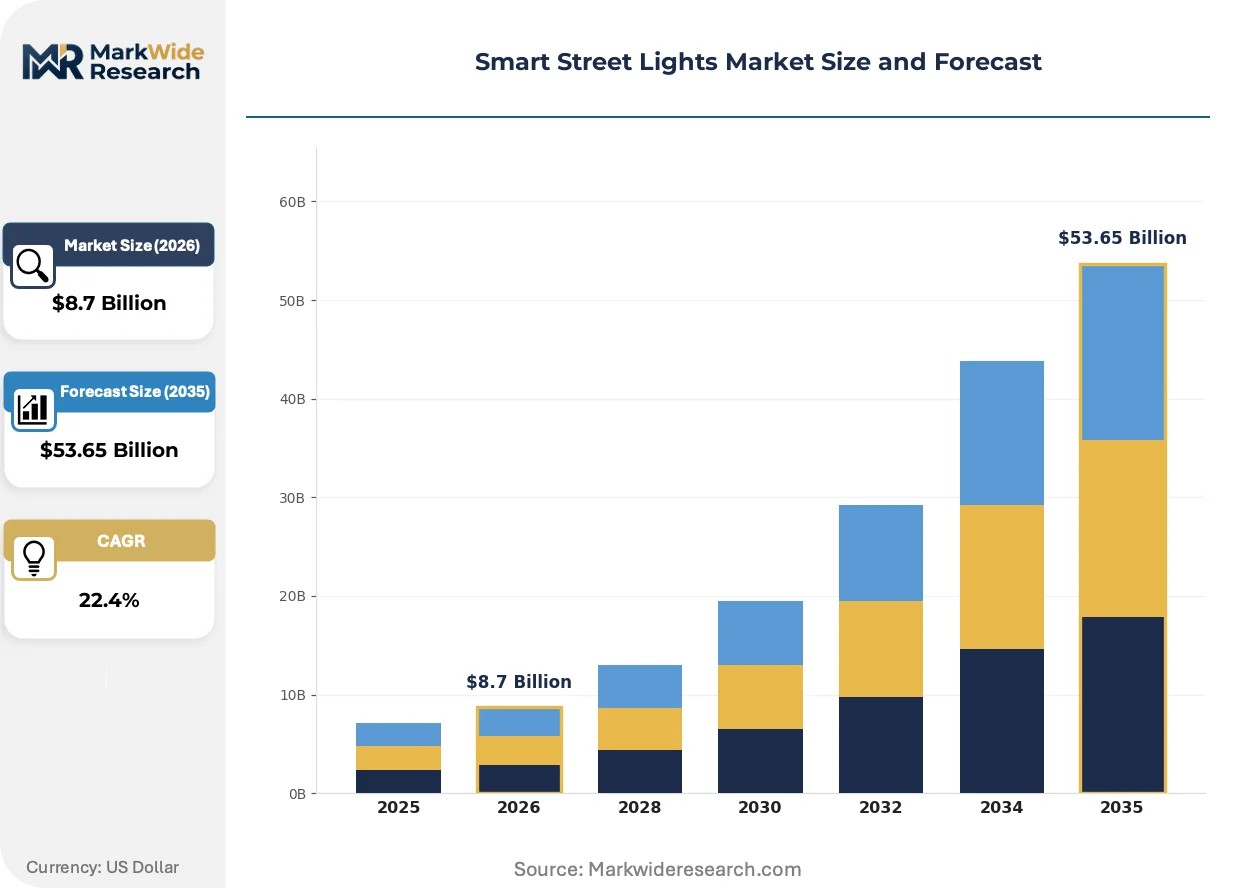
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $53.65 Billion |
| CAGR (2026 – 2036) | 22.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Solar, Traditional, Hybrid Technology: IoT, Wireless, Adaptive, Smart Sensors End User: Municipalities, Private Sector, Urban Planners, Transport Authorities Installation: New Installation, Retrofit, Upgrade, Maintenance |
| Companies Covered | Philips Lighting, Hubbell, Signify, GE Current, Cree Lighting, Acuity Brands, Eaton, Telensa, Schneider Electric, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Street Lights Market Strategic Shifts
Active optical networking and software-defined lighting control are converging to transform streetlights from passive illumination assets into programmable urban computing nodes. This shift demands new competencies from electrical contractors and municipal engineering departments alike.
Li-Fi visible light communication is supplanting narrowband RF mesh as the preferred backhaul technology for dense urban deployments. Singapore's Land Transport Authority is piloting vehicle-to-infrastructure data exchange through modulated LED streetlight arrays. This technology is compressing latency for autonomous traffic signal coordination while eliminating spectrum licensing costs.
The FCC's 2023 spectrum reallocation for unlicensed 6 GHz Wi-Fi is forcing streetlight-mounted small cell providers to redesign radio configurations. Equipment vendors must now certify dual-band architectures that avoid interference with municipal Wi-Fi networks. North American deployments are absorbing eighteen-month hardware redesign cycles as a consequence.
Municipal finance departments are bundling streetlight upgrades with performance guarantees from energy service companies. Brazilian cities including São Paulo now contract luminaire-as-a-service models where private operators retain ownership and monetize sensor data. This structure transfers technology obsolescence risk away from constrained public balance sheets.
Smart Street Lights Market Segmentation
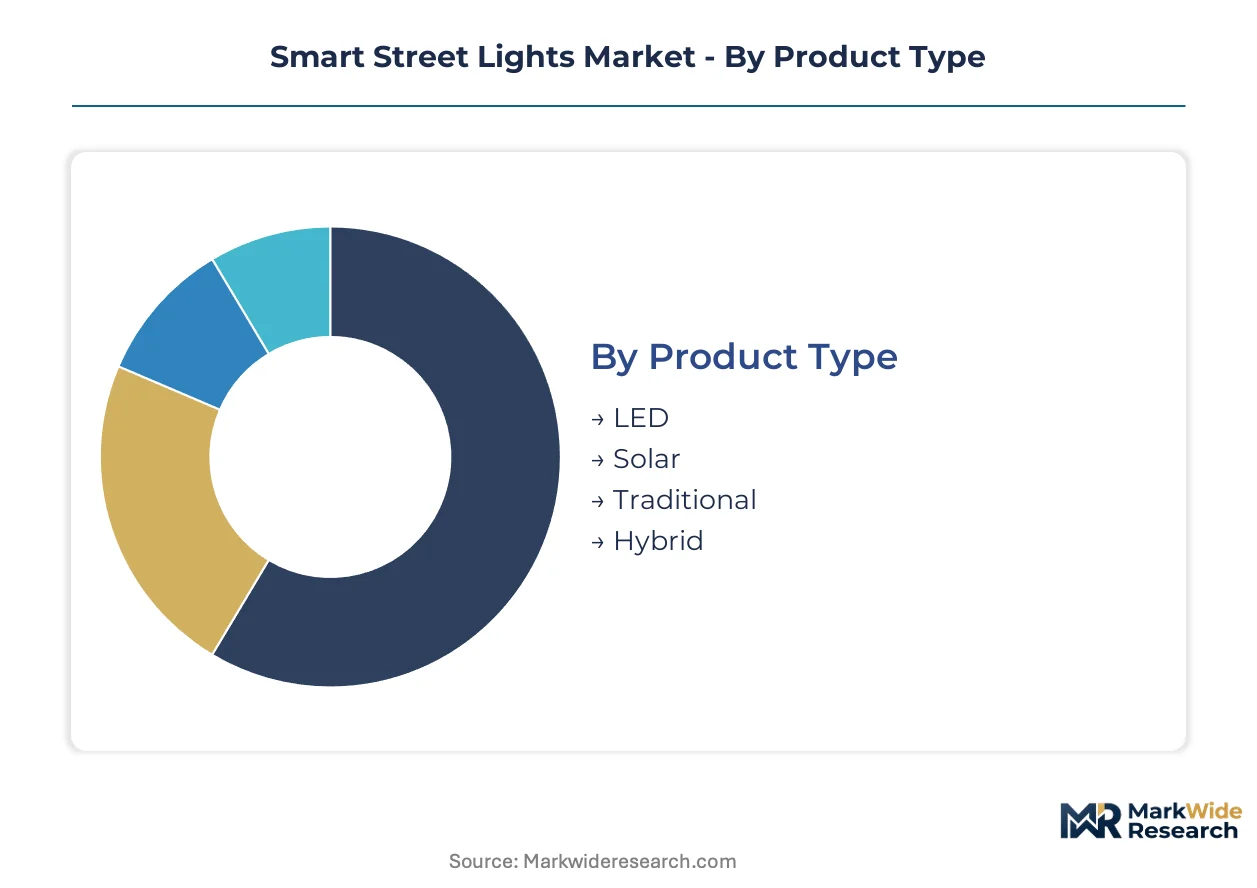
Segmentation reveals how procurement economics, technical specifications, and stakeholder requirements fragment the smart street lights market. Understanding these divides exposes where vendors can command premium positioning versus where competition compresses margins.
Product Type:
Margin pools concentrate in segments where retrofit economics and energy efficiency create procurement urgency.
- LED:Solid-state luminaires delivering 130-150 lumens per watt with 50,000-hour operational lifespans. Municipal procurement in India, Germany, and Japan concentrates here as sodium vapor infrastructure reaches end-of-life simultaneously, with India's Bureau of Energy Efficiency mandating minimum performance standards that constrain import eligibility.
- Solar:Photovoltaic-integrated pole assemblies with battery storage for off-grid operation. Grid-unreliable regions in Indonesia and rural India drive demand, where the Smart Cities Mission funds standalone installations bypassing distribution infrastructure constraints.
- Traditional:High-pressure sodium and metal halide luminaires with magnetic ballast technology. Replacement demand persists in legacy maintenance contracts and budget-constrained municipalities.
- Hybrid:Dual-source systems combining grid connection with solar backup and battery buffering. Singapore and Dubai pilot these for resilience in critical traffic corridors.
The dominant share belongs to LED, while Solar is closing the gap fastest.
Technology:
Volume concentrates in established connectivity layers, but application expansion is reshaping competitive positioning.
- IoT:Networked luminaires with edge-computing capability, API interoperability, and integration with urban digital twins. European municipalities under CSRD reporting obligations favor these for embedded carbon metering, while India's Smart Cities Mission mandates intelligent infrastructure in 100 urban centers.
- Wireless:Narrowband RF mesh and cellular backhaul for remote management without fiber trenching. UK utility-scale deployments and US municipal networks concentrate here, though FCC spectrum reallocation for 6 GHz Wi-Fi forces eighteen-month hardware redesign cycles.
- Adaptive:Dynamic dimming and spectral tuning responding to traffic density and ambient conditions. Traffic signal coordination pilots in Singapore leverage this for autonomous vehicle integration.
- Smart Sensors:Environmental monitoring modules for air quality, noise, and flood detection. Indonesia's 100 Smart Cities initiative deploys these as primary IoT backbones in Jakarta and Surabaya.
IoT commands the revenue concentration, with Smart Sensors expanding most quickly as municipalities monetize data streams.
End User:
Customer type determines contract structure, from capital procurement to performance-guaranteed service models.
- Municipalities:City governments managing public lighting assets through direct procurement or energy service company partnerships. São Paulo and Brazilian cities now contract luminaire-as-a-service models transferring technology obsolescence risk to private operators.
- Private Sector:Commercial developers and campus operators seeking branded sustainability credentials. Corporate headquarters and logistics parks in Germany and the Netherlands concentrate here.
- Urban Planners:Cross-departmental coordination bodies integrating lighting with broader spatial strategy. Singapore's Land Transport Authority exemplifies this with vehicle-to-infrastructure Li-Fi pilots.
- Transport Authorities:Dedicated agencies prioritizing traffic safety and signal coordination. These stakeholders drive specification for latency-sensitive adaptive systems.
Municipalities retain the dominant procurement volume, while Private Sector adoption is climbing the fastest as ESG reporting requirements harden.
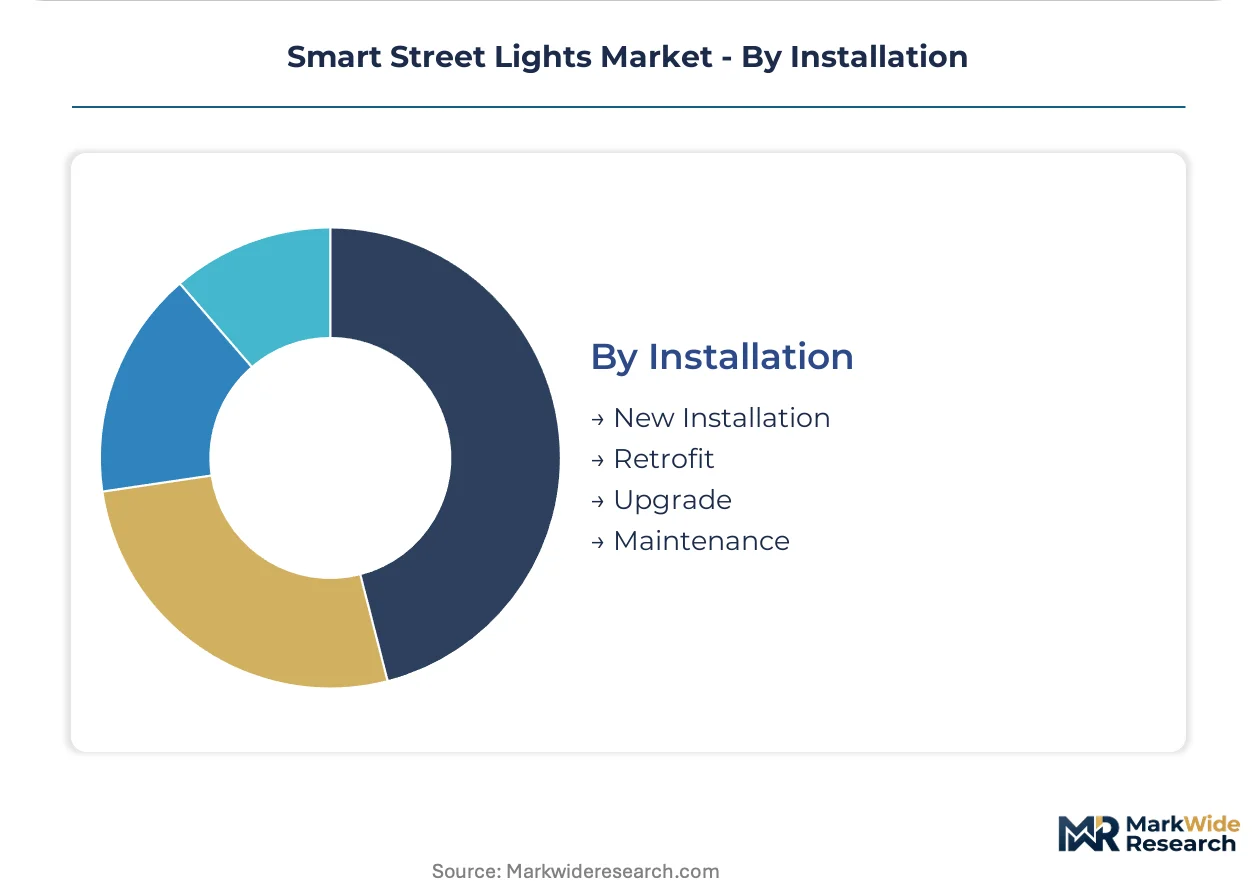
Installation:
Project type dictates margin structure through civil works intensity and technology risk allocation.
- New Installation:Greenfield pole deployment with trenching, foundation work, and grid connection. Greenfield smart city developments in Saudi Arabia and UAE concentrate here.
- Retrofit:LED and IoT module installation on existing pole infrastructure minimizing permitting burden. This category captures the largest project pipeline across Europe and North America as legacy sodium vapor reaches simultaneous end-of-life.
- Upgrade:Partial system enhancement adding sensors or connectivity to previously installed LED luminaires. Second-wave smart city programs in Spain and Italy favor this lower-capex pathway.
- Maintenance:Service contracts covering replacement, cleaning, and firmware updates. Long-term agreements in UK utility networks and Dutch municipal portfolios concentrate here.
Retrofit holds the dominant share, with Upgrade gaining share fastest as first-generation LED installations mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The FCC shapes spectrum allocation for streetlight-mounted small cells and IoT backhaul in the United States, while the EU Green Deal and CSRD reporting obligations pressure municipalities to document carbon reduction from lighting upgrades.
United States
Municipal procurement concentrates on retrofit economics as legacy sodium vapor infrastructure reaches simultaneous end-of-life. The FCC's 2023 spectrum reallocation for unlicensed 6 GHz Wi-Fi forces eighteen-month hardware redesign cycles for small cell providers. Chicago and Los Angeles anchor large-scale deployment programs where energy service companies bundle performance guarantees with luminaire-as-a-service contracts.
Germany
Industrial demand centers on high-efficiency LED retrofits driven by municipal budget pressures and ESG reporting requirements. The EU F-Gas Regulation phase-down restricts high-GWP refrigerants in outdoor equipment, favoring solid-state lighting thermal management. Munich and Hamburg lead deployment velocity with integrated urban digital twin platforms requiring API-interoperable luminaires.
India
Central government funding through the Smart Cities Mission mandates intelligent infrastructure across 100 urban centers. The Bureau of Energy Efficiency mandates minimum performance standards for LED street lighting under its domestic labeling program, constraining import eligibility. Delhi and Mumbai drive standardized procurement templates for networked luminaires with edge-computing capability.
United Kingdom
Utility-scale streetlight networks prioritize narrowband RF mesh density for remote management without fiber trenching. The EU Green Deal CSRD reporting obligations accelerate replacement timelines favoring connected systems with embedded metering. London and Birmingham concentrate deployment of multi-tenant capable luminaires generating recurring lease revenue from 5G network operators.
Singapore
Urban planners integrate lighting with autonomous vehicle infrastructure through vehicle-to-infrastructure data exchange pilots. The Land Transport Authority pilots Li-Fi visible light communication through modulated LED streetlight arrays, compressing latency for traffic signal coordination. The city-state serves as the primary testbed for dense urban deployments eliminating spectrum licensing costs.
Smart Street Lights Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, producing a tiered competitive structure. The vendor base clusters around three strategic positions: vertically integrated lighting conglomerates controlling captive LED driver manufacturing, specialized RF mesh communication providers, and diversified electrical equipment suppliers leveraging existing municipal relationships. Dominant competitive moves include backward integration into semiconductor sourcing and strategic partnerships with 5G infrastructure operators seeking neutral-host pole access.
Among diversified electrical equipment suppliers, Schneider Electric and Eaton occupy positions emphasizing broad municipal relationships and integrated energy management portfolios. Signify anchors the vertically integrated tier with proprietary light-management protocols sustaining differentiation across European deployments. Telensa exemplifies the specialized communication archetype, sitting within the narrowband RF mesh segment where density and coverage metrics determine competitive position.
| Leading Market Players |
|---|
| Philips Lighting |
| Hubbell |
| Signify |
| GE Current |
| Cree Lighting |
| Acuity Brands |
| Eaton |
| Telensa |
| Schneider Electric |
| Others |
Value Chain & Pricing Dynamics
Long-term luminaire-as-a-service contracts lock in municipal procurement pipelines while insulating vendors from copper and aluminum price volatility through indexed escalation clauses. São Paulo's performance-guaranteed service models demonstrate how this structure transfers technology obsolescence risk to operators while securing decade-long revenue visibility.
Pricing Analysis
Price spreads between German and Indian deployments exceed forty percent driven by certification tier divergence and after-sales bundling intensity. Three-tier pricing structure across premium, standard, and economy levels separates API-interoperable IoT luminaires from basic LED retrofits and legacy maintenance contracts. Cost compression in the economy tier is intensifying because India's Bureau of Energy Efficiency mandates minimum performance standards constraining import eligibility. Municipal procurement departments exhibit highest price sensitivity while transport authorities prioritizing latency-critical adaptive systems show lowest.
Supply Chain Analysis
Inventory buffers for LED driver ICs and RF communication modules have stretched to twenty-six weeks as foundry capacity concentrates in Taiwan, South Korea, and China. Pole-mounted enclosures draw from copper and aluminum feedstock anchored in Chilean and Indonesian smelter output. Single-source vulnerability in East Asian semiconductor fabrication exposes project timelines to geopolitical disruption. Distribution runs through electrical contractor networks and energy service company partnerships rather than direct municipal sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Municipal procurement consolidation through standardized Smart Cities Mission templates is shifting buyer power toward volume-aggregated tendering, fragmenting vendor pricing autonomy across Asia-Pacific deployments.
For Market Incumbents: Secure proprietary protocol ecosystems against API interoperability mandates from European urban digital twin platforms. Backward integration into captive LED driver manufacturing anchors margin defense against commodity metal volatility. Counter narrowband RF mesh specialists through edge-computing capability investments that expand addressable use cases beyond illumination. For New Entrants and Emerging Players: Cybersecurity fast-track certification for critical infrastructure IoT unlocks procurement qualification in EU member states where CSRD reporting obligations accelerate connected system adoption. Target Indonesia's 100 Smart Cities initiative where flood monitoring and traffic management applications remain underpenetrated by established vendors. Lead with sensor-data monetization revenue sharing to bypass capital-constrained municipal budgets. For Investors and Strategic Acquirers: Specialized RF mesh communication providers with utility-scale deployment density represent prime acquisition targets as 5G neutral-host infrastructure demand converges with streetlight network assets. Long-term viability hinges on protocol standardization outcomes across the analysis window. Monitor FCC spectrum reallocation implementation as inflection indicator for hardware redesign cycle intensity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Semiconductor Sourcing | Taiwanese foundry partnerships reduce LED driver IC supply vulnerability for European deployments. |
| Strategic Partnership with 5G Infrastructure Operators | Multi-tenant capable luminaires generate recurring lease revenue from London and Birmingham network densification. |
| Edge Computing Capability Investment | On-pole processing enables real-time traffic analytics for Singapore's Land Transport Authority pilots. |
| Cybersecurity Certification Fast-Track | EU critical infrastructure IoT standards accelerate vendor qualification timelines under CSRD obligations. |
| Sensor Data Monetization Platform | Brazilian luminaire-as-a-service models transfer technology risk while unlocking urban analytics revenue streams. |
Study Parameters
Initial hypotheses were tested against primary input from municipal procurement officers, electrical contractor project managers, energy service company executives, and urban planning department leads and refined through secondary validation against Bureau of Energy Efficiency labeling databases, FCC spectrum allocation filings, EU Green Deal implementation reports, and Smart Cities Mission tender documentation. Bottom-up deployment volume estimates triangulated with top-down infrastructure spending forecasts.
Variance decomposition across product type, technology layer, installation mode, and end-user archetype dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from segment-level growth rate reconciliation against macroeconomic infrastructure investment trajectories. Forecast inputs incorporated semiconductor supply lead times, copper futures price curves, and municipal debt capacity indicators.
Decision-makers should treat outputs as directional under assumptions of sustained central government funding continuity and stable East Asian foundry capacity; material deviation would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
Global Smart Ticketing Market
Smart City Technology
City Data Platform Market
Smart City Technology
Smart City Kiosk Deployment Market
Smart City Technology
Smart Space Market
Smart City Technology
US Smart Cities Market
Smart City Technology
India Smart City Market
Smart City Technology
Global Smart Hubs Market
Smart City Technology
Smart Parcel Delivery Locker Market
Smart City Technology
Global Smart/Connected Street Lights Market
Smart City Technology
Outdoor LED Smart Lighting Solution Market
Smart City Technology
Smart Shade Device Market
Smart City Technology
Smart Package Lockers Market
Smart City Technology
Smart Parking Meters Market
Smart City Technology
Global Smart City Market
Smart City Technology
Smart Communities Market
Smart City Technology
UAE Smart Furniture Market