
 Smart Parcel Delivery Locker Market | 2026-2036
Smart Parcel Delivery Locker Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Parcel Delivery Locker Market Outlook
The shift from single-source hardware procurement to multi-vendor ecosystem partnerships is broadening competitive access for locker operators. Quadient leverages its mail automation heritage to anchor European parcel locker networks. Cleveron sustains technology leadership in robotics-enabled pickup towers. KEBA Group AG dominates electromechanical locking systems for outdoor installations.
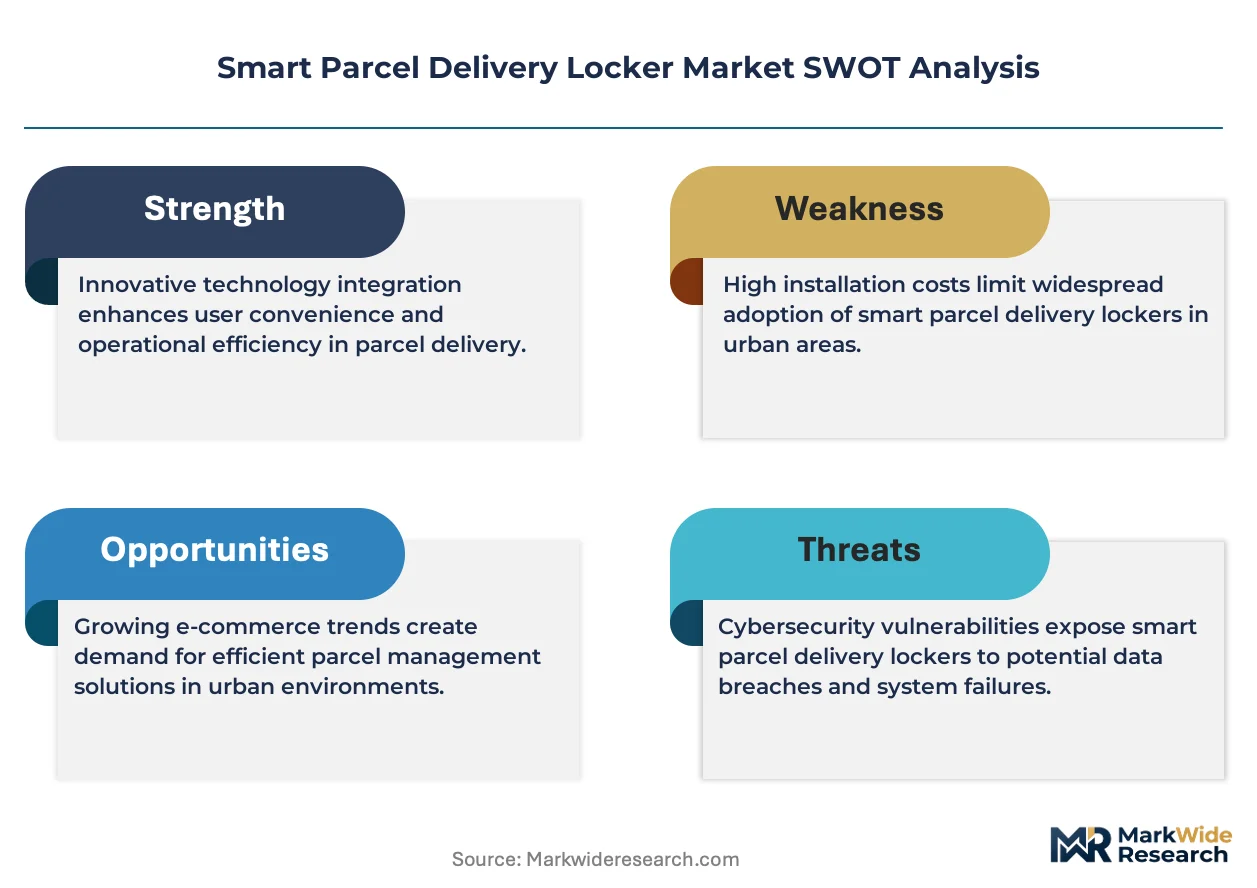
Smart parcel delivery lockers consist of modular, electronically controlled compartment arrays with integrated authentication, notification, and remote management capabilities, typically constructed from galvanized steel with IP-rated enclosures for weather resistance. These systems serve as decentralized nodes in last-mile logistics, reducing failed delivery attempts and enabling asynchronous package collection. Standard lockers occupy the highest volume share due to universal parcel compatibility, while refrigerated lockers capture concentrated margin pools from grocery and pharmaceutical cold chain applications. Cloud-based solutions lead technology adoption by enabling centralized fleet management across dispersed locker networks.
FCC regulations govern wireless communication modules in US locker deployments, while the EU AI Act shapes algorithmic access control and biometric authentication pathways. REACH compliance constrains coating and electronics material selection for European manufacturers. Stakeholders must monitor evolving cybersecurity standards for IoT-connected locker fleets as data protection frameworks tighten across jurisdictions.
Market Dynamics
The EU Green Deal's mandate for last-mile emission reductions is forcing logistics operators to consolidate delivery endpoints into electric vehicle-compatible locker networks, compressing capital deployment timelines across European markets.
Growth Catalysts
- REACH compliance requirements:European manufacturers are redesigning coating and electronics material selections to meet chemical safety standards, accelerating modular locker component standardization.
- Apartment complex density:Property developers in Germany and France are pre-installing locker infrastructure as tenant amenity requirements harden in urban rental markets.
- Cloud-based fleet management:Centralized remote monitoring platforms are enabling operators to scale dispersed networks without proportional headcount expansion.
Market Restraints
- Galvanized steel input volatility:Weather-rated enclosure fabrication faces cost pressure from fluctuating steel commodity markets and energy-intensive galvanization processes.
- Electromechanical locking supply concentration:Austria-based component specialists control critical IP for outdoor-rated locking actuators, creating single-source vulnerability for tier-two locker assemblers.
- FCC certification timelines:US wireless module approvals add six to nine months to product launch cycles, delaying network expansion for capital-constrained entrants.
Strategic Opportunities
- India campus networks:Tier-one engineering universities and IT parks present untapped deployment potential for refrigerated pharmaceutical and standard parcel configurations.
- EU AI Act biometric pathways:Algorithmic access control systems compliant with European artificial intelligence governance frameworks will unlock enterprise campus and healthcare facility segments.
- Cold chain grocery convergence:Temperature-controlled locker modules integrated with last-mile refrigerated logistics are capturing margin pools from meal-kit and fresh produce delivery services.
Industry Challenges
- Cybersecurity certification complexity:IoT-connected locker fleets must navigate tightening data protection frameworks across multiple jurisdictions simultaneously.
- Legacy logistics system integration:API harmonization with established carrier tracking and notification platforms requires specialized middleware development.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Parcel Delivery Locker Market |
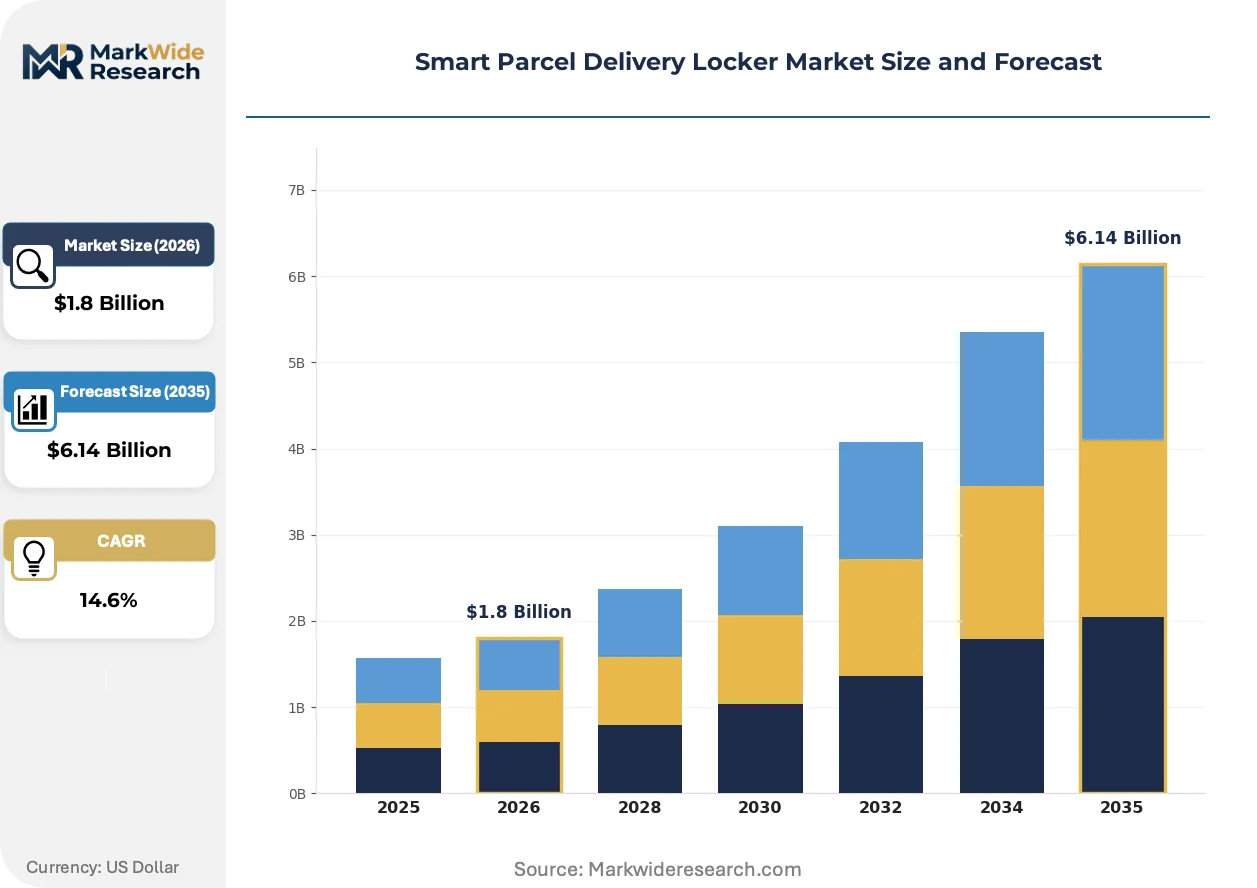
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Standard Lockers, Refrigerated Lockers, Secure Lockers, Automated Lockers End User: Residential Users, Retail Stores, Corporate Offices, Logistics Providers Technology: Cloud-based Solutions, RFID Systems, IoT Integration, Mobile App Interfaces Installation: Indoor Installation, Outdoor Installation, Modular Systems, Retrofit Solutions |
| Companies Covered | Ricoh Group, Quadient, Pitney Bowes Inc, Cleveron, InPost S.A., TZ Limited, KEBA Group AG, Hollman Inc, LUXER Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Parcel Delivery Locker Market Strategic Shifts
Authentication and access technologies are compressing the gap between hardware deployment and software-enabled service models, enabling locker operators to monetize usage data beyond per-transaction fees.
Computer vision-enabled pickup verification is rewriting customer interaction protocols in high-traffic locker installations. Grocery and pharmaceutical distributors are piloting facial recognition and QR-code hybrid systems to reduce PIN-code friction. This convergence of biometrics with mobile credentialing is compressing transaction times and enabling higher throughput density in premium real estate locations.
The EU AI Act's risk-based classification system for biometric identification is reshaping algorithmic access control procurement decisions. Locker operators must now document conformity assessments for facial recognition deployments in public spaces. German and French network operators are prioritizing privacy-preserving edge-computing architectures to minimize centralized biometric data storage liabilities.
Subscription-based locker access is displacing per-parcel fees in dense urban residential markets. Property management platforms in Berlin and Amsterdam are bundling unlimited locker usage into monthly service charges. This shift from transactional to recurring revenue models is most visible in premium apartment segments where tenant retention metrics drive amenity investment decisions.
Smart Parcel Delivery Locker Market Segmentation
Parcel locker purchasing decisions diverge sharply between cost-driven mass deployment and premium functionality requirements. Understanding these segment boundaries reveals where hardware commoditization ends and software-enabled service differentiation begins.
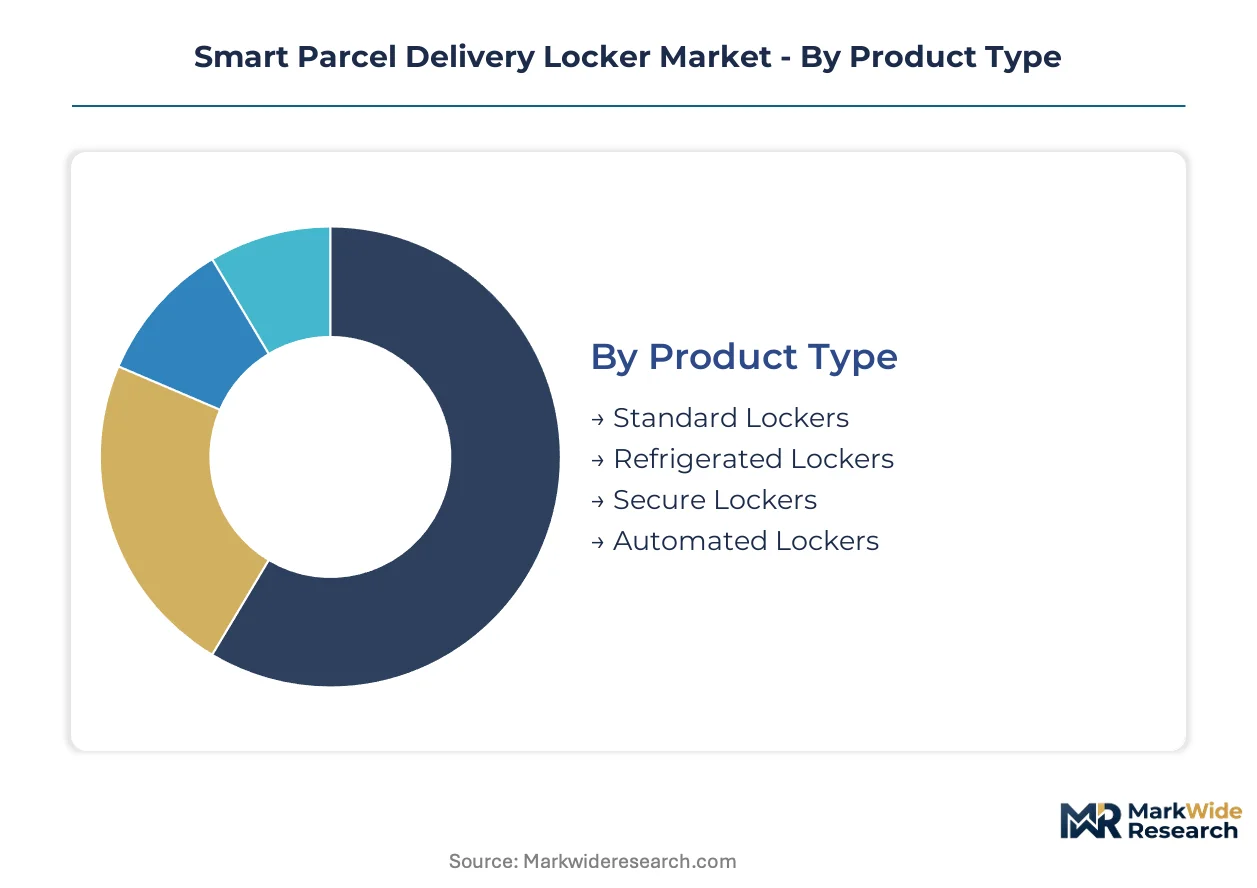
Product Type:
Buyers prioritize compartment versatility against total cost of ownership when selecting locker configurations for specific deployment environments.
- Standard Lockers:Galvanized steel compartments with IP-rated weather enclosures accommodate universal parcel dimensions without temperature control. Apartment complexes in Germany and France specify these for baseline tenant amenity packages, driven by rental market competition for logistics convenience.
- Refrigerated Lockers:Thermoelectric or compressor-based cooling modules maintain pharmaceutical and grocery cold chains from -20°C to +8°C. Meal-kit distributors in urban Netherlands clusters are expanding refrigerated locker networks to reduce last-mile refrigeration costs.
- Secure Lockers:Reinforced steel construction with audit-trail logging serves high-value electronics and jewelry fulfillment. Banking and luxury retail segments in Switzerland specify these for customer pickup points.
- Automated Lockers:Robotic retrieval systems with vertical storage towers maximize footprint efficiency in premium real estate. University campuses in Japan deploy these where land scarcity constrains horizontal expansion.
Standard lockers lead on scale; refrigerated lockers lead on momentum.
End User:
Deployment economics shift dramatically based on who controls site access and bears capital expenditure.
- Residential Users:Apartment tenants and homeowners access lockers as amenities or standalone neighborhood installations. Property developers in Berlin and Amsterdam pre-install infrastructure to meet tenant retention targets in competitive rental markets.
- Retail Stores:Brick-and-mortar locations host lockers as foot-traffic drivers and fulfillment nodes. Grocery chains in France integrate pickup points with existing refrigerated logistics to capture click-and-collect demand.
- Corporate Offices:Enterprise campuses deploy private locker networks for employee package receipt and interoffice logistics. IT parks in India are piloting pharmaceutical-grade refrigerated units for workforce health programs.
- Logistics Providers:Carriers operate locker networks as last-mile density tools and failed-delivery mitigation. DHL Packstation density in Germany creates the reference model for carrier-operated automated pickup infrastructure.
Logistics providers dominate installed base; residential deployments are climbing the fastest.
Technology:
Technology selection determines whether locker networks scale as capital-intensive hardware or software-enabled service platforms.
- Cloud-based Solutions:Centralized fleet management platforms enable remote monitoring, dynamic compartment allocation, and API integration with carrier tracking systems. European operators prioritize these to manage dispersed networks without proportional staffing expansion.
- RFID Systems:Radio-frequency identification enables touchless access and inventory tracking without biometric data collection. German operators favor these under GDPR-conscious procurement policies.
- IoT Integration:Sensor networks report temperature, humidity, door status, and power consumption for predictive maintenance. Cold chain grocery applications in France require continuous environmental monitoring for regulatory compliance.
- Mobile App Interfaces:Smartphone credentialing with QR codes and push notifications replaces PIN-code friction. Urban residential markets in Japan and South Korea show highest adoption of app-first access protocols.
Cloud-based solutions anchor current deployment; mobile app interfaces show steepest expansion trajectory.
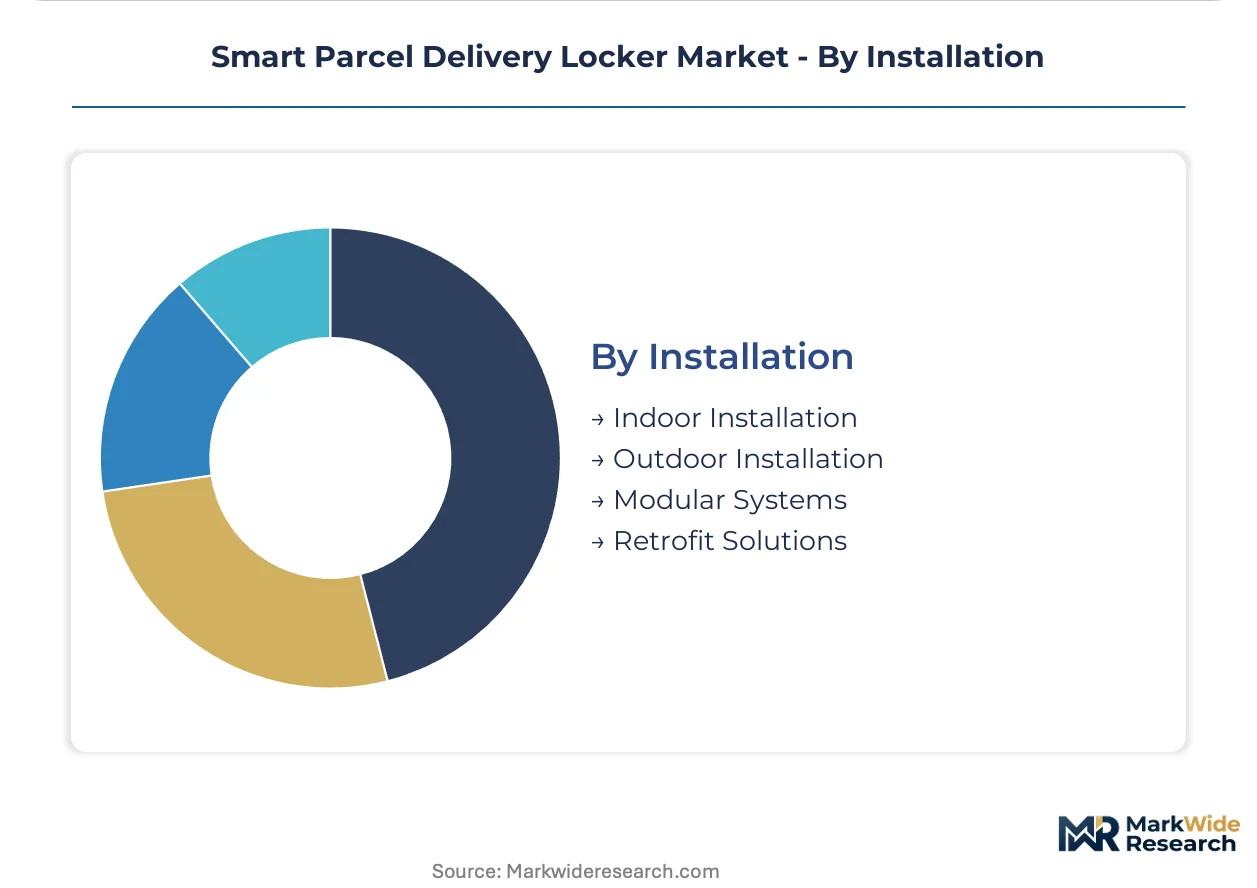
Installation:
Site constraints and capital recovery timelines drive installation methodology selection.
- Indoor Installation:Climate-controlled environments eliminate weatherproofing costs and extend electromechanical component lifespan. University campuses and corporate offices in Japan prefer these for high-traffic, high-frequency use cases.
- Outdoor Installation:IP-rated enclosures with heating elements and drainage systems withstand temperature extremes and precipitation. European logistics providers deploy these for sidewalk and parking-lot accessibility.
- Modular Systems:Expandable compartment arrays allow phased capital deployment aligned with demand growth. Property developers in India favor these for campus networks with uncertain initial volume.
- Retrofit Solutions:Locker integration into existing mailrooms, lobbies, or retail footprints minimizes structural modification. Older apartment stock in Germany uses these to add amenity value without new construction.
Outdoor installation commands volume leadership; modular systems are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
DHL Packstation density in Germany creates the reference model for automated pickup networks worldwide. The EU Green Deal accelerates electric vehicle-compatible locker infrastructure deployment across European markets. Campus networks and apartment complex pre-installations drive expansion in Asia-Pacific and North American urban clusters.
United States
Apartment complex developers in Austin and Seattle pre-install locker infrastructure as tenant amenity requirements harden. FCC certification timelines for wireless modules add six to nine months to product launch cycles. University campuses in California deploy refrigerated units for pharmaceutical and meal-kit cold chain applications.
Germany
DHL Packstation networks set the density benchmark for carrier-operated automated pickup infrastructure. REACH compliance requirements accelerate modular locker component standardization among domestic manufacturers. Berlin property developers bundle unlimited locker access into monthly service charges for premium apartment segments.
France
Grocery chains integrate pickup points with existing refrigerated logistics to capture click-and-collect demand. The EU AI Act shapes algorithmic access control procurement for facial recognition deployments in public spaces. Paris and Lyon clusters prioritize privacy-preserving edge-computing architectures to minimize biometric data storage liabilities.
Japan
University campuses deploy automated vertical storage towers where land scarcity constrains horizontal expansion. METI standards guide IoT sensor integration for predictive maintenance protocols. Tokyo and Osaka residential markets show highest adoption of app-first access protocols with QR-code and push notification credentialing.
India
Tier-one engineering universities and IT parks present deployment potential for refrigerated pharmaceutical and standard parcel configurations. BIS certification requirements shape electromechanical component sourcing decisions. Bangalore and Hyderabad campuses pilot pharmaceutical-grade refrigerated units for workforce health programs.
Smart Parcel Delivery Locker Market Competitive Environment
Global majors compete with regional champions across hardware fabrication and software-enabled service platforms. The vendor base organizes around mail automation heritage, robotics integration, and electromechanical locking specialization. Three archetypes dominate: postal incumbents with established logistics relationships, robotics specialists with vertical storage expertise, and component suppliers controlling critical actuator IP. Competitive moves concentrate on ecosystem partnerships and cloud-based fleet management licensing.
Within the postal heritage tier, Quadient leverages mail automation capabilities to anchor European parcel locker networks. Among robotics-enabled specialists, Cleveron occupies a position exemplifying vertical storage tower technology leadership. KEBA Group AG represents the electromechanical component archetype, with Austrian-based fabrication controlling critical IP for outdoor-rated locking actuators.
| Leading Market Players |
|---|
| Ricoh Group |
| Quadient |
| Pitney Bowes Inc |
| Cleveron |
| InPost S.A. |
| TZ Limited |
| KEBA Group AG |
| Hollman Inc |
| LUXER Corporation |
| Others |
Value Chain & Pricing Dynamics
Apartment complex developers in Berlin and Amsterdam demanding pre-installed locker infrastructure as tenant amenities are compressing procurement timelines and forcing suppliers to standardize modular components, which flattens price premiums across mid-tier configurations while concentrating margin capture in refrigerated and automated locker tiers.
Pricing Analysis
Galvanized steel input volatility passes through directly to weather-rated enclosure fabrication costs, with energy-intensive galvanization processes amplifying price sensitivity in outdoor installation segments. Three-tier pricing structure across premium refrigerated units, standard galvanized compartments, and economy retrofit modules differentiates on IP-rating certification and cooling capability. Pricing pressure stems from REACH compliance redesign costs among European manufacturers. Logistics providers show least price sensitivity due to fleet-scale procurement power, while independent property developers in India exhibit highest price elasticity.
Supply Chain Analysis
Container freight rate fluctuations between Chinese steel fabricators and European assembly plants compress margins for tier-two locker assemblers dependent on Asian galvanized steel inputs. Electromechanical locking actuator production concentrates in Austria and Germany, while cloud-based fleet management software development clusters in Estonia and Finland. Single-source vulnerability around outdoor-rated locking IP creates supply chain fragility. Distribution runs through carrier-direct procurement for logistics providers and property developer specification channels for residential deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart Parcel Delivery Locker Market functions as a geographic-arbitrage play where EU AI Act compliance costs in France and Germany create 15-20% cost disadvantages against Indian and US deployments with lighter biometric regulation, rewarding capital deployment in regulatory-permissive jurisdictions.
For Market Incumbents: Deploy cloud-based fleet management platform licensing to anchor recurring revenue streams against hardware commoditization pressure from Chinese fabricators. Consolidate electromechanical locking IP through exclusive supply agreements with Austrian component specialists to defend against tier-two assemblers. Deepen vertical integration into refrigerated module compressor sourcing to capture cold chain grocery margin pools. For New Entrants and Emerging Players: The premium-to-economy price gap in automated vertical storage towers offers entry opportunity for robotics-enabled specialists targeting Japanese university campuses with land-scarce deployment constraints. White-space exists in Indian IT park pharmaceutical-grade refrigerated networks and US apartment complex retrofit solutions. Go-to-market through property management platform partnerships rather than carrier-direct sales accelerates residential penetration. For Investors and Strategic Acquirers: Asymmetric upside sits with robotics-enabled pickup tower specialists possessing vertical storage IP in Japanese and South Korean markets. Long-term viability favors vendors with software-enabled service platforms over pure hardware fabricators. Watch FCC certification timeline compression as signal of US market entry feasibility for capital-constrained entrants.| Strategic Initiative | Industry Significance |
|---|---|
| Cloud Platform Licensing | Enables DHL Packstation-scale fleet management without proportional staffing expansion. |
| Refrigerated Module Expansion | Captures meal-kit and pharmaceutical cold chain margins in urban Netherlands clusters. |
| Biometric Access Certification | Unlocks EU AI Act-compliant enterprise campus and healthcare facility segments. |
| Modular System Standardization | Reduces REACH compliance redesign costs across European manufacturing footprints. |
| Mobile App Interface Integration | Replaces PIN-code friction in Tokyo and Osaka residential markets with QR credentialing. |
Study Parameters
Bottom-up residential and logistics provider deployment modeling reconciled against top-down electromechanical component and steel enclosure supply tracking forms the analytical core. Primary interviews with property development executives, carrier network planners, electromechanical component procurement leads, and cloud platform engineering directors combined with secondary validation against customs trade data, SEC filings from logistics technology vendors, EU Green Deal implementation reports, and BIS certification registries. Triangulation between demand-side installation forecasts and supply-side capacity announcements ensures consistency.
Input-output matrices map parcel volume projections through locker density assumptions, compartment utilization rates, and technology adoption curves across the projection horizon. Segmentation dimensions include product type, end user archetype, technology platform, and installation methodology. CAGRs derive from logistic curve fitting to deployment saturation patterns observed in German Packstation networks. Industry-specific forecast inputs incorporate REACH compliance cost pass-throughs and FCC certification timeline distributions.
Caveats apply where EU AI Act biometric governance revisions or galvanized steel commodity shocks could materially shift the outlook. Forecasts reflect modeling assumptions around apartment complex pre-installation rates and carrier fleet expansion commitments. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
Smart Signaling Market
Smart City Technology
Smart Communities Market
Smart City Technology
Singapore ICT Market
Smart City Technology
Outdoor LED Smart Lighting Solution Market
Smart City Technology
Global Smart Hubs Market
Smart City Technology
Smart Parking Meters Market
Smart City Technology
Smart Parcel Locker Market
Smart City Technology
Smart Package Lockers Market
Smart City Technology
Smart City Platform Market
Smart City Technology
Smart City Kiosk Market
Smart City Technology
Global Smart City Market
Smart City Technology
Smart Space Market
Smart City Technology
Global Smart Ticketing Market
Smart City Technology
Saudi Arabia Smart Cities Market
Smart City Technology
US Smart Cities Market
Smart City Technology
Global Smart/Connected Street Lights Market