
 Smart Mailbox Market | 2026-2036
Smart Mailbox Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Mailbox Market Analytics
Aftermarket service revenue is narrowing as hardware margins compress across the smart mailbox value chain. iPostal1 leverages its virtual mail scanning infrastructure to sustain recurring subscription income. Anytime Mailbox competes through aggressive franchise expansion across North American retail locations. US Global Mail anchors its position in expatriate and corporate relocation segments with specialized forwarding services.
A smart mailbox is an electronically connected receptacle integrating sensors, cellular or Wi-Fi modules, and cloud software to authenticate deliveries, notify recipients, and log access events; units typically incorporate weatherproof enclosures rated for outdoor installation and battery or hardwired power configurations. The primary commercial purpose centers on reducing failed delivery attempts, mitigating theft, and enabling remote package management for absent recipients. Parcel lockers dominate capital deployment among product types due to their suitability for multifamily and retail consolidation points. IoT Solutions lead technology adoption where real-time status signaling and API integration with carrier systems matter most. Security Applications within usage scenarios command premium positioning as insurers and property managers quantify loss prevention value.
The FCC governs radio frequency emissions for connected mailbox modules, while the FDA holds limited relevance unless biometric access systems trigger medical device thresholds. State-level consumer protection frameworks in California and Texas increasingly mandate delivery notification standards for rental properties. Stakeholders must monitor evolving municipal ordinances that mandate smart parcel infrastructure in new construction permits.
Market Dynamics
The smart mailbox market is experiencing structural compression as hardware commoditization forces vendors to capture value through software integration and recurring service layers rather than unit sales alone.
Growth Catalysts
- FCC Part 15 Certification:Clear radio frequency device rules in the United States accelerate product approval timelines and reduce regulatory uncertainty for cellular-connected units.
- Multifamily Housing Construction:Dense residential development in California and Texas creates concentrated deployment opportunities for parcel locker systems.
- Package Theft Liability:Property management firms face mounting insurance pressure to deploy secure receptacles as porch piracy claims escalate.
Market Restraints
- Lithium-Ion Battery Supply:Outdoor-rated power modules depend on volatile battery chemistry costs and constrained cell manufacturing capacity.
- Cellular Module Concentration:Narrow supplier bases for LTE-M and NB-IoT chipsets create single-source vulnerabilities in connected hardware.
- Biometric Regulatory Thresholds:FDA medical device classification risks emerge for fingerprint or facial recognition access systems.
Strategic Opportunities
- Corporate Relocation Services:Specialized forwarding and virtual mail management for expatriate populations remains underpenetrated relative to consumer segments.
- API Integration with Carrier Systems:Real-time status signaling creates differentiation where FedEx, UPS, and postal APIs enable seamless delivery handoffs.
- Municipal Construction Mandates:Emerging ordinances in Texas cities require smart parcel infrastructure in new multifamily building permits.
Industry Challenges
- Embedded Firmware Talent:Scarcity of engineers with combined IoT security and low-power optimization skills delays product roadmaps.
- UL 294 Access Control Certification:Extended testing timelines for electronic locking mechanisms compress launch windows.
- Legacy Property Management Software:Integration friction with established tenant platforms slows enterprise sales cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Mailbox Market |
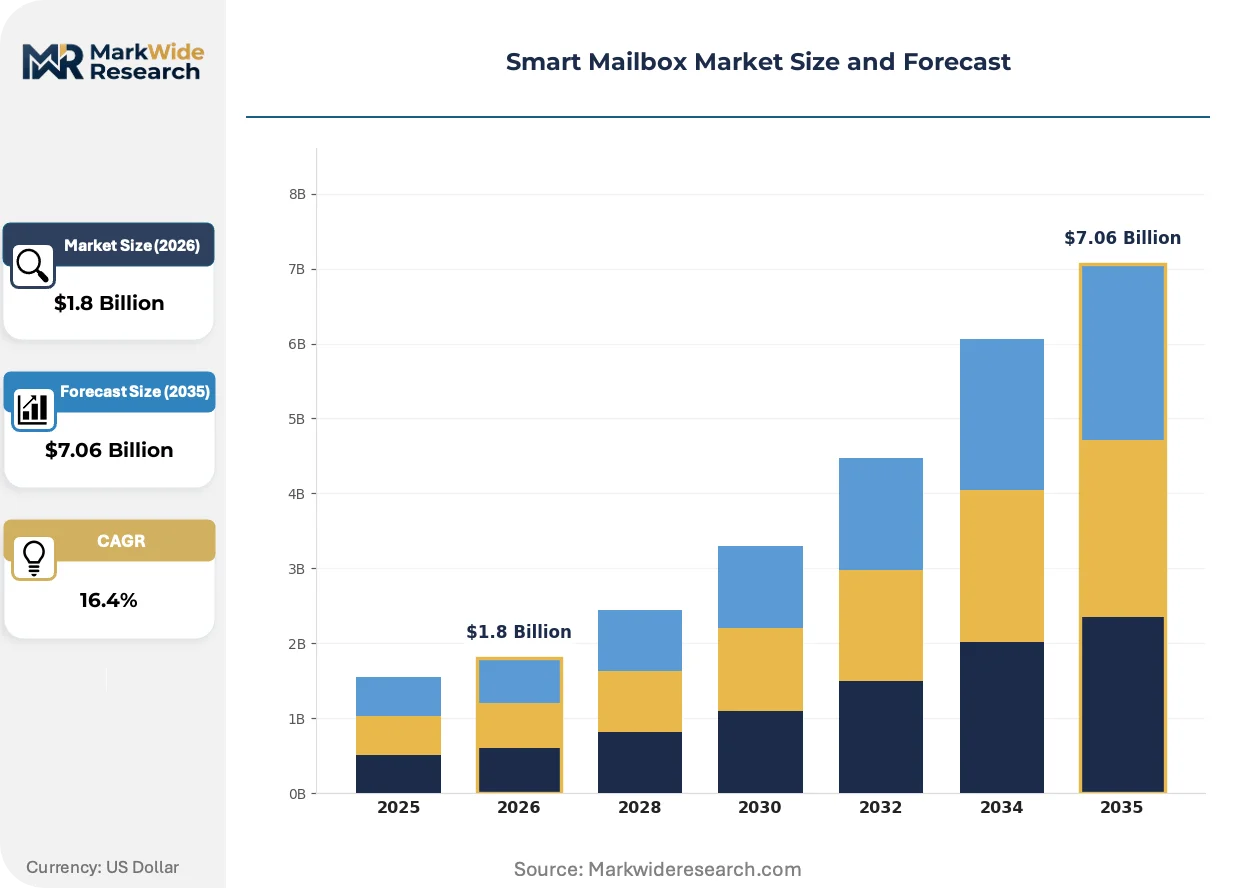
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $7.06 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Residential Mailboxes, Commercial Mailboxes, Parcel Lockers, Specialized Units Technology: IoT Solutions, Cloud-Based Systems, Remote Monitoring, Security Features Usage Scenario: Home Delivery, Package Retrieval, Security Applications, Urban Solutions End User: Households, Businesses, Property Management Firms, Municipalities |
| Companies Covered | iPostal1, Google Workspace, Traveling Mailbox, Rackspace Email, Zoho Mail, PostScan Mail, Anytime Mailbox, Missive, US Global Mail, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Mailbox Market Evolving Landscape
Connected mailbox technology is pivoting from standalone hardware to software-defined service platforms, with vendor differentiation increasingly anchored in data orchestration capabilities rather than physical enclosure design.
Cellular connectivity is migrating from Wi-Fi dependency to LTE-M and NB-IoT modules that eliminate tenant network configuration burdens. Property managers in Texas and California are adopting these standalone units to reduce support tickets. This shift is compressing total cost of ownership calculations and marginalizing Wi-Fi-only SKUs in enterprise procurement.
State-level consumer protection frameworks in California are mandating delivery notification standards for rental properties. The industrial consequence is accelerated RFP activity from multifamily operators seeking compliant infrastructure. Security-focused applications command premium positioning as insurers quantify loss prevention value in underwriting decisions.
Buyer procurement patterns are consolidating around integrated facility management platforms rather than point solutions. Channel disintermediation is visible as direct vendor relationships replace distributor intermediaries in enterprise accounts. This concentration is most pronounced in California's largest property management conglomerates.
Smart Mailbox Market Segmentation
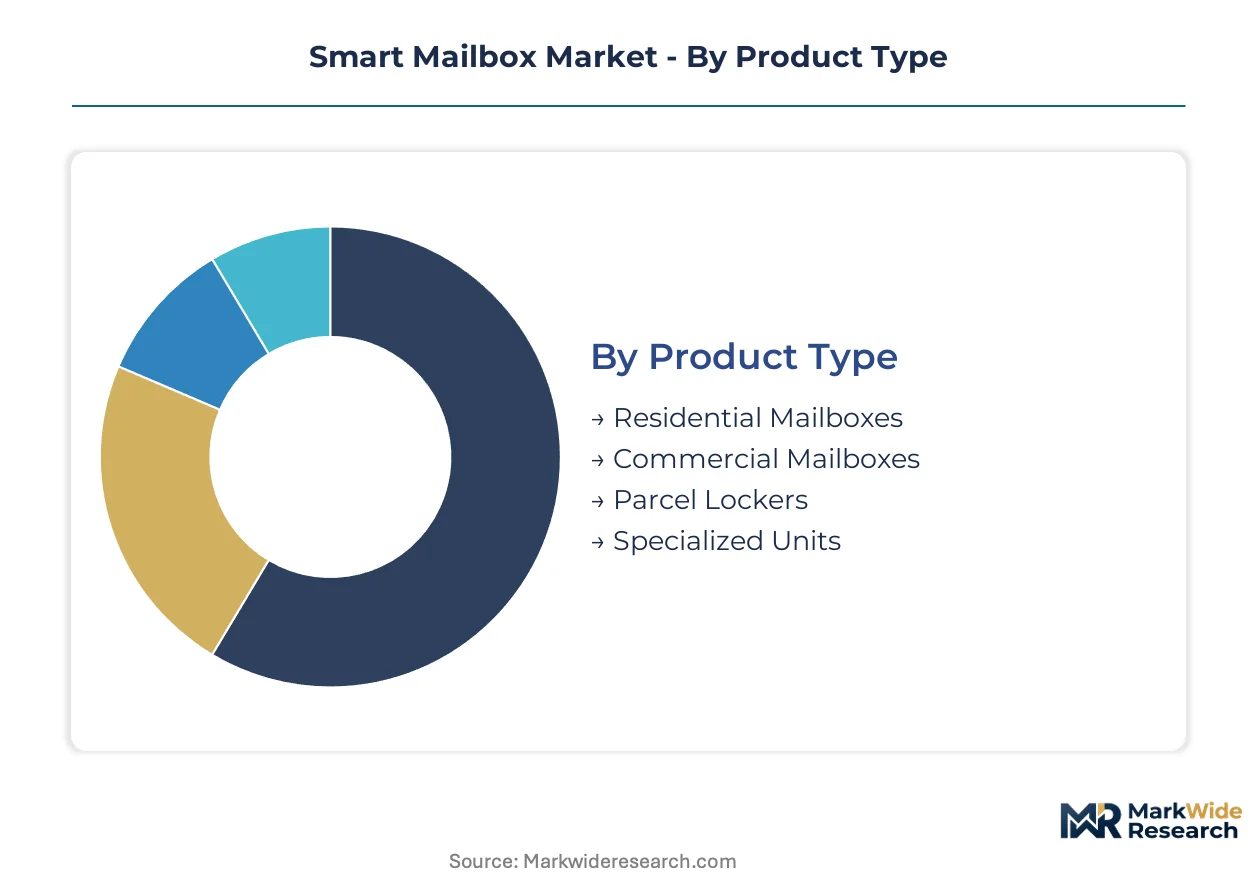
Segmentation in smart mailboxes reveals how hardware commoditization pushes vendors toward software-defined service layers. Product configuration, connectivity architecture, and end-use application each determine pricing power and recurring revenue potential differently.
Product Type:
Cost tier separation defines competitive positioning across physical form factors, with capital intensity and installation complexity driving margin structures.
- Parcel Lockers:Modular steel enclosures with integrated electronic locking and cellular telemetry support high-density multifamily deployments. California and Texas property managers prioritize these units to satisfy municipal construction mandates and reduce theft liability exposure.
- Commercial Mailboxes:Clustered receptacle systems designed for business parks and retail consolidation points incorporate weatherproofing and centralized key or credential management. Demand concentrates where USPS cluster box requirements intersect with private carrier API integration needs.
- Residential Mailboxes:Single-unit connected receptacles for detached homes feature battery or solar power configurations with Wi-Fi or LTE-M connectivity.
- Specialized Units:Temperature-controlled or oversized enclosures serve pharmaceutical deliveries and perishable goods in healthcare and grocery verticals.
Parcel lockers hold installed capacity. Specialized units are rotating up the share rankings.
Technology:
Application architecture determines whether vendors capture value through hardware margins or subscription services, with cloud dependency creating divergent customer lifetime economics.
- IoT Solutions:Embedded sensor arrays and cellular modules enable real-time status signaling and API handoffs with FedEx, UPS, and postal systems. Property managers in Texas deploy these standalone units to eliminate tenant Wi-Fi configuration burdens and reduce support tickets.
- Cloud-Based Systems:Software-defined platforms centralizing delivery logging, recipient notification, and access credential management across distributed hardware estates. Enterprise procurement favors these architectures for remote firmware updates and multi-site visibility.
- Remote Monitoring:Video verification and tamper detection capabilities support insurance underwriting and loss prevention documentation.
- Security Features:Biometric access and encrypted communications modules address compliance with state-level consumer protection frameworks.
IoT Solutions anchor current deployments. Cloud-Based Systems are climbing the fastest as facility management platforms consolidate procurement.
Usage Scenario:
Volume concentration varies by delivery density and security sensitivity, with urban infrastructure investments creating distinct deployment economics from suburban markets.
- Security Applications:Insurance-mandated installations with video audit trails and tamper-evident logging command premium positioning. Property managers quantify loss prevention value in underwriting negotiations, particularly where porch piracy claims have escalated.
- Urban Solutions:Curbside and lobby-mounted systems serving high-rise and mixed-use developments with carrier consolidation and 24-hour retrieval access. Municipalities in Texas increasingly require these in new construction permits.
- Home Delivery:Single-residence installations addressing failed delivery attempts and absentee recipient convenience.
- Package Retrieval:Click-and-collect and buy-online-pickup-in-store configurations for retail and grocery partners.
Security Applications command pricing power. Urban Solutions are gaining share fastest through construction mandate compliance.
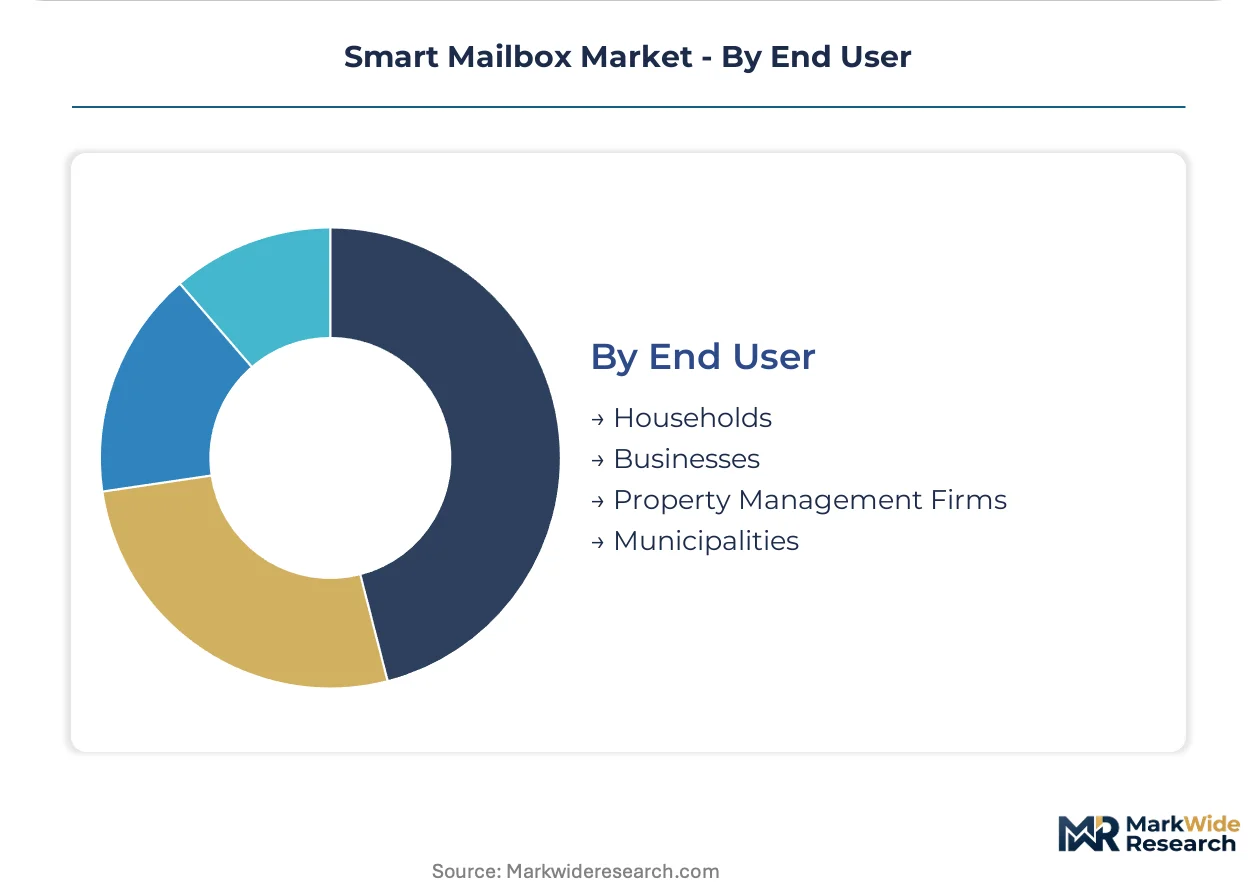
End User:
Customer type determines procurement channel and contract structure, with enterprise accounts demanding platform integration and municipalities imposing specification mandates.
- Property Management Firms:Multifamily operators in California and Texas drive enterprise-scale deployments, consolidating smart mailbox procurement within integrated facility management platforms. FCC Part 15 certification accelerates their approval timelines for cellular-connected estates.
- Households:Individual consumers purchasing through retail channels or builder-installed options in new construction, with Wi-Fi dependency creating higher support costs than cellular alternatives.
- Businesses:Corporate campuses and retail chains seeking consolidation points for internal logistics and customer pickup services.
- Municipalities:City governments embedding smart parcel infrastructure in public rights-of-way and transit-adjacent locations.
Property Management Firms dominate contract value. Municipalities are rotating up the share rankings through ordinance-driven mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in California and Texas demonstrate low price elasticity as municipal mandates and insurance requirements override cost concerns, while individual consumers in suburban markets remain highly sensitive to hardware pricing and subscription fees.
United States
The FCC's Part 15 certification framework accelerates product approval timelines for cellular-connected units, reducing regulatory friction for vendors entering the market. Property management firms in Texas cities face emerging ordinances mandating smart parcel infrastructure in new multifamily construction permits. Dallas and Houston clusters concentrate deployment activity where e-commerce penetration intersects with dense residential development.
Germany
REACH compliance and CE marking requirements shape hardware import pathways for connected mailbox modules entering the European market. The EU Green Deal pressures vendors toward energy-efficient power configurations and recyclable enclosure materials. Industrial procurement in Bavaria and North Rhine-Westphalia favors parcel locker systems integrated with facility management platforms.
China
MIIT radio transmission regulations and GB standards govern cellular module certification for IoT-enabled receptacles manufactured for domestic and export markets. Dual carbon goals accelerate demand for solar-powered residential units in tier-one cities. Manufacturing clusters in the Yangtze River Delta and Pearl River Delta dominate component supply for global smart mailbox assembly.
Japan
METI guidelines on IoT security and JIS standards for outdoor electrical enclosures establish product compliance baselines for connected mailbox deployments. Aging demographics and single-person households drive demand for remote package management in Tokyo and Osaka metropolitan areas. Kanto region property developers integrate parcel lockers into new condominium construction as standard amenity.
United Kingdom
GDPR compliance requirements shape data handling protocols for delivery notification systems and access credential management platforms. Royal Mail API integration capabilities determine vendor competitiveness in urban consolidation point deployments. London and Southeast England concentrate multifamily construction activity where smart mailbox adoption aligns with tenant convenience expectations.
Smart Mailbox Market Competitive Landscape
Capability concentration sits with software-defined platform specialists; scale advantage sits with franchise-network operators and virtual mail infrastructure incumbents. The vendor base organizes around three strategic archetypes: virtual mail scanning services with recurring subscription models, hardware-software integrated platform providers, and franchise-expansion networks targeting retail consolidation points. Dominant competitive moves include API integration partnerships with major carriers and vertical integration into cloud-based tenant management platforms.
Among virtual mail specialists, iPostal1 exemplifies the software-centric archetype with infrastructure sustaining recurring revenue streams. Anytime Mailbox represents the franchise-expansion model with North American retail location penetration. US Global Mail anchors the corporate relocation segment serving expatriate and specialized forwarding demand. These three occupy distinct positioning vectors without direct feature-for-feature competition.
| Leading Market Players |
|---|
| iPostal1 |
| Google Workspace |
| Traveling Mailbox |
| Rackspace Email |
| Zoho Mail |
| PostScan Mail |
| Anytime Mailbox |
| Missive |
| US Global Mail |
| Others |
Value Network & Pricing Analysis
Trans-Pacific container freight corridors from Shanghai to Long Beach anchor cost dynamics across smart mailbox supply chains, with rate volatility compressing hardware margins and forcing tiered pricing separation between cellular-connected premium units and Wi-Fi-dependent economy SKUs.
Pricing Analysis
Aftermarket service revenue tiers now drive lifetime value capture as hardware margins compress across the smart mailbox value chain. Three-tier pricing structure across premium, standard, and economy levels stratifies by connectivity architecture and certification grade, with UL 294-certified cellular units commanding sustained premiums while Wi-Fi-only SKUs face price erosion from commoditized enclosure supply. Property management firms in Texas and California demonstrate low price sensitivity where municipal mandates override cost concerns, whereas individual suburban households remain highly responsive to subscription fee thresholds.
Supply Chain Analysis
Upstream feedstock concentration in lithium-ion battery cells centers on China, South Korea, and Japan, with cylindrical 18650 and 21700 formats serving as the dominant power module chemistry for outdoor-rated smart mailbox deployments. LTE-M and NB-IoT cellular chipsets draw from narrow supplier bases in Taiwan and the United States, creating single-source vulnerability for connected hardware vendors. Tariff exposure on steel enclosures and electronic locking mechanisms from China-based fabrication compresses procurement flexibility. Distribution runs through direct vendor relationships with property management conglomerates, displacing traditional distributor intermediaries in enterprise accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among California and Texas property management conglomerates, with procurement consolidation into integrated facility management platforms fragmenting vendor negotiation leverage.
For Market Incumbents: Insulate recurring revenue streams by deepening API integration with FedEx, UPS, and postal systems to create switching costs that defend against emerging software-centric competitors. Backward integration into cloud-based tenant management platforms addresses the threat of procurement consolidation by embedding smart mailbox functionality within broader facility management workflows. Certification investment in FCC Part 15 and emerging state-level delivery notification standards preserves access to enterprise RFP pipelines. For New Entrants and Emerging Players: Pursue corporate relocation and expatriate forwarding services as the most penetrable white-space segment, where specialized virtual mail management remains underdeveloped relative to saturated consumer markets. Municipal ordinance mandates in Texas cities create immediate deployment opportunities for compliant parcel locker systems in new multifamily construction. A franchise-expansion go-to-market angle replicates proven retail consolidation point models without requiring direct enterprise sales infrastructure. For Investors and Strategic Acquirers: FCC Part 15 regulatory clarity reshapes the acquisition landscape by reducing approval timeline risk for cellular-connected hardware portfolios. Long-term viability centers on software-defined platform specialists with demonstrated API integration capabilities and recurring subscription economics rather than pure hardware vendors. The signal to watch is municipal construction mandate adoption velocity across additional state jurisdictions beyond California and Texas.| Strategic Initiative | Industry Significance |
|---|---|
| API Integration Partnership | Real-time FedEx and UPS handoff capabilities differentiate vendor positioning in enterprise procurement. |
| Cloud Platform Acquisition | Control over tenant management software embeds smart mailbox functionality within facility workflows. |
| Cellular Module Supply Agreement | Locked capacity for LTE-M chipsets mitigates single-source vulnerability in connected hardware. |
| Municipal Compliance Certification | State-level delivery notification standards unlock RFP access from regulated property portfolios. |
| Franchise Network Expansion | Retail consolidation point penetration captures consumer segment demand without direct sales overhead. |
Research Methodology
Operator-level perspectives from property management executives, smart mailbox procurement officers, IoT platform engineers, and municipal planning officials anchored the qualitative base for this study. Primary interviews combined with secondary validation from FCC equipment authorization databases, UL certification registries, multifamily housing construction permits, and carrier API integration documentation. Bottom-up unit deployment estimates triangulated against top-down market sizing from facility management platform consolidation trends.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product configuration, connectivity architecture, usage scenario, and end-user procurement channel. CAGRs derived from deployment trajectory modeling incorporating municipal mandate adoption curves, e-commerce penetration elasticities, and insurance underwriting evolution for theft liability. Industry-specific inputs included property management software integration friction coefficients and cellular module cost decline trajectories.
Macroeconomic conditions sit as an overlay; deviation in residential construction starts, lithium cell pricing, and trans-Pacific freight rates would shift the trajectory. Forecasts reflect documented assumptions about regulatory adoption timelines and carrier API standardization progress. Cross-checking against municipal permit issuance data and property insurance claim trends is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
UAE Smart Furniture Market
Smart City Technology
Smart Parcel Delivery Locker Market
Smart City Technology
Global Smart/Connected Street Lights Market
Smart City Technology
Outdoor LED Smart Lighting Solution Market
Smart City Technology
India Smart City Market
Smart City Technology
US Smart Cities Market
Smart City Technology
Smart Package Lockers Market
Smart City Technology
Global Smart Ticketing Market
Smart City Technology
Singapore ICT Market
Smart City Technology
Smart Ticketing Solutions Market
Smart City Technology
Smart City Framework Market
Smart City Technology
Saudi Arabia Smart Cities Market
Smart City Technology
Global Smart City Market
Smart City Technology
Smart Street Lights Market
Smart City Technology
Global Smart Hubs Market
Smart City Technology
Smart Parking Meters Market