
 Smart City Framework Market | 2026-2036
Smart City Framework Market Size, Share, and Industry Trends Forecast 2026-2036
Smart City Framework Market Analytics
Transportation authority procurement is decoupling from legacy siloed systems as cities prioritize unified command platforms. Siemens leverages deep domain expertise in rail signaling and traffic control to anchor European infrastructure bids. Huawei Technologies dominates integrated IoT-to-cloud deployments across Asian municipalities with vertically bundled hardware-software stacks. Cisco Systems extends its enterprise networking dominance into urban edge computing through specialized smart streetlight and sensor gateway portfolios.
A smart city framework constitutes an integrated digital architecture combining IoT sensor networks, AI-driven analytics engines, cloud computing infrastructure, and big data processing layers to orchestrate urban services in real time. The system operates through edge-to-cloud data pipelines that ingest telemetry from distributed endpoints—traffic cameras, environmental monitors, utility meters—and apply machine learning models to optimize resource allocation, emergency response routing, and energy load balancing across municipal boundaries. IoT and AI segments command the deepest R&D investment as cities demand predictive rather than reactive operational capabilities. Cloud computing deployment models are splitting sharply between public cloud preference among mid-sized municipalities and hybrid architectures favored by large metros with legacy on-premises security requirements. Energy management applications within the application layer are attracting disproportionate capital as grid decentralization and building electrification mandates intensify.
The EU AI Act imposes algorithmic transparency requirements on automated urban decision systems, while GDPR constrains how citizen mobility data can be stored and processed across municipal cloud instances. The U.S. FCC governs spectrum allocation for city-scale IoT networks, and NHTSA coordinates vehicle-to-infrastructure communication standards that directly shape traffic management platform specifications. Stakeholders must monitor how divergent data localization rules across national regulators fragment otherwise standardized framework deployments.
Market Dynamics
Transportation authorities are decoupling from legacy siloed systems and consolidating procurement around unified command platforms that integrate traffic signals, emergency dispatch, and utility grids into single-pane-of-glass operations.
Growth Catalysts
- India's Smart Cities Mission:Central government funding mandates IoT backbone deployment across 100 urban centers, creating standardized procurement templates for integrated traffic and waste management systems.
- EU AI Act algorithmic transparency rules:Automated urban decision systems must maintain audit trails, accelerating vendor investment in explainable AI architectures for traffic routing and energy load balancing.
- Vehicle-to-infrastructure communication standards:NHTSA coordination of CV2X protocols is forcing traffic management platform upgrades that support real-time collision avoidance and signal preemption.
Market Restraints
- Semiconductor supply concentration:Edge computing gateways and sensor modules depend on foundry capacity concentrated in Taiwan and South Korea, exposing municipal procurement timelines to wafer allocation volatility.
- GDPR data localization friction:Cross-border cloud processing of citizen mobility telemetry requires jurisdictional instance separation, fragmenting otherwise standardized framework architectures.
- Legacy system entrenchment:Decades-old SCADA and traffic signal controllers in established metros resist API-based integration without costly middleware layers.
Strategic Opportunities
- Grid decentralization mandates:Building electrification codes in Germany and California are creating demand for district-level energy management modules that optimize behind-the-meter storage and EV charging loads.
- Privacy-preserving analytics convergence:Federated learning architectures combined with edge AI enable predictive maintenance without centralizing sensitive infrastructure telemetry.
- Municipal data monetization frameworks:Singapore and Barcelona are piloting regulated marketplaces where aggregated anonymized mobility data generates revenue streams for smart city reinvestment.
Industry Challenges
- Cyber-physical security skill scarcity:Municipal IT departments lack personnel trained in both OT network segmentation and cloud-native zero-trust architectures.
- Interoperability certification delays:Fragmented testing protocols across ISO, IEC, and national standards bodies prolong vendor validation cycles before framework deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart City Framework Market |
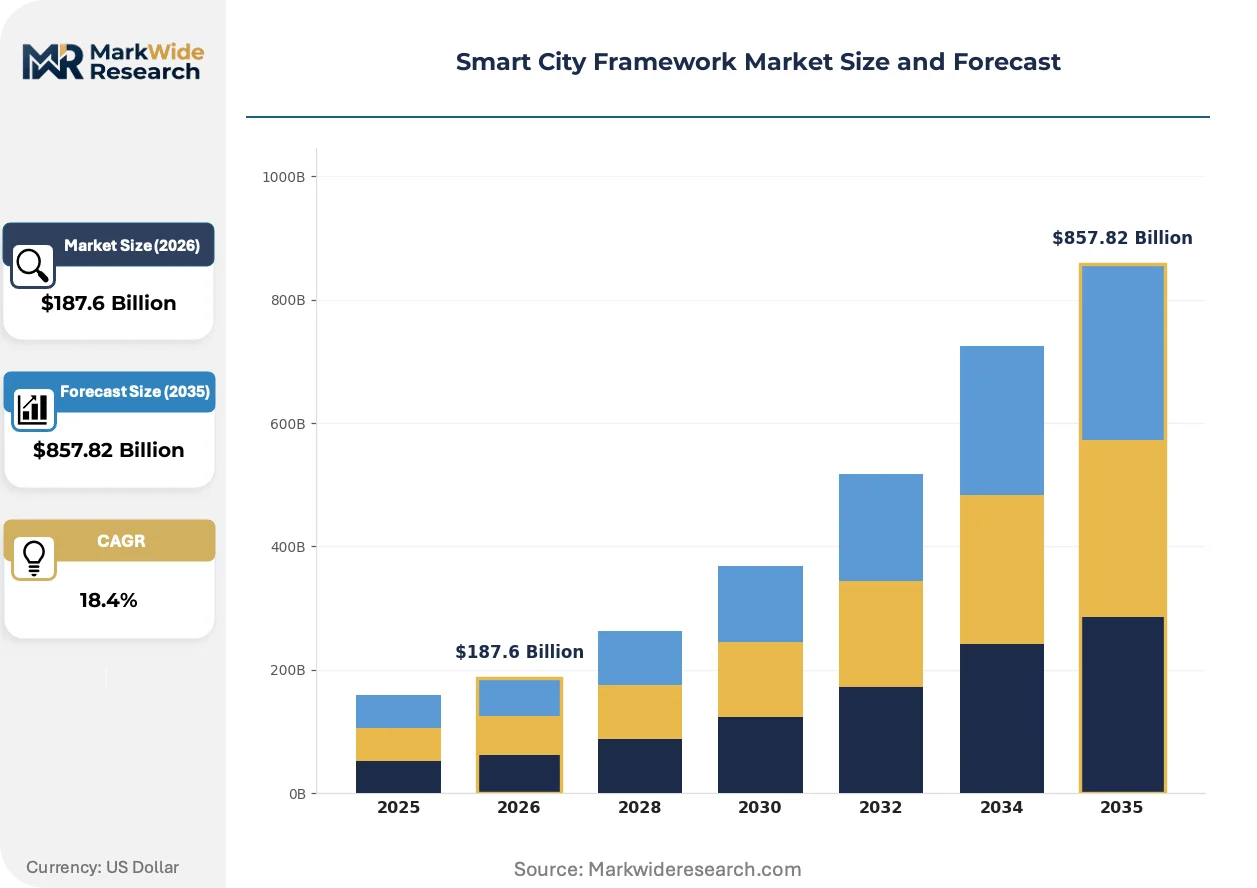
| Market Size in 2026 | $187.6 Billion |
| Market Size in 2035 | $857.82 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: IoT, AI, Cloud Computing, Big Data Application: Traffic Management, Waste Management, Energy Management, Smart Lighting End User: Municipalities, Transportation Authorities, Utility Companies, Telecommunication Providers Deployment Model: Public Cloud, Private Cloud, Hybrid Cloud, On-Premises |
| Companies Covered | IBM, Siemens, Cisco Systems, Hitachi, Microsoft, Huawei Technologies, Schneider Electric, Nokia, NEC, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart City Framework Market Evolving Landscape
Edge AI inference is migrating from centralized cloud instances to street-level gateways, compressing response latency for safety-critical applications while complicating software update orchestration across distributed device fleets.
Digital twin platforms are absorbing real-time sensor feeds from traffic cameras, air quality monitors, and water pressure sensors to simulate infrastructure stress scenarios before physical deployment. Asian transportation authorities are adopting these tools fastest, using them to model signal timing adjustments without disrupting live traffic flows. The technology is absorbing capital previously allocated to standalone simulation software suites.
The EU AI Act's risk classification system for automated urban decision-making is forcing vendors to rearchitect black-box machine learning models into interpretable rule-based overlays where high-stakes determinations occur. Traffic management platforms face the strictest scrutiny, with authorities in France and Germany demanding algorithmic impact assessments before procurement approval. Vendors are responding by open-sourcing model documentation and establishing third-party audit partnerships.
Municipal procurement offices are consolidating vendor relationships around outcome-based service level agreements that tie payment to measurable reductions in congestion or energy consumption. Large metros in Texas and Ontario are leading this shift, replacing capital-intensive hardware purchases with subscription models where vendors retain equipment ownership. This restructuring is visible most clearly in streetlight-as-a-service contracts that bundle LED conversion, sensor deployment, and maintenance into unified 10-year agreements.
Smart City Framework Market Segmentation
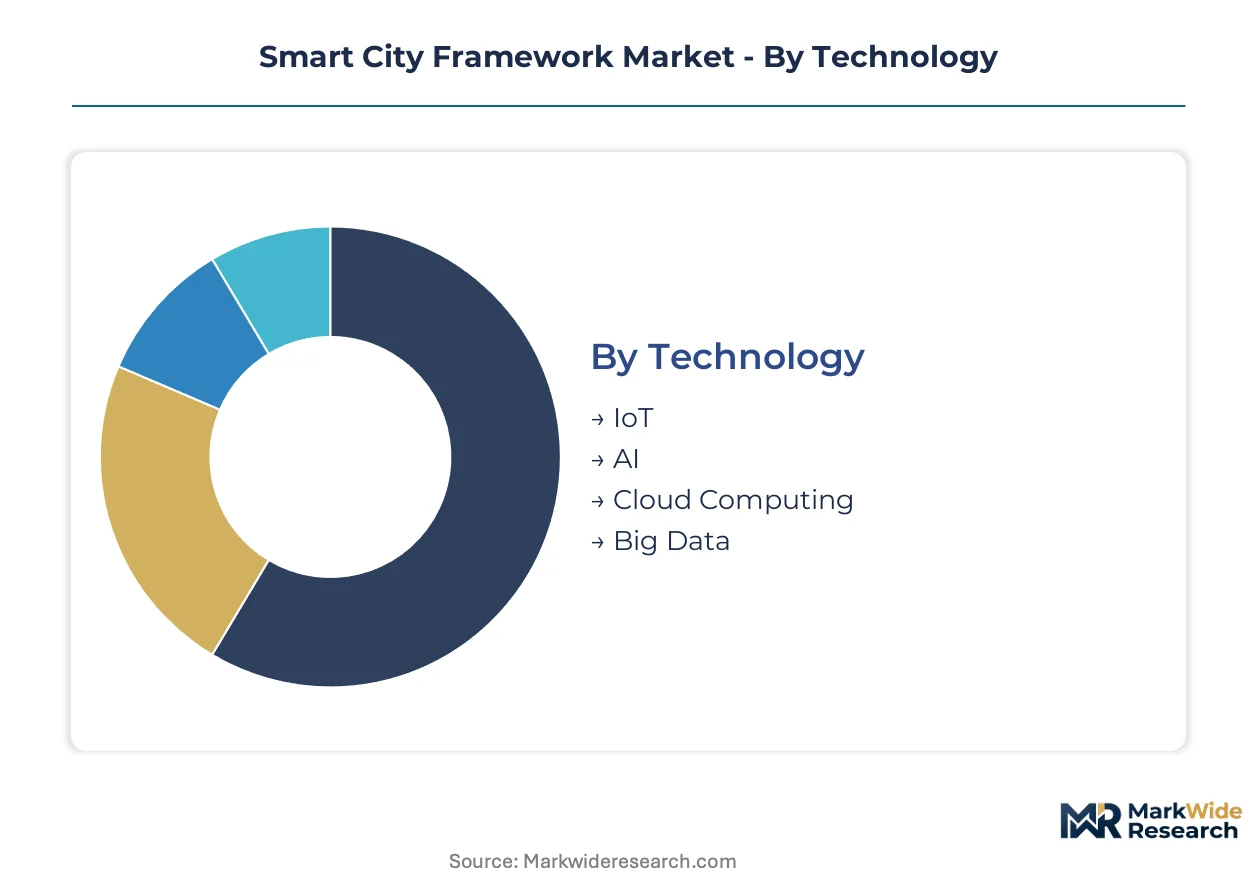
Smart city framework procurement splits sharply by technology stack, operational application, and governance model. Municipal buyers evaluate segments against legacy integration burdens, cybersecurity postures, and long-term vendor viability.
Technology:
Capital intensity peaks in hardware-dependent layers requiring sensor deployment and edge infrastructure, while software-centric segments scale with lower marginal costs.
- IoT:Distributed sensor networks and edge gateways form the physical data ingestion layer. Indian municipalities under the Smart Cities Mission are deploying street-level environmental and traffic monitors at scale, though semiconductor supply concentration in Taiwan and South Korea creates procurement timeline risk.
- AI:Machine learning engines process telemetry for predictive optimization. EU AI Act algorithmic transparency mandates are forcing vendors to rearchitect black-box models into interpretable rule-based overlays for traffic routing and energy load balancing applications.
- Cloud Computing:Scalable compute and storage resources host analytics workloads. Mid-sized municipalities favor public cloud for cost efficiency, while large metros with legacy security requirements adopt hybrid architectures.
- Big Data:Distributed processing frameworks aggregate multi-source urban telemetry. GDPR data localization constraints fragment otherwise standardized architectures across jurisdictional cloud instances.
Most installed capacity flows through IoT. Expansion is steepest in AI.
Application:
Demand concentrates where regulatory mandates intersect with visible citizen impact and measurable operational savings.
- Traffic Management:Unified signal control, emergency dispatch integration, and vehicle-to-infrastructure communication platforms. NHTSA coordination of CV2X protocols is forcing upgrades that support real-time collision avoidance across Texas and Ontario metros.
- Energy Management:Grid optimization, behind-the-meter storage coordination, and EV charging load balancing. Germany and California building electrification codes are creating demand for district-level modules that optimize decentralized resources.
- Waste Management:Sensor-enabled collection routing and fill-level optimization. Smart Cities Mission standardized procurement templates accelerate deployment across Indian urban centers.
- Smart Lighting:LED conversion bundled with sensor hosting and connectivity infrastructure. Municipal procurement offices in North America are shifting to 10-year streetlight-as-a-service contracts with outcome-based payment tied to energy reduction metrics.
Traffic management absorbs the largest share of municipal capital budgets. Energy management is climbing the fastest as grid decentralization mandates intensify.
End User:
Procurement authority fragmentation across departmental silos complicates unified framework deployment.
- Municipalities:City governments with consolidated IT and operational technology budgets. Indian Smart Cities Mission creates standardized procurement templates that bypass traditional departmental fragmentation.
- Transportation Authorities:Regional bodies managing traffic signal networks and public transit systems. Asia-Pacific authorities are decoupling from legacy siloed systems fastest, consolidating around unified command platforms.
- Utility Companies:Electricity, water, and gas distributors with grid modernization mandates. California and German electrification codes are accelerating investment in behind-the-meter optimization modules.
- Telecommunication Providers:Carriers deploying city-scale IoT network infrastructure and edge computing nodes. FCC spectrum allocation governs deployment parameters in the United States.
Municipalities command the largest aggregate procurement volume. Transportation authorities are gaining share fastest as regional integration mandates proliferate.
Deployment Model:
Security posture and legacy system entrenchment drive architectural divergence between public and private infrastructure preferences.
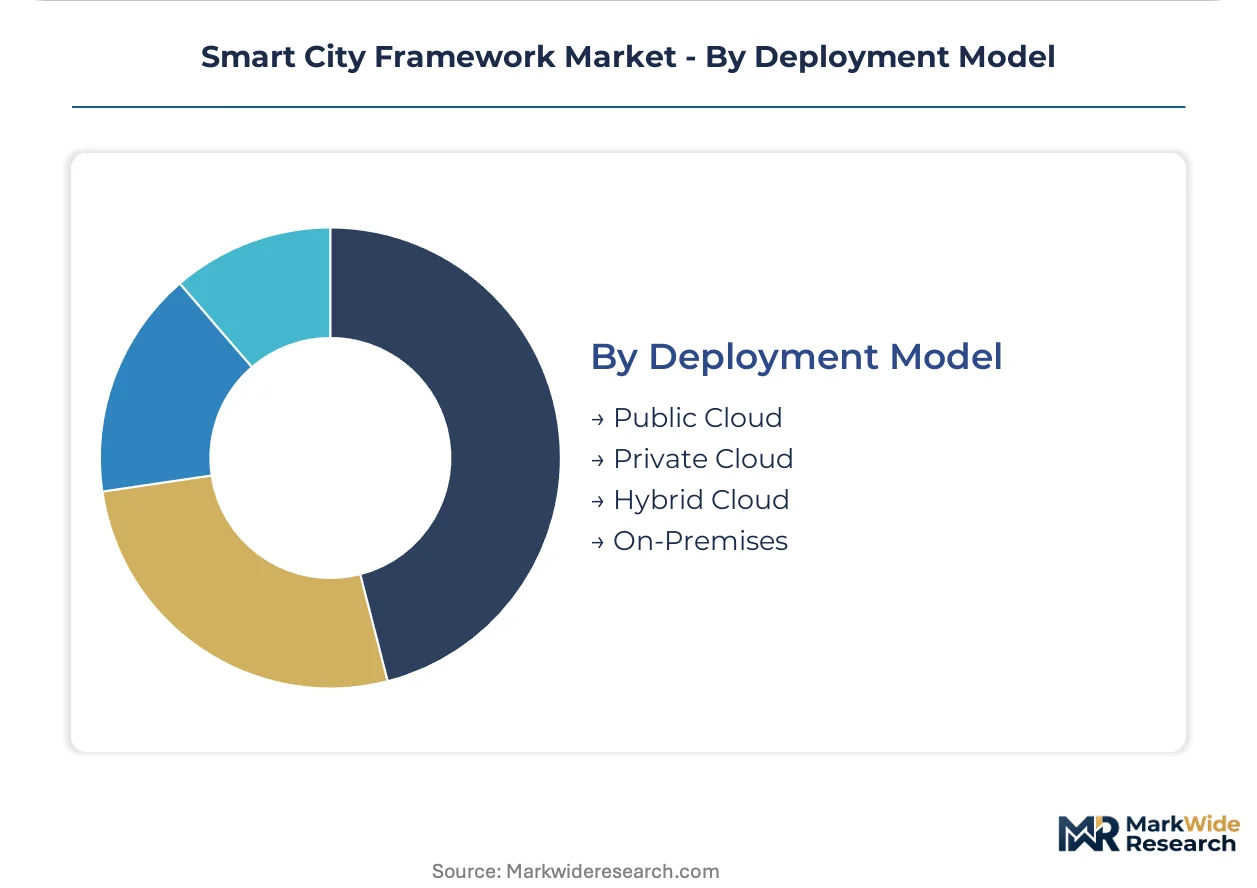
- Public Cloud:Third-party hosted compute and storage with shared infrastructure economics. Mid-sized municipalities in North America and Europe favor this model for rapid deployment without capital-intensive data center construction.
- Hybrid Cloud:Split workloads across on-premises and cloud-hosted resources. Large metros with decades-old SCADA systems and stringent data residency requirements adopt this architecture to satisfy GDPR localization constraints.
- Private Cloud:Dedicated infrastructure with single-tenant isolation. Defense-adjacent or critical infrastructure applications in Germany and France mandate this model under national cybersecurity frameworks.
- On-Premises:Fully localized hardware and software stacks. Legacy traffic signal controllers and utility SCADA systems in established metros resist API-based integration without costly middleware layers.
Hybrid cloud carries the largest installed base. Public cloud is expanding most quickly among mid-sized municipalities with limited legacy entanglement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pearl River Delta anchors smart city framework deployment through Shenzhen's integrated IoT-to-cloud infrastructure and Guangzhou's traffic management digitization.
United States
Texas and Ontario metros are consolidating procurement around unified command platforms that integrate traffic signals with emergency dispatch systems. The FCC governs spectrum allocation for city-scale IoT networks while NHTSA coordinates vehicle-to-infrastructure communication standards. Austin and Dallas transportation authorities are decoupling fastest from legacy siloed systems.
Germany
Building electrification codes in Bavaria and North Rhine-Westphalia are creating demand for district-level energy management modules. The EU AI Act imposes algorithmic transparency requirements on automated urban decision systems while GDPR constrains citizen mobility data processing. Berlin and Munich municipalities favor hybrid cloud architectures to satisfy data residency requirements.
India
The Smart Cities Mission mandates IoT backbone deployment across 100 urban centers with standardized procurement templates for integrated traffic and waste management systems. BIS certification requirements shape vendor qualification protocols. Pune and Ahmedabad are accelerating municipal digitization at scale through central government funding.
China
MIIT standards govern smart city framework specifications while dual carbon goals intensify energy management application demand. Shanghai and Beijing metros deploy edge AI inference at street-level gateways for safety-critical traffic applications. Yangtze River Delta municipalities lead digital twin platform adoption for infrastructure stress simulation.
Singapore
Pilot programs for regulated data marketplaces enable revenue generation from aggregated anonymized mobility data. The city-state's national cybersecurity framework mandates private cloud deployment for critical infrastructure applications. Smart nation initiatives concentrate vendor relationships around outcome-based service level agreements.
Smart City Framework Market Competitive Landscape
Strategic partnerships dominate the current landscape as vendors bundle hardware, software, and service layers into unified offerings. The vendor base organizes around three archetypes: diversified industrial conglomerates with deep domain expertise in infrastructure, cloud-native technology providers with analytics capabilities, and specialized networking equipment manufacturers with edge computing portfolios. Technology licensing agreements and geographic expansion represent the most visible competitive moves.
Among diversified industrial specialists, Siemens leverages rail signaling and traffic control expertise to anchor European infrastructure bids. Huawei Technologies occupies a position exemplifying vertically bundled hardware-software stack deployment across Asian municipalities. Cisco Systems represents the networking-centric archetype extending enterprise dominance into urban edge computing through specialized gateway portfolios.
| Leading Market Players |
|---|
| IBM |
| Siemens |
| Cisco Systems |
| Hitachi |
| Microsoft |
| Huawei Technologies |
| Schneider Electric |
| Nokia |
| NEC |
| Others |
Value Network & Pricing Analysis
Performance-tier divergence between mission-critical infrastructure deployments and pilot municipal projects manifests in both procurement economics and component sourcing strategies. Premium-tier frameworks command substantial cost premiums through hardened edge hardware and private cloud architectures, while economy-tier deployments rely on commoditized sensor modules and public cloud instances that source from entirely different supplier ecosystems.
Pricing Analysis
Input-cost pass-through from semiconductor foundry capacity constraints directly shapes municipal procurement timelines and vendor margin structures. Three-tier pricing structure across premium, standard, and economy levels differentiates on cybersecurity certification grade and edge-computing redundancy specifications. Pricing pressure stems from foundry concentration in Taiwan and South Korea exposing gateway and sensor module costs to wafer allocation volatility. Mid-sized municipalities exhibit highest price sensitivity, deferring hybrid cloud investments for public cloud economics, while defense-adjacent applications in Germany and France absorb premium private cloud pricing without elasticity.
Supply Chain Analysis
Edge AI processor supply rests on Taiwanese semiconductor foundries and South Korean memory fabricators, with Chinese module assemblers completing gateway production. Critical dependencies include ARM-based system-on-chip designs, industrial-grade sensor MEMS, and fiber-optic transceivers for backhaul connectivity. Single-source vulnerability concentrates in advanced node lithography for AI inference accelerators, where geopolitical export controls threaten component availability. Distribution runs through systems integrators with municipal procurement relationships rather than direct vendor-to-city sales channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Smart City Framework Market operates as a regulatory compounder where the EU AI Act's algorithmic transparency mandates accelerate vendor investment cycles and reshape competitive positioning around explainable AI architectures.
For Market Incumbents: Deploy federated learning architectures to neutralize GDPR data localization friction as a competitive differentiator against cloud-native entrants. Incumbent vendors must consolidate around outcome-based service level agreements that tie payment to congestion reduction metrics, defending against specialized networking equipment manufacturers with edge computing portfolios. Certification investment in BIS compliance for Indian Smart Cities Mission procurement templates represents a critical lever for market retention. For New Entrants and Emerging Players: The price-point gap between premium private-cloud deployments and economy-tier public-cloud pilots creates entry opportunity for hybrid-edge specialists with modular subscription pricing. New entrants should target mid-sized North American municipalities with limited legacy SCADA entanglement as the most penetrable segment, using streetlight-as-a-service contracts as the go-to-market angle to bypass capital-intensive municipal budget cycles. For Investors and Strategic Acquirers: Consolidation pressure builds where cyber-physical security skill scarcity fragments municipal IT department capabilities across OT network segmentation and cloud-native zero-trust architectures. Long-term viability favors vendors with integrated hardware-software stacks and deep domain expertise in traffic control or rail signaling. The signal to watch is interoperability certification delays across ISO, IEC, and national standards bodies, which prolong vendor validation cycles and favor incumbents with established testing relationships.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies traffic signal, emergency dispatch, and utility grid telemetry into single-pane operations for Texas and Ontario metros. |
| Strategic Partnership | Establishes third-party audit relationships for EU AI Act algorithmic impact assessments in France and Germany. |
| Geographic Expansion | Positions vendors for standardized procurement templates across 100 urban centers under India's Smart Cities Mission. |
| Acquisition of Specialist Firm | Absorbs digital twin simulation capabilities for infrastructure stress modeling in Yangtze River Delta municipalities. |
| Product Launch | Introduces district-level energy management modules optimized for Germany and California building electrification codes. |
Research Methodology
Direct dialogue with municipal CIOs, transportation authority procurement directors, utility grid modernization leads, and smart city program managers grounded qualitative insights in operational reality. Secondary validation drew from FCC spectrum allocation filings, NHTSA vehicle-to-infrastructure communication standards, EU AI Act regulatory texts, and Indian Smart Cities Mission procurement documentation. Bottom-up and top-down triangulation reconciled vendor shipment data with municipal budget appropriations and infrastructure deployment timelines.
Bottom-up modeling segmented revenue across IoT sensor networks, AI analytics engines, cloud computing infrastructure, and big data processing layers, with cross-validation against top-down macroeconomic indicators and urbanization trends. Deployment model splits between public cloud, hybrid cloud, private cloud, and on-premises architectures were modeled alongside application segmentation across traffic management, energy management, waste management, and smart lighting. CAGRs derived from historical procurement velocity and regulatory mandate implementation schedules, with semiconductor supply concentration and data localization constraints as scenario variables.
Caveats apply where foundry capacity allocation volatility, cross-border data processing restrictions, or legacy system integration failures could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement consistency and municipal budget continuity that may not hold across the projection horizon. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Smart City Technology
Smart Signaling Market
Smart City Technology
Smart Mailbox Market
Smart City Technology
Singapore ICT Market
Smart City Technology
India Smart City Market
Smart City Technology
US Smart Cities Market
Smart City Technology
Smart Package Lockers Market
Smart City Technology
Global Smart Hubs Market
Smart City Technology
Smart Parcel Locker Market
Smart City Technology
Smart Shade Device Market
Smart City Technology
Smart City Kiosk Deployment Market
Smart City Technology
Global Smart City Market
Smart City Technology
Smart Parcel Delivery Locker Market
Smart City Technology
Smart City Kiosk Market
Smart City Technology
City Data Platform Market
Smart City Technology
UAE Smart Furniture Market
Smart City Technology
E-Governance Market