
 Automotive Belts and Hoses Market | 2026-2036
Automotive Belts and Hoses Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Belts and Hoses Market Outlook
Electric vehicle thermal management is realigning traditional belt and hose portfolios toward battery cooling circuits and electric compressor drives. Gates Corporation leverages its fluoropolymer hose expertise to anchor positions in EV coolant architectures across North American and Asian OEM programs. Continental AG sustains broad manufacturing scale across serpentine belt systems while competing in integrated thermal module supply. Dayco IP Holdings LLC specializes in lightweight tensioner and decoupler technologies that differentiate its portfolio in hybrid powertrain applications.
Automotive belts and hoses encompass elastomeric power transmission and fluid conveyance components, typically constructed from ethylene-propylene-diene monomer rubber reinforced with polyester or aramid cord, operating within temperature ranges of minus forty to one hundred fifty degrees Celsius to synchronize engine timing, drive accessories, and circulate coolant or fuel. Serpentine belts and cooling system hoses occupy the largest volume positions due to universal fitment across internal combustion architectures, though timing belts face gradual displacement by maintenance-free chain systems in certain engine families. Polyurethane and silicone material segments command premium positioning for high-turbocharger and electric vehicle thermal applications where reinforced rubber formulations encounter durability limits.
EPA Corporate Average Fuel Economy standards and the EU F-Gas Regulation constrain refrigerant hose permeability specifications, while China's MIIT enforces GB standards for engine accessory drive durability that OEMs must satisfy for type approval. NHTSA defect investigation protocols and Japan's METI energy efficiency frameworks further condition product liability exposure and material substitution timelines for suppliers. Stakeholders must monitor regulatory divergence between thermal management refrigerant chemistries and belt efficiency testing protocols to align R&D allocation with compliance windows.
Market Dynamics
Electric vehicle thermal architecture is compressing traditional accessory belt volumes while expanding fluoropolymer hose specifications for battery cooling loops, forcing suppliers to rebalance manufacturing footprints between legacy internal combustion and emerging EV platforms.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:These mandates accelerate lightweight aramid-reinforced belt adoption across passenger vehicle programs to reduce parasitic engine losses.
- China's NEV platform proliferation:Domestic OEM procurement for integrated thermal management modules is expanding hose assembly volumes beyond conventional cooling circuit specifications.
- Silicone material advancement:High-temperature elastomer formulations enable turbocharger feed lines and electric compressor connections that EPDM rubber cannot sustain.
Market Restraints
- Petrochemical feedstock volatility:EPDM and fluoropolymer resin costs fluctuate with crude oil derivatives, compressing compounder margins on fixed-price OEM contracts.
- German supplier concentration:Continental AG and specialized Tier-2 compounders dominate premium serpentine belt supply, creating bottleneck risk for mid-tier manufacturers seeking qualification.
- Timing belt substitution:Maintenance-free chain systems from Japanese and Korean powertrain specialists are displacing toothed rubber belts in four-cylinder engine families.
Strategic Opportunities
- India aftermarket expansion:Aging passenger vehicle parc and fragmented service networks create demand for branded replacement belts and molded coolant hoses outside OEM channels.
- EU F-Gas Regulation phase-down:Refrigerant hose permeability mandates for low-GWP chemistries favor fluoropolymer barrier constructions over standard rubber formulations.
- Vehicle-to-grid thermal integration:Bidirectional charging architectures require expanded battery cooling capacity, opening specification windows for multi-layer hose assemblies.
Industry Challenges
- Aramid cord processing expertise:Specialized tensioning and adhesion chemistry knowledge resides with aging technical workforces in Japanese and Italian manufacturing clusters.
- Dual-platform tooling investment:Suppliers must simultaneously maintain EPDM extrusion lines for legacy volume and install fluoropolymer cleanroom capacity for EV thermal contracts.
- GB standard compliance timelines:China's MIIT durability testing protocols for accessory drive systems impose extended validation cycles that delay program launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Belts and Hoses Market |
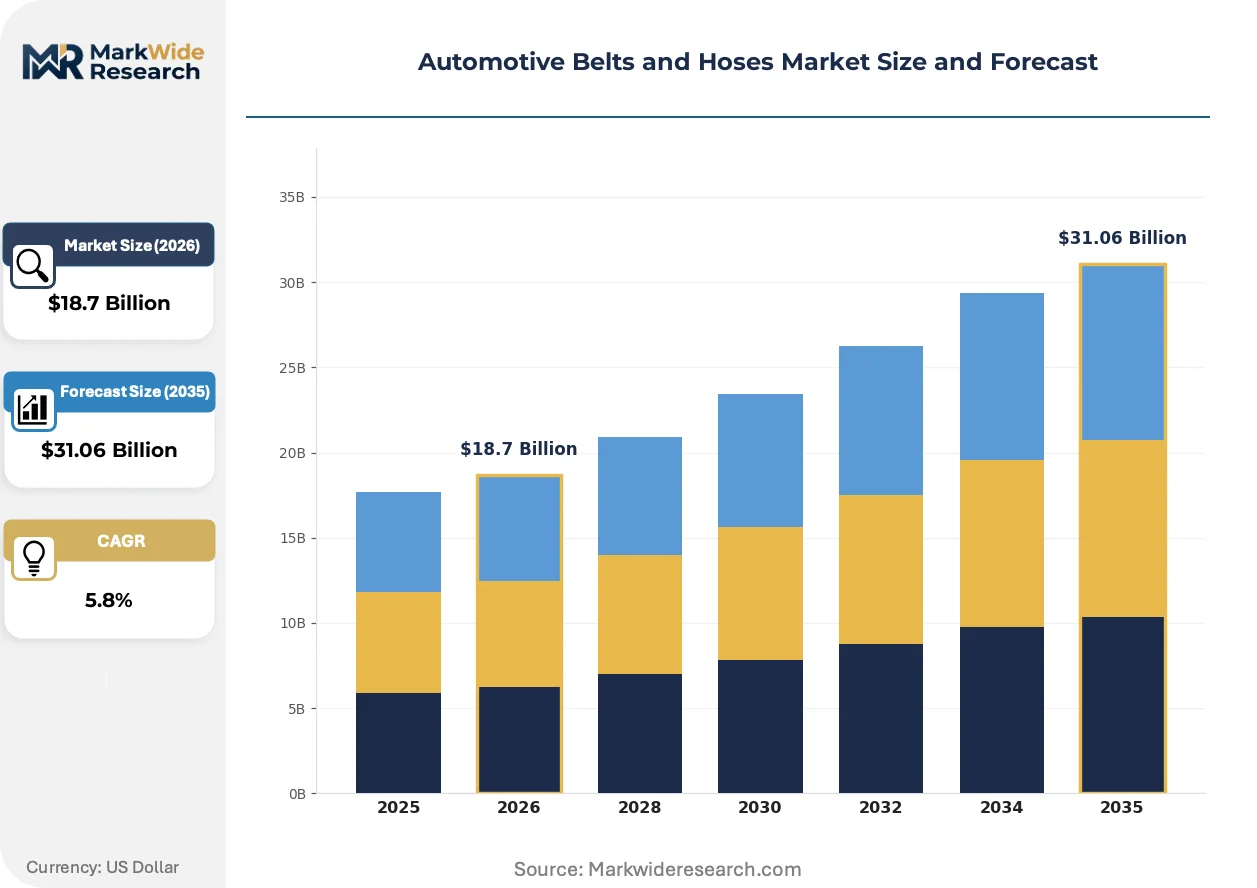
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $31.06 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Timing Belts, V-Belts, Serpentine Belts, Hoses Material: Rubber, Polyurethane, Silicone, Reinforced Application: Engine Components, Transmission, Cooling Systems, Fuel Systems End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Repair Shops |
| Companies Covered | Dayco IP Holdings LLC, Yokohama Rubber Co Ltd, Continental AG, Toyoda Gosei Co Ltd, Hutchinson SA, Sumitomo Riko Co Ltd, Goodyear Tire & Rubber Co, Schaeffler AG, Gates Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Belts and Hoses Market Strategic Shifts
Material science convergence with electrified powertrain thermal requirements is redrawing competitive boundaries between traditional rubber compounders and specialized fluoropolymer processors.
Multi-layer fluoropolymer barrier hoses with aramid fiber reinforcement are electrifying battery cooling circuit specifications. Korean and Chinese EV platforms specify these assemblies for dielectric fluid compatibility and rapid thermal cycling endurance. The technology is electrifying supplier qualification criteria, compressing incumbent EPDM compounders into commodity accessory belt segments.
REACH chemical authorization and EU F-Gas Regulation are tightening permissible polymer additives and refrigerant permeability thresholds. Compounders face reformulation costs for plasticizers and stabilizers previously grandfathered under legacy registrations. Thermal management hose suppliers serving European OEM programs absorb the most severe compliance burden, accelerating substitution toward pre-approved fluoropolymer stock.
Fleet operators and independent repair chains now demand predictive replacement intervals based on connected vehicle telemetry rather than fixed mileage schedules. Traditional wholesale distribution through jobber networks faces compression from direct-to-workshop digital procurement platforms. North American commercial vehicle segments exhibit the most pronounced behavioral shift, with large fleet managers consolidating purchases through integrated maintenance software vendors.
Automotive Belts and Hoses Market Segmentation
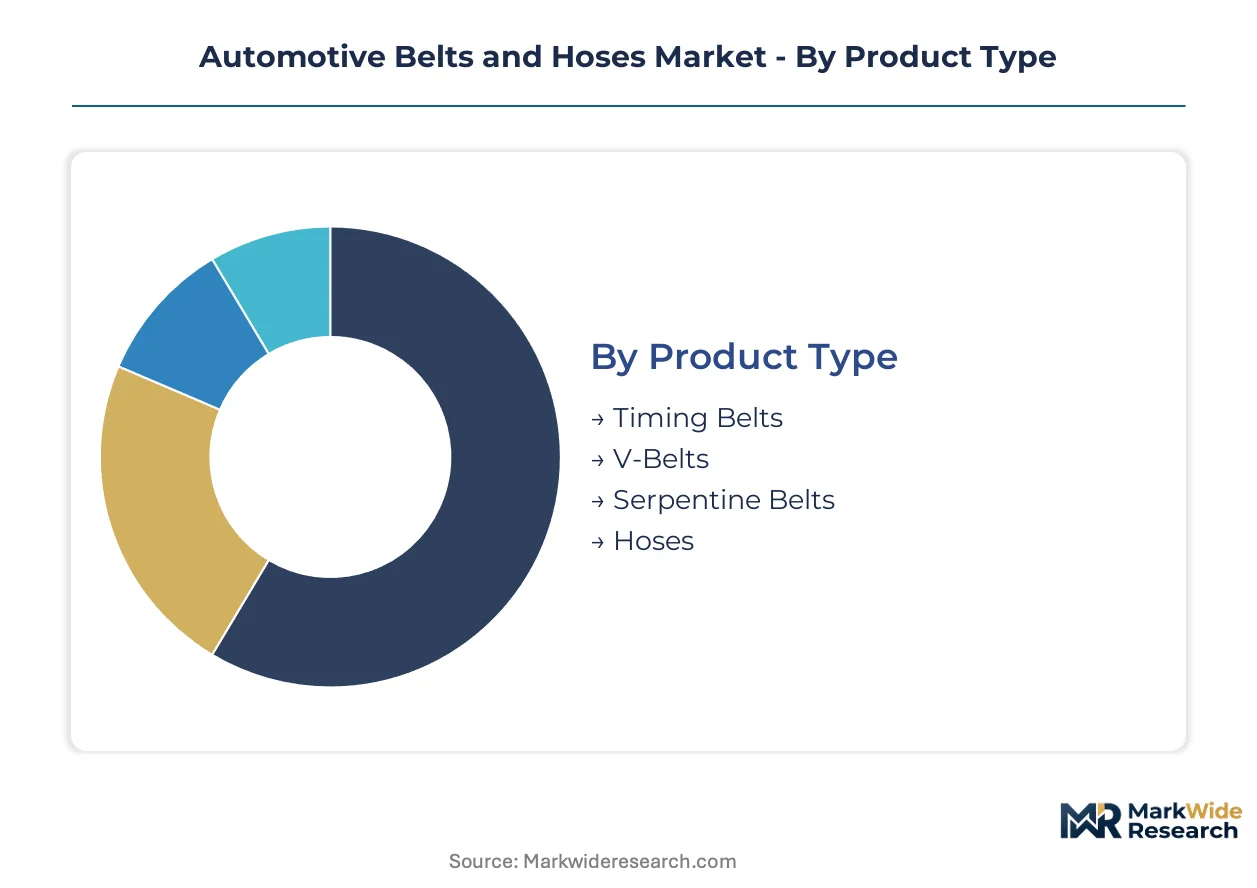
Segmentation in automotive belts and hoses reveals divergent technical requirements between legacy internal combustion architectures and electrified thermal systems. Suppliers must calibrate material science capabilities and manufacturing footprints across distinct integration depths—from standalone replacement components to embedded subsystem assemblies.
Product Type:
Standalone replacement belts dominate aftermarket channels, while embedded hose assemblies integrate directly into OEM thermal modules with minimal field serviceability.
- Timing Belts:Toothed rubber belts with fiberglass or aramid cord reinforcement synchronize crankshaft and camshaft rotation in interference engines. Demand concentrates in Southeast Asian and Latin American vehicle parcs where cost-sensitive four-cylinder architectures persist; chain substitution from Japanese powertrain specialists constrains growth in developed markets.
- Serpentine Belts:Multi-ribbed EPDM constructions drive alternators, air conditioning compressors, and power steering pumps through automatic tensioner systems. Volume placements cluster in North American and German light truck programs where accessory load requirements exceed V-belt capacity; EPA fuel economy standards accelerate aramid-reinforced lightweight specifications.
- V-Belts:Trapezoidal cross-section designs persist in commercial vehicle and agricultural equipment applications requiring high torque transmission at low speeds.
- Hoses:Multi-layer elastomeric assemblies convey coolant, fuel, and refrigerant through engine bays and thermal management circuits.
Volume placements concentrate in Serpentine Belts; the faster expansion belongs to Hoses.
Material:
Cost tiers separate commodity rubber formulations from premium polymer systems required for electrified powertrain thermal envelopes.
- Rubber:EPDM compounds reinforced with polyester cord dominate mass-market accessory belt and coolant hose specifications due to cost efficiency and broad temperature tolerance. Procurement concentrates in Chinese and Indian domestic OEM programs where GB standard compliance and BIS certification requirements prioritize proven formulations over advanced materials.
- Silicone:High-temperature elastomer formulations withstand turbocharger feed line conditions exceeding 200 degrees Celsius and electric compressor connections in battery thermal loops. Korean and Chinese EV platforms specify silicone for rapid thermal cycling endurance; EU F-Gas Regulation refrigerant compatibility mandates accelerate fluorosilicone barrier adoption.
- Polyurethane:Thermoplastic elastomers deliver abrasion resistance and flex fatigue performance in tensioner pulley coatings and select belt undercord applications.
- Reinforced:Aramid fiber and fluoropolymer composite constructions address dielectric fluid compatibility and permeability requirements in battery cooling circuits.
Cost-sensitive procurement favors Rubber; steepest expansion trajectory belongs to Reinforced composites.
Application:
Application scope determines thermal envelope severity and regulatory exposure across powertrain subsystems.
- Engine Components:Accessory drive belts and crankcase ventilation hoses operate within well-characterized temperature and vibration parameters. Fitment concentrates in Brazilian and Mexican light vehicle assembly where ANVISA environmental compliance and PROCONVE emission standards condition material selection for domestic market vehicles.
- Cooling Systems:Radiator hoses, heater core lines, and battery coolant loops manage thermal transfer across widening temperature differentials. Chinese NEV platform proliferation expands multi-layer hose specifications beyond conventional EPDM capabilities; MIIT GB standards for durability testing extend validation cycles for integrated thermal module suppliers.
- Transmission:Hydraulic clutch lines and CVT belt systems require specialized friction coefficients and fluid compatibility.
- Fuel Systems:Permeation-resistant barrier constructions address evaporative emission standards in gasoline direct injection architectures.
Volume placements concentrate in Engine Components; the fastest share gains belong to Cooling Systems.
End User:
Customer type dictates specification authority, contract structure, and service life accountability.
- OEMs:Vehicle manufacturers specify integrated belt-drive and thermal management assemblies through multi-year platform contracts with stringent validation protocols. Procurement authority concentrates in Wolfsburg, Detroit, and Shanghai engineering centers where design-in decisions commit suppliers to dedicated tooling investments.
- Tier-1 Suppliers:Thermal module integrators and powertrain subsystem contractors aggregate hose and belt specifications from qualified Tier-2 compounders. German supplier concentration around Continental AG and specialized compounders creates bottleneck risk for mid-tier manufacturers seeking qualification.
- Aftermarket Providers:Independent distributors and private-label brands serve replacement demand through jobber networks and digital procurement platforms.
- Repair Shops:Service bay installations of individual belts and molded hoses respond to failure modes and preventive maintenance schedules.
Volume placements concentrate in OEMs; the fastest expansion belongs to Aftermarket Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's Yangtze River Delta special economic zones concentrate fluoropolymer hose fabrication for NEV thermal modules. German supplier engineering centers in Wolfsburg and Stuttgart anchor serpentine belt specification authority. Detroit's automotive corridor sustains integrated belt-drive procurement for light truck platforms.
China
Domestic NEV platform proliferation from BYD, NIO, and Xpeng expands multi-layer coolant hose specifications beyond conventional EPDM capabilities. MIIT enforces GB standards for accessory drive durability that extend supplier validation cycles. Yangtze River Delta manufacturing clusters around Shanghai and Suzhou concentrate fluoropolymer cleanroom capacity for battery thermal contracts.
Germany
Continental AG and specialized Tier-2 compounders dominate premium serpentine belt supply for Volkswagen Group and BMW programs. EU F-Gas Regulation mandates low-GWP refrigerant hose permeability thresholds that favor fluoropolymer barrier constructions. Stuttgart engineering centers specify integrated thermal management modules that compress standalone component procurement.
United States
EPA Corporate Average Fuel Economy standards accelerate aramid-reinforced lightweight belt adoption across Ford and GM passenger vehicle programs. NHTSA defect investigation protocols condition product liability exposure for cooling system hose suppliers. Detroit's automotive corridor concentrates OEM procurement authority for integrated belt-drive assemblies.
Japan
Toyoda Gosei and Sumitomo Riko anchor timing belt and vibration-damping hose supply for Toyota and Honda powertrain platforms. METI energy efficiency frameworks accelerate material substitution timelines toward maintenance-free chain systems. Nagoya manufacturing clusters retain specialized aramid cord processing expertise for high-durability specifications.
India
Aging passenger vehicle parc and fragmented service networks create aftermarket demand for branded replacement belts and molded coolant hoses. BIS certification requirements prioritize proven EPDM formulations over advanced materials in domestic OEM programs. Maharashtra and Gujarat manufacturing corridors concentrate rubber compounding capacity for cost-sensitive procurement.
Automotive Belts and Hoses Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with integrated thermal module suppliers capturing specification authority over standalone component vendors. German and Japanese engineering centers dominate design-in decisions that commit suppliers to dedicated tooling investments. Three archetypes populate the competitive terrain: diversified rubber compounders with broad manufacturing scale, specialized fluoropolymer processors serving EV thermal architectures, and regional aftermarket distributors with fragmented service networks. Capacity expansion and portfolio diversification toward battery cooling circuits represent the dominant competitive moves.
Within the diversified compounder tier, Continental AG and Gates Corporation occupy positions that exemplify scale-driven supply across both legacy internal combustion and emerging EV platforms. Among Japanese fabricators, Toyoda Gosei and Sumitomo Riko represent specialized expertise in vibration-damping and high-durability specifications. Dayco IP Holdings LLC sits within the lightweight tensioner and decoupler specialization vector that differentiates hybrid powertrain applications.
| Leading Market Players |
|---|
| Dayco IP Holdings LLC |
| Yokohama Rubber Co Ltd |
| Continental AG |
| Toyoda Gosei Co Ltd |
| Hutchinson SA |
| Sumitomo Riko Co Ltd |
| Goodyear Tire & Rubber Co |
| Schaeffler AG |
| Gates Corporation |
| Others |
Value Chain & Pricing Dynamics
Captive fluoropolymer compounding in Germany and Japan anchors premium hose pricing power while forcing mid-tier compounders toward commodity EPDM segments with thinner margins. This integration choice concentrates specification authority with OEM engineering centers in Wolfsburg and Nagoya, compressing pricing leverage for non-integrated suppliers competing on volume.
Pricing Analysis
Short lead-time premiums of 15-25 percent apply to aramid-reinforced serpentine belts for North American light truck programs, while spot inventory of standard EPDM coolant hoses trades at discounts in fragmented Indian aftermarket channels. Contract-based long-term offtake dominates OEM procurement, with price differentiation driven by GB standard certification tier and volume scale. Cost compression in commodity rubber segments is intensifying because fixed-price contracts expose compounders to petrochemical feedstock volatility. Fleet managers show least price sensitivity for predictive maintenance bundles, while independent repair shops in Maharashtra and Gujarat remain most sensitive to per-unit hose costs.
Supply Chain Analysis
Freight cost differentials between Yangtze River Delta fluoropolymer cleanrooms and Detroit assembly plants favor regional co-location for battery thermal contracts. Manufacturing concentrates in China, Germany, and the United States, with raw material dependencies spanning Saudi petrochemical feedstocks for EPDM resin and Japanese aramid cord for high-durability specifications. Single-source vulnerability from German Tier-2 compounder concentration creates bottleneck risk for mid-tier qualification. Distribution runs through integrated thermal module suppliers rather than standalone component channels, compressing direct aftermarket access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation phase-down creates a cost-of-compliance moat that favors fluoropolymer-capable incumbents while screening out EPDM-only compounders from premium refrigerant hose specifications.
For Market Incumbents: To counter timing belt displacement by maintenance-free chain systems from Japanese powertrain specialists, accelerate capacity addition in Yangtze River Delta fluoropolymer cleanrooms and deepen backward integration into aramid cord adhesion chemistry. Certification investment in MIIT GB standard compliance extends program launch timelines but secures platform lock-in with BYD and NIO. For New Entrants and Emerging Players: EPA Corporate Average Fuel Economy standards in the United States open a window for lightweight tensioner specialists to penetrate Ford and GM passenger vehicle programs. Target fragmented Indian aftermarket channels through digital procurement platforms serving Maharashtra service networks. Pursue private-label partnerships with commercial fleet managers seeking predictive replacement telemetry. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified rubber compounders seeking fluoropolymer capability. Long-term viability hinges on dual-platform tooling positions spanning legacy EPDM volume and emerging EV thermal specifications. Watch for inflection in Chinese NEV platform procurement intensity as the signal for valuation step-ups in cleanroom-equipped processors.| Strategic Initiative | Industry Significance |
|---|---|
| Fluoropolymer Cleanroom Capacity Expansion | Yangtze River Delta installations anchor battery cooling contracts with BYD and NIO. |
| Aramid Cord Backward Integration | In-house adhesion chemistry production reduces dependency on Japanese and Italian technical workforces. |
| GB Standard Certification Investment | MIIT compliance extends validation cycles but secures type approval for Chinese OEM programs. |
| Digital Aftermarket Platform Launch | Direct-to-workshop procurement bypasses fragmented Indian jobber networks. |
| Predictive Maintenance Software Partnership | Fleet telemetry integration creates recurring revenue streams from North American commercial vehicle segments. |
Study Parameters
Multi-period observation of vehicle production databases, IHS Markit registration data, and fluoropolymer capacity buildouts anchored the trend analysis, supplemented by interviews with Tier 1 supplier procurement leads, OEM platform engineers, aftermarket distributors, and dealership operations heads. Secondary validation drew from SEC 10-K filings, customs and trade data, and ACC industry reports. Bottom-up segment sizing and top-down macroeconomic cross-checks triangulated volume and value estimates.
Input-output matrices modeled demand across propulsion architecture, content per vehicle, OEM tier, and regional production cluster dimensions over the projection horizon. CAGRs derived from regression analysis of historical fitment rates against regulatory compliance timelines, with battery thermal content per vehicle and aramid-reinforced belt penetration serving as primary forecast drivers.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery thermal management would alter the outlook for multi-layer hose specifications. Forecasts reflect assumptions about NEV platform proliferation rates and refrigerant chemistry transitions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Oil Filter Market
Automotive Parts
Automotive Parts Die Casting Market
Automotive Parts
India Automotive Parts Magnesium Die Casting Market
Automotive Parts
South Korea Automotive Parts Zinc Die Casting Market
Automotive Parts
Fuel Injection Cleaning Machine Market
Automotive Parts
Iran Automotive Engine Oils Market
Automotive Parts
Cheetah Friction Reduction Technologies Market
Automotive Parts
Bulgaria Automotive Lubricants Market
Automotive Parts
South America Gear Market
Automotive Parts
France Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Valve Stem Seal Market
Automotive Parts
Mechanical Performance Tuning Components Market
Automotive Parts
Norway Automotive Engine Oils Market
Automotive Parts
Automotive Common Rail System Market
Automotive Parts
Automotive Air Conditioning Electric Scroll Compressors Market
Automotive Parts
Argentina Passenger Vehicles Lubricants Market