
 Automotive Cylinder Head Gasket Market | 2026-2036
Automotive Cylinder Head Gasket Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Cylinder Head Gasket Market Analytics
Euro 7 emission standards and EPA Tier 4 regulations are shifting demand toward higher-precision sealing systems that withstand elevated combustion pressures and tighter tolerances. Dana Incorporated leverages its vertically integrated materials science portfolio to sustain competitive positioning in multi-layer steel production. MAHLE GmbH anchors its presence through R&D intensity in thermal management interfaces. ElringKlinger AG specializes in polymer-composite formulations that differentiate its aftermarket and OEM channels.
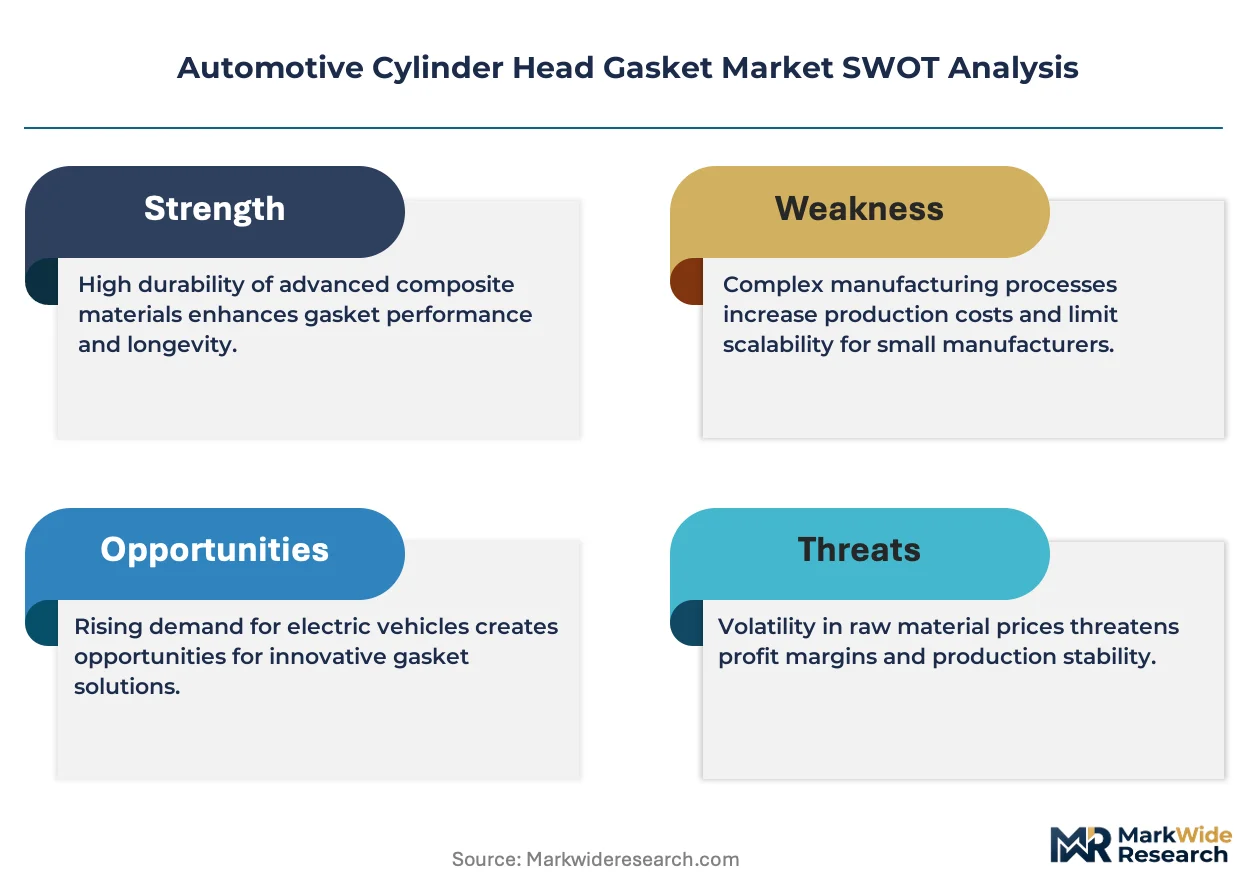
An automotive cylinder head gasket is a critical engine sealing component, typically fabricated from multi-layer steel, composite fiber, or graphite-reinforced materials, engineered to maintain compression seal integrity between the engine block and cylinder head while managing thermal expansion differentials and coolant-oil separation. Multi-layer steel gaskets dominate OEM installations due to superior creep resistance and cylinder pressure tolerance, while composite and graphite variants occupy significant aftermarket share where cost sensitivity and retrofit compatibility shape procurement. Electric vehicle powertrains present emerging demand divergence as thermal management systems require adapted sealing architectures distinct from traditional combustion geometries.
Federal-Mogul and Victor Reinz navigate compliance frameworks spanning EPA emission mandates, ECE R100 standards for hybrid systems, and ISO 9001 quality certifications that govern supplier qualification across automotive value chains. NHTSA safety protocols and REACH material restrictions further constrain formulation choices and cross-border component eligibility. Stakeholders must monitor regulatory convergence between emission and material standards to anticipate product obsolescence risks and qualification timeline compression.
Market Dynamics
Compression ratio escalation under EPA Tier 4 and Euro 7 emission mandates is forcing gasket architectures toward multi-layer steel dominance as thermal-mechanical loading intensifies beyond composite material limits.
Growth Catalysts
- EPA Tier 4 emission mandates:Heavy-duty diesel fleets in the United States face combustion pressure thresholds that only multi-layer steel gaskets reliably seal, accelerating OEM specification upgrades.
- Commercial vehicle fleet durability requirements:Long-haul operators in Germany and Japan now specify 1.5 million kilometer service intervals, eliminating graphite-composite alternatives from procurement shortlists.
- Thermal management interface R&D:Advanced polymer-composite formulations for hybrid powertrains are opening adjacent sealing applications as combustion-electric thermal cycling demands new material science.
Market Restraints
- Specialized alloy input volatility:Cold-rolled steel and nickel-alloy prices fluctuate with energy-intensive European smelter output, compressing margin stability for precision stamping operations.
- Precision manufacturing concentration:High-volume multi-layer steel production clusters in Stuttgart, Nagoya, and Detroit create geographic supply vulnerability and logistics cost inflation for distant OEM assembly plants.
- Electric powertrain substitution:Battery-electric vehicle platforms eliminate cylinder head sealing entirely, threatening long-term demand foundations in passenger car segments.
Strategic Opportunities
- India commercial vehicle aftermarket:Bharat Stage VI enforcement is retrofitting older truck fleets with upgraded sealing systems, creating demand for compatible composite and graphite-reinforced gasket architectures.
- Hybrid thermal management convergence:Combined combustion-electric powertrains require adapted gasket geometries for auxiliary coolant circuits, enabling product line extensions beyond traditional cylinder head applications.
- REACH material compliance services:European aftermarket distributors now value technical documentation support as a bundled service, opening channel partnership models for certified suppliers.
Industry Challenges
- Multi-layer steel welding precision:Laser micro-welding of 0.2mm alloy layers demands specialized technician training that outpaces vocational education pipeline capacity in manufacturing regions.
- OEM qualification timeline compression:Euro 7 pre-certification testing cycles now overlap with production ramp schedules, forcing parallel validation workflows that strain engineering bandwidth.
- Legacy tooling amortization:Composite gasket production equipment cannot be economically converted to steel stamping, stranding capital investments as product mix shifts accelerate.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Cylinder Head Gasket Market |
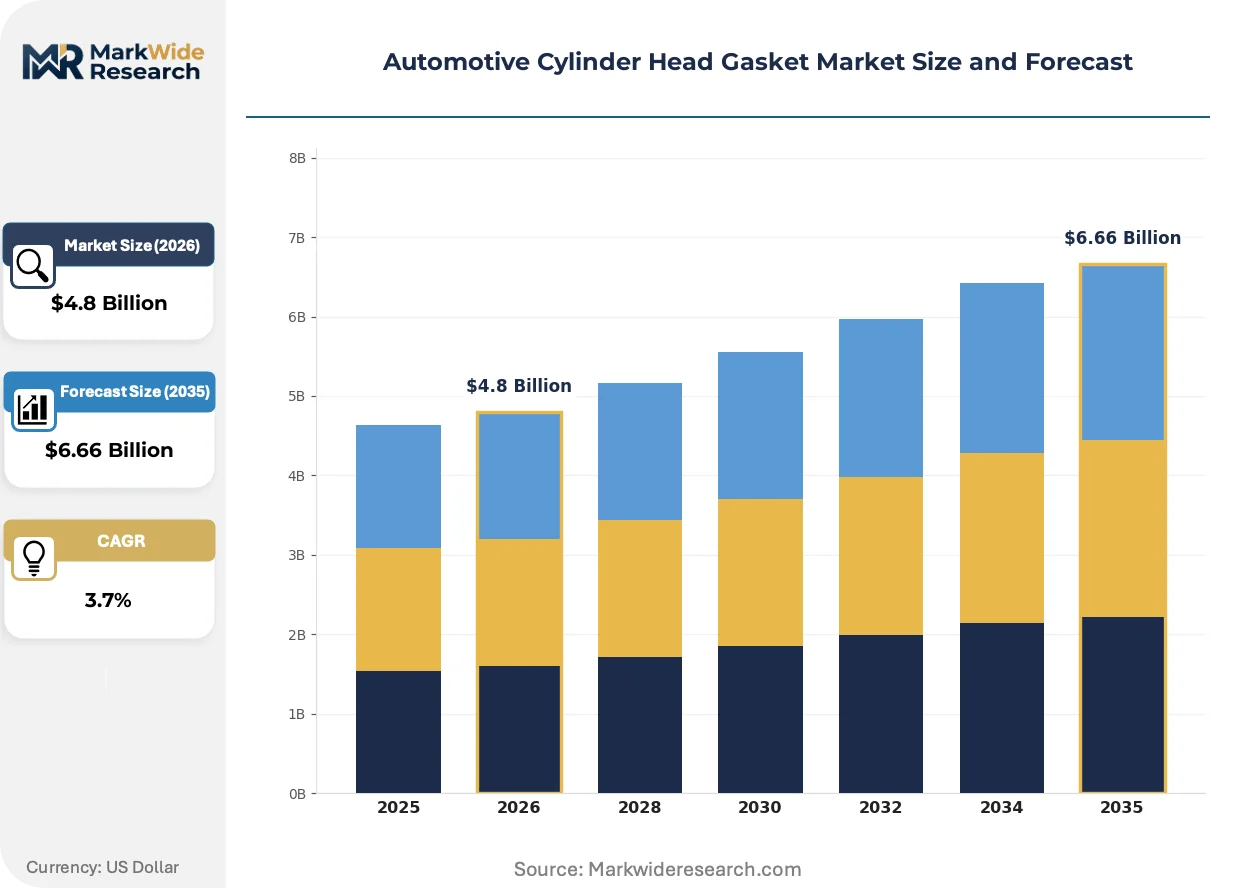
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Multi-Layer Steel, Composite, Rubber, Graphite Engine Type: Petrol, Diesel, Hybrid, Electric Installation Type: OEM, Aftermarket, Custom, Rebuilt Material: Metallic, Polymer, Fiber, Others |
| Companies Covered | ElringKlinger AG, Dana Incorporated, Tenneco Inc., MAHLE GmbH, NOK Corporation, Nippon Gasket Co., Ltd., Federal-Mogul, Victor Reinz, Fel-Pro, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Cylinder Head Gasket Market Evolving Landscape
Material science convergence with additive manufacturing is redefining prototyping velocity and small-batch customization economics across sealing component development cycles.
Multi-layer steel gasket architectures with integrated stopper layers and full-surface elastomer coatings are decentralizing the historical trade-off between cylinder pressure tolerance and micro-sealing conformity. Commercial vehicle engine manufacturers in Germany and Japan are specifying these configurations for next-generation high-pressure common-rail diesel platforms. The technology is decentralizing procurement authority from central engineering teams to regional fleet specification committees as durability data accumulates.
REACH substance restrictions and EPA material disclosure requirements are eliminating certain solvent-based coating chemistries from qualified supplier lists. Formulation substitution timelines now dictate product development roadmaps more than performance optimization targets. European aftermarket channels are responding fastest, with distributors consolidating supplier bases to simplify compliance documentation.
Direct OEM-to-fleet procurement relationships are compressing traditional aftermarket channel margins as telematics-enabled condition monitoring extends predictive maintenance intervals. Fleet operators in the United States now negotiate gasket replacement as bundled powertrain service contracts rather than discrete parts purchases. This behavioral shift is most pronounced in long-haul trucking verticals where total cost of ownership contracting dominates vendor selection criteria.
Automotive Cylinder Head Gasket Market Segmentation
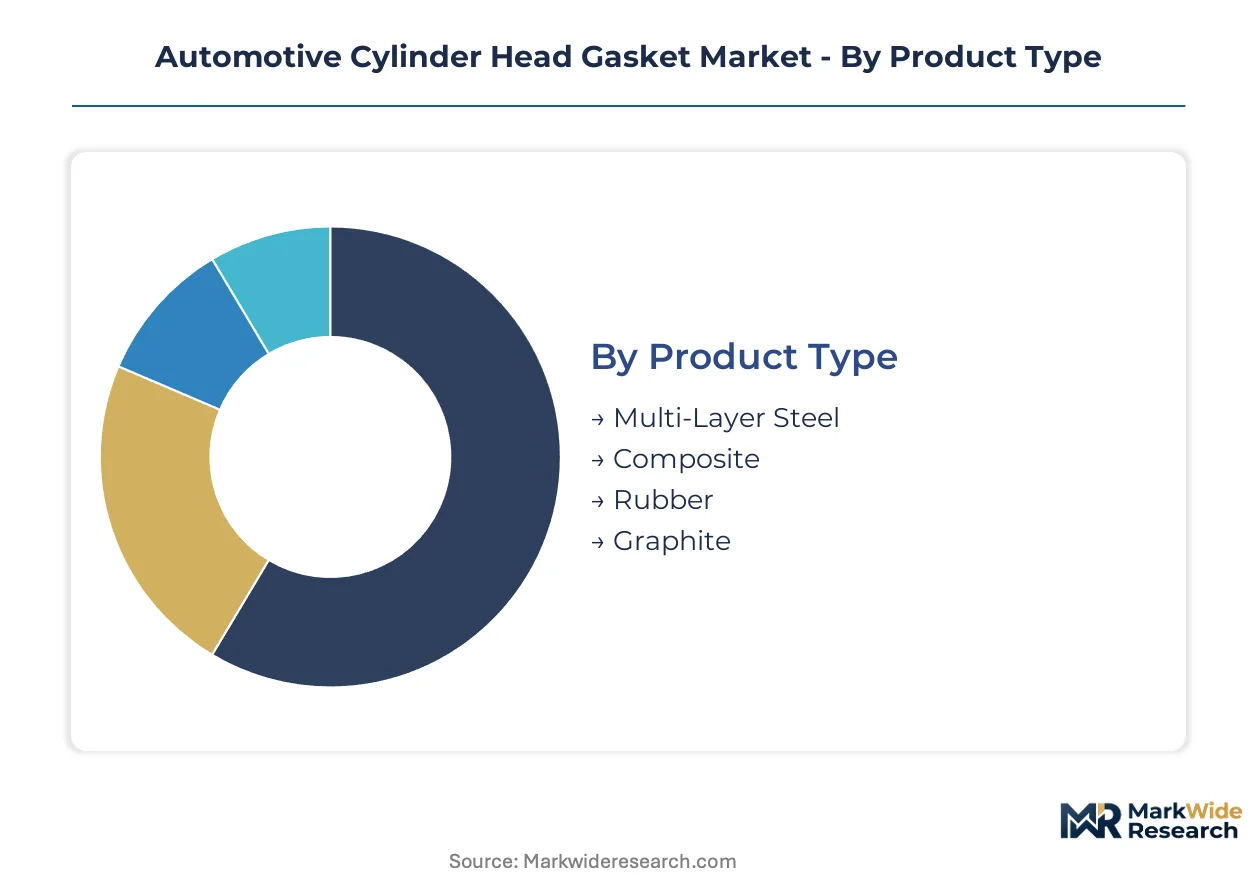
Material specifications and installation contexts fragment demand across distinct performance tiers. Each segmentation axis reveals divergent procurement patterns between combustion-engine durability requirements and emerging thermal management architectures.
Product Type:
Integration depth varies sharply—multi-layer steel ships as standalone precision components while composite variants often embed within broader engine rebuild kits.
- Multi-Layer Steel:Cold-rolled steel sheets (0.2-0.3mm) laminated with elastomer coatings deliver creep resistance under 200+ bar combustion pressures. German and Japanese commercial vehicle OEMs specify these exclusively for Euro 7 and EPA Tier 4 platforms where thermal-mechanical loading exceeds composite limits.
- Composite:Fiber-reinforced polymer matrices with graphite fillers balance cost against moderate pressure tolerance. Demand concentrates in India's Bharat Stage VI retrofit market where fleet operators prioritize compatibility over extended service intervals.
- Rubber:Nitrile and fluorocarbon elastomer formulations serve auxiliary sealing in coolant and oil circuits rather than primary combustion boundaries.
- Graphite:Expanded graphite sheets with metal inserts retain aftermarket relevance for legacy engine platforms where pressure specifications predate modern emission mandates.
Volume placements concentrate in Multi-Layer Steel; the faster expansion belongs to Composite as emerging market retrofit cycles accelerate.
Engine Type:
Application context determines whether gaskets seal combustion chambers or manage thermal interfaces in electrified powertrains.
- Petrol:Spark-ignition architectures with compression ratios below 12:1 tolerate composite sealing solutions in mass-market passenger vehicles. Japanese compact car production sustains steady procurement of mid-grade polymer-composite configurations.
- Diesel:Compression-ignition platforms with 18:1+ ratios and high-pressure common-rail injection mandate multi-layer steel across all duty cycles. Long-haul operators in Germany specify 1.5 million kilometer service intervals that eliminate alternative materials from consideration.
- Hybrid:Combined thermal cycles—combustion spikes alternating with electric motor heat dissipation—require adapted gasket geometries for auxiliary coolant circuits. These applications are climbing fastest as powertrain electrification penetrates commercial fleets.
- Electric:Battery-electric platforms eliminate cylinder head sealing entirely, though thermal management systems create adjacent demand for adapted polymer sealing in coolant distribution modules.
Procurement gravity centers on Diesel for revenue density; Hybrid applications are gaining share fastest as thermal interface complexity multiplies.
Installation Type:
Customer type and volume scale separate captive OEM supply from fragmented aftermarket channels with diverging margin structures.
- OEM:Direct supply contracts to engine manufacturers and vehicle assemblers specify multi-layer steel with full qualification documentation. Stuttgart, Nagoya, and Detroit production clusters concentrate procurement authority among tier-1 sealing specialists.
- Aftermarket:Distributor and jobber channels serving independent repair facilities favor composite and graphite variants where price elasticity dominates specification decisions. REACH compliance documentation is becoming a valued bundled service in European channels.
- Custom:Low-volume specialty engine builders and motorsport applications demand rapid prototyping capabilities and material flexibility rather than economies of scale.
- Rebuilt:Engine remanufacturing operations balance cost containment against warranty exposure, often specifying mid-tier composite solutions with documented traceability.
Revenue concentration favors OEM; aftermarket channels are expanding most quickly in India's commercial vehicle retrofit segment.
Material:
Supply chain configuration and formulation chemistry determine qualification barriers and geographic sourcing patterns.
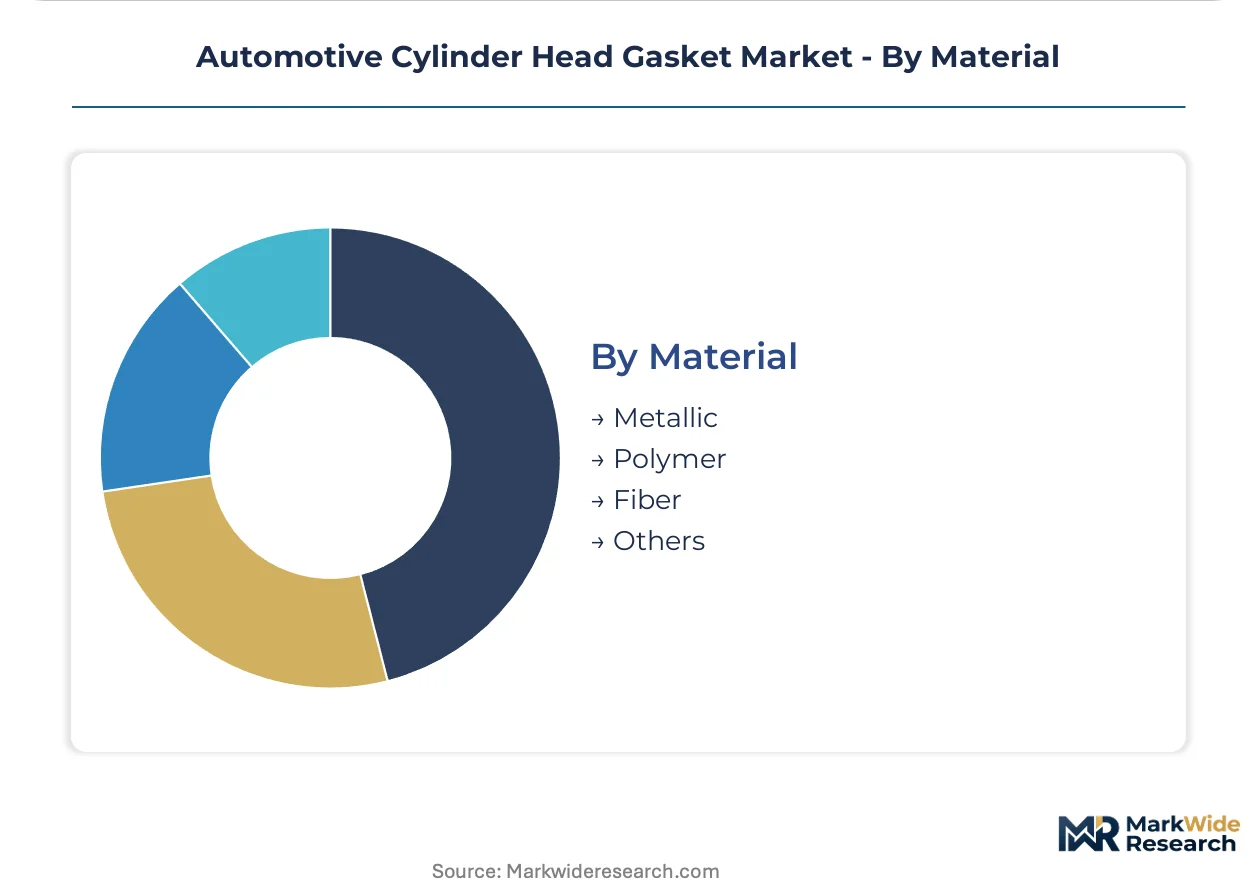
- Metallic:Cold-rolled steel, stainless alloys, and nickel-based materials dominate high-performance combustion sealing. European smelter energy costs create input price volatility that compresses margin stability for precision stamping operations.
- Polymer:Advanced elastomer and thermoplastic formulations serve hybrid thermal management interfaces where flexibility and chemical resistance outweigh pressure tolerance. These materials are climbing fastest as electrified powertrains proliferate.
- Fiber:Aramid, cellulose, and glass fiber reinforcements provide structural integrity in composite gasket architectures at moderate cost points.
- Others:Mica, ceramic, and proprietary ceramic-metal composites occupy niche high-temperature applications where standard material sets fail.
Procurement volumes concentrate in Metallic materials; Polymer formulations are expanding most quickly as thermal management applications diversify beyond traditional combustion geometries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stuttgart anchors precision manufacturing for multi-layer steel gaskets serving Euro 7 diesel platforms. Nagoya and Detroit clusters concentrate OEM procurement authority for high-pressure common-rail sealing systems. These three metropolitan manufacturing zones collectively shape global supply patterns for emission-compliant cylinder head architectures.
Germany
Commercial vehicle OEMs in Baden-Württemberg specify 1.5 million kilometer service intervals that eliminate composite alternatives from procurement lists. The KBA enforces Euro 7 pre-certification timelines that compress supplier qualification cycles. Stuttgart-based stamping operations supply multi-layer steel architectures to MAN and Daimler Truck assembly lines.
Japan
Long-haul fleet operators in the Chubu region demand durability specifications exceeding graphite-composite material limits. METI coordinates domestic supplier qualification under harmonized JIS standards for export markets. Nagoya precision metalworkers dominate laser micro-welding capacity for 0.2mm alloy layer production.
United States
Heavy-duty diesel fleets operating EPA Tier 4 platforms generate specification upgrades toward multi-layer steel exclusively. The NHTSA maintains safety protocols governing material traceability across cross-border supply chains. Detroit-area tier-1 sealing specialists anchor OEM supply contracts for domestic truck and powertrain manufacturers.
India
Bharat Stage VI retrofit cycles are upgrading older commercial vehicle fleets with compatible sealing architectures. The BIS certifies aftermarket component eligibility under phased emission compliance schedules. Maharashtra-based distributors consolidate procurement of composite and graphite-reinforced gasket variants for independent repair channels.
China
Domestic commercial vehicle production is absorbing multi-layer steel technologies for next-generation diesel platforms. MIIT coordinates GB standard alignment with Euro 7 equivalent emission thresholds. Yangtze River Delta stamping operations are expanding capacity for high-volume alloy layer lamination.
Automotive Cylinder Head Gasket Market Competitive Landscape
The competitive structure tilts toward vertically integrated materials specialists controlling precision stamping and coating operations in-house. Market concentration remains moderate, with tier-1 OEM suppliers occupying distinct positions from aftermarket-focused fabricators. Two strategic archetypes dominate: multi-layer steel specialists serving emission-compliant diesel platforms, and polymer-composite formulators targeting cost-sensitive retrofit markets. Competitive moves center on qualification timeline acceleration and geographic proximity to Stuttgart, Nagoya, and Detroit assembly clusters.
Among German-based sealing specialists, ElringKlinger AG and MAHLE GmbH occupy positions representing polymer-composite and thermal management interface expertise respectively. Dana Incorporated exemplifies the vertically integrated archetype through captive materials science capabilities. These three entities anchor distinct competitive vectors without overlapping strategic positioning in multi-layer steel, composite formulation, or integrated supply chain control.
| Leading Market Players |
|---|
| ElringKlinger AG |
| Dana Incorporated |
| Tenneco Inc. |
| MAHLE GmbH |
| NOK Corporation |
| Nippon Gasket Co., Ltd. |
| Federal-Mogul |
| Victor Reinz |
| Fel-Pro |
| Others |
Value Network & Pricing Analysis
Laser micro-welding of 0.2mm alloy layers is compressing production economics toward Stuttgart, Nagoya, and Detroit precision clusters while simultaneously amplifying pricing power for qualified suppliers serving Euro 7 and EPA Tier 4 platforms. This technology transition concentrates value capture among vertically integrated stampers with captive coating capabilities, leaving composite gasket fabricators exposed to margin erosion from stranded tooling and input cost volatility.
Pricing Analysis
Service-interval-based pricing anchors multi-layer steel procurement decisions, with German and Japanese fleet operators contracting 1.5 million kilometer durability guarantees that eliminate price-sensitive alternatives from consideration. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and thermal-mechanical load tolerance, with Euro 7-qualified architectures commanding substantial premiums over Bharat Stage VI retrofit specifications. Cost compression in composite tiers is intensifying because REACH compliance documentation is becoming a bundled service cost rather than a separable line item. Aftermarket distributors serving India's independent repair channels exhibit highest price elasticity, while OEM procurement teams in Baden-Württemberg prioritize uptime guarantees over unit cost minimization.
Supply Chain Analysis
Cold-rolled steel and nickel-alloy supply rests on European smelter output tied to energy-intensive production economics, with German, Japanese, and United States precision metalworkers dominating high-volume lamination capacity. Specialty elastomer coatings for stopper-layer integration draw from polymer formulators in the Yangtze River Delta and Chubu region, while graphite sheet supply feeds from Chinese and Indian mining operations. Single-source vulnerability concentrates in laser micro-welding equipment where Japanese and German machine tool builders control technician training pipelines. Distribution runs through tier-1 sealing specialists holding direct OEM contracts in Stuttgart, Nagoya, and Detroit, with aftermarket channels consolidating around REACH-certified distributors in European markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where backward integration into specialty alloy supply and forward integration into fleet service contracting determines margin sustainability. Players are pursuing captive control over laser micro-welding technician pipelines as the decisive upstream lever.
For Market Incumbents: Acquire precision stamping capacity in Nagoya and Stuttgart to secure proximity to MAN, Daimler Truck, and domestic Japanese OEM assembly lines. Consolidate laser micro-welding training programs through vocational partnerships that outpace competitor technician pipeline development. Battery-electric vehicle substitution threatens long-term passenger car demand foundations, necessitating defensive positioning in commercial vehicle thermal management interfaces where hybrid architectures sustain gasket relevance. For New Entrants and Emerging Players: Bharat Stage VI in India opens a window for composite gasket architectures serving retrofit cycles in Maharashtra-based independent repair channels. Target aftermarket distributors bundling REACH compliance documentation as a value-added service for European jobber networks. A white-space opportunity exists in auxiliary coolant circuit sealing for hybrid powertrains where adapted polymer geometries are climbing fastest. Go-to-market execution should anchor on technical documentation partnerships with BIS-certified distributors rather than direct OEM qualification. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to automotive tier-1 conglomerates seeking thermal management interface capabilities. Long-term viability over a five-to-ten year window hinges on positioning beyond cylinder head applications toward electrified powertrain thermal systems. Acquisition target archetypes include polymer-composite formulators with hybrid cooling circuit expertise and REACH-certified aftermarket distributors with consolidated European channel control. Watch commercial vehicle fleet telematics adoption as the inflection signal—predictive maintenance interval extension accelerates bundled service contracting and compresses discrete parts margin pools.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Alloy Supply | Captive nickel-alloy sourcing insulates margin stability from European smelter energy cost volatility. |
| Laser Micro-Welding Technician Pipeline Development | Vocational partnerships in Stuttgart and Nagoya outpace competitor qualification capacity expansion. |
| REACH Compliance Documentation Bundling | European aftermarket distributors consolidate supplier bases around certified technical support services. |
| Hybrid Thermal Management Interface Expansion | Auxiliary coolant circuit geometries open adjacent revenue streams as battery-electric platforms eliminate traditional sealing. |
| Fleet Service Contract Integration | Telematics-enabled predictive maintenance shifts procurement authority from parts distributors to powertrain service integrators. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs, combining primary interviews with OEM platform engineers, tier-1 supplier procurement leads, aftermarket distributors, and fleet maintenance directors with validation against EPA Tier 4 certification databases, KBA pre-approval registries, and BIS aftermarket eligibility lists. Bottom-up production volume estimates triangulated against top-down emission standard implementation timelines across the analysis window.
Segmentation-level modeling disaggregated material specifications, engine architectures, and installation channels throughout the forecast period, with vehicle class, propulsion type, and regional production cluster as cross-cutting dimensions. CAGRs derived from production volume trajectories under Euro 7, EPA Tier 4, and Bharat Stage VI compliance schedules, incorporating alloy input cost elasticity and qualification timeline compression as industry-specific forecast inputs.
Caveats apply where battery-electric vehicle penetration rates or hybrid thermal management design standardization could materially shift the outlook beyond combustion-engine sealing demand foundations. Forecasts reflect assumptions regarding emission mandate enforcement timing and fleet operator specification behavior. A small set of triggers—electric commercial vehicle adoption curves, REACH substance restriction expansions, and laser welding equipment import constraints—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Global Automotive Gear Shift System Market
Automotive Parts
Two Wheeler Chain Sprocket Kit Market
Automotive Parts
Nigeria Passenger Vehicles Lubricants Market
Automotive Parts
North America Passenger Vehicles Lubricants Market
Automotive Parts
Mexico Passenger Vehicles Lubricants Market
Automotive Parts
Japan Automotive Parts Zinc Die Casting Market
Automotive Parts
Full Synthetic Motor Oil Market
Automotive Parts
France Automotive Airfilters Market
Automotive Parts
RV Gear Reducer Market
Automotive Parts
Engine Fogging Oil Market
Automotive Parts
Automotive Brake Actuator Market
Automotive Parts
Europe Automotive Aftermarket Spare Parts Market
Automotive Parts
Smoke Spill Motor Market
Automotive Parts
Tappet Market
Automotive Parts
Morocco Passenger Vehicles Lubricants Market
Automotive Parts
Mexico Automotive Parts Die Casting Market