
 Europe Automotive Engine Oils Market | 2026-2036
Europe Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Automotive Engine Oils Market Foresight
Commercial fleet servicing is hardening as the dominant demand channel across Europe, displacing traditional retail-driven volume. BP plc leverages its integrated refinery network to secure feedstock advantages for high-performance synthetics. TotalEnergies anchors its position through partnerships with French and German OEM service networks. FUCHS specializes in industrial-grade formulations that meet extended drain intervals demanded by logistics operators.
Europe automotive engine oils are lubricating fluids formulated from base oils and additive packages designed to reduce friction, dissipate heat, and protect internal combustion engine components under thermal and mechanical stress. These products typically contain viscosity index improvers, detergents, dispersants, and anti-wear agents such as zinc dialkyldithiophosphate to maintain film strength across operating temperatures. Synthetic oil types command premium positioning as OEMs specify lower viscosity grades for fuel efficiency compliance. Aftermarket providers represent the fastest-growing end-user channel as independent garages expand their share of out-of-warranty vehicle maintenance across Eastern Europe.
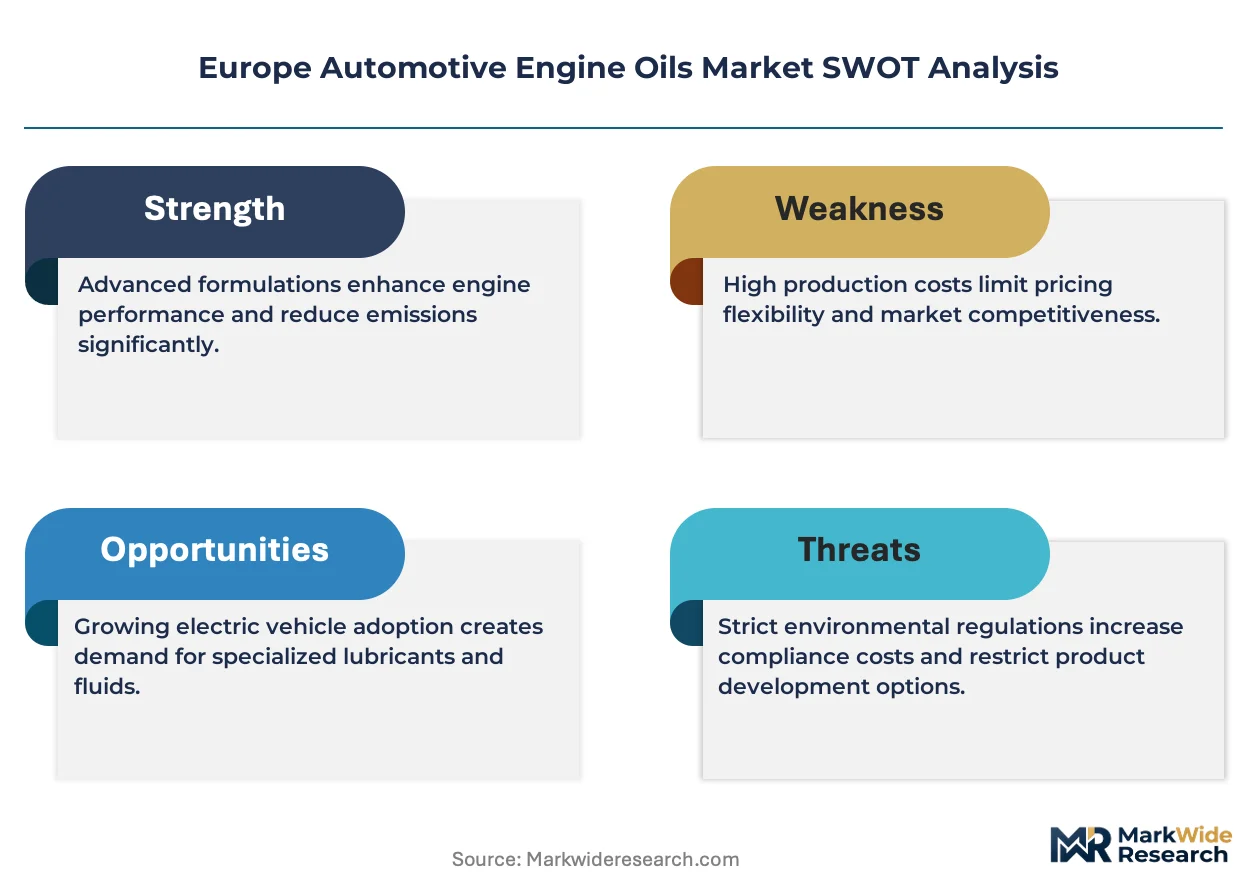
REACH and the EU Green Deal constrain additive chemistries and mandate biodegradability benchmarks for lubricant formulations. The F-Gas Regulation and ECHA substance evaluations are forcing reformulation of traditional engine oil components. EMA guidelines on oil compatibility with aftertreatment systems directly influence product development priorities. Stakeholders must monitor how Euro 7 implementation timelines reshape specification requirements for particulate filter-compatible low-SAPS formulations.
Market Dynamics
Euro 7 emission standards are compressing formulation timelines across the European lubricant supply base, forcing rapid recalibration of additive packages and base oil sourcing strategies.
Growth Catalysts
- Hybrid powertrain penetration:Germany's automotive manufacturing corridor generates concentrated demand for low-viscosity synthetics compatible with start-stop thermal cycling. OEM service networks specify these grades for warranty compliance.
- REACH biodegradability mandates:The EU Green Deal's lubricant benchmarks push reformulation toward bio-based base stocks. Suppliers investing in Group III+ and PAO capacity capture specification premiums.
- Fleet maintenance centralization:Logistics operators across France and Italy are consolidating service contracts with integrated lubricant-and-filter programs. Extended drain intervals reduce total cost of ownership calculations.
Market Restraints
- API Group III base oil concentration:Northwest European refining capacity for high-performance base stocks remains tight. Reliance on Middle Eastern and Asian imports exposes margins to freight volatility and currency fluctuation.
- ECHA substance evaluation backlog:Pending restrictions on zinc dialkyldithiophosphate and boron-containing additives create formulation uncertainty. Product development cycles extend while toxicity data packages compile.
- Electric vehicle lubricant substitution:Battery electric powertrains eliminate crankcase oil demand entirely. OEMs reducing ICE platform investments compress long-term volume visibility for passenger car motor oil suppliers.
Strategic Opportunities
- Eastern European aftermarket expansion:Poland and Romania exhibit underpenetrated independent garage networks. Out-of-warranty vehicle populations create pull for mid-tier synthetic products through distributor-led technical training programs.
- Industrial-fluid convergence:Hydraulic-transmission-engine oil compatibility requirements in agricultural and construction equipment enable cross-selling. FUCHS and comparable specialists leverage formulation overlap to displace single-purpose competitors.
- CSRD supply chain disclosure:The EU's corporate sustainability reporting directive rewards lubricant suppliers with verified carbon intensity data. Scope 3 emissions tracking becomes a procurement differentiator for fleet sustainability officers.
Industry Challenges
- Additive chemist talent scarcity:Formulation expertise in SAPS (sulfated ash, phosphorus, sulfur) optimization for aftertreatment compatibility commands premium compensation. University polymer chemistry pipelines insufficiently address lubricant-specific applications.
- Dual certification timelines:ACEA and API sequences rarely synchronize release dates. Parallel testing protocols strain R&D budgets and delay product launches for multi-regional OEM approvals.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Automotive Engine Oils Market |
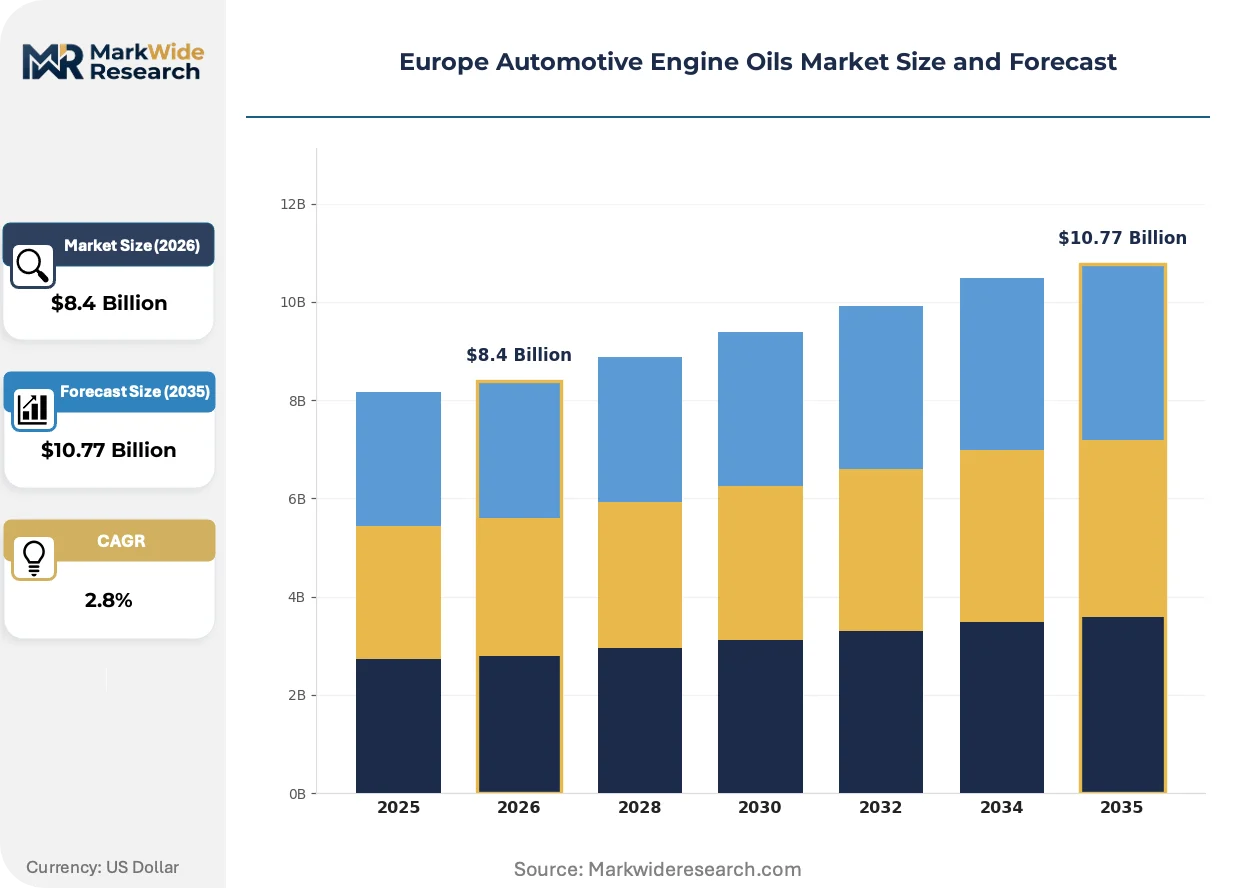
| Market Size in 2026 | $8.4 Billion |
| Market Size in 2035 | $10.77 Billion |
| CAGR (2026 – 2036) | 2.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Oil Type: Synthetic, Conventional, Semi-Synthetic, Bio-Based End User: OEMs, Aftermarket Providers, Dealerships, Fleet Operators Viscosity Grade: 0W-20, 5W-30, 10W-40, 15W-50 Packaging Type: Bulk, Bottle, Canister, Pail |
| Companies Covered | ExxonMobil Corporation, LUKOIL, BP plc, Motul, LIQUI MOLY, Royal Dutch Shell plc, FUCHS, Chevron Corporation, TotalEnergies, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Automotive Engine Oils Market Shifts & Advancements
Synthetic base oil technology is compressing the performance gap between mineral and engineered lubricants, while regulatory chemistry constraints and fleet procurement centralization reshape competitive differentiation vectors.
Polyalphaolefin (PAO) and Group III+ base stocks is overtaking traditional mineral formulations in OEM first-fill specifications. German premium vehicle manufacturers now specify 0W-20 and 0W-16 grades for CO2 fleet compliance. The shift is compressing margin structures for suppliers lacking integrated synthetic production.
REACH authorization procedures and the F-Gas Regulation are restricting traditional friction modifier chemistries. ECHA's rolling substance evaluation program targets boron, chlorine, and certain phosphorus compounds for restriction or authorization requirements. Formulators in Belgium and the Netherlands are accelerating bio-based ester development to preempt regulatory displacement.
Fleet procurement departments are consolidating lubricant purchasing through integrated maintenance contracts. Independent garages in Spain and Portugal lose share to authorized dealer networks with captive fluid programs. The channel shift concentrates volume with suppliers possessing direct OEM service partnerships and national distribution density.
Europe Automotive Engine Oils Market Segmentation
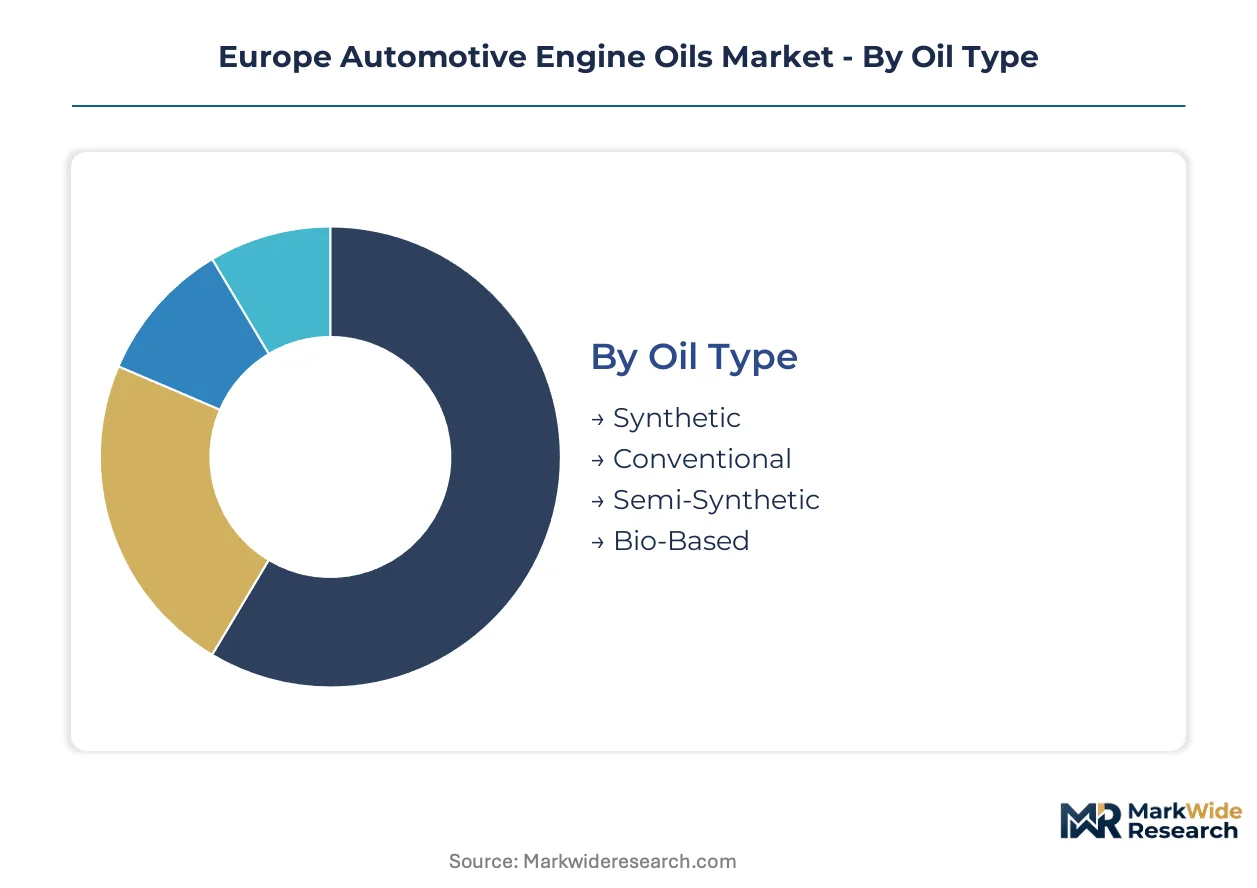
European lubricant procurement splits sharply between OEM-mandated specifications and fleet operator cost optimization. Segmentation reveals where synthetic premiums concentrate and how packaging formats adapt to centralized maintenance contracts.
Oil Type:
Customization intensity runs highest at the premium synthetic tier, where ACEA and manufacturer approvals demand formulation precision, while conventional products compete on price in price-sensitive channels.
- Synthetic:PAO and Group III+ base stocks dominate OEM first-fill specifications. German premium manufacturers specify 0W-20 and 0W-16 grades for CO2 fleet compliance, compressing margins for suppliers lacking integrated synthetic production.
- Conventional:Mineral base stocks retain volume in Eastern European aftermarket channels. Poland and Romania's independent garage networks favor these formulations for out-of-warranty vehicles where cost sensitivity outweighs performance premiums.
- Semi-Synthetic:Blended formulations bridge price-performance gaps for mid-tier service providers. These products capture fleet operators balancing drain interval extension against per-liter cost.
- Bio-Based:Ester formulations from Belgian and Dutch producers address REACH biodegradability mandates. EU Green Deal lubricant benchmarks push reformulation toward renewable base stocks with verified carbon intensity data.
Leading the category by volume: Conventional. Growing fastest: Synthetic.
End User:
Channel concentration determines margin structure, with fleet procurement centralization squeezing distributor layers while OEM partnerships lock in specification premiums.
- OEMs:First-fill specifications demand synchronized ACEA and API sequence compliance. Parallel testing protocols strain R&D budgets and delay product launches for multi-regional approvals.
- Aftermarket Providers:Independent garages across Spain and Portugal lose share to authorized dealer networks. Distributor-led technical training programs in Eastern Europe create pull for mid-tier synthetics.
- Dealerships:Captive fluid programs concentrate volume with suppliers possessing direct OEM service partnerships. Extended drain interval offerings reduce total cost of ownership for warranty-compliant maintenance.
- Fleet Operators:Logistics providers across France and Italy consolidate service contracts with integrated lubricant-and-filter programs. CSRD supply chain disclosure rewards suppliers with verified Scope 3 emissions tracking.
Dominant by revenue: Fleet Operators. Expanding most quickly: Aftermarket Providers.
Viscosity Grade:
Lower viscosity specifications track Euro 7 thermal management requirements, while legacy grades retain installed-base servicing demand.
- 0W-20:Ultra-low viscosity grades specified for hybrid powertrain start-stop thermal cycling. Germany's automotive manufacturing corridor generates concentrated demand for these formulations.
- 5W-30:Versatile grades balance cold-start protection and high-temperature film strength. Fleet operators specify these for mixed-vehicle portfolios where inventory simplification reduces logistics complexity.
- 10W-40:Higher viscosity retention for aged engines and severe operating conditions. Southern European climates sustain demand where thermal stress accelerates oil degradation.
- 15W-50:Heavy-duty specifications for commercial vehicles and performance applications. Extended drain interval compatibility supports total cost of ownership calculations in logistics procurement.
Highest volume: 5W-30. Steepest specification shift: 0W-20.
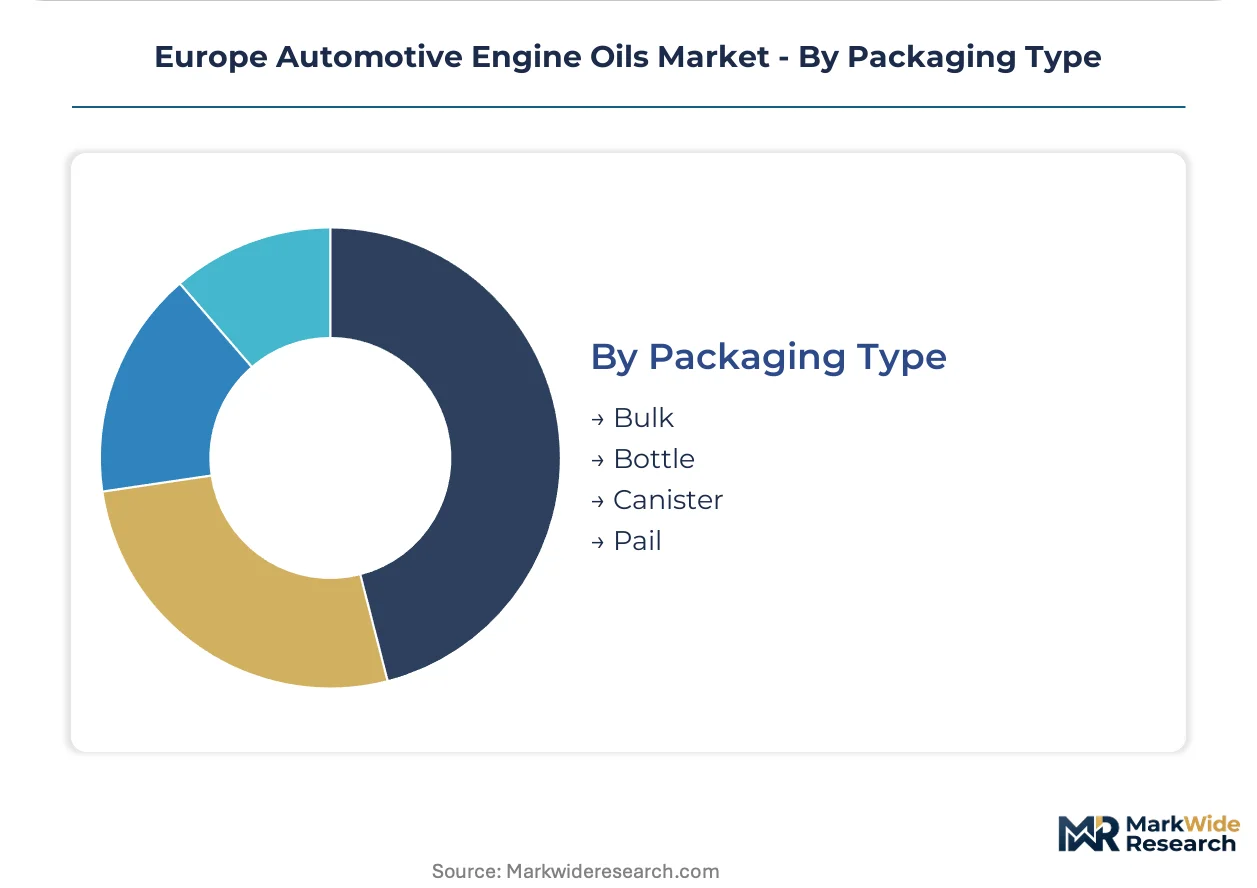
Packaging Type:
Format selection reflects supply chain density and service model centralization, with bulk systems displacing retail formats in fleet channels.
- Bulk:Tanker and tote deliveries serve centralized fleet maintenance depots. Integrated refinery networks secure feedstock advantages for high-volume synthetic supply.
- Bottle:Retail formats retain presence in DIY and small independent garage channels. Convenience positioning commands per-liter premiums against bulk alternatives.
- Canister:Mid-size containers balance portability with unit economics for regional distributors. National distribution density determines competitive positioning in this format.
- Pail:Industrial-grade packaging for agricultural and construction equipment crossover applications. Hydraulic-transmission-engine oil compatibility requirements enable cross-selling opportunities.
Largest volume: Bulk. Gaining share fastest: Pail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of high-performance base stocks concentrates in Northwest European refining corridors, while consumption patterns diverge between mature Western European fleet markets and expanding Eastern European aftermarket channels. Germany, France, and Italy absorb the majority of synthetic formulation volumes, whereas Poland and Romania drive growth in conventional and semi-synthetic segments.
Germany
Hybrid powertrain assembly lines in Stuttgart and Munich generate concentrated demand for 0W-20 and 0W-16 ultra-low viscosity grades. The KBA enforces stringent lubricant compatibility requirements with gasoline particulate filters under evolving emission frameworks. The Baden-Württemberg automotive manufacturing corridor hosts OEM first-fill specification development, compressing formulation timelines for suppliers.
France
Logistics operators in the Île-de-France region consolidate lubricant procurement through integrated maintenance contracts with extended drain intervals. ANSM oversight of chemical substance classifications influences additive package compositions for domestic formulators. The Auvergne-Rhône-Alpes industrial belt supports bio-based ester development aligned with EU Green Deal biodegradability benchmarks.
Italy
Commercial fleet servicing in Lombardy and Emilia-Romagna hardens as the dominant demand channel, displacing traditional retail-driven volume. ECHA substance evaluations on zinc dialkyldithiophosphate create formulation uncertainty for Turin-based lubricant blenders. The Po Valley logistics corridor exhibits rising adoption of centralized bulk delivery systems for heavy-duty applications.
Poland
Independent garage networks in Warsaw and Kraków remain underpenetrated, creating pull for mid-tier synthetic products through distributor-led technical training programs. REACH compliance costs filter down to aftermarket providers through reformulated product lines. The Silesian industrial region sustains mineral base stock consumption for aged vehicle populations.
Netherlands
Rotterdam's integrated refining complex secures feedstock advantages for Group III+ and PAO synthetic production serving premium OEM specifications. The F-Gas Regulation restricts traditional friction modifier chemistries, accelerating bio-based formulation development among Belgian and Dutch producers. The Randstad port cluster handles bulk import logistics for Northwest European distribution networks.
Europe Automotive Engine Oils Market Competitive Landscape
Top-tier vendors anchor integrated refinery and formulation operations, while mid-tier specialists occupy niche specification segments. The market structure exhibits moderate consolidation around petroleum majors with captive base oil supply, alongside independent lubricant compounders focused on industrial-grade applications. Three strategic archetypes dominate: integrated energy majors leveraging upstream feedstock control, specialized lubricant formulators emphasizing extended-drain technologies, and regional distributors capturing aftermarket density. Competitive dynamics center on securing OEM service network partnerships and expanding Eastern European distribution footprints.
Among integrated energy majors, ExxonMobil Corporation, BP plc, and TotalEnergies exemplify the feedstock-integrated archetype with positions spanning base oil production through finished lubricant distribution. These entities occupy positions defined by refinery network density and direct OEM contractual relationships. FUCHS represents the specialized industrial formulator archetype, with its GmbH structure indicating German corporate origins and a focus on technical-grade applications. Royal Dutch Shell plc anchors the premium synthetic segment through positions in Group III+ capacity and low-viscosity grade development. The competitive terrain rewards suppliers with verified carbon intensity data under CSRD disclosure requirements and established technical service capabilities for fleet procurement centralization.
| Leading Market Players |
|---|
| ExxonMobil Corporation |
| LUKOIL |
| BP plc |
| Motul |
| LIQUI MOLY |
| Royal Dutch Shell plc |
| FUCHS |
| Chevron Corporation |
| TotalEnergies |
| Others |
Supply & Pricing Matrix
Fleet procurement centralization across France and Italy compresses supplier margins while demanding extended payment terms, forcing lubricant blenders to recalibrate base oil sourcing toward integrated refinery partnerships that can absorb working capital pressure. This buyer-driven restructuring elevates synthetic premium tiers where ACEA certification barriers protect pricing power, while conventional segments face spot-market volatility.
Pricing Analysis
Short lead time premiums command 15-20% markups over contract-scheduled deliveries as Rotterdam's Group III+ capacity runs tight against German OEM first-fill deadlines. Pricing stratifies across ACEA C5-certified synthetics, mid-tier semi-synthetics for Eastern European fleets, and mineral-based economy grades for Poland's independent garages. Cost compression in the conventional tier is intensifying because Middle Eastern base oil imports expose margins to freight volatility and euro-dollar fluctuation. Fleet operators exhibit lowest price sensitivity where warranty compliance and CSRD carbon disclosure requirements lock in specification premiums, while Romania's aftermarket channels remain most elastic.
Supply Chain Analysis
REACH biodegradability mandates and the EU Green Deal's lubricant benchmarks are reshaping sourcing toward Belgian and Dutch bio-based ester producers with verified renewable content certificates. Geographic concentration rests on the Netherlands for Group III+ and PAO synthetic base stocks, Germany for formulation and OEM first-fill integration, and Belgium for bio-based additive development. Raw material dependencies include Group II/III base oils from Middle Eastern refiners, PAO feedstocks from ethylene crackers, and zinc dialkyldithiophosphate anti-wear packages facing ECHA restriction uncertainty. Single-source vulnerability concentrates in Northwest European high-performance base stock capacity, with limited alternative supply for 0W-16 and 0W-20 ultra-low viscosity grades. Distribution runs through Rotterdam's port cluster for bulk fleet deliveries, national distributor networks for canister and pail formats, and authorized dealer channels for captive OEM service programs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe's automotive engine oils market functions as a cost-of-compliance arena where REACH authorization timelines and Euro 7 specification requirements erect formidable barriers to entry, entrenching incumbents with established ECHA data packages and ACEA testing capabilities.
For Market Incumbents: Lock in synthetic base stock supply through backward integration into Group III+ capacity or long-term offtake agreements with Rotterdam refiners, insulating margin structures from import volatility. Secure direct OEM service network partnerships in Germany and France before fleet procurement centralization consolidates volume with top-tier suppliers, defending against petroleum majors leveraging captive refinery feedstock. For New Entrants and Emerging Players: Poland's independent garage networks represent the most penetrable white-space target, where distributor-led technical training programs can establish brand recognition before national players consolidate share. Romania's underpenetrated aftermarket channels offer secondary expansion terrain for mid-tier synthetic products priced between premium OEM specifications and mineral economy grades. A technical service-led go-to-market approach emphasizing drain interval education and CSRD compliance support differentiates against price-commoditized competitors. For Investors and Strategic Acquirers: The window for entry favors specialized formulators with established bio-based ester capabilities and verified carbon intensity data, positioning for EU Green Deal procurement preferences. Acquisition targets should demonstrate ACEA sequence synchronization capabilities and Eastern European distribution density. The signal to watch is Euro 7 implementation timeline acceleration, which would compress formulation windows and strand conventional mineral capacity investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Group III+ Base Oil Capacity | Secures feedstock supply for German OEM first-fill specifications against Rotterdam capacity constraints. |
| CSRD-Compliant Carbon Intensity Verification | Enables procurement differentiation with French and Italian fleet sustainability officers under EU disclosure mandates. |
| Eastern European Distributor Network Expansion | Captures Poland and Romania aftermarket growth through technical training programs for independent garages. |
| Bio-Based Ester Formulation Development | Preempts REACH displacement of traditional friction modifiers with Belgian and Dutch renewable base stock alternatives. |
| OEM Service Network Partnership Lock-In | Concentrates volume with authorized dealer channels as fleet procurement centralization squeezes independent distributors. |
Research Methodology
Document review covered ACEA oil sequence specifications, ECHA substance evaluation dossiers, and EU Green Deal lubricant biodegradability benchmarks, complemented by interviews with lubricant formulators, fleet procurement directors at French and Italian logistics operators, base oil traders at Rotterdam terminals, and technical service managers at German OEM networks. Secondary validation drew from customs trade data on Group II/III base oil imports, SEC filings of integrated petroleum majors, and national vehicle registration databases tracking hybrid powertrain penetration. Bottom-up volume estimates from end-user channel interviews were triangulated against top-down base oil production capacity assessments.
Cross-referencing historical ACEA specification adoption curves against panel input from OEM lubricant engineers and aftermarket distributors informed the analytical framework across the analysis window. Segmentation dimensions modeled included oil type tier, end-user channel concentration, viscosity grade specification shift, and regional production cluster alignment. CAGRs were derived from elasticity-adjusted volume projections incorporating hybrid powertrain penetration rates and fleet maintenance contract centralization trends.
Revisions become necessary when Euro 7 implementation timelines accelerate, ECHA restrictions on zinc dialkyldithiophosphate or boron-containing additives materialize ahead of baseline assumptions, or battery electric vehicle adoption compresses ICE platform investments faster than modeled. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Oil and Air Filters Market
Automotive Parts
High Speed Rolling Bearings Market
Automotive Parts
Automotive Parts Zinc Die Casting Market
Automotive Parts
Camshaft Bearings Market
Automotive Parts
Global Automotive Hydraulics System Market
Automotive Parts
Automotive Step Plate Market
Automotive Parts
Middle East Automotive Lubricants Market
Automotive Parts
Connecting Rods Market
Automotive Parts
Global Automotive Gasoline Particulate Filter (GPF) Market
Automotive Parts
Automotive Brake Friction Products Market
Automotive Parts
Two Wheeler Chain Sprocket Kit Market
Automotive Parts
United Kingdom Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Cup Holder Market
Automotive Parts
Italy Automotive Airfilters Market
Automotive Parts
Engine Oil Pan Market
Automotive Parts
Automotive Weatherstrips Market