
 Diesel Engine Market | 2026-2036
Diesel Engine Market Size, Share, and Industry Trends Forecast 2026-2036
Diesel Engine Market Intelligence
Consolidation of specialized engine block casting capacity in Germany is repositioning the supply base for high-horsepower units. Cummins leverages its extensive global service network and brand recognition to support its dominant position in commercial vehicle applications. Caterpillar specializes in ruggedized engines for heavy-duty off-highway equipment used in mining and construction sectors. Wärtsilä differentiates with its large-bore, medium-speed engines designed specifically for the marine propulsion and stationary power generation markets.
A diesel engine is a type of internal combustion engine that ignites fuel by injecting it into a combustion chamber filled with air compressed to a high temperature. Its operation relies on the principle of compression ignition, achieving high thermal efficiency, often exceeding 40% in modern designs. Four-stroke engines represent the largest segment by volume, while common rail fuel injection systems gain share due to superior fuel atomization and emissions control. The commercial vehicles application remains a mature, high-volume segment, with power generation offering higher margins.
Engine manufacturers must navigate a complex web of emissions standards, including the US Environmental Protection Agency's Tier 4 Final and Europe's Stage V regulations for off-road machinery. In parallel, China's GB standards for non-road mobile machinery impose increasingly strict limits on nitrogen oxides and particulate matter, impacting design choices. The central strategic decision for engine producers involves balancing investment in next-generation diesel efficiency against the parallel development of alternative powertrain technologies like battery-electric and hydrogen.
Market Dynamics
The central structural force is the dual investment pressure on manufacturers. They must simultaneously fund next-generation diesel platforms to meet stringent emissions standards while also allocating significant capital to the parallel development of zero-emission alternative powertrains like battery-electric and hydrogen.
Growth Catalysts
- Common Rail Injection:This system’s adoption enhances fuel atomization, helping manufacturers meet emissions rules like Europe's Stage V while improving fuel economy.
- Indian Infrastructure Projects:Government-backed construction and power generation initiatives drive consistent demand for high-torque diesel units in heavy equipment.
- Agricultural Machinery Reliability:The need for high torque and uptime in tractors and combines sustains a core demand base, especially for large-scale farming operations.
Market Restraints
- Battery-Electric Substitution:Advances in battery technology create a potent substitution threat, especially for commercial vehicles in urban delivery and logistics applications.
- Urban Access Restrictions:A growing number of cities are implementing low-emission zones that restrict diesel vehicles, directly curtailing sales for specific segments.
- Aftertreatment System Costs:Mandated components like Diesel Particulate Filters (DPFs) and Selective Catalytic Reduction (SCR) systems add significant expense to engine manufacturing.
Strategic Opportunities
- Hydrogen Internal Combustion Engines:Adapting diesel platforms to burn hydrogen leverages existing manufacturing assets to meet zero-carbon goals, offering a transitional pathway.
- Data Center Backup Power:The expansion of hyperscale data centers drives demand for large diesel generators, valued for reliability and rapid start-up capability.
- African Off-Grid Markets:Inconsistent grid infrastructure in parts of Africa sustains a market for diesel generators in prime power industrial and commercial applications.
Industry Challenges
- Skilled Technician Scarcity:The growing complexity of modern diesel engines, integrating advanced electronics and aftertreatment systems, leads to a shortage of qualified maintenance and repair technicians.
- Dual-Track R&D Investment:Manufacturers face the capital-intensive challenge of funding both next-generation diesel platforms and parallel development of alternative powertrains like battery-electric and hydrogen.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Diesel Engine Market |
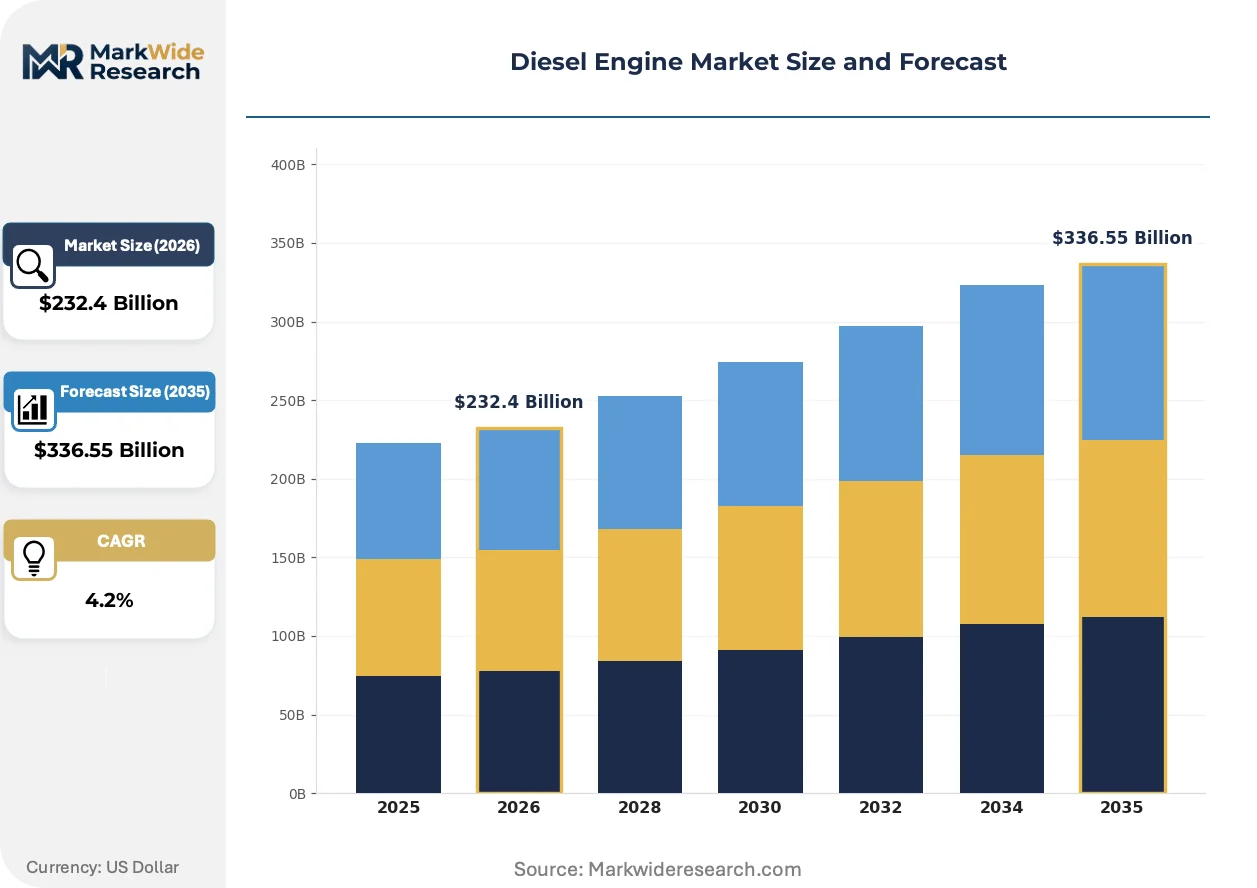
| Market Size in 2026 | $232.4 Billion |
| Market Size in 2035 | $336.55 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Two-Stroke, Four-Stroke, Common Rail, Direct Injection, Turbocharged, Naturally Aspirated Application: Construction Equipment, Agricultural Machinery, Marine Vessels, Power Generation, Commercial Vehicles, Locomotives Fuel System: Mechanical Fuel Injection, Electronic Fuel Injection, Unit Injector System, Common Rail Fuel Injection, Distributor Pump System End User: Mining Contractors, Farm Operators, Fishing Fleets, Energy Providers, Transportation Fleets, Rail Operators |
| Companies Covered | Continental AG, Deere & Company, Cummins, Wärtsilä, Volvo Penta, Caterpillar, Mitsubishi Heavy Industries, MAN Energy Solutions, Robert Bosch GmbH, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Diesel Engine Market Strategic Shifts & Innovations
A fundamental shift towards intelligent engine management and powertrain hybridization is defining the next generation of diesel technology. This evolution is driven by the twin goals of maximizing thermal efficiency and achieving near-zero emissions to extend diesel's viability.
Advanced thermal management systems actively control engine and aftertreatment temperatures using technologies like variable coolant pumps and exhaust gas heat recovery. Heavy-duty truck and off-highway equipment manufacturers are rapidly adopting these systems to optimize performance across varied operating cycles. This intelligent control of heat is absorbing inefficiencies previously lost to the environment, directly improving fuel economy and reducing the energy required for aftertreatment system regeneration.
China's GB standards for non-road mobile machinery impose progressively stricter limits on nitrogen oxides and particulate matter. These regulations compel engine manufacturers to integrate more sophisticated aftertreatment systems, such as Diesel Oxidation Catalysts and Selective Catalytic Reduction, for equipment sold into the Chinese market. The off-highway equipment segment, particularly construction and mining machinery, is most affected, requiring significant design and engineering recalibration to ensure compliance.
Fleet operators are shifting from transactional engine purchases to demanding total cost of ownership models that include predictive maintenance and uptime guarantees. This disrupts the traditional model of selling hardware and spare parts, favoring manufacturers who can provide integrated telematics and analytics-driven service packages. The trend is most visible in the long-haul trucking and large-scale mining sectors, where equipment uptime is directly linked to operational revenue.
Diesel Engine Market Segmentation
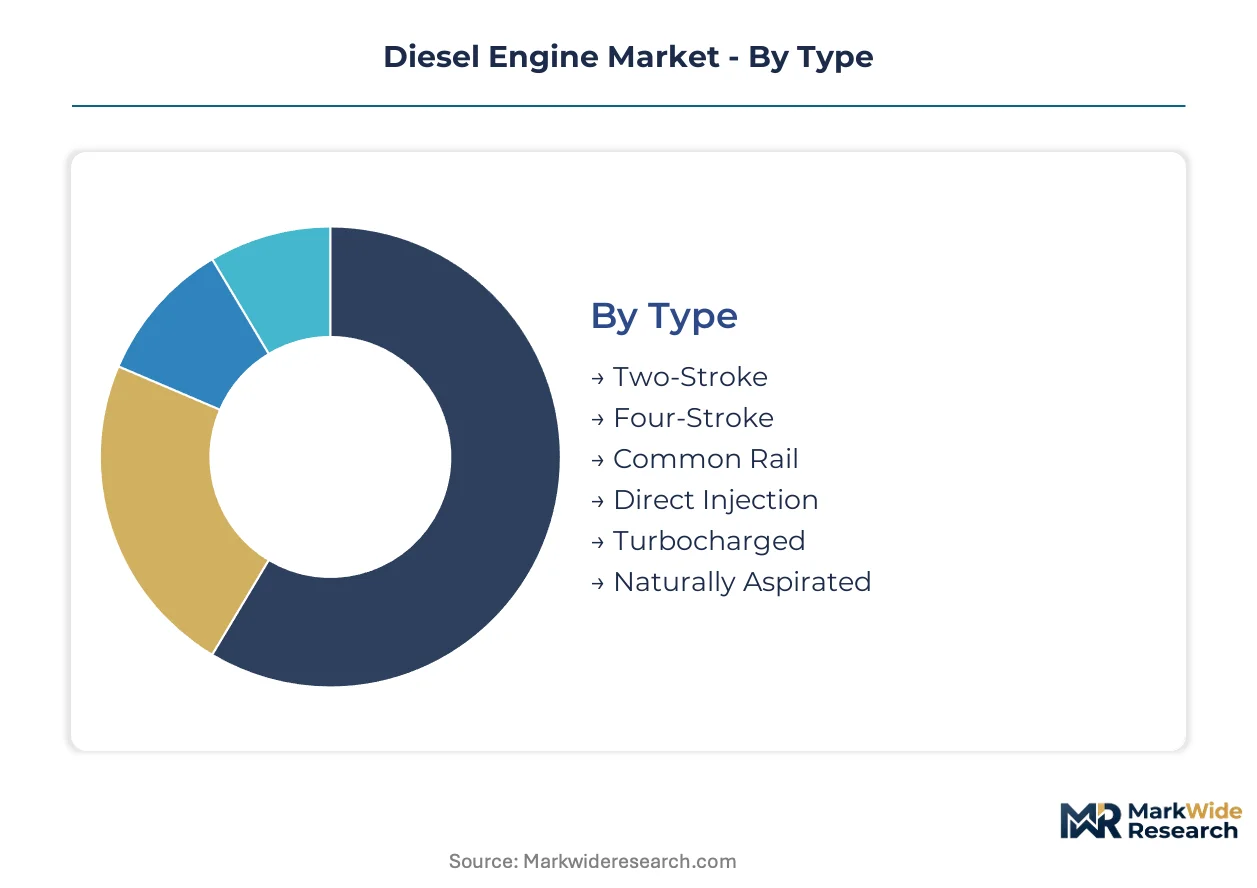
Understanding the Diesel Engine Market requires granular analysis across its diverse segments. This segmentation outlines the distinct engine types, their varied applications, the fuel delivery mechanisms employed, and the ultimate end-users driving demand. Each category reveals specific technological preferences and operational requirements.
Type:
Engine buyers in this category differentiate based on fundamental operational design and efficiency characteristics.
- Four-Stroke:This engine type represents the largest segment by volume, completing a power cycle with four piston strokes. Its widespread adoption in commercial vehicles and industrial machinery drives consistent demand across India and China.
- Common Rail:This advanced fuel injection system utilizes a high-pressure fuel rail to supply precise fuel amounts to each cylinder, enhancing atomization and emissions control. Its integration helps manufacturers meet stringent regulations like Europe's Stage V, particularly in off-highway equipment.
- Two-Stroke:These engines complete a power cycle in two piston strokes, offering high power-to-weight ratios often favored in specific marine and small-engine applications.
- Direct Injection:Fuel is directly injected into the combustion chamber, a common method for achieving higher thermal efficiency in many diesel engine designs.
- Turbocharged:An exhaust gas-driven turbine compresses intake air, increasing engine power output and efficiency, especially in heavy-duty applications.
- Naturally Aspirated:These engines draw air into the cylinders without forced induction, offering simpler designs and lower manufacturing costs for less demanding applications.
Four-Stroke leads volumes today; Common Rail is gaining share fastest.
Application:
Demand patterns in this segment reflect the specific operational environments and power needs of various industries.
- Commercial Vehicles:This segment includes trucks, buses, and vans, representing a mature, high-volume market for diesel engines globally. Stringent emissions standards in Germany and the US continually push for cleaner diesel technologies.
- Power Generation:This application involves stationary and portable generators, offering higher margins due to the need for reliability and rapid start-up capabilities. Hyperscale data centers in the US and Europe increasingly rely on these units for backup power.
- Construction Equipment:Diesel engines power excavators, loaders, and cranes, with robust demand in India driven by large-scale infrastructure projects.
- Agricultural Machinery:Tractors and combines require high torque and uptime, sustaining a core demand base in large-scale farming operations across Brazil and the US.
- Marine Vessels:Large-bore, medium-speed diesel engines power cargo ships, ferries, and tugboats, with a focus on fuel efficiency and durability for long voyages.
- Locomotives:Diesel engines provide propulsion for trains, valued for their high torque and reliability in heavy-haul freight and passenger rail systems.
Commercial Vehicles command the largest share; Power Generation applications exhibit the highest margin potential.
Fuel System:
Technological sophistication and emissions compliance are primary differentiators for fuel system components.
- Common Rail Fuel Injection:This system uses a high-pressure accumulator to precisely control fuel delivery, improving fuel atomization and emissions control. Its adoption is driven by strict regulations in Europe and China.
- Electronic Fuel Injection:This system uses electronic controls to manage fuel delivery, offering improved precision and efficiency over mechanical systems. Modern heavy-duty engines incorporate this technology for optimal performance.
- Mechanical Fuel Injection:This traditional system uses mechanical pumps and injectors to deliver fuel, offering robustness and simplicity for less regulated or older engine designs.
- Unit Injector System:Each cylinder has its own integrated pump and injector, providing high injection pressures and precise control, common in some heavy-duty engine designs.
- Distributor Pump System:A single pump distributes fuel to all cylinders, a more compact and cost-effective solution for smaller or older diesel engines.
Electronic Fuel Injection systems are widely adopted; Common Rail Fuel Injection systems are experiencing the steepest expansion trajectory.
End User:
The operational scale and specific equipment needs define the purchasing behavior of end-user segments.
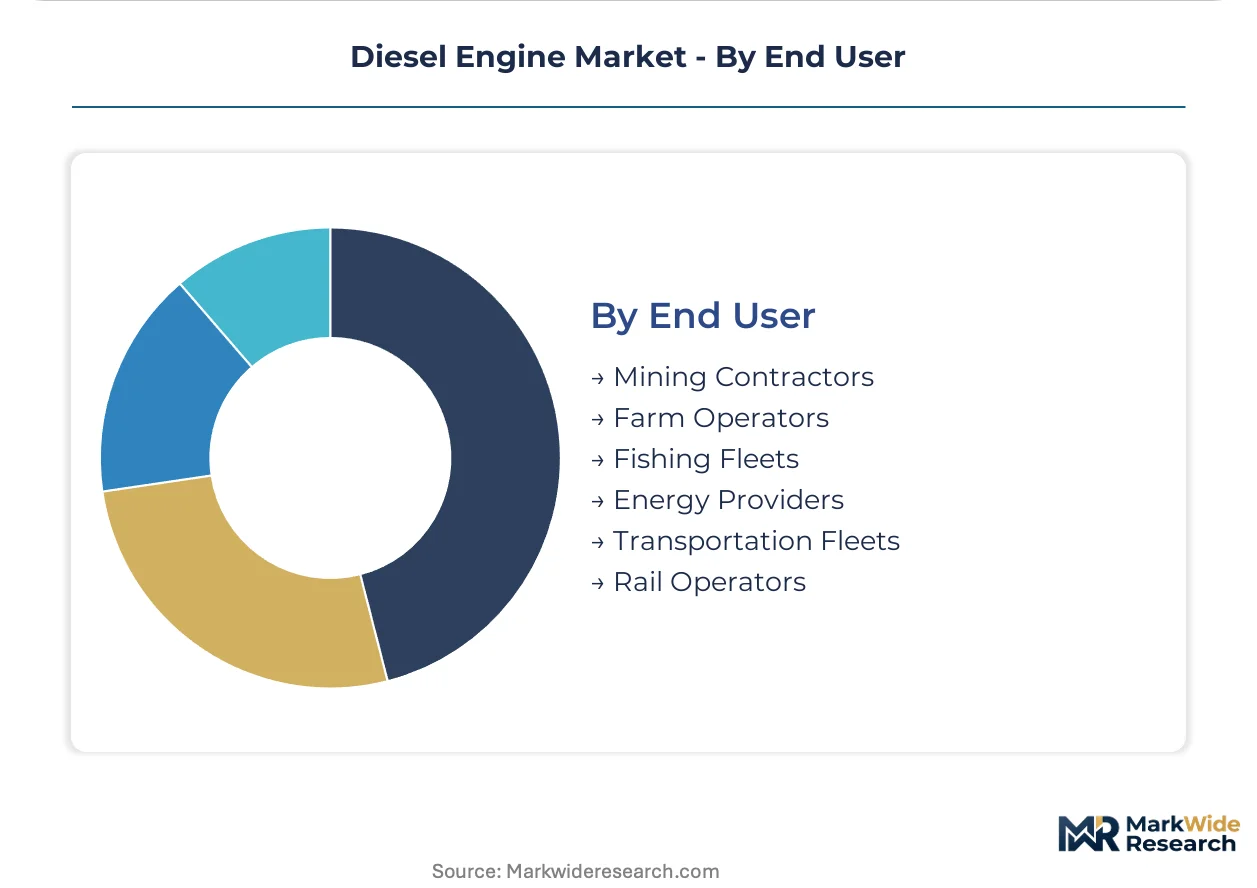
- Transportation Fleets:These operators manage commercial vehicles for logistics and passenger transport, prioritizing fuel efficiency and uptime guarantees. Long-haul trucking companies in the US demand integrated telematics for predictive maintenance.
- Energy Providers:Utilities and independent power producers use diesel generators for prime power and backup, valuing reliability and rapid deployment. Off-grid markets in parts of Africa depend on these units.
- Mining Contractors:Heavy-duty off-highway equipment for excavation and haulage requires ruggedized diesel engines capable of operating in harsh environments. Operations in Australia and Canada rely on these specialized units.
- Farm Operators:Agricultural machinery users, from small farms to large agribusinesses, require durable engines with high torque for demanding field work. Large-scale operations in Brazil and Argentina depend on powerful diesel units.
- Fishing Fleets:Marine diesel engines power fishing vessels, where reliability and fuel economy are critical for extended periods at sea. Coastal fleets globally rely on these specialized propulsion systems.
- Rail Operators:Companies managing freight and passenger rail services utilize diesel engines for locomotives, emphasizing durability and power for heavy loads and long distances.
Transportation Fleets represent the largest purchasing volume; Energy Providers are demonstrating the highest growth in demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage drives production decisions, as manufacturers balance stringent emissions standards in developed markets with less restrictive environments in other regions. This dynamic influences investment in next-generation diesel platforms, often leading to differentiated product offerings across geographies. Localized demand for specific applications also shapes regional market evolution.
India
Government-backed infrastructure and construction projects consistently drive demand for high-torque diesel units in heavy equipment. India's PLI scheme encourages domestic manufacturing, supporting local engine production. Delhi-NCR and Mumbai regions show concentrated demand for construction and power generation equipment.
Germany
Europe's Stage V regulations for off-road machinery compel significant investment in advanced emissions control technologies. Consolidation of specialized engine block casting capacity in Germany repositions the supply base for high-horsepower units. The Stuttgart region remains a hub for automotive and industrial engineering, influencing diesel engine innovation.
United States
EPA Tier 4 Final standards for off-road equipment necessitate advanced aftertreatment systems for agricultural and construction machinery. Strong demand for data center backup power generators continues across the US. The Illinois manufacturing belt supports heavy equipment production, sustaining demand for robust diesel engines.
China
China's GB standards for non-road mobile machinery impose increasingly strict limits on nitrogen oxides and particulate matter, impacting design choices. Large-scale construction and mining activities sustain demand for compliant diesel engines. The Yangtze River Delta region concentrates manufacturing capabilities for diverse industrial equipment.
Brazil
Agricultural machinery, particularly for large-scale farming operations, forms a core demand base for durable diesel engines. Brazil's PROCONVE emissions regulations influence engine design for both on-road and off-road applications. The São Paulo industrial region remains central to the country's manufacturing and heavy equipment sectors.
Diesel Engine Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue adjacent opportunities in alternative powertrains and hybrid solutions. The market structure exhibits consolidation within high-horsepower segments and fragmentation in niche applications. Strategic archetypes include diversified industrial conglomerates, specialized engine manufacturers, and component suppliers. Dominant competitive moves include strategic partnerships for technology co-development and portfolio diversification into alternative fuel systems.
Within the specialized engine manufacturing archetype, Cummins exemplifies a strong presence in commercial vehicle applications, leveraging its global service network. Caterpillar anchors the heavy-duty off-highway equipment sector, providing ruggedized engines for mining and construction. Wärtsilä differentiates with its large-bore, medium-speed engines, designed specifically for the marine propulsion and stationary power generation markets.
| Leading Market Players |
|---|
| Continental AG |
| Deere & Company |
| Cummins |
| Wärtsilä |
| Volvo Penta |
| Caterpillar |
| Mitsubishi Heavy Industries |
| MAN Energy Solutions |
| Robert Bosch GmbH |
| Others |
Cost & Logistics Intelligence
Indian infrastructure projects, for instance, drive specific demand for high-torque diesel units. This demand concentration influences component sourcing and overall engine pricing strategies.
Pricing Analysis
Direct-to-OEM discounts and specialized dealer margins characterize the dominant pricing structure. Per-unit transactional pricing prevails, especially for commercial vehicles and power generation units. Customization level for specific applications and after-sales service bundling significantly differentiate pricing. Pricing softness reflects intense competition from alternative powertrain technologies. Transportation fleets are highly price-sensitive, while data center backup power providers prioritize reliability over cost.
Supply Chain Analysis
Remanufacturing and refurbishment programs form a key part of the reverse logistics in the diesel engine market. Geographic supply concentrates in Germany, China, and the United States for specialized engine block casting and component manufacturing. High-grade steel alloys, advanced fuel injection systems, and aftertreatment catalysts are critical inputs. Regulatory restrictions on emissions standards create a structural risk for component sourcing. Direct-to-OEM sales and specialized dealer networks form the dominant downstream structure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The diesel engine market is a late-cycle quality story, as fleet operators shift from transactional engine purchases to total cost of ownership models. This demand shift prioritizes predictive maintenance and uptime guarantees.
For Market Incumbents: Deploy advanced thermal management systems to extend diesel's viability against battery-electric substitution. Invest in next-generation diesel efficiency while simultaneously funding alternative powertrain R&D. Strengthen global service networks to leverage brand recognition and combat skilled technician scarcity. This approach reinforces market leadership against emerging threats.
For New Entrants and Emerging Players: Price-point gaps exist in less regulated off-grid markets in Africa for reliable power generation units. Target the agricultural machinery segment in Brazil for durable engines with high torque. A go-to-market angle involves offering integrated telematics for analytics-driven service packages. Focus on regions with inconsistent grid infrastructure for prime power applications.
For Investors and Strategic Acquirers: Asymmetric upside sits with specialized engine manufacturers possessing strong intellectual property in hydrogen internal combustion engine adaptation. Long-term viability hinges on balancing diesel efficiency with zero-emission powertrain development. Monitor China's GB standards evolution for non-road mobile machinery as an inflection indicator for design shifts. Acquisitions should target firms with proven emissions control technologies.
| Strategic Initiative | Industry Significance |
|---|---|
| Hydrogen Engine Adaptation | Leverages existing manufacturing assets for a transitional pathway to zero-carbon goals. |
| Telematics Integration | Enhances total cost of ownership models for long-haul trucking and mining sectors. |
| Global Service Network Expansion | Supports dominant positions in commercial vehicle applications like Cummins. |
| Advanced Emissions Control R&D | Meets stringent regulations such as Europe's Stage V for off-road machinery. |
| Data Center Backup Power Focus | Capitalizes on demand for reliable, rapid-start diesel generators in the US. |
Research Approach
Multiple input streams — primary interviews, secondary publications, and proprietary databases — were reconciled to build the market view. Stakeholders included OEM procurement leads, aftertreatment system engineers, fleet managers, and regulatory affairs specialists. Secondary validation drew from government reports, industry association data, and financial disclosures, triangulating bottom-up and top-down insights.
Historical performance data was cross-referenced with expert panel input to construct the forecast framework. Segmentation dimensions modeled include engine type, application, fuel system, end-user, and regional regulatory compliance. Compound annual growth rates derived from volume and value projections across the analysis window. Key inputs included infrastructure spending projections and alternative powertrain investment levels.
Caveats apply where rapid shifts in battery technology or hydrogen infrastructure development could materially shift the outlook. Forecasts reflect assumptions regarding regulatory enforcement and economic stability. Practitioners should monitor policy changes regarding diesel vehicle restrictions for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Powertrain
South Korea Electro Hydraulic Power Steering Market
Powertrain
Yaw Damper Market
Powertrain
Advanced Gear Shifter System Market
Powertrain
Global Automotive Transmission Engineering Services Outsourcing Market
Powertrain
Transmission Mounting Brackets Market
Powertrain
Engine Actuators Market
Powertrain
Automotive Variable Discharge Oil Pump Market
Powertrain
North America Automotive Engine Oils Market
Powertrain
Car Drive System Market
Powertrain
Positive Crankcase Ventilation Valve Market
Powertrain
Global Automotive Clutch Market
Powertrain
Global Automotive Damper Pulley Market
Powertrain
CNG Powertrain Market
Powertrain
Automotive Belt Tensioner Pulley Market
Powertrain
Sway Bar Bushing Market
Powertrain
Diesel Particulate Filter (DPF) Market