
 Small Cell Backhaul Market | 2026-2036
Small Cell Backhaul Market Size, Share, and Industry Trends Forecast 2026-2036
Small Cell Backhaul Market Intelligence
The bundling of backhaul equipment with small cell hardware is recalibrating procurement decisions for network operators. Cisco Systems leverages its extensive IP networking portfolio to offer integrated transport solutions. Ericsson competes by providing end-to-end mobile network systems, including both radio access and backhaul components. Meanwhile, Nokia Corporation differentiates with a strong focus on passive optical networks and advanced microwave radio links.
Small cell backhaul refers to the high-capacity transport links connecting low-power radio access nodes, or small cells, to the core network. These links must deliver multi-gigabit-per-second throughput with sub-millisecond latency to support advanced mobile applications. Fiber optic solutions provide the highest capacity for urban connectivity, while microwave backhaul offers rapid deployment for suburban networks. The ongoing rollout of 5G NR technology is the primary factor driving investment across all backhaul types, particularly for enterprise campus use cases.
Spectrum allocation policies from regulators like the US Federal Communications Commission (FCC) directly impact the viability of wireless backhaul options. In parallel, municipal permitting rules and right-of-way regulations, influenced by frameworks like the EU's Connectivity Toolbox, govern the deployment of essential fiber optic infrastructure. Operators must continually evaluate the trade-off between the high initial capital outlay for fiber and the operational agility of millimeter wave systems.
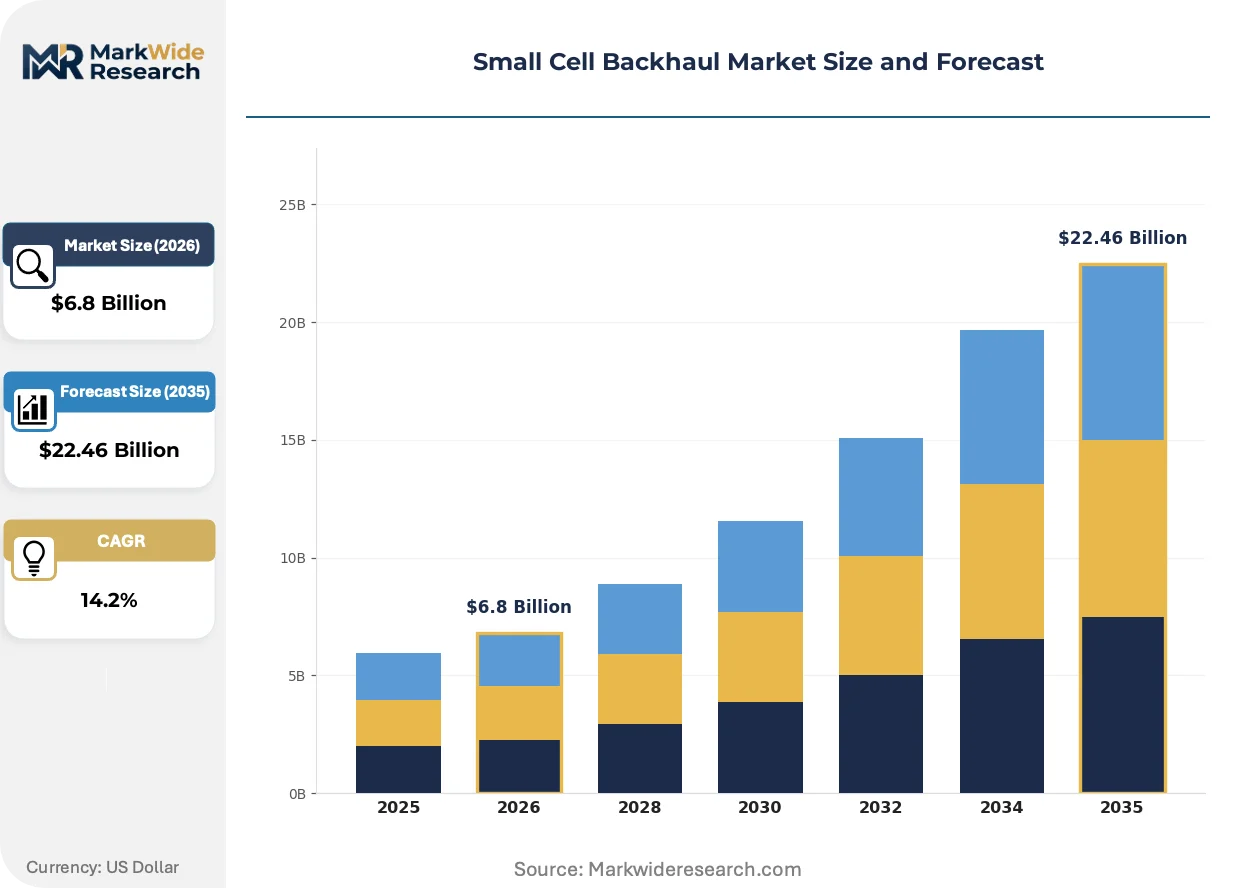
Market Dynamics
The fundamental transition from non-standalone to standalone 5G architectures is the central structural force defining the market. This shift necessitates a complete re-evaluation and build-out of backhaul infrastructure to meet stringent latency and capacity requirements previously unneeded.
Growth Catalysts
- 5G Standalone Deployments:The migration to 5G SA networks is a primary catalyst, demanding new backhaul investments to support enhanced mobile broadband (eMBB) and massive IoT applications in urban centers like Seoul and Berlin.
- Enterprise Private Networks:The expansion of private cellular networks for industrial automation and smart campus use cases creates a distinct demand channel for dedicated, high-performance on-premises backhaul solutions, separate from public carrier networks.
- Urban Network Densification:Telecom operators are aggressively deploying small cells in dense metropolitan areas to augment macro network capacity, directly fueling the need for fiber, microwave, and millimeter wave backhaul links.
Market Restraints
- Fiber Installation Costs:The high initial capital expenditure required for trenching and deploying new fiber optic cable, particularly in congested urban environments with extensive permitting hurdles, remains a significant barrier to entry.
- Spectrum Availability and Cost:Competition for suitable licensed microwave and millimeter wave spectrum, governed by auction and allocation policies from regulators like the US FCC, restricts the scalability of wireless backhaul options.
- Municipal Permitting Complexity:Navigating disparate and often lengthy municipal right-of-way permitting processes for siting small cells and laying fiber slows down network deployment timelines, a challenge the EU's Connectivity Toolbox aims to address.
Strategic Opportunities
- Neutral Host Infrastructure:The rise of neutral host providers, who build and lease backhaul infrastructure to multiple mobile operators, presents an opportunity to lower individual carrier capex and accelerate network rollouts.
- Integrated Access and Backhaul:The commercialization of 5G NR Integrated Access and Backhaul (IAB) technology allows gNodeB assets to serve both access and backhaul functions, creating an opportunity for wireless-only deployments in difficult-to-reach locations.
- Sub-6 GHz NLOS Backhaul:Developing advanced Non-Line-of-Sight (NLOS) backhaul systems using sub-6 GHz spectrum offers a path to connect small cells in locations where fiber and traditional microwave links are impractical.
Industry Challenges
- Network Synchronization:Maintaining the precise network-wide timing and phase synchronization required for advanced 5G services like TDD and Coordinated Multi-Point (CoMP) poses a significant operational challenge across multi-vendor transport networks.
- Macro Layer Integration:Ensuring seamless mobility management, load balancing, and interference coordination between the new small cell underlay and the existing macro network layer requires complex and continuous radio network optimization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Small Cell Backhaul Market |
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $22.46 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Backhaul Type: Microwave, Fiber Optic, Millimeter Wave, Copper, Satellite Technology: 4G LTE, 5G NR, Wi-Fi, Ethernet Application: Urban Connectivity, Suburban Networks, Rural Access, Enterprise Campus End User: Telecom Operators, Managed Service Providers, Network Integrators, Government Agencies |
| Companies Covered | Cisco Systems, Fujitsu Limited, Huawei Technologies, CommScope Holding Company, Ceragon Networks, Nokia Corporation, ZTE Corporation, NEC Corporation, Ericsson, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Small Cell Backhaul Market Strategic Shifts & Innovations
The convergence of transport technologies with software-defined automation is redefining how backhaul networks are designed, deployed, and managed. This evolution focuses on creating agile, programmable infrastructure capable of supporting a diverse range of 5G services and deployment scenarios.
Software-Defined Networking (SDN) for transport is a key innovation allowing for the centralized control and automation of backhaul resources. Major network operators are adopting SDN to manage complex, multi-technology networks that include fiber, microwave, and IP/MPLS elements. This technology is integrating previously siloed transport domains into a single, programmable fabric that can dynamically allocate resources and reduce operational expenditures.
Regulatory initiatives are opening new possibilities for wireless backhaul. The US Federal Communications Commission's (FCC) continued efforts to make more millimeter-wave spectrum, specifically in the E-band and V-band, available for terrestrial use directly enables multi-gigabit wireless connectivity. This policy shift most heavily impacts equipment vendors and operators planning dense deployments in cities across the United States, providing a viable alternative to fiber.
A clear shift toward disaggregated and multi-vendor network architectures is altering procurement models. Operators are moving away from single-vendor, turnkey solutions in favor of a best-of-breed approach for radio, transport, and core components, influenced by Open RAN principles. This trend is most prominent in greenfield network builds and among operators in markets like Japan and Germany looking to increase supply chain diversity.
Small Cell Backhaul Market Segmentation
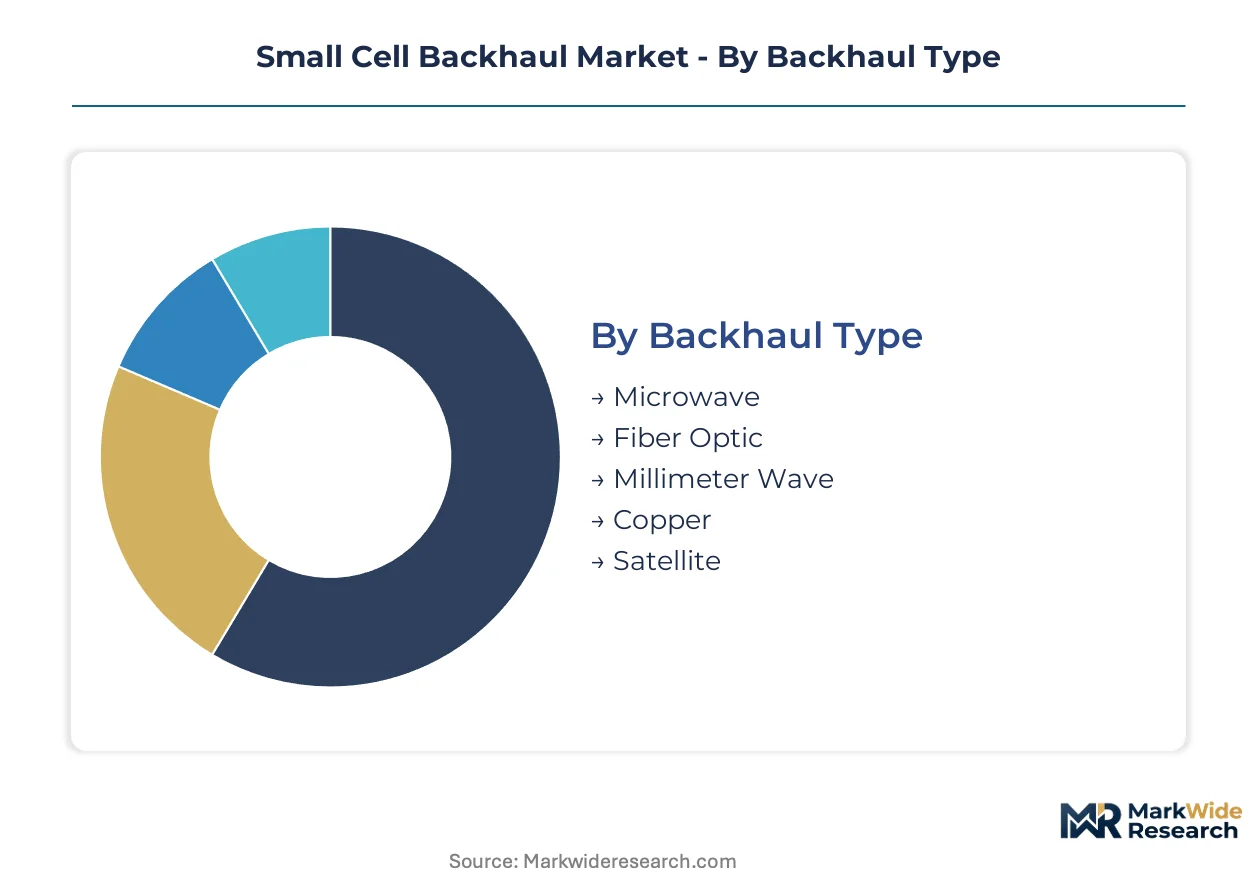
The Small Cell Backhaul Market segments reflect the diverse requirements for connecting low-power radio access nodes to core networks. Understanding these distinctions is critical for network operators to optimize infrastructure investments and for vendors to tailor their product offerings effectively. Each segment addresses specific operational challenges and deployment scenarios within the evolving 5G ecosystem.
Backhaul Type:
The ongoing upgrade cycle for network infrastructure drives differentiation across various small cell backhaul technologies. Operators are evaluating existing deployments for capacity enhancements and considering new solutions for greenfield 5G standalone networks.
- Fiber Optic:These solutions provide the highest capacity and lowest latency transport links, essential for dense urban 5G deployments and core network connectivity. Demand concentrates in metropolitan centers across the United States and Germany, driven by the need for multi-gigabit throughput.
- Millimeter Wave:Operating in spectrum bands like E-band and V-band, millimeter wave systems offer multi-gigabit wireless connectivity with rapid deployment capabilities. This technology addresses backhaul needs in urban and suburban areas where fiber installation is cost-prohibitive or time-consuming.
- Microwave:Traditional microwave links offer a balance of capacity and deployment flexibility, serving as a reliable backhaul option for suburban and rural small cell sites.
- Copper:Legacy copper-based solutions, such as DSL or DOCSIS, provide limited capacity and are primarily used for low-bandwidth small cell deployments or as temporary solutions.
- Satellite:Satellite backhaul serves remote or geographically challenging locations where terrestrial options are unavailable, providing essential connectivity for isolated small cells.
Fiber Optic sits at the top of the volume ranking, with Millimeter Wave climbing the fastest.
Technology:
Different technological standards dictate the performance and compatibility of small cell backhaul solutions, directly impacting their suitability for various mobile applications and network architectures.
- 5G NR:This technology supports the advanced capabilities of 5G, including enhanced mobile broadband, ultra-low latency, and massive machine-type communications, necessitating high-capacity and low-latency backhaul. Investment is concentrated in urban centers like Seoul, driven by enterprise private network deployments.
- 4G LTE:Backhaul for 4G LTE small cells continues to be crucial for expanding network coverage and capacity, particularly in areas transitioning to 5G. This technology remains prevalent in suburban networks, extending mobile broadband access.
- Wi-Fi:Wi-Fi-based backhaul leverages unlicensed spectrum for cost-effective connectivity, often used for indoor small cells or localized deployments with lower capacity demands.
- Ethernet:Ethernet-based backhaul provides flexible and scalable transport for small cells, integrating seamlessly into existing IP networks and supporting various radio access technologies.
5G NR technology is currently experiencing the steepest expansion trajectory, while 4G LTE maintains a substantial installed base.
Application:
The cost-effectiveness of small cell backhaul solutions varies significantly based on the specific application, influencing deployment choices and infrastructure investment strategies for network operators.
- Urban Connectivity:This application demands ultra-high capacity and extremely low-latency backhaul to support dense small cell deployments in metropolitan areas. Fiber optic solutions are paramount for urban connectivity in cities like Berlin.
- Enterprise Campus:Dedicated, high-performance backhaul solutions are required for private cellular networks within enterprise environments, supporting industrial automation and smart campus use cases. This segment is gaining momentum in manufacturing hubs.
- Suburban Networks:Backhaul for suburban small cells balances capacity requirements with deployment ease, often utilizing a mix of microwave and fiber solutions to extend coverage.
- Rural Access:Providing mobile services to underserved rural areas requires cost-optimized backhaul, frequently relying on satellite or longer-range wireless options due to infrastructure limitations.
Urban Connectivity commands the largest share of backhaul deployments, with Enterprise Campus applications expanding most quickly.
End User:
The volume of small cell backhaul deployed by different end-user types reflects their respective network scale, strategic objectives, and operational models within the telecommunications ecosystem.
- Telecom Operators:These entities are the primary consumers of small cell backhaul, deploying extensive networks to enhance mobile broadband services and support 5G rollout. Major operators in the United States drive significant infrastructure investments.
- Managed Service Providers:These providers offer end-to-end network solutions, including backhaul, to other businesses and sometimes smaller operators, focusing on operational efficiency and specialized expertise. Their demand is increasing for outsourced network management.
- Network Integrators:Integrators design and implement complex network solutions for various clients, often procuring and deploying backhaul components as part of larger projects.
- Government Agencies:Government entities deploy small cells for specific public safety networks, smart city initiatives, or critical infrastructure, requiring dedicated and secure backhaul.
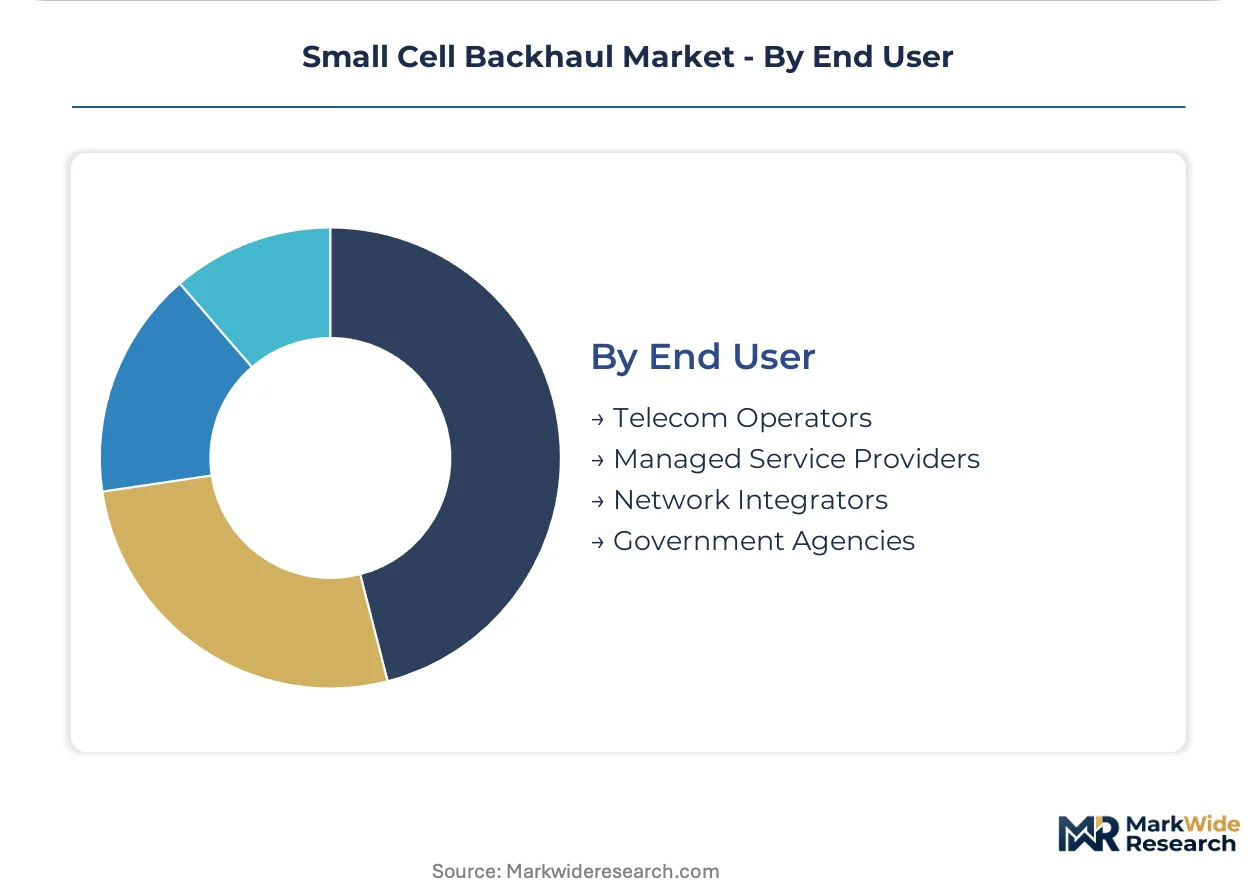
Telecom Operators represent the largest end-user segment, while Managed Service Providers are gaining share fastest through specialized offerings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The small cell backhaul market initially scaled with early mobile network deployments, evolving significantly with the advent of 4G LTE and now 5G technologies. Demand for high-capacity, low-latency transport links has driven infrastructure investments across key global markets. Regional variations in regulatory frameworks and deployment priorities shape market dynamics.
United States
The United States experiences strong demand from telecom operators deploying dense 5G networks and enterprise private networks. The US Federal Communications Commission (FCC) actively allocates millimeter-wave spectrum for terrestrial use, providing wireless backhaul alternatives. Major metropolitan areas like New York City and Los Angeles are densifying small cell networks for enhanced mobile broadband.
Germany
German telecom providers prioritize urban network densification and enterprise private networks for industrial applications. The EU's Connectivity Toolbox framework aims to streamline municipal permitting for fiber optic infrastructure. Cities such as Berlin and Munich are seeing significant investment in high-capacity backhaul for smart city initiatives.
South Korea
South Korea drives innovation in 5G NR technology deployments, particularly for enhanced mobile broadband and massive IoT. The MFDS regulations support the rapid rollout of advanced telecom infrastructure. Seoul remains a critical hub for enterprise private network deployments requiring ultra-low latency backhaul.
Japan
Japanese operators focus on expanding 5G NR services and developing smart city infrastructure. METI policies encourage digital transformation and investment in robust network backbones. Tokyo and Osaka are key areas for integrated access and backhaul (IAB) technology trials to optimize wireless deployments.
India
Indian telecom operators are expanding rural access and suburban networks to bridge digital divides. The TRAI's regulatory policies promote widespread digital connectivity and infrastructure sharing. Bangalore and Hyderabad are seeing increased demand for dedicated backhaul solutions supporting enterprise campus applications.
Small Cell Backhaul Market Key Industry Players
The competitive structure tilts toward integrated network solution providers offering comprehensive portfolios spanning radio access and transport. The market exhibits a blend of established telecom equipment vendors and specialized backhaul technology firms. Strategic archetypes include end-to-end system integrators, wireless backhaul specialists, and fiber optic infrastructure providers. Competitive moves involve extensive portfolio diversification and strategic partnerships to deliver integrated offerings.
Within the end-to-end system integrator archetype, Cisco Systems leverages its extensive IP networking portfolio to offer integrated transport solutions for diverse network environments, often serving as a foundational provider. Ericsson occupies a strong position by providing complete mobile network systems, encompassing both radio access and backhaul components, addressing operator needs for seamless deployment and operational efficiency. Nokia Corporation, a global telecommunications company, differentiates with a strong focus on passive optical networks and advanced microwave radio links, catering to specific capacity and deployment flexibility requirements for next-generation networks.
| Leading Market Players |
|---|
| Cisco Systems |
| Fujitsu Limited |
| Huawei Technologies |
| CommScope Holding Company |
| Ceragon Networks |
| Nokia Corporation |
| ZTE Corporation |
| NEC Corporation |
| Ericsson |
Cost & Logistics Intelligence
Outsourced infrastructure models anchor competitive supply positions, directly influencing long-term service contract pricing within the small cell backhaul market. This approach enables operators to manage high upfront capital expenditures.
Pricing Analysis
Contract-based long-term offtake agreements define pricing in the small cell backhaul market. Price differentiation stems from the required capacity volume and the level of managed services bundled. Pricing softness reflects intense competition among infrastructure providers aiming to secure large operator contracts. Managed Service Providers exhibit high price sensitivity, while major Telecom Operators prioritize reliability and performance for core deployments.
Supply Chain Analysis
Reverse logistics for small cell backhaul equipment focuses on component recycling and refurbishment to extend lifecycle value. Supply of critical network hardware concentrates in China, South Korea, and the United States. Key dependencies include specialized integrated circuits and high-grade fiber optic cables. Single-source vulnerability for specific millimeter wave components represents a structural risk. Distribution largely involves direct sales channels to major telecom operators, supplemented by network integrators for project-based deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The small cell backhaul market presents a margin-expansion opportunity, driven by the premium-tier shift towards high-capacity fiber and millimeter wave solutions for 5G standalone networks. Operators seek reliable, high-performance infrastructure.
For Market Incumbents: Deepen integrated transport solution portfolios to counter emerging specialized wireless backhaul providers. Consolidate market share by offering end-to-end mobile network systems, including advanced synchronization capabilities for 5G. Leverage existing channel control through comprehensive service agreements. Strategic partnerships with neutral host providers can mitigate the threat of high fiber installation costs.
For New Entrants and Emerging Players: Capture white-space demand in rural access markets using advanced sub-6 GHz NLOS backhaul systems. Focus on enterprise private networks by providing dedicated, high-performance on-premises solutions. Suburban networks represent the most penetrable application segment for cost-effective millimeter wave deployments. A go-to-market angle emphasizing rapid deployment and specialized solution integration will resonate with underserved clients.
For Investors and Strategic Acquirers: Roll-up economics work for specialized backhaul technology firms because infrastructure fragmentation creates integration opportunities. This market offers significant long-term viability, driven by the multi-year 5G standalone network build-out. Target specialized wireless backhaul providers with strong millimeter wave or sub-6 GHz NLOS intellectual property. The signal to watch for inflection points is regulatory shifts in millimeter-wave spectrum availability and municipal permitting streamlining.
| Strategic Initiative | Industry Significance |
|---|---|
| Integrated Access and Backhaul (IAB) Development | This initiative optimizes wireless deployments by enabling gNodeB assets to serve dual functions. |
| Neutral Host Infrastructure Partnerships | These partnerships lower individual operator capital expenditure and accelerate network rollouts for small cells. |
| Fiber Optic Network Expansion | Expanding fiber optic networks provides the highest capacity and lowest latency for urban 5G connectivity. |
| Advanced Microwave Radio Link R&D | Research in microwave radio links offers rapid deployment capabilities for suburban small cell backhaul needs. |
| Software-Defined Networking (SDN) Implementation | SDN provides centralized control and automation of backhaul resources across multi-technology networks. |
Research Approach
Direct dialogue with telecom operator network architects, small cell equipment manufacturers, backhaul solution providers, and regulatory body representatives forms the primary data grounding. This primary intelligence combines with secondary validation from FCC filings, EU Connectivity Toolbox documents, and telecom industry association reports. A robust bottom-up and top-down triangulation process ensures data accuracy.
A bottom-up analytical framework, validated by top-down market sizing, underpins projections across the analysis window. Segmentation dimensions modeled include backhaul type, technology, application, end user, and regional deployment density. Compound annual growth rates are derived from granular segment-level projections. Key forecast inputs include global 5G NR deployment roadmaps and evolving spectrum allocation policies.
Underlying measurement precision varies by segment; urban connectivity and telecom operators carry tighter precision than rural access. Forecasts reflect assumptions regarding technology adoption rates and regulatory stability. Practitioners should monitor unexpected economic downturns or significant shifts in spectrum policy for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Europe 5G Infrastructure Market
Telecommunications Infrastructure
Vietnam Telecom Towers Market
Telecommunications Infrastructure
Wireless Infrastructure Market
Telecommunications Infrastructure
Bangladesh Telecom Towers Market
Telecommunications Infrastructure
Morocco Telecom Tower Market
Telecommunications Infrastructure
Germany Telecom Towers Market
Telecommunications Infrastructure
China Telecom Towers Market
Telecommunications Infrastructure
Latin America Telecom Tower Market
Telecommunications Infrastructure
France Telecom Towers Market
Telecommunications Infrastructure
Global Integrated Telecom Infrastructure Market
Telecommunications Infrastructure
NLD and ILD Telecom Service Market
Telecommunications Infrastructure
Fiber to the X (FTTX) Market
Telecommunications Infrastructure
Slovenia Telecom Market
Telecommunications Infrastructure
Spain Telecom Towers Market
Telecommunications Infrastructure
United States Telecom Towers Market
Telecommunications Infrastructure
Iraq Telecom Market