
 NLD and ILD Telecom Service Market | 2026-2036
NLD and ILD Telecom Service Market Size, Share, and Industry Trends Forecast 2026-2036
NLD and ILD Telecom Service Market Foresight
The EU AI Act is decoupling compliance costs from traditional licensing frameworks for cross-border data transit operators. Deutsche Telekom AG leverages its pan-European backbone to sustain premium SLA tiers for financial services clients. NTT Communications Corporation anchors its competitiveness through deep submarine cable holdings across Asia-Pacific routes. Bharti Airtel Limited navigates price-sensitive African corridors with localized termination partnerships.
NLD and ILD telecom services encompass domestic and international long-distance transmission of voice, data, and multimedia traffic over fiber-optic, satellite, and IP-based infrastructures operating at wavelengths from 1310 nm to 1550 nm with latency budgets under 150 milliseconds for transoceanic routes. These services enable enterprises to interconnect geographically dispersed operations, cloud regions, and customer bases across sovereign boundaries. Data services dominate value capture as hyperscaler interconnection and cloud egress fees expand, while VoIP segments face margin compression from over-the-top substitution. Satellite technology is gaining structural share in remote and maritime corridors where fiber deployment remains uneconomical.
The FCC enforces submarine cable licensing and foreign ownership restrictions that shape US market entry pathways, while the EU Green Deal mandates energy-efficiency disclosures for data transmission networks affecting operator capex planning. India's TRAI regulates ILD tariffs and interconnection charges that directly influence carrier pricing flexibility. Stakeholders must monitor divergence between EU AI Act data-localization requirements and emerging national data-sovereignty statutes when routing traffic through third-country cable systems.
Market Dynamics
Hyperscaler cloud infrastructure expansion is concentrating traffic demand along specific submarine cable corridors, forcing carriers to prioritize latency-optimized routes over traditional cost-minimized paths. This demand compression is reshaping capacity planning across transoceanic and terrestrial fiber networks.
Growth Catalysts
- EU F-Gas Regulation:Mandates for low-global-warming-potential cooling systems at cable landing stations are accelerating infrastructure modernization programs across Mediterranean and North Sea facilities.
- Enterprise cloud migration:Financial services and SaaS providers are expanding consumption of international leased lines to interconnect distributed cloud regions with guaranteed latency SLAs.
- Mumbai-Chennai fiber corridor:Hyperscaler investment in dedicated express routes to Singapore and Europe is concentrating capital deployment along this specific Indian coastal axis.
Market Restraints
- Submarine cable supply concentration:Manufacturing capacity for 8,000 km+ cable systems concentrates among three specialized vessel operators, creating 18-24 month installation backlogs for new routes.
- Copper and specialized optical fiber volatility:Pricing instability for ultra-low-loss fiber cores and armoring materials compresses project margins on fixed-price construction contracts.
- Over-the-top VoIP substitution:Enterprise voice traffic migration to Microsoft Teams and Zoom Phone platforms is eroding traditional international voice settlement revenues.
Strategic Opportunities
- Remote maritime connectivity:Offshore energy platforms and shipping lanes off West Africa and Southeast Asia remain underserved by fiber, creating addressable demand for LEO satellite backhaul integration.
- EU AI Act data-localization requirements:Cross-border transit operators can develop certified compliance layers that premium-price sovereign routing guarantees for financial and healthcare data.
- Edge computing interconnection:Distributed AI inference workloads are creating demand for metro-to-metro low-latency services between secondary cities bypassing traditional hub-and-spoke architectures.
Industry Challenges
- Submarine cable repair technician scarcity:Specialized deep-water splicing and power-feed equipment expertise concentrates among retiring cohorts, constraining maintenance response times for faults below 3,000 meters.
- Legacy SDH/TDM system integration:Enterprises in regulated sectors still require circuit-switched interfaces, forcing IP-native carriers to maintain parallel operational support systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | NLD and ILD Telecom Service Market |
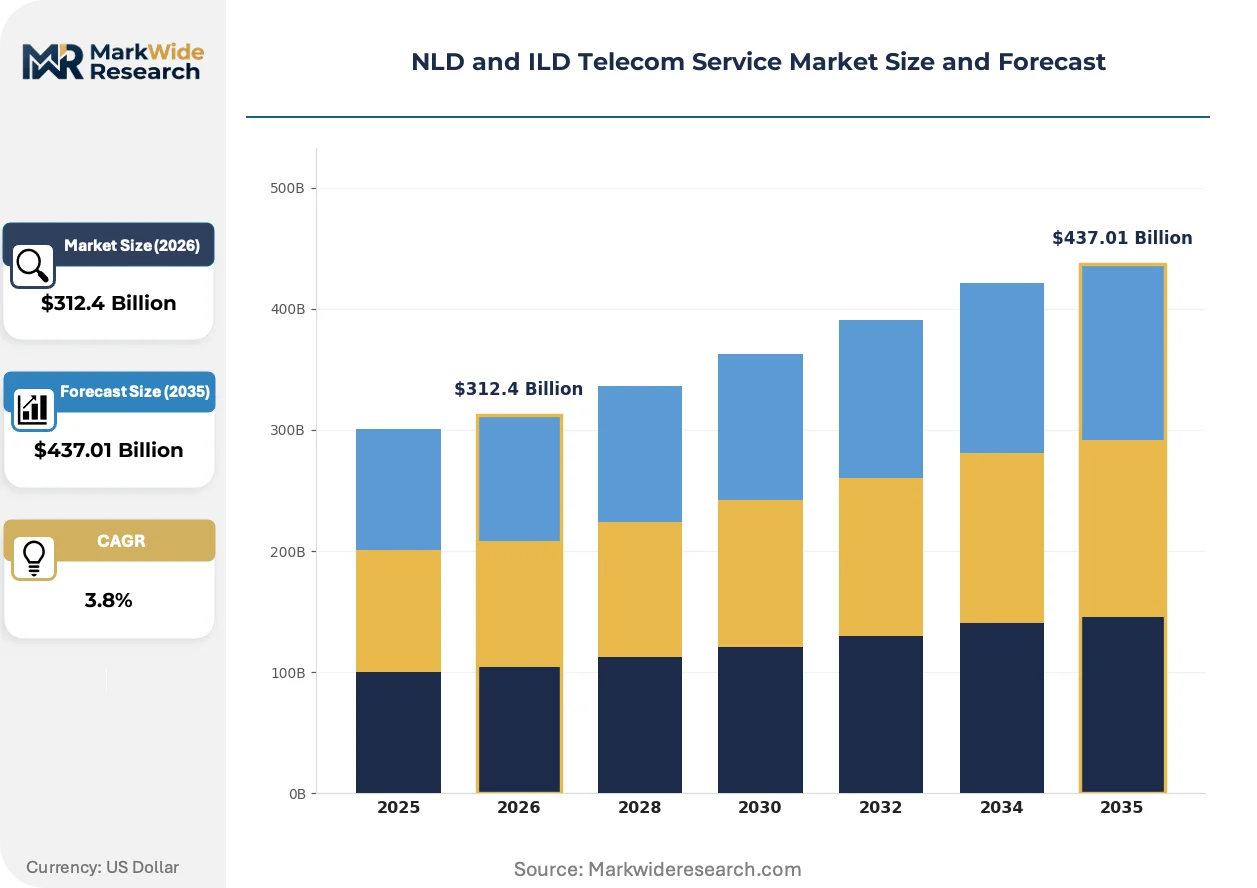
| Market Size in 2026 | $312.4 Billion |
| Market Size in 2035 | $437.01 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: VoIP, SMS, Data, Voice Technology: IP, GSM, LTE, Satellite Customer Type: Residential, SMEs, Enterprises, Government Pricing Model: Subscription, Pay-As-You-Go, Bundled Packages, Flat Rate |
| Companies Covered | Deutsche Telekom AG, NTT Communications Corporation, AT&T Inc., Orange S.A., Vodafone Group plc, Verizon Communications Inc., Bharti Airtel Limited, Tata Communications, China Mobile Communications Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
NLD and ILD Telecom Service Market Shifts & Advancements
Optical transmission technology is advancing through coherent DSP upgrades and space-division multiplexing, while regulatory frameworks increasingly embed sustainability and data sovereignty requirements into network design specifications.
Coherent optical engines operating at 800 Gbps per wavelength are converging with AI-optimized traffic engineering algorithms. Hyperscalers are deploying these systems on priority routes between Frankfurt, London, Amsterdam, and Paris metro areas. The technology is converging with real-time path computation to enable sub-50 millisecond failover guarantees that displace traditional protection switching architectures.
The EU AI Act's cross-border data transit provisions are imposing documentation burdens on cable operators routing through third-country systems. Carriers must now maintain audit trails for training data provenance that transits their fiber. Submarine cable consortia serving EU-Asia routes are restructuring ownership to ensure at least one EU-registered entity holds landing rights in member states.
Enterprise procurement of international capacity is compressing contract durations from 36-month commitments toward 12-month rolling agreements with burst provisions. This flexibility demand disrupts carrier revenue predictability and is forcing wholesale pricing toward spot-market mechanisms. The shift is most visible among hedge funds and algorithmic trading firms colocated in London and Singapore.
NLD and ILD Telecom Service Market Segmentation
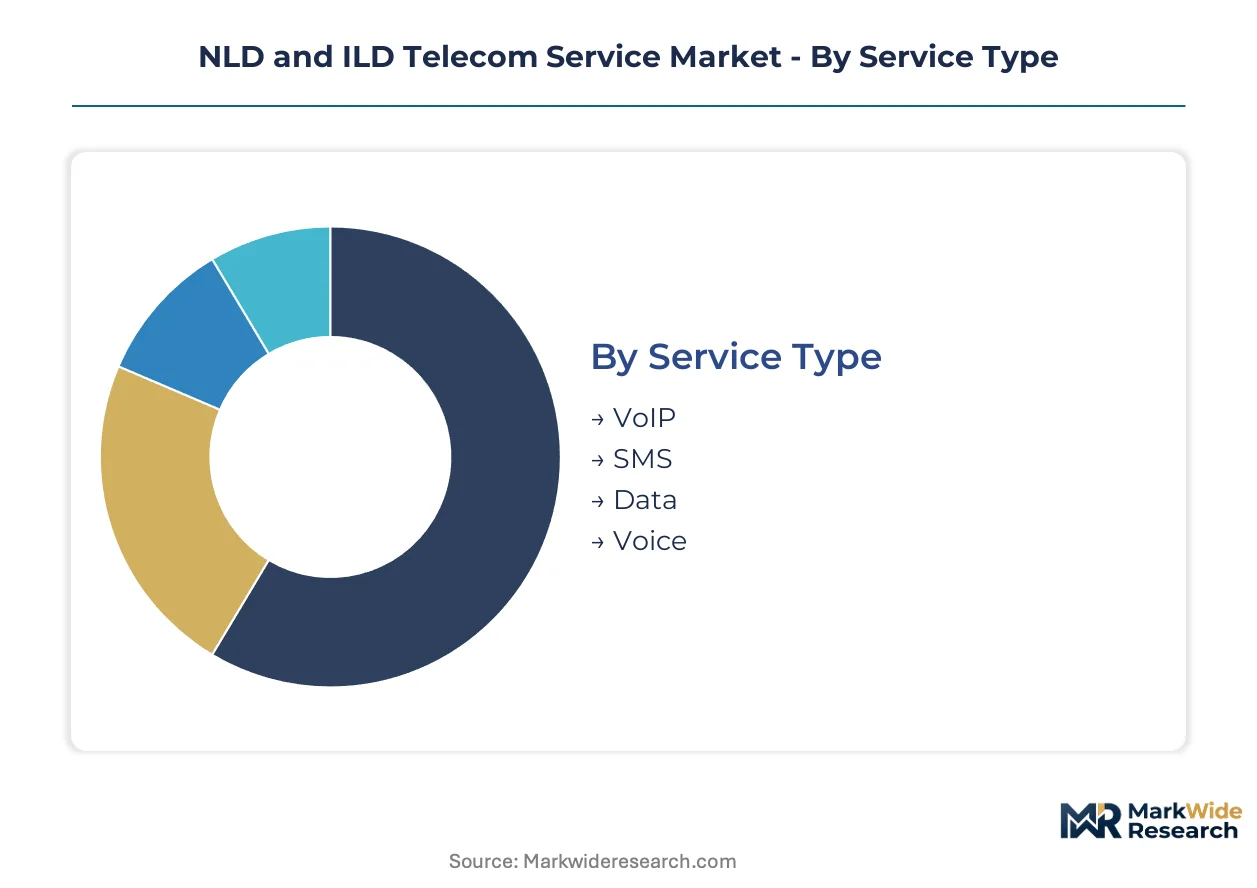
Segmentation in NLD and ILD telecom services reveals how supply-side specialization aligns with divergent latency, reliability, and regulatory requirements across customer tiers. Distinct pricing models and technology stacks create non-overlapping competitive arenas that carriers must navigate simultaneously.
Service Type:
Supply concentration in submarine cable landing rights and spectrum licenses determines which service types carriers can profitably bundle across domestic and international footprints.
- Data:International leased lines and cloud interconnects operating at 100 Gbps to 400 Gbps wavelengths carry hyperscaler traffic between Frankfurt, Mumbai, and Singapore metro areas. Financial services firms in London and New York consume premium capacity for algorithmic trading routes requiring sub-50 millisecond latency guarantees.
- VoIP:Session Initiation Protocol trunking and WebRTC-based enterprise voice platforms compete directly with Microsoft Teams and Zoom Phone for international calling minutes. Margin compression is most severe on transatlantic and Asia-Europe corridors where over-the-top substitution exceeds 60 percent of former circuit-switched volumes.
- SMS:Application-to-person messaging and two-factor authentication traffic transits SS7 and Diameter signaling networks. Demand concentrates in India's banking and government notification systems.
- Voice:Traditional time-division multiplexing circuits persist in regulated sectors requiring circuit-switched reliability for emergency services and legacy banking infrastructure.
Data absorbs the bulk of installed capacity; VoIP is expanding most quickly in emerging market corridors.
Technology:
Cost tier differentiation separates capital-intensive fiber deployments from asset-light satellite overlays serving remote geographies.
- IP:MPLS and Segment Routing over IPv6 enable traffic engineering across multi-vendor backbone infrastructures. Hyperscalers in Amsterdam and Frankfurt deploy 800 Gbps coherent optics on priority routes.
- Satellite:Low-earth-orbit constellations provide backhaul for offshore energy platforms and maritime corridors off West Africa where fiber deployment remains uneconomical. Starlink and OneWeb compete for enterprise maritime contracts.
- LTE:Mobile backhaul for international roaming traffic concentrates in border regions and airport hubs.
- GSM:Legacy 2G signaling persists for machine-to-machine applications and developing market voice services.
IP dominates capital deployment; satellite is gaining share fastest in maritime and remote energy applications.
Customer Type:
Volume concentration among hyperscalers and multinational banks creates pricing power asymmetries that reshape carrier negotiation strategies.
- Enterprises:Multinational corporations procure international private lines with committed information rates and guaranteed availability SLAs. Cloud egress fees and interconnection charges represent the fastest-growing cost category for SaaS providers.
- Government:Sovereign networks require data-localization compliance and encrypted transit through domestically controlled landing stations. EU AI Act documentation burdens fall heaviest on this segment.
- SMEs:Small and medium enterprises purchase managed SD-WAN services with simplified procurement and zero-touch provisioning.
- Residential:International calling plans and roaming packages face direct competition from over-the-top messaging applications.
Enterprises absorb the bulk of installed capacity; government is expanding most quickly due to sovereignty requirements.
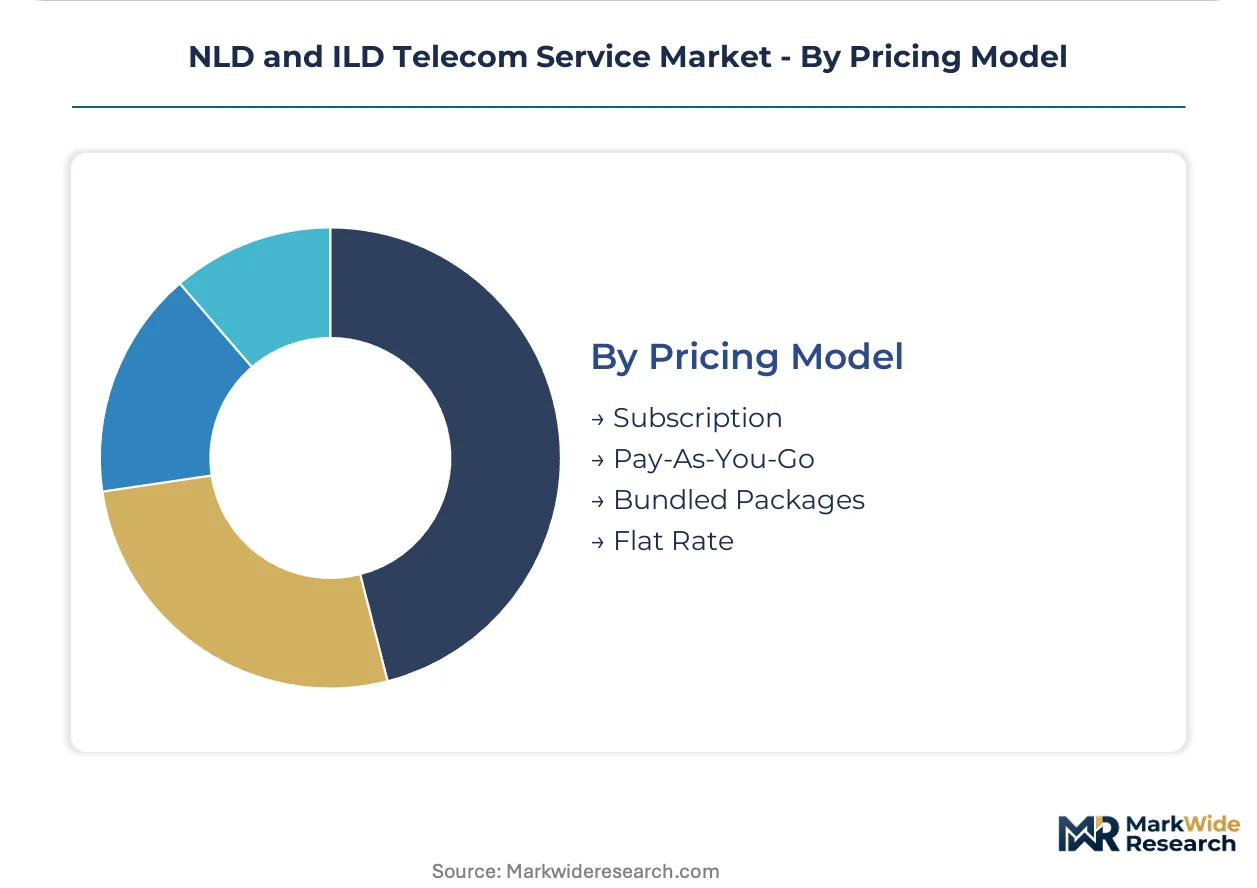
Pricing Model:
Margin structure varies dramatically between long-term committed capacity and spot-market burst pricing for algorithmic trading firms.
- Subscription:Fixed monthly fees for committed information rates provide revenue predictability for carriers serving enterprise WAN contracts.
- Pay-As-You-Go:Usage-based metering for cloud interconnect and burst capacity appeals to hedge funds and seasonal retail platforms.
- Flat Rate:Unlimited international calling plans for residential and SME segments face margin pressure from over-the-top substitution.
- Bundled Packages:Combined voice, data, and security services with unified SLAs simplify procurement for mid-market enterprises.
Subscription absorbs the bulk of installed capacity; pay-as-you-go is expanding most quickly among financial services clients.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for submarine cable landing stations in India, Singapore, and the UAE concentrate capital deployment. Tax incentives for data center co-location accelerate fiber buildouts along coastal corridors. Sovereign data localization mandates reshape traffic routing across jurisdictions.
United States
Hyperscaler cloud regions in Northern Virginia and Oregon absorb trans-Pacific and trans-Atlantic capacity. The FCC enforces foreign ownership restrictions on submarine cable landing licenses. Miami serves as the primary interconnection hub for Latin American traffic.
Germany
Frankfurt's DE-CIX anchors European IP transit with sub-10 millisecond reach to London, Amsterdam, and Paris. The EU F-Gas Regulation mandates low-global-warming-potential cooling retrofits at North Sea cable stations. Bavaria hosts redundant fiber routes serving financial services latency requirements.
India
Hyperscaler investment in the Mumbai-Chennai corridor concentrates express fiber builds to Singapore and Europe. TRAI regulates ILD tariffs and interconnection charges affecting carrier pricing flexibility. Tamil Nadu's submarine cable landing stations handle rising traffic from cloud region expansions.
Singapore
Equinix and Global Switch facilities aggregate subsea capacity from 15+ cable systems. The country's data protection framework imposes localization requirements for financial and healthcare traffic. Tuas hosts new cable landings bypassing traditional chokepoints.
United Arab Emirates
Dubai's Smart City infrastructure attracts regional cloud on-ramp investments. The telecommunications regulator mandates in-country data residency for government contracts. Fujairah serves as an alternative Red Sea cable landing point to Egyptian routes.
NLD and ILD Telecom Service Market Competitive Landscape
European and Asian carriers anchor separate competitive tiers; North American operators hold trans-Atlantic capacity advantages. Market structure consolidates around submarine cable consortium ownership and terrestrial fiber rights-of-way. Three archetypes dominate: pan-regional integrated carriers, submarine cable specialists, and cloud-interconnect pure-plays. Competitive moves center on landing station acquisitions and AI-optimized routing partnerships.
Among European integrated carriers, Deutsche Telekom AG and Orange S.A. exemplify pan-regional backbone operators with sovereign landing rights across multiple jurisdictions. NTT Communications Corporation anchors the Asia-Pacific specialist tier through deep submarine cable holdings. AT&T Inc. occupies a position bridging North American enterprise demand with international capacity aggregation. These three represent distinct geographic and capability archetypes rather than direct substitutes.
| Leading Market Players |
|---|
| Deutsche Telekom AG |
| NTT Communications Corporation |
| AT&T Inc. |
| Orange S.A. |
| Vodafone Group plc |
| Verizon Communications Inc. |
| Bharti Airtel Limited |
| Tata Communications |
| China Mobile Communications Corporation |
| Others |
Supply & Pricing Matrix
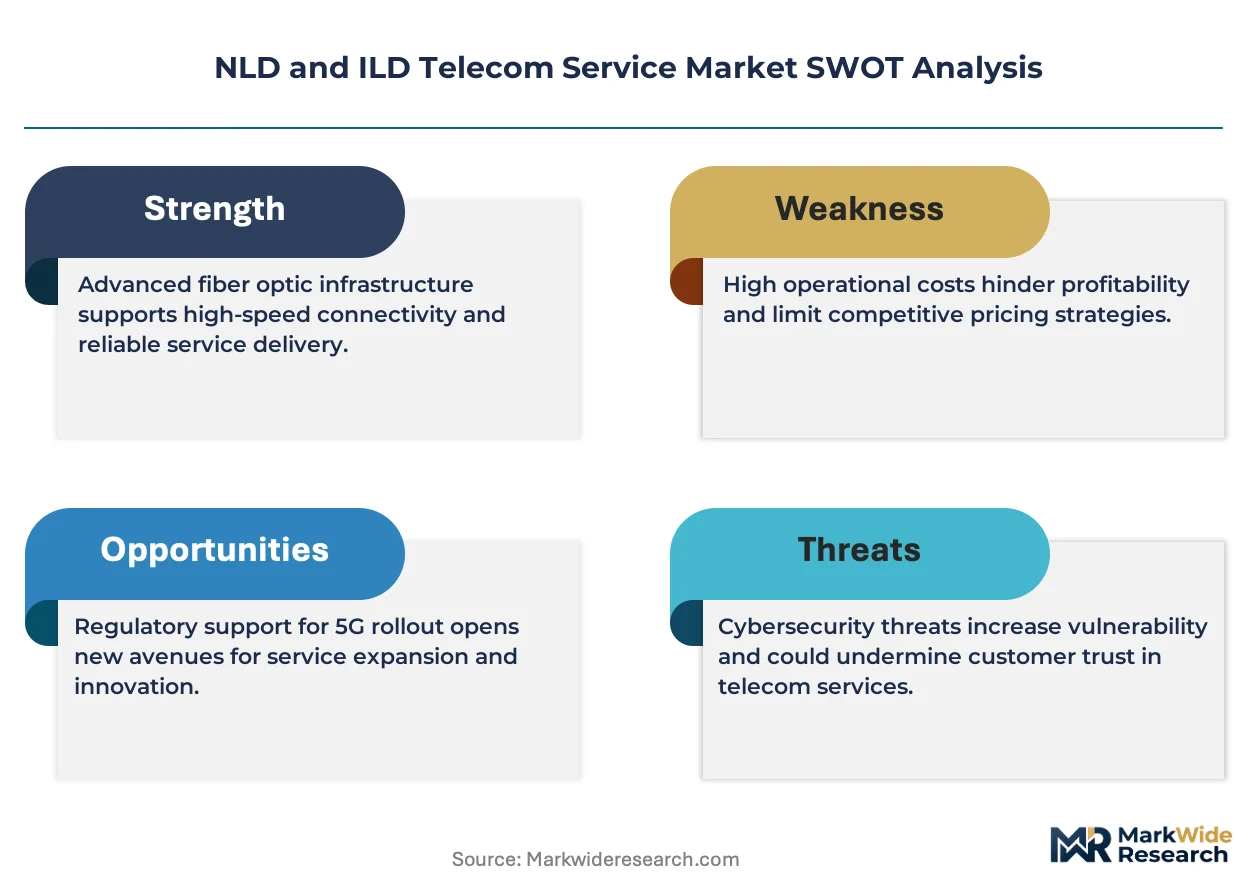
Enterprise procurement of international capacity compressing contract durations from 36-month commitments toward 12-month rolling agreements forces carriers to restructure supply commitments and accept pricing volatility on fixed-fiber contracts. This flexibility demand disrupts revenue predictability and pushes wholesale pricing toward spot-market mechanisms.
Pricing Analysis
Premium pricing for sub-50 millisecond latency guarantees on transoceanic routes commands substantial markups over standard tier services, while spot-market burst capacity for algorithmic trading firms trades at discounts to committed-rate contracts. Price differentiation rests on latency performance tiers and sovereign routing certification under EU AI Act compliance frameworks. Pricing pressure stems from over-the-top VoIP substitution eroding traditional voice settlement revenues. Hedge funds and financial services clients exhibit lowest price sensitivity; residential and SME segments face highest price sensitivity due to direct competition from free messaging applications.
Supply Chain Analysis
Direct-to-hyperscaler channels handle demand from cloud providers in Northern Virginia, Frankfurt, and Singapore metro areas, bypassing traditional wholesale aggregators. Manufacturing of ultra-low-loss fiber cores concentrates in the United States, Japan, and China, while specialized cable-laying vessel capacity clusters among operators based in France, Italy, and Japan. Raw material dependencies include high-purity silica, specialized armoring steel, and coherent optical DSP chipsets. Supply chain risk centers on single-source vulnerability for deep-water splicing equipment and power-feed gear. Distribution runs through submarine cable consortium structures and terrestrial fiber rights-of-way acquisitions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU AI Act's documentation burdens for cross-border data transit operators create substantial compliance moats that favor incumbent carriers with established audit infrastructure and EU-registered landing rights.
For Market Incumbents: Cement defensive positioning by acquiring submarine cable landing station assets in Mediterranean and North Sea facilities ahead of F-Gas Regulation retrofit deadlines, and by deepening backward integration into coherent optical engine production to reduce exposure to DSP chipset supply volatility. Threat substitution from LEO satellite constellations demands countermeasures through latency-optimized fiber route investments. For New Entrants and Emerging Players: Enter via maritime and remote energy corridors off West Africa and Southeast Asia where fiber deployment remains uneconomical and LEO satellite backhaul integration creates addressable white space. Sovereign routing compliance services for financial and healthcare data represent the most penetrable segment given EU AI Act premium-pricing opportunities. Go-to-market positioning should emphasize certified data-localization guarantees. For Investors and Strategic Acquirers: Re-rating potential sits with pan-regional integrated carriers possessing submarine cable consortium ownership and terrestrial fiber rights-of-way given hyperscaler cloud infrastructure expansion concentrating traffic demand along specific corridors. Long-term viability favors operators with diversified geographic footprints spanning EU, Asia-Pacific, and North American landing rights. Monitor hyperscaler capex disclosure patterns as the signal indicating inflection in express route deployment priorities.| Strategic Initiative | Industry Significance |
|---|---|
| Submarine Cable Landing Station Acquisition | Secures sovereign rights under EU F-Gas Regulation retrofit timelines and AI Act compliance frameworks. |
| Coherent Optical Engine Upgrade | Enables 800 Gbps wavelength deployment on priority routes between Frankfurt, London, Amsterdam, and Paris. |
| LEO Satellite Backhaul Integration | Addresses connectivity gaps for offshore energy platforms and maritime corridors off West Africa. |
| Sovereign Routing Certification Layer | Premium-prices compliance guarantees for financial and healthcare data under EU AI Act requirements. |
| Metro-to-Metro Edge Interconnection | Captures distributed AI inference workload demand bypassing traditional hub-and-spoke architectures. |
Research Methodology
Multi-period observation of hyperscaler capex allocations, submarine cable installation backlogs, and carrier pricing disclosure patterns anchored the trend analysis, supplemented by interviews with network engineering directors at pan-regional carriers, procurement leads at financial services firms, regulatory affairs specialists at submarine cable consortia, and cloud interconnection product managers at data center operators. Secondary validation drew from FCC submarine cable licensing records, EU F-Gas Regulation implementation reports, TRAI tariff orders, SEC 10-K filings by listed carriers, and hyperscaler infrastructure expansion announcements. Bottom-up capacity deployment tracking and top-down revenue aggregation were triangulated to produce segment-level estimates.
Segment-weighting approaches modeled service type, technology platform, customer tier, and pricing model dimensions across the projection horizon. CAGRs were derived from fitted growth curves calibrated to observed capacity deployment and pricing trajectories. Industry-specific forecast inputs included hyperscaler cloud region expansion timelines, submarine cable manufacturing lead times, and regulatory compliance cost burdens under EU AI Act and F-Gas Regulation frameworks.
Forecast precision tightens around the base case; tail outcomes carry wider variance under scenarios of accelerated LEO satellite substitution, copper and specialized optical fiber price spikes, or divergence between EU AI Act requirements and emerging national data-sovereignty statutes. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Germany Telecom Towers Market
Telecommunications Infrastructure
France Telecom Towers Market
Telecommunications Infrastructure
Latin America Telecom Tower Market
Telecommunications Infrastructure
Kenya Telecom Tower Market
Telecommunications Infrastructure
United States Telecom Towers Market
Telecommunications Infrastructure
Canada Telecom Towers Market
Telecommunications Infrastructure
China Telecom Towers Market
Telecommunications Infrastructure
Global Telecom Cable Market
Telecommunications Infrastructure
Broadcast Infrastructure Market
Telecommunications Infrastructure
UAE Telecom Towers Market
Telecommunications Infrastructure
Japan Telecom Towers Market
Telecommunications Infrastructure
Bangladesh Telecom Towers Market
Telecommunications Infrastructure
OTN Equipment Market
Telecommunications Infrastructure
Colombia Telecom Tower Market
Telecommunications Infrastructure
Global Mobile and Wireless Backhaul Equipment Market
Telecommunications Infrastructure
Peru Telecom Tower Market