
 Global Mobile and Wireless Backhaul Market | 2026-2036
Global Mobile and Wireless Backhaul Market Size, Share, and Industry Trends Forecast 2026-2036
Global Mobile and Wireless Backhaul Market Foresight
Enterprise connectivity buyers are collapsing the traditional hierarchy that favored mobile network operators as the dominant procurement channel for backhaul infrastructure. Huawei Technologies leverages its integrated radio-access and transport portfolio to anchor large-scale 5G deployments across multiple continents. Ericsson competes through specialized microwave and fiber-optic transport solutions that sustain its position in European and North American carrier networks. Nokia differentiates via programmable IP routing platforms that extend software-defined control into the backhaul layer.
Mobile and wireless backhaul encompasses the transmission infrastructure that connects cell sites to core networks, typically operating over distances from hundreds of meters to tens of kilometers using carrier-grade latency thresholds below five milliseconds. Microwave systems historically dominated this function through licensed spectrum links in the six to forty-two gigahertz range, though millimeter-wave and fiber-optic alternatives now penetrate dense urban corridors where capacity demands exceed gigabit-per-cell thresholds. Fiber optic transport leads in total deployed capacity within urban network applications, while millimeter-wave segments represent the fastest-growing technology dimension as operators pursue street-level small-cell densification without trenching constraints. Satellite backhaul occupies niche margin pools in rural networks and public safety communications where terrestrial infrastructure remains economically prohibitive.
The Federal Communications Commission in the United States, the European Telecommunications Standards Institute across EU member states, and the Ministry of Industry and Information Technology in China collectively shape equipment certification timelines, spectrum auction structures, and open-interface mandates that determine vendor market access. REACH compliance and CE marking requirements within Europe impose material and electromagnetic-emission standards that filter non-conforming hardware from commercial deployment. Stakeholders must monitor evolving national security screening regimes for foreign telecommunications equipment as these frameworks increasingly dictate supplier eligibility before technical evaluation begins.
Market Dynamics
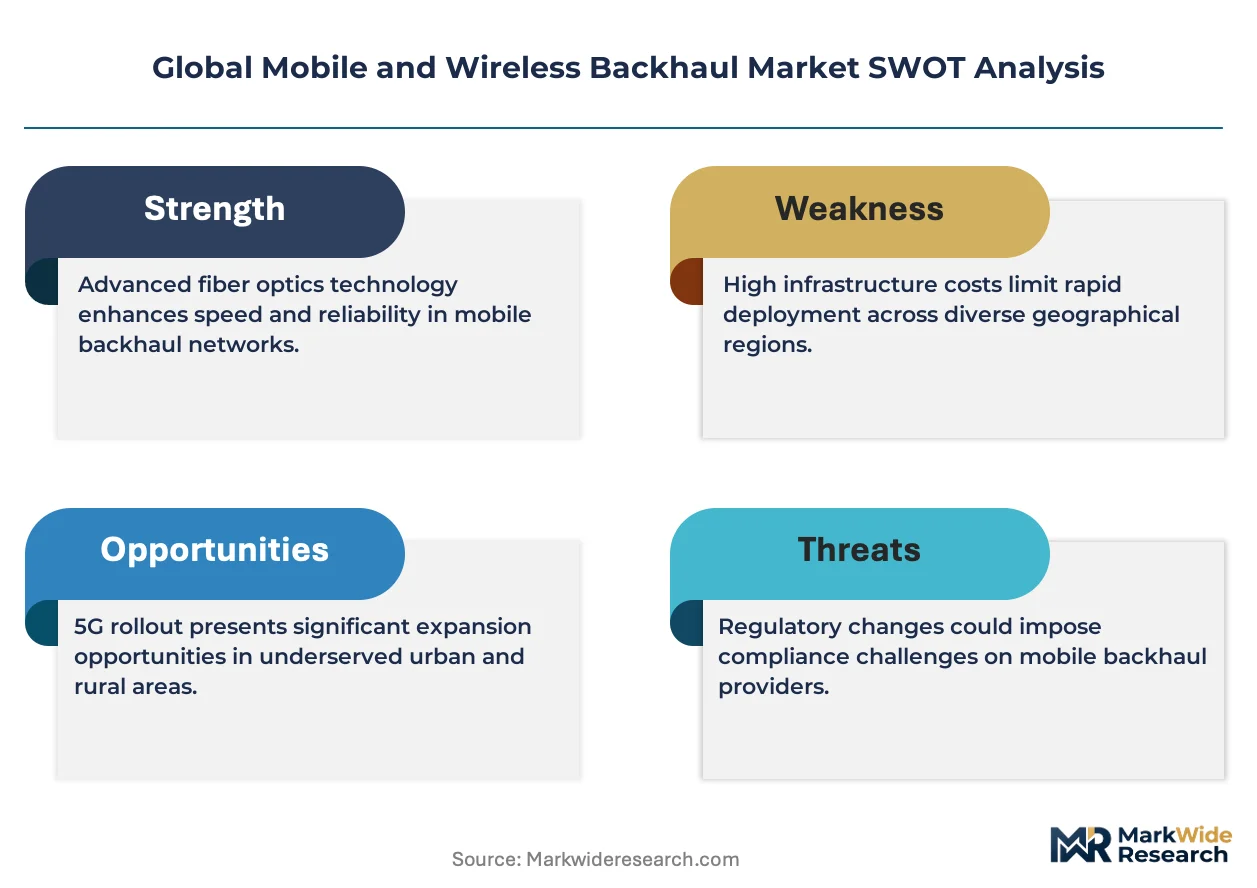
Telecom operators in dense urban corridors are compressing 5G transport deployment timelines as fiber-optic and millimeter-wave technologies systematically displace legacy copper and lower-band microwave infrastructure. This technology transition is reshaping vendor procurement criteria and compressing equipment certification cycles across multiple regulatory jurisdictions.
Growth Catalysts
- Net Neutrality Mandates:Regulatory frameworks in the United States, Germany, and South Korea are accelerating infrastructure investment timelines by removing traffic management uncertainty for operators.
- Small-Cell Densification:Street-level 5G deployments in metropolitan centers are generating demand for high-capacity backhaul links below five-millisecond latency thresholds.
- Spectrum Auction Structures:High-band and millimeter-wave allocations by the Federal Communications Commission and equivalent bodies are unlocking capacity for gigabit-per-cell transport requirements.
Market Restraints
- Fiber Trenching Costs:Physical infrastructure deployment in dense urban environments faces right-of-way fees and construction permitting delays that inflate project budgets.
- Equipment Certification Timelines:REACH compliance and CE marking requirements in Europe impose electromagnetic-emission and material standards that filter non-conforming hardware from commercial deployment.
- Licensed Spectrum Scarcity:Microwave backhaul in the six to forty-two gigahertz range faces congestion in metropolitan corridors where multiple operators compete for identical frequency blocks.
Strategic Opportunities
- Satellite Backhaul Expansion:Rural networks and public safety communications in remote geographies present niche margin pools where terrestrial infrastructure remains economically prohibitive.
- Open Interface Mandates:Regulatory pressure for vendor interoperability is creating entry pathways for specialized transport equipment suppliers outside incumbent radio-access portfolios.
- Software-Defined Convergence:Programmable IP routing platforms are extending software-defined control into the backhaul layer, enabling traffic engineering automation across multi-vendor environments.
Industry Challenges
- Multi-Technology Integration:Operators must synchronize fiber, millimeter-wave, and legacy microwave systems within unified management frameworks while maintaining carrier-grade reliability.
- Security Screening Complexity:National security regimes for foreign telecommunications equipment are increasingly dictating supplier eligibility before technical evaluation begins, elongating procurement cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Mobile and Wireless Backhaul Market |
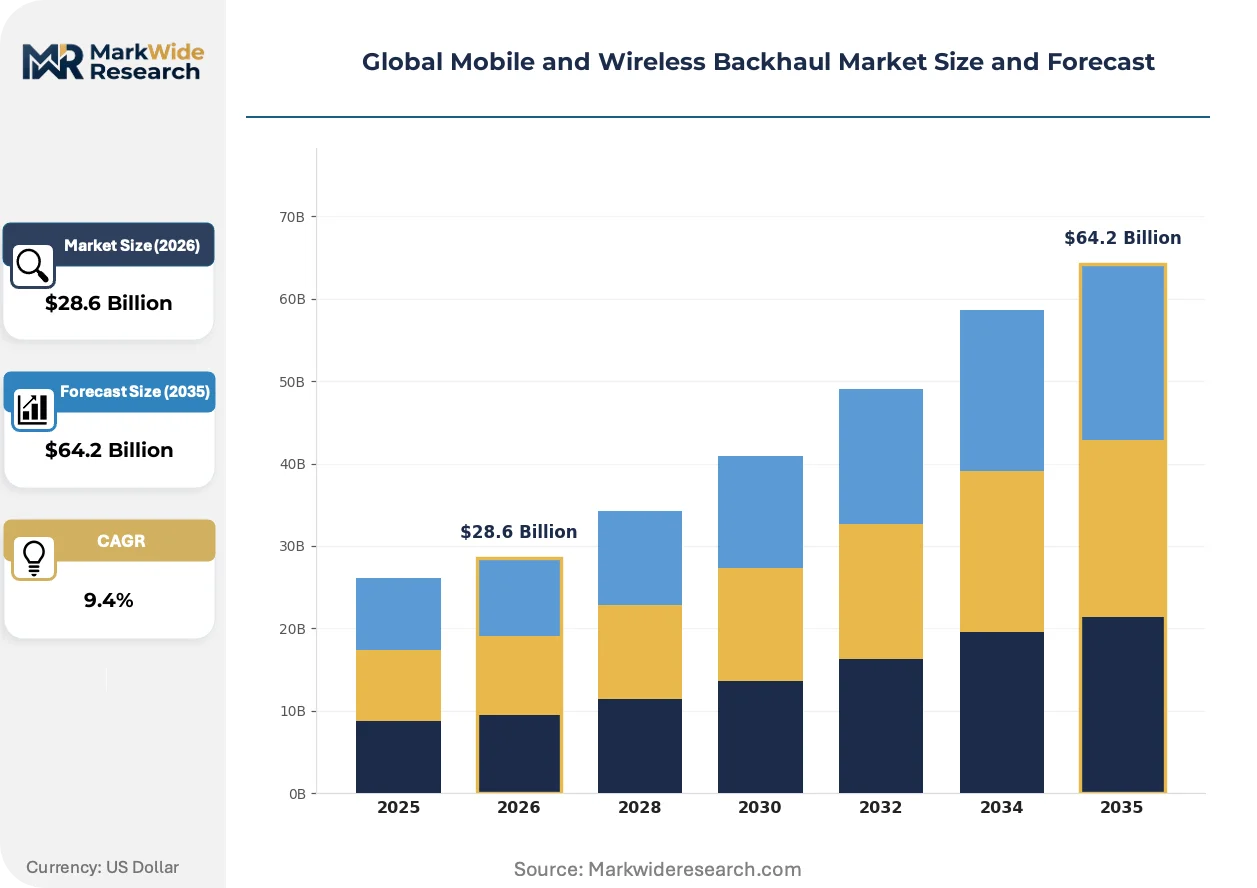
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Microwave, Fiber Optic, Satellite, Millimeter Wave, Ethernet Application: Urban Networks, Rural Networks, Enterprise Connectivity, Public Safety Communications End User: Mobile Network Operators, Internet Service Providers, Government Agencies, Managed Service Providers Service Type: Leased Line, Packet Transport, Optical Transport Network, IP Transit |
| Companies Covered | Ericsson, Huawei Technologies, Nokia, Cisco Systems, ZTE Corporation, Samsung Electronics, Juniper Networks, Ciena Corporation, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Mobile and Wireless Backhaul Market Shifts & Advancements
Transport technology evolution is compressing deployment models as operators abandon hierarchical network architectures in favor of flat, software-controlled backhaul topologies. Regulatory mandates and procurement pattern shifts are simultaneously reshaping how infrastructure reaches the field.
Millimeter-wave backhaul systems operating in the E-band and V-band spectrum are displacing traditional microwave links in urban small-cell deployments. Mobile network operators in metropolitan corridors are adopting these systems at accelerated pace to avoid fiber trenching constraints. The technology is displacing copper and lower-frequency microwave as the default transport medium for street-level densification projects.
The European Telecommunications Standards Institute has finalized open-interface specifications that mandate interoperability between radio-access and transport equipment. This framework fragments procurement patterns by enabling operators to source backhaul components independently from baseband hardware. Carrier networks across EU member states are restructuring vendor relationships to exploit this regulatory opening.
Enterprise connectivity buyers are collapsing the traditional hierarchy that favored mobile network operators as the dominant procurement channel for backhaul infrastructure. Large industrial campuses and smart city authorities are contracting directly with transport equipment vendors and systems integrators. This pattern is most visible in South Korea and Germany where municipal fiber initiatives and private 5G networks bypass incumbent carrier relationships.
Global Mobile and Wireless Backhaul Market Segmentation
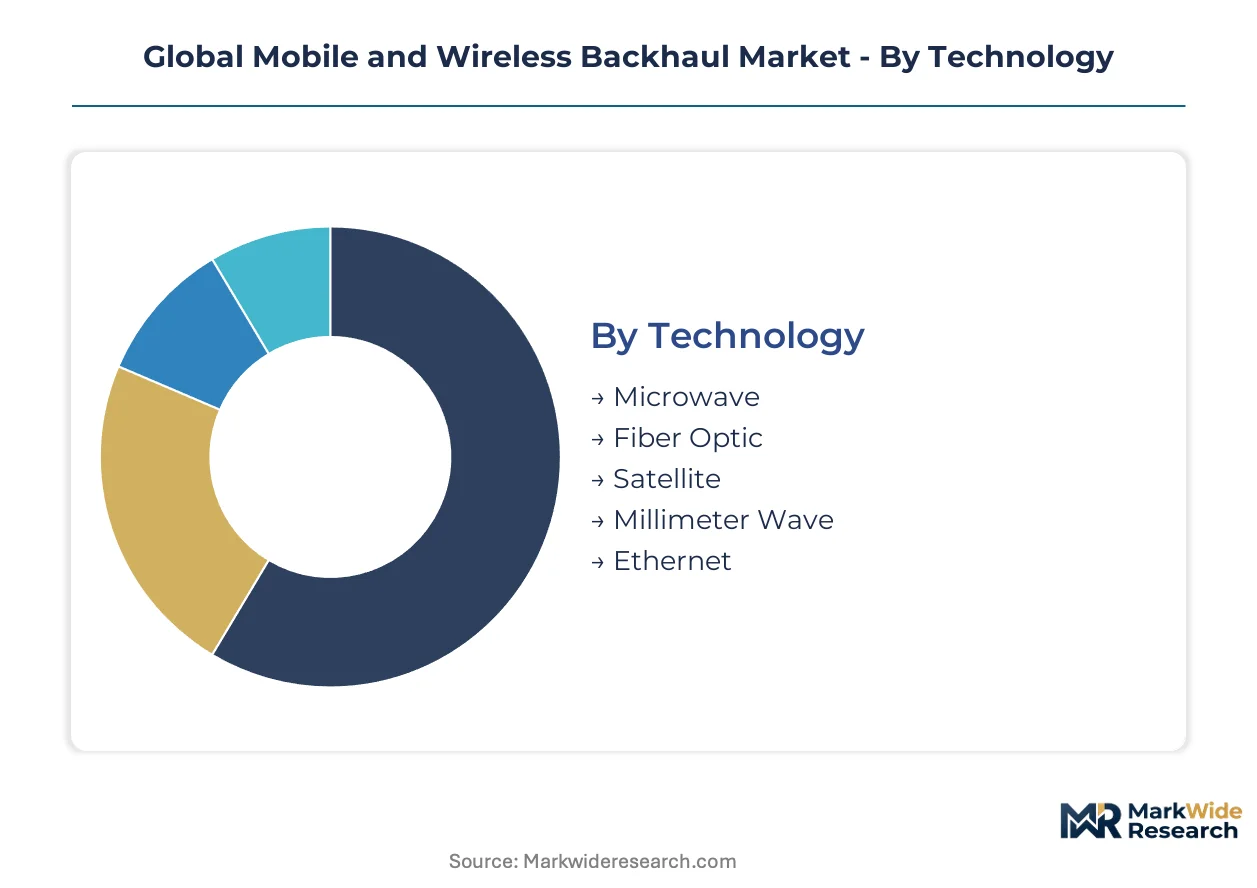
Technology choice in backhaul infrastructure locks in fifteen-year depreciation cycles and determines spectral efficiency ceilings. Procurement patterns across the four segmentation dimensions reveal divergent geographic concentrations and margin structures that reshape competitive positioning.
Technology:
Microwave and fiber optic deployments concentrate in domestic carrier networks across the United States, Germany, and South Korea, while millimeter wave and satellite systems serve export-led demand corridors in emerging markets.
- Microwave:Licensed spectrum links in the six to forty-two gigahertz range deliver carrier-grade latency below five milliseconds across distances up to fifty kilometers. United States mobile network operators in metropolitan corridors face licensed spectrum scarcity as multiple carriers compete for identical frequency blocks, compressing deployment timelines.
- Fiber Optic:Single-mode and multi-mode fiber deployments provide unlimited capacity scaling for gigabit-per-cell thresholds in dense urban environments. German operators absorb right-of-way fees and construction permitting delays that inflate project budgets, slowing trenching velocity relative to Asian markets.
- Satellite:Geostationary and low-earth-orbit constellations serve rural networks and public safety communications in remote geographies where terrestrial infrastructure remains economically prohibitive.
- Millimeter Wave:E-band and V-band systems operating at seventy-one to eighty-six gigahertz enable street-level small-cell densification without trenching constraints.
- Ethernet:Copper and fiber-based Ethernet transport supports enterprise campus interconnect and last-mile aggregation in cost-sensitive deployments.
Fiber optic holds installed capacity across urban corridors. Millimeter wave is rotating up the share rankings as operators pursue densification without physical infrastructure constraints.
Application:
Urban network deployments command premium pricing tiers due to latency sensitivity and capacity density requirements, while rural and public safety applications operate on constrained procurement budgets with longer replacement cycles.
- Urban Networks:Street-level 5G deployments in metropolitan centers generate demand for high-capacity backhaul links with sub-five-millisecond latency thresholds. South Korean operators accelerate small-cell densification through municipal fiber initiatives that bypass traditional carrier hierarchies.
- Rural Networks:Sparse subscriber density and extended transport distances favor microwave and satellite technologies over fiber trenching. United States rural carriers face Universal Service Fund uncertainty that compresses capital planning horizons.
- Enterprise Connectivity:Private 5G networks and smart city authorities contract directly with transport equipment vendors, collapsing traditional mobile network operator procurement channels.
- Public Safety Communications:Mission-critical voice and data requirements mandate hardened infrastructure with geographic redundancy and cyber resilience certifications.
Urban networks concentrate vendor margin pools. Enterprise connectivity is expanding most quickly as industrial campuses bypass incumbent carrier relationships.
End User:
Mobile network operators and internet service providers dominate volume procurement with standardized technical specifications, while government agencies and managed service providers introduce customization requirements that elongate sales cycles.
- Mobile Network Operators:Tier-one carriers in the United States, Germany, and South Korea drive technology roadmaps through consolidated procurement of radio-access and transport infrastructure.
- Internet Service Providers:Fixed-wireless and fiber-overbuilders compete for backhaul capacity to support residential broadband expansion in suburban and exurban markets.
- Government Agencies:Defense and public safety networks impose national security screening regimes that dictate supplier eligibility before technical evaluation begins.
- Managed Service Providers:Outsourced network operations for enterprise and government clients require multi-tenant management platforms with service-level agreement automation.
Mobile network operators anchor procurement volume. Managed service providers are climbing the fastest as enterprises externalize infrastructure operations.
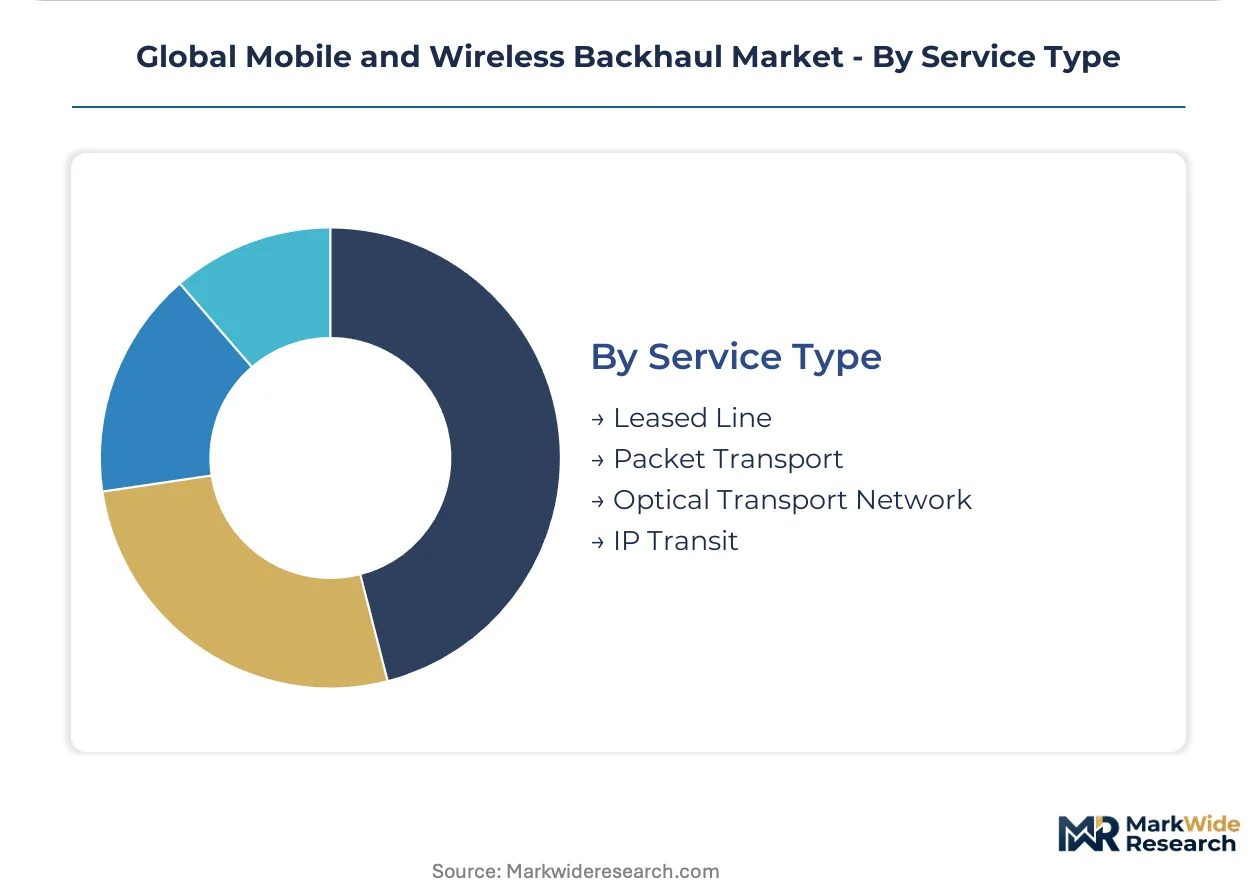
Service Type:
Leased line and packet transport services generate recurring revenue streams with long contract tenors, while optical transport network and IP transit offerings face price compression from commoditization and overbuild competition.
- Leased Line:Dedicated point-to-point circuits guarantee bandwidth and latency for mission-critical applications with contractual availability commitments exceeding 99.999 percent.
- Packet Transport:MPLS and segment routing technologies enable statistical multiplexing efficiency across converged voice, video, and data traffic.
- Optical Transport Network:ITU-T standardized framing and forward error correction extend fiber reach while enabling multi-vendor interoperability.
- IP Transit:Border gateway protocol peering and transit arrangements connect cellular networks to internet exchange points and content delivery networks.
Leased line services retain pricing power in latency-sensitive segments. Packet transport is gaining share fastest as operators converge legacy circuit networks onto unified IP infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The fiber-optic cable networks spanning the Atlantic seaboard and Great Lakes manufacturing belt underwrite United States leadership in 5G transport infrastructure deployment. Dense metropolitan fiber rings and millimeter-wave relay towers anchor capacity expansion across three continents.
United States
Verizon and AT&T drive small-cell densification in Manhattan, Chicago, and Los Angeles corridors. The FCC's mid-band spectrum auctions compress equipment deployment timelines for C-band backhaul links. Dallas-Fort Worth and Atlanta clusters concentrate millimeter-wave manufacturing and systems integration capacity.
Germany
Deutsche Telekom accelerates fiber-to-the-antenna upgrades across the Rhine-Ruhr and Bavarian industrial zones. REACH compliance and CE marking requirements filter non-conforming hardware before commercial deployment. Berlin-Brandenburg hosts ETSI standardization workshops that reshape open-interface procurement across EU member states.
South Korea
SK Telecom and KT Corporation pursue street-level 5G densification through Seoul municipal fiber initiatives. The Ministry of Science and ICT mandates multi-vendor interoperability in carrier procurement specifications. Busan-Ulsan manufacturing corridors produce E-band and V-band millimeter-wave transmission equipment for export markets.
China
China Mobile and China Unicom deploy integrated radio-access and transport portfolios across Yangtze River Delta megacities. MIIT spectrum allocations in the 26 GHz and 40 GHz bands unlock millimeter-wave capacity for gigabit-per-cell thresholds. Shenzhen and Beijing clusters concentrate programmable IP routing and software-defined networking development.
Japan
NTT Docomo and SoftBank synchronize fiber and millimeter-wave systems for Tokyo-Osaka corridor 5G coverage. METI funding programs subsidize rural microwave backhaul replacement in Hokkaido and Tohoku regions. Nagoya industrial precincts manufacture carrier-grade optical transport equipment for Asia-Pacific export demand.
Global Mobile and Wireless Backhaul Market Competitive Landscape
Concentration sits with integrated radio-access vendors that anchor procurement decisions through bundled transport and baseband offerings. The vendor base spans three tiers: full-stack telecommunications equipment suppliers, specialized microwave and optical transport specialists, and programmable networking software vendors. Strategic moves center on open-interface certification investments and direct enterprise connectivity contracts that bypass traditional mobile network operator channels.
Among the integrated equipment tier, Huawei Technologies and Ericsson occupy positions that exemplify divergent geographic market access patterns. Nokia represents the programmable networking archetype through software-defined control platforms. Samsung Electronics anchors the Asian vendor contingent with vertically integrated semiconductor and systems capabilities. These four companies collectively illustrate how regulatory screening regimes and spectrum auction structures now determine competitive positioning before technical evaluation begins.
| Leading Market Players |
|---|
| Ericsson |
| Huawei Technologies |
| Nokia |
| Cisco Systems |
| ZTE Corporation |
| Samsung Electronics |
| Juniper Networks |
| Ciena Corporation |
| NEC Corporation |
| Others |
Supply & Pricing Matrix
REACH compliance and CE marking requirements in Europe gate both supplier qualification and price differentiation simultaneously, filtering non-conforming hardware from commercial deployment while creating tiered cost structures based on certification investment levels. Equipment vendors absorb electromagnetic-emission testing and material-standard compliance costs that inflate entry-level pricing, compressing margins for uncertified competitors and concentrating pricing power among pre-qualified incumbents.
Pricing Analysis
Volume-discount tiering structures dominate procurement contracts, with three-tier pricing separating carrier-grade certification holders from standard-compliance vendors and economy-tier resellers. Price differentiation hinges on millimeter-wave spectrum certification depth and fiber-optic reach performance, with latency guarantees below five milliseconds commanding substantial premiums. Cost compression in the economy tier is intensifying because open-interface mandates fragment procurement volumes across multiple specialized suppliers. Mobile network operators exhibit lowest price sensitivity due to fifteen-year depreciation cycles, while managed service providers face acute margin pressure from multi-tenant SLA automation requirements.
Supply Chain Analysis
Strategic stockpiling of E-band and V-band radio frequency components prevails over just-in-time inventory models, as semiconductor lead times for gallium nitride power amplifiers and beamforming integrated circuits create supply vulnerability. Manufacturing concentrates in China, South Korea, and Germany, with Shenzhen and Busan-Ulsan clusters producing millimeter-wave transmission equipment and Bavarian industrial zones hosting optical transport assembly. Raw material dependencies include rare-earth elements for magnet manufacturing, high-purity silica for fiber drawing, and specialized substrates for compound semiconductors. Single-source vulnerability in gallium arsenide wafer supply creates concentrated risk. Distribution runs through carrier-direct procurement channels and systems integrator partnerships serving enterprise bypass markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open RAN interoperability specifications are collapsing traditional bundled procurement hierarchies, transforming backhaul infrastructure into a platform-economy battleground where transport vendors compete independently from radio-access suppliers.
For Market Incumbents: Shield core carrier relationships through accelerated open-interface certification investments that preempt regulatory fragmentation across EU member states. Deepen backward integration into programmable silicon development to defend against merchant chip vendors commoditizing routing functions. Prioritize direct enterprise connectivity contracts in South Korea and Germany where municipal fiber initiatives bypass incumbent mobile network operator hierarchies. For New Entrants and Emerging Players: Rural satellite backhaul integration services represent the most penetrable white-space target, as geostationary and low-earth-orbit constellation operators lack terrestrial systems integration capabilities. Target public safety communications procurement channels where national security screening regimes elongate incumbent sales cycles. Pursue managed service provider partnerships as the primary go-to-market angle, leveraging multi-tenant automation platforms to displace carrier-direct relationships. For Investors and Strategic Acquirers: FCC mid-band spectrum auction completion reshapes the acquisition landscape by unlocking C-band deployment capital for transport infrastructure specialists. Frame long-term viability around software-defined convergence plays with five-to-ten-year technology depreciation alignment. Target programmable IP routing platform developers with open-interface certification momentum. Watch ETSI standardization workshop outputs as the signal indicating procurement pattern fragmentation velocity across EU markets.| Strategic Initiative | Industry Significance |
|---|---|
| Open Interface Certification Investment | ETSI mandates unlock vendor interoperability procurement pathways across EU carrier networks. |
| Millimeter-Wave Manufacturing Scale-Up | E-band and V-band capacity expansion in Busan-Ulsan corridors captures small-cell densification demand. |
| Enterprise Direct Contracting | Municipal fiber initiatives in Seoul and Berlin bypass traditional mobile network operator hierarchies. |
| Software-Defined Convergence Platform | Programmable IP routing extends automation control into multi-vendor backhaul environments. |
| Satellite-Terrestrial Integration Partnership | Low-earth-orbit constellation alliances address rural and public safety coverage gaps. |
Research Methodology
Operator-level perspectives from mobile network transport engineers, carrier procurement directors, and systems integration specialists anchored the qualitative base, supplemented by regulatory affairs leads at ETSI and FCC proceedings. Primary interview insights combined with secondary validation from ITU-T standards documentation, SEC equipment vendor filings, and national spectrum auction records. Bottom-up cell-site deployment modeling and top-down infrastructure investment tracking triangulated market sizing across the projection horizon.
Sensitivity analysis tested forecast robustness against spectrum allocation delays, open-interface adoption velocity, and fiber trenching cost inflation scenarios. Segmentation dimensions modeled include technology type, application environment, end-user category, and service delivery model, with regional regulatory clusters as an additional cross-cutting dimension. CAGRs derived from equipment shipment trajectories and carrier capex disclosure patterns, incorporating millimeter-wave deployment timelines and small-cell densification curves as industry-specific inputs.
Underlying assumptions cover regulatory mandate enforcement consistency, semiconductor supply normalization, and carrier consolidation stability, with deviation risk concentrated in national security screening regime expansion and spectrum auction schedule disruptions. Revision becomes warranted when open-interface procurement penetration crosses critical mass thresholds or when satellite-terrestrial integration economics disrupt rural microwave backhaul viability.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wireless Technologies
Public Wi-Fi Market
Wireless Technologies
USA Li-Fi Market
Wireless Technologies
Global Gi Fi Technology Market
Wireless Technologies
Wireless Camera Market
Wireless Technologies
Femtocell Market
Wireless Technologies
Wireless Intercom Equipment Market
Wireless Technologies
Telecom Wireless Data Market
Wireless Technologies
Public Safety Wireless Communication and Municipal Wireless Communication Market
Wireless Technologies
5G Wireless Equipment Market
Wireless Technologies
LTE and 5G Market
Wireless Technologies
Underwater Wireless Communication Market
Wireless Technologies
Cellular Repeater Market
Wireless Technologies
Europe Fixed Wireless Access (FWA) Market
Wireless Technologies
Asia-Pacific Wireless Microphone Market
Wireless Technologies
Wireless Microphone Market
Wireless Technologies
Global Bluetooth Beacon and Ibeacon Market