
 France Telecom Towers Market | 2026-2036
France Telecom Towers Market Size, Share, and Industry Trends Forecast 2026-2036
France Telecom Towers Market Insights
Buyer concentration among France's four mobile network operators is repositioning the tower market toward infrastructure-sharing models and neutral host arrangements. Cellnex France leverages its European portfolio scale to compete for anchor-tenant contracts across dense urban zones. TOTEM France, spun from Orange's captive tower base, sustains deep relationships with its former parent while extending services to rival operators. American Tower France anchors its position through long-term lease structures with SFR and Bouygues Telecom.
France telecom towers are steel or concrete structures engineered to support multiple antenna arrays at heights typically ranging from 15 to 80 meters, designed to withstand Eurocode wind loads and electromagnetic interference thresholds while enabling multi-tenant radio access network deployment. Macro towers dominate the installed base due to their capacity for multi-band co-location, though small cells represent the fastest-growing segment as municipalities tighten zoning restrictions and operators target capacity infill in pedestrian-dense districts. Distributed antenna systems capture concentrated margin pools in transport hubs and stadium venues where traditional tower placement proves impractical.
ANFR governs electromagnetic field exposure limits and site authorization timelines, while ARCEP enforces wholesale access obligations and infrastructure-sharing mandates that directly shape operator procurement decisions. France's national 5G security certification framework, administered by ANSSI, imposes equipment vetting requirements that filter through to tower-level hardware specifications and vendor eligibility. Stakeholders must monitor the interplay between municipal zoning liberalization for small cells and escalating energy-efficiency audits under the national low-carbon transition strategy.
Market Dynamics
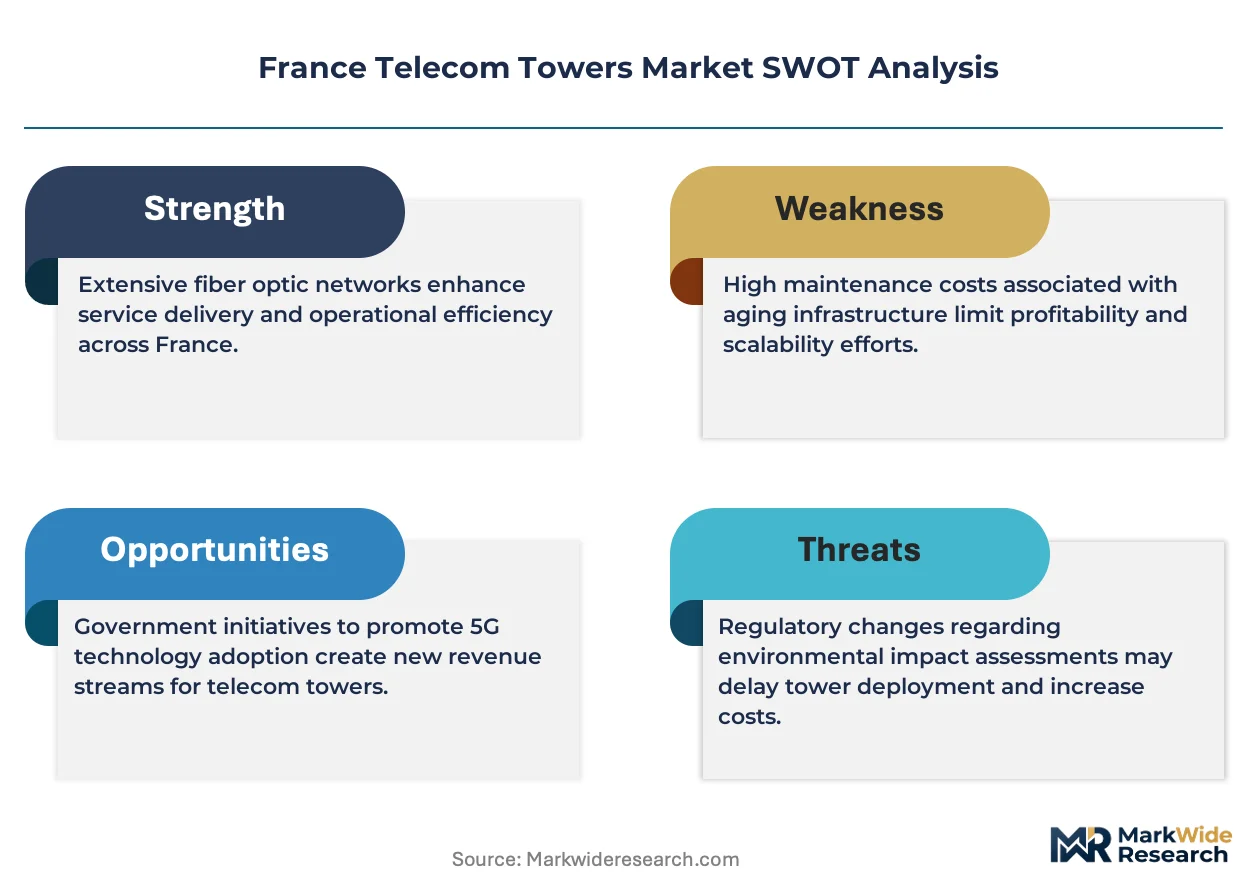
France's 5G spectrum rollout under ANFR allocation rules is compressing site authorization timelines while mandating infrastructure-sharing, forcing operators to abandon single-tenant tower strategies in favor of neutral-host architectures across dense urban corridors.
Growth Catalysts
- ANFR Spectrum Allocation:The national frequency agency's 5G band assignments require rapid site densification, accelerating co-location demand on existing macro towers.
- Small Cell Zoning Liberalization:Municipal reforms in Lyon, Marseille, and Toulouse streamline right-of-way access for pedestrian-zone capacity infill.
- Multi-Operator Sharing Mandates:ARCEP enforcement of wholesale access obligations compels infrastructure pooling, reducing redundant build-outs in the Greater Paris zone.
Market Restraints
- Steel Input Volatility:Fluctuating European hot-rolled coil prices compress fabrication margins for lattice tower producers serving the Île-de-France corridor.
- Electromagnetic Field Exposure Limits:ANFR's conservative public exposure thresholds restrict antenna placement density in residential districts, constraining revenue per site.
- Concrete Foundation Lead Times:Specialized geotechnical contractors for 80-meter monopoles face capacity bottlenecks extending deployment schedules.
Strategic Opportunities
- Edge Computing Convergence:Tower-mounted micro data centers combining 5G baseband with AI inference hardware open new tenancy revenue streams.
- Transport Hub DAS Expansion:Distributed antenna system deployment in TGV stations and Paris Métro extensions addresses coverage gaps where macro towers fail.
- National Low-Carbon Transition:Energy-efficiency audits under France's decarbonization strategy reward solar-hybrid tower retrofits with accelerated permitting.
Industry Challenges
- RF Engineering Talent Scarcity:Specialized electromagnetic simulation and interference mitigation skills command premium wages, constraining deployment velocity.
- Multi-Tenant Integration Complexity:Harmonizing antenna configurations for Orange, SFR, Bouygues Telecom, and Free Mobile on shared structures demands intensive radio frequency coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Telecom Towers Market |
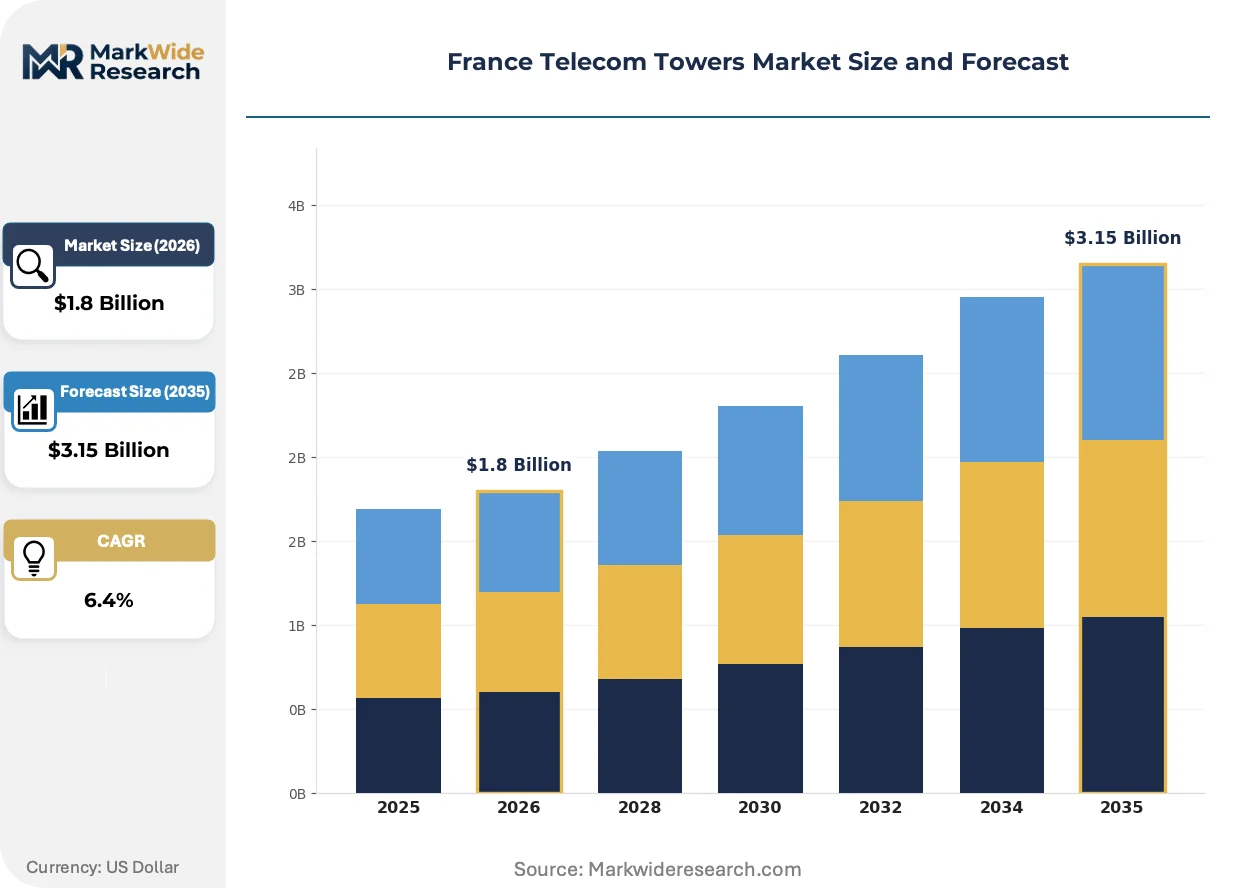
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Macro Towers, Micro Towers, Small Cells, Distributed Antenna Systems Technology: 4G LTE, 5G, Fiber Optic, Microwave End User: Telecommunication Operators, Broadcasting Companies, ISPs, Government Agencies Installation: Onshore, Rooftop, Greenfield, Brownfield |
| Companies Covered | Cellnex France, TOTEM France, TDF Infrastructure, American Tower France, Phoenix Tower International France, Orange, SFR, Bouygues Telecom, Free Mobile, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Telecom Towers Market Trends and Innovations
Active antenna systems and software-defined radio architectures are collapsing the distinction between tower infrastructure and network intelligence, while regulatory pressure on embodied carbon reshapes material selection and site design protocols.
Massive MIMO active antenna units is electrifying traditional passive tower economics by integrating beamforming intelligence directly at the radiating element. Mobile network operators in the Greater Paris metropolitan zone are replacing legacy passive arrays at 40% of macro sites annually. This convergence is electrifying tower valuations as real estate assets become compute-hosting platforms rather than mere steel structures.
ANSSI's 5G security certification framework is filtering hardware procurement toward pre-approved vendor lists, restricting antenna and transmission equipment eligibility for critical infrastructure sites. Tower operators must now validate component traceability through supply chain documentation. The certification burden falls heaviest on small cell deployments in government-adjacent zones, where operators face extended vetting timelines.
Long-term lease structures are giving way to shorter-term, revenue-sharing arrangements as mobile network operators seek balance-sheet flexibility. Infrastructure funds and tower specialists now compete on variable-rate models tied to tenancy count rather than fixed escalators. This recalibration is most visible in the Île-de-France industrial corridors, where anchor-tenant negotiations increasingly feature performance-linked rent mechanisms.
France Telecom Towers Market Segmentation
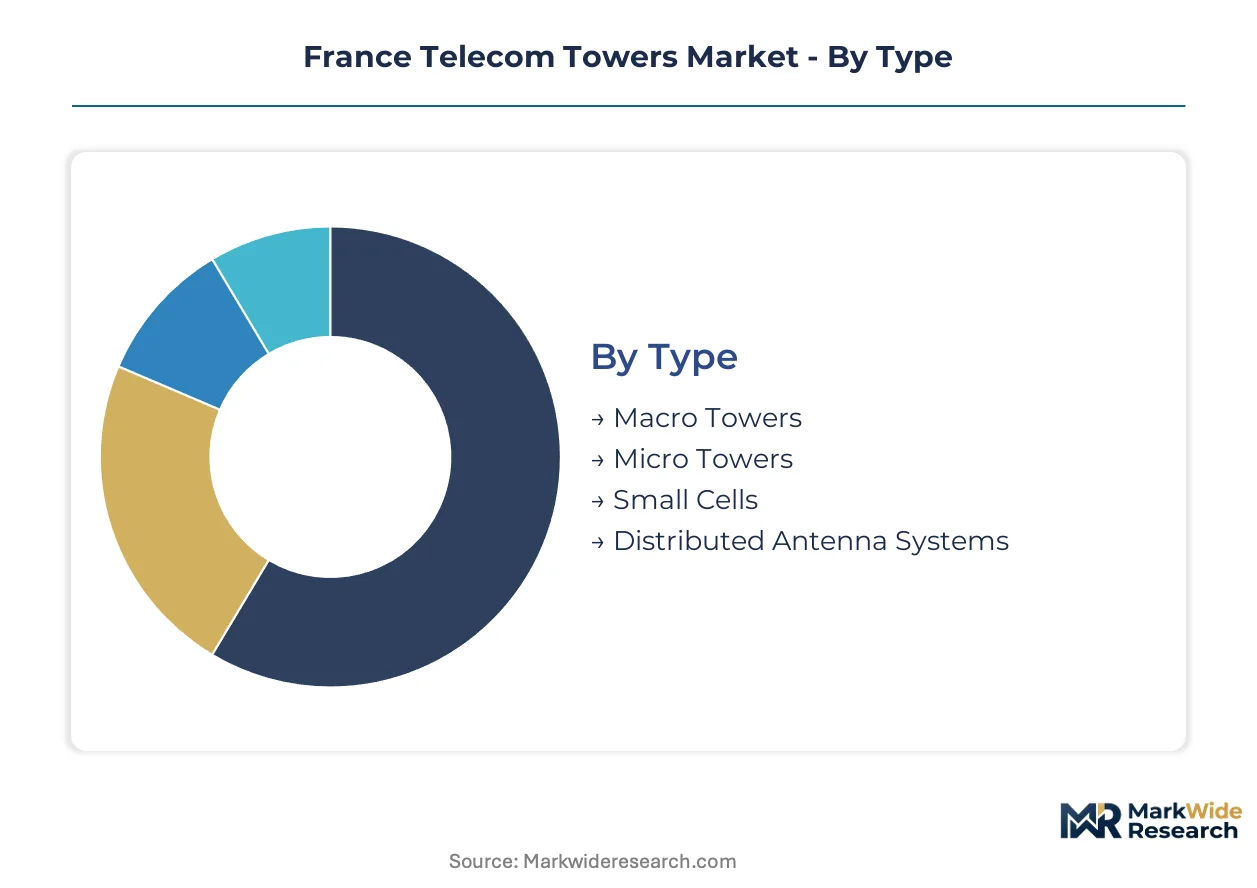
Tower infrastructure in France fragments across structural types, radio technologies, tenant categories, and deployment modes. Each dimension shapes procurement patterns, lease economics, and regulatory compliance burdens for site operators and mobile network operators alike.
Type:
Structural standardization dominates at the macro scale, while small-form factors demand bespoke engineering for municipal integration.
- Macro Towers:Steel lattice or tubular structures ranging 30-80 meters support multi-tenant antenna arrays across rural coverage zones and suburban capacity rings. Orange and SFR anchor long-term leases on these assets in the Greater Paris periphery, where ANFR co-location mandates maximize tenancy density per site.
- Micro Towers:Compact structures under 30 meters address intermediate coverage gaps in peri-urban corridors. Deployment concentrates along Île-de-France transport arteries where full-height macros face zoning exclusion.
- Small Cells:Pole-mounted or building-integrated nodes enable pedestrian-zone capacity infill. Lyon and Marseille have streamlined right-of-way permitting for these installations.
- Distributed Antenna Systems:Indoor coaxial or fiber-fed antenna networks serve venues where outdoor towers fail. TGV stations and Paris Métro extensions represent concentrated demand pockets.
Most installed capacity flows through Macro Towers. Expansion is steepest in Small Cells.
Technology:
Radio generation determines power requirements, backhaul topology, and hardware refresh cadence across the installed base.
- 5G:Massive MIMO active antenna units integrate beamforming intelligence at the radiating element, collapsing traditional distinctions between tower infrastructure and network processing. ANFR spectrum allocation rules compress site authorization timelines for 5G rollouts in dense urban corridors.
- 4G LTE:Legacy macro sites undergo selective modernization rather than full replacement. Rural coverage obligations sustain maintenance revenue on these assets.
- Fiber Optic:Fronthaul and backhaul connectivity links tower bases to core networks. Deployment concentrates in the Greater Paris zone where fiber density supports centralized baseband processing.
- Microwave:Point-to-point radio links serve sites where fiber trenching proves uneconomical. Mountainous terrain in Alpine and Pyrenean zones sustains this technology.
Capital deployment tilts heavily toward 5G infrastructure. Fiber backhaul is expanding most quickly as centralized RAN architectures proliferate.
End User:
Tenant concentration among mobile operators creates pricing power asymmetries that reshape lease structure negotiations.
- Telecommunication Operators:Orange, SFR, Bouygues Telecom, and Free Mobile drive aggregate demand through national coverage obligations and capacity scaling requirements. ARCEP infrastructure-sharing mandates compel these rivals to co-locate on neutral-host structures.
- Broadcasting Companies:Digital terrestrial television and radio transmission operators lease tower space for nationwide signal distribution. ANFR coordinates spectrum coexistence between broadcast and mobile services.
- ISPs:Fixed wireless access providers mount customer premise equipment on tower structures to bypass last-mile fiber deployment. Rural broadband subsidy programs accelerate this tenant category.
- Government Agencies:Emergency services and defense applications require hardened sites with ANSSI security certification. These tenants pay premium rates for isolated, sovereign-controlled infrastructure.
Telecommunication Operators anchor the revenue base. Government tenancy delivers the highest margin per square meter of tower space.
Installation:
Site preparation methodology determines capital intensity, timeline risk, and community acceptance profiles for new deployments.
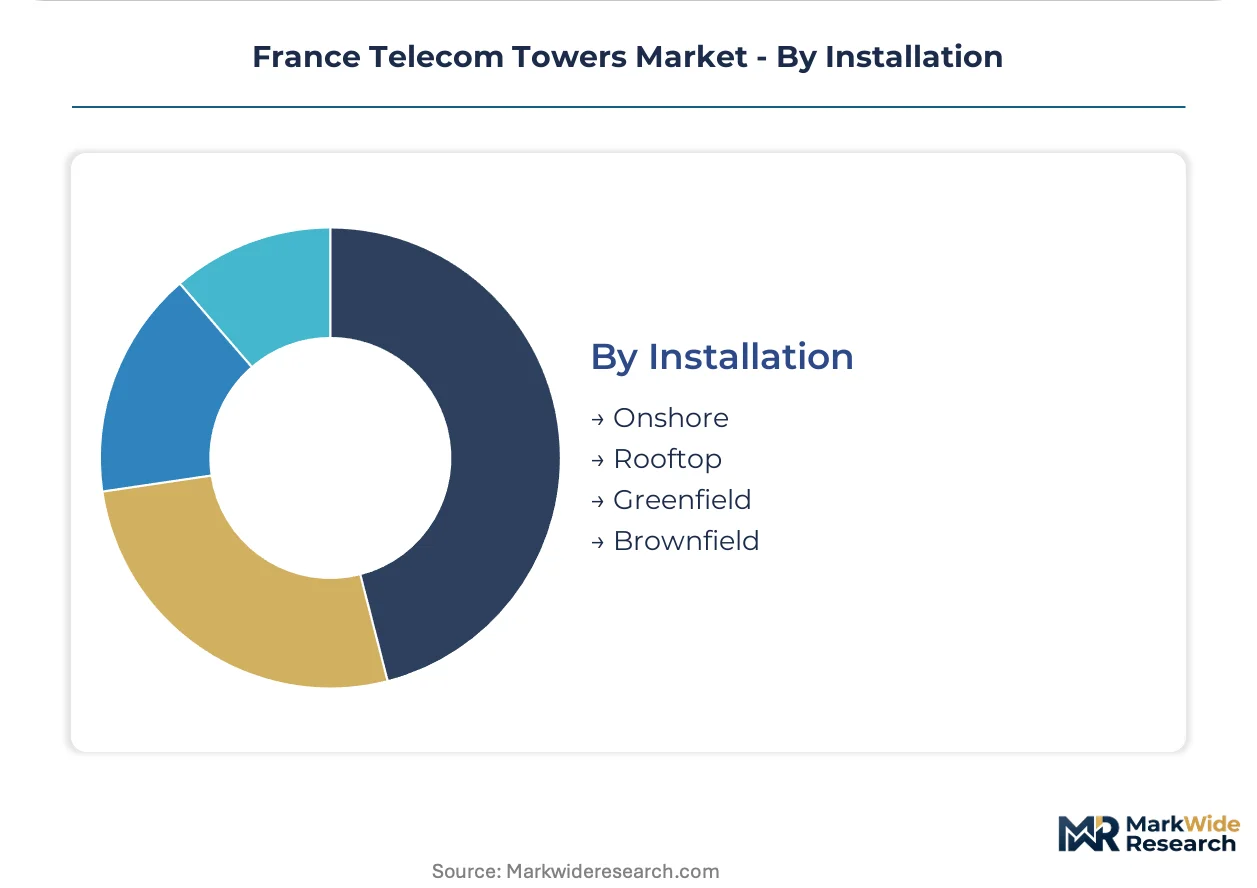
- Brownfield:Retrofit of existing structures—whether legacy telecom towers, power pylons, or building rooftops—minimizes civil works and accelerates time-to-revenue. TOTEM France specializes in extracting additional tenancy from Orange's captive brownfield portfolio.
- Greenfield:New tower construction on previously undeveloped land addresses coverage white spots. Municipal opposition and agricultural land preservation rules constrain greenfield permitting in Brittany and Normandy.
- Rooftop:Building-integrated installations exploit urban height without ground footprint. Paris Haussmann-era building stock presents structural load challenges that limit rooftop viability.
- Onshore:Ground-based deployments on public or private land outside dense urban cores. Standardized foundation designs reduce geotechnical uncertainty for these installations.
Brownfield deployment dominates volume given co-location economics. Greenfield construction is climbing the fastest as 5G coverage mandates push into underserved zones.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's tower market prioritizes rural coverage parity, while France concentrates investment in dense urban 5G corridors. Both markets face ANFR and Bundesnetzagentur co-location mandates, yet deployment patterns diverge sharply across their industrial heartlands.
Germany
Deutsche Telekom and Vodafone pursue aggressive site densification along Autobahn corridors and industrial zones in North Rhine-Westphalia. Bundesnetzagentur enforces infrastructure-sharing under the Telecommunications Act, reducing redundant macro tower construction. Bavaria's Munich-Stuttgart axis hosts concentrated small cell rollouts targeting manufacturing 5G campuses.
United Kingdom
BT's Openreach and VMO2 accelerate tower separation strategies, spinning infrastructure into independent entities. Ofcom's 5G spectrum auction conditions mandate coverage obligations in rural Scotland and Wales. London's Square Mile and Canary Wharf districts drive premium DAS deployments in transport nodes.
Spain
Telefónica and Orange España consolidate tower assets through sale-and-leaseback arrangements with Cellnex. CNMC wholesale access rules compel network sharing in duplicated coverage zones. Barcelona and Madrid metropolitan areas prioritize Massive MIMO upgrades on existing macro sites.
Italy
TIM and Vodafone Italia pool infrastructure via INWIT, the jointly controlled tower vehicle. AGCOM's 5G spectrum licenses impose population coverage targets in southern regions. Lombardy's Milan-Bergamo industrial corridor anchors the densest antenna concentration in the national grid.
Netherlands
KPN and T-Mobile Netherlands pursue aggressive fiber-backhaul integration with tower-mounted radio units. ACM enforces symmetric wholesale pricing for shared infrastructure access. The Randstad conurbation—Amsterdam-Rotterdam-The Hague—hosts the majority of multi-tenant small cell deployments.
France Telecom Towers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists for tenancy contracts across France's four-operator mobile ecosystem. Market structure tilts toward consolidation as infrastructure funds acquire captive tower portfolios from former parent operators. Two strategic archetypes dominate: European-scale neutral hosts leveraging cross-border procurement power, and domestically rooted operators exploiting incumbent relationships with former parents. Competitive dynamics center on anchor-tenant lease renegotiations and municipal small cell concession bidding.
Among France-based tower operators, Cellnex France and TOTEM France exemplify contrasting strategic postures. Cellnex France occupies a position as the European-scale neutral host, drawing on portfolio breadth across multiple jurisdictions. TOTEM France anchors the domestically rooted archetype, maintaining structural ties to Orange's operational requirements while extending tenancy to rival operators. American Tower France represents the third archetype: the global infrastructure fund with long-duration lease structures and balance-sheet capacity for portfolio expansion.
| Leading Market Players |
|---|
| Cellnex France |
| TOTEM France |
| TDF Infrastructure |
| American Tower France |
| Phoenix Tower International France |
| Orange |
| SFR |
| Bouygues Telecom |
| Free Mobile |
| Others |
Pricing and Supply Chain Analysis
RF engineering specialists concentrated in the Greater Paris metropolitan zone command wage premiums that widen spreads between premium-tier site deployments and economy-grade rural installations. Labor-cost differentials across Île-de-France and provincial markets stratify tenancy pricing, with multi-tenant coordination complexity driving tier separation.
Pricing Analysis
Capacity additions in the Île-de-France corridor are reshaping price floors for macro tower tenancy as Cellnex France and TOTEM France expand co-location availability. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by site certification grade under ANSSI security frameworks and fiber backhaul density. Pricing pressure stems from steel input volatility compressing fabrication margins for lattice tower producers. Government agencies exhibit lowest price sensitivity due to sovereign security requirements, while rural broadband ISPs face acute cost constraints under subsidy program caps.
Supply Chain Analysis
Freight costs from German and Italian steel mills to French fabrication centers fluctuate with Rhine water levels and Alpine tunnel capacity, conditioning just-in-time delivery schedules for 80-meter monopole components. Supply concentrates in Spain, Poland, and Turkey for hot-rolled coil, with geotechnical contracting capacity anchored in domestic markets. Raw material dependencies span European steel grades, concrete admixtures, and copper grounding systems. Single-source vulnerability persists in specialized antenna mounting hardware qualified under ANFR electromagnetic specifications. Distribution runs through tower specialists holding long-term municipal concessions rather than direct operator procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's telecom tower market offers margin expansion through energy-efficiency retrofits qualifying for accelerated permitting under national decarbonization audits, while premium-tier DAS deployments in transport hubs capture pricing power from coverage-gap urgency.
For Market Incumbents: Acquire brownfield rooftop portfolios in Lyon and Marseille where zoning liberalization accelerates small cell densification. Neutral-host operators should deepen fiber-backhaul integration to defend tenancy against emerging edge-computing specialists. ANFR electromagnetic field threshold tightening threatens revenue per site in residential districts, requiring proactive antenna reconfiguration investments. For New Entrants and Emerging Players: Enter via transport hub DAS concessions where macro tower placement fails and incumbent presence remains thin. TGV station extensions and Paris Métro line expansions represent the most penetrable deployment mode. Government-adjacent zones with ANSSI certification requirements offer premium-rate tenancy with extended vetting timelines that deter rapid competitive response. For Investors and Strategic Acquirers: Infrastructure funds with European portfolio scale are the most active acquirer in this space, consolidating captive towers from mobile network operators seeking balance-sheet flexibility. Long-term viability rests on tenancy-count growth rather than fixed-escalator lease structures. Monitor ARCEP enforcement intensity on wholesale access obligations as the inflection signal for co-location demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Co-Location Agreement Expansion | ARCEP mandates infrastructure-sharing, pooling Orange, SFR, Bouygues Telecom, and Free Mobile on neutral-host structures. |
| Edge Computing Tower Integration | Micro data centers combining 5G baseband with AI inference hardware open new tenancy revenue streams beyond radio access. |
| Solar-Hybrid Retrofit Program | Energy-efficiency audits under France's low-carbon transition reward renewable tower upgrades with accelerated municipal permitting. |
| Small Cell Zoning Concession Bidding | Municipal reforms in Lyon, Marseille, and Toulouse streamline right-of-way access for pedestrian-zone capacity infill. |
| ANSSI Security Certification Investment | Hardware vetting requirements filter antenna and transmission equipment eligibility for critical infrastructure sites. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with network planning executives at mobile operators, tower portfolio managers, municipal zoning officers, and RF engineering contractors with secondary validation. Regulatory filings from ANFR and ARCEP, steel trade association data, and infrastructure fund disclosure documents anchored supply-side assessment. Bottom-up site-level tenancy modeling and top-down market sizing triangulated volume estimates.
Historical reference periods spanning the installed base evolution through 4G LTE densification and initial 5G Massive MIMO deployment anchored the projection framework across the analysis window. Segmentation dimensions modeled include structural type, radio technology generation, tenant category, and installation mode. CAGRs derived from tenancy growth curves, lease rate escalator patterns, and small cell deployment velocity assumptions. Forecast inputs incorporated ANFR spectrum allocation timelines and municipal zoning reform trajectories.
The model holds under sustained ARCEP infrastructure-sharing enforcement and stable steel input costs; deviation in electromagnetic field threshold tightening or geotechnical contractor capacity bottlenecks would shift deployment schedules and tenancy economics. Forecasts reflect documented assumptions about operator co-location willingness and municipal permitting velocity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Fixed-Line Communications Market
Telecommunications Infrastructure
OTN Equipment Market
Telecommunications Infrastructure
Microwave Backhaul System Market
Telecommunications Infrastructure
Panama Telecom Market
Telecommunications Infrastructure
Asia Pacific Voice Over LTE Market
Telecommunications Infrastructure
Brazil Telecom Tower Market
Telecommunications Infrastructure
Iraq Telecom Market
Telecommunications Infrastructure
Communication Repeater Market
Telecommunications Infrastructure
UAE Telecom Towers Market
Telecommunications Infrastructure
United States Telecom Towers Market
Telecommunications Infrastructure
South Korea Telecom Tower Market
Telecommunications Infrastructure
Broadcast Infrastructure Market
Telecommunications Infrastructure
Latin America Telecom Tower Market
Telecommunications Infrastructure
Global Cellular Networks Market
Telecommunications Infrastructure
Africa Telecom Towers and Allied Market
Telecommunications Infrastructure
Global Telecom Towers Market