
 Germany Telecom Towers Market | 2026-2036
Germany Telecom Towers Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Telecom Towers Market Insights
Site-sharing and colocation bundling is rebalancing procurement economics for German mobile operators. Deutsche Funkturm (GD Towers) leverages its spun-off infrastructure portfolio to anchor long-term tenancy agreements with legacy carriers. Vantage Towers AG competes through open-access models that sustain independent positioning against integrated operator-tower hybrids. American Tower Germany differentiates via standardized colocation interfaces that reduce tenant onboarding complexity.
Germany telecom towers are steel or concrete structures engineered to support multiple antenna arrays, transmission equipment, and power systems at heights typically ranging from 15 to 80 meters, designed for electromagnetic compliance and wind-load resistance. Their primary function is to host radio access network infrastructure for terrestrial wireless communication across licensed spectrum bands. Macro towers still dominate installed base value, though small cells and distributed antenna systems are capturing incremental growth in urban 5G NR densification corridors where fiber backhaul availability constrains deployment economics. Rooftop installations occupy a mature niche in dense city centers where greenfield tower permitting faces municipal resistance.
The Federal Network Agency (Bundesnetzagentur) enforces spectrum coverage obligations that directly mandate tower buildout timelines, while the Federal Emissions Control Act (BImSchG) governs site approval and environmental impact assessments for new structures. CE marking and DIN standards for structural integrity shape equipment procurement specifications and limit vendor pools to certified suppliers. Stakeholders must monitor how the EU Green Deal's embodied carbon reporting requirements and Germany's accelerating renewable energy siting conflicts reshape tower construction material choices and permitting durations.
Market Dynamics
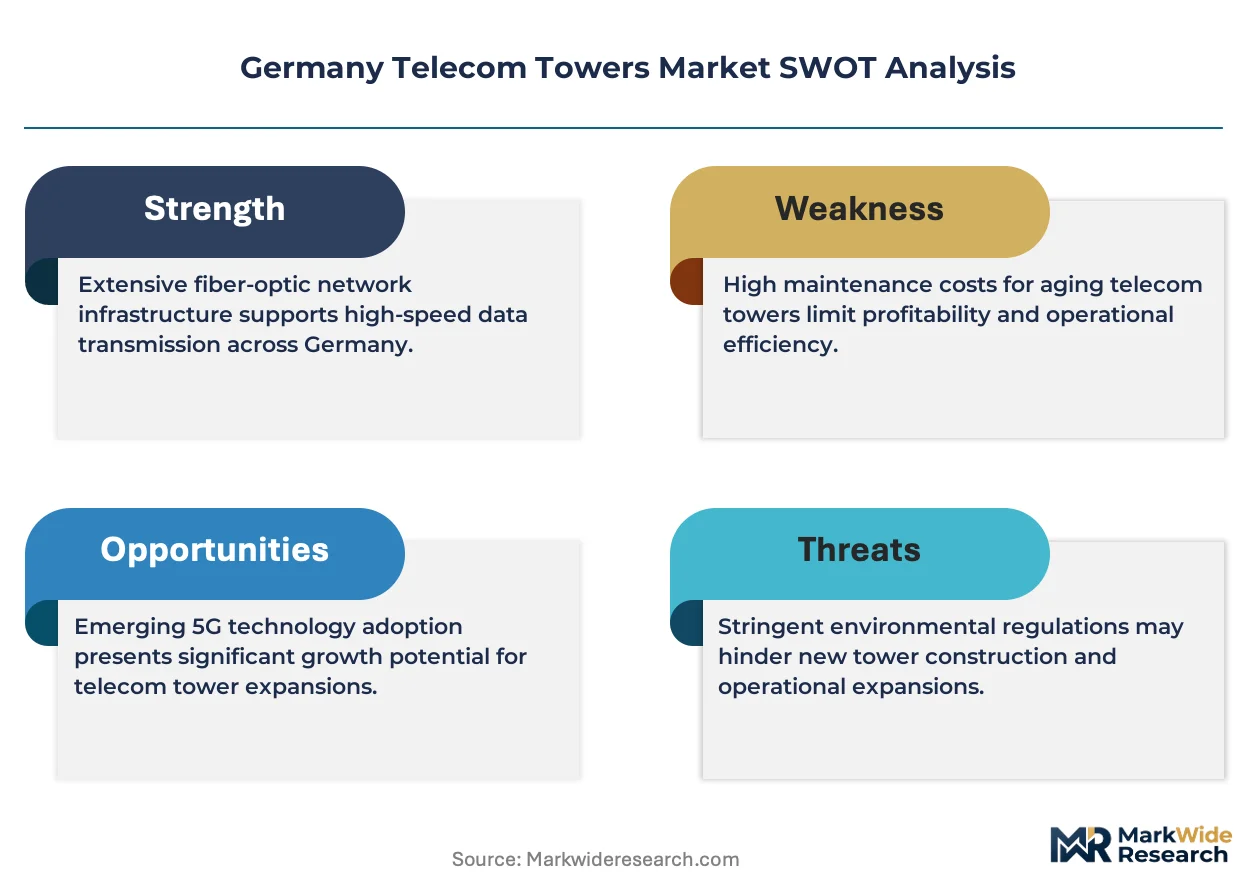
The Federal Network Agency's 5G coverage mandates are compressing buildout timelines while forcing operators toward shared infrastructure models that reshape capital deployment patterns across Germany's federal states.
Growth Catalysts
- 5G NR Densification Mandates:The Federal Network Agency's spectrum auction obligations require rapid macro tower and small cell deployment in underserved municipalities, accelerating tenancy demand.
- Industrial Enterprise Connectivity:Manufacturing clusters in Bavaria and Baden-Württemberg require ultra-reliable low-latency links that drive private network colocation on existing tower assets.
- Open RAN Architecture:Disaggregated radio access networks enable multi-vendor equipment stacking on single structures, improving space utilization economics for tower operators.
Market Restraints
- Steel Price Volatility:Fluctuations in hot-rolled steel coil costs directly impact lattice tower fabrication budgets and project IRR calculations.
- Municipal Permitting Friction:The Federal Emissions Control Act's environmental impact assessment requirements extend greenfield site approval timelines by 18-24 months in dense urban districts.
- Fiber Backhaul Constraints:Limited dark fiber availability in eastern federal states restricts small cell deployment economics regardless of radio equipment readiness.
Strategic Opportunities
- Rural Coverage Obligations:The Federal Network Agency's universal service mandates create tenancy guarantees for towers serving sub-1,000 inhabitant communities in Mecklenburg-Vorpommern and Saxony-Anhalt.
- Edge Computing Integration:Tower-mounted micro data centers hosting MEC nodes attract hyperscale cloud providers seeking distributed compute real estate.
- Renewable Energy Siting Synergies:Wind turbine tower-sharing agreements allow telecom equipment co-location on existing renewable structures, bypassing standalone permitting hurdles.
Industry Challenges
- RF Engineering Talent Scarcity:Electromagnetic compliance specialists with DIN-standard certification command premium compensation, constraining tower operator technical staffing.
- Legacy Equipment Decommissioning:3G infrastructure removal and 2G sunset coordination create site access scheduling conflicts that delay 5G overlay installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Telecom Towers Market |
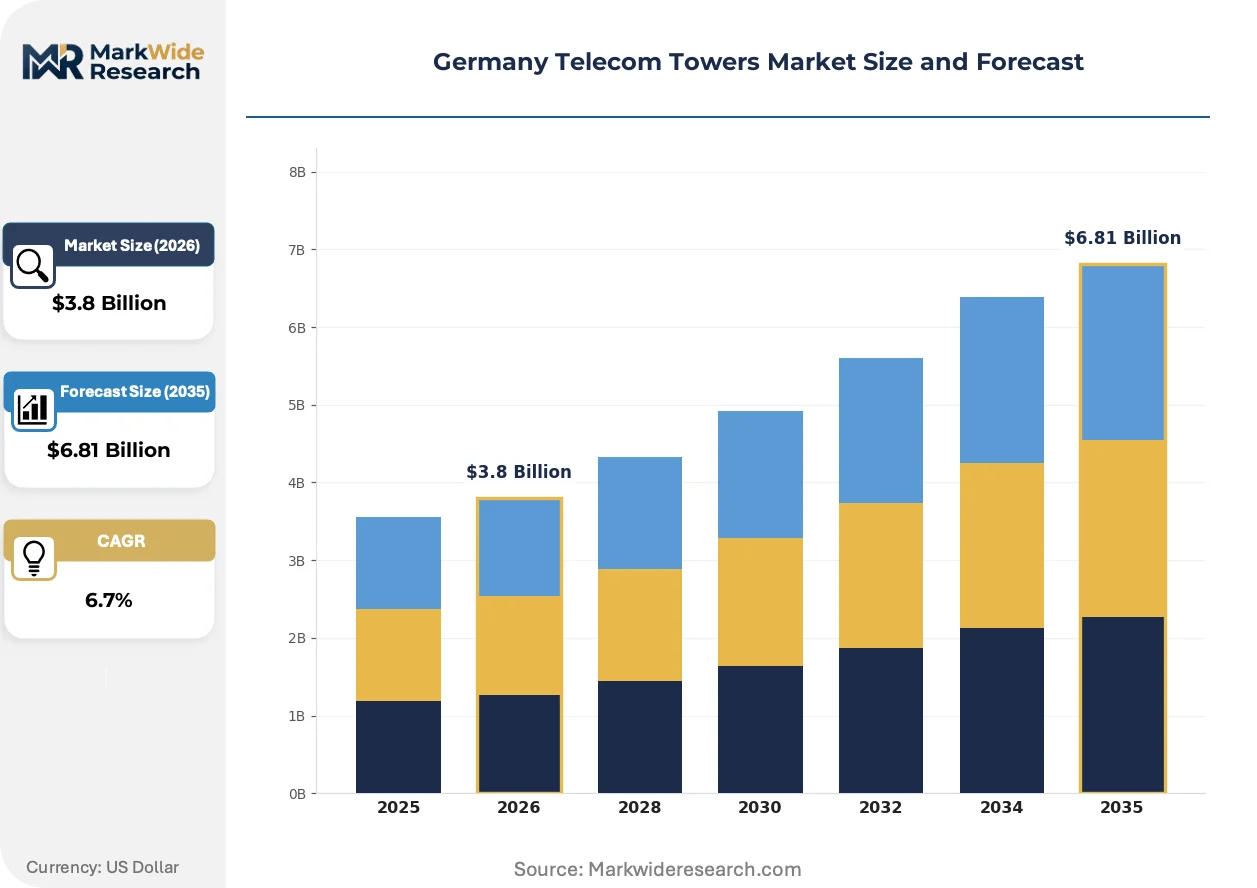
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Macro Towers, Small Cells, Distributed Antenna Systems, Rooftops Technology: 4G LTE, 5G NR, Microwave, Fiber Optics Deployment: Urban, Suburban, Rural, Remote Locations End User: Mobile Operators, Internet Service Providers, Cloud Service Providers, Enterprises |
| Companies Covered | Deutsche Funkturm (GD Towers), Vantage Towers AG, American Tower Germany, Phoenix Tower International, Vodafone Germany, Deutsche Telekom, O2 Telefónica, Telefónica Germany, 1&1 Drillisch, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Telecom Towers Market Trends and Innovations
Active antenna systems and AI-driven energy management are compressing operational cost structures while enabling denser spectrum reuse across Germany's heterogeneous topography.
Massive MIMO arrays with 64T64R configurations are absorbing increasing shares of new macro site capital allocation. Mobile operators in North Rhine-Westphalia deploy these units to serve stadium and transport corridor capacity spikes. The technology is absorbing what previously required three separate single-band passive antenna installations, reducing tower loading and wind exposure profiles.
The EU Green Deal's embodied carbon reporting requirements are mandating lifecycle emissions disclosure for steel and concrete tower procurement. DIN standards committees are incorporating recycled content thresholds into structural certification protocols. Tower fabricators in Bavaria now source low-carbon steel from electric arc furnace mills to maintain eligibility for public sector tenancy contracts.
Enterprise buyers in automotive and logistics verticals are consolidating radio access network procurement under single managed service agreements rather than direct tower leases. System integrators capture margin previously retained by mobile network operators. This concentration is most visible in Baden-Württemberg's manufacturing belt, where private 5G network demand outpaces operator-led deployment capacity.
Germany Telecom Towers Market Segmentation
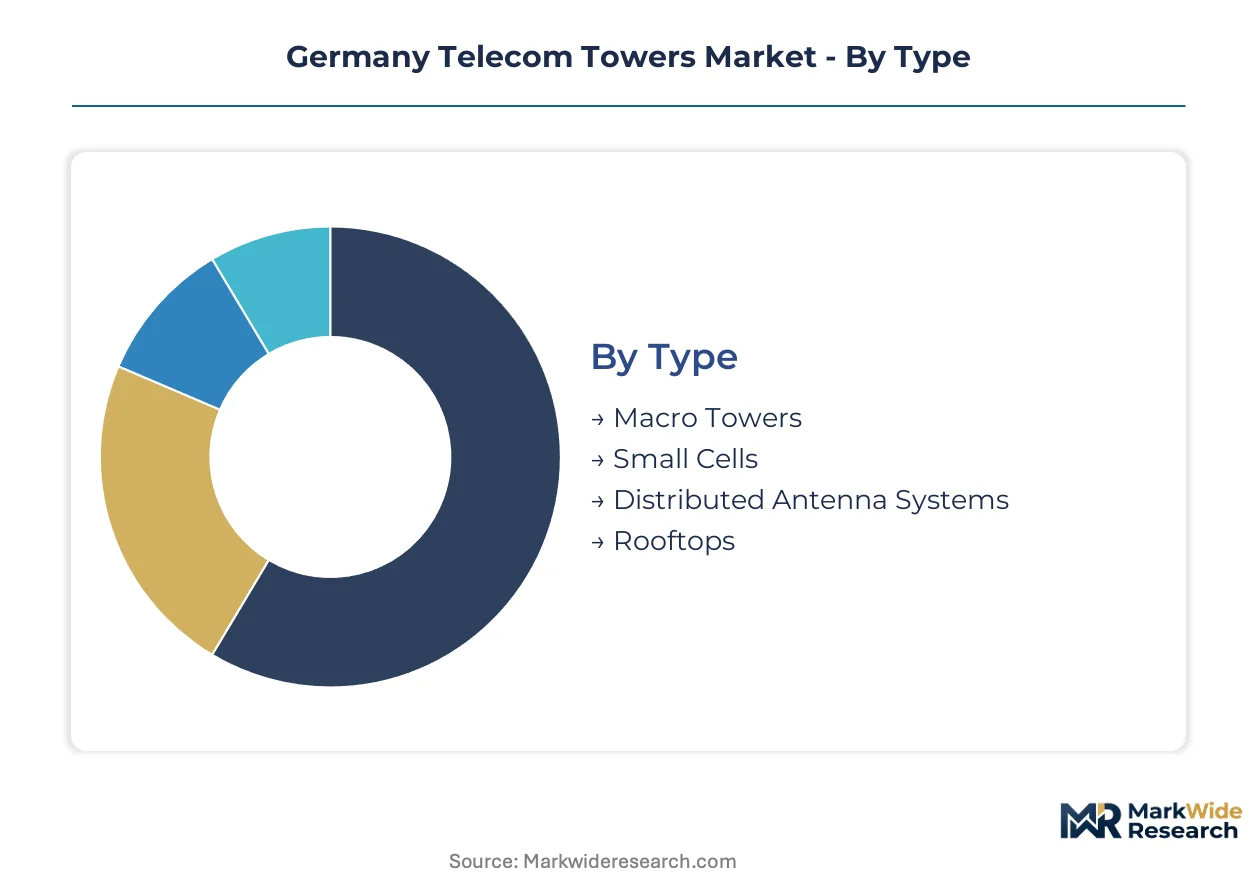
Structural variation across tower types, radio technologies, deployment geographies, and tenant categories creates distinct procurement economics and tenancy yield profiles for German infrastructure operators. Understanding these segment boundaries clarifies where capital deployment concentrates and where margin compression risks emerge.
Type:
Steel and concrete structures vary in height, load capacity, and colocation potential, creating tiered investment profiles across the German tower base.
- Macro Towers:Lattice or monopole structures ranging 30-80 meters support multi-tenant antenna arrays with 15-20kW power budgets. Bavaria and North Rhine-Westphalia concentrate demand where population density and industrial corridors overlap coverage priorities.
- Small Cells:Compact 6-15 meter pole-mounted units enable 5G NR densification in urban canyons and transport corridors. Frankfurt and Munich deployment timelines accelerate where fiber backhaul availability permits street-level installation economics.
- Distributed Antenna Systems:Indoor and tunnel coverage solutions extend signal penetration where macro propagation fails.
- Rooftops:Building-mounted installations bypass greenfield permitting in dense municipal centers.
Macro Towers leads on scale; Small Cells leads on momentum.
Technology:
Radio access generation and backhaul modality determine equipment refresh cycles and tenancy stacking potential across German federal states.
- 5G NR:New radio interfaces in sub-6GHz and mmWave bands enable massive MIMO configurations that triple spectral efficiency over 4G predecessors. The Federal Network Agency's coverage mandates accelerate deployment in Mecklenburg-Vorpommern and Saxony-Anhalt where legacy infrastructure gaps persist.
- 4G LTE:Mature macro layer technology sustains capacity in suburban rings while operators prioritize 5G overlay investments in core revenue zones.
- Microwave:Point-to-point backhaul links serve remote sites where fiber trenching costs prohibit fixed-line connectivity.
- Fiber Optics:Dark fiber and wavelength services anchor small cell economics in urban 5G densification corridors.
4G LTE retains tenancy volume; 5G NR commands capital allocation priority.
Deployment:
Geographic density gradients shape permitting complexity, backhaul availability, and revenue per site across Germany's heterogeneous topography.
- Urban:Dense city centers in Berlin, Hamburg, and Cologne concentrate rooftop and small cell deployment where macro greenfield options face municipal resistance and visual impact restrictions.
- Suburban:Ring municipalities around major metros balance coverage obligation fulfillment with higher tenancy yields than rural equivalents.
- Rural:Sub-1,000 inhabitant communities in eastern federal states trigger universal service mandate guarantees that de-risk tower operator investment.
- Remote Locations:Forest and alpine zones require specialized structural engineering for wind-load compliance.
Urban sites maximize revenue density; Rural deployments expand under regulatory obligation frameworks.
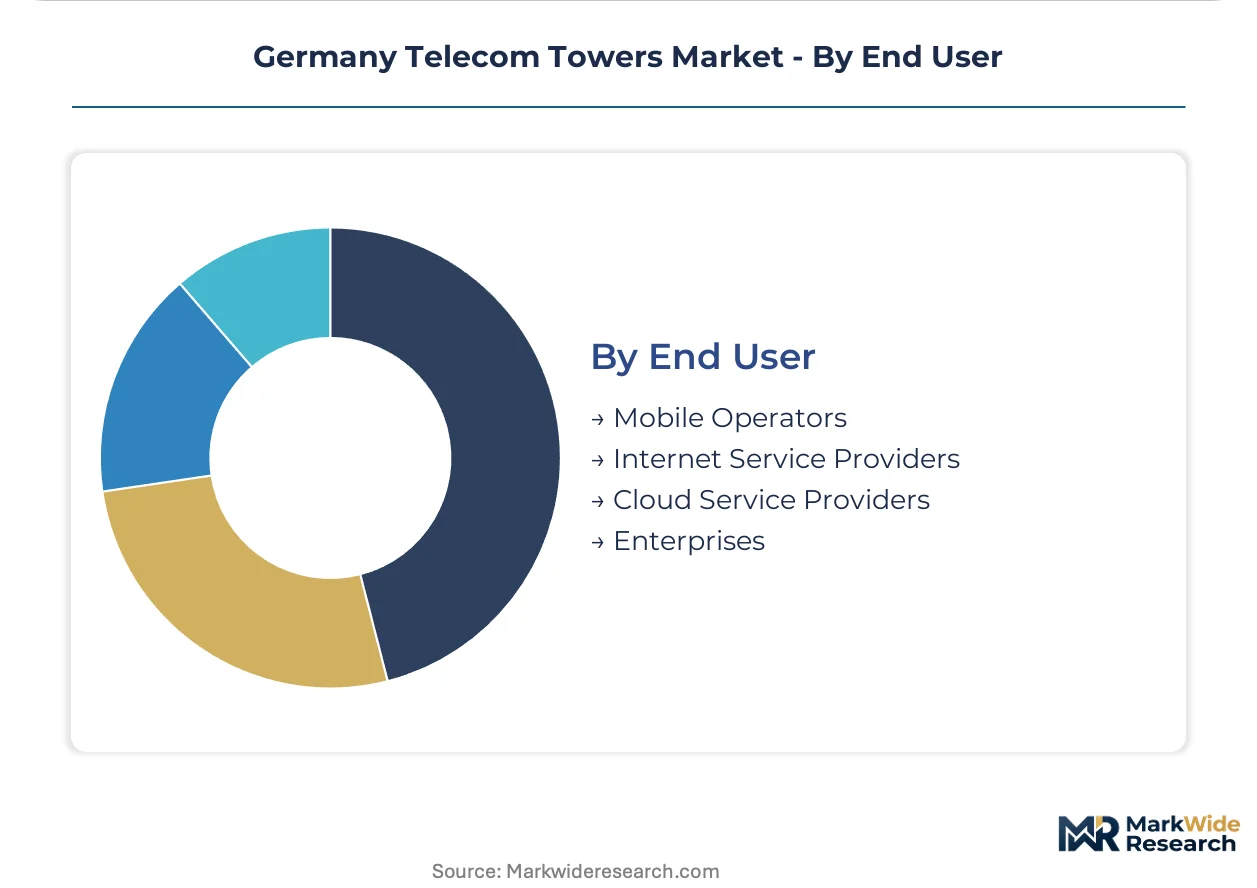
End User:
Tenant category diversity determines contract duration, credit risk profiles, and service-level agreement complexity for tower operators.
- Mobile Operators:Deutsche Telekom, Vodafone, and Telefónica Deutschland anchor long-term tenancy agreements with 10-15 year lease structures and inflation-linked escalators.
- Enterprises:Automotive and logistics verticals in Baden-Württemberg procure private 5G network hosting through managed service intermediaries rather than direct tower contracts.
- Internet Service Providers:Fixed wireless access providers lease tower space to bypass last-mile copper infrastructure limitations.
- Cloud Service Providers:Hyperscalers seek edge computing real estate for MEC node colocation on tower-mounted micro data centers.
Mobile Operators anchor tenancy volume; Cloud Service Providers represent the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's telecom tower infrastructure traces its modern scaling to Deutsche Telekom's post-reunification network buildout in the 1990s, establishing the federal state system that still governs site deployment patterns today.
Bavaria
Automotive manufacturing clusters around Munich and Ingolstadt drive private 5G network demand for ultra-reliable low-latency connectivity. The Federal Network Agency's coverage mandates accelerate rural buildout in Upper Bavaria's sub-1,000 inhabitant communities. Munich anchors small cell densification corridors where fiber backhaul availability permits street-level 5G NR deployment.
North Rhine-Westphalia
Industrial enterprise connectivity requirements in the Ruhr Valley overlap with dense population corridors to create multi-tenant tower demand. DIN standards for structural integrity govern steel procurement specifications for lattice tower fabrication across the state. Cologne and Düsseldorf concentrate rooftop installations where greenfield macro tower permitting faces municipal resistance.
Baden-Württemberg
Precision engineering clusters in Stuttgart and Mannheim require private network colocation on existing tower assets for manufacturing automation. The Federal Emissions Control Act extends environmental impact assessment timelines for new structures in the Black Forest conservation zones. Karlsruhe's transport corridor hosts massive MIMO deployments serving highway capacity spikes.
Lower Saxony
Wind energy siting synergies enable telecom equipment co-location on existing renewable structures across the North German Plain. Universal service mandates de-risk tower operator investment in rural communities below 1,000 inhabitants. Hanover's suburban ring balances coverage obligation fulfillment with higher tenancy yields than eastern equivalents.
Hesse
Frankfurt's financial district drives edge computing integration demand for tower-mounted micro data centers hosting MEC nodes. The EU Green Deal's embodied carbon reporting requirements mandate lifecycle emissions disclosure for steel tower procurement in the Rhine-Main metropolitan region. Wiesbaden and Darmstadt exhibit accelerated small cell deployment where fiber backhaul economics permit.
Germany Telecom Towers Market Competitive Landscape
Premium-margin players sit above commodity-margin players across tenancy duration and colocation stacking depth, with integrated operator-tower hybrids commanding structural advantages in legacy site access. The vendor base organizes around three archetypes: spun-off infrastructure portfolios anchoring long-term carrier relationships, open-access specialists sustaining independent positioning, and international platforms standardizing tenant onboarding interfaces. Scale-driven consolidation and vertical integration into power systems represent the dominant competitive vectors reshaping procurement economics.
Among Germany-based infrastructure operators, Deutsche Funkturm (GD Towers) occupies the spun-off portfolio archetype following its separation from Deutsche Telekom's wireless operations. Vantage Towers AG exemplifies the open-access model competing against integrated hybrids. American Tower Germany represents international platform standardization, leveraging parent-company colocation interface protocols to reduce tenant onboarding friction across its federal state footprint.
| Leading Market Players |
|---|
| Deutsche Funkturm (GD Towers) |
| Vantage Towers AG |
| American Tower Germany |
| Phoenix Tower International |
| Vodafone Germany |
| Deutsche Telekom |
| O2 Telefónica |
| Telefónica Germany |
| 1&1 Drillisch |
| Others |
Pricing and Supply Chain Analysis
Mobile operator procurement concentration in Germany's three-carrier oligarchy anchors long-term tenancy contracting with inflation-linked escalators rather than spot-market volatility. Deutsche Telekom, Vodafone, and Telefónica Deutschland negotiate master lease agreements that bundle colocation access across federal states, compressing price discovery into bilateral frameworks insulated from commodity tower markets.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels governs German tower tenancy, with premium tiers commanding structural certification under DIN standards and CE marking compliance. Price differentiation separates Bavarian industrial corridors with private 5G hosting requirements from rural coverage obligation sites in eastern federal states. Cost compression in standard-tier macro tower segments is intensifying because American Tower Germany and Vantage Towers AG compete on standardized colocation interfaces. Rural universal service mandate sites exhibit highest price sensitivity due to regulatory tenancy guarantees, while Frankfurt and Munich edge computing colocation shows lowest sensitivity.
Supply Chain Analysis
EU Green Deal embodied carbon reporting requirements and Germany's accelerating renewable energy siting conflicts are reshaping domestic-content mandates for steel tower procurement. Lattice tower fabrication draws from German electric arc furnace mills, Polish rolling facilities, and Chinese structural steel exporters. Hot-rolled steel coil, aluminum antenna housings, and fiber optic backhaul cables constitute critical input dependencies. Single-source vulnerability concentrates in low-carbon steel certification compliant with DIN structural integrity protocols. Distribution runs through tower operator direct procurement teams and specialized telecom infrastructure EPC contractors serving federal state deployment timelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Germany's telecom towers market compounds steadily as Federal Network Agency 5G coverage mandates enforce structural demand visibility across the projection horizon.
For Market Incumbents: Anticipate margin compression from open-access competitors by deepening tenancy stacking through active antenna system upgrades that expand colocation capacity per site. Secure long-term steel supply agreements with DIN-certified electric arc furnace mills before EU Green Deal carbon border adjustments tighten. Vertical integration into tower-mounted micro data center power systems represents a defensible moat against hyperscale cloud provider bypass strategies. For New Entrants and Emerging Players: The premium-economy price-point gap in rural universal service obligation sites creates entry opportunity for specialized operators willing to accept regulatory tenancy guarantees in Mecklenburg-Vorpommern and Saxony-Anhalt. Target wind turbine tower-sharing agreements in Lower Saxony's North German Plain to bypass standalone permitting hurdles. Go-to-market through managed service intermediaries serving Baden-Württemberg automotive private 5G networks rather than direct carrier contracting. For Investors and Strategic Acquirers: Hyperscale cloud providers seeking edge computing real estate are the most active acquirer in this space, driving valuation premiums for tower portfolios with Frankfurt and Munich MEC node deployment permits. Mid-scale operators with 500-2,000 site footprints and renewable energy siting synergies represent the most logical acquisition target archetype. Watch Federal Network Agency rural coverage mandate enforcement intensity as the signal indicating tenancy guarantee durability versus regulatory forbearance risk.| Strategic Initiative | Industry Significance |
|---|---|
| Tenancy Stacking Optimization | Massive MIMO deployments in North Rhine-Westphalia triple spectral efficiency per tower loading unit. |
| Renewable Energy Siting Synergies | Wind turbine co-location agreements in Lower Saxony bypass 18-24 month standalone permitting timelines. |
| Edge Computing Integration | Tower-mounted micro data centers hosting MEC nodes attract AWS and Microsoft Azure distributed compute procurement. |
| Low-Carbon Steel Certification | DIN standards compliance with EU Green Deal thresholds maintains eligibility for public sector tenancy contracts. |
| Open RAN Architecture Deployment | Disaggregated radio access networks enable multi-vendor equipment stacking that improves space utilization economics. |
Research Methodology
Bottom-up mobile operator tenancy modeling reconciled against top-down tower operator site tracking forms the analytical core of this study. Primary interviews with Deutsche Funkturm network deployment directors, Vantage Towers AG colocation sales leads, Federal Network Agency spectrum policy officers, Bavarian automotive plant connectivity managers, and DIN standards committee engineers combined with secondary validation. Secondary sources encompassed Bundesnetzagentur auction documentation, EU Green Deal regulatory filings, CE marking certification databases, and federal state environmental impact assessment records. Triangulation across these sources anchored installed base estimates and tenancy yield projections.
Input-output matrices mapped radio access generation deployment timelines against structural type capacity constraints across the projection horizon. Segmentation dimensions modeled include tower type, radio technology generation, deployment geography density gradient, and tenant category credit risk profile. CAGRs derived from tenancy growth run rates applied to per-site revenue yields, with Federal Network Agency coverage mandate enforcement schedules and fiber backhaul availability curves as industry-specific forecast inputs.
The model assumes a particular 5G NR densification technology adoption path; alternative pathways for Open RAN architecture deployment or satellite backhaul substitution would alter the outlook. Forecasts reflect assumptions regarding steel price volatility, municipal permitting friction, and electromagnetic compliance specialist labor availability. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
China Telecom Towers Market
Telecommunications Infrastructure
United Kingdom Telecom Towers Market
Telecommunications Infrastructure
Slovenia Telecom Market
Telecommunications Infrastructure
Panama Telecom Market
Telecommunications Infrastructure
Europe 5G Infrastructure Market
Telecommunications Infrastructure
5G Infrastructure Equipment Market
Telecommunications Infrastructure
Fiber to the X (FTTX) Market
Telecommunications Infrastructure
OTN Equipment Market
Telecommunications Infrastructure
China Telecom Equipment Market
Telecommunications Infrastructure
Small Cell Backhaul Market
Telecommunications Infrastructure
UAE Telecom Towers Market
Telecommunications Infrastructure
Global Telecom Towers Market
Telecommunications Infrastructure
Global Telecom System Integration Market
Telecommunications Infrastructure
South Korea Telecom Tower Market
Telecommunications Infrastructure
Global Integrated Telecom Infrastructure Market
Telecommunications Infrastructure
Brazil Telecom Tower Market