
 US Enterprise Legal Management Software Market | 2026-2036
US Enterprise Legal Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
US Enterprise Legal Management Software Market Analytics
API-first architecture is repositioning legacy enterprise legal management stacks toward composable platforms. Onit leverages its workflow automation engine to anchor complex legal operations for Global 2000 clients. Thomson Reuters Legal Tracker sustains dominance in spend management through deep integration with its broader information services ecosystem. Brightflag differentiates via AI-driven invoice review that reduces outside counsel billing leakage.
Enterprise legal management software encompasses integrated technology platforms that govern corporate legal workflows including matter lifecycle tracking, vendor engagement, spend analytics, and regulatory document control, typically deployed through REST APIs and role-based access protocols with SOC 2 Type II certification requirements. The primary commercial purpose centers on reducing total legal spend while enforcing compliance mandates across distributed legal departments. Contract management and e-billing currently occupy the largest margin pools as corporations prioritize spend visibility and obligation tracking amid vendor proliferation. Cloud-based and SaaS deployment models represent the fastest-expanding configuration as IT security teams relax on-premises requirements for non-privileged operational data.
The SEC, state bar ethics committees, and HIPAA oversight entities collectively shape product roadmaps through disclosure timelines, client confidentiality rules, and healthcare data handling protocols that mandate immutable audit logs. Sarbanes-Oxley retention standards and emerging state privacy laws in California and Virginia further harden requirements for document lineage and access controls. Stakeholders must weigh interoperability investments against the risk of vendor lock-in as platform consolidation accelerates among mid-market buyers.
Market Dynamics
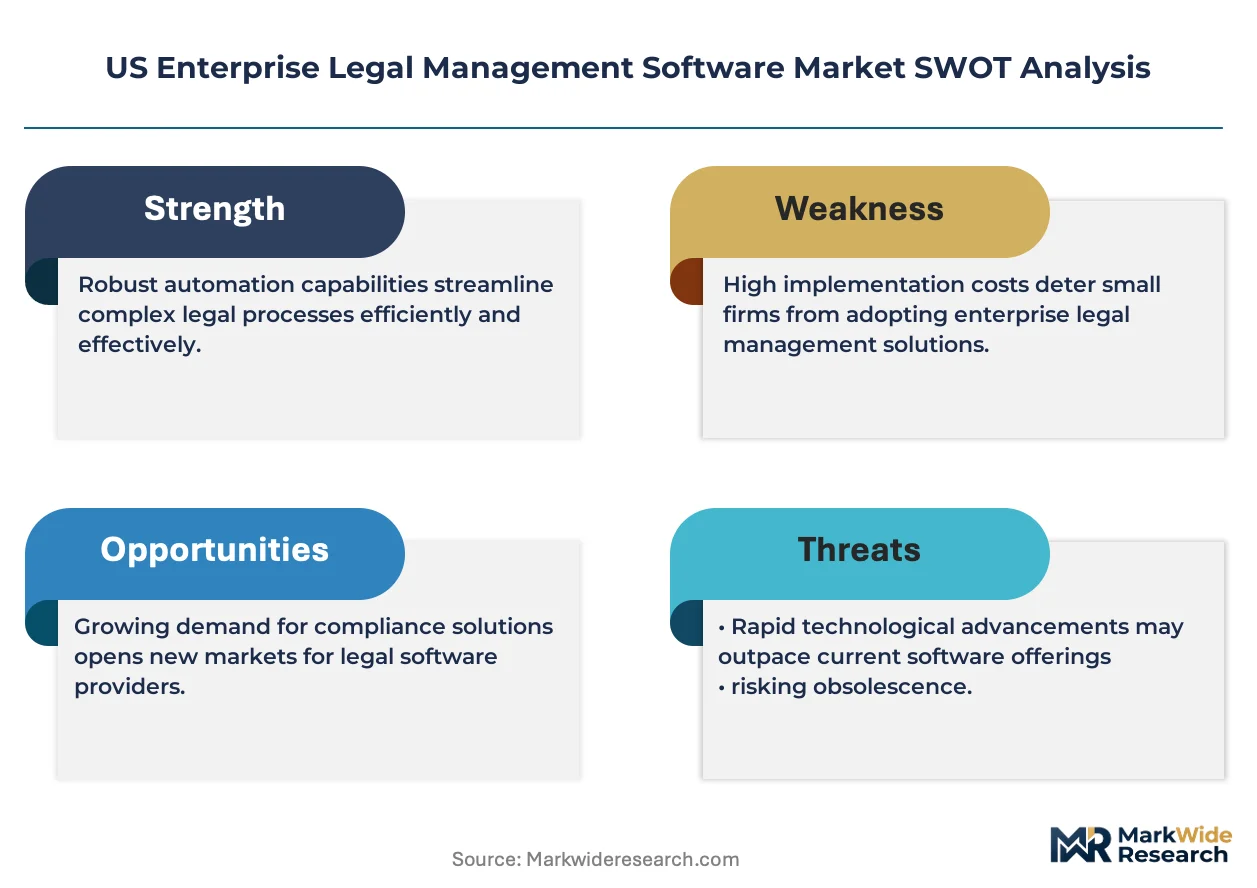
SEC climate disclosure mandates and cybersecurity incident reporting rules are forcing Fortune 500 legal departments to replace fragmented point solutions with unified audit-trail platforms. This regulatory compression is electrifying demand for API-native architectures that can ingest multi-source compliance data without custom integration layers.
Growth Catalysts
- SEC Cybersecurity Disclosure Rules:Public companies must now report material cybersecurity incidents within four business days, requiring automated legal hold and incident response workflows that legacy email-based systems cannot execute.
- Pharmaceutical headquarters clusters:Dense concentrations of life sciences legal operations in New Jersey and New York generate concentrated demand for HIPAA-compliant matter management with immutable document lineage.
- API-first platform architecture:REST-based integration protocols enable legal departments to embed spend analytics and contract lifecycle management directly into enterprise ERP systems without middleware bottlenecks.
Market Restraints
- Implementation cost structure:Mid-market legal departments face six-figure minimum commitments for SOC 2 Type II certified deployments, creating a floor that excludes organizations below 50-person legal teams.
- Cloud security clearance friction:Financial services firms in New York must navigate NYDFS cybersecurity regulations that impose additional encryption and access-log requirements beyond standard SaaS certifications.
- Legacy system entrenchment:Decades of on-premises document management investment in SharePoint and OpenText repositories creates data migration complexity that prolongs replacement cycles.
Strategic Opportunities
- State privacy law fragmentation:Virginia CDPA and California CPRA create divergent compliance obligations that legal operations platforms can productize into automated jurisdiction-specific workflows.
- AI-native invoice review:Machine learning models trained on historical billing data can flag guideline violations before payment authorization, capturing leakage that rules-based systems miss.
- Alternative legal service provider integration:Managed legal service vendors and contract attorney staffing platforms represent an underconnected channel for matter management distribution.
Industry Challenges
- Legal operations talent scarcity:Hybrid professionals who combine law firm practice experience with Salesforce or Tableau administration skills command premium compensation that stretches department budgets.
- Multi-jurisdiction privilege preservation:Cross-border matter collaboration requires threading state bar ethics rules that differ on client confidentiality in cloud environments, complicating single-tenant architecture decisions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Enterprise Legal Management Software Market |
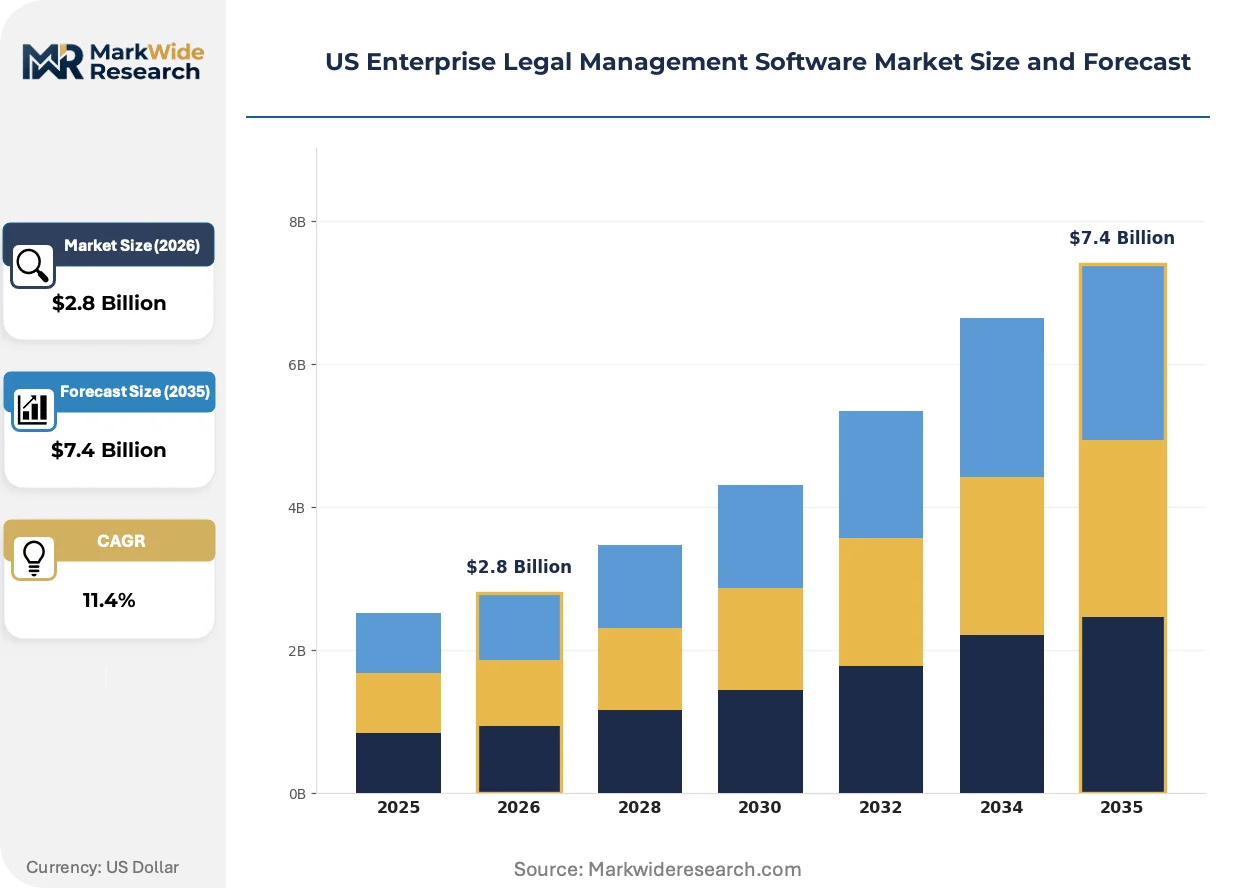
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Document Management, Contract Management, E-Billing, Case Management Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Corporations, Compliance Departments, Law Firms, Government Agencies Pricing Model: Subscription-Based, One-Time License, Freemium, Pay-As-You-Go |
| Companies Covered | Onit, Ascent ELM, Thomson Reuters Legal Tracker, Fulcrum GT, Everlaw, Brightflag, Litify, iManage, Relativity, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Enterprise Legal Management Software Market Evolving Landscape
Generative AI is compressing document review timelines while regulatory pressure hardens data residency requirements. These forces are pulling legal technology stacks toward modular, jurisdiction-aware platforms.
Large language models trained on legal billing narratives and contract clause libraries are electrifying the extraction of structured data from unstructured legal documents. Corporate legal departments in financial services are deploying these tools for real-time outside counsel spend classification. The technology is electrifying competitive positioning by collapsing the analyst hours previously required for manual invoice line-item review.
The SEC's expanded climate disclosure framework under the 2024 final rules requires legal departments to coordinate sustainability attestations with financial reporting controls. This regulatory compression is mandating immutable audit trails that link climate risk assessments to board deliberation records. Pharmaceutical and energy sector legal teams in Houston and New York are rebuilding document retention architectures to satisfy these lineage requirements.
General counsel offices are consolidating vendor relationships from an average of seven point solutions to two or three integrated platforms. This buyer concentration is compressing procurement cycles for standalone e-billing or contract management tools. The pattern is most visible among Fortune 500 manufacturers with distributed legal operations across multiple state jurisdictions.
US Enterprise Legal Management Software Market Segmentation
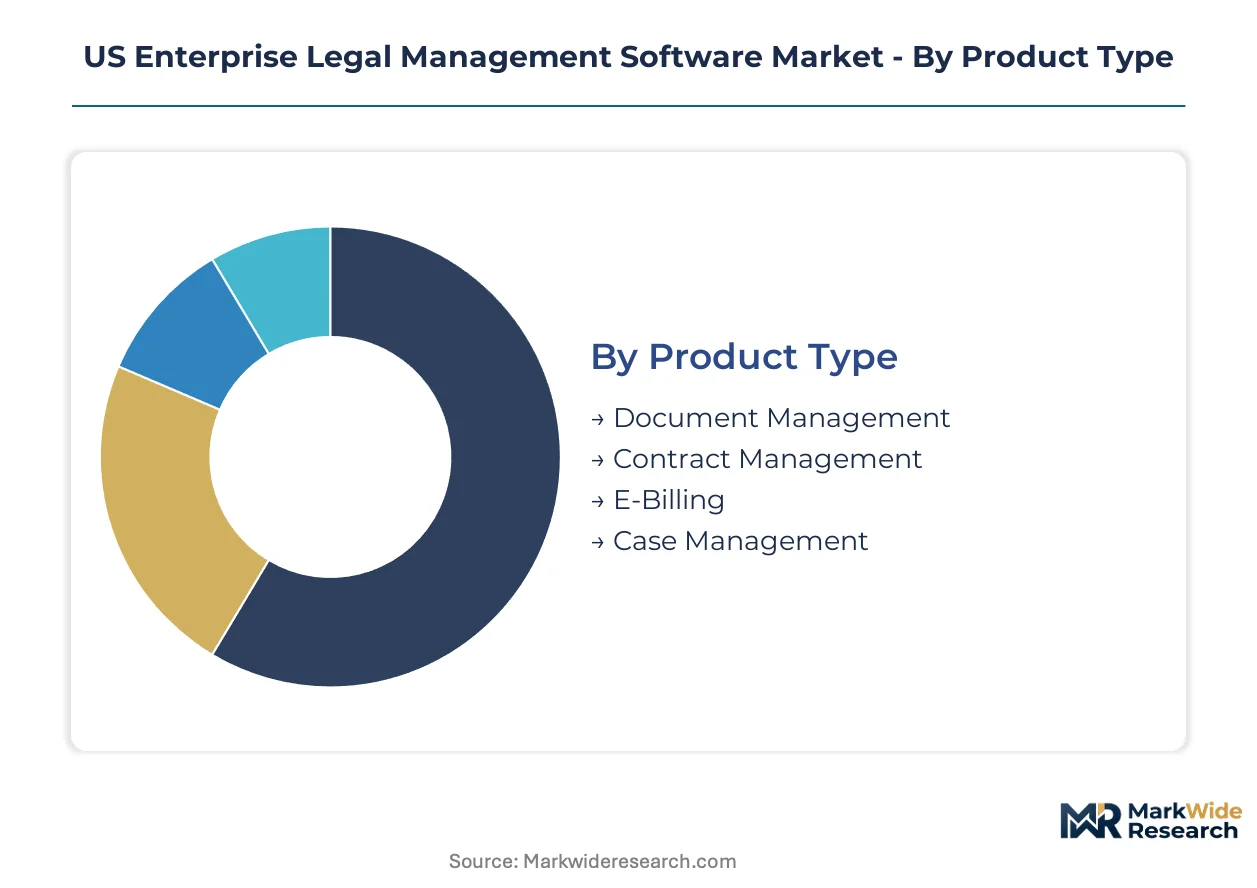
Segmentation reveals how vendor specialization aligns with divergent compliance burdens and IT security postures across the US legal technology landscape. Procurement patterns vary sharply between regulated financial institutions requiring on-premises control and mid-market corporations prioritizing SaaS agility.
Product Type:
Supply concentration clusters around modules that directly reduce outside counsel spend or satisfy SEC audit requirements.
- E-Billing:Platforms ingest law firm invoices through standardized LEDES formats, applying automated guideline enforcement that flags block billing and excess staffing before payment authorization. Fortune 500 legal operations in New York and New Jersey deploy these tools to compress the 45-60 day invoice review cycle to under 10 days. Demand concentrates among financial services and pharmaceutical headquarters seeking to stem the 8-12% billing leakage that manual review misses.
- Contract Management:Systems govern obligation extraction, renewal alerts, and clause standardization across procurement and sales agreements. Life sciences legal departments in New Jersey leverage these platforms to track HIPAA business associate agreements and FDA commitment letters with immutable version control. The segment captures margin from integration complexity—connecting contract data to ERP systems requires professional services engagements that extend customer lifetime value.
- Document Management:Repositories with role-based access and legal hold capabilities preserve privilege while enabling cross-border collaboration. Federal contractors and government agencies mandate FedRAMP-authorized deployments that extend sales cycles.
- Case Management:Workflow engines track litigation milestones, discovery deadlines, and settlement authority with matter-centric document organization. Regional law firms and corporate litigation departments drive adoption where docket volume exceeds 50 active matters.
Today's leader: E-Billing. Tomorrow's challenger: Contract Management.
Deployment:
IT security clearance requirements fragment procurement between regulated industries and unregulated mid-market buyers.
- Cloud-Based:Multi-tenant architectures with SOC 2 Type II certification enable rapid provisioning for legal departments under 50 attorneys. SaaS deployments among technology and manufacturing corporations in California and Texas bypass capital expenditure approval processes that delay on-premises projects.
- SaaS:Subscription delivery with API-native integration protocols allows embedding of spend analytics directly into Salesforce or Workday environments without middleware. Financial services firms in New York face NYDFS cybersecurity regulations that impose additional encryption and access-log requirements beyond standard certifications.
- On-Premises:Single-tenant installations satisfy data residency mandates for classified government legal work and certain pharmaceutical intellectual property protection. Implementation timelines stretch 12-18 months with seven-figure total cost of ownership.
- Hybrid:Configurations segregate privileged matter data on-premises while routing operational analytics to cloud infrastructure. Large manufacturers with distributed legal operations across multiple state jurisdictions adopt this model to balance compliance with cost efficiency.
Cloud-Based deployments are expanding most quickly as IT security teams relax requirements for non-privileged operational data. On-Premises retains defensive moats in federal and defense contractor segments.
End User:
Buyer sophistication and procurement authority reshape solution packaging across organizational types.
- Corporations:Fortune 500 legal departments with 50+ attorneys drive demand for integrated platforms spanning matter management, e-billing, and contract lifecycle. SEC climate disclosure mandates force these buyers to prioritize audit trail completeness over point solution depth.
- Compliance Departments:Cross-functional teams spanning legal, finance, and sustainability require jurisdiction-aware workflows that automate Virginia CDPA and California CPRA obligation tracking. These buyers prioritize regulatory content libraries over traditional legal operations functionality.
- Law Firms:AmLaw 200 firms and regional practices purchase client-matter collaboration tools and time entry systems that interface with corporate client e-billing portals. Pricing pressure from corporate legal departments compresses technology budgets.
- Government Agencies:Federal, state, and municipal legal offices mandate FedRAMP or StateRAMP authorization, creating procurement barriers that favor established vendors with existing compliance infrastructure.
Corporations command platform roadmap prioritization through volume commitments. Compliance Departments represent the steepest expansion trajectory as regulatory fragmentation multiplies.
Pricing Model:
Revenue predictability and customer acquisition cost trade-offs shape vendor packaging strategies.
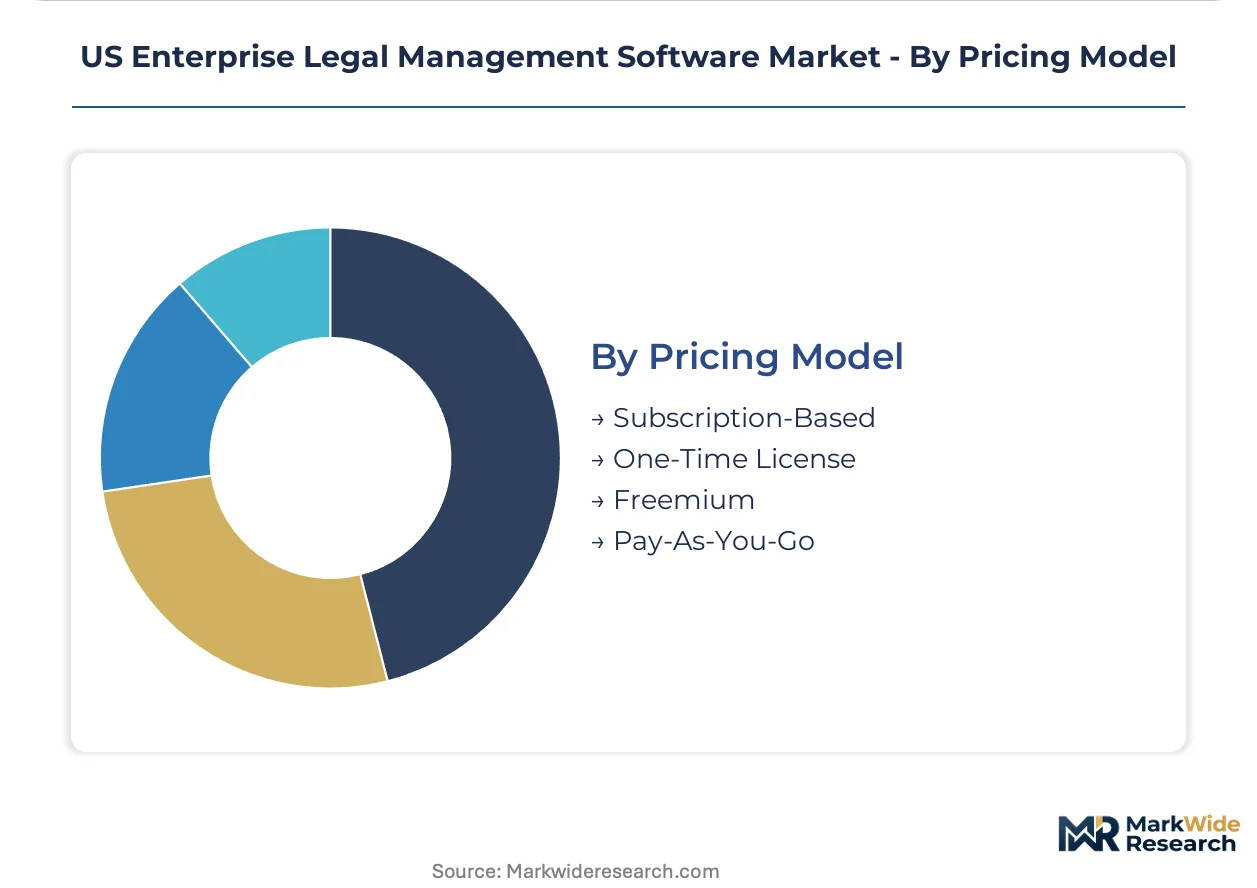
- Subscription-Based:Annual or multi-year contracts with per-user or per-matter pricing provide recurring revenue visibility that supports R&D investment. Enterprise legal management vendors anchor customer relationships through three-year commitments with annual escalation clauses.
- One-Time License:Perpetual rights with annual maintenance fees persist in government and highly regulated segments where capital budgeting processes favor depreciation schedules. This model concentrates among on-premises deployments with professional services dependencies.
- Freemium:Limited-feature entry tiers with matter or user caps convert solo practitioners and small law firms to paid tiers for advanced analytics or integration capabilities. Customer acquisition costs challenge unit economics at scale.
- Pay-As-You-Go:Consumption pricing tied to invoice volume processed or documents analyzed aligns vendor success with customer value realization. Mid-market legal departments with variable outside counsel spend favor this flexibility.
Subscription-Based pricing dominates vendor preference for revenue predictability. Pay-As-You-Go gains share fastest among cost-conscious mid-market buyers seeking to align technology spend with legal matter volume.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Northeast Corridor anchors US demand for enterprise legal management software, driven by overlapping financial services and pharmaceutical headquarters clusters that face intensifying SEC disclosure mandates.
Northeast Corridor
Financial services legal departments in Manhattan and life sciences operations in New Jersey drive concentrated platform adoption. NYDFS cybersecurity regulations impose encryption and access-log requirements beyond standard SaaS certifications. Pharmaceutical headquarters in Bridgewater and Princeton are rebuilding document retention architectures to satisfy immutable audit trail mandates under SEC climate rules.
California
Technology corporations and venture-backed legal operations prioritize API-native deployments that embed spend analytics into existing ERP ecosystems. The California Privacy Rights Act creates automated jurisdiction-specific workflow demand that vendors are productizing. San Francisco Bay Area legal departments lead cloud-first adoption as IT security teams relax on-premises requirements for non-privileged operational data.
Texas
Energy sector legal teams in Houston face SEC climate disclosure coordination requirements that link sustainability attestations to board deliberation records. The state's business-friendly regulatory environment accelerates SaaS procurement cycles compared to coastal counterparts. Dallas-Fort Worth manufacturing legal operations are consolidating vendor relationships from seven point solutions to two or three integrated platforms.
Illinois
Midwest manufacturing headquarters and agricultural conglomerates drive mid-market demand for subscription-based matter management. Chicago-based legal departments balance cost efficiency against SOC 2 Type II certification requirements that create six-figure implementation floors. The region shows growing interest in pay-as-you-go pricing models that align technology spend with variable outside counsel volume.
Washington
Pacific Northwest technology giants and aerospace contractors mandate FedRAMP-authorized deployments that extend sales cycles and favor established vendors. Seattle legal operations prioritize hybrid configurations that segregate privileged matter data on-premises while routing operational analytics to cloud infrastructure. The state's emerging privacy legislation parallels California and Virginia frameworks, creating multi-jurisdiction compliance automation opportunities.
US Enterprise Legal Management Software Market Competitive Landscape
Global majors compete with regional champions across integration depth and regulatory specialization, producing a tiered structure where scale-driven information services conglomerates anchor the premium segment while workflow automation specialists capture mid-market share. The vendor landscape organizes around three archetypes: information services ecosystems with embedded legal modules, pure-play legal operations platforms with API-first architectures, and litigation-focused document management specialists. Competitive dynamics center on M&A consolidation to broaden platform scope and strategic partnerships that embed legal workflows into enterprise ERP systems without middleware friction.
Within the workflow automation tier, Onit and Brightflag exemplify API-native positioning that reduces outside counsel billing leakage through automated guideline enforcement. Thomson Reuters Legal Tracker anchors the information services ecosystem archetype, leveraging deep integration with broader research and analytics infrastructure. These three companies represent divergent strategic bets on whether legal operations platforms succeed as standalone best-of-breed solutions or as embedded modules within larger enterprise software stacks.
| Leading Market Players |
|---|
| Onit |
| Ascent ELM |
| Thomson Reuters Legal Tracker |
| Fulcrum GT |
| Everlaw |
| Brightflag |
| Litify |
| iManage |
| Relativity |
| Others |
Value Network & Pricing Analysis
Hybrid legal-technology professionals concentrated in the Northeast corridor command compensation premiums that compress pricing spreads between enterprise and mid-market SaaS tiers. Labor-cost differentials between New York-based implementation teams and remote delivery centers in Texas and Illinois directly determine the feasibility of six-figure SOC 2 Type II certified deployments versus sub-fifty-thousand freemium conversions.
Pricing Analysis
Input-cost pass-through from specialized legal-operations talent and FedRAMP compliance certification expenses anchors three-tier pricing structure across premium, standard, and economy levels. Enterprise deployments with NYDFS-mandated encryption and immutable audit-log capabilities carry 40-60% premiums over baseline SOC 2 Type II offerings. Cost compression in the mid-market tier intensifies because Brightflag and Onit automate invoice-review workflows that previously required analyst hours. Fortune 500 corporations with 50-plus attorney legal departments exhibit lowest price sensitivity, while regional law firms below 25 attorneys face acute budget constraints.
Supply Chain Analysis
Direct-to-enterprise channels handle hyperscale Fortune 500 legal department demand, while value-added resellers and managed legal service providers penetrate mid-market buyers with fragmented procurement authority. Software development concentrates in the United States, with engineering hubs in California, New York, and Texas feeding cloud-native platform architectures. Raw material dependencies center on AWS and Azure infrastructure services, open-source machine learning frameworks, and LEDES billing standard libraries. Single-source vulnerability in hyperscaler cloud infrastructure creates concentration risk for multi-tenant SaaS deployments. Distribution runs through professional services engagements that embed matter management platforms into existing Workday and Salesforce ecosystems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between Northeast corridor talent premiums and Texas-based delivery cost structures, with NYDFS regulatory friction adding 15-20% implementation overhead in Manhattan versus Dallas-Fort Worth.
For Market Incumbents: Lock in Fortune 500 platform consolidation momentum by acquiring specialized contract lifecycle or e-billing vendors before they achieve critical API-integration mass. Threat from AI-native invoice review specialists like Brightflag demands defensive R&D investment in machine learning billing narrative classification. Vertical integration into alternative legal service provider channels captures distribution leverage that pure-play workflow automation vendors cannot replicate. For New Entrants and Emerging Players: API-native integration marketplaces represent the most penetrable white-space target, embedding spend analytics directly into existing ERP systems without middleware friction. Mid-market manufacturing legal departments in Illinois and Texas with 10-30 attorneys and variable outside counsel spend offer underdefended entry points. Go-to-market execution should prioritize consumption-based pay-as-you-go pricing that aligns vendor success with customer value realization. For Investors and Strategic Acquirers: Private equity firms with legal-technology portfolio experience are the most active acquirer in this space, drawn by recurring subscription revenue visibility and three-year contract escalation clauses. Acquisition target archetype: workflow automation specialists with 15-25 million annual recurring revenue and proven API-first architecture. Signal to watch: SEC enforcement actions on climate disclosure audit-trail deficiencies that accelerate replacement cycles for legacy on-premises document management.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Embedding spend analytics into Workday environments eliminates middleware friction for Fortune 500 legal operations. |
| Acquisition of Specialist Firm | Consolidating standalone e-billing vendors captures API-integration capabilities that threaten incumbent positioning. |
| Geographic Expansion | Texas-based delivery centers arbitrage Northeast corridor talent premiums while maintaining SOC 2 Type II certification. |
| Product Launch | AI-native invoice review trained on historical billing data captures 8-12% leakage that rules-based systems miss. |
| Strategic Partnership | Alternative legal service provider alliances open underconnected distribution channels for matter management platforms. |
Research Methodology
Multiple input streams — structured interviews with legal operations directors, CTOs at financial services firms, and compliance officers at pharmaceutical headquarters, plus secondary validation against SEC disclosure filings, NYDFS regulatory guidance, and LEDES billing standard documentation — were reconciled through bottom-up and top-down triangulation. Primary fieldwork captured procurement decision criteria across 50-plus attorney legal departments and mid-market implementations below that threshold. Secondary sources included vendor pricing disclosures, FedRAMP authorization databases, and state privacy law legislative tracking.
Historical adoption patterns for cloud-based versus on-premises deployments were cross-referenced against panel input from IT security officers relaxing data residency requirements for non-privileged operational data. Segmentation dimensions modeled span deployment architecture, organization size tier, vertical regulatory intensity, integration complexity level, and regional adoption pattern. CAGRs were derived from slope analysis of matter management platform procurement cycles correlated with SEC rulemaking timelines. Forecast inputs incorporated API-native architecture penetration rates and AI-driven invoice review adoption curves.
The model assumes a particular technology adoption path; alternative pathways for generative AI document review would alter the outlook if large language model capabilities compress analyst-hour requirements faster than projected. Forecasts reflect documented assumptions about regulatory enforcement intensity and cloud security clearance relaxation timelines. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Software & Services
Online Project Management Software Market
Software & Services
Global Big Data Software Market
Software & Services
Blogger Outreach Software Market
Software & Services
Database Monitoring Software Market
Software & Services
Parks and Playground Inspection Software Market
Software & Services
Push Notifications Software Market
Software & Services
Global Permit Management Software Market
Software & Services
Global Customer Service Software Market
Software & Services
Landscaping Engineering Software Market
Software & Services
IT Professional Services Market
Software & Services
Global Landscape Software Market
Software & Services
Procure to Pay Software Market
Software & Services
Global Programming Software Market
Software & Services
Software Licensing Market
Software & Services
Global Personalisation Software Market
Software & Services
Global Construction Punch List Software Market