
 Latin America Telecom Tower Market | 2026-2036
Latin America Telecom Tower Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Telecom Tower Market Insights
ANATEL's updated infrastructure sharing mandates are pivoting carrier capex toward neutral-host tower models across Brazil. American Tower Corporation leverages its scale to consolidate urban microsite portfolios, while Phoenix Tower International anchors expansion in secondary Mexican markets through build-to-suit agreements. Sitios Latam differentiates by specializing in rural coverage gaps where single-tenant macro towers remain economically viable.
Latin America telecom towers are steel or reinforced concrete structures engineered to host multiple antenna arrays at heights typically ranging from 30 to 120 meters, designed to withstand regional wind loads and seismic activity while supporting radio frequency transmission for wireless networks. Monopole designs dominate urban deployments where zoning restrictions limit footprint, while lattice towers sustain margin pools in rural zones through lower material costs and simpler maintenance access. 5G technology segments are accelerating fastest as mid-band spectrum deployments demand denser site spacing, whereas microwave backhaul retains relevance in remote Andean corridors where fiber penetration remains shallow.
ANATEL in Brazil, IFT in Mexico, and SUBTEL in Chile enforce structural safety standards, electromagnetic emission limits, and environmental licensing that collectively extend deployment timelines and elevate compliance costs for new entrants. Brazil's PLI scheme for telecom manufacturing and Mexico's Federal Telecommunications Law provisions on infrastructure sharing reshape competitive access to public rights-of-way. Stakeholders must monitor pending spectrum auction conditions that tie license awards to coverage obligations, as these terms directly determine tower build schedules and tenancy ratios across the region.
Market Dynamics
Neutral-host infrastructure sharing is compressing carrier-owned tower counts across Brazil and Mexico, forcing operators to divest vertical assets and outsource site management to specialized tower companies under long-term leaseback structures.
Growth Catalysts
- ANATEL Infrastructure Mandates:Brazil's regulator requires MNOs to share passive infrastructure, redirecting capital toward multi-tenant towers and accelerating neutral-host consolidation in dense urban corridors.
- Mid-Band 5G Spectrum:C-band and 3.5 GHz allocations demand site spacing below 500 meters, multiplying addressable locations for small-cell and macro tower augmentation across São Paulo and Rio de Janeiro.
- Rural Broadband Obligations:Spectrum auction terms tie license awards to universal service coverage, compelling tower builds in underserved municipalities where single-tenant economics previously failed.
Market Restraints
- Steel Price Volatility:Galvanized steel coil fluctuations from Chinese export quotas compress tower fabrication margins and delay project financing approvals.
- Seismic Engineering Standards:Chile's SUBTEL-mandated structural reinforcement for Zone 3 earthquake loading adds 15-20% to foundation costs versus standard lattice designs.
- Fiber Backhaul Substitution:Deep fiber penetration in Brazilian state capitals reduces microwave relay dependency, limiting tenancy expansion for towers serving legacy transport functions.
Strategic Opportunities
- Andean Microwave Corridors:Peru and Bolivia's fiber gaps sustain demand for long-haul microwave towers where terrain obstructs cable deployment and satellite latency disqualifies alternatives.
- Renewable Energy Integration:Solar-hybrid power systems eliminate diesel generator dependency at off-grid rural sites, unlocking opex savings and carbon credit eligibility under Mexico's Federal Telecommunications Law sustainability provisions.
- Edge Data Center Colocation:Tower base shelters are being retrofit with micro data centers to host CDN nodes and MEC infrastructure, capturing latency-sensitive enterprise workloads.
Industry Challenges
- RF Engineer Scarcity:Specialized talent for 5G antenna alignment and interference modeling commands premium wages, stretching deployment timelines for build-to-suit contracts.
- Environmental Licensing Delays:IBAMA and SEMARNAT approval processes for greenfield tower sites in Brazilian Amazon municipalities extend permitting to 18-24 months.
- Legacy Lease Renegotiation:Carriers resist rent escalators on first-generation towers, forcing towercos into arbitration over contractual markup clauses signed during 3G-era deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Telecom Tower Market |
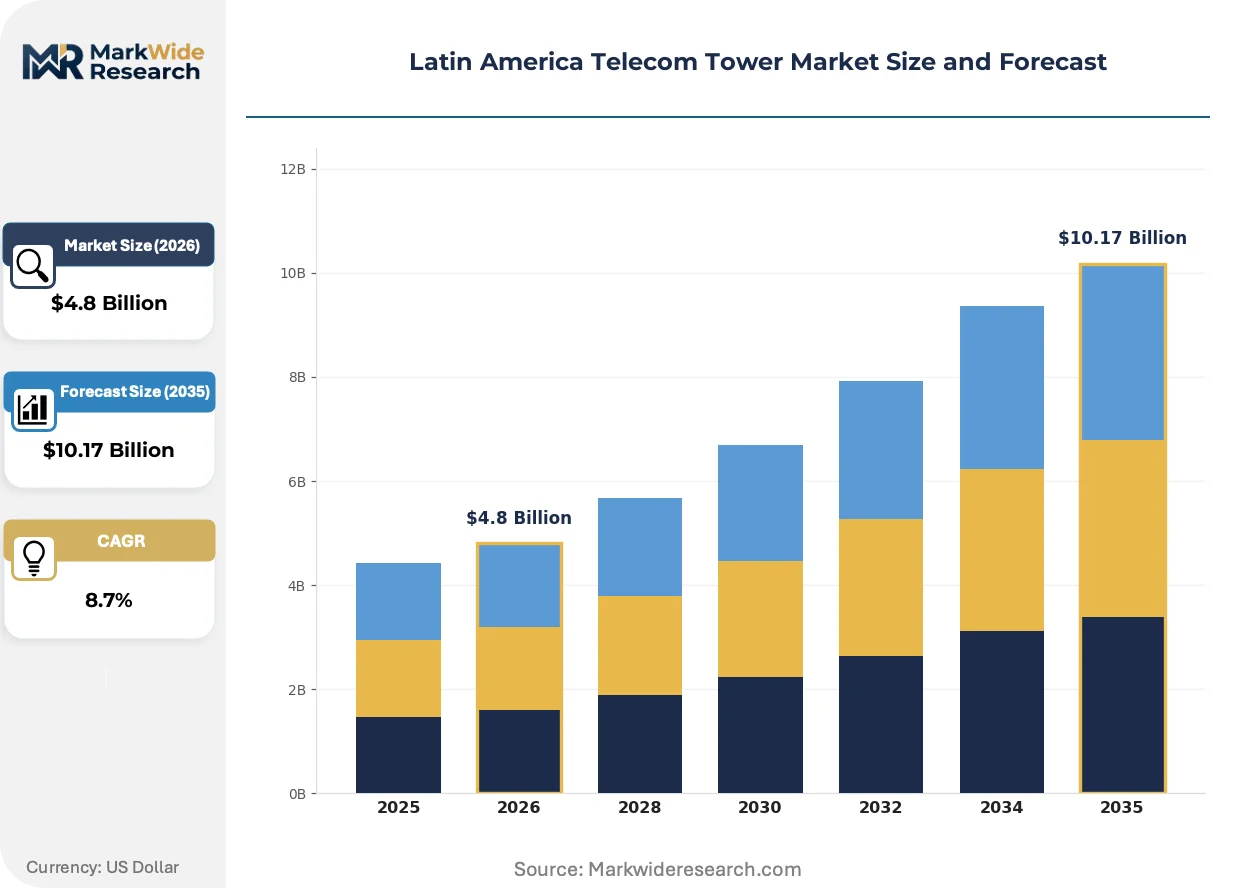
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Mobile Network, Broadcast, Wi-Fi, Data Centers Product Type: Monopole, Lattice, Stealth, Guyed End User: Telecom Operators, Broadcasting Companies, Enterprises, Government Technology: 4G, 5G, LTE, Microwave |
| Companies Covered | American Tower Corporation, Sitios Latam, Phoenix Tower International, SBA Communications Corporation, Torrecom Partners, TELESITES, Telxius, DigitalBridge, Macquarie, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Telecom Tower Market Trends and Innovations
Active antenna systems and software-defined radio architectures are collapsing traditional radio head and antenna separation, compressing tower load profiles while multiplying spectral efficiency targets.
Massive MIMO arrays are rewriting tenancy economics by consolidating multiple frequency bands into single aperture installations. Mobile operators in Brazil's southeast corridor are deploying 64T64R configurations at 70% of new macro sites. This compression is rewriting landlord negotiation leverage as space-per-tenant requirements fall by half.
IFT's 2024 infrastructure catalog mandate requires Mexican towercos to register standardized site specifications in a national database, accelerating due diligence for carrier co-location. The regulation forces disclosure of structural capacity, power availability, and fiber access. Secondary market participants are responding by consolidating fragmented portfolios to achieve catalog eligibility thresholds.
Enterprise buyers are unbundling tower access from managed services, preferring dark-fiber and dark-tower arrangements where they retain operational control. Financial institutions and logistics operators in Mexico City are driving this shift, procuring raw infrastructure through real estate investment trusts rather than traditional telecom vendors. The pattern is most visible in verticals with captive network engineering capabilities.
Latin America Telecom Tower Market Segmentation
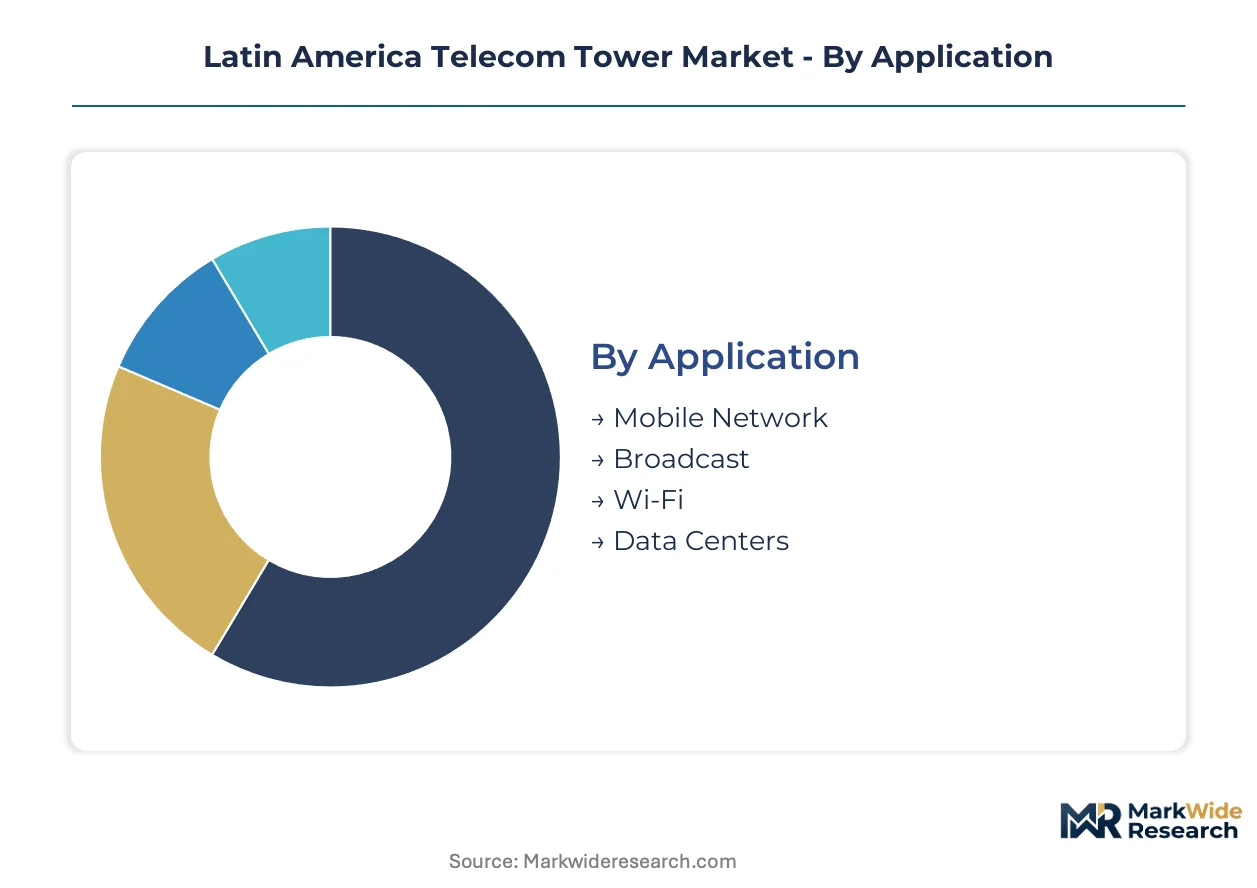
Tower segmentation in Latin America determines capital allocation across structurally different deployment economics. Product type and technology choices cascade through tenancy ratios, permitting complexity, and opex profiles in ways that reshape competitive returns.
Application:
Supply concentration in mobile infrastructure has pulled fabrication capacity and engineering talent away from legacy broadcast deployments.
- Mobile Network:Steel and reinforced concrete structures engineered for 30-120 meter heights support multi-tenant antenna arrays across Brazil's southeastern corridor. São Paulo and Rio de Janeiro density justifies premium lease rates for macro sites serving 5G mid-band propagation.
- Broadcast:Tall guyed masts and heavy-lattice towers carry FM and television transmission equipment, with demand concentrating in Mexico's central plateau where terrain elevation extends coverage footprints. Regulatory mandates for digital transition sustain replacement cycles despite cord-cutting trends.
- Wi-Fi:Short monopole and wall-mounted installations serve municipal hotspot networks and enterprise campus coverage in Colombian urban centers.
- Data Centers:Tower base shelters retrofit with micro data centers host CDN nodes and MEC infrastructure for latency-sensitive workloads.
Mobile Network absorbs the bulk of installed capacity; Data Centers is expanding most quickly.
Product Type:
Cost tier differentiation separates premium urban solutions from rural economy deployments.
- Monopole:Single-shaft steel designs minimize ground footprint for zoning-constrained Brazilian municipalities. ANATEL infrastructure sharing mandates accelerate multi-tenant attachments at São Paulo microsites where space commands premium valuations.
- Lattice:Triangular or square-section steel frameworks sustain lower material costs and simpler maintenance access in rural zones. Peru and Bolivia's Andean corridors favor these structures for microwave backhaul where terrain obstructs fiber deployment.
- Stealth:Concealed designs mimic architectural elements or vegetation to satisfy aesthetic restrictions in historic Mexican districts and Chilean coastal zones.
- Guyed:Tension-wire supported masts achieve maximum height-to-cost ratios for broadcast and remote coverage applications.
Lattice structures retain the widest geographic footprint; Monopole configurations are climbing the fastest on urban 5G densification.
End User:
Customer type determines contract duration, credit risk, and service-level requirements across the tenancy base.
- Telecom Operators:Mobile network carriers drive volume demand through long-term leaseback arrangements and build-to-suit contracts. Mexico's IFT infrastructure catalog mandate standardizes procurement terms for these anchor tenants.
- Broadcasting Companies:Radio and television stations require specialized tall structures with heavy antenna load capacity.
- Enterprises:Financial institutions and logistics operators in Mexico City increasingly procure dark-tower arrangements through real estate investment trusts.
- Government:Universal service obligations and public safety networks generate single-tenant rural builds where commercial economics fail.
Telecom Operators anchor revenue concentration; Enterprises are gaining share fastest on unbundled infrastructure preferences.
Technology:
Technology generation determines spectral efficiency requirements and site spacing economics.
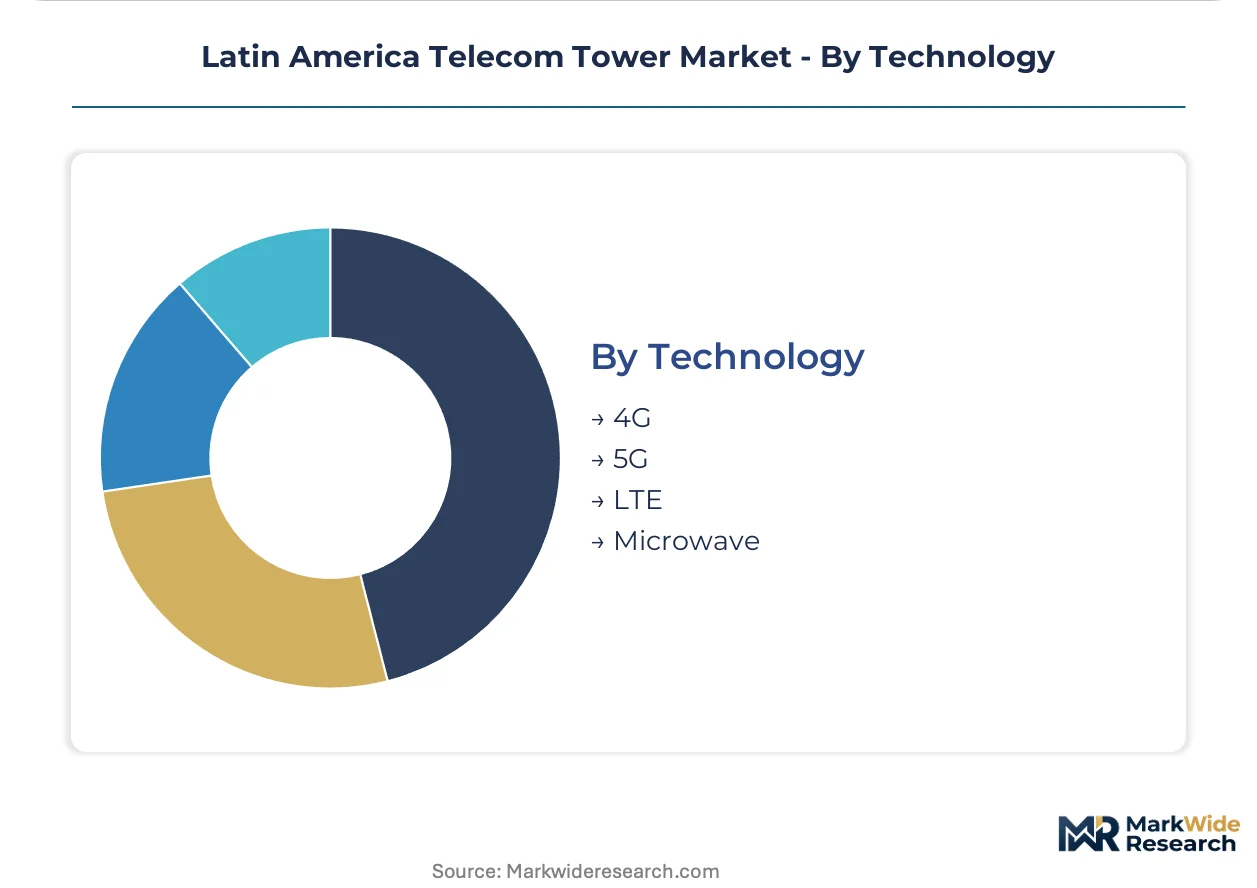
- 5G:Mid-band C-band and 3.5 GHz deployments demand site spacing below 500 meters, multiplying addressable locations for small-cell augmentation. Massive MIMO arrays at 64T64R configurations compress space-per-tenant requirements while multiplying spectral throughput.
- 4G:Legacy macro sites sustain tenancy through capacity overlays and rural coverage maintenance.
- LTE:Existing infrastructure provides fallback compatibility and voice service continuity.
- Microwave:Point-to-point relay towers bridge fiber gaps in Andean corridors and Amazon municipalities where cable deployment remains uneconomic.
4G infrastructure retains the largest installed base; 5G deployment shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil and Mexico concentrate over two-thirds of regional tower investment, driven by 5G spectrum mandates and rural broadband obligations. Secondary markets in Chile, Colombia, and Peru are accelerating as fiber backhaul gaps sustain microwave relay demand.
Brazil
ANATEL's infrastructure sharing mandates and 5G spectrum auction coverage obligations are redirecting carrier capex toward neutral-host models. The National Broadband Plan requires universal service builds in Amazon municipalities. São Paulo and Rio de Janeiro anchor multi-tenant investments where population density justifies premium lease rates.
Mexico
IFT's 2024 infrastructure catalog mandate standardizes site specifications and accelerates carrier co-location decisions. Build-to-suit agreements dominate secondary market expansion beyond Mexico City. The Federal Telecommunications Law provisions on infrastructure sharing reshape competitive access to public rights-of-way.
Chile
SUBTEL enforces Zone 3 seismic engineering standards that add foundation costs but attract insurance-backed institutional investment. The Santiago-Valparaíso corridor concentrates urban 5G densification. Coastal zones favor stealth designs to satisfy aesthetic restrictions in historic districts.
Colombia
Municipal hotspot networks and enterprise campus coverage drive short monopole deployments in Bogotá and Medellín. The national spectrum regulator ties license awards to rural coverage obligations. Andean terrain sustains microwave backhaul demand where fiber penetration remains shallow.
Peru
Long-haul microwave towers bridge fiber gaps in remote corridors where terrain obstructs cable deployment. The Ministry of Transport and Communications enforces structural safety standards for high-altitude installations. Lima anchors urban capacity overlays while rural builds concentrate in Cusco and Arequipa regions.
Latin America Telecom Tower Market Competitive Landscape
Brazilian and Mexican operators anchor one tier of the competitive structure; U.S.-based specialists hold portfolio scale advantages in cross-border consolidation. The vendor base separates into three archetypes: integrated towercos with leaseback structures, build-to-suit specialists targeting secondary markets, and infrastructure funds acquiring stabilized cash-flow assets. M&A activity concentrates on urban microsite portfolios, while strategic partnerships address rural coverage gaps where single-tenant economics require subsidy alignment.
Among U.S.-based tower operators, American Tower Corporation exemplifies the integrated towerco archetype through scale-driven urban consolidation. Sitios Latam occupies a position within the build-to-suit specialist tier, targeting rural coverage gaps where single-tenant macro towers remain economically viable. Phoenix Tower International anchors expansion in secondary Mexican markets through long-term lease agreements with mobile network operators.
| Leading Market Players |
|---|
| American Tower Corporation |
| Sitios Latam |
| Phoenix Tower International |
| SBA Communications Corporation |
| Torrecom Partners |
| TELESITES |
| Telxius |
| DigitalBridge |
| Macquarie |
| Others |
Pricing and Supply Chain Analysis
Mobile network operators in Brazil and Mexico concentrate procurement power through long-term leaseback structures, anchoring contract-based pricing that rewards multi-tenant site commitments and penalizes single-tenant spot arrangements. This buyer concentration forces tower companies to absorb steel price volatility while competing for anchor tenancy through extended contract terms.
Pricing Analysis
Short lead-time premiums apply to urban microsite deployments where ANATEL-mandated 5G densification compresses build schedules, while spot inventory discounts emerge in rural lattice tower markets with excess fabrication capacity. Three-tier pricing structure across premium, standard, and economy levels separates monopole urban sites with fiber backhaul from lattice rural towers and legacy guyed masts. Cost compression in standard-tier lattice products is intensifying because Chinese galvanized steel export quotas disrupt fabrication margins. Government universal service programs show highest price sensitivity due to subsidy-dependent budgets, while enterprise dark-tower buyers demonstrate lowest sensitivity given captive network engineering capabilities.
Supply Chain Analysis
Skilled welder and RF engineer scarcity in Brazilian southeastern manufacturing zones extends tower fabrication timelines and elevates labor cost premiums above Mexican and Colombian production alternatives. Geographic supply concentration centers on Brazil, Mexico, and China for structural steel components, with galvanized coil and antenna mounting hardware drawing from East Asian mills. Supply chain risk rests on single-source vulnerability for specialized seismic-grade steel alloys required under Chile's SUBTEL Zone 3 standards. Distribution runs through integrated towerco direct-lease models to mobile network operators, supplemented by build-to-suit specialists serving secondary municipalities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over steel fabrication and renewable energy systems at tower bases determines margin capture. Players are pursuing downstream integration into edge data center colocation to monetize latency-sensitive enterprise workloads.
For Market Incumbents: Deepen backward integration into galvanized steel coil supply through offtake agreements with Brazilian mills, insulating fabrication margins from Chinese export quota volatility. Anchor tenancy ratios in São Paulo and Rio de Janeiro microsites must be defended against emerging build-to-suit specialists by accelerating fiber backhaul co-investment with mobile network operators.
For New Entrants and Emerging Players: Municipal governments in Amazon municipalities and Andean corridor provinces represent the most penetrable customer segment, as universal service obligations compel tower builds where commercial economics previously failed. Target these single-tenant rural deployments through renewable energy-integrated offerings that qualify for carbon credits under Mexico's Federal Telecommunications Law sustainability provisions.
For Investors and Strategic Acquirers: The window for entry favors stabilized cash-flow portfolios with long-term leaseback structures and 5G-upgrade-ready structural capacity. Monitor pending spectrum auction coverage obligation terms as the inflection indicator that will trigger accelerated build schedules and tenancy ratio expansion across Brazil and Mexico.
| Strategic Initiative | Industry Significance |
|---|---|
| Renewable Energy Integration | Solar-hybrid power systems at off-grid rural sites unlock opex savings and carbon credit eligibility under Mexican sustainability provisions. |
| Edge Data Center Colocation | Tower base shelters retrofit with micro data centers capture latency-sensitive CDN and MEC workloads from financial institutions. |
| Build-to-Suit Expansion | Secondary market agreements in Mexican states beyond Mexico City diversify tenancy base away from saturated urban corridors. |
| Seismic Engineering Certification | Zone 3 structural compliance attracts insurance-backed institutional investment for Chilean portfolio acquisitions. |
| Infrastructure Catalog Registration | IFT-mandated standardized site specifications accelerate carrier co-location decisions and consolidate fragmented Mexican portfolios. |
Research Methodology
Multi-period observation of tenancy ratio trajectories, steel input cost indices, and spectrum auction coverage obligations anchored the trend analysis, supplemented by interviews with tower company portfolio managers, mobile network operator infrastructure planners, ANATEL regulatory affairs specialists, and IBAMA environmental licensing officers. Secondary validation drew from ANATEL infrastructure sharing mandates, IFT infrastructure catalog specifications, SUBTEL seismic engineering standards, customs data on galvanized steel coil imports, and SEC filings of publicly traded tower operators. Bottom-up site-level economics triangulated against top-down regional capex forecasts.
Input-output matrices mapped structural steel requirements per tower type against mobile data traffic density projections across the analysis window. Segmentation dimensions modeled include product type, technology generation, application, and end-user category. CAGRs were derived from regression analysis of historical tenancy growth and forward projection of 5G site spacing requirements. Industry-specific forecast inputs incorporated mid-band spectrum propagation characteristics and rural broadband obligation build schedules.
Caveats apply where steel price volatility, environmental licensing delays in Brazilian Amazon municipalities, or spectrum auction term revisions could materially shift the outlook. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
France Telecom Towers Market
Telecommunications Infrastructure
Global Cellular Networks Market
Telecommunications Infrastructure
Global Integrated Telecom Infrastructure Market
Telecommunications Infrastructure
Philippines Telecom Towers Market
Telecommunications Infrastructure
Nigeria Telecom Tower Market
Telecommunications Infrastructure
Terrestrial Trunked Radio (TETRA) System Market
Telecommunications Infrastructure
5G Network Infrastructure Market
Telecommunications Infrastructure
Microwave Backhaul System Market
Telecommunications Infrastructure
Brazil Telecom Tower Market
Telecommunications Infrastructure
Slovenia Telecom Market
Telecommunications Infrastructure
Global Telecom System Integration Market
Telecommunications Infrastructure
Iraq Telecom Market
Telecommunications Infrastructure
Broadcast Infrastructure Market
Telecommunications Infrastructure
Vietnam Telecom Towers Market
Telecommunications Infrastructure
Colombia Telecom Tower Market
Telecommunications Infrastructure
NLD and ILD Telecom Service Market