
 Fiber to the X (FTTX) Market | 2026-2036
Fiber to the X (FTTX) Market Size, Share, and Industry Trends Forecast 2026-2036
Fiber to the X (FTTX) Market Intelligence
The capital investment capacity for deploying next-generation passive optical networks is bifurcating the competitive landscape. Large-scale infrastructure providers like Huawei Technologies sustain extensive R&D for advanced network components. In contrast, specialists such as Prysmian Group differentiate through high-performance optical fiber and cable manufacturing. Corning Incorporated leverages its deep material science expertise to lead in specialty glass and optical solutions.
Fiber to the X (FTTX) refers to any broadband network architecture using optical fiber to provide all or part of the local loop for last-mile telecommunications. These networks utilize single-mode fiber to deliver high-bandwidth services directly to subscribers. Among deployment types, Fiber to the Home (FTTH) represents the dominant and fastest-growing category. Within technology, GPON remains the most widely deployed standard, though operators are exploring next-generation solutions like DWDM for future capacity upgrades.
Regulatory frameworks, including the FCC's oversight of broadband deployment in the United States and the EU's Digital Services Act, shape market access and competition. Standards from the International Telecommunication Union (ITU), such as the G.98x series for PON, ensure interoperability and guide equipment design. Network operators must now decide between incremental upgrades to existing infrastructure or wholesale replacement with next-generation architectures.
Market Dynamics
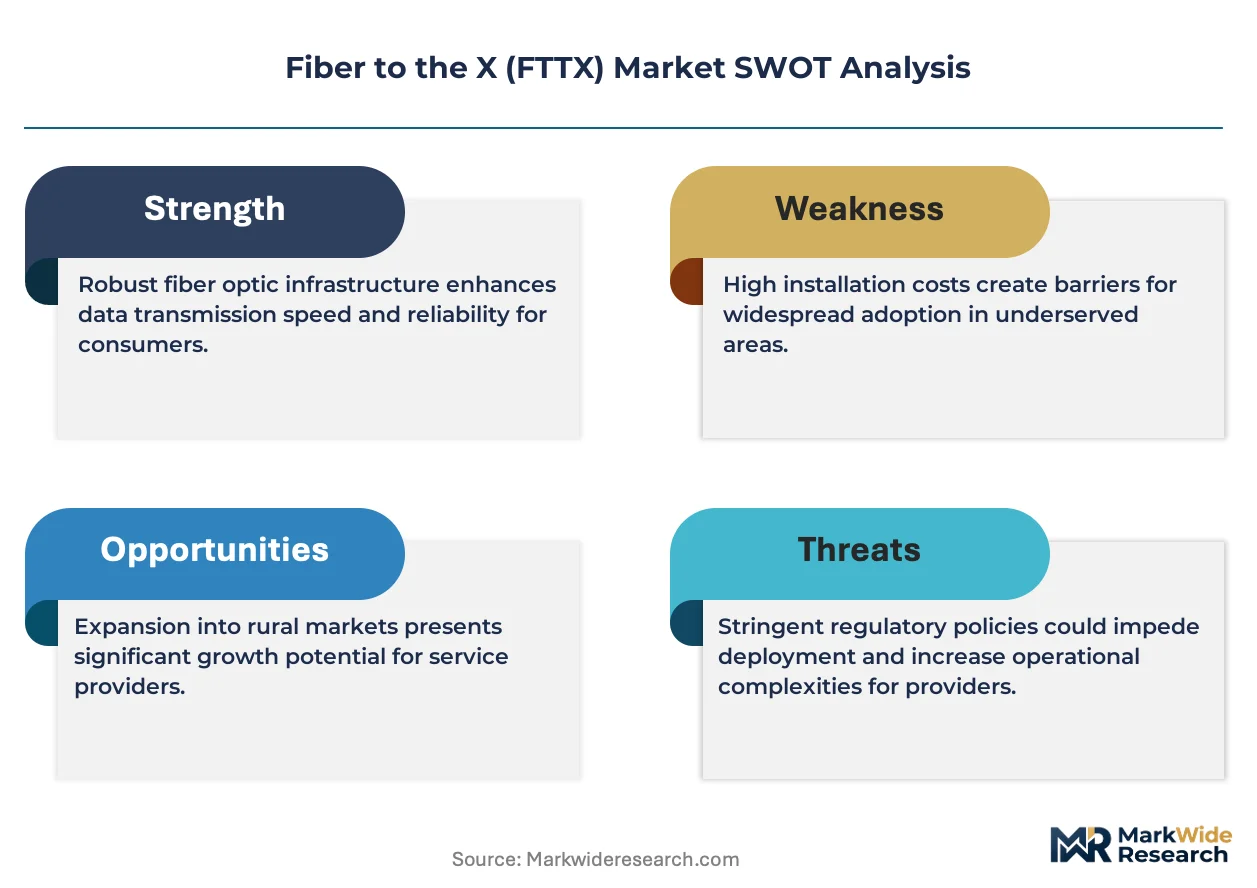
The central structural force shaping the FTTX market is the operator's decision between costly, incremental upgrades to existing GPON infrastructure and wholesale replacement with next-generation architectures to meet exponential bandwidth demand from residential and enterprise users.
Growth Catalysts
- Government Initiatives:National broadband plans, such as the US Broadband Equity, Access, and Deployment (BEAD) program, provide substantial public funding that de-risks and accelerates private investment in last-mile fiber infrastructure, particularly in unserved areas.
- Residential Bandwidth Demand:The proliferation of high-resolution streaming, online gaming, and remote work applications creates sustained consumer demand for gigabit-speed internet connections, making Fiber to the Home (FTTH) a preferred access technology.
- Digital Transformation in Developing Economies:Countries like India are pursuing ambitious national digitization goals, driving massive public and private investment in fiber optic networks as foundational infrastructure for economic development and digital inclusion.
Market Restraints
- High Initial Capital Outlay:The civil engineering costs associated with trenching, ducting, and laying fiber optic cable represent the largest portion of deployment expenses, creating a significant financial barrier to entry and slowing network rollout.
- Right-of-Way and Permitting Complexity:Gaining approvals from multiple municipal, regional, and national authorities to access public and private land for cable installation is a time-consuming and administratively burdensome process that introduces project delays.
- Legacy Infrastructure Integration:Operators with extensive existing copper or coaxial cable networks face technical challenges and costs associated with integrating new fiber deployments, managing hybrid networks, and migrating subscribers.
Strategic Opportunities
- Rural and Remote Market Penetration:Vast, underserved populations in rural areas of North America and developing regions of Asia-Pacific represent a significant greenfield opportunity for operators, often supported by government subsidies.
- 5G and Edge Computing Synergy:FTTX networks provide ideal high-capacity backhaul for 5G small cells and can support the low-latency requirements of distributed edge computing nodes, creating new revenue streams for infrastructure owners.
- Smart City Infrastructure:The deployment of ubiquitous fiber connectivity serves as a backbone for smart city applications, including intelligent traffic management, public safety surveillance, and utility monitoring, opening opportunities for public-private partnerships.
Industry Challenges
- Skilled Labor Shortages:A deficit of trained fiber optic technicians, particularly splicers and network engineers, creates a bottleneck in deployment capacity, leading to project delays and increased labor costs for network operators.
- Network Upgrade Path Complexity:Operators must navigate complex technical and financial decisions regarding migration from GPON to next-generation PON standards, balancing future capacity needs with the cost of replacing customer and network equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fiber to the X (FTTX) Market |
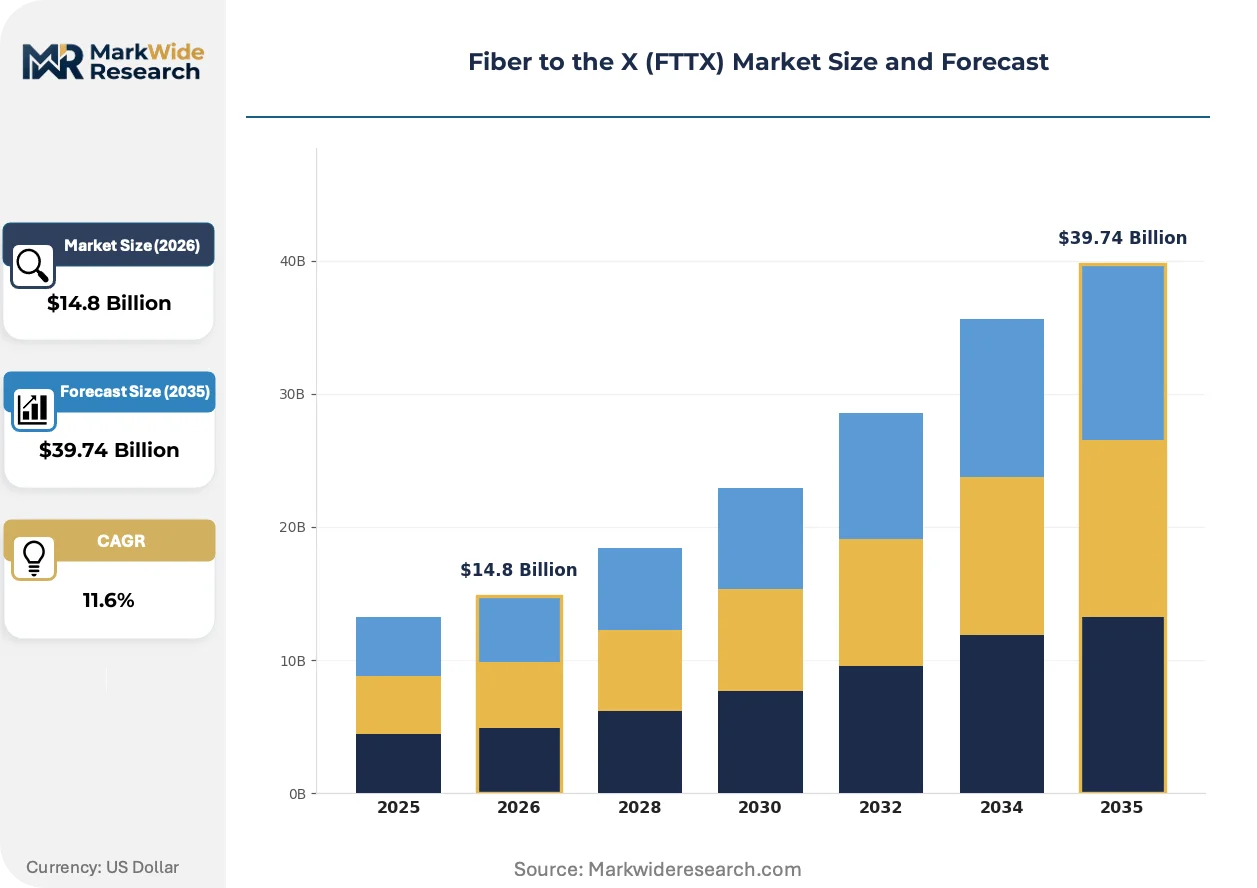
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $39.74 Billion |
| CAGR (2026 – 2036) | 11.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Type: Fiber to the Home, Fiber to the Building, Fiber to the Node, Fiber to the Curb, Fiber to the Premises Technology: GPON, EPON, Active Ethernet, RF Overlay, DWDM Application: High-Speed Internet, IP Telephony, IPTV, Cloud Connectivity, Video Streaming End User: Residential Subscribers, Small and Medium Enterprises, Large Corporations, Government Agencies, Educational Institutions |
| Companies Covered | ZTE Corporation, Prysmian Group, Huawei Technologies, FiberHome Technologies, Ericsson, Nokia Corporation, CommScope, Fujikura Ltd., Corning Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fiber to the X (FTTX) Market Strategic Shifts & Innovations
Technological advancement is focused on increasing the bandwidth capacity of a single fiber strand and extending the reach of optical networks. This drive for efficiency is creating divergent pathways for network evolution, influencing long-term capital investment strategies for operators globally.
Next-generation Passive Optical Network (PON) standards, including 25G-PON and 50G-PON, provide a significant leap in data throughput over existing GPON technology. Major telecommunications operators are adopting these standards to support future-proof residential services and high-bandwidth enterprise applications. This pursuit of higher speeds is fragmenting the technology roadmap as providers evaluate the business case for different upgrade cycles.
Regulatory frameworks like the European Union's Digital Decade policy are setting ambitious targets for universal gigabit connectivity. This policy compels member states to accelerate fiber rollouts through direct funding and by simplifying permit regulations for civil works. Network operators in countries such as Germany and Spain are consequently adjusting their investment timelines to align with these mandates.
A notable behavioral shift is occurring as providers move from selling simple speed tiers to bundling connectivity with value-added services. This disrupts the traditional internet service provider model, as telcos now package offerings like cloud gaming, telehealth, and advanced cybersecurity. This service-layer differentiation is most prominent in mature FTTX markets like South Korea, where high penetration enables competition beyond pure bandwidth.
Fiber to the X (FTTX) Market Segmentation
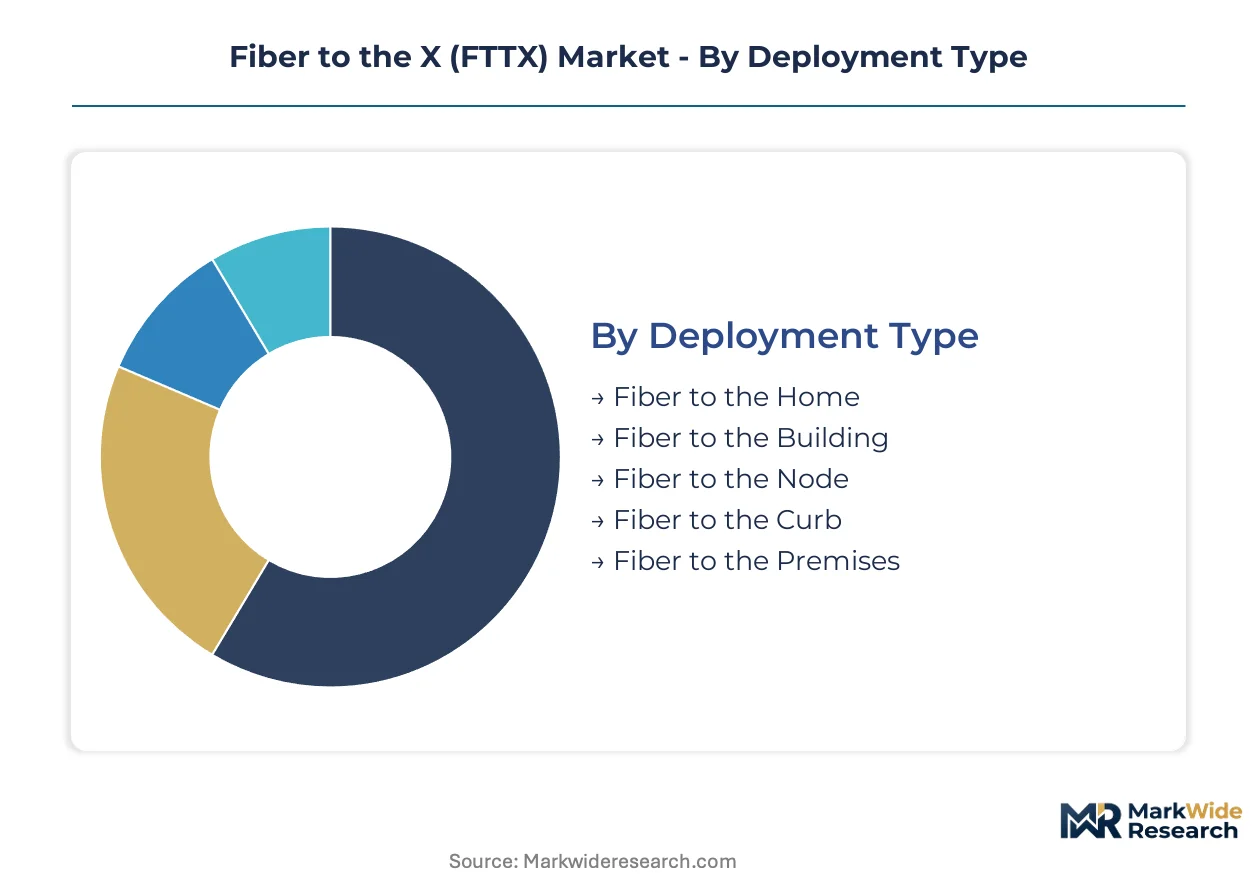
The Fiber to the X (FTTX) market is segmented to analyze the diverse infrastructure deployment methods, technological standards, service applications, and distinct end-user requirements. This granular breakdown helps operators and investors identify specific opportunities for network expansion and service differentiation across various market segments.
Deployment Type:
The FTTX market exhibits varied deployment models, influencing the final mile of connectivity through different infrastructure channels.
- Fiber to the Home (FTTH):This architecture extends optical fiber directly into individual living units, providing dedicated high-bandwidth connections. Demand concentrates among residential subscribers in countries like Japan and South Korea, driven by pervasive high-resolution streaming and online gaming.
- Fiber to the Premises (FTTP):This deployment involves running optical fiber directly to the boundary of a residential or commercial property. Large enterprises and data centers in North America increasingly adopt FTTP for secure, high-capacity links to support cloud computing and distributed operations.
- Fiber to the Building (FTTB):Optical fiber terminates within a multi-dwelling unit or office building, distributing connectivity to individual units via copper or Ethernet. This model is common in densely populated urban centers, serving apartments and shared office spaces.
- Fiber to the Node (FTTN):Fiber runs to a street cabinet or distribution point, with the final connection to the customer premises made over existing copper infrastructure. Operators in Germany and the United Kingdom utilize FTTN as an interim upgrade solution.
- Fiber to the Curb (FTTC):Optical fiber extends to a pedestal near the customer's home or business, with a short copper segment completing the connection. This approach balances cost and performance, often seen in suburban deployments.
By volume, Fiber to the Home (FTTH) leads. By growth pace, Fiber to the Premises (FTTP) is ahead.
Technology:
Technological choices within FTTX networks define the performance tiers and upgrade pathways for service providers.
- GPON:Gigabit Passive Optical Network utilizes a single optical fiber to serve multiple endpoints through passive splitters, offering cost-effective broadband deployment. Operators in India and Brazil widely deploy GPON for mass-market residential internet access due to its efficiency.
- DWDM:Dense Wavelength Division Multiplexing increases bandwidth capacity by transmitting multiple data streams simultaneously over a single optical fiber using different wavelengths of light. Telecommunication providers in the United States explore DWDM for backbone networks and future capacity upgrades to meet escalating demand.
- EPON:Ethernet Passive Optical Network is an alternative passive optical network standard, providing Ethernet-based connectivity over fiber. EPON deployments are prevalent in East Asian markets, supporting various consumer and business services.
- Active Ethernet:This technology provides a dedicated point-to-point fiber connection from the central office to each subscriber, offering symmetrical high-speed bandwidth. Active Ethernet serves specific enterprise clients requiring guaranteed service level agreements.
- RF Overlay:This method integrates traditional radio frequency video signals onto a passive optical network, allowing operators to deliver broadcast TV alongside internet services. RF Overlay offers a solution for cable operators migrating to fiber-based infrastructure.
GPON technology dominates current deployments, while DWDM represents a critical path for future network scaling.
Application:
The FTTX infrastructure supports a diverse range of applications, catering to both consumer and enterprise requirements.
- High-Speed Internet:This fundamental application provides broadband connectivity for general web browsing, email, and basic online activities. Residential and small business users globally prioritize high-speed internet for daily digital interactions.
- Video Streaming:This application involves delivering on-demand and live video content, requiring substantial bandwidth and low latency for optimal user experience. Consumer demand for 4K and 8K video streaming drives network upgrades in mature markets such as Canada and the United Kingdom.
- IP Telephony:Voice over Internet Protocol (VoIP) services enable phone calls over the internet, replacing traditional landlines. Businesses adopt IP Telephony for cost-effective communication solutions and unified communications platforms.
- Cloud Connectivity:FTTX networks provide direct, high-capacity links to cloud service providers, facilitating data storage, application hosting, and virtualized services. Large corporations and government agencies increasingly rely on robust cloud connectivity for digital transformation initiatives.
- IPTV:Internet Protocol Television delivers television programming over IP networks, offering advanced features like video-on-demand and interactive services. Operators bundle IPTV with internet and telephony to enhance subscriber value.
High-Speed Internet forms the core offering, while Video Streaming is a primary driver for capacity expansion.
End User:
FTTX services are tailored to meet the specific connectivity needs of various end-user segments, from individual households to large institutions.
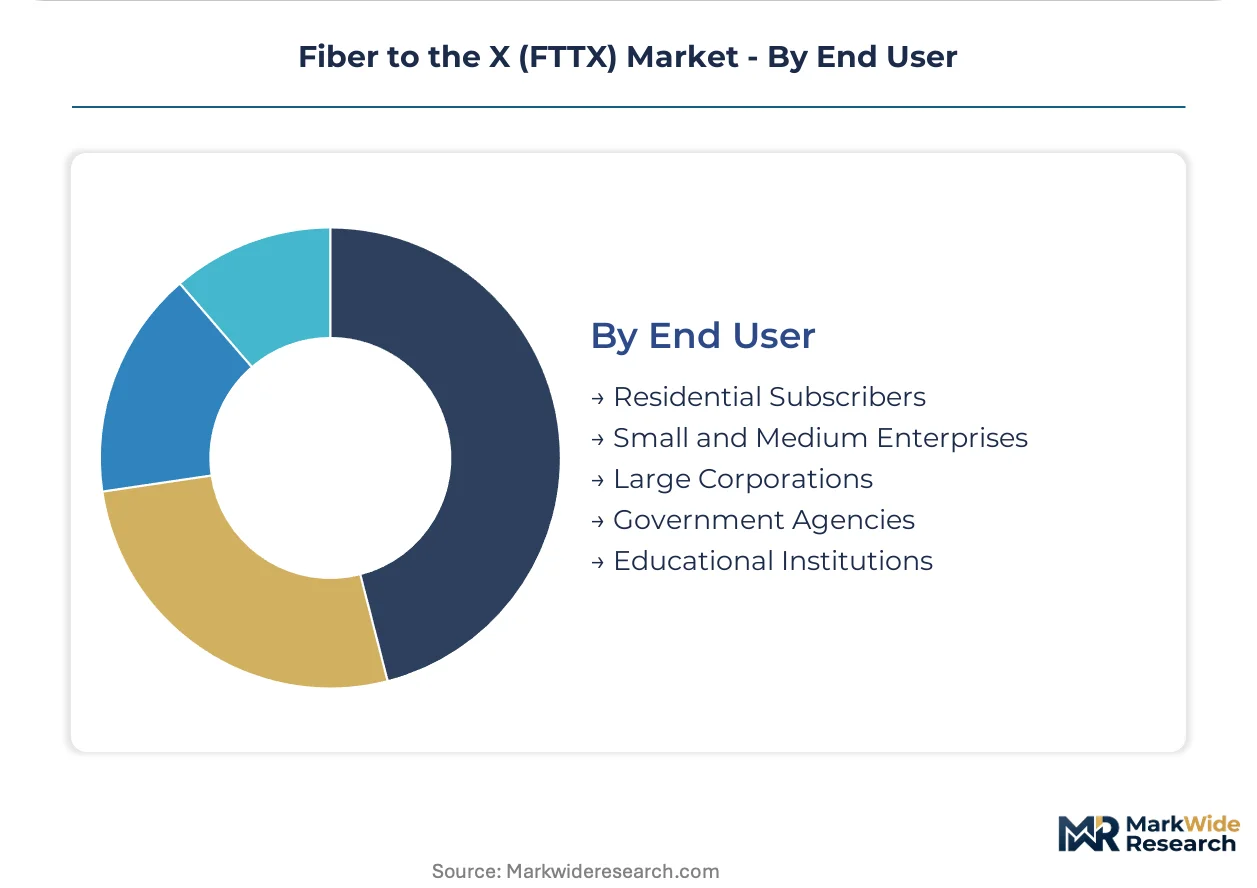
- Residential Subscribers:This segment includes individual households requiring internet access for entertainment, communication, education, and remote work. Government initiatives across the European Union aim to achieve universal gigabit connectivity for residential users.
- Large Corporations:These entities demand high-bandwidth, low-latency, and highly reliable fiber connections to support extensive data transfer, cloud applications, and global operations. Financial institutions and technology firms in Singapore often require dedicated fiber links.
- Small and Medium Enterprises (SMEs):SMEs utilize FTTX for business-critical internet access, cloud services, and digital communication tools. Affordable and scalable fiber solutions are crucial for SME growth in developing economies.
- Government Agencies:Public sector organizations require secure, resilient, and high-capacity networks for critical infrastructure, public services, and inter-agency communication. National defense and public safety networks leverage FTTX.
- Educational Institutions:Universities, colleges, and schools depend on robust fiber connectivity for online learning platforms, research networks, and administrative functions. High-speed access supports digital curricula and remote collaboration for students and faculty.
Residential Subscribers represent the largest volume segment, with Large Corporations contributing significantly to revenue value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand elasticity for FTTX services varies significantly across global markets. Developing economies often exhibit high price sensitivity, prioritizing basic connectivity over premium features. Conversely, mature markets prioritize advanced features and higher bandwidth, demonstrating lower price sensitivity.
United States
The United States sees strong demand for high-speed internet driven by remote work and advanced streaming applications. The Broadband Equity, Access, and Deployment (BEAD) program provides substantial federal funding to expand fiber infrastructure in unserved and underserved areas. Major metropolitan hubs like New York City and Los Angeles are experiencing significant Fiber to the Home (FTTH) deployments to meet urban density requirements.
India
India's FTTX market is propelled by national digital transformation initiatives and a vast, underserved population. The BharatNet project aims to connect rural areas with optical fiber, fostering digital inclusion across the country. Cities such as Mumbai and Bangalore are foundational for enterprise cloud connectivity and widespread residential GPON deployments.
Germany
Germany's FTTX expansion is driven by a strategic shift from Fiber to the Node (FTTN) to Fiber to the Home (FTTH) to meet increasing bandwidth needs. The European Union's Digital Decade targets compel accelerated fiber rollouts, supported by national funding programs. Frankfurt, as a major financial hub, requires robust fiber networks for data centers and high-speed enterprise links.
South Korea
South Korea maintains high FTTX penetration, with demand centered on ultra-high-definition content and advanced smart home services. Government policies consistently promote universal gigabit connectivity and technological innovation in network infrastructure. Seoul's dense urban environment facilitates widespread FTTH adoption and next-generation PON deployments.
Brazil
Brazil's FTTX growth is fueled by expanding internet access in urban and peri-urban areas and increasing digital service adoption. Regulatory incentives from ANATEL encourage investment in fiber optic networks, particularly for residential users. São Paulo, as the largest city, is a key market for GPON expansion and competitive service offerings.
Fiber to the X (FTTX) Market Key Industry Players
Technology leadership and cost leadership are held by different player archetypes within the FTTX market. The competitive structure is tiered, with large-scale infrastructure providers dominating the high-end technology segments, often leveraging extensive R&D. Specialist manufacturers differentiate through high-performance optical fiber and cable, focusing on material science expertise. Key strategic moves include substantial capacity expansion to meet global deployment demand and strategic partnerships to integrate diverse network solutions across the value chain.
Within the large-scale infrastructure provider archetype, Huawei Technologies Co., Ltd., a Chinese corporation, exemplifies extensive R&D capabilities for advanced network components, often leading in next-generation PON standards. Prysmian Group S.p.A., an Italian-based specialist, anchors the high-performance optical fiber and cable manufacturing segment, focusing on innovative cable designs. Corning Incorporated, a U.S.-based entity, occupies a leading position through its deep material science expertise in specialty glass and optical solutions, crucial for extending network reach. These companies collectively represent the diverse approaches to innovation and market penetration across the FTTX ecosystem.
| Leading Market Players |
|---|
| ZTE Corporation |
| Prysmian Group |
| Huawei Technologies |
| FiberHome Technologies |
| Ericsson |
| Nokia Corporation |
| CommScope |
| Fujikura Ltd. |
| Corning Incorporated |
| Others |
Cost & Logistics Intelligence
Project-based contracts for FTTX infrastructure deployment lock in multi-year equipment supply, providing operators with predictable component costs and ensuring network rollout continuity. These agreements mitigate volatility in optical fiber and network hardware pricing.
Pricing Analysis
After-sales service contracts for network maintenance and managed services drive significant lifetime value for FTTX operators. Subscription-tiered models dominate residential offerings, while project-based contracts define infrastructure procurement. Price differentiation stems from guaranteed bandwidth speeds and bundled value-added services like advanced cybersecurity. Pricing pressure intensifies for basic residential connectivity due to government subsidies and increased competition from alternative providers. Residential subscribers in developing economies exhibit the highest price sensitivity, whereas large corporations prioritize service level agreements over cost.
Supply Chain Analysis
China anchors the production of critical network components and GPON equipment, while Italy and the United States lead in high-performance optical fiber and specialty glass manufacturing. The FTTX supply chain relies heavily on high-purity silica for fiber optics and complex semiconductors for active network devices. Geopolitical tensions affecting trade routes and technology access present a structural supply chain risk for global operators. Distribution runs through direct procurement channels for major telecommunication providers and a network of system integrators for regional deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FTTX market represents a high-growth disruption, driven by the imperative for universal gigabit connectivity and the regulatory push from initiatives like the EU's Digital Decade. This foundational infrastructure enables future digital economies.
For Market Incumbents: Compound existing network reach by selectively upgrading GPON to next-generation PON standards in high-demand urban centers. Consolidate regional market share through strategic acquisitions of smaller, local fiber providers to counter emerging alternative access technologies. The threat of commoditization for basic connectivity requires incumbents to leverage R&D for advanced network components and value-added service bundles.
For New Entrants and Emerging Players: Anchor in underserved rural markets of North America, capitalizing on government subsidies like the US BEAD program. Target enterprises requiring dedicated, symmetrical bandwidth for cloud connectivity, leveraging agile deployment models. The most penetrable segment remains residential subscribers in developing economies seeking reliable, affordable internet access. A go-to-market angle focused on simplified service bundles and rapid installation can gain traction.
For Investors and Strategic Acquirers: Regional fiber infrastructure providers with established rights-of-way represent compelling acquisition targets for long-term value creation over the next five to ten years. These entities offer critical last-mile access in high-growth areas. Acquiring specialists in optical fiber manufacturing can secure supply chains and R&D capabilities. The signal to watch is the acceleration of national broadband plan disbursements, indicating deployment readiness.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Increasing fiber optic cable production meets rising global demand for FTTX deployments. |
| Strategic Partnership | Collaborating with equipment vendors and operators accelerates next-generation PON adoption. |
| R&D Investment | Developing advanced optical solutions enhances bandwidth capacity and network reach. |
| Geographic Market Entry | Expanding into underserved developing economies captures new subscriber bases and revenue streams. |
| Value-Added Service Bundling | Integrating cloud gaming or telehealth differentiates offerings beyond basic internet speed for residential users. |
Research Approach
Findings reconcile primary fieldwork against secondary review of ITU standards, national broadband plan reports, and corporate financial disclosures. Interviews with network architects, telecom executives, and regulatory officials provided qualitative insights into market dynamics. This primary data was triangulated with quantitative secondary research, employing both bottom-up market sizing from specific deployments and top-down validation against macroeconomic indicators.
Deployment type, technology standard, application, and end-user segments define the modeled segmentation dimensions across the analysis window. Compound annual growth rates derive from historical market progression and projected demand drivers for high-bandwidth services. Key industry-specific forecast inputs include government subsidy commitments for rural broadband expansion and projected residential subscriber growth rates in developing economies.
Material uncertainties — including shifts in regulatory funding and unforeseen technological breakthroughs in wireless access — sit outside the modeled envelope. Forecasts reflect current market assumptions and deployment trajectories. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Global Telecom Cable Market
Telecommunications Infrastructure
Telecom Network Infrastructure Market
Telecommunications Infrastructure
Chile Telecom Tower Market
Telecommunications Infrastructure
Bangladesh Telecom Towers Market
Telecommunications Infrastructure
China Telecom Equipment Market
Telecommunications Infrastructure
Broadcast Infrastructure Market
Telecommunications Infrastructure
Peru Telecom Tower Market
Telecommunications Infrastructure
Session Initiation Protocol (SIP) Trunk Market
Telecommunications Infrastructure
Communication Repeater Market
Telecommunications Infrastructure
Fixed Telephony Service Market
Telecommunications Infrastructure
5G Infrastructure Market
Telecommunications Infrastructure
Canada Telecom Towers Market
Telecommunications Infrastructure
Global Optical Transport Network (OTN) Equipment Market
Telecommunications Infrastructure
Nigeria Telecom Tower Market
Telecommunications Infrastructure
Spain Telecom Towers Market
Telecommunications Infrastructure
Philippines Telecom Towers Market