
 Global Integrated Telecom Infrastructure Market | 2026-2036
Global Integrated Telecom Infrastructure Market Size, Share, and Industry Trends Forecast 2026-2036
Global Integrated Telecom Infrastructure Market Foresight
Smart manufacturing and autonomous logistics are restructuring demand patterns across the Global Integrated Telecom Infrastructure Market. Huawei Technologies Co. Ltd leverages its end-to-end 5G portfolio to dominate integrated radio access and transport solutions for industrial private networks. Nokia Corporation anchors European supply chains through its Open RAN-compliant base station and core network equipment programs. Ericsson competes aggressively in North American markets with its cloud-native 5G core and spectrum-sharing technologies.
Integrated telecom infrastructure encompasses the unified hardware, software, and management systems that enable end-to-end voice, data, and video transmission across terrestrial and wireless networks, typically operating at frequencies from sub-1 GHz to millimeter-wave bands with latency targets below 10 milliseconds for ultra-reliable low-latency communications. Its primary purpose is to provide scalable, interoperable connectivity platforms that bridge access networks, core switching fabrics, and customer termination points for commercial and public service delivery. Base stations and core network equipment capture the dominant share of capital expenditure as carriers prioritize coverage expansion and network slicing capabilities. SD-WAN and 5G NR represent the fastest-growing technology segments, driven by enterprise demand for software-defined branch connectivity and massive machine-type communications.
FCC spectrum auction frameworks in the United States, EU 5G security requirements under the Cybersecurity Act, and India's TRAI recommendations on network interoperability collectively shape equipment certification timelines and vendor eligibility across major procurement markets. GDPR and emerging national data localization mandates further constrain how network management systems handle subscriber metadata and traffic analytics across jurisdictional boundaries. Stakeholders must monitor evolving Open RAN interoperability standards and sovereign cloud requirements to align R&D roadmaps with shifting compliance thresholds.
Market Dynamics
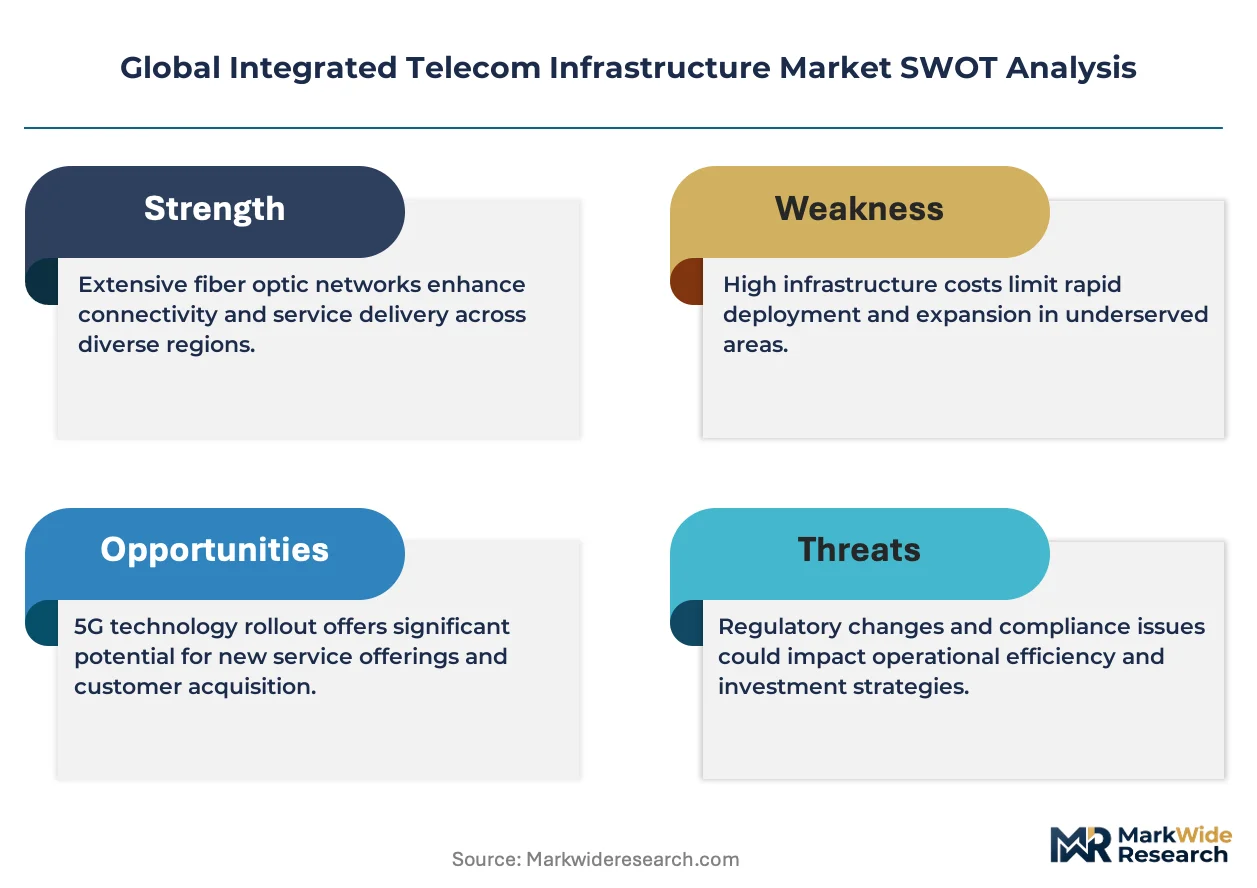
Open RAN disaggregation and sovereign cloud mandates are fragmenting traditional vendor lock-ins while accelerating procurement diversification among tier-one carriers and enterprise private network operators.
Growth Catalysts
- BharatNet rural fiber mandate:India's universal service obligation fund is subsidizing last-mile fiber-to-the-home deployments across 600,000 villages, creating sustained equipment demand for optical line terminals and passive optical network gear.
- EU 5G security certification:The Cybersecurity Act's Common Criteria certification for network equipment is channeling public procurement toward verified vendors, accelerating replacement cycles in European critical infrastructure sectors.
- Millimeter-wave spectrum allocation:Dense urban environments in Japan, South Korea, and the United States are absorbing massive MIMO antenna arrays and beamforming hardware to support fixed wireless access competition.
Market Restraints
- Semiconductor fabrication concentration:Advanced node chipsets for baseband units and radio frequency transceivers depend on Taiwan and South Korean foundry capacity, exposing equipment lead times to geopolitical supply disruptions.
- GDPR data localization friction:Network management systems handling subscriber metadata face jurisdictional constraints that complicate cloud-native core deployments across European multi-country footprints.
- Copper and rare earth input volatility:Power amplifier substrates and cable sheathing face price instability from concentrated mining operations in the Democratic Republic of Congo and Chile.
Strategic Opportunities
- Indonesia's Palapa Ring completion:The archipelago's undersea fiber backbone termination points are creating demand for terrestrial backhaul aggregation and edge data center co-location in secondary cities.
- AI-driven network automation convergence:Machine learning inference engines are integrating with software-defined radio platforms to enable real-time spectrum optimization and predictive maintenance in private 5G deployments.
- US IRA clean energy incentives:Tax credits for renewable-powered data centers are redirecting capital toward solar-integrated telecom shelters and lithium-ion backup systems in Texas and Arizona.
Industry Challenges
- Open RAN interoperability certification delays:Multi-vendor integration testing for fronthaul interfaces and orchestration layers is extending deployment timelines by 30-40% compared to single-vendor stacks.
- Legacy TDM migration complexity:Circuit-switched voice infrastructure in established markets requires phased decommissioning that constrains capital allocation toward packet-core modernization.
- Specialized RF engineering scarcity:Millimeter-wave propagation modeling and massive MIMO beamforming optimization skills are concentrated among a shrinking cohort of experienced practitioners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Integrated Telecom Infrastructure Market |
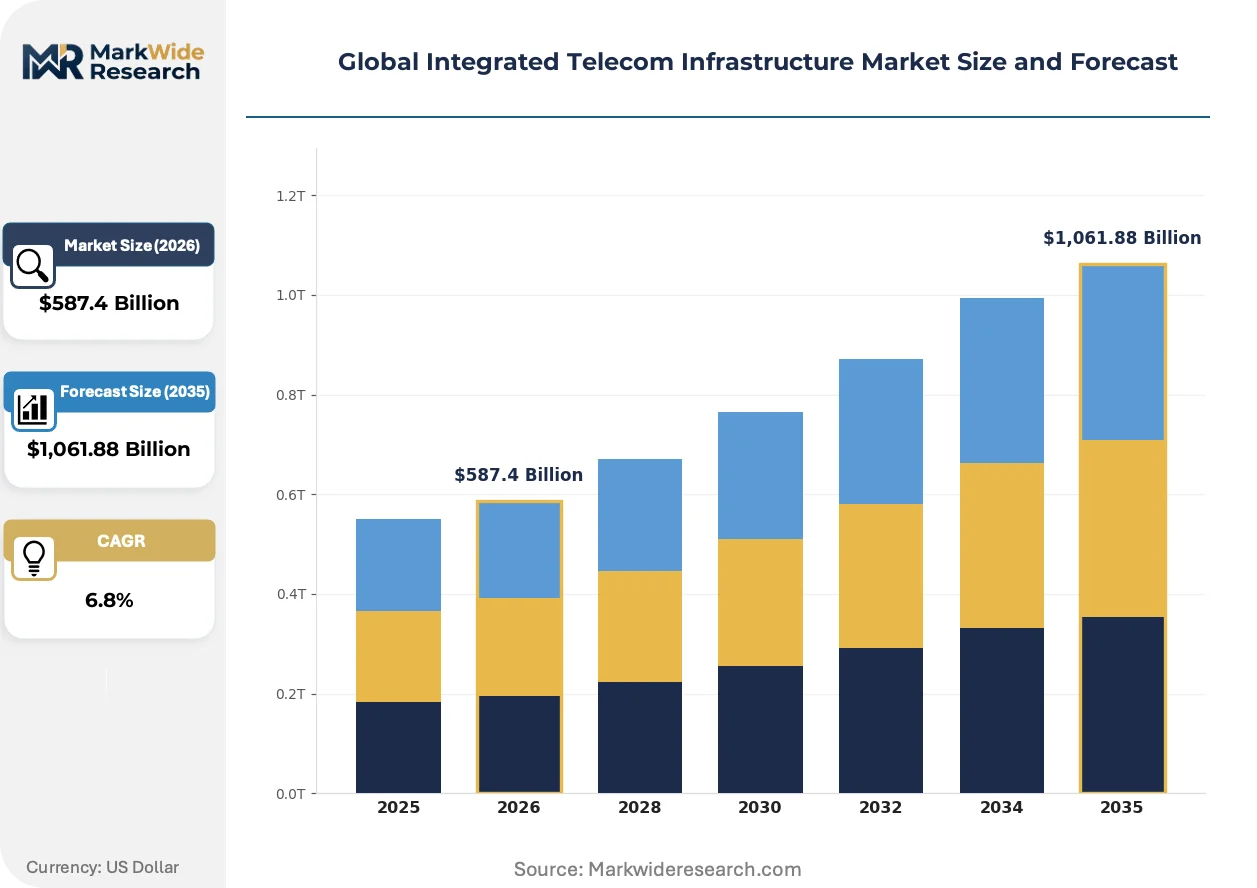
| Market Size in 2026 | $587.4 Billion |
| Market Size in 2035 | $1,061.88 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Base Stations, Core Network Equipment, Transmission Equipment, Customer Premises Equipment, Network Management Systems Technology: 5G NR, LTE, MPLS, SD-WAN, DWDM, Microwave Application: Mobile Broadband, Fixed Wireless Access, IoT Connectivity, Cloud Services Support, VoIP, Content Delivery Networks End User: Telecom Operators, Data Centers, Internet Service Providers, Government Agencies, System Integrators |
| Companies Covered | Huawei Technologies Co. Ltd, Nokia Corporation, Ericsson, Cisco Systems Inc, ZTE Corporation, Samsung Electronics Co. Ltd, Juniper Networks Inc, Ciena Corporation, NEC Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Integrated Telecom Infrastructure Market Shifts & Advancements
Telecom infrastructure is undergoing architectural decoupling that separates hardware from software control planes, enabling multi-vendor composability while complicating system integration and testing protocols.
Containerized network functions are modularizing the 5G core into microservices that deploy across hybrid cloud environments. Enterprise manufacturers and mining operators are adopting these disaggregated cores for on-premises private networks within 18-month procurement cycles. This modularization is compressing vendor margins on integrated hardware-software bundles while expanding addressable market for pure-play software licensors.
The EU AI Act's risk classification framework for automated network management systems is mandating human-in-the-loop oversight for traffic optimization algorithms in critical infrastructure. Equipment vendors must now document training data provenance and decision transparency for core network AI modules. German and French carriers are responding by segregating AI-driven functions into sandboxed edge deployments with explicit audit trails.
Enterprise buyers are consolidating vendor relationships through managed service contracts that bundle equipment, software licenses, and operational support into single accountability structures. This displaces traditional capex-heavy procurement where carriers owned and operated discrete network layers. The shift is most visible in North American healthcare and logistics verticals where IT-OT convergence demands guaranteed service-level agreements across wireless and wireline domains.
Global Integrated Telecom Infrastructure Market Segmentation
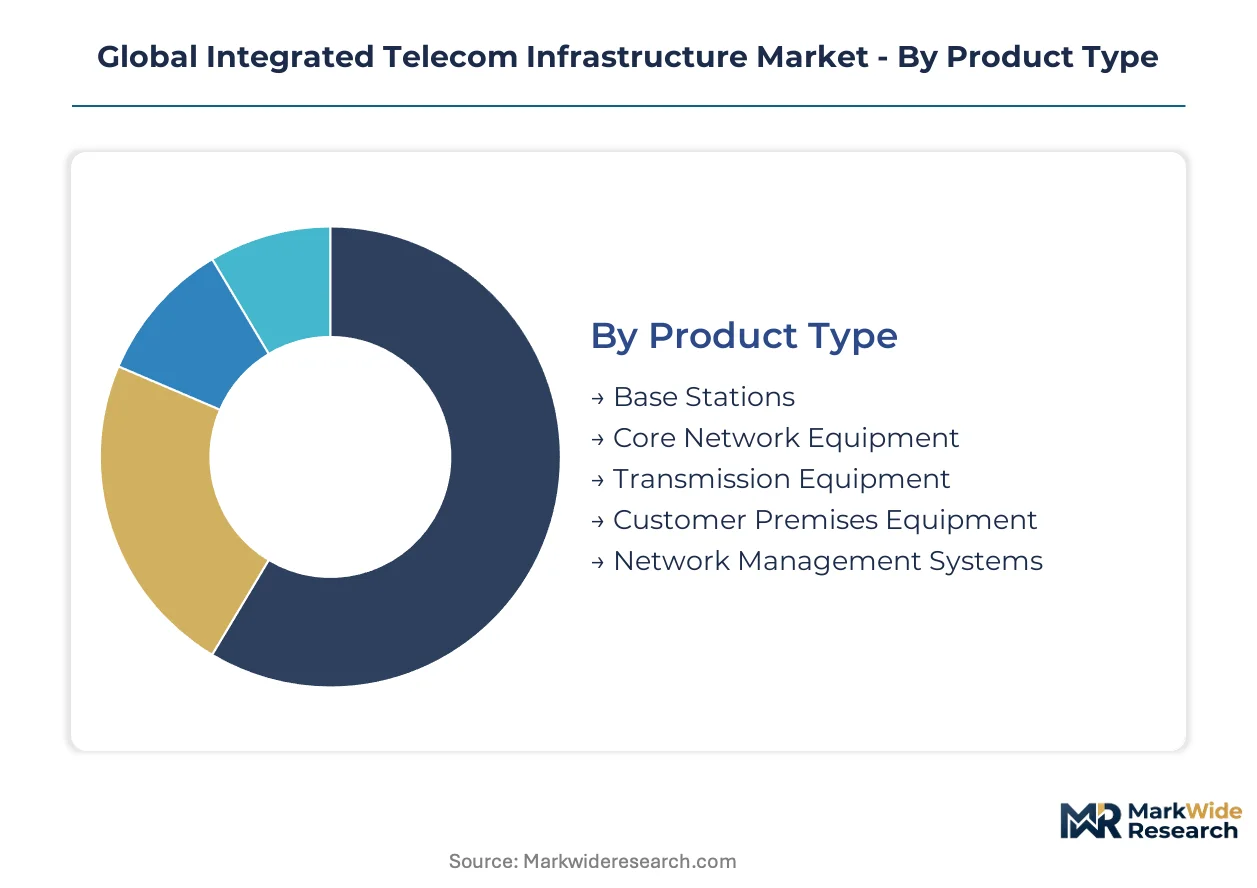
Segmentation in integrated telecom infrastructure reveals how procurement priorities diverge across deployment contexts. Equipment specifications, technology generations, and buyer sophistication create distinct commercial pockets with varying margin profiles and vendor qualification barriers.
Product Type:
Customization intensity spans from standardized mass-market units to engineered-to-order systems requiring site-specific calibration and integration services.
- Base Stations:Radio access nodes integrate antenna arrays, baseband processing, and power systems into weather-hardened enclosures for macro, small cell, and indoor deployments. India's 5G spectrum auctions and BharatNet rural mandates are concentrating orders for massive MIMO units and compact microcells. Towercos in Indonesia and Vietnam are driving demand for multi-band, multi-operator configurations to optimize tenancy ratios.
- Core Network Equipment:Packet gateways, session management functions, and subscriber databases form the centralized switching fabric enabling network slicing and edge orchestration. European carriers under EU 5G security certification requirements are replacing legacy hardware with cloud-native, disaggregated core instances. GDPR data localization constraints are forcing architectural choices that separate control plane functions across jurisdictional boundaries.
- Transmission Equipment:Optical transport and microwave backhaul systems bridge aggregation points to core facilities.
- Customer Premises Equipment:Optical network terminals, residential gateways, and enterprise routers terminate subscriber connections.
- Network Management Systems:Orchestration platforms and element management software provision, monitor, and optimize multi-vendor infrastructure.
Most installed capacity flows through Base Stations. Expansion is steepest in Core Network Equipment.
Technology:
Cost tier differentiation separates premium licensed-spectrum platforms from unlicensed and shared-spectrum alternatives with lower deployment barriers.
- 5G NR:New Radio specifications enable enhanced mobile broadband, ultra-reliable low-latency communications, and massive machine-type communications through flexible numerology and advanced antenna techniques. Japanese and South Korean carriers are absorbing millimeter-wave massive MIMO arrays for dense urban fixed wireless access competition. Standalone core deployments in Germany and France are accelerating procurement of 5G NR gNodeB units with Open RAN fronthaul interfaces.
- SD-WAN:Software-defined wide area networking abstracts transport underlay from policy-driven overlay routing, enabling enterprise branch connectivity across hybrid MPLS and broadband access. North American healthcare and logistics verticals are consolidating vendor relationships through managed SD-WAN contracts bundling equipment, licenses, and operational support. The shift from capex-heavy procurement to subscription-based consumption is compressing hardware margins while expanding addressable market for pure-play software licensors.
- LTE:Long Term Evolution remains the workhorse for coverage continuity and IoT narrowband deployments.
- MPLS:Multi-Protocol Label Switching persists in enterprise VPN and wholesale carrier services requiring deterministic quality of service.
- DWDM:Dense wavelength division multiplexing scales fiber capacity through coherent optical transmission.
- Microwave:Point-to-point and point-to-multipoint radio links provide rapid backhaul deployment where fiber trenching is uneconomical.
Most installed capacity flows through LTE. Expansion is steepest in SD-WAN.
Application:
Volume concentration versus margin opportunity splits this category between high-scale consumer services and specialized enterprise connectivity with stringent service level agreements.
- Mobile Broadband:Consumer and enterprise data services over cellular networks generate the dominant traffic volume requiring continuous capacity expansion. India's urban network densification and rural fiber backhaul through BharatNet are creating sustained demand for macro and small cell infrastructure. Indonesian operators completing Palapa Ring terrestrial termination are investing in backhaul aggregation to feed mobile broadband demand in secondary cities.
- IoT Connectivity:Massive machine-type communications and critical IoT applications connect sensors, actuators, and industrial controllers through licensed and unlicensed spectrum. German automotive manufacturers and French utility operators are deploying private 5G networks with on-premises core instances for predictive maintenance and real-time process control. EU AI Act risk classifications are mandating human-in-the-loop oversight for automated network management in these critical infrastructure contexts.
- Fixed Wireless Access:Residential and business broadband delivery over cellular spectrum competes with wireline alternatives.
- Cloud Services Support:Hyperscale data center interconnect and edge computing infrastructure enable distributed cloud workloads.
- VoIP:Packetized voice services replace circuit-switched infrastructure with session initiation protocol-based delivery.
- Content Delivery Networks:Edge caching and traffic localization reduce latency for streaming and web services.
Most installed capacity flows through Mobile Broadband. Expansion is steepest in IoT Connectivity.
End User:
Customer type determines procurement sophistication, with tier-one carriers demanding full system integration against enterprise and government buyers prioritizing managed service accountability.
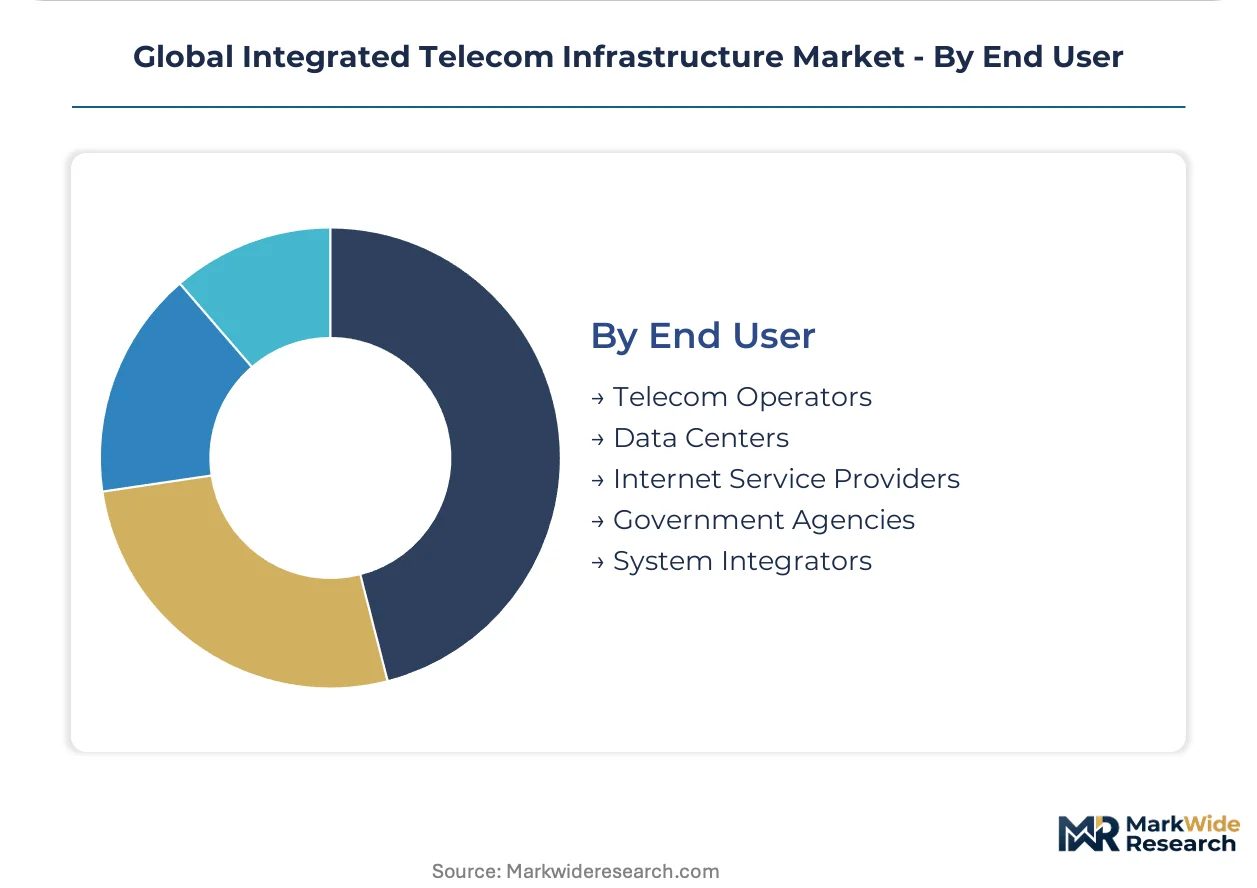
- Telecom Operators:Mobile and fixed network service providers own and operate national infrastructure with multi-billion dollar capital programs and multi-vendor interoperability requirements. FCC spectrum auction frameworks in the United States and EU 5G security certification under the Cybersecurity Act are channeling procurement toward verified vendors with documented supply chain provenance. Open RAN disaggregation is fragmenting traditional vendor lock-ins while extending multi-vendor integration timelines.
- Data Centers:Colocation, hyperscale, and edge facilities require switching, optical transport, and interconnection infrastructure scaled to cloud computing workload growth. US IRA clean energy tax credits are redirecting capital toward solar-integrated telecom shelters and lithium-ion backup systems in Texas and Arizona. Containerized network functions are modularizing deployments across hybrid cloud environments with 18-month procurement cycles.
- Internet Service Providers:Fixed broadband and wholesale connectivity providers compete on coverage and price with varying technology neutrality.
- Government Agencies:Defense, public safety, and universal service programs demand secure, resilient infrastructure with sovereign control requirements.
- System Integrators:Engineering and construction firms aggregate multi-vendor equipment into turnkey network deployments for carrier and enterprise clients.
Most installed capacity flows through Telecom Operators. Expansion is steepest in Data Centers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's BharatNet fiber mandate and 5G spectrum allocations concentrate the most visible infrastructure buildout, while Japan, Germany, the United States, and Indonesia each anchor distinct technology deployment patterns across access, core, and transport layers.
India
BharatNet Phase III targets 600,000 villages with subsidized fiber-to-the-home, absorbing massive volumes of optical line terminals and passive optical network equipment. TRAI interoperability recommendations channel procurement toward multi-vendor radio access networks. Towercos in Maharashtra and Gujarat densify urban 5G coverage with massive MIMO macro cells and street-level small cells.
Japan
Millimeter-wave spectrum allocations in dense metropolitan corridors drive absorption of massive MIMO antenna arrays and beamforming hardware for fixed wireless access competition. METI spectrum frameworks prioritize local 5G private network licenses for industrial zones. Osaka and Nagoya manufacturing clusters deploy on-premises 5G cores for autonomous logistics and predictive maintenance.
Germany
EU Cybersecurity Act Common Criteria certification accelerates replacement cycles in critical infrastructure sectors with documented supply chain provenance requirements. GDPR data localization constraints force architectural separation of control plane functions across jurisdictional boundaries. Bavarian automotive manufacturers anchor private 5G network deployments with cloud-native core instances and Open RAN-compliant base stations.
United States
FCC spectrum auction frameworks channel tier-one carrier procurement toward verified vendors with documented interoperability testing. IRA clean energy tax credits redirect capital toward solar-integrated telecom shelters and lithium-ion backup systems. Texas and Arizona data center clusters absorb containerized network functions across hybrid cloud environments with compressed procurement cycles.
Indonesia
Palapa Ring undersea fiber backbone completion creates demand for terrestrial backhaul aggregation and edge data center co-location in secondary cities. National broadband universal service obligations subsidize last-mile connectivity in underserved archipelago regions. Surabaya and Medan urban corridors densify mobile broadband infrastructure to absorb backhaul capacity from submarine cable landing points.
Global Integrated Telecom Infrastructure Market Competitive Landscape
Portfolio diversification dominates the current landscape as incumbent vendors restructure around disaggregated architectures. The market exhibits tiered concentration with three to four integrated suppliers commanding tier-one carrier relationships, flanked by specialist radio and optical component vendors. Two archetypes prevail: end-to-end portfolio holders spanning radio access through core networks, and pure-play software licensors capitalizing on cloud-native core modularization. M&A activity and Open RAN interoperability certification investments constitute the primary competitive moves.
Within the integrated portfolio tier, Huawei Technologies Co. Ltd and Nokia Corporation exemplify divergent geographic positioning strategies, while Ericsson anchors North American market access through cloud-native core and spectrum-sharing technology representation. ZTE Corporation and Samsung Electronics Co. Ltd occupy positions bridging radio access hardware with emerging Open RAN software layers. Cisco Systems Inc and Juniper Networks Inc sit within the enterprise and data center interconnect specialization tier, with Ciena Corporation and NEC Corporation representing optical transport and submarine cable system archetypes respectively.
| Leading Market Players |
|---|
| Huawei Technologies Co. Ltd |
| Nokia Corporation |
| Ericsson |
| Cisco Systems Inc |
| ZTE Corporation |
| Samsung Electronics Co. Ltd |
| Juniper Networks Inc |
| Ciena Corporation |
| NEC Corporation |
| Others |
Supply & Pricing Matrix
Sovereign-backed equipment vendors in China and state-affiliated carriers across India and Indonesia anchor procurement financing patterns that compress payment cycles for radio access hardware while extending capital lock-up periods for optical transport suppliers. This ownership structure concentrates pricing power among integrated portfolio holders capable of bundling base stations with managed service contracts, forcing specialist component vendors into margin-concession negotiations to maintain tenancy on multi-vendor bills of materials.
Pricing Analysis
Distributor margin layers in emerging market supply chains absorb 12-18 points of equipment value before reaching tower companies and rural broadband contractors. Three-tier pricing structure across premium certified, standard interoperable, and economy single-vendor levels differentiates base station procurement, with EU Cybersecurity Act Common Criteria certification commanding substantial premiums over uncertified alternatives. Pricing pressure stems from Open RAN disaggregation enabling mix-and-match component sourcing that fragments traditional bundled premiums. Enterprise private network operators exhibit lowest price sensitivity due to outcome-based service level requirements, while rural universal service obligation fund recipients operate under rigid capital constraints.
Supply Chain Analysis
Advanced node chipset supply rests on Taiwan Semiconductor Manufacturing and Samsung Foundry capacity for baseband processing units and millimeter-wave radio frequency transceivers. Power amplifier substrates draw from concentrated mining operations in the Democratic Republic of Congo and Chile, while optical fiber preform manufacturing centers on American, Japanese, and Chinese specialty glass producers. Single-source vulnerability in Taiwan and South Korean foundry exposure creates lead time volatility that propagates through equipment delivery schedules. Distribution runs through carrier-direct procurement teams for tier-one accounts, with system integrators and regional distributors handling secondary city and rural deployments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where EU Cybersecurity Act certification mandates and India's BharatNet rural fiber obligations generate sustained equipment replacement cycles independent of pure demand growth. Compliance-driven procurement creates defensive revenue visibility for vendors with documented supply chain provenance.
For Market Incumbents: Lock in carrier relationships through Open RAN interoperability certification investments that extend multi-vendor integration timelines and raise switching costs. Prioritize backward integration into gallium nitride power amplifier substrate supply to mitigate rare earth input volatility from Congolese mining concentration. Defend against emerging cloud-native software licensors by embedding AI-driven network automation modules into managed service contracts with explicit performance guarantees. For New Entrants and Emerging Players: Mid-sized German automotive manufacturers and French utility operators represent underserved buyer archetypes seeking private 5G networks with sovereign cloud core instances and EU AI Act-compliant human-in-the-loop oversight. Indonesian secondary cities completing Palapa Ring terrestrial termination offer lowest competitive density for edge data center co-location bundled with backhaul aggregation. Pursue system integrator partnerships rather than carrier-direct sales to bypass incumbent relationship lock-in. For Investors and Strategic Acquirers: Valuations sit cheapest among optical transport specialists with submarine cable landing point expertise and established relationships with Indonesian and Philippine archipelago operators. Long-term viability hinges on containerized network function software margins expanding as hardware commoditization compresses radio access equipment yields. Watch Open RAN interoperability testing standardization as the inflection signal—accelerated certification protocols would compress multi-vendor integration penalties and erode incumbent integration service premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Interoperability Certification | EU Cybersecurity Act verification accelerates vendor qualification for European critical infrastructure procurement. |
| Backward Integration into RF Components | Gallium nitride substrate captive supply mitigates rare earth price volatility from concentrated mining jurisdictions. |
| Private 5G Network System Integration | German automotive manufacturing clusters demand on-premises core instances with predictive maintenance AI modules. |
| Edge Data Center Co-location Expansion | Indonesian Palapa Ring termination points create terrestrial backhaul aggregation demand in Surabaya and Medan. |
| AI-Driven Network Automation Development | Machine learning inference engines enable real-time spectrum optimization for enterprise private network deployments. |
Research Methodology
Bottom-up carrier capital expenditure modeling reconciled against top-down equipment shipment tracking forms the analytical core of this study. Primary interviews with network planning executives at tier-one mobile operators, procurement leads at tower companies, regulatory affairs directors at equipment vendors, and field engineers at system integrators were validated against secondary sources including FCC spectrum auction filings, EU Cybersecurity Act certification databases, TRAI interoperability recommendations, and SEC 10-K disclosures from listed infrastructure suppliers.
Input-output matrices map radio access unit deployments to spectrum allocation timelines, fiber backhaul investments to BharatNet phase completions, and core network modernization to 5G standalone core migration schedules across the projection horizon. Segmentation dimensions include product type, technology generation, application vertical, and end-user procurement sophistication, with CAGRs derived from equipment vendor order backlog analysis and carrier disclosed capital intensity ratios. Forecast inputs incorporate millimeter-wave spectrum release calendars and sovereign cloud mandate implementation timelines.
Underlying measurement precision varies by segment; base station shipment volumes carry tighter precision than emerging private 5G network deployments where procurement opacity limits visibility. Forecasts reflect assumptions around Open RAN interoperability testing standardization, foundry capacity allocation priorities, and rare earth supply chain stability that warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Asia Pacific Voice Over LTE Market
Telecommunications Infrastructure
Africa Telecom Towers and Allied Market
Telecommunications Infrastructure
Global Mobile and Wireless Backhaul Equipment Market
Telecommunications Infrastructure
Global Telecom Towers Market
Telecommunications Infrastructure
5G Infrastructure Equipment Market
Telecommunications Infrastructure
Fixed Telephony Service Market
Telecommunications Infrastructure
Session Initiation Protocol (SIP) Trunk Market
Telecommunications Infrastructure
5G Infrastructure Market
Telecommunications Infrastructure
Spain Telecom Towers Market
Telecommunications Infrastructure
5G Network Infrastructure Market
Telecommunications Infrastructure
Global Telecom Cable Market
Telecommunications Infrastructure
Vietnam Telecom Towers Market
Telecommunications Infrastructure
Communication Repeater Market
Telecommunications Infrastructure
Broadcast Infrastructure Market
Telecommunications Infrastructure
Global Cellular Networks Market
Telecommunications Infrastructure
France Telecom Towers Market