
 China Telecom Towers Market | 2026-2036
China Telecom Towers Market Size, Share, and Industry Trends Forecast 2026-2036
China Telecom Towers Market Insights
MIIT's unified infrastructure sharing mandates is broadening the cost-of-entry calculus for new tower operators. China Tower Corporation Limited leverages its state-backed scale to dominate shared infrastructure deployment across all provincial tier cities. China Mobile anchors its competitive position through captive ownership of macro sites in dense urban corridors. ZTE Corporation specializes in integrated antenna-tower systems that reduce civil works expenditure for carriers.
China telecom towers are steel or reinforced concrete structures engineered to support multiple antenna arrays, transmission equipment, and power systems at heights typically ranging from 30 to 150 meters, manufactured through hot-dip galvanization of welded lattice or tubular sections to ensure structural integrity against wind loads and corrosion over 25-30 year design lives. These structures serve as the physical backbone for wireless signal propagation, enabling coverage extension and capacity densification for mobile and fixed wireless networks. 5G deployment models command premium positioning as carriers prioritize millimeter-wave small cell integration atop existing macro towers, while greenfield installations face margin compression due to rising land acquisition costs in eastern coastal provinces. Rooftop installation types represent the fastest-growing structural category as urban densification limits ground-based construction permits in Shenzhen, Chengdu, and Hangzhou municipal jurisdictions.
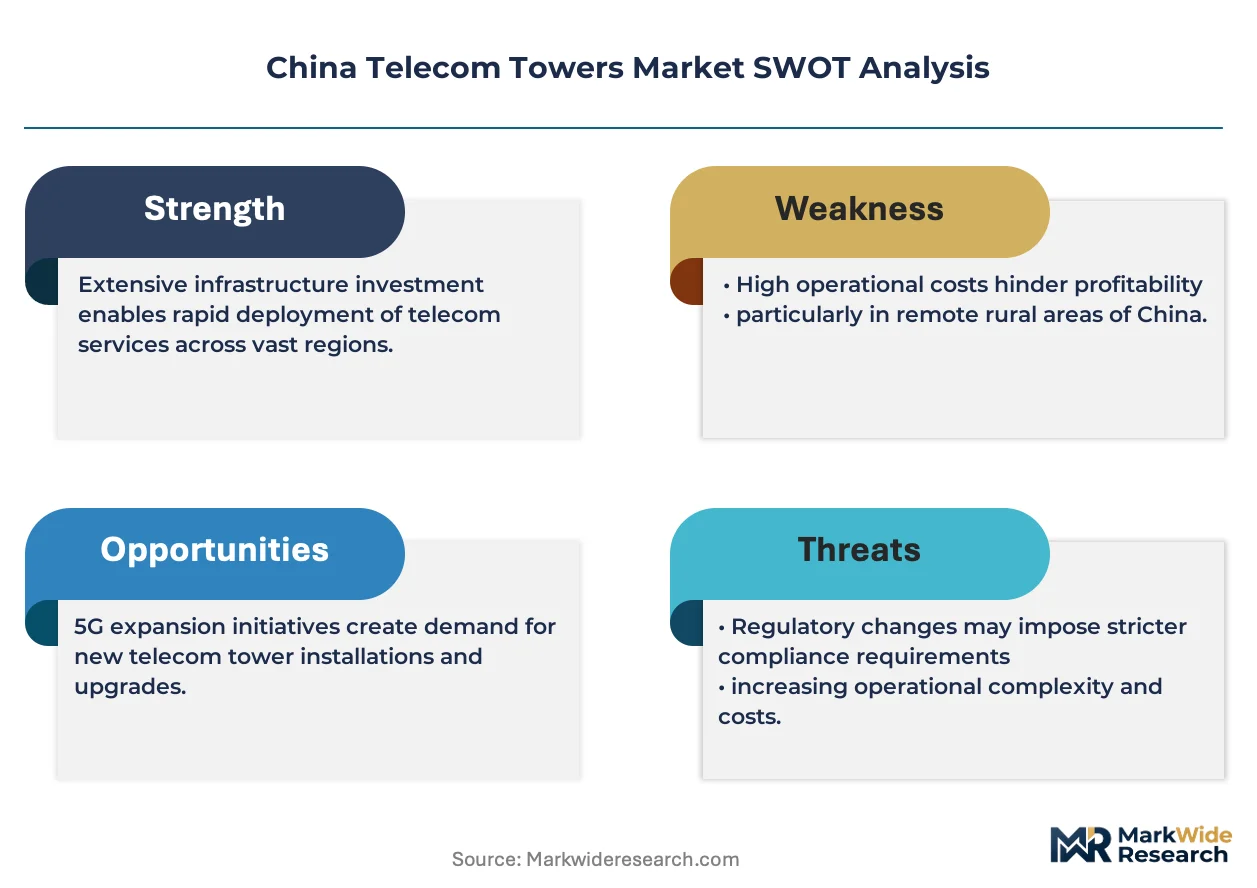
MIIT spectrum allocation directives and GB standards for structural wind resistance shape tower design specifications and equipment interoperability requirements across all provincial deployments. The national dual carbon goals from MEE impose energy efficiency benchmarks on tower power systems, accelerating lithium battery and solar hybrid adoption at remote sites. Stakeholders must monitor municipal zoning fragmentation where city-level planning bureaus increasingly restrict tower heights and visual impact near cultural heritage districts.
Market Dynamics
MIIT's infrastructure sharing mandates have fundamentally restructured site economics, forcing carriers to surrender captive tower assets to third-party operators while concentrating procurement leverage in state-backed aggregators. This policy-driven consolidation now dictates deployment velocity across all provincial tier classifications.
Growth Catalysts
- Rural broadband mandates:Western provinces including Guizhou and Sichuan require specialized guyed mast structures to overcome mountainous terrain constraints. Steel lattice tower orders from mobile network operators accelerate as universal service obligations tighten.
- GB wind resistance standards:Updated national structural codes mandate upgraded foundation specifications for existing macro sites. Retrofit demand generates recurring revenue streams for tower engineering services.
- Lithium battery hybridization:Remote site electrification requirements under MEE dual carbon goals drive solar-storage integration at off-grid installations. Power system upgrades expand addressable equipment attach rates per tower.
Market Restraints
- Land acquisition cost inflation:Eastern coastal municipalities including Shenzhen and Hangzhou impose escalating land use fees for greenfield tower construction. Ground-based permits face effective moratoria in dense urban cores.
- Steel price volatility:Hot-dip galvanized lattice sections constitute the dominant material input. Raw material cost swings compress fabrication margins for domestic tower manufacturers.
- Height restriction fragmentation:Municipal planning bureaus impose inconsistent visual impact limits near cultural heritage districts. Zoning heterogeneity extends site approval timelines unpredictably.
Strategic Opportunities
- Rooftop installation expansion:Urban densification in Chengdu and Hangzhou shifts deployment toward building-mounted structures. This structural category bypasses ground-based permitting constraints entirely.
- Millimeter-wave small cell integration:5G densification requirements create antenna co-location demand atop existing macro towers. Multi-tenant equipment stacking raises per-site revenue yields.
- Provincial tier-3 penetration:Western region network coverage gaps present unsaturated addressable inventory. Lower incumbent density reduces site acquisition competition.
Industry Challenges
- Structural engineering talent scarcity:Specialized expertise in guyed mast design for high-altitude wind loading remains concentrated among state-designated research institutes. Private operators face recruitment bottlenecks for certified design personnel.
- NMPA equipment certification timelines:Transmission equipment interoperability testing protocols extend product qualification cycles. Vendor lock-in risks intensify as carriers prioritize pre-certified supplier relationships.
- Legacy site integration complexity:Existing 4G antenna configurations constrain 5G equipment mounting geometries. Civil works modifications at occupied towers disrupt live network operations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | China Telecom Towers Market |
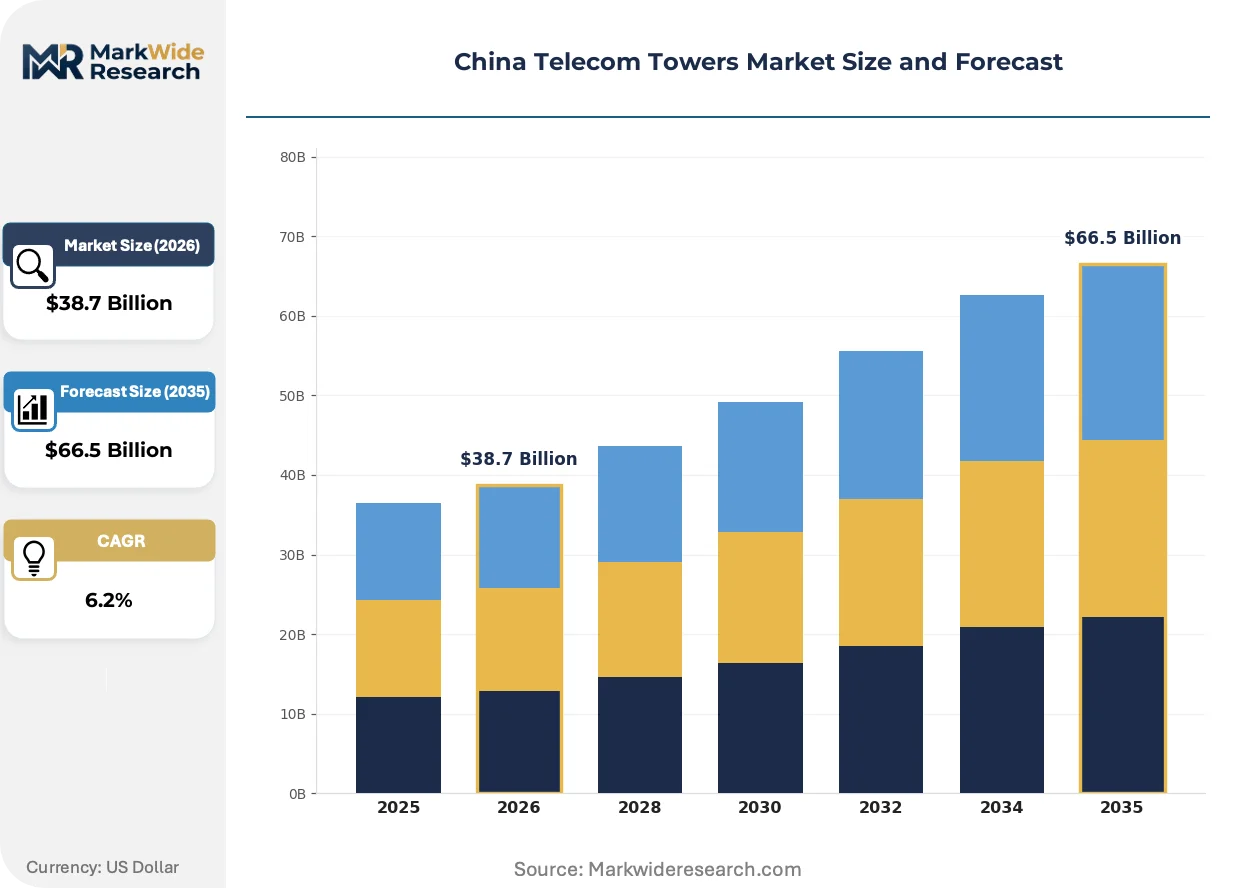
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $66.5 Billion |
| CAGR (2026 – 2036) | 6.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: 3G, 4G, 5G, Fiber Optic Installation Type: Outdoor, Indoor, Rooftop, Street Furniture Ownership Model: Carrier-Owned, Tower Company, Hybrid, Municipal Deployment Model: Greenfield, Brownfield, DAS, Small Cells |
| Companies Covered | China Tower Corporation Limited, China Mobile, China Unicom, China Telecom, ZTT Group, FiberHome Telecommunication Technologies Co Ltd, ZTE Corporation, Huawei Technologies Co Ltd, Datang Telecom Technology Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
China Telecom Towers Market Trends and Innovations
Active antenna system integration is compressing traditional tower-mounted equipment footprints while forcing structural load recalculations across the installed base. Three concurrent developments now reshape deployment economics and technical specifications simultaneously.
Integrated antenna-tower systems combine radiating elements with structural support members in unified factory-assembled modules. China Mobile and China Unicom procurement teams now specify these configurations for dense urban corridors where crane access is restricted. The technology is converging with modular foundation systems that eliminate poured concrete curing delays, compressing site activation timelines from weeks to days.
MIIT spectrum allocation directives now mandate specific antenna height and spacing parameters for millimeter-wave bands. These binding technical rules force structural modifications at existing macro sites before new frequency layers activate. Tower operators in eastern provinces face accelerated retrofit obligations as 5G-Advanced deployment windows tighten.
Carrier procurement teams now unbundle civil works from equipment supply in tender specifications. State-owned mobile operators issue separate contracts for structural engineering, power systems, and antenna integration. This purchasing fragmentation favors specialized subcontractors with municipal permitting relationships over full-service tower vendors.
China Telecom Towers Market Segmentation
Technology cycles and infrastructure sharing mandates fragment procurement patterns across China's telecom tower ecosystem. Each segmentation dimension carries distinct regulatory, cost, and deployment velocity implications for network operators.
Technology:
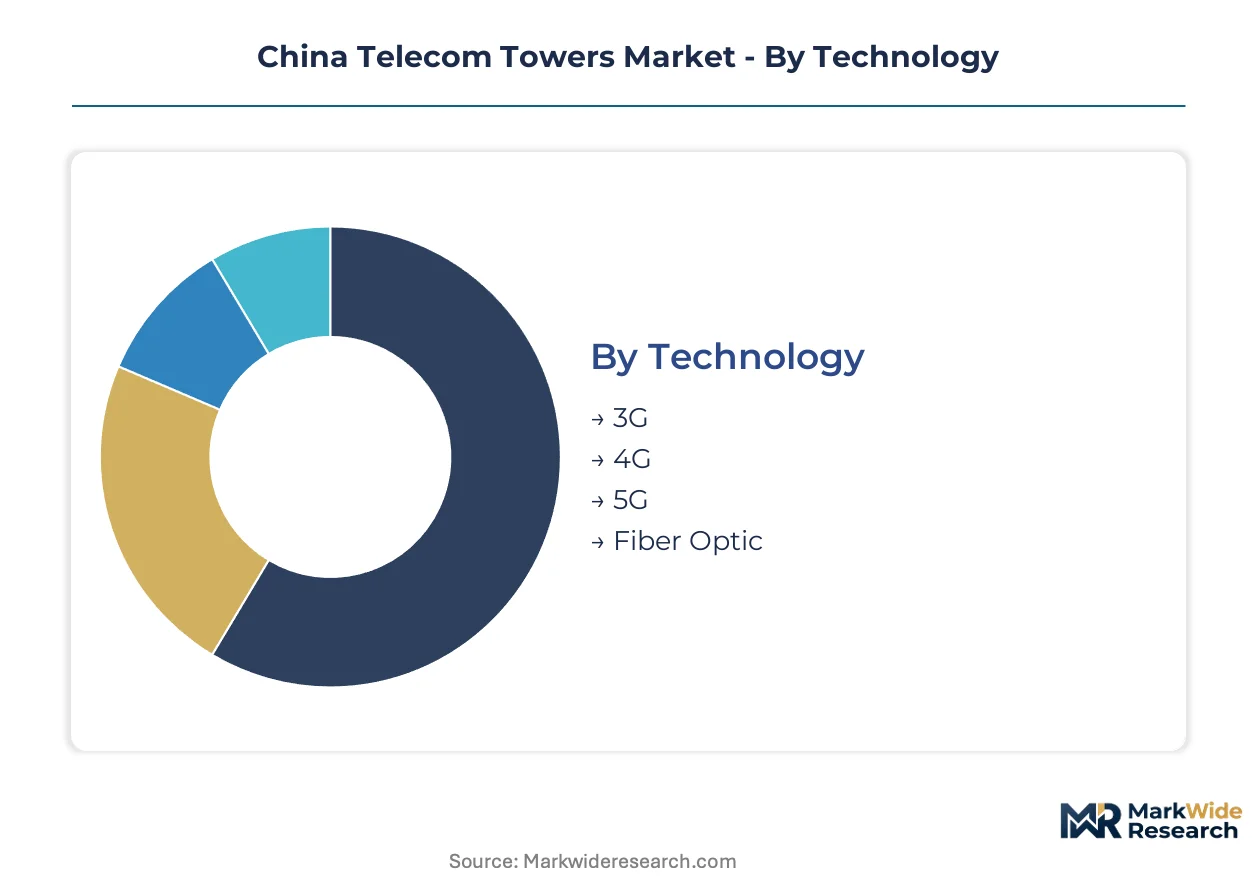
Upgrade cycles from legacy 3G through 5G-Advanced create overlapping equipment generations with divergent structural load requirements.
- 5G:Millimeter-wave integration demands reinforced mounting platforms and enhanced power systems atop existing macro structures. Guizhou and Sichuan provinces prioritize these upgrades for universal service coverage obligations.
- 4G:Refurbishment demand concentrates on antenna consolidation and wind resistance retrofits under updated GB standards. Eastern coastal carriers accelerate decommissioning schedules to recover urban real estate.
- 3G:Sunset protocols trigger site rationalization programs, with steel recovery value offsetting dismantling costs in tier-3 municipalities.
- Fiber Optic:Hybrid tower-fiber convergence enables fronthaul consolidation, reducing separate civil works expenditure for China Mobile and China Unicom.
5G sits at the top of the volume ranking, with fiber optic convergence climbing the fastest.
Installation Type:
Site economics shift dramatically based on ground access availability and municipal zoning enforcement intensity.
- Rooftop:Building-mounted structures bypass Shenzhen and Hangzhou ground-permitting moratoria entirely. Chengdu municipal planning bureaus fast-track visual impact assessments for concealed antenna configurations.
- Outdoor:Traditional steel lattice towers dominate western province deployment where terrain permits standard foundation systems. Land acquisition inflation in eastern coastal zones compresses greenfield margins.
- Indoor:Stadium and transportation hub densification drives distributed antenna system integration with structural concealment requirements.
- Street Furniture:Lamp post and utility pole co-location accelerates in Hangzhou smart city corridors under MIIT small cell mandates.
Rooftop deployment commands premium positioning in tier-1 cities, while street furniture gains share fastest in municipal smart infrastructure programs.
Ownership Model:
State policy reconfiguration has transferred asset control from vertically integrated carriers to specialized infrastructure aggregators.
- Tower Company:China Tower Corporation Limited dominates shared infrastructure procurement through MIIT-mandated asset transfers. Scale economies concentrate site acquisition leverage across all provincial tiers.
- Carrier-Owned:China Mobile retains strategic macro sites in dense urban corridors where co-location economics fail. Captive ownership persists for competitive differentiation in premium coverage zones.
- Hybrid:Joint venture structures emerge in tier-3 western provinces where universal service obligations exceed commercial returns.
- Municipal:City governments in cultural heritage districts acquire towers directly to enforce visual impact controls.
Tower company ownership sits at the top of the volume ranking, with hybrid models climbing the fastest in underpenetrated western regions.
Deployment Model:
Site activation velocity depends on legacy asset density and civil works modification complexity.
- Brownfield:Existing macro tower retrofit dominates 5G rollout economics, with antenna stacking and power system upgrades generating recurring engineering revenue.
- Greenfield:New construction concentrates in Guizhou and Sichuan coverage gaps where terrain necessitates guyed mast specialization.
- Small Cells:Millimeter-wave densification drives equipment miniaturization and rapid-deployment foundation systems in Shenzhen and Chengdu.
- DAS:Distributed antenna systems penetrate transportation infrastructure and commercial complexes where macro coverage proves insufficient.
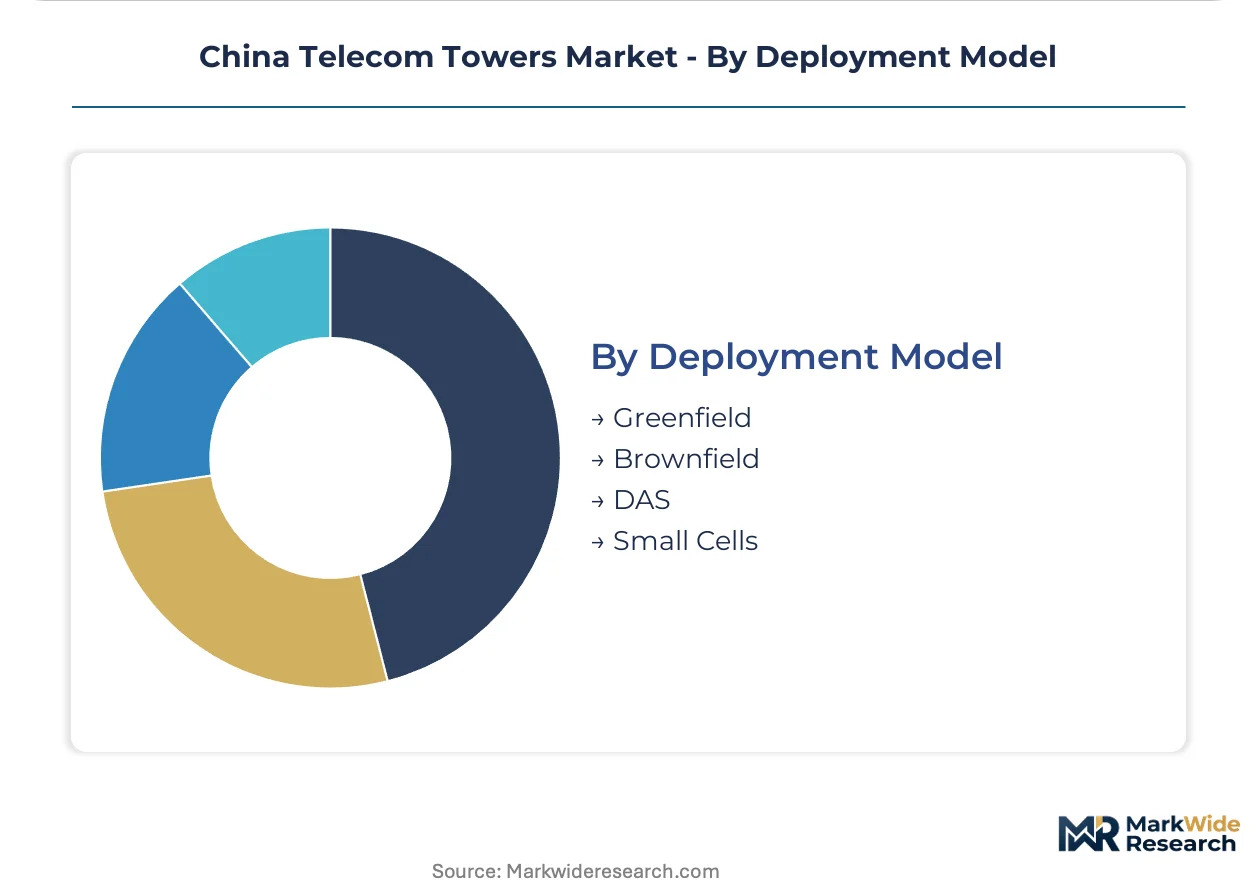
Brownfield deployment sits at the top of the volume ranking, with small cells climbing the fastest under MIIT 5G-Advanced timelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's telecom tower industry traces its modern scale to the 2014 MIIT-mandated consolidation that transferred carrier-owned assets to centralized infrastructure platforms. Provincial deployment patterns now reflect this state-coordinated foundation, with western expansion priorities diverging sharply from eastern retrofit imperatives.
Guizhou Province
Mountainous terrain and universal service obligations drive specialized guyed mast procurement from China Mobile and China Unicom. MIIT rural broadband mandates accelerate steel lattice tower deployment across karst topography where standard foundations prove infeasible. Guiyang municipal authorities fast-track concealed rooftop installations to bypass visual impact restrictions in heritage districts.
Sichuan Province
Chengdu's dense urban corridors generate premium demand for integrated antenna-tower systems that minimize crane access requirements. GB wind resistance standards mandate upgraded foundation specifications for macro sites in the Chengdu-Chongqing economic zone. Western Sichuan coverage gaps attract hybrid ownership joint ventures targeting tier-3 municipality penetration.
Guangdong Province
Shenzhen's ground-based permitting moratoria force deployment toward rooftop and street furniture configurations under smart city infrastructure programs. MIIT 5G-Advanced timelines compress retrofit windows for existing macro towers in the Pearl River Delta. Guangzhou municipal planning bureaus enforce strict height restrictions near cultural heritage zones.
Zhejiang Province
Hangzhou's urban densification shifts carrier procurement toward building-mounted structures that circumvent land acquisition cost inflation. NMPA equipment certification requirements extend vendor qualification cycles for transmission gear deployed across the Yangtze River Delta. Ningbo port logistics support steel lattice component fabrication for western province export.
Beijing-Tianjin-Hebei
Capital region network coverage mandates prioritize millimeter-wave small cell integration atop existing macro infrastructure. MEE dual carbon goals accelerate lithium battery hybridization at remote monitoring sites across Hebei coverage corridors. Tianjin's industrial base supplies hot-dip galvanized lattice sections for national distribution.
China Telecom Towers Market Competitive Landscape
The competitive structure tilts toward state-backed aggregators with MIIT-mandated asset transfer privileges. China Tower Corporation Limited concentrates procurement leverage across all provincial tier classifications through scale economies in site acquisition. Three archetypes dominate: centralized infrastructure platforms, vertically integrated carriers retaining strategic urban assets, and equipment-integrated specialists. Competitive moves center on municipal permitting relationship cultivation and power system upgrade bundling.
Among state-designated infrastructure platforms, China Tower Corporation Limited exemplifies the centralized aggregator archetype with MIIT-conferred deployment scale. Carrier-retained specialists include China Mobile, which occupies a position in dense urban corridor ownership where co-location economics underperform. Equipment-integrated technology providers such as ZTE Corporation sit within the integrated antenna-tower system segment, representing factory-assembled module specialization for crane-restricted deployment environments.
| Leading Market Players |
|---|
| China Tower Corporation Limited |
| China Mobile |
| China Unicom |
| China Telecom |
| ZTT Group |
| FiberHome Telecommunication Technologies Co Ltd |
| ZTE Corporation |
| Huawei Technologies Co Ltd |
| Datang Telecom Technology Co Ltd |
| Others |
Pricing and Supply Chain Analysis
State-backed infrastructure aggregators concentrate procurement leverage across all provincial tier classifications, anchoring contract-based long-term offtake as the dominant pricing model. China Tower Corporation Limited's scale economies compress supplier margins while locking in multi-year equipment supply agreements that insulate carriers from raw material volatility.
Pricing Analysis
Contract-based long-term offtake arrangements dominate tower procurement, with pricing stratifying across premium, standard, and economy tiers based on structural complexity and wind-load certification grade. Volume scale and MIIT-mandated standardization drive price differentiation between tier-1 urban deployments and tier-3 rural installations. Cost compression in greenfield construction is intensifying because land acquisition fees in eastern coastal provinces escalate unpredictably. Municipal planning bureaus exhibit highest price sensitivity for visual-impact-compliant configurations, while western province carriers prioritize structural performance over unit cost.
Supply Chain Analysis
Domestic-content mandates under MIIT equipment certification protocols reshape sourcing toward in-country fabrication of hot-dip galvanized lattice sections. Supply concentrates in Hebei, Jiangsu, and Shandong provinces where steel rolling capacity feeds tower manufacturing clusters. Raw material dependencies center on galvanized steel coil, zinc ingot, and structural bolts. Single-source vulnerability persists for specialized guyed mast engineering expertise concentrated at state-designated research institutes. Distribution runs through China Tower Corporation Limited's centralized procurement platform to carrier deployment sites.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Western province network coverage gaps present geographic-arbitrage opportunities as land acquisition costs in Guizhou and Sichuan run substantially below eastern coastal benchmarks, while MIIT rural broadband mandates guarantee demand visibility.
For Market Incumbents: To counter margin compression from steel price volatility and escalating land fees in tier-1 cities, China Tower Corporation Limited should deepen backward integration into hot-dip galvanization capacity in Hebei industrial corridors. Captive control over structural engineering certification pipelines defends against talent scarcity bottlenecks for high-altitude guyed mast design. For New Entrants and Emerging Players: Digital-channel route through municipal smart city procurement platforms offers lowest friction entry into Hangzhou and Shenzhen street furniture deployment. Rooftop installation specialization in Chengdu's dense urban corridors represents the most penetrable white-space segment. Joint venture structures with western province governments unlock hybrid ownership models where universal service obligations exceed commercial returns. For Investors and Strategic Acquirers: State-owned mobile operators are the most active acquirer in this space, consolidating captive tower assets before MIIT-mandated transfer deadlines. Long-term viability hinges on 5G-Advanced densification cycles and millimeter-wave small cell attach rates. Monitor NMPA equipment certification timeline compression as the critical signal for vendor consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Galvanization | Hebei-based captive steel processing mitigates raw material margin volatility for tower fabricators. |
| Rooftop Installation Specialization | Concealed antenna configurations bypass Shenzhen ground-permitting moratoria entirely. |
| Hybrid Ownership Joint Ventures | Tier-3 western province structures balance universal service obligations with commercial returns. |
| Millimeter-Wave Small Cell Integration | MIIT 5G-Advanced mandates drive antenna stacking revenue atop existing macro infrastructure. |
| Lithium Battery Hybridization | MEE dual carbon goals accelerate solar-storage adoption at remote Guizhou monitoring sites. |
Research Methodology
Bottom-up carrier deployment modeling reconciled against top-down steel fabrication capacity tracking forms the analytical core of this study. Primary interviews with China Tower Corporation Limited procurement directors, MIIT policy researchers, Hebei-based galvanization plant managers, and Guizhou provincial planning bureau officials combined with secondary validation from MIIT infrastructure white papers, GB structural standards documentation, China Mobile annual procurement disclosures, and provincial land use fee registries. Triangulation across these sources ensures demand-side and supply-side estimates converge.
Input-output matrices map tower installation volumes against steel consumption patterns, technology upgrade cycles, and ownership model transitions across the projection horizon. Segmentation dimensions modeled include technology generation, installation type, ownership structure, and deployment model, with provincial tier classifications as an industry-specific overlay. CAGRs derive from fitted growth curves against MIIT-mandated coverage targets and carrier capital expenditure trajectories. Forecast inputs incorporate GB wind resistance standard retrofit schedules and lithium battery hybridization adoption curves at remote sites.
The model assumes a particular technology adoption path; alternative pathways for active antenna system integration would alter the outlook if carrier procurement teams accelerate unbundling of civil works from equipment supply. Forecasts reflect assumptions regarding MIIT policy continuity, steel price mean reversion, and municipal zoning enforcement intensity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Global Mobile and Wireless Backhaul Equipment Market
Telecommunications Infrastructure
Microwave Backhaul System Market
Telecommunications Infrastructure
NLD and ILD Telecom Service Market
Telecommunications Infrastructure
Fixed Telephony Service Market
Telecommunications Infrastructure
Session Initiation Protocol (SIP) Trunk Market
Telecommunications Infrastructure
Small Cell Backhaul Market
Telecommunications Infrastructure
Telecom Network Infrastructure Market
Telecommunications Infrastructure
Asia Pacific Voice Over LTE Market
Telecommunications Infrastructure
Morocco Telecom Tower Market
Telecommunications Infrastructure
Canada Telecom Towers Market
Telecommunications Infrastructure
Fixed-Line Communications Market
Telecommunications Infrastructure
Brazil Telecom Tower Market
Telecommunications Infrastructure
Fiber to the X (FTTX) Market
Telecommunications Infrastructure
Carrier Infrastructure in Telecom Applications Market
Telecommunications Infrastructure
Philippines Telecom Towers Market
Telecommunications Infrastructure
Thailand Telecom Towers Market