
 Spain Telecom Towers Market | 2026-2036
Spain Telecom Towers Market Size, Share, and Industry Trends Forecast 2026-2036
Spain Telecom Towers Market Insights
Site-sharing and colocation bundling is repositioning procurement patterns across the Spanish tower ecosystem. Cellnex Telecom leverages Europe's largest independent tower portfolio to sustain pricing power in multi-tenant agreements. American Tower Corporation anchors its Iberian footprint through long-term lease contracts with converged mobile operators. Vantage Towers differentiates by specializing in energy-efficient tower designs that reduce operational expenditure for tenant carriers.
Telecom towers are steel or lattice structures engineered to heights between 15 and 100 meters, designed to mount antennas, remote radio heads, and transmission equipment for wireless signal propagation across designated coverage cells. Macro Cell installations dominate current revenue pools due to their role in wide-area 4G and 5G coverage, though Small Cell deployments are expanding fastest as urban capacity demands intensify. Ground Mounted towers retain the largest installed base, while Rooftop placements are gaining share in dense municipal zones where zoning restrictions limit greenfield construction.
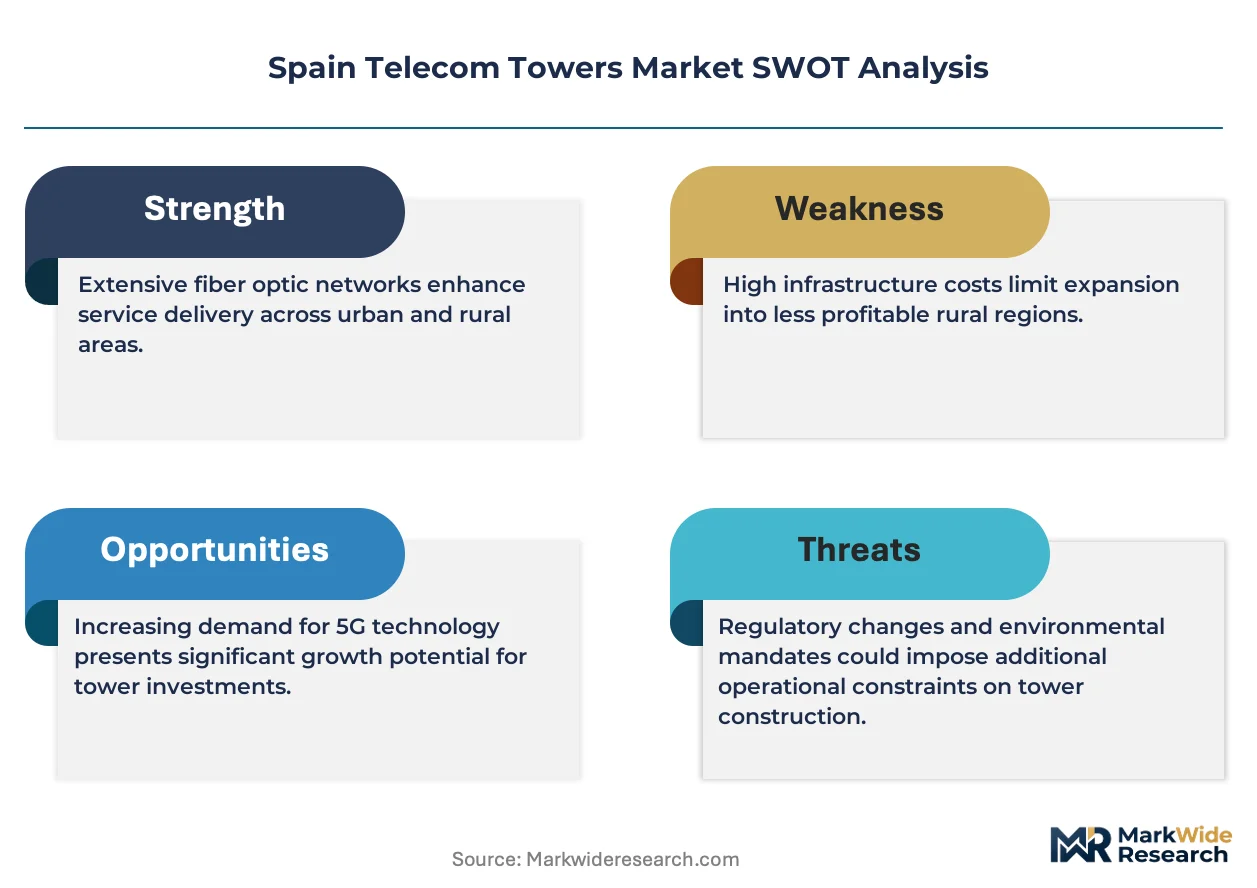
Spain's General Telecommunications Law, the EU Green Deal framework, and CE marking requirements for structural and electromagnetic compliance are tightening specifications for new tower deployments and retrofit obligations. The national regulator CNMC enforces wholesale access terms that shape tenancy economics and infrastructure sharing mandates. Stakeholders must monitor spectrum auction timelines and renewable energy integration deadlines to align capital allocation with evolving tenancy demand and regulatory compliance thresholds.
Market Dynamics
Spain's tower market is restructuring around infrastructure sharing mandates and fiber-backhaul convergence, with mobile operators divesting passive assets to independent tower companies while retaining active network control.
Growth Catalysts
- EU Green Deal compliance:Renewable energy integration deadlines are accelerating tower retrofit programs and new-build specifications across Spanish provinces.
- Small cell densification:Municipal zoning in Madrid, Barcelona, and Valencia is driving rooftop placement demand for 5G capacity layers.
- Catalonia and Andalusia:Regional governments are streamlining permitting for shared infrastructure corridors along transport routes.
Market Restraints
- Steel price volatility:Lattice tower fabrication costs fluctuate with global commodity markets, compressing margins for domestic manufacturers.
- CE marking complexity:Structural and electromagnetic certification timelines extend deployment schedules by eight to fourteen months.
- Optical fiber substitution:Fixed wireless access deployment is slowing in areas where fiber-to-the-home penetration exceeds sixty percent.
Strategic Opportunities
- Edge computing integration:Tower-mounted micro data centers are creating new tenancy revenue streams for computing workloads.
- Andalusian coastal corridors:Tourism-dependent municipalities lack coverage depth and present greenfield build-to-suit prospects.
- CNMC wholesale mandates:Regulator-enforced access terms are opening historically captive operator portfolios to multi-tenant arrangements.
Industry Challenges
- RF engineering talent scarcity:Specialized skills for interference modeling and antenna configuration are concentrated among a shrinking pool of experienced professionals.
- Legacy 2G/3G decommissioning:Site rationalization contracts require complex renegotiation of lease terms and power supply arrangements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Spain Telecom Towers Market |
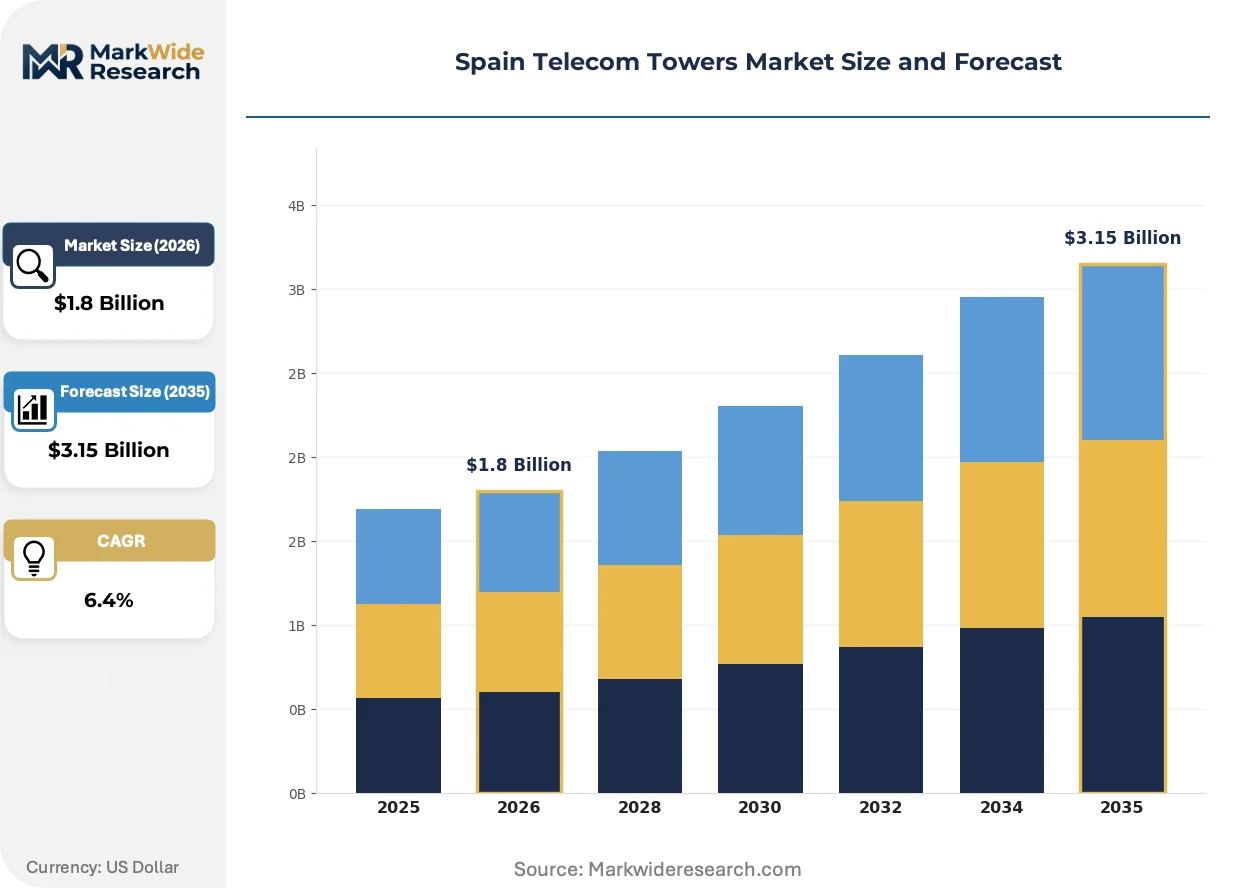
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Macro Cell, Mini Cell, Small Cell, Distributed Antenna System Technology: 4G, 5G, LTE, Wi-Fi Installation: Ground Mounted, Rooftop, Pole, Indoor End User: Mobile Operators, ISPs, Enterprises, Government |
| Companies Covered | Cellnex Telecom, American Tower Corporation, Vantage Towers, TOTEM España, Axión Infraestructuras de Telecomunicaciones, Telefónica, Orange Espagne, Vodafone España, MásOrange, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Spain Telecom Towers Market Trends and Innovations
Open RAN architectures and virtualization are redrawing equipment placement logic, pushing radio intelligence toward tower edges while centralizing baseband processing. This shift is altering power, cooling, and space requirements at cell sites.
Virtualized baseband units are decentralizing network intelligence from centralized hotels to tower-mounted edge locations. Mobile operators are deploying these units in Madrid's metropolitan corridor to reduce fronthaul latency. This architecture is decentralizing the traditional hub-and-spoke topology that dominated 4G deployments.
Spain's General Telecommunications Law is mandating infrastructure sharing as a condition for spectrum license renewal. The regulation is forcing operational separation between passive tower assets and active network equipment. Rural coverage obligations in Castile-La Mancha and Extremadura are most affected, with operators pooling macro cell sites rather than building duplicate networks.
Long-term lease contracts are giving way to shorter-term, volume-flexible agreements as mobile operators seek capacity without balance-sheet commitment. Independent tower companies are responding with service-based models that bundle site access with maintenance and power. This transition is most advanced in Barcelona's dense urban core where zoning constraints limit site alternatives.
Spain Telecom Towers Market Segmentation
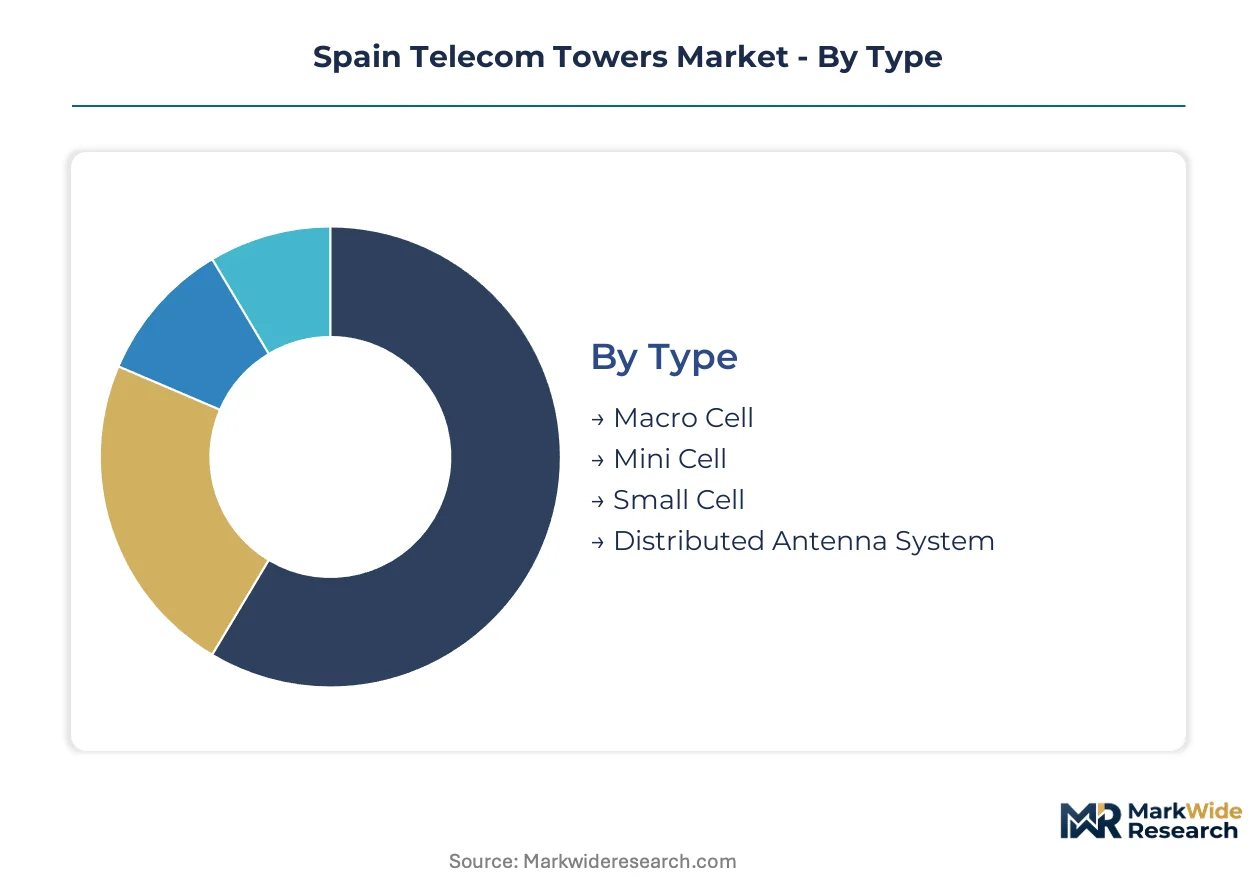
Segmentation in Spain's tower market reveals distinct procurement economics across deployment scales and tenancy models. Tower type and installation method determine capital intensity, while technology generation shapes power and backhaul requirements for each site category.
Type:
Volume deployment concentrates in wide-area coverage solutions, while premium economics attach to capacity-dense installations in urban corridors.
- Macro Cell:Steel lattice structures spanning 30 to 100 meters support multiple antenna arrays for regional 4G and 5G coverage. Madrid's metropolitan corridor and Andalusian transport routes sustain the heaviest deployment concentration, driven by CNMC-mandated rural coverage obligations and long-distance connectivity requirements.
- Small Cell:Compact pole-mounted or building-integrated units deliver targeted capacity in dense urban zones. Barcelona and Valencia municipal authorities are accelerating permitting for these installations where zoning restrictions block greenfield macro construction, making this the steepest expansion trajectory across the forecast window.
- Mini Cell:Intermediate form factors bridge coverage gaps between macro and small cell layers. Suburban Madrid ring municipalities and Catalonian industrial parks represent the primary demand nodes.
- Distributed Antenna System:Fiber-fed indoor-outdoor antenna networks serve venues and transport infrastructure. High-speed rail corridors through Aragon and airport terminals in Andalusia anchor current deployment.
Mature deployment sits with Macro Cell infrastructure. Newer deployment is concentrated in Small Cell networks.
Technology:
Technology generation determines equipment refresh cycles and tenancy revenue durability across Spanish provinces.
- 5G:New radio interfaces operating in mid-band and millimeter-wave spectrum demand modified tower loading and power profiles. Madrid, Barcelona, and Valencia account for the densest rollout, with fiber-backhaul integration requirements intensifying site selection criteria.
- 4G:Legacy LTE infrastructure retains the largest installed base across Castile-La Mancha and Extremadura. Tenancy revenues here are stabilizing as operators shift capital toward 5G overlay.
- LTE:Advanced 4G variants support VoLTE and IoT connectivity layers. Rural coverage obligations under Spain's General Telecommunications Law sustain residual buildout in Extremadura.
- Wi-Fi:Unlicensed spectrum offload points complement licensed cellular in high-density venues. Municipal smart city contracts in Barcelona and Valencia drive placement decisions.
Established infrastructure relies on 4G and LTE platforms. Investment velocity is climbing fastest for 5G deployment.
Installation:
Installation method constrains site acquisition timelines and structural compliance pathways under CE marking requirements.
- Ground Mounted:Greenfield lattice or monopole structures on dedicated land parcels. Andalusian coastal corridors and Castile-La Mancha highway routes offer the clearest expansion prospects where land availability exceeds rooftop alternatives.
- Rooftop:Building-sited installations leveraging existing structures. Madrid's dense urban core and Barcelona's historic districts concentrate demand, though structural engineering assessments extend deployment schedules.
- Pole:Street furniture and utility pole attachments for small cell densification. Valencia's smart streetlight retrofit program creates bundled procurement opportunities.
- Indoor:In-building systems for coverage penetration in commercial and transport facilities. High-speed rail stations and Barcelona-El Prat airport anchor current deployment.
Ground Mounted structures carry the deepest installed history. Pole and Rooftop placements are gaining share in capacity-constrained zones.
End User:
End user category shapes contract duration, service bundling, and pricing structure across tenancy agreements.
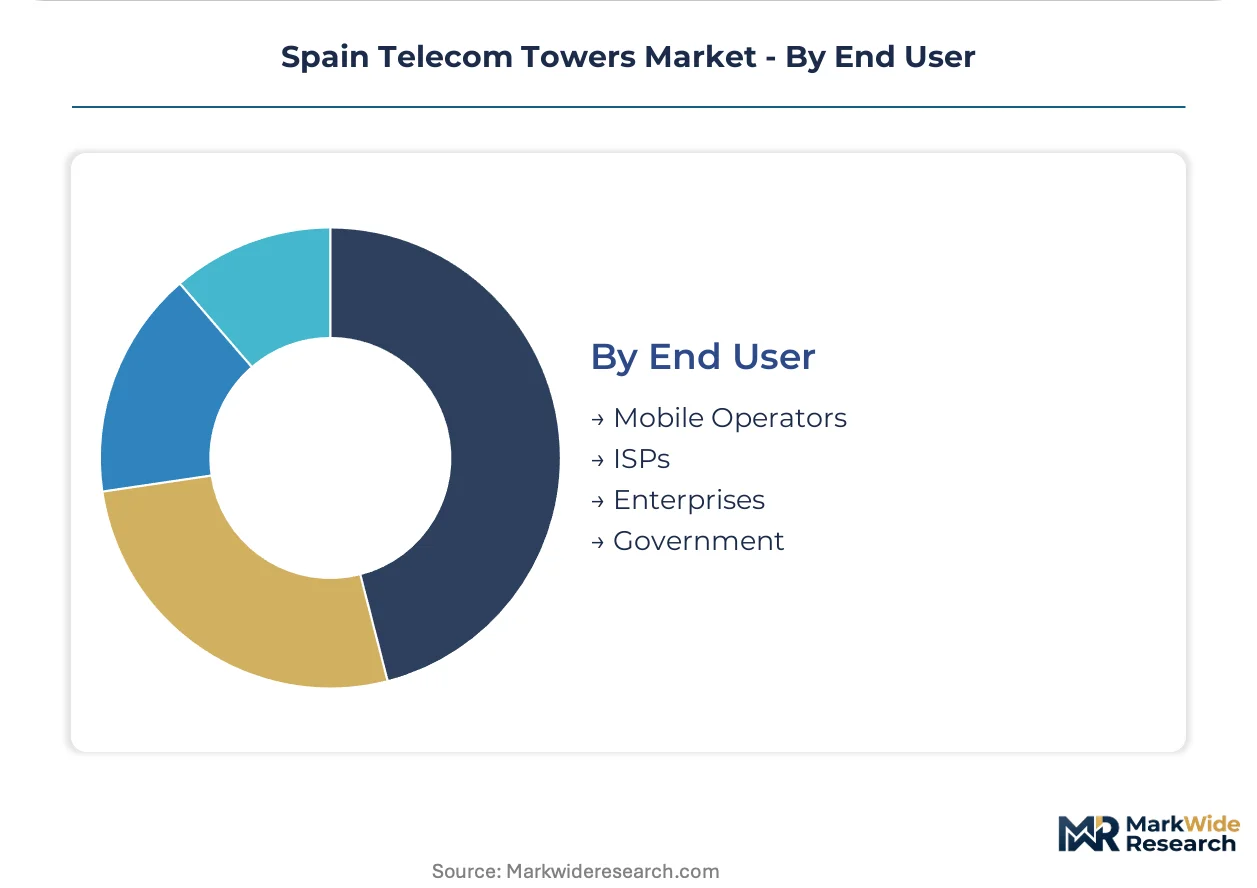
- Mobile Operators:Tier-one carriers drive volume tenancy with long-term lease commitments. Shared infrastructure mandates under Spain's General Telecommunications Law are forcing operational separation between passive assets and active network control.
- ISPs:Fixed wireless access providers lease tower capacity for last-mile connectivity. Fiber-to-the-home penetration above sixty percent in Madrid and Barcelona suburbs is constraining this segment's expansion.
- Enterprises:Private network deployments for industrial campuses and logistics facilities. Catalonian automotive manufacturing clusters represent emerging demand nodes.
- Government:Emergency services and smart city infrastructure contracts. CNMC wholesale access terms shape procurement economics for municipal deployments.
Mobile Operators anchor established tenancy patterns. Enterprise and Government contracts are diversifying revenue streams fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Tower deployment concentrates in metropolitan corridors while rural obligations under Spain's General Telecommunications Law mandate coverage extensions into lower-density provinces. Production of steel lattice structures clusters in northern industrial zones, with installation crews mobilizing across regional transport networks.
Madrid
5G densification and fiber-backhaul convergence drive the steepest capacity investment in the capital corridor. CNMC wholesale access terms force infrastructure sharing among converged operators. The metropolitan ring municipalities host the densest small cell pole attachments as zoning restrictions block greenfield macro construction.
Catalonia
Barcelona's historic districts and industrial parks generate dual demand streams for rooftop placements and mini cell suburban infill. Regional authorities streamlined permitting for shared infrastructure corridors along Mediterranean transport routes. Automotive manufacturing clusters around Tarragona are emerging as private network demand nodes.
Andalusia
Tourism-dependent coastal municipalities lack coverage depth and present build-to-suit prospects for independent tower companies. The regional government accelerated environmental permitting for renewable energy integration at tower sites. High-speed rail corridors through Seville and Málaga anchor distributed antenna system deployment.
Valencia
Municipal smart streetlight retrofit programs create bundled procurement opportunities for pole-mounted small cells. The port authority's logistics facilities are driving enterprise private network inquiries. Structural engineering assessments for rooftop installations extend deployment schedules in the dense urban core.
Basque Country
Industrial automation demand from Bilbao and San Sebastián manufacturing clusters supports edge computing integration at tower sites. Regional energy efficiency mandates exceed national baselines, favoring tower companies with specialized low-consumption designs. The coastal highway corridor requires macro cell reinforcement for maritime connectivity.
Spain Telecom Towers Market Competitive Landscape
The competitive structure tilts toward independent tower companies holding passive assets under long-term lease arrangements with mobile operators divesting infrastructure. Market concentration is moderate, with three large independents controlling substantial tenancy portfolios while regional specialists retain niche geographic positions. Two strategic archetypes dominate: scale-driven portfolio aggregators and efficiency-focused design specialists. M&A activity targets regional bolt-on acquisitions, while contract renegotiation toward shorter-term, volume-flexible agreements reshapes tenancy economics.
Among the independent tower archetype, Cellnex Telecom and American Tower Corporation occupy positions as portfolio aggregators with broad geographic tenancy bases. Vantage Towers exemplifies the efficiency-focused tier through its specialization in energy-efficient structural designs. These three entities anchor the competitive field, with Cellnex leveraging Europe's largest independent tower position and American Tower securing its Iberian footprint through lease contract structures. Regional operators including TOTEM España and Axión Infraestructuras de Telecomunicaciones sit within specialized sub-market tiers serving specific municipal or corridor deployments.
| Leading Market Players |
|---|
| Cellnex Telecom |
| American Tower Corporation |
| Vantage Towers |
| TOTEM España |
| Axión Infraestructuras de Telecomunicaciones |
| Telefónica |
| Orange Espagne |
| Vodafone España |
| MásOrange |
| Others |
Pricing and Supply Chain Analysis
RF engineering talent scarcity in Madrid and Barcelona widens labor-cost differentials between premium-tier structural design services and standard installation contracts. Steel price volatility feeds directly into tower fabrication economics, compressing margins for domestic manufacturers serving volume deployment segments.
Pricing Analysis
Margin tightening in standard-tier tenancy agreements traces to shorter-term, volume-flexible contract structures displacing legacy long-term leases. Three-tier pricing structure across premium, standard, and economy levels separates energy-efficient tower designs with integrated micro data centers from basic steel lattice structures and refurbished legacy assets. Price differentiation hinges on CE marking certification tier and after-sales power-maintenance bundling. Mobile operators exhibit highest price sensitivity in rural coverage obligation zones, while enterprise private network buyers accept premium positioning for edge computing integration.
Supply Chain Analysis
Steel supply rests on Spanish domestic mills and German specialty producers, with antenna and remote radio head sourcing concentrated in China and South Korea. Lattice tower fabrication draws from hot-rolled steel coils, galvanized coating chemicals, and precision-engineered antenna mounting hardware. Single-source vulnerability concentrates in semiconductor components for virtualized baseband units. Distribution runs through regional installation contractors mobilizing across Catalonia, Andalusia, and Madrid metropolitan corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Site acquisition bottlenecks in Madrid's dense urban core and Barcelona's historic districts prop pricing power for independent tower companies holding permitted rooftop positions. Regulatory-mandated infrastructure sharing limits new-build greenfield economics.
For Market Incumbents: Anticipate accelerated lease renegotiation cycles by pre-positioning service-based bundling that wraps site access with power and maintenance. Cellnex Telecom and American Tower Corporation should deepen backward integration into energy-efficient structural design capabilities to defend against Vantage Towers' efficiency-focused differentiation. CNMC wholesale access mandates threaten captive tenancy pools.
For New Entrants and Emerging Players: Direct-to-tower-company digital procurement platforms offer white-space entry around municipal smart city contracts in Valencia and enterprise private networks in Catalonian automotive clusters. Andalusian coastal corridors present the most penetrable geography given tourism-dependent municipalities' coverage gaps. Target build-to-suit arrangements with fiber-backhaul integration as the primary go-to-market angle.
For Investors and Strategic Acquirers: Re-rating potential sits with regional specialists holding permitted positions in capacity-constrained zones given EU Green Deal compliance deadlines accelerating retrofit demand. Long-term viability favors tower companies with operational separation capabilities between passive assets and active equipment. Watch CNMC spectrum auction timelines as the inflection signal for tenancy volume acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge Computing Integration | Tower-mounted micro data centers create new revenue streams from computing workloads in Madrid's metropolitan corridor. |
| Energy-Efficient Retrofit Program | EU Green Deal compliance deadlines accelerate tower power-system upgrades across Spanish provinces. |
| Regional Permit Portfolio Acquisition | Permitted rooftop positions in Barcelona's historic districts command scarcity premiums under zoning restrictions. |
| Fiber-Backhaul Partnership | Convergence with fiber networks intensifies site selection criteria for 5G small cell densification. |
| Private Network Deployment | Enterprise contracts in Catalonian automotive clusters diversify revenue beyond mobile operator tenancy. |
Research Methodology
Document review covered CNMC regulatory filings, EU Green Deal implementation directives, and steel commodity trade data, complemented by interviews with tower company procurement directors, mobile operator network planning executives, and municipal smart city program managers. Secondary validation drew from Spanish customs records, infrastructure development databases, and SEC filings of listed tower companies. Bottom-up site deployment modeling and top-down market sizing triangulated volume estimates.
Cross-referencing historical tenancy growth patterns against panel input from regional network engineers anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include tower type, installation method, technology generation, and end-user category. CAGRs derived from weighted average of historical trajectory and forward-looking capacity deployment schedules, with fiber-backhaul penetration rates and spectrum auction timelines as industry-specific forecast inputs.
The model holds under stable steel pricing and permitting velocity; deviation in EU renewable energy integration deadlines or CNMC wholesale mandate enforcement would shift tenancy economics. Forecasts reflect documented assumptions about infrastructure sharing adoption curves and small cell densification rates. A small set of named triggers—spectrum auction timelines, steel price volatility, and municipal zoning rulings—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
NLD and ILD Telecom Service Market
Telecommunications Infrastructure
5G Network Infrastructure Market
Telecommunications Infrastructure
Panama Telecom Market
Telecommunications Infrastructure
Global Telecom Towers Market
Telecommunications Infrastructure
Session Initiation Protocol (SIP) Trunk Market
Telecommunications Infrastructure
Global Telecom Cable Market
Telecommunications Infrastructure
Carrier Infrastructure in Telecom Applications Market
Telecommunications Infrastructure
South Korea Telecom Tower Market
Telecommunications Infrastructure
Saudi Arabia Telecom Towers Market
Telecommunications Infrastructure
Japan Telecom Market
Telecommunications Infrastructure
Chile Telecom Tower Market
Telecommunications Infrastructure
Global Telecom System Integration Market
Telecommunications Infrastructure
Broadcast Infrastructure Market
Telecommunications Infrastructure
Global Mobile and Wireless Backhaul Equipment Market
Telecommunications Infrastructure
UAE Telecom Towers Market
Telecommunications Infrastructure
Bangladesh Telecom Towers Market