
 Iraq Telecom Market | 2026-2036
Iraq Telecom Market Size, Share, and Industry Trends Forecast 2026-2036
Iraq Telecom Market Insights
The Communications and Media Commission licensing framework is repositioning spectrum allocation rules for new market entrants in Iraq. Asiacell Communications PJSC leverages its established mobile infrastructure across northern and central provinces. Zain Iraq sustains brand recognition through diversified prepaid and postpaid portfolios. Korek Telecom Company LLC anchors its position in the Kurdistan Region with localized network investments.
Iraq telecom encompasses voice, data, and broadband services delivered via terrestrial and wireless infrastructure, typically operating across frequency bands from 700 MHz to 3.5 GHz with fiber backhaul requirements for 4G and 5G densification. Mobile service generates the dominant revenue pool due to prepaid subscriber density, while fiber optic deployment in business corridors represents the fastest-expanding technology segment. Residential customer segments absorb the majority of prepaid mobile and DSL volumes, though government and SOHO buyers are shifting toward bundled fiber offerings as municipal fiber-to-the-premises builds advance in Baghdad and Basra.
The Communications and Media Commission governs licensing and spectrum policy, while the Central Bank of Iraq influences digital payment integration for telecom-bundled financial services. BIS-equivalent technical standards shape equipment import compliance for base station and fiber hardware deployments. Stakeholders must monitor regulatory clarity on 5G spectrum auctions and infrastructure-sharing mandates as these will determine capital deployment sequencing and partnership structures.
Market Dynamics
The Communications and Media Commission's spectrum reallocation framework is compressing licensing timelines for new mobile network operators while fiber-to-the-premises infrastructure concentrates capital deployment in Baghdad and Basra commercial corridors.
Growth Catalysts
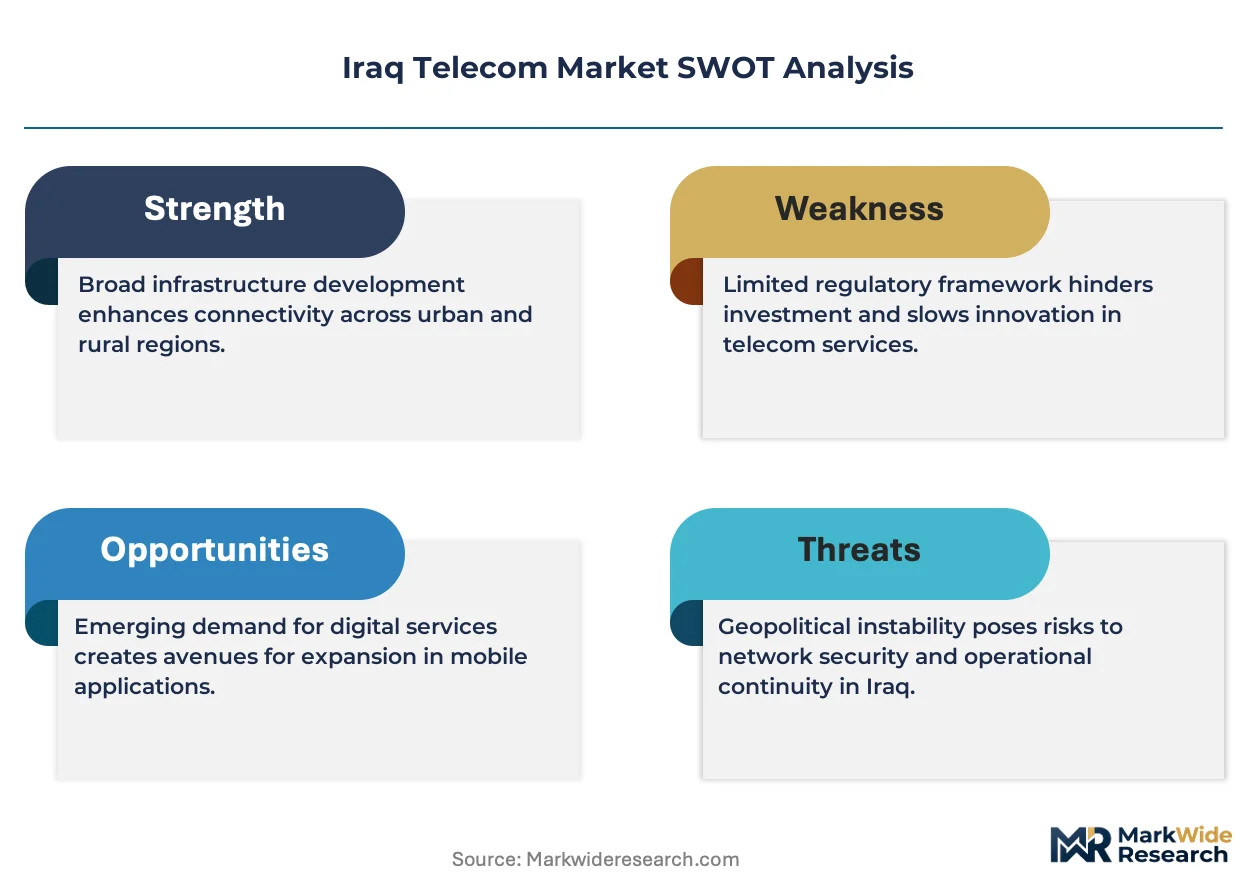
- 5G spectrum harmonization:The Communications and Media Commission's revised allocation rules are unlocking contiguous frequency blocks in the 3.5 GHz band, enabling operators to densify urban coverage without cross-border interference constraints.
- Enterprise cloud migration:Banking and logistics clusters in Baghdad are consuming symmetric fiber connectivity, pulling capital from mobile CAPEX toward fixed-line infrastructure with 99.99% SLA guarantees.
- Kurdistan Region digital corridor:Erbil and Sulaymaniyah municipal authorities are fast-tracking right-of-way permits for fiber trenching, reducing deployment cycles from 18 months to 9 months for qualified infrastructure providers.
Market Restraints
- Import duty volatility:Base station and optical transport equipment face unpredictable customs valuations at Umm Qasr port, inflating project budgets by 15-25% versus landed-cost forecasts.
- Generator fuel dependency:Grid instability forces tower operators to maintain diesel backup systems, consuming 40% of opex budgets and constraining rural site economics.
- Security corridor fragmentation:Fiber routes through Anbar and Nineveh provinces require armed escort provisions, segmenting the national backbone into non-contiguous operational zones.
Strategic Opportunities
- Southern province underpenetration:Maysan and Dhi Qar governorates operate below 60% 4G coverage, presenting greenfield buildout potential for operators with generator-integrated microgrid expertise.
- Mobile money convergence:Central Bank of Iraq e-wallet licensing is enabling telecom-bundled financial services, creating ARPU uplift through airtime-to-cash conversion products.
- Passive infrastructure sharing:The Communications and Media Commission's draft co-location mandate is opening tower and fiber duct access, reducing duplication capex for second-mover operators.
Industry Challenges
- Fiber splicing technician scarcity:Certification programs through the Ministry of Labor produce fewer than 200 qualified installers annually, creating 18-month backlogs for FTTH activation queues.
- Legacy copper migration friction:DSL subscriber bases resist service discontinuation timelines, forcing parallel maintenance of obsolete copper plant while fiber overlays absorb maintenance resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Iraq Telecom Market |
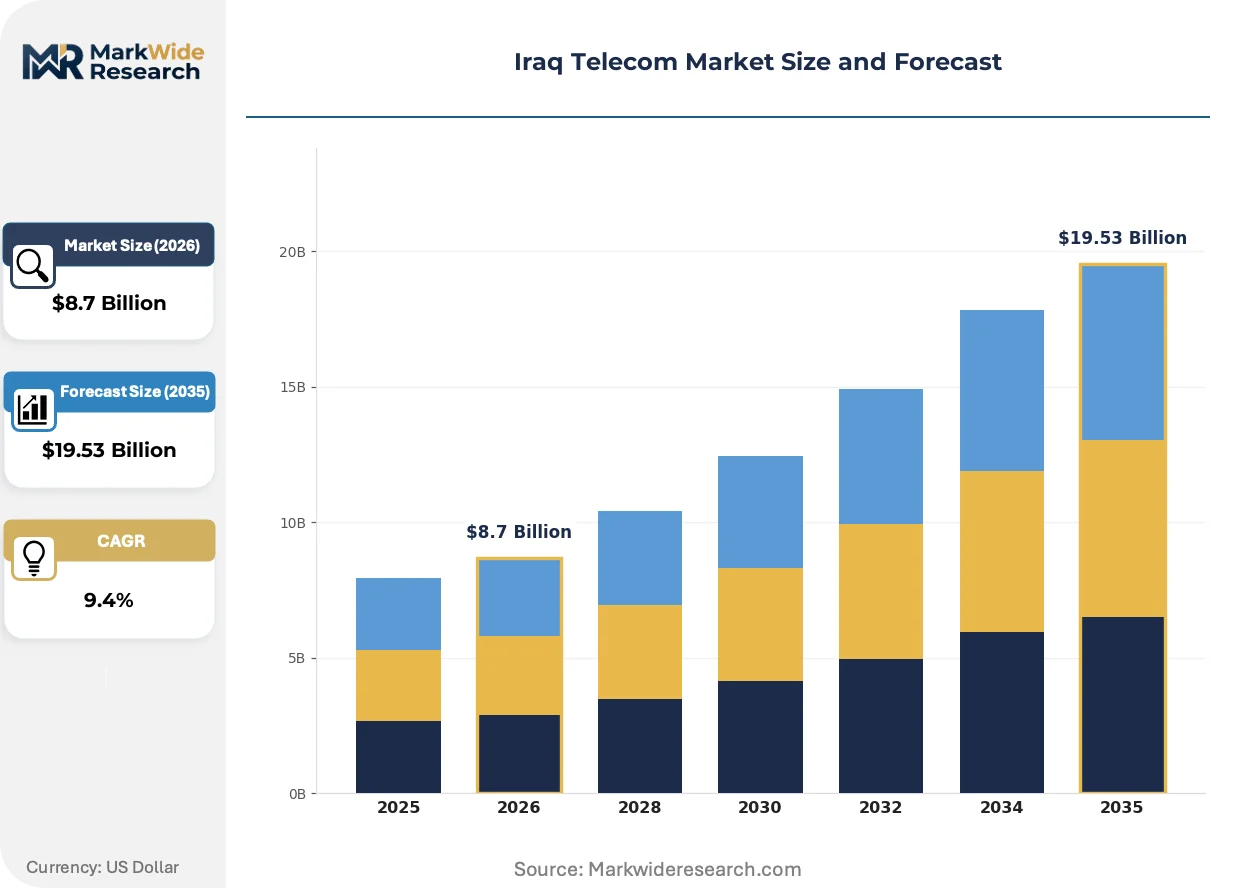
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Mobile, Fixed Line, Internet, VoIP Customer Type: Residential, Business, Government, SOHO Technology: 4G, 5G, Fiber Optic, DSL Pricing Model: Prepaid, Postpaid, Bundled, Pay-as-you-go |
| Companies Covered | Asiacell Communications PJSC, Zain Iraq, Korek Telecom Company LLC, Allai Newroz Telecom, Talia Communications Limited, Uruklink, AL HAYAT COMPANY FOR INTERNET AND COMMUNICATION LIMITED, Freeone Space LLC, Linkdata.com, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Iraq Telecom Market Trends and Innovations
Network virtualization and open RAN architectures are decoupling hardware from software layers, enabling Iraqi operators to diversify vendor relationships while the Central Bank's digital payment frameworks integrate with telecom billing systems.
Open RAN is expanding into the Kurdistan Region's 4G densification programs. Asiacell and Korek Telecom are trialing multi-vendor radio units in Erbil suburbs, reducing single-source dependency on traditional equipment suppliers. This disaggregation is compressing base station costs and accelerating feature deployment cycles from 24 months to 12 months.
The Communications and Media Commission's infrastructure-sharing directive is mandating co-location on towers and fiber ducts. This regulatory pressure is consolidating passive asset ownership toward specialized infrastructure companies, altering competitive dynamics between mobile network operators. Baghdad and Basra metropolitan areas are seeing the first compliance deadlines.
Enterprise buyers in oil services and logistics are unbundling connectivity from managed services. Procurement committees now separate bandwidth contracts from SLA-guaranteed network operations, creating dual-vendor structures where specialized integrators assume operational accountability. This pattern concentrates in Basra's port and industrial zones.
Iraq Telecom Market Segmentation
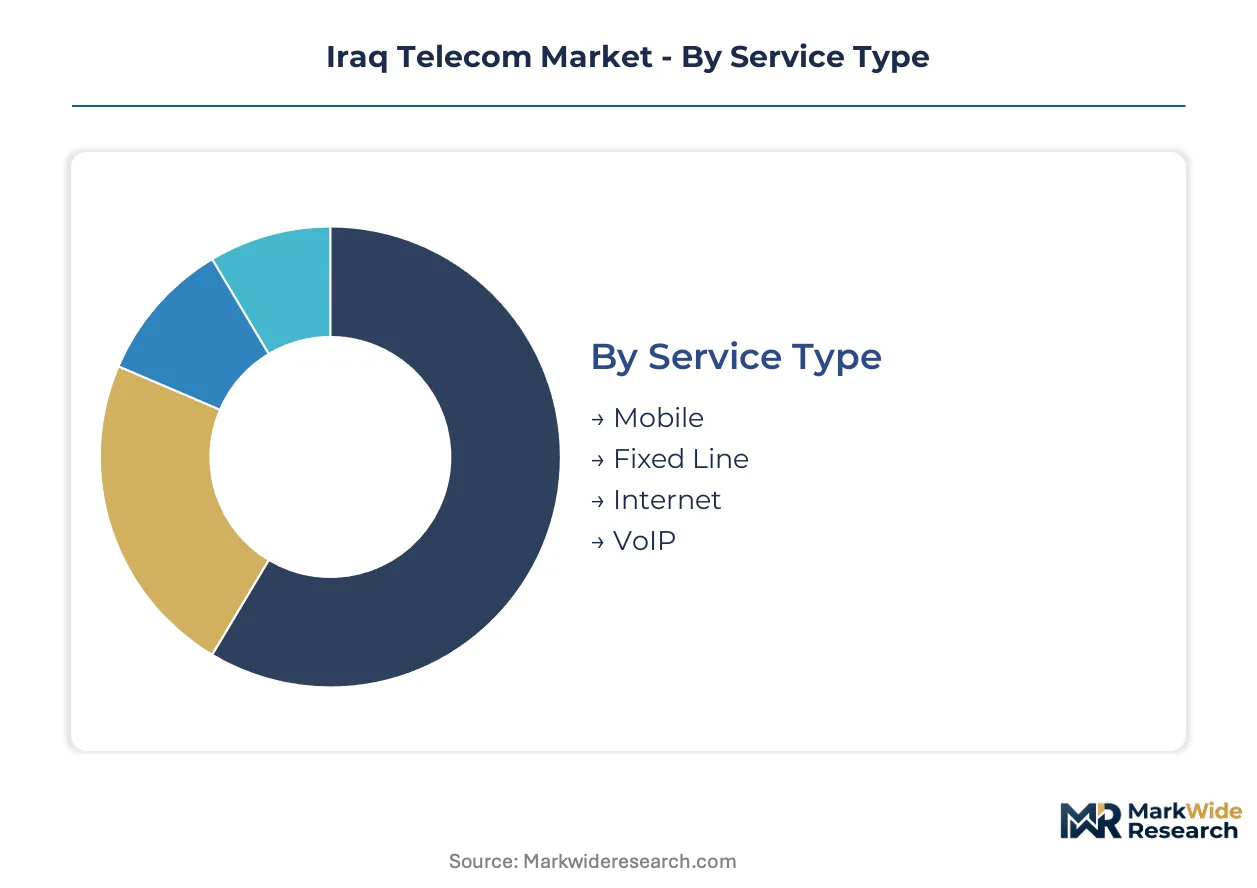
Iraq's telecom segmentation reveals divergent investment priorities across infrastructure layers. Service type and customer category dictate capital allocation between mobile densification and fiber backhaul expansion.
Service Type:
Revenue concentration follows subscriber density and ARPU stability rather than technology novelty.
- Mobile:Prepaid subscriber bases across Baghdad and southern governorates generate recurring revenue through airtime purchases. Network operators prioritize 4G site densification over 5G pilots due to handset ecosystem limitations and spectrum auction delays.
- Internet:Enterprise fiber connectivity in Basra's port corridors and Erbil's business districts commands premium pricing with SLA guarantees. Banking and logistics clusters are unbundling bandwidth procurement from managed services, creating dual-vendor procurement structures.
- Fixed Line:Legacy copper infrastructure persists in older Baghdad neighborhoods where DSL subscribers resist service migration timelines.
- VoIP:International calling traffic concentrates in diaspora corridors, with quality-of-service differentiation driving carrier selection.
Mobile leads on scale; Internet leads on momentum.
Customer Type:
Procurement sophistication separates volume buyers from price-sensitive segments.
- Residential:Prepaid mobile and DSL subscriptions absorb majority volumes across Baghdad, Basra, and Kurdistan Region urban centers. Price sensitivity limits ARPU growth despite rising data consumption per subscriber.
- Business:Oil services and logistics clusters in Basra industrial zones demand symmetric fiber with 99.99% uptime guarantees. Procurement committees now separate bandwidth contracts from operational accountability, enabling specialized integrator participation.
- Government:Ministry-level contracts prioritize nationwide coverage obligations over cost minimization, with security corridor fragmentation complicating service delivery in Anbar and Nineveh provinces.
- SOHO:Bundled fiber-to-the-premises offerings in Baghdad and Basra municipal buildouts are capturing micro-enterprise migration from consumer-grade DSL.
Residential commands absolute volume; Business shows steepest expansion trajectory.
Technology:
Deployment sequencing reflects infrastructure maturity and regulatory clarity gaps.
- 4G:Dominant radio access technology with coverage gaps in Maysan and Dhi Qar governorates presenting greenfield buildout potential. Generator-integrated microgrid expertise determines rural site economics.
- Fiber Optic:Metropolitan builds in Baghdad and Basra commercial corridors absorb capital shifted from mobile CAPEX. Right-of-way permit acceleration in Erbil and Sulaymaniyah is compressing deployment cycles.
- 5G:Spectrum auction delays and contiguous frequency block uncertainty constrain operator commitment despite equipment vendor readiness.
- DSL:Legacy copper plant requires parallel maintenance resources while fiber overlays progress, creating operational drag on transition timelines.
4G anchors current revenue; Fiber Optic is gaining share fastest.
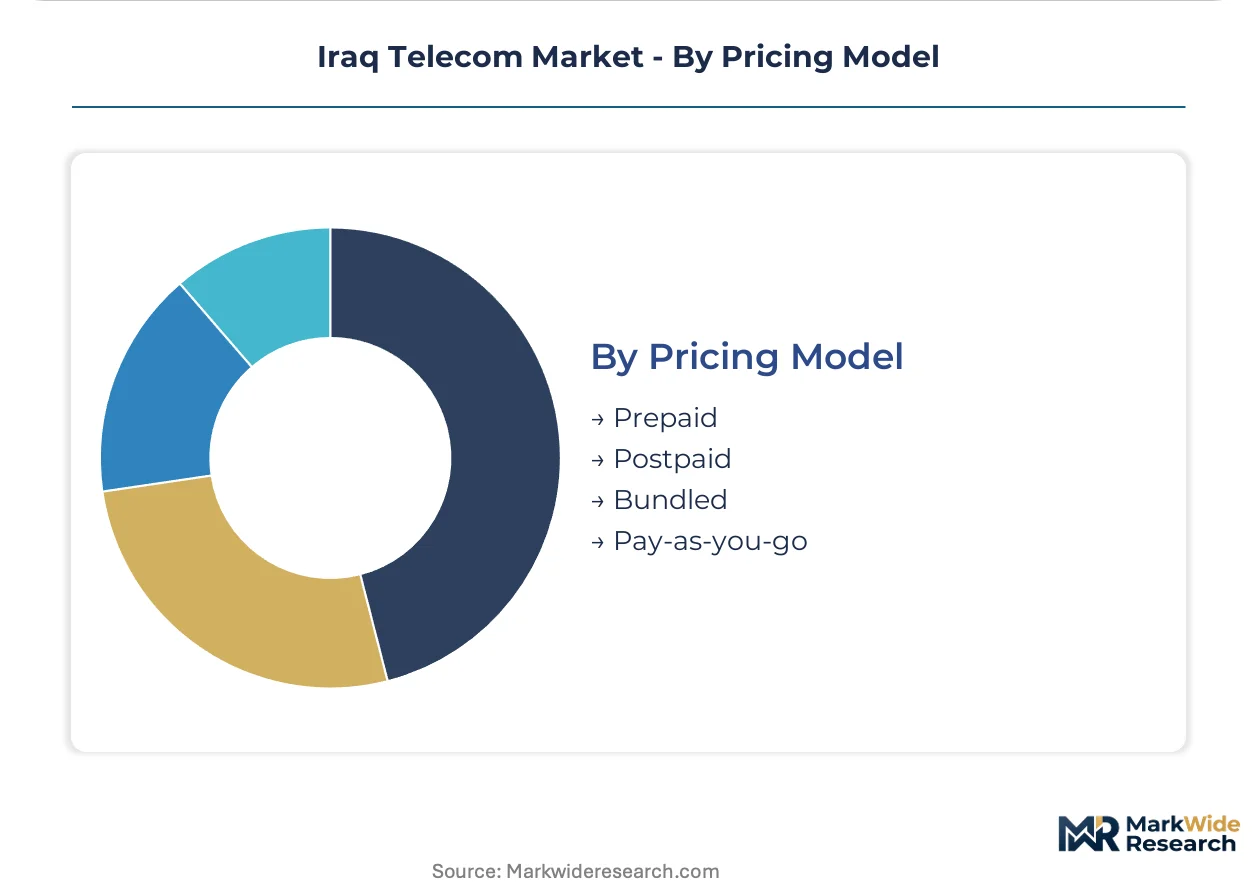
Pricing Model:
Cash-flow predictability and customer lifetime value shape operator preference.
- Prepaid:Dominant mobile acquisition mechanism with airtime-to-cash conversion products enabled by Central Bank of Iraq e-wallet licensing. Subscriber churn remains elevated versus postpaid counterparts.
- Postpaid:Concentrated among business and government segments with credit verification requirements limiting addressable market expansion.
- Bundled:Fiber-to-the-premises plus mobile convergence offers gaining traction in Baghdad municipal buildouts as operators pursue share-of-wallet consolidation.
- Pay-as-you-go:Residual category for intermittent users and temporary worker populations in construction and logistics sectors.
Prepaid dominates subscriber count; Bundled shows strongest ARPU uplift potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Skilled fiber splicing technicians and network engineers concentrate in Baghdad and Erbil, anchoring deployment capacity for national infrastructure buildouts. The Communications and Media Commission's spectrum policies and municipal permitting frameworks shape investment sequencing across governorates. Regional performance diverges sharply between generator-dependent southern provinces and grid-stable Kurdish urban centers.
Baghdad Governorate
Banking and logistics clusters drive symmetric fiber demand with 99.99% SLA requirements. The Communications and Media Commission's infrastructure-sharing directive mandates co-location compliance deadlines in metropolitan Baghdad. Municipal fiber-to-the-premises builds advance in commercial corridors, absorbing capital shifted from mobile CAPEX.
Basra Governorate
Oil services procurement committees unbundle connectivity from managed services, creating dual-vendor structures. Central Bank of Iraq e-wallet licensing enables telecom-bundled financial services for port and industrial zone workers. Generator fuel costs consume 40% of opex budgets, constraining rural site economics outside the city core.
Kurdistan Region
Erbil and Sulaymaniyah municipal authorities compress fiber deployment cycles from 18 months to 9 months through accelerated right-of-way permits. The Kurdistan Regional Government's digital corridor initiative anchors localized network investments. Open RAN trials in Erbil suburbs reduce single-source dependency on traditional equipment suppliers.
Southern Governorates
Maysan and Dhi Qar operate below 60% 4G coverage, presenting greenfield buildout potential. Generator-integrated microgrid expertise determines rural site economics where grid instability persists. Security corridor fragmentation requires armed escort provisions for fiber routes through adjacent Anbar and Nineveh provinces.
Northern and Western Provinces
Anbar and Nineveh fiber backbone segments remain non-contiguous operational zones due to security constraints. Legacy copper DSL infrastructure requires parallel maintenance while fiber overlays progress. The Communications and Media Commission's licensing framework repositions spectrum allocation rules for infrastructure recovery in post-conflict zones.
Iraq Telecom Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across Iraq's telecom infrastructure layers. The market structure concentrates around three mobile network operators with established spectrum holdings, while specialized infrastructure companies consolidate passive asset ownership under regulatory co-location mandates. Strategic archetypes include integrated mobile-fiber operators, tower and duct infrastructure specialists, and regional internet service providers. Dominant competitive moves encompass passive infrastructure sharing partnerships and fiber backhaul capacity expansion in commercial corridors.
Among Iraq-based mobile operators, Asiacell Communications PJSC, Zain Iraq, and Korek Telecom Company LLC occupy positions across the competitive spectrum. Asiacell leverages established infrastructure across northern and central provinces. Zain Iraq sustains brand recognition through diversified service portfolios. Korek Telecom anchors its market presence in the Kurdistan Region with localized network investments. These three operators exemplify the integrated mobile-fiber archetype while navigating the Communications and Media Commission's evolving licensing framework.
| Leading Market Players |
|---|
| Asiacell Communications PJSC |
| Zain Iraq |
| Korek Telecom Company LLC |
| Allai Newroz Telecom |
| Talia Communications Limited |
| Uruklink |
| AL HAYAT COMPANY FOR INTERNET AND COMMUNICATION LIMITED |
| Freeone Space LLC |
| Linkdata.com |
| Others |
Pricing and Supply Chain Analysis
Open RAN disaggregation across the Kurdistan Region is simultaneously compressing base station procurement costs and fragmenting vendor concentration among multi-source radio unit suppliers. This technology transition feeds pricing volatility into equipment import budgets while creating arbitrage opportunities between traditional integrated suppliers and emerging modular providers.
Pricing Analysis
Bundled fiber-to-the-premises plus mobile convergence offers in Baghdad municipal buildouts compete against unbundled bandwidth contracts where enterprise procurement committees separate connectivity from operational accountability. Three-tier pricing structure across premium SLA-guaranteed, standard business-grade, and economy residential tiers separates segments by uptime commitment and support response time. Cost compression in the economy tier stems from generator fuel dependency consuming operator opex budgets. Residential prepaid subscribers exhibit highest price sensitivity while oil services clusters in Basra demonstrate lowest elasticity due to operational criticality.
Supply Chain Analysis
Reverse logistics for base station refurbishment and optical transport equipment remanufacturing flow through Dubai and Turkey as regional redistribution hubs for Iraqi operators. Equipment sourcing draws from China, South Korea, and Finland for radio access network hardware and fiber optic components. Single-source vulnerability concentrates in 3.5 GHz radio unit supply where traditional integrated vendors still dominate. Distribution runs through Umm Qasr port with unpredictable customs valuations creating landed-cost uncertainty.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Iraq's telecom market functions as a geographic-arbitrage play where operators exploit the cost differential between grid-stable Kurdistan Region operations and generator-dependent southern provinces. The Communications and Media Commission's infrastructure-sharing mandate compresses passive asset duplication costs in Baghdad while security corridor fragmentation inflates operational expenditures in Anbar and Nineveh.
For Market Incumbents: Cement spectrum portfolio positions through contiguous frequency block aggregation ahead of formal 5G auction announcements. Prioritize fiber backhaul capacity expansion in Basra port corridors where oil services procurement committees unbundle connectivity from managed services. Defensive consolidation through tower and duct infrastructure partnerships neutralizes second-mover advantages under co-location mandates.
For New Entrants and Emerging Players: Capture greenfield 4G buildout potential in Maysan and Dhi Qar governorates where coverage remains below sixty percent. Target generator-integrated microgrid expertise as the most penetrable technical wedge against incumbent rural economics. Deploy localized network investments with municipal right-of-way permit acceleration in Erbil and Sulaymaniyah.
For Investors and Strategic Acquirers: Valuations sit cheapest among specialized infrastructure companies consolidating passive asset ownership under regulatory co-location pressure. Long-term viability hinges on fiber-to-the-premises penetration rates in Baghdad and Basra commercial corridors over the medium-term horizon. Monitor Communications and Media Commission clarity on 5G spectrum auction timing as the primary inflection signal for capital deployment sequencing.
| Strategic Initiative | Industry Significance |
|---|---|
| Open RAN Multi-Vendor Deployment | Asiacell and Korek Telecom trials in Erbil suburbs reduce single-source dependency on traditional equipment suppliers. |
| Passive Infrastructure Sharing Partnership | Co-location mandates from the Communications and Media Commission consolidate tower and fiber duct ownership toward specialized infrastructure companies. |
| Enterprise Fiber Backhaul Expansion | Banking and logistics clusters in Baghdad demand symmetric connectivity with 99.99% SLA guarantees. |
| Mobile Money Convergence Launch | Central Bank of Iraq e-wallet licensing enables airtime-to-cash conversion products for ARPU uplift. |
| Generator-Integrated Microgrid Buildout | Rural site economics in Maysan and Dhi Qar depend on diesel backup systems consuming forty percent of opex budgets. |
Research Methodology
Multiple input streams — operator network planning executives, Communications and Media Commission regulatory affairs leads, fiber infrastructure procurement managers, and enterprise IT directors — were reconciled against secondary validation from equipment vendor SEC disclosures, customs import records at Umm Qasr, and Central Bank of Iraq digital payment framework documentation. Bottom-up subscriber and site-level data were triangulated with top-down market sizing from national regulatory filings across the analysis window.
Data-stream reconciliation anchored volume and value projections across service type, customer category, technology deployment, and regional governorate segmentation dimensions. CAGRs were derived from trend extrapolation of capital expenditure shifts between mobile densification and fixed-line infrastructure. Forecast inputs incorporated spectrum auction timing assumptions and municipal right-of-way permit velocity in Erbil versus Baghdad.
Spectrum auction delays, security corridor fragmentation in Anbar and Nineveh, and import duty volatility at Umm Qasr are the dominant revision risks to modeled outcomes. Practitioners should monitor Communications and Media Commission regulatory announcements and generator fuel cost movements for early signals of forecast deviation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Latin America Telecom Tower Market
Telecommunications Infrastructure
Peru Telecom Tower Market
Telecommunications Infrastructure
Nepal Telecom Market
Telecommunications Infrastructure
France Telecom Towers Market
Telecommunications Infrastructure
Thailand Telecom Towers Market
Telecommunications Infrastructure
Colombia Telecom Tower Market
Telecommunications Infrastructure
Fixed Telephony Service Market
Telecommunications Infrastructure
OTN Equipment Market
Telecommunications Infrastructure
Kenya Telecom Tower Market
Telecommunications Infrastructure
Global Cellular Networks Market
Telecommunications Infrastructure
China Telecom Equipment Market
Telecommunications Infrastructure
Telecom Network Infrastructure Market
Telecommunications Infrastructure
Global Telecom Towers Market
Telecommunications Infrastructure
Germany Telecom Towers Market
Telecommunications Infrastructure
Asia Pacific Voice Over LTE Market
Telecommunications Infrastructure
Brazil Telecom Tower Market