
 United States Telecom Towers Market | 2026-2036
United States Telecom Towers Market Size, Share, and Industry Trends Forecast 2026-2036
United States Telecom Towers Market Analytics
Buyer concentration among mobile network operators is restructuring lease negotiation dynamics across the tower ecosystem. American Tower Corporation leverages its nationwide portfolio scale to sustain long-term tenancy agreements with national carriers. Crown Castle Inc. differentiates through its dense urban small-cell and fiber-integrated tower strategy. Vertical Bridge anchors its competitive stance with a focus on rural and suburban macro-site expansion.
Telecom towers are steel or composite structures engineered to heights between 50 and 500 feet, designed to support multiple antenna arrays, transmission equipment, and power systems while withstanding wind loads specified by TIA-222 structural standards. Monopole installations dominate urban and suburban deployments due to smaller footprints and zoning compliance advantages, while lattice towers retain cost efficiencies for high-capacity rural macro sites. 5G technology segments command premium lease rates as carriers pursue millimeter-wave and mid-band densification.
FCC licensing requirements govern spectrum use and tower registration, while FAA Part 77 rules mandate obstruction lighting and marking for structures exceeding 200 feet above ground level. OSHA fall protection standards shape maintenance cost structures and operational safety protocols. Stakeholders must monitor state-level streamlining statutes for wireless infrastructure siting as these directly affect deployment timelines and capital allocation decisions.
Market Dynamics
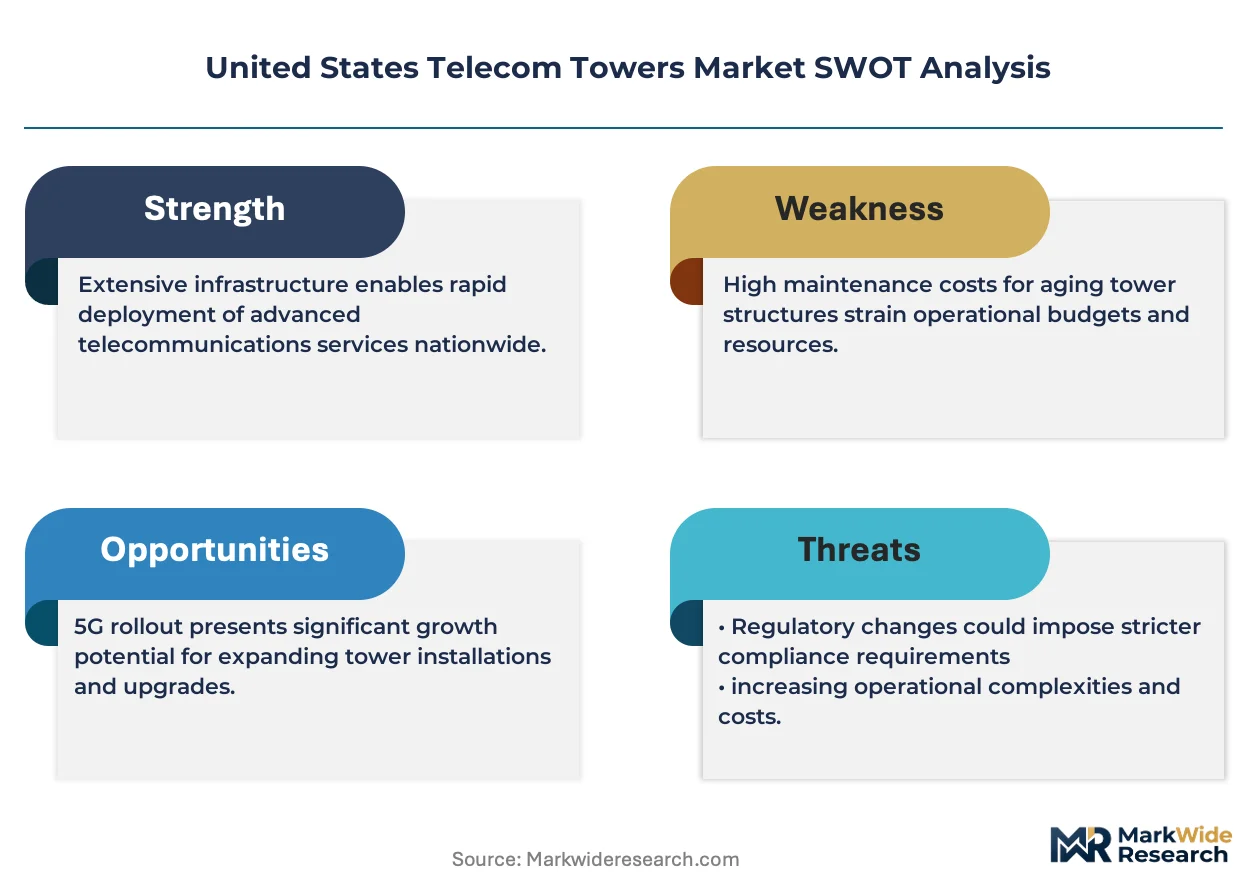
5G mid-band densification is compressing tower spacing requirements nationwide, forcing carriers to triple site counts while FAA obstruction rules constrain height and siting options across metropolitan corridors.
Growth Catalysts
- FCC Spectrum Auctions:Mid-band C-band and 3.45 GHz allocations are accelerating carrier infrastructure commitments. Auction proceeds fund accelerated buildout timelines.
- Texas-Florida-California Demand Cluster:Population density intersecting with 5G priority markets creates concentrated deployment zones. These three states absorb disproportionate capital allocation.
- Monopole Technology:Smaller footprint designs streamline municipal zoning approvals. Urban and suburban jurisdictions favor these structures for aesthetic compliance.
Market Restraints
- Steel Price Volatility:Galvanized structural steel input costs fluctuate with commodity markets. Tower fabricators face margin compression during price spikes.
- FAA Part 77 Compliance:Structures exceeding 200 feet trigger obstruction lighting and marking mandates. These requirements extend permitting timelines and elevate operational costs.
- Fixed Wireless Substitution:Cable operators deploying millimeter-wave residential service threaten macro-site demand in suburban fringe markets.
Strategic Opportunities
- Rural Broadband Mandates:USDA ReConnect and FCC Rural Digital Opportunity Fund programs subsidize underserved area builds. Tower operators capture public financing for macro-site expansion.
- Edge Computing Co-location:Hyperscale cloud providers seek tower-adjacent real estate for distributed compute nodes. This convergence creates new tenancy revenue streams.
- California Streamlining Statutes:State-level wireless infrastructure siting reforms accelerate municipal approval processes. Deployment timelines compress in the largest addressable market.
Industry Challenges
- Climbing Technician Shortage:OSHA-certified tower erectors and maintenance crews remain scarce. Compensation inflation follows safety training requirements.
- Legacy Lease Renegotiation:Existing macro-site contracts carry below-market escalation clauses. Carriers exploit tenant concentration to resist rate adjustments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Telecom Towers Market |
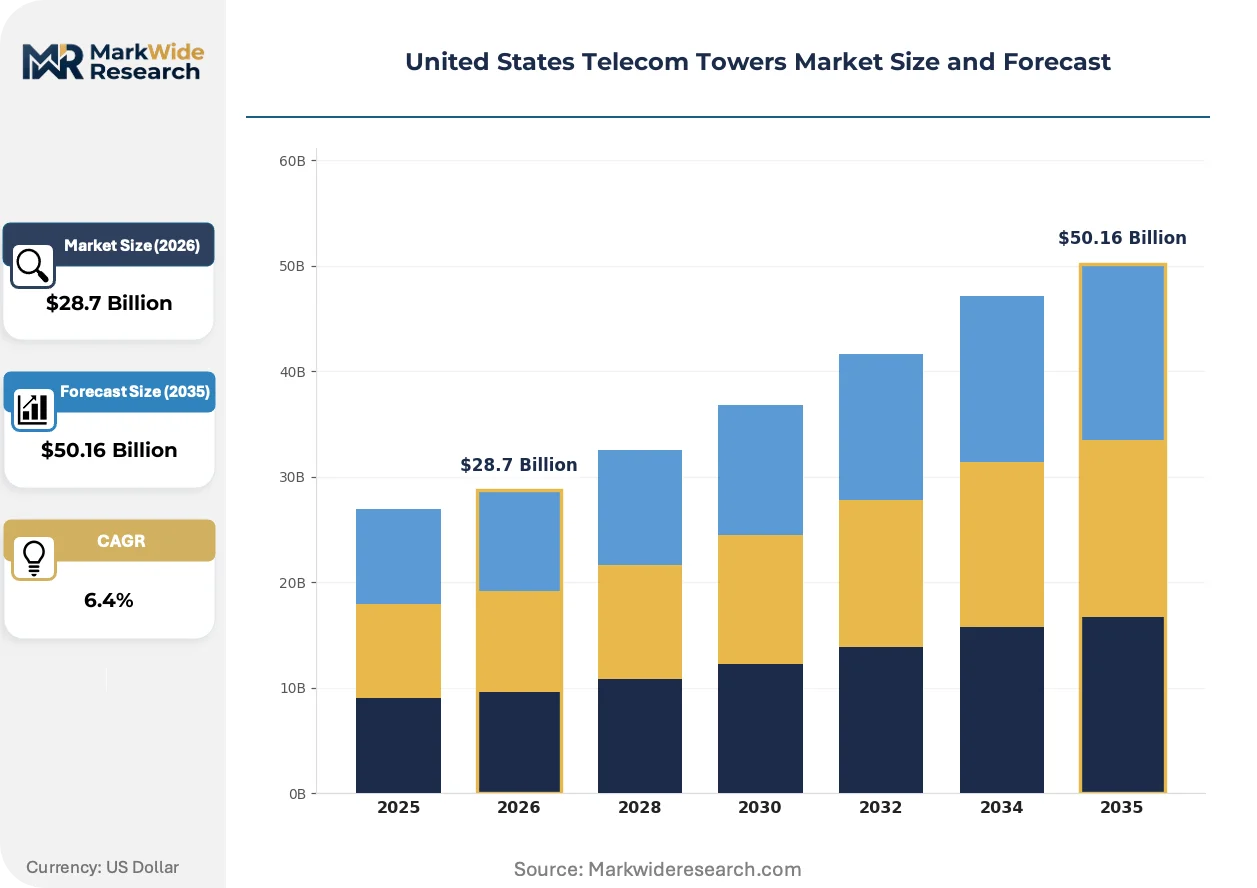
| Market Size in 2026 | $28.7 Billion |
| Market Size in 2035 | $50.16 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monopole, Lattice, Stealth, Guyed End User: Mobile Network Operators, Internet Service Providers, Government, Enterprises Installation Type: On-Grid, Off-Grid, Rooftop, Ground Technology: 4G LTE, 5G, Microwave, Fiber Optics |
| Companies Covered | Vertical Bridge, Tillman Infrastructure, American Tower Corporation, Diamond Communications, Steel In The Air, Crown Castle Inc., Phoenix Tower International, Harmoni Towers, SBA Communications Corp., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Telecom Towers Market Evolving Landscape
Carrier procurement models are pivoting from long-term tenancy toward infrastructure-as-a-service arrangements, compressing traditional lease structures while embedding performance guarantees.
Active antenna systems with integrated radio units are rewriting tower loading and power distribution specifications. Verizon and AT&T procurement teams specify these configurations for new builds. The technology is rewriting structural engineering standards as legacy passive antenna designs face obsolescence.
FCC tower registration requirements are tightening environmental and historical review integration. The industrial consequence is extended pre-construction timelines and elevated legal compliance costs. Texas and Florida jurisdictions are responding with dedicated wireless infrastructure coordinators to streamline dual-agency reviews.
Carrier network engineering teams are unbundling tower access from managed services, shifting toward direct equipment ownership and self-performed maintenance. This procurement pattern disrupts traditional turnkey providers. The shift is most visible in California markets where labor costs accelerate the business case for in-house technical staffing.
United States Telecom Towers Market Segmentation
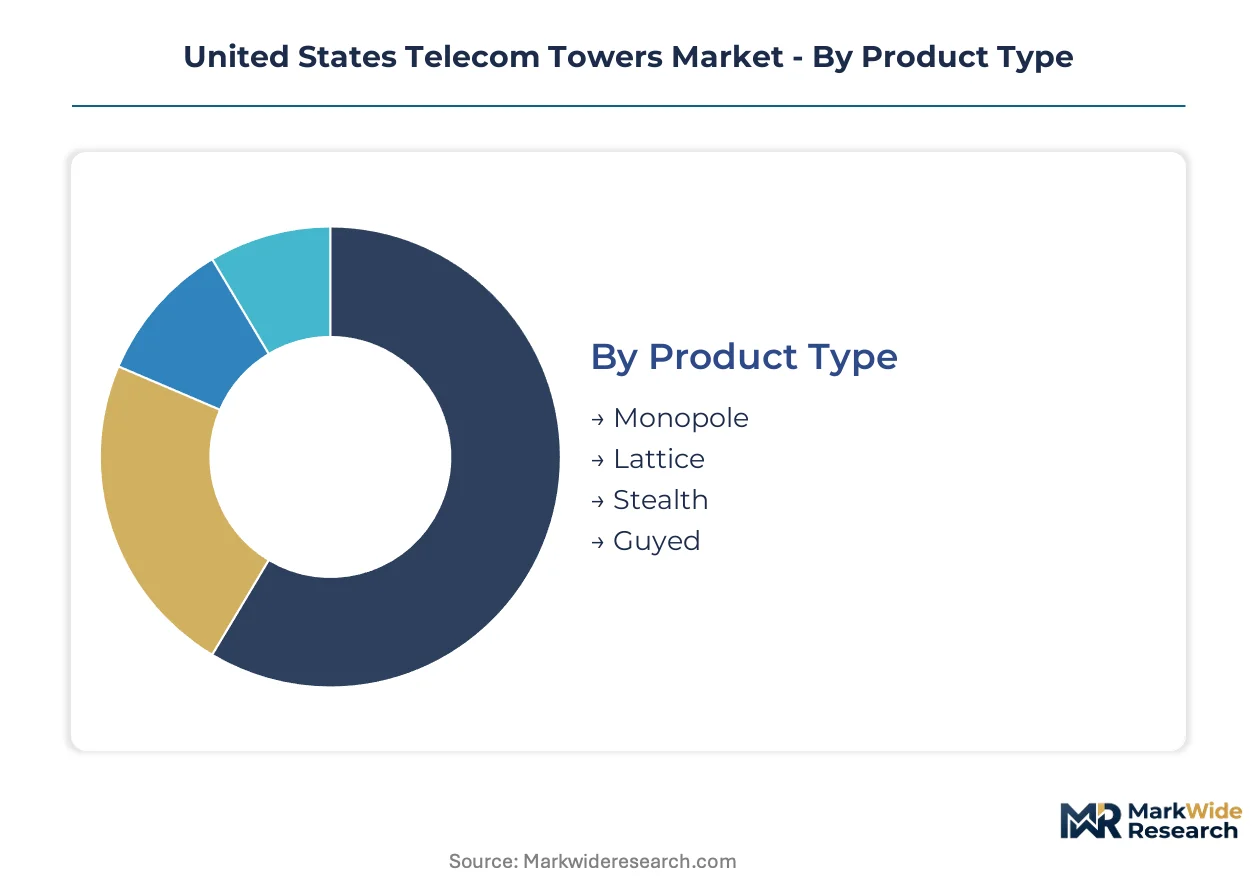
Tower selection criteria vary sharply across deployment scenarios. Carriers weigh zoning constraints, load capacity requirements, and power availability against total cost of ownership. Each segmentation dimension reveals distinct procurement patterns and margin structures.
Product Type:
Site acquisition teams prioritize footprint compatibility and visual impact above structural efficiency alone.
- Monopole:Single-pole steel or composite designs with diameters tapering from 8 to 15 feet support multiple carriers through sectorized mounting platforms. Municipal zoning boards in California and Florida approve these structures at higher rates due to reduced visual intrusion. 5G mid-band densification in Texas metro corridors is accelerating monopole procurement as carriers triple site counts.
- Lattice:Triangular or square-sectioned open-frame steel assemblies deliver superior load-bearing capacity for rural macro sites requiring extensive microwave backhaul. USDA ReConnect-funded builds in underserved counties favor lattice configurations for their cost efficiency at heights exceeding 300 feet. FAA Part 77 lighting mandates add operational complexity.
- Stealth:Architecturally disguised structures mimicking flagpoles, church steeples, or pine trees satisfy stringent aesthetic codes in affluent suburban jurisdictions. Palm Beach County and Orange County deploy these for high-revenue coverage zones.
- Guyed:Masts stabilized by tensioned cable arrays occupy the lowest cost tier for temporary or low-capacity deployments. Remote Alaska installations and emergency response networks utilize these for rapid field deployment.
Monopole leads on scale; stealth leads on momentum.
End User:
Contract structures and lease durations diverge based on tenant credit quality and infrastructure ownership models.
- Mobile Network Operators:AT&T, Verizon, and T-Mobile dominate tenancy with 10-15 year master lease agreements. These carriers drive specifications for active antenna integration and edge computing readiness.
- Internet Service Providers:Fixed wireless providers including cable operators lease tower access for millimeter-wave residential service. Their suburban fringe deployments threaten traditional macro-site demand in select markets.
- Government:Federal, state, and municipal agencies procure towers for public safety networks and emergency communications. FirstNet Authority deployments follow hardened infrastructure standards.
- Enterprises:Mining operations, agricultural conglomerates, and logistics hubs construct private networks for campus coverage. These deployments favor off-grid power integration.
Mobile network operators anchor revenue concentration; internet service providers are expanding most quickly.
Installation Type:
Power availability and real estate access determine deployment feasibility across rural-urban gradients.
- On-Grid:Grid-connected installations with dedicated utility service dominate urban and suburban macro sites. Texas and California utilities require extended interconnection timelines that compress deployment windows.
- Off-Grid:Solar-battery hybrid or diesel generator systems enable rural coverage extension where utility infrastructure is absent. USDA ReConnect subsidies improve project economics.
- Rooftop:Building-mounted installations leverage existing structures in dense urban cores. San Francisco and Manhattan zoning codes restrict ground-based alternatives.
- Ground:Traditional greenfield tower construction on dedicated parcels retains preference for capacity-intensive rural macro sites.
On-grid commands the largest installed base; off-grid gains share fastest.
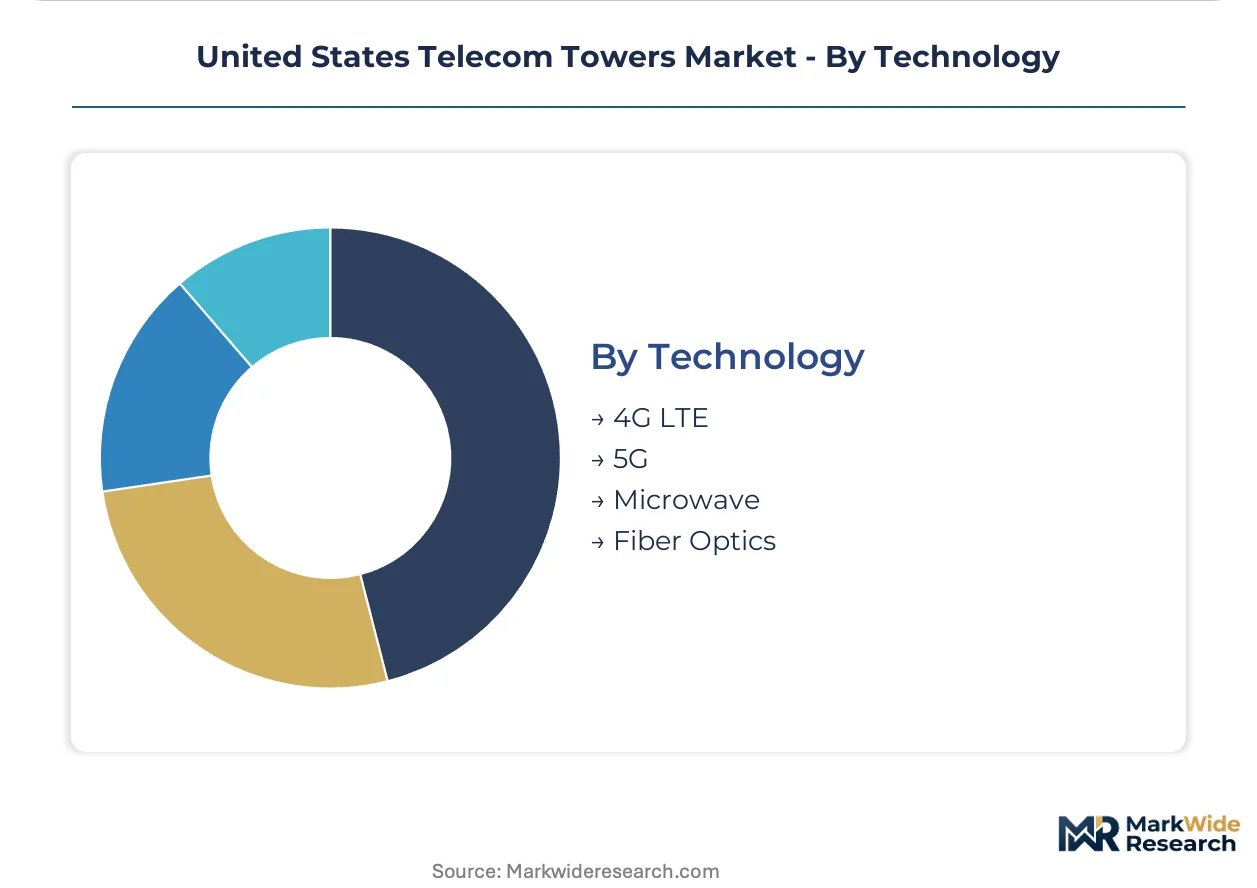
Technology:
Radio generation and backhaul method dictate power, weight, and spatial requirements.
- 4G LTE:Legacy macro-layer infrastructure supports voice and mid-band data services. Carriers maintain these assets for coverage continuity while overlaying 5G.
- 5G:Millimeter-wave and C-band deployments demand densified site spacing and upgraded power distribution. Active antenna systems with integrated radios are rewriting loading specifications.
- Microwave:Point-to-point radio backhaul connects remote towers to fiber aggregation points. FCC licensing governs frequency coordination.
- Fiber Optics:Direct fiber connectivity enables highest-capacity fronthaul for distributed antenna systems and small-cell hubs.
4G LTE maintains the broadest footprint; 5G shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Texas concentrates tower deployment capital more heavily than California despite the latter's larger population base, reflecting divergent zoning efficiency and carrier rollout priorities across state jurisdictions.
Texas
Houston and Dallas-Fort Worth metro corridors absorb disproportionate 5G mid-band densification investment from national carriers. The Texas Commission on Environmental Quality coordinates with municipal governments to streamline tower siting permits. Austin's technology corridor hosts dense small-cell deployments serving enterprise and residential demand clusters.
California
Los Angeles and San Francisco Bay Area markets drive stealth tower procurement for aesthetic compliance in affluent jurisdictions. The California Public Utilities Commission oversees utility interconnection timelines that compress deployment windows. San Diego's border proximity creates specialized capacity requirements for cross-border roaming infrastructure.
Florida
Miami and Orlando metropolitan areas prioritize hurricane-hardened tower specifications for network resilience. The Florida Department of Transportation coordinates highway corridor siting through dedicated wireless infrastructure coordinators. Palm Beach County deploys architecturally disguised structures for high-revenue coverage zones.
Southeast
Atlanta anchors regional backhaul aggregation with fiber-connected macro sites serving the broader Georgia-Carolinas corridor. State-level wireless infrastructure streamlining statutes accelerate municipal approval processes. Charlotte and Raleigh-Durham markets concentrate edge computing co-location demand from financial services tenants.
Mountain West
Denver and Phoenix markets balance urban densification with rural coverage extension into underserved counties. USDA ReConnect subsidies improve project economics for off-grid solar-battery installations. Salt Lake City's logistics hub concentration drives private network construction for warehouse automation.
United States Telecom Towers Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the tower ecosystem, producing a tiered structure where scale advantages separate national portfolio operators from regional site developers. The market concentrates tenancy revenue among entities controlling dense metropolitan asset clusters. Three archetypes dominate: nationwide portfolio scale players, urban small-cell integrators, and rural macro-site specialists. Competitive dynamics center on long-term lease renewal rates and strategic site acquisition in priority corridors.
Within the nationwide scale tier, American Tower Corporation and Crown Castle Inc. exemplify divergent strategic positioning through portfolio composition emphasis. Vertical Bridge anchors the rural-specialist archetype with suburban and exurban macro-site concentration. These three entities collectively represent the spectrum of competitive approaches visible across the industry structure, from fiber-integrated urban density to distributed rural coverage extension.
| Leading Market Players |
|---|
| Vertical Bridge |
| Tillman Infrastructure |
| American Tower Corporation |
| Diamond Communications |
| Steel In The Air |
| Crown Castle Inc. |
| Phoenix Tower International |
| Harmoni Towers |
| SBA Communications Corp. |
| Others |
Value Network & Pricing Analysis
OSHA fall protection compliance gates both qualified tower erector supply and premium-tier lease rate access, as carriers demand certified maintenance crews bundled into long-term tenancy agreements. Steel price volatility and FAA obstruction mandates further stratify procurement economics across urban monopole and rural lattice deployments.
Pricing Analysis
Capacity additions in Texas metro corridors are reshaping price floors for monopole installations as national carriers triple site counts. Three-tier pricing structure across premium stealth, standard monopole, and economy lattice levels reflects zoning compliance burden and load capacity specifications. Price differentiation hinges on FAA Part 77 lighting requirements and active antenna system integration. Cost compression in economy lattice tiers is intensifying because galvanized steel input costs fluctuate with commodity markets. Fixed wireless providers exhibit highest price sensitivity; mobile network operators with master lease agreements show lowest.
Supply Chain Analysis
Single-source vulnerability sits with domestic steel fabricators concentrated in the Great Lakes and Gulf Coast regions. Tower manufacturing draws from South Korean and Chinese steel inputs alongside domestic galvanized structural steel. Raw material dependencies include high-strength steel alloys, obstruction lighting systems, and composite stealth cladding materials. Tariff exposure on imported steel components elevates landed cost volatility. Distribution runs through tower operators with nationwide portfolio scale, who aggregate tenancy demand and contract directly with regional fabricators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States telecom towers market represents a late-cycle quality story as 5G mid-band densification shifts carrier procurement toward premium specifications for active antenna integration and edge computing readiness.
For Market Incumbents: Lock in long-term tenancy renewals before legacy lease renegotiation pressure intensifies. Defend portfolio positions by acquiring strategic corridor sites in Texas-Florida-California demand clusters. Vertical integration into certified tower erector crews mitigates OSHA climbing technician shortage risks. For New Entrants and Emerging Players: Direct-to-tower-operator digital procurement platforms offer lower-friction entry into rural broadband mandate programs. Target USDA ReConnect-subsidized counties in Mountain West and Southeast regions where incumbent coverage gaps persist. Position around off-grid solar-battery hybrid installations as the most penetrable installation type. For Investors and Strategic Acquirers: Roll-up economics work for rural macro-site specialists because tenancy revenue concentrates among entities controlling dense metropolitan asset clusters. Five-to-ten year viability hinges on carrier infrastructure-as-a-service procurement model adoption. Monitor FCC spectrum auction proceeds as the signal to watch for capital deployment inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Active Antenna System Integration | Verizon and AT&T procurement teams specify integrated radio configurations that rewrite tower loading standards. |
| Edge Computing Co-location | Hyperscale cloud providers seek tower-adjacent real estate for distributed compute nodes in Charlotte and Raleigh-Durham markets. |
| Rural Broadband Infrastructure Expansion | USDA ReConnect and FCC Rural Digital Opportunity Fund programs subsidize underserved area macro-site builds. |
| Stealth Tower Procurement | Los Angeles and San Francisco Bay Area markets drive architecturally disguised structures for aesthetic compliance. |
| Certified Maintenance Crew Development | OSHA fall protection training requirements create scarcity economics for qualified tower erectors and maintenance technicians. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with tower operator portfolio managers, carrier network engineering directors, municipal zoning officials, steel fabricator procurement leads, and FCC regulatory specialists with secondary validation. Secondary sources encompassed FCC tower registration databases, FAA obstruction filings, USDA ReConnect program disbursement records, and SEC 10-K infrastructure disclosures. Bottom-up site count modeling and top-down carrier capex allocation analysis provided cross-verification.
Segment-weighting approaches distributed value across product type, end user, installation configuration, and technology generation dimensions. CAGRs were derived from carrier infrastructure commitment timelines and public financing program allocations across the projection horizon. Industry-specific forecast inputs included 5G mid-band densification site spacing requirements and state-level wireless infrastructure siting reform implementation schedules.
The model assumes a particular technology adoption path; alternative pathways for millimeter-wave fixed wireless substitution would alter the outlook. Forecasts reflect assumptions regarding carrier tenancy renewal rates and steel input cost stabilization. Regulatory shifts in FAA obstruction standards or FCC environmental review integration could revise deployment timelines. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications Infrastructure
Asia Pacific Voice Over LTE Market
Telecommunications Infrastructure
OTN Equipment Market
Telecommunications Infrastructure
Small Cell Backhaul Market
Telecommunications Infrastructure
Global Mobile and Wireless Backhaul Equipment Market
Telecommunications Infrastructure
5G Network Infrastructure Market
Telecommunications Infrastructure
Global Cellular Networks Market
Telecommunications Infrastructure
Africa Telecom Towers and Allied Market
Telecommunications Infrastructure
Nepal Telecom Market
Telecommunications Infrastructure
Global Telecom Cable Market
Telecommunications Infrastructure
Canada Telecom Towers Market
Telecommunications Infrastructure
5G Infrastructure Market
Telecommunications Infrastructure
Morocco Telecom Tower Market
Telecommunications Infrastructure
Fixed Telephony Service Market
Telecommunications Infrastructure
Thailand Telecom Towers Market
Telecommunications Infrastructure
Israel Telecom Market
Telecommunications Infrastructure
5G Infrastructure Equipment Market