
 Tongue Scraper Market | 2026-2036
Tongue Scraper Market Size, Share, and Industry Trends Forecast 2026-2036
Tongue Scraper Market Insights
REACH compliance is rebalancing material sourcing costs for European manufacturers, compelling suppliers to certify full supply chain documentation for stainless steel and medical-grade silicone inputs. Dr. Tung's leverages its established distribution through natural health retailers to sustain premium positioning in North America. Orabrush competes through direct-to-consumer digital channels that bypass traditional dental retail gatekeepers. DenTek anchors mass-market shelf presence through pharmacy chain partnerships across the United States.
A tongue scraper is a curved or flat instrument designed to remove bacterial coating, dead cells, and debris from the dorsal surface of the tongue, typically measuring 5–7 inches in length with a scraping edge precision-formed to 0.5–1.0 mm thickness to balance efficacy against mucosal trauma. Metal scrapers fabricated from surgical-grade stainless steel dominate professional dental settings due to autoclavability and indefinite service life, while silicone variants capture personal care consumers seeking flexible, non-traumatic home use. Halitosis control applications command the strongest margin pools as consumers link visible tongue debris to social and professional confidence, whereas plaque reduction sits at earlier stages of clinical validation.
The FDA Center for Devices and Radiological Health classifies manual tongue cleaners as Class I medical devices exempt from premarket notification, lowering US entry barriers while still requiring quality system compliance. The EU MDR and ECHA REACH frameworks impose stricter substance restrictions and clinical evidence thresholds on instruments claiming therapeutic outcomes. Stakeholders must monitor diverging regulatory stringency between jurisdictions as it determines whether premium positioning through clinical claims or commodity positioning through general wellness framing proves more defensible.
Market Dynamics
The EU Medical Device Regulation is forcing material traceability upgrades across European supply chains, compelling stainless steel processors to document alloy composition from smelter to finished instrument. This regulatory pressure is reshaping competitive positioning toward certified suppliers while squeezing undifferentiated commodity producers.
Growth Catalysts
- EU MDR compliance mandates:Dental clinics in Germany and France now require autoclavable instruments with full supply chain documentation, accelerating replacement cycles for legacy scrapers.
- Ayurvedic wellness integration:Copper tongue scrapers are gaining traction among personal care consumers in India where traditional medicine practices drive daily oral hygiene rituals.
- Halitosis-conscious professional segments:Corporate wellness programs in the United States are distributing branded tongue cleaners as part of employee health initiatives.
Market Restraints
- Nickel price volatility:Surgical-grade stainless steel formulations depend on nickel alloys, and London Metal Exchange price swings compress margins for European fabricators.
- Silicone import concentration:Medical-grade silicone supply for flexible scrapers concentrates among a handful of Southeast Asian compounders, creating single-source vulnerability.
- FDA exemption ceiling:Class I device status bars manufacturers from making therapeutic claims, limiting premium pricing for clinically validated designs.
Strategic Opportunities
- Brazilian market underpenetration:ANVISA regulatory pathways for oral care devices remain less stringent than EU or US equivalents, enabling faster market entry for compliant exporters.
- Subscription oral care bundles:Direct-to-consumer brands are integrating tongue scrapers into recurring shipment models alongside toothpaste and floss.
- ISO 13485 certification arbitrage:Quality management certification is becoming a de facto requirement for hospital procurement tenders in Saudi Arabia and the UAE.
Industry Challenges
- Biocompatibility testing timelines:Cytotoxicity and sensitization studies for novel polymer formulations add 18-24 months to product development cycles.
- Autoclave validation protocols:Dental service organizations demand documented sterilization cycle endurance, requiring capital investment in accelerated aging equipment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tongue Scraper Market |
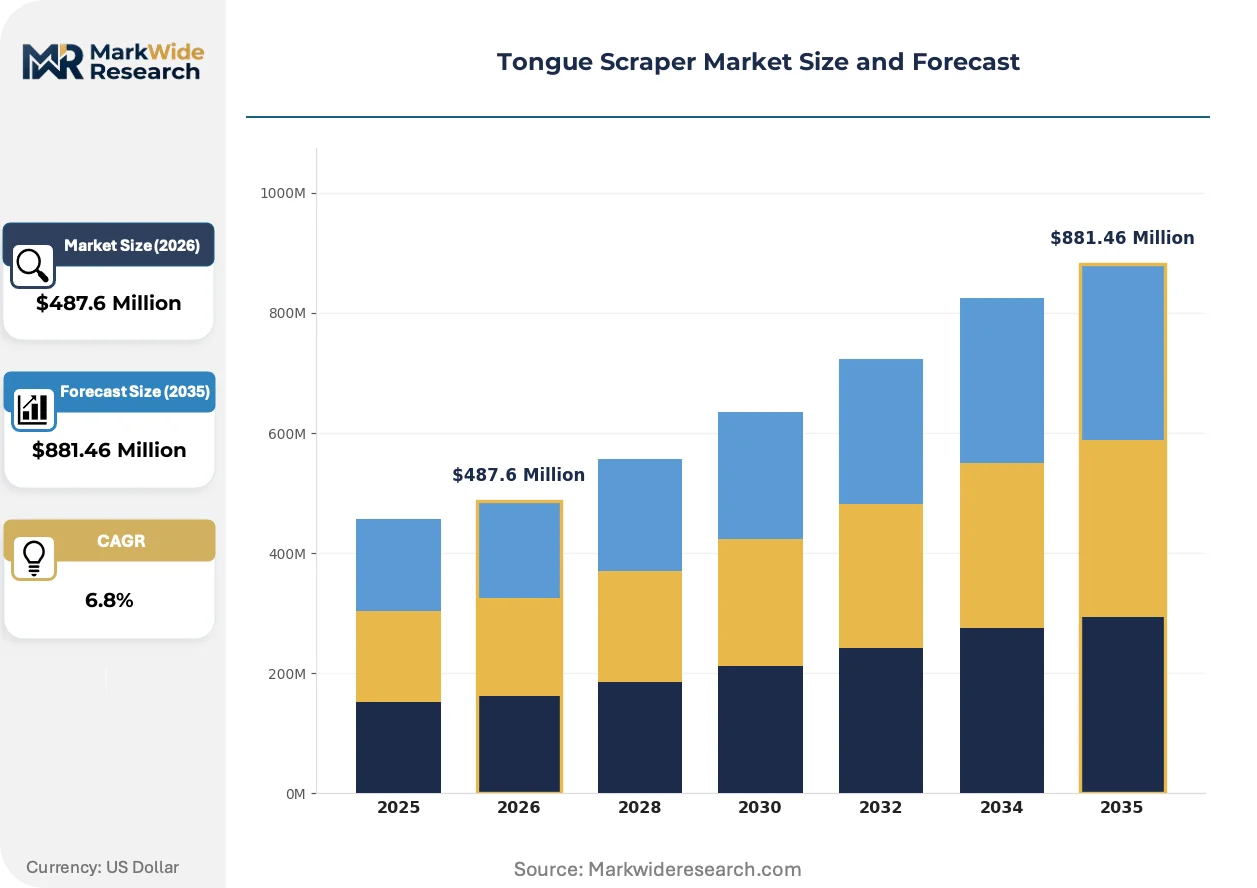
| Market Size in 2026 | $487.6 Million |
| Market Size in 2035 | $881.46 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Scrapers, Plastic Scrapers, Silicone Scrapers, Bamboo Scrapers, Dual-Ended Scrapers Material: Stainless Steel, Medical-Grade Silicone, Bamboo Fiber, Polypropylene, Thermoplastic Elastomer Application: Oral Hygiene, Halitosis Control, Plaque Reduction, Taste Enhancement End User: Dental Clinics, Personal Care Consumers, Wellness Centers, Dental Retailers |
| Companies Covered | Dr. Tung's, Orabrush, DenTek, GUM, Oxyfresh, Supersmile, TePe, Water Pik, TheraBreath, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tongue Scraper Market Trends and Innovations
Smart oral care ecosystems are pulling tongue scrapers into connected health platforms, with pressure sensors and Bluetooth modules appearing in premium personal care launches. Material science advances and regulatory digitization are simultaneously elevating performance standards and compliance burdens.
Copper-infused polymer formulations are converging with antimicrobial surface engineering to deliver sustained bacterial reduction between uses. Wellness retailers in California and New York are stocking these hybrid designs at 40-60% price premiums over baseline stainless steel. The convergence is compressing addressable market share for pure metal fabricators unable to source compliant polymer substrates.
ECHA REACH substance restrictions are tightening limits on nickel release rates from metal alloys that contact mucosal tissue. German dental instrument distributors now require third-party migration testing certificates before adding suppliers to approved vendor lists. Stainless steel grades 316L and 304 with modified surface passivation are capturing preference in professional channels.
Consumers are abandoning single-use plastic scrapers for durable alternatives with documented environmental footprints. Refill and repair service models are displacing disposable consumption patterns in Scandinavian markets. Retailers in Sweden and Norway now feature take-back programs for metal scrapers at end-of-life, with material recovery rates becoming a visible purchase criterion.
Tongue Scraper Market Segmentation
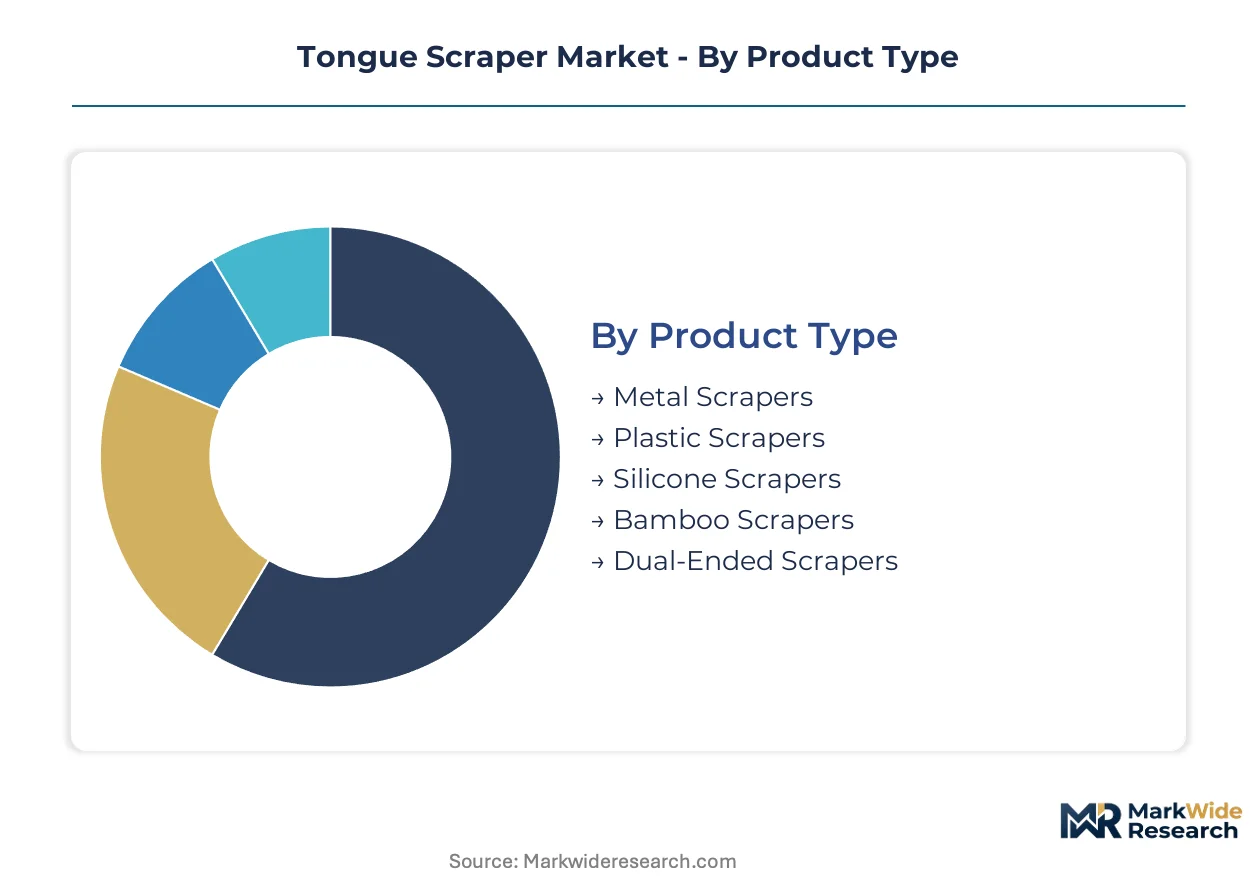
Material composition and sterilization compatibility determine procurement pathways for tongue scrapers. Dental service organizations impose divergent specifications from personal care retailers, fragmenting supplier strategies across clinical and consumer channels.
Product Type:
Surgical-grade metal instruments anchor professional procurement due to thermal sterilization tolerance, while polymer variants serve cost-sensitive home use segments.
- Metal Scrapers:Fabricated from austenitic stainless steel grades 304 and 316L with electropolished scraping edges measuring 0.5–0.8 mm thickness. German and French dental clinics now mandate full EU MDR traceability documentation, accelerating replacement of legacy instruments lacking smelter-to-finished-goods certification.
- Silicone Scrapers:Medical-grade elastomer formulations offer flexible, non-traumatic contact surfaces suited for sensitive mucosal tissue. California wellness retailers stock these at substantial premiums over metal alternatives, driven by consumer preference for antimicrobial copper-infused hybrid designs.
- Plastic Scrapers:Polypropylene and ABS constructions dominate pharmacy chain shelf presence through DenTek and comparable mass-market distributors across the United States.
- Bamboo Scrapers:Renewable fiber composites target Scandinavian sustainability mandates, with Swedish retailers now featuring end-of-life material recovery programs.
- Dual-Ended Scrapers:Combined scraping and brushing surfaces serve travelers and compact storage preferences in Japanese urban markets.
Mature deployment sits with metal scrapers in European dental clinics. Newer deployment is concentrated in silicone variants for North American wellness consumers.
Material:
Supply chain documentation requirements are rebalancing procurement weights toward certified alloy suppliers and away from commodity polymer compounders.
- Stainless Steel:Surgical grades 316L and modified 304 with enhanced passivation layers satisfy ECHA REACH nickel release limits for mucosal contact devices. German distributors require third-party migration testing certificates before vendor list inclusion.
- Medical-Grade Silicone:Platinum-cured elastomer formulations from Southeast Asian compounders supply flexible scraper production, though concentration among limited suppliers creates single-source vulnerability for European fabricators.
- Bamboo Fiber:Compressed lignocellulosic composites serve Nordic environmental compliance requirements with documented carbon footprint advantages over petroleum-based alternatives.
- Polypropylene:Injection-molded homopolymer constructions enable lowest-unit-cost production for pharmacy and supermarket private label programs.
- Thermoplastic Elastomer:TPE overmolding delivers grip-enhanced handles for aging consumer demographics in Japanese and South Korean markets.
Stainless steel captures the steepest expansion trajectory in professional channels. Thermoplastic elastomer adoption is climbing fastest in ergonomic home-use designs.
Application:
Clinical validation depth determines pricing authority, with therapeutic claims requiring regulatory substantiation that general wellness positioning avoids.
- Halitosis Control:Volatile sulfur compound reduction claims command strongest margin pools as consumers link visible tongue debris to professional and social confidence. Corporate wellness programs in the United States distribute branded instruments under this positioning.
- Oral Hygiene:General bacterial load reduction framing bypasses FDA premarket notification requirements for Class I exempt devices, enabling faster commercialization cycles.
- Plaque Reduction:Biofilm disruption applications sit at earlier stages of clinical validation, limiting premium pricing authority despite mechanistic plausibility.
- Taste Enhancement:Fungiform papillae cleaning claims target gastronomy enthusiasts and wine tasting demographics in France and Italy.
Mature deployment sits with oral hygiene in mass retail. Newer deployment is concentrated in halitosis control through professional and corporate channels.
End User:
Procurement sophistication varies sharply between institutional tenders and individual purchase decisions, fragmenting go-to-market requirements.
- Dental Clinics:Autoclavable instrument specifications with documented sterilization cycle endurance dominate German and French procurement tenders. ISO 13485 quality management certification is becoming de facto mandatory for hospital system vendors in Saudi Arabia and the UAE.
- Personal Care Consumers:Direct-to-consumer digital channels bypass traditional dental retail gatekeepers, with subscription bundle models integrating scrapers into recurring oral care shipments.
- Wellness Centers:Ayurvedic tradition alignment drives copper scraper uptake in Indian metropolitan markets where traditional medicine practices shape daily hygiene rituals.
- Dental Retailers:Pharmacy chain partnerships anchor mass-market shelf presence, with placement fees and promotional calendars determining competitive viability.
Mature deployment sits with dental retailers in established Western markets. Newer deployment is concentrated in wellness centers across South Asian traditional medicine corridors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India concentrates the strongest personal care demand for tongue scrapers, where Ayurvedic wellness traditions embed daily tongue cleaning into household hygiene routines across metropolitan and tier-two cities.
United States
Corporate wellness programs distribute branded tongue cleaners to employees, linking oral hygiene to professional confidence. The FDA Center for Devices and Radiological Health classifies manual cleaners as Class I exempt devices, lowering entry barriers for direct-to-consumer brands. Los Angeles and New York wellness retailers stock copper-infused silicone variants at substantial premiums.
Germany
Dental clinics in Munich and Hamburg mandate autoclavable stainless steel instruments with full EU MDR traceability documentation. ECHA REACH nickel release limits compel fabricators to source modified 316L and 304 grades with enhanced passivation. Berlin-based distributors require third-party migration testing certificates before vendor list inclusion.
India
Ayurvedic practitioners in Mumbai and Delhi recommend copper scrapers for antimicrobial properties rooted in traditional medicine. The Bureau of Indian Standards governs metal content in consumer wellness products. Bangalore wellness centers integrate tongue scraping into subscription oral care bundles targeting urban professionals.
Sweden
Scandinavian sustainability mandates drive consumer abandonment of single-use plastic scrapers for bamboo and metal alternatives. Retailers in Stockholm and Oslo operate take-back programs with documented material recovery rates. The Swedish Chemicals Agency enforces strict substance restrictions on polymers contacting mucosal tissue.
Brazil
ANVISA regulatory pathways for oral care devices remain less stringent than EU or US equivalents, enabling faster market entry for compliant exporters. São Paulo pharmacy chains expand shelf space for imported stainless steel scrapers. Rio de Janeiro wellness startups pilot subscription models integrating tongue cleaners with toothpaste shipments.
Tongue Scraper Market Competitive Landscape
German fabricators anchor the professional-tier supply base; California wellness specialists hold the premium personal care vector. Market structure fragments across clinical certification requirements and consumer branding imperatives. Three archetypes dominate: ISO 13485-certified surgical instrument suppliers, direct-to-consumer digital natives, and mass-market pharmacy distributors. Capacity expansion and strategic partnerships represent the dominant competitive moves as players bridge channel divides.
Within the premium wellness tier, Dr. Tung's and Orabrush occupy positions shaped by divergent distribution strategies. Dr. Tung's exemplifies natural health retail anchoring through established shelf relationships. Orabrush represents direct-to-consumer digital channel bypassing of traditional gatekeepers. DenTek sits within the mass-market archetype, anchoring pharmacy chain presence across United States retail networks.
| Leading Market Players |
|---|
| Dr. Tung's |
| Orabrush |
| DenTek |
| GUM |
| Oxyfresh |
| Supersmile |
| TePe |
| Water Pik |
| TheraBreath |
| Others |
Pricing and Supply Chain Analysis
Family-owned mid-cap fabricators in Germany and India anchor supply-side discipline through generational ownership structures that resist short-term margin compression. Their patient capital deployment sustains certified alloy inventories through nickel price cycles, insulating professional-tier pricing from spot-market volatility that erodes commodity competitors.
Pricing Analysis
Short lead-time premiums of fifteen to twenty percent apply to EU MDR-certified stainless steel instruments for German dental clinics facing replacement deadlines. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13485-certified surgical grades from uncertified personal care variants and mass-market plastic alternatives. Cost compression in economy tiers is intensifying because polypropylene compounders in Southeast Asia are absorbing resin price spikes to defend pharmacy chain contracts. Corporate wellness programs show least price sensitivity, while individual consumers through supermarket channels exhibit highest elasticity.
Supply Chain Analysis
Dual-sourcing mandates from French and German dental service organizations now require qualified backup suppliers for all autoclavable instrument categories. Manufacturing concentrates in Germany, India, and China, with surgical-grade stainless steel drawing from Swedish and Finnish smelters. Medical-grade silicone hinges on platinum-cured elastomer from Thai and Malaysian compounders. Single-source vulnerability in Southeast Asian polymer supply creates exposure to regional logistics disruptions. Distribution runs through specialized dental instrument distributors in Europe, direct-to-consumer platforms in North America, and Ayurvedic wellness retailers in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is becoming a vertical-integration race as players pursue captive control over EU MDR-compliant alloy supply to escape nickel price volatility and certification bottlenecks.
For Market Incumbents: Extend certification moats by acquiring distressed stainless steel processors with existing smelter-to-finished-goods documentation. Deepen hospital system partnerships in Saudi Arabia and the UAE before ISO 13485 becomes mandatory, locking out undifferentiated competitors. For New Entrants and Emerging Players: Capture Brazilian pharmacy channel shelf space ahead of ANVISA pathway tightening, using expedited regulatory positioning against EU-validated exporters. Target subscription oral care bundles in Rio de Janeiro and São Paulo, integrating tongue scrapers with toothpaste and floss shipments. For Investors and Strategic Acquirers: Distressed-cycle entries favor EU MDR-certified mid-cap fabricators in southern Germany facing working capital pressure from nickel alloy cost spikes. Long-term viability centers on quality management certification depth rather than brand recognition. The inflection signal to watch is ANVISA harmonization with EU MDR standards, which would strand non-compliant Brazilian inventory.| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Certification Investment | Full traceability documentation unlocks German and French dental clinic procurement tenders. |
| Backward Integration into Alloy Supply | Captive sourcing of 316L stainless steel insulates margins from London Metal Exchange volatility. |
| Subscription Bundle Launch | Recurring shipment models with toothpaste and floss build predictable revenue in North America. |
| ANVISA Fast-Track Entry | Expedited Brazilian regulatory pathway enables market share capture before standards tighten. |
| ISO 13485 Quality Certification | Hospital system vendor qualification in Gulf Cooperation Council markets requires documented compliance. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with dental instrument procurement managers, Ayurvedic wellness retailers, biomedical engineers at hospital systems, and GPO contracts managers combined with FDA 510(k) exemptions databases, EU MDR notified body certificates, and Bureau of Indian Standards metal content specifications. Bottom-up channel volume estimates and top-down macroeconomic triangulation validated segment sizing.
Reconciliation of production volume data from German and Indian fabricators with import statistics from Brazilian and Swedish customs authorities informed the analytical framework across the analysis window. Segmentation dimensions modeled include material composition, sterilization compatibility, end-user procurement sophistication, and regional regulatory cluster. CAGRs derived from weighted average of historical replacement cycle analysis and projected compliance-driven upgrade rates. Nickel price trajectory assumptions and EU MDR implementation timelines served as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ANVISA regulatory harmonization and REACH substance restriction expansion. Deviation in nickel alloy cost trajectories or ECHA nickel release limit tightening would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Health
Global OTC Hair Loss Treatment Market
Personal Health
Asia Pacific Hair Loss Treatment Products Market
Personal Health
Health Check-Up Market
Personal Health
Maternity Personal Care Products Market
Personal Health
High Concentration Respiratory Masks Market
Personal Health
Sleep Mask Market
Personal Health
Disposable Underwear Market
Personal Health
Piercing Aftercare Spray Market
Personal Health
Feminine Hygiene Market
Personal Health
Sextech and Sexual Wellness Market
Personal Health
Corporate Wellness Market
Personal Health
North America Hair Loss Treatment Products Market
Personal Health
Menstrual Cup Market
Personal Health
Skin Tag Remover Market
Personal Health
Blackhead Removing Vacuum Market
Personal Health
Smoking Cessation and Nicotine De Addiction Market