
 Dental Orthodontic Wax Market | 2026-2036
Dental Orthodontic Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Orthodontic Wax Market Analysis
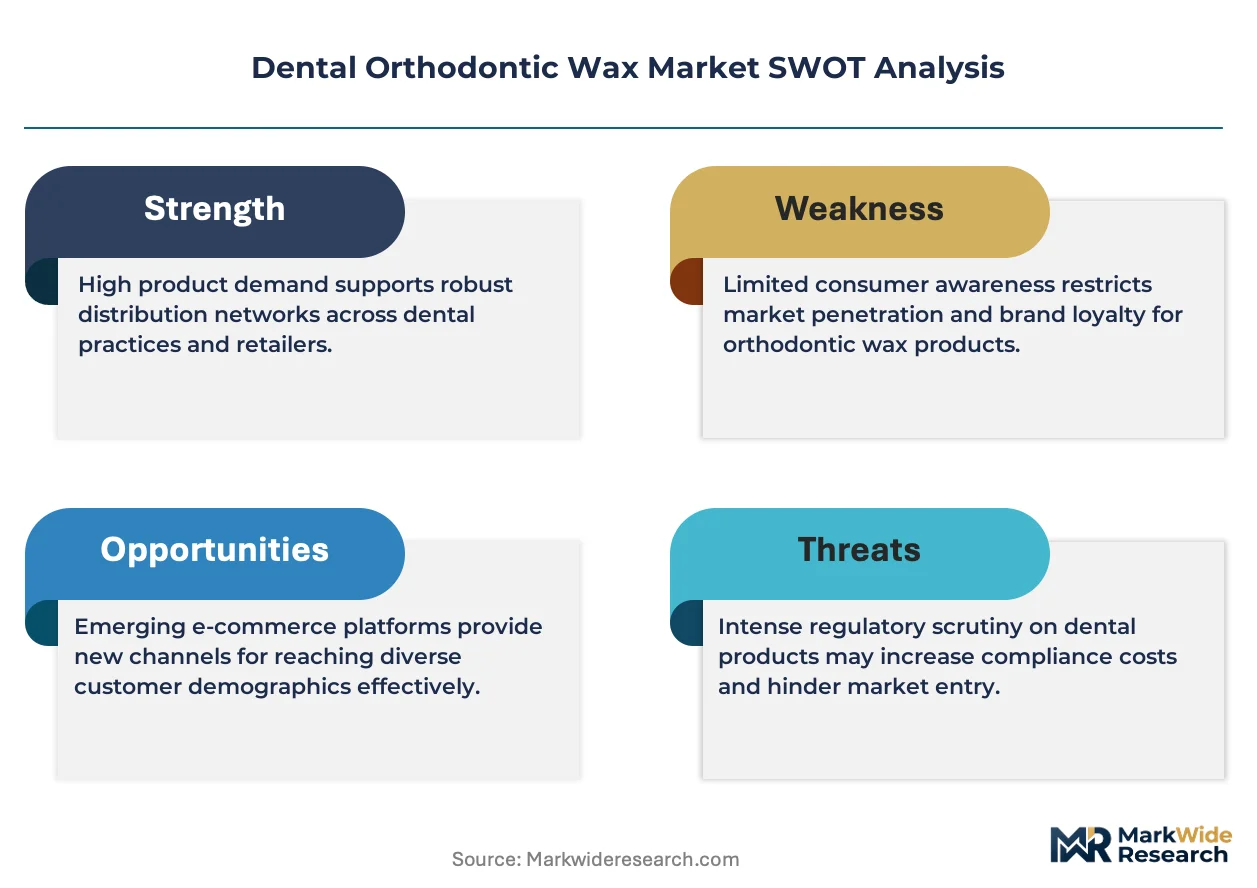
Medical-grade paraffin and microcrystalline formulations are unwinding low-spec commodity supply as practitioners and patients prioritize biocompatibility certificates and ISO 10993 compliance. Colgate-Palmolive Company leverages its retail pharmacy channel dominance to push flavored and colored wax SKUs into home care segments. Bracon Dental anchors European orthodontic clinic supply through specialized bite wax formulations. DWS Systems differentiates via synthetic wax R&D targeting hypoallergenic patient profiles.
Dental orthodontic wax comprises pliable, non-toxic formulations—typically paraffin, beeswax, or synthetic polymer blends with melting points between 46°C and 68°C—applied to orthodontic brackets and wires to prevent mucosal irritation and ulceration during treatment. The product serves as a first-line patient comfort intervention across fixed appliance orthodontics. Flavored wax generates premium pricing power among pediatric and adolescent end users, while synthetic wax materials capture fastest-growing demand from allergy-sensitive patient populations. Orthodontic clinics remain the dominant end-user channel, though home care purchasing through e-commerce and retail pharmacy blisters accelerates as direct-to-consumer aligner brands bundle wax into starter kits.
FDA 510(k) clearance pathways and CE marking under the EU Medical Device Regulation govern dental wax biocompatibility, driving manufacturers toward ISO 10993-5 cytotoxicity testing and documented shelf-life validation. REACH compliance in Europe and state-level dental board procurement specifications in the United States further filter market access for uncertified suppliers. Stakeholders must monitor evolving MDR classification debates and patient-direct subscription model regulatory clarity as channel structures fragment across professional and retail boundaries.
Market Dynamics
Clear aligner manufacturers bundling orthodontic wax into direct-to-consumer starter kits is fragmenting traditional clinic-centric distribution, forcing incumbent suppliers to build e-commerce fulfillment capabilities or lose patient touchpoints.
Growth Catalysts
- EU Medical Device Regulation (MDR) implementation:CE marking requirements for biocompatibility testing under MDR Article 10 are filtering out uncertified suppliers, concentrating procurement among ISO 10993-compliant manufacturers with documented shelf-life validation.
- Adolescent orthodontic volume expansion:Rising bracket-based and aligner treatment rates among teen patients in the United States and Germany are elevating wax consumption as a standard comfort protocol.
- Hypoallergenic synthetic formulations:Petroleum-derived paraffin alternatives with documented cytotoxicity clearance are capturing allergy-sensitive patient segments previously underserved by beeswax and mineral oil blends.
Market Restraints
- Medical-grade paraffin supply concentration:Feedstock for premium wax formulations depends on a narrow base of refined petroleum suppliers in the United States and Germany, exposing margins to upstream price volatility.
- REACH compliance burden:ECHA substance registration requirements for synthetic polymer additives create fixed compliance costs that disproportionately burden small-batch European manufacturers.
- Silicone-based oral protectants:Reusable silicone barrier products for bracket irritation are gaining traction among adult orthodontic patients as durable substitutes to disposable wax.
Strategic Opportunities
- Direct-to-consumer aligner bundling:Partnerships with teledentistry platforms to include wax in home impression kits open patient acquisition channels outside traditional orthodontic clinic procurement.
- Japan's aging orthodontic market:Adult treatment volume in Tokyo and Osaka metropolitan areas is expanding faster than pediatric cases, creating demand for discreet, unflavored wax SKUs.
- ISO 10993-5 cytotoxicity certification:Early movers documenting full biocompatibility test panels can command premium positioning as FDA 510(k) pathways tighten for dental device accessories.
Industry Challenges
- Formulation chemist scarcity:Specialized expertise in medical-grade wax compounding with documented thermal stability across 46°C to 68°C melting ranges is concentrated among a small cohort of dental materials scientists.
- Dual-channel inventory complexity:Manufacturers serving both professional clinic bulk orders and retail pharmacy blister packs face SKU proliferation and packaging format incompatibilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Orthodontic Wax Market |
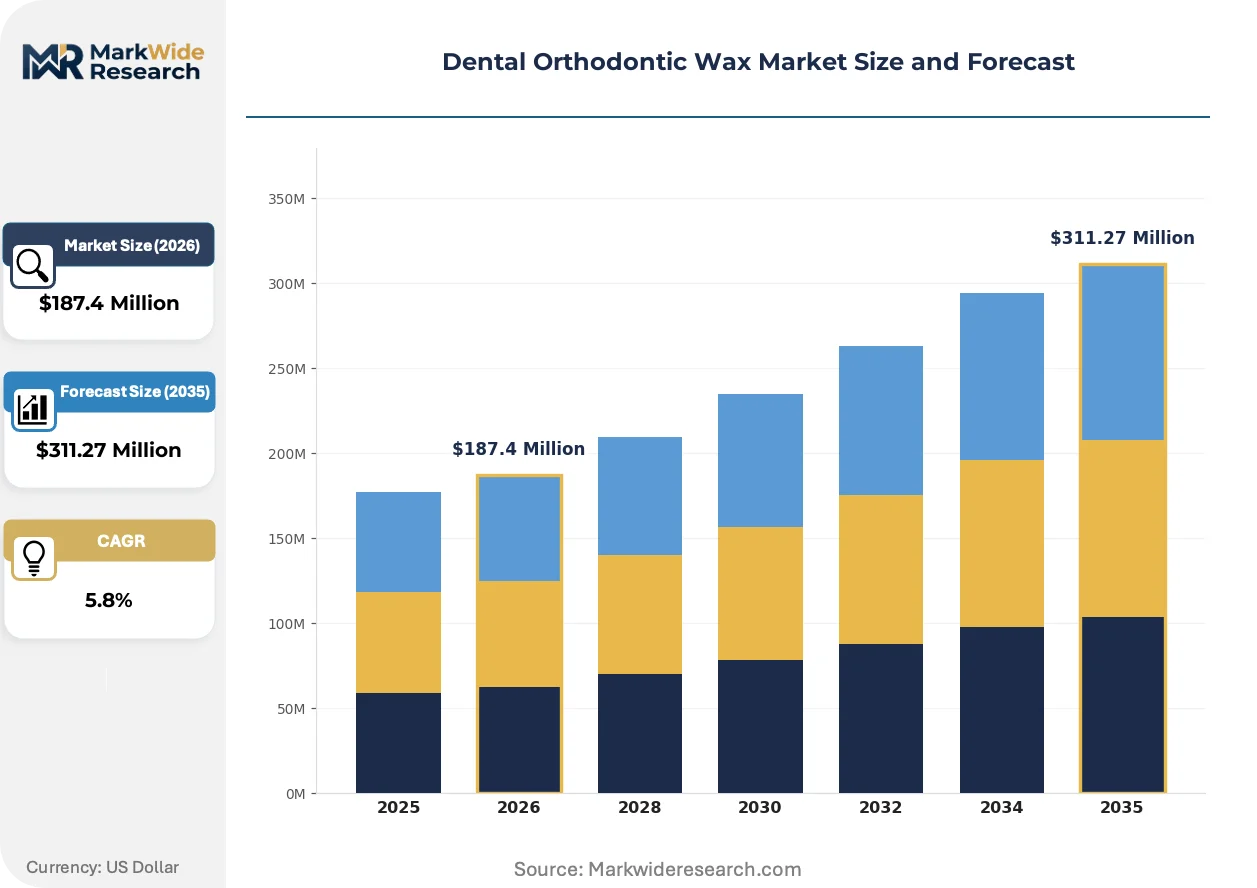
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $311.27 Million |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: General Purpose Wax, Bite Wax, Flavored Wax, Colored Wax End User: Orthodontic Clinics, Dental Hospitals, Home Care, Dental Laboratories Material: Paraffin Wax, Beeswax, Microcrystalline Wax, Synthetic Wax Packaging Type: Tubes, Boxes, Blisters, Pouches |
| Companies Covered | DWS Systems, C.J. Robinson Company, Carmel Industries, Bracon Dental, Solstice T&I, Bilkim Ltd. Co., Pyrex Polymars Inc., Metrodent Ltd., Colgate-Palmolive Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Orthodontic Wax Market Emerging Trajectories
Synthetic polymer R&D and regulatory biocompatibility documentation are converging to redefine product differentiation, while channel structures fragment between professional procurement and patient-direct fulfillment models.
Plant-derived synthetic wax alternatives with controlled melting point precision are decomposing the historical dominance of petroleum-based paraffin in premium product tiers. Orthodontic clinics in Germany and Japan are piloting these formulations for pediatric patients with documented skin sensitivity profiles. The shift is compressing addressable volume for conventional mineral wax suppliers while opening formulation partnerships between dental device manufacturers and specialty chemical firms.
REACH substance authorization requirements for microcrystalline wax additives are tightening raw material traceability obligations across European supply chains. Manufacturers must now document full substance inventory and safety data sheet alignment with ECHA's candidate list updates. Small-batch compounders in Italy and Spain are responding by consolidating supplier relationships and reducing additive complexity in base formulations.
Subscription-based wax replenishment bundled with aligner treatment plans is displacing episodic pharmacy purchasing among adult orthodontic patients. Teledentistry platforms in the United States are integrating automated refill scheduling into patient management portals. This pattern is most visible in California and Texas metropolitan markets where direct-to-consumer aligner penetration exceeds national averages.
Dental Orthodontic Wax Market Segmentation
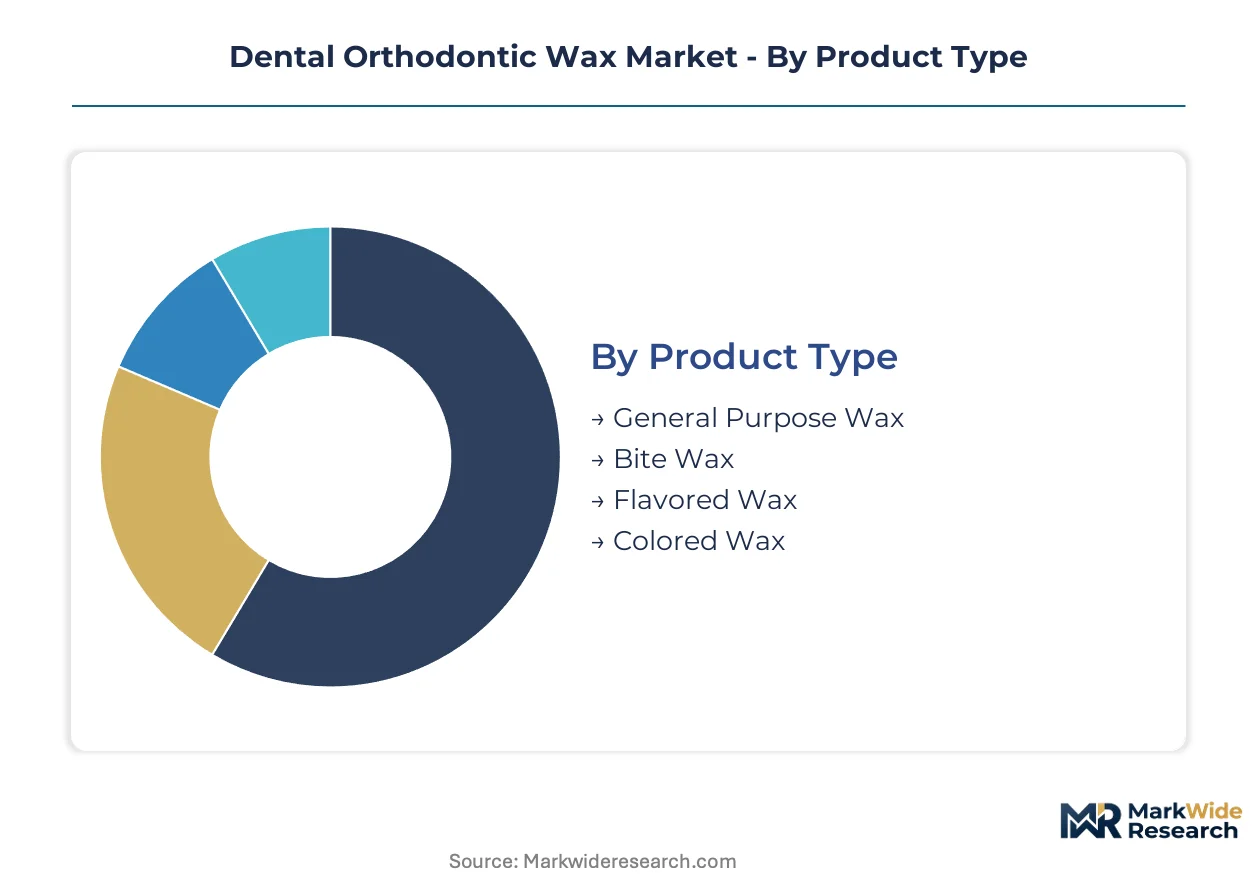
Orthodontic wax segmentation reflects divergent regulatory pathways across patient-care settings. ISO 10993-5 cytotoxicity documentation and FDA 510(k) clearance requirements fragment competitive positioning between professional-grade and retail-accessible formulations.
Product Type:
CE marking under EU MDR Article 10 and FDA 510(k) pathways create divergent compliance burdens across functional wax categories, concentrating procurement among manufacturers with documented biocompatibility test panels.
- General Purpose Wax:Standard paraffin and microcrystalline formulations with melting points between 46°C and 68°C serve as the default patient comfort intervention across bracket-based orthodontics. Demand concentrates in orthodontic clinics across the United States and Germany where practitioners prioritize ISO 10993-5 clearance for liability protection.
- Bite Wax:Specialized formulations with elevated viscosity and thermal stability support occlusal registration and bracket protection during functional jaw movement. German orthodontic specialists drive adoption through procurement specifications that mandate REACH-compliant additive documentation.
- Flavored Wax:Pediatric and adolescent patient compliance in US metropolitan markets elevates mint, fruit, and bubblegum variants.
- Colored Wax:Aesthetic differentiation targets teen aligner patients in direct-to-consumer channels.
General Purpose Wax handles the majority of throughput; Bite Wax is the fastest mover on share.
End User:
Channel economics and volume scale separate institutional procurement from patient-direct purchasing patterns.
- Orthodontic Clinics:Specialist practices across Japan, Germany, and the United States account for the dominant share of bulk wax consumption. Clinic procurement specifications increasingly require full ISO 10993 biocompatibility documentation and validated shelf-life data.
- Home Care:Direct-to-consumer aligner starter kits and subscription replenishment models are displacing episodic pharmacy purchasing. Teledentistry platforms in California and Texas bundle automated wax refills into patient management portals.
- Dental Hospitals:Academic medical centers in Osaka and Berlin anchor volume for training and complex case protocols.
- Dental Laboratories:Appliance fabrication workflows consume wax for model work and temporary protective applications.
Orthodontic Clinics retain the dominant volume position; Home Care is expanding most quickly as channel structures fragment.
Material:
Feedstock chemistry determines thermal performance, allergenicity profiles, and regulatory classification pathways.
- Paraffin Wax:Refined petroleum-derived formulations with established melting point precision dominate cost-sensitive procurement. Supply concentration among US and German refiners exposes margins to upstream price volatility.
- Synthetic Wax:Polymer-based alternatives with documented hypoallergenic clearance capture allergy-sensitive patient segments previously underserved by natural waxes. Japanese orthodontic clinics pilot these formulations for pediatric patients with documented skin sensitivity.
- Beeswax:Natural origin appeals to clean-label preferences in European retail pharmacy channels.
- Microcrystalline Wax:Enhanced plasticity and adhesive properties serve specialized bite wax applications.
Paraffin Wax maintains the installed base; Synthetic Wax shows the steepest expansion trajectory.
Packaging Type:
Format economics and shelf-life requirements separate professional bulk supply from retail-accessible units.
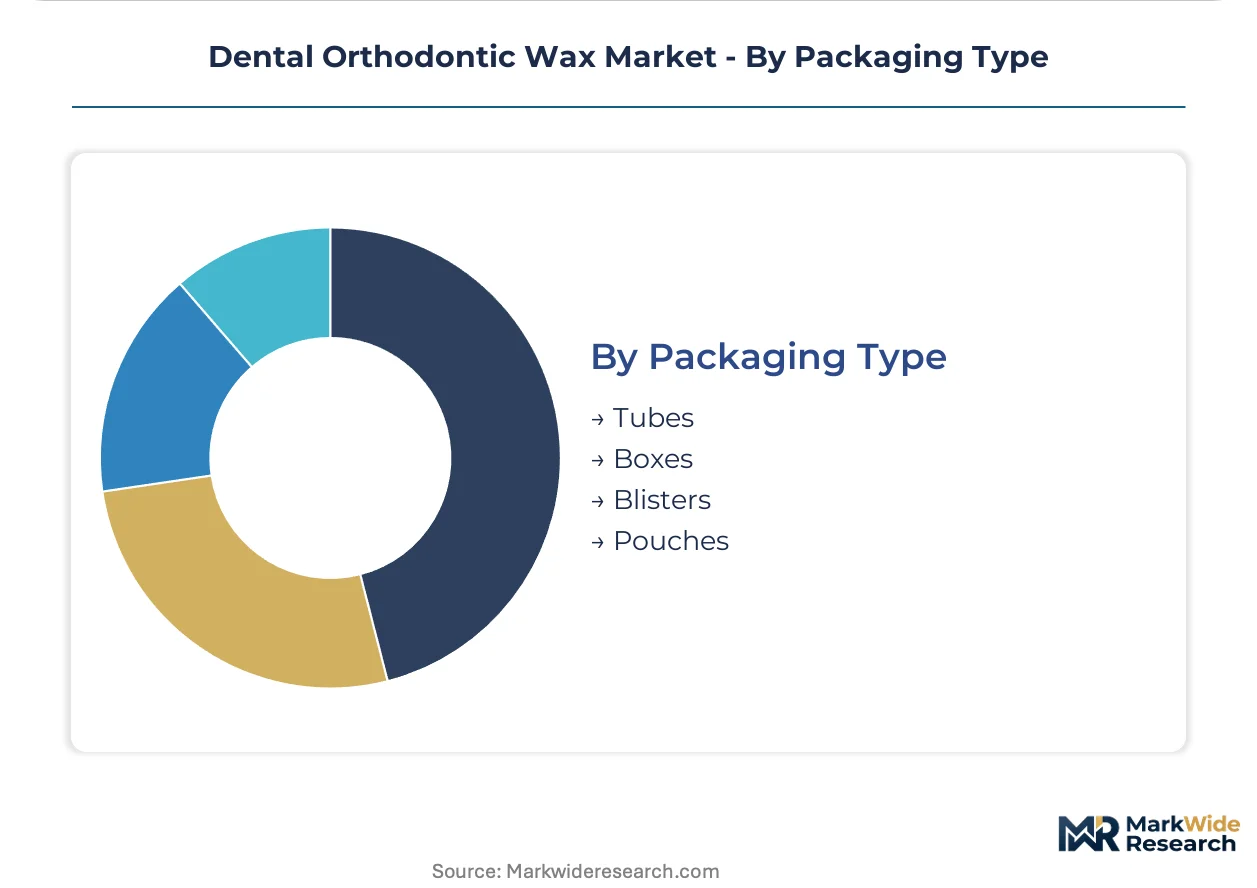
- Blisters:Unit-dose packaging dominates retail pharmacy and e-commerce channels across the United States. Format compatibility with direct-to-consumer aligner starter kits drives volume concentration.
- Tubes:Squeeze-dispense formats suit home care patients seeking controlled application volume.
- Boxes:Multi-unit packaging serves orthodontic clinic bulk procurement with cost efficiency.
- Pouches:Flexible single-use sachets support travel and trial-size distribution.
Blisters lead retail channel penetration; Boxes anchor professional procurement scale.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across orthodontic wax markets. German and Japanese buyers absorb premium pricing for ISO 10993-certified formulations, while Indian and Brazilian procurement prioritizes cost efficiency over biocompatibility documentation.
United States
Teledentistry platforms in California and Texas bundle wax into direct-to-consumer aligner kits, fragmenting traditional clinic distribution. FDA 510(k) clearance requirements filter supplier access, concentrating procurement among documented biocompatibility holders. The Dallas-Fort Worth metroplex anchors specialist orthodontic clinic density, driving bulk wax consumption for bracket-based adolescent treatments.
Germany
REACH compliance obligations and EU MDR Article 10 CE marking reshape formulation standards for European export. German orthodontic specialists mandate additive documentation for bite wax procurement, elevating compliance costs for small-batch compounders. The Rhine-Ruhr industrial corridor concentrates medical-grade paraffin refining capacity, exposing margins to upstream petroleum price swings.
Japan
Adult orthodontic volume in Tokyo and Osaka expands faster than pediatric cases, creating demand for discreet unflavored SKUs. METI guidelines on dental device biocompatibility align with ISO 10993-5 cytotoxicity protocols. Osaka's Kansai region hosts specialized dental materials distributors serving the aging orthodontic demographic with synthetic hypoallergenic formulations.
India
Bracket-based orthodontic adoption among urban middle-class families elevates wax consumption as a comfort protocol. The national pharmaceutical regulator maintains import clearance requirements for dental device accessories without harmonized biocompatibility mandates. Mumbai and Delhi-NCR dental clusters rely on cost-optimized paraffin formulations from domestic compounders serving price-sensitive clinic procurement.
Brazil
ANVISA medical device registration requirements for dental wax remain less stringent than FDA or CE pathways, enabling regional supplier participation. São Paulo's orthodontic specialist concentration drives volume demand for flavored pediatric variants. The Southeast industrial corridor hosts petroleum derivative processors supplying feedstock for commodity-grade wax production.
Dental Orthodontic Wax Market Vendor Landscape
Technology leadership and cost leadership are held by different player archetypes across the dental orthodontic wax market. ISO 10993-5 cytotoxicity certification and synthetic polymer R&D concentrate among specialized dental materials firms, while paraffin-based commodity production scales through petroleum derivative processors and private-label compounders. Three archetypes define competitive positioning: biocompatibility-certified specialists, retail pharmacy channel dominators, and regional private-label suppliers. Capacity consolidation and e-commerce fulfillment partnerships represent the dominant competitive moves as channel structures fragment.
Among biocompatibility-focused specialists, DWS Systems and Bracon Dental occupy positions emphasizing documented thermal stability and hypoallergenic formulation development. Colgate-Palmolive Company exemplifies the retail pharmacy archetype, leveraging consumer packaged goods distribution infrastructure for flavored and colored SKU penetration into home care segments. These three companies anchor the competitive spectrum from professional clinic supply to patient-direct fulfillment models.
| Leading Market Players |
|---|
| DWS Systems |
| C.J. Robinson Company |
| Carmel Industries |
| Bracon Dental |
| Solstice T&I |
| Bilkim Ltd. Co. |
| Pyrex Polymars Inc. |
| Metrodent Ltd. |
| Colgate-Palmolive Company |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at US and German medical-grade paraffin refineries sits above 85%, compressing marginal supply availability and establishing hard price floors for ISO 10993-certified formulations. This scale concentration simultaneously elevates procurement costs for small-batch European compounders and reinforces pricing power among integrated petroleum derivative processors serving orthodontic device manufacturers.
Pricing Analysis
FDA 510(k) clearance pathways dictate the pricing tier structure across dental orthodontic wax markets, separating premium biocompatibility-certified formulations from commodity paraffin alternatives. Three-tier pricing structure across premium, standard, and economy levels stratifies by ISO 10993-5 documentation completeness, with synthetic hypoallergenic variants commanding the highest position. Cost compression in standard paraffin tiers is intensifying because REACH compliance burdens and feedstock volatility squeeze small-batch European manufacturers. Price-sensitive procurement concentrates among Indian and Brazilian clinic buyers, while German and Japanese orthodontic specialists absorb premium pricing for documented thermal stability and shelf-life validation.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes are elevating inbound logistics costs for microcrystalline wax additive shipments from Southeast Asian chemical processors. Raw material supply concentrates in the United States, Germany, and Japan, where medical-grade paraffin refining capacity and synthetic polymer R&D infrastructure anchor production. Feedstock chemistry draws from petroleum derivatives, beeswax apiary networks, and specialty polymer resin streams. Single-source vulnerability pervades the narrow base of ISO 10993-compliant compounders with validated thermal stability documentation. Distribution runs through orthodontic clinic bulk procurement, retail pharmacy blister packs, and direct-to-consumer aligner kit bundling.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Teledentistry platform economics are rewiring patient acquisition and replenishment patterns, creating interoperability requirements between wax suppliers and aligner brand subscription infrastructure.
For Market Incumbents: Shield clinic relationships by securing exclusive supply contracts with top-20 US orthodontic practice groups before teledentistry platforms consolidate patient touchpoints. Deepen backward integration into medical-grade paraffin refining through offtake agreements with Rhine-Ruhr petroleum processors to defend margin position against feedstock volatility. Prioritize ISO 10993-10 sensitization testing documentation to preempt regulatory tightening. For New Entrants and Emerging Players: FDA 510(k) fast-track pathways for dental device accessories offer the most penetrable entry route for synthetic wax formulations targeting allergy-sensitive patient segments. White-space opportunity concentrates in Japan's aging orthodontic demographic seeking discreet unflavored SKUs, and in teledentistry platform partnerships for automated subscription replenishment. Go-to-market execution should lead with direct-to-consumer aligner bundling rather than clinic procurement displacement. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among synthetic wax specialists with teledentistry platform integration and subscription replenishment infrastructure. Long-term viability favors acquisition targets combining ISO 10993 biocompatibility certification with e-commerce fulfillment capabilities spanning both professional clinic and patient-direct channels. Monitor FDA 510(k) clearance pathway modifications for dental device accessories as the inflection signal for regulatory moat widening or narrowing.| Strategic Initiative | Industry Significance |
|---|---|
| ISO 10993-5 Cytotoxicity Certification | Establishes premium positioning as FDA tightens 510(k) documentation requirements for dental accessories. |
| Direct-to-Consumer Aligner Bundling | Captures patient touchpoints outside traditional orthodontic clinic procurement through teledentistry platform partnerships. |
| Synthetic Polymer R&D Investment | Opens hypoallergenic patient segments previously underserved by petroleum-derived paraffin formulations. |
| Backward Integration into Feedstock | Reduces exposure to US and German refinery price volatility for medical-grade paraffin supply. |
| Subscription Replenishment Infrastructure | Converts episodic pharmacy purchasing into recurring revenue streams through automated patient portal integration. |
Methodological Framework
Two parallel data streams informed the analysis: primary interviews with orthodontic practitioners, dental materials procurement managers, teledentistry platform operators, and regulatory affairs specialists; and secondary validation through FDA 510(k) clearance databases, EU MDR CE marking registries, ECHA REACH substance notifications, and orthodontic clinic procurement specification documents. Bottom-up volume triangulation across product type, material chemistry, and end-user channel combined with top-down market sizing anchored in petroleum derivative production data and dental device trade flows.
Across the projection horizon, the analytical framework modeled segmentation dimensions spanning product functionality, feedstock chemistry, packaging format, and channel structure. CAGRs derived from orthodontics procedure volume trajectories, clear aligner adoption curves, and biocompatibility certification penetration rates. Synthetic wax substitution elasticity and direct-to-consumer channel share evolution served as industry-specific forecast inputs alongside regulatory pathway timeline assumptions.
Decision-makers should treat outputs as directional under base assumptions of sustained FDA 510(k) documentation requirements and EU MDR Article 10 enforcement continuity; material deviation in regulatory stringency or teledentistry platform consolidation pace would warrant model refresh. Practitioners should keep alternative scenarios live as REACH substance authorization updates and patient-direct subscription regulatory clarity evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Canada Dental Devices Market
Dental Devices
Dental Chair Market
Dental Devices
Global Dental Microscope Market
Dental Devices
Toothbrush Sterilizer Market
Dental Devices
Global Restorative Dentistry Market
Dental Devices
Global Dental Endodontics Market
Dental Devices
Turkey CAD/CAM Dental Devices Market
Dental Devices
Global Dental Obturators Market
Dental Devices
Global Dental Hygiene Devices Market
Dental Devices
Guided Biofilm Therapy Market
Dental Devices
Dental Erbium Lasers Market
Dental Devices
Dental Prosthetics Market
Dental Devices
Dental Implants and Dental Prosthetics Market
Dental Devices
Dental Fittings Market
Dental Devices
Dental Regeneration Market
Dental Devices
Teeth Whitening Pen Market