
 Dental Inlays and Onlays Market | 2026-2036
Dental Inlays and Onlays Market Size, Share, and Industry Trends Forecast 2026-2036
Dental Inlays and Onlays Market Intelligence
Germany is reshaping competitive dynamics in precision-milled dental restorations through expanded laboratory capacity and digital workflow adoption. Dentsply Sirona leverages its integrated CAD/CAM ecosystem to control distribution across European dental practices. Ivoclar Vivadent AG specializes in glass-ceramic formulations that anchor premium positioning in aesthetic dentistry segments. Institut Straumann AG competes through its Straumann CARES manufacturing network, sustaining scale advantages in custom abutment and restoration production.
Dental inlays and onlays constitute indirect restorations fabricated extraorally to restore damaged posterior teeth, typically requiring minimum occlusal clearance of 1.5-2.0 millimeters and bonding with resin cements for structural integration. Ceramic variants, particularly lithium disilicate and zirconia-reinforced glass-ceramics, dominate margin pools due to their balance of fracture resistance and optical properties. Composite materials occupy economy-tier positioning in price-sensitive channels, while porcelain segments lead aesthetic dentistry applications where translucency matching natural dentin remains paramount. Laboratories represent the fastest-growing end-user channel as chairside milling adoption shifts complexity upstream from individual practitioners.
FDA 510(k) clearance requirements govern ceramic and composite restoration materials in the United States, while the EU Medical Device Regulation (MDR) reclassifies certain custom dental devices and intensifies clinical evidence expectations for market access. ISO 20795-1 standards for polymer-based restorative materials establish baseline biocompatibility and mechanical performance benchmarks that manufacturers must satisfy across jurisdictions. Stakeholders must monitor evolving MDR technical documentation requirements and FDA digital dentistry guidance to anticipate compliance costs and competitive positioning shifts.
Market Dynamics
CAD/CAM fabrication is compressing production timelines for indirect restorations while shifting value capture from chairside practitioners to centralized laboratories with milling capacity. This technology migration reconfigures margin distribution across the supply chain.
Growth Catalysts
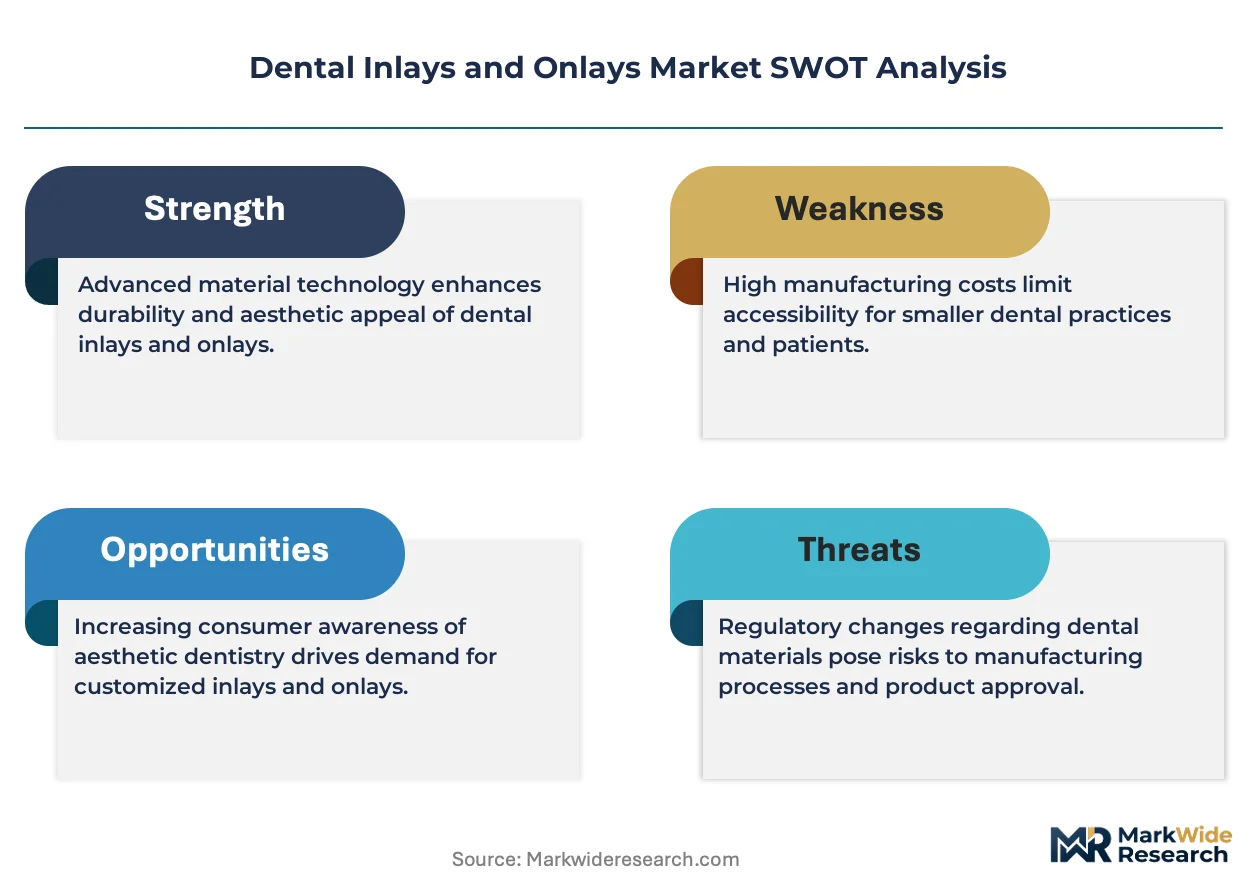
- FDA 510(k) Streamlining:Accelerated clearance pathways for ceramic-based devices reduce time-to-market for novel lithium disilicate formulations. Manufacturers gain competitive advantage through faster regulatory validation.
- Laboratory Outsourcing Surge:Dental clinics in Germany and Switzerland are consolidating restoration production with specialized milling centers. This concentrates technical expertise and equipment investment upstream.
- Resin Cement Bonding Protocols:Improved adhesive systems enable thinner restoration profiles and expanded clinical indications. Practitioners achieve stronger structural integration with less tooth reduction.
Market Restraints
- Zirconia Powder Supply Concentration:Raw material sourcing clusters in Chinese processing facilities. Geographic concentration creates vulnerability to export restriction or quality inconsistency.
- EU MDR Clinical Evidence Burden:Reclassification of custom dental devices under Medical Device Regulation intensifies documentation requirements. Smaller manufacturers face compliance cost barriers.
- Direct Composite Substitution:Chairside bulk-fill composites capture price-sensitive cases with acceptable durability. Economy-tier indirect restorations lose volume to simplified direct techniques.
Strategic Opportunities
- Spain and Italy Laboratory Consolidation:Fragmented southern European markets present acquisition targets for integrated CAD/CAM networks. Scale operators can capture underserved practitioner bases.
- AI-Assisted Occlusal Design:Machine learning algorithms integrated with intraoral scanning optimize restoration morphology. Convergence of diagnostic imaging and manufacturing software reduces remakes.
- Subscription-Based Milling Services:Pay-per-unit models eliminate capital barriers for small practices. Channel innovation expands addressable market beyond high-volume clinics.
Industry Challenges
- CAD/CAM Technician Scarcity:Digital design expertise lags behind equipment deployment. Laboratories compete for operators proficient in 3Shape and exocam software environments.
- Biocompatibility Certification Delays:ISO 20795-1 testing protocols extend product launch timelines. Manufacturers await mechanical performance validation for novel glass-ceramic hybrids.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Dental Inlays and Onlays Market |
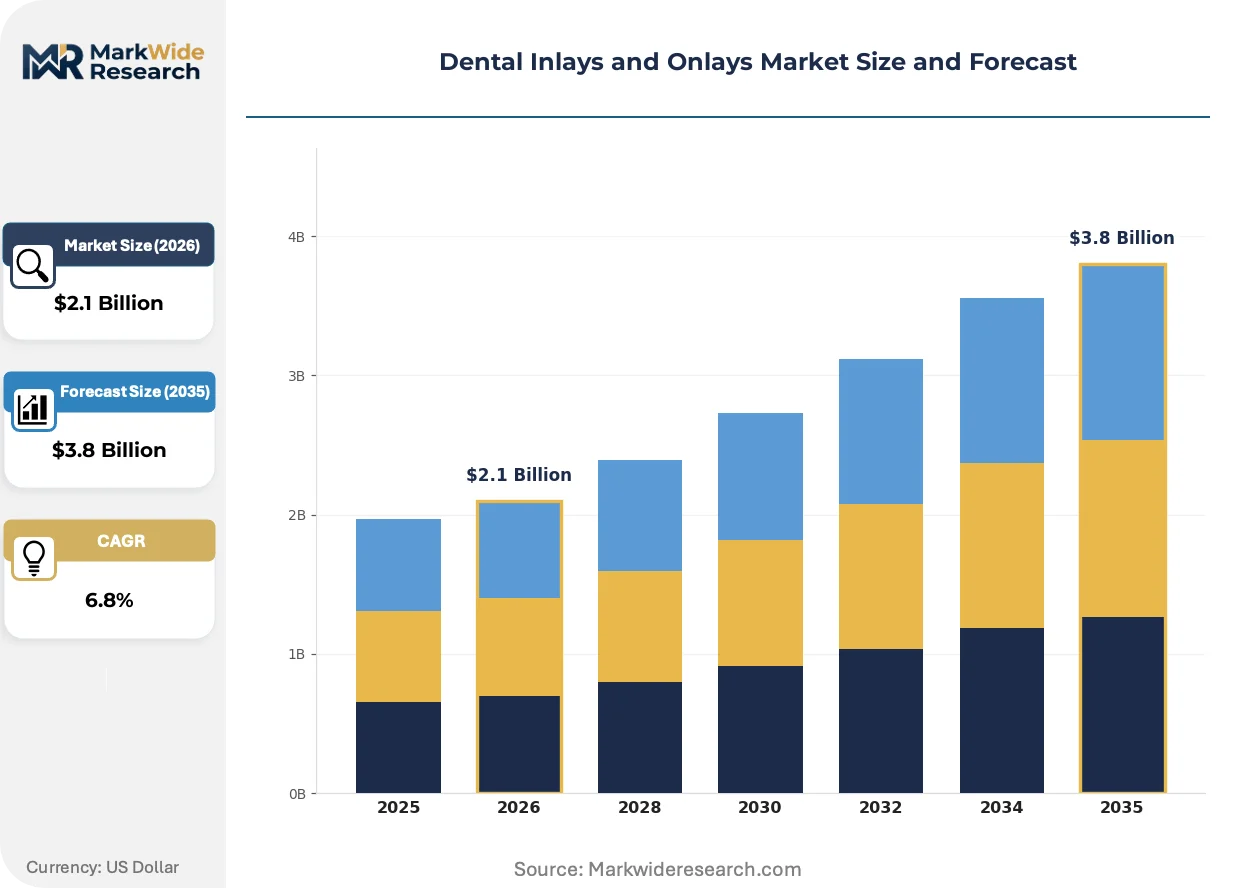
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $3.8 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Composite, Ceramic, Gold, Porcelain Application: Restorative Dentistry, Aesthetic Dentistry, Preventive Care, Orthodontics End User: Dentists, Dental Clinics, Hospitals, Laboratories Material: Resin-Based, Metal, Glass-Ceramics, Ceramics |
| Companies Covered | COLTENE Holding AG, Glidewell Laboratories, Dentsply Sirona, Aspen Dental, National Dentex Corporation, Ivoclar Vivadent AG, Institut Straumann AG, DenMat, 3M Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Dental Inlays and Onlays Market Strategic Shifts & Innovations
Digital workflows are collapsing traditional boundaries between diagnosis, design, and fabrication. This convergence demands new competencies while creating efficiency dividends for early adopters.
Intraoral scanning systems are digitizing impression capture and eliminating physical mold logistics. General practitioners in urban US markets adopt chairside units at accelerating rates. The technology is digitizing patient data flows while compressing turnaround times from days to hours for same-visit restorations.
EU MDR technical documentation requirements are intensifying clinical evidence standards for permanent restorative materials. Manufacturers must submit biocompatibility and mechanical performance data beyond previous directives. Ceramic inlay producers serving European markets are restructuring quality management systems to satisfy notified body expectations.
Group purchasing organizations are consolidating procurement authority among multi-location dental service organizations. Independent practitioners face margin pressure as DSOs negotiate volume-based ceramic supply contracts. This concentration is most visible in Texas and Florida metropolitan corridors where corporate dentistry expansion accelerates.
Dental Inlays and Onlays Market Segmentation
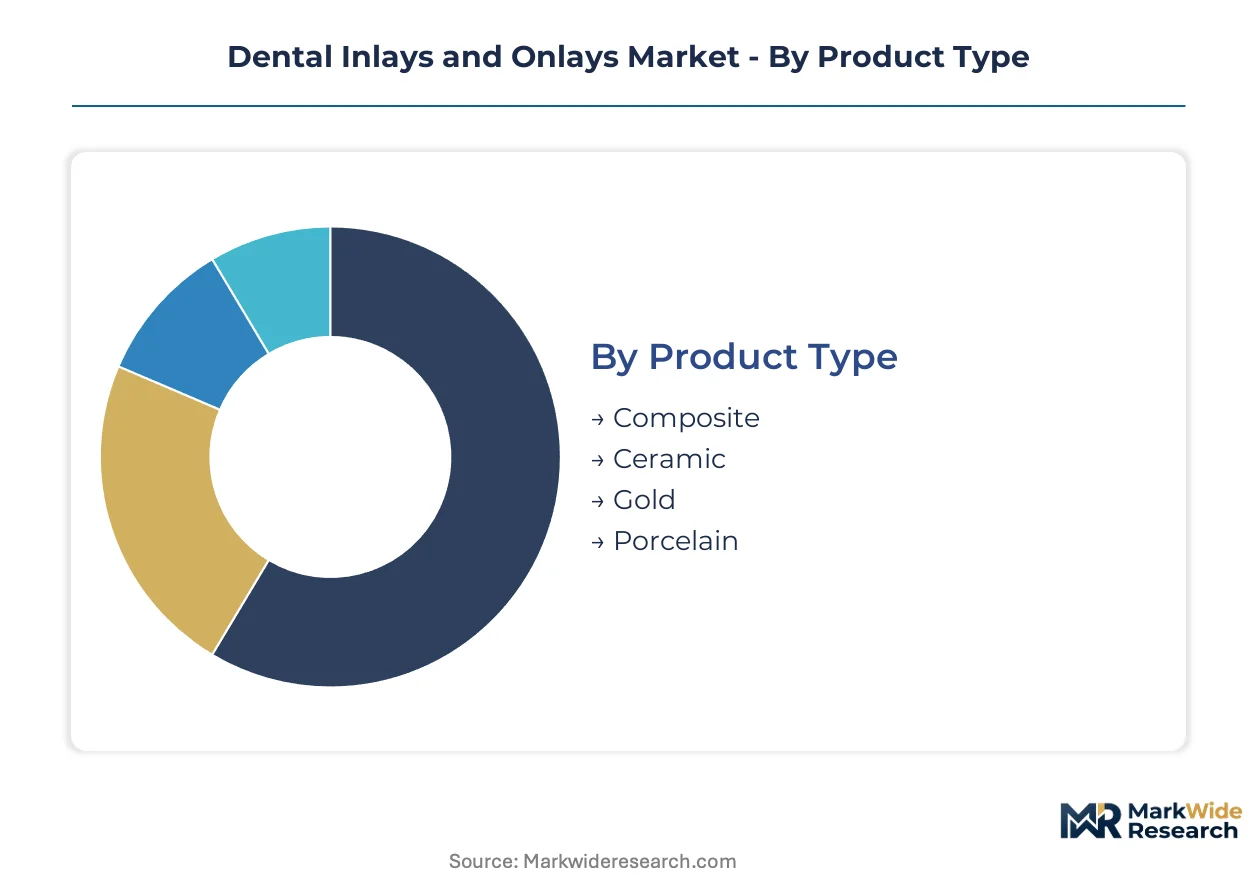
Dental inlays and onlays segment across material science, clinical application, and delivery channel dimensions. Each axis reveals distinct margin structures and competitive intensity patterns that shape manufacturer positioning.
Product Type:
Mature ceramic formulations dominate premium positioning while emerging composite variants capture cost-sensitive volume.
- Ceramic:Lithium disilicate and zirconia-reinforced glass-ceramics deliver fracture resistance above 400 MPa with optical properties matching natural dentin. German laboratories specify ceramic for posterior restorations requiring occlusal loads above 800 Newtons, driven by adhesive cementation protocol refinements that enable thinner profiles.
- Composite:Particle-filled and fiber-reinforced resin formulations occupy economy-tier positioning with direct milling compatibility. Chairside production in US metropolitan practices accelerates same-visit delivery, constrained by wear resistance limitations under heavy occlusal function.
- Gold:Cast noble metal alloys retain indication in bruxism cases and deep subgingival margins where biocompatibility overrides aesthetic concerns.
- Porcelain:Feldspathic and leucite-reinforced variants anchor aesthetic dentistry segments requiring maximum translucency in anterior applications.
Ceramic retains volume leadership; composite holds the steepest expansion curve.
Application:
Clinical indication splits between functional reconstruction and aesthetic optimization, with divergent technical requirements.
- Restorative Dentistry:Posterior tooth reconstruction following caries removal or fracture management. Swiss and German clinics concentrate demand for CAD/CAM-milled inlays replacing large direct composite restorations with documented longevity advantages.
- Aesthetic Dentistry:Discoloration masking and smile line optimization drive porcelain and glass-ceramic selection. US coastal metropolitan practices generate premium pricing for anterior onlay applications where optical integration is paramount.
- Preventive Care:Minimal-intervention cusp coverage for cracked tooth syndrome diagnosis and management.
- Orthodontics:Anchorage reinforcement and occlusal plane modification through bonded overlay restorations.
Restorative applications command the installed base; aesthetic indications climb the fastest.
End User:
Channel structure reflects capital intensity gradients and technical specialization requirements.
- Laboratories:Centralized milling centers with 5-axis CNC capacity and digital design expertise. German outsourcing networks consolidate production for chairside practitioners lacking in-house CAD/CAM investment, expanding most quickly as workflow complexity shifts upstream.
- Dental Clinics:Multi-chair group practices and dental service organizations with captive milling units. Texas and Florida metropolitan corridors concentrate procurement authority through group purchasing organizations.
- Dentists:Solo practitioners relying on conventional impression and external laboratory submission.
- Hospitals:Academic medical centers and oral surgery departments managing complex trauma reconstruction cases.
Laboratories capture production volume leadership; dental clinics show the steepest adoption acceleration.
Material:
Substrate classification tracks chemical composition and processing pathway rather than finished restoration morphology.
- Glass-Ceramics:Lithium disilicate and zirconia-reinforced formulations balance strength and aesthetics with crystalline phase control enabling machinability. EU MDR technical documentation requirements intensify biocompatibility certification timelines for novel glass-ceramic hybrids.
- Ceramics:Alumina and zirconia polycrystalline structures for high-strength indications. Zirconia powder sourcing concentrates in Chinese processing facilities, creating supply vulnerability.
- Resin-Based:Bis-GMA and urethane dimethacrylate matrices with filler loading above 80% by weight for milling compatibility.
- Metal:High-noble and base metal alloys for cast restorations in functional priority cases.
Glass-ceramics dominate revenue contribution; resin-based materials gain share fastest in price-sensitive channels.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Zirconia powder processing clusters in Chinese facilities supply raw material for ceramic restorations worldwide. This geographic concentration shapes manufacturing economics and vulnerability profiles across dental laboratory networks.
Germany
Laboratory outsourcing and digital dentistry integration drive demand for precision-milled restorations. EU MDR technical documentation requirements intensify quality management system investments for ceramic producers. Bavaria and Baden-Württemberg host concentrated milling center capacity serving chairside practitioners across Central Europe.
United States
Group purchasing organizations consolidate procurement authority among dental service organizations in metropolitan corridors. FDA 510(k) clearance pathways streamline market entry for novel lithium disilicate formulations. Texas and Florida concentrate multi-location DSO expansion and volume-based ceramic supply contracting.
Switzerland
Swiss clinics concentrate demand for CAD/CAM-milled inlays with documented longevity advantages over direct composites. Swissmedic maintains stringent biocompatibility certification timelines for permanent restorative materials. Zurich and Geneva anchor specialized milling networks serving premium aesthetic dentistry segments.
China
Domestic zirconia powder processing facilities supply global ceramic restoration manufacturers. NMPA regulatory frameworks govern medical device classification for dental materials. Yangtze River Delta industrial zones concentrate raw material refining capacity for export markets.
United Kingdom
London and Southeast England concentrate private aesthetic dentistry demand for porcelain and glass-ceramic restorations. MHRA post-Brexit regulatory alignment with EU MDR standards affects market access documentation. Midlands laboratory networks expand digital workflow adoption for NHS and private channel supply.
Dental Inlays and Onlays Market Key Industry Players
Integrated CAD/CAM ecosystem providers and specialized ceramic formulation specialists split the market into distinct capability tiers. Consolidation pressures concentrate around laboratory networks with 5-axis milling capacity and digital design expertise. Three archetypes dominate: full-platform integrators controlling hardware-software-materials stacks, premium ceramic specialists commanding aesthetic dentistry margins, and scale laboratory operators capturing outsourcing volume. Competitive moves center on laboratory network acquisitions and subscription-based milling service launches that eliminate capital barriers for small practices.
Within the full-platform integrator tier, Dentsply Sirona and 3M Company exemplify archetypes that bundle intraoral scanning, design software, and materials supply. Ivoclar Vivadent AG occupies a position as a premium ceramic formulation specialist with glass-ceramic expertise. Among laboratory-scale operators, Glidewell Laboratories and National Dentex Corporation represent consolidation-driven models capturing outsourced production volume from chairside practitioners lacking captive milling investment.
| Leading Market Players |
|---|
| COLTENE Holding AG |
| Glidewell Laboratories |
| Dentsply Sirona |
| Aspen Dental |
| National Dentex Corporation |
| Ivoclar Vivadent AG |
| Institut Straumann AG |
| DenMat |
| 3M Company |
| Others |
Cost & Logistics Intelligence
Shanghai-Ningbo port freight corridors transmit raw material cost volatility from Chinese zirconia refineries directly into European laboratory milling economics, compressing margins for ceramic restoration producers while enabling tiered pricing separation between lithium disilicate premium formulations and economy-grade composite alternatives.
Pricing Analysis
FDA 510(k) clearance tiers dictate the pricing structure across premium, standard, and economy levels in the United States, with ISO 20795-1 certification grades and brand reputation from Dentsply Sirona or Ivoclar Vivadent anchoring price premiums. Pricing pressure stems from direct composite substitution in price-sensitive channels, while dental service organizations in Texas and Florida metropolitan corridors exhibit the highest price sensitivity due to volume-based procurement consolidation.
Supply Chain Analysis
Extended payment terms from Chinese zirconia powder processors to European milling centers have become standard practice, stabilizing working capital for laboratory networks. Raw material sourcing draws from Chinese processing facilities for zirconia, German specialty chemical suppliers for resin monomers, and Swiss precision equipment manufacturers for 5-axis CNC systems. Single-source vulnerability concentrates in Yangtze River Delta zirconia refineries. Distribution runs through centralized laboratory networks with digital workflow integration serving chairside practitioners.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Subscription-based milling services represent a service-attach opportunity expanding faster than hardware sales, as pay-per-unit models eliminate capital barriers for small practices while generating recurring revenue streams.
For Market Incumbents: Build captive laboratory network moats through acquisition of southern European milling centers in Spain and Italy, consolidating fragmented production capacity. Backward integration into zirconia powder processing mitigates supply concentration risk from Chinese sourcing clusters. Channel control through integrated CAD/CAM software-hardware-materials stacks defends against emerging platform competitors. For New Entrants and Emerging Players: Pursue AI-assisted occlusal design software partnerships with existing intraoral scanning manufacturers, accessing the restoration design layer without capital-intensive milling infrastructure. White-space opportunity concentrates in subscription-based milling services for solo practitioners lacking chairside CAD/CAM investment. Go-to-market positioning targets price-sensitive US metropolitan practices through direct composite-compatible workflows. For Investors and Strategic Acquirers: Carve-out targets emerge from dental service organization laboratory subsidiaries seeking operational focus, particularly multi-location DSO captive milling operations in Texas and Florida. Long-term viability favors scale operators with digital workflow integration and 5-axis CNC capacity. Watch FDA digital dentistry guidance evolution as inflection indicator for compliance cost barriers affecting smaller manufacturer exits.| Strategic Initiative | Industry Significance |
|---|---|
| Laboratory Network Acquisition | Consolidation of Spanish and Italian milling centers captures underserved practitioner bases. |
| Subscription Milling Service Launch | Pay-per-unit models expand addressable market beyond high-volume clinic segments. |
| AI-Assisted Design Software Integration | Machine learning convergence with intraoral scanning reduces restoration remake rates. |
| EU MDR Quality System Investment | Technical documentation restructuring satisfies notified body expectations for ceramic producers. |
| Resin Cement Bonding Protocol Development | Improved adhesive systems enable thinner ceramic profiles and expanded clinical indications. |
Research Approach
Findings reconcile primary fieldwork against secondary review of FDA 510(k) filings, EU MDR technical documentation databases, and dental laboratory trade association records. Primary interviews engaged CAD/CAM equipment manufacturers, dental laboratory operators, intraoral scanning distributors, and group purchasing organization contract managers. Secondary validation drew from ISO standards documentation, notified body guidance publications, and customs trade data for zirconia powder flows. Bottom-up restoration volume modeling triangulated against top-down market value estimates.
Forecast inputs include material science segmentation by ceramic, composite, gold, and porcelain formulations; end-user channel splits across laboratories, dental clinics, and solo practitioners; and regional regulatory cluster differentiation. CAGRs derive from installed base growth in CAD/CAM milling capacity, laboratory outsourcing velocity, and adhesive cementation protocol adoption curves. Industry-specific inputs incorporate EU MDR implementation timelines and FDA digital dentistry guidance evolution.
Macroeconomic conditions sit as an overlay; deviation in dental reimbursement rates, raw material export restrictions, or clinical evidence requirements would shift the trajectory. Forecasts reflect documented assumptions regarding technology adoption curves and regulatory implementation pacing. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Dental Devices
Global Digital Dentistry Market
Dental Devices
Dental 3D Printing Market
Dental Devices
Dental Prosthetics Market
Dental Devices
3D Printing Dental Device Market
Dental Devices
Asia Pacific Dental Market
Dental Devices
China Dental Devices Market
Dental Devices
Dental Calipers Market
Dental Devices
Europe Dental Implants and Prosthetics Market
Dental Devices
Dental Dam Market
Dental Devices
Dental Rapid Prototyping Systems Market
Dental Devices
Global Restorative Dentistry Market
Dental Devices
Subperiosteal Dental Implants Market
Dental Devices
Dental Erbium Lasers Market
Dental Devices
Dental Irrigation Devices Market
Dental Devices
Global Dental Microscope Market
Dental Devices
Dental Laboratories Market