
 Bulk Material Handling Products and Technologies Market | 2026-2036
Bulk Material Handling Products and Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Bulk Material Handling Products and Technologies Market Analysis
Mining operators are rotating capital toward integrated port-to-plant systems that cut transfer losses. Caterpillar Inc dominates the large-class haulage segment through its dealer network density. thyssenkrupp AG leverages its engineering heritage in overland conveying to anchor European heavy-industry contracts. Komatsu Ltd competes on autonomous haulage integration with downstream processing equipment.
Bulk material handling products and technologies encompass mechanical, pneumatic, and hydraulic systems engineered to move granular, powdered, or lump materials at throughput rates exceeding 10,000 tonnes per hour in mining and terminal applications. Conveyors represent the mature volume backbone where margin pools have compressed to maintenance and retrofit services. Automated Systems is displacing manual loading in high-labor-cost environments, while Robotic Handling extends into hazardous-material sorting where human exposure limits apply. Pneumatic Conveying leads in food-grade and pharmaceutical powder transfer where contamination control dictates system selection.
EPA emissions standards and MEE air-quality directives are accelerating replacement of open-belt transfers with enclosed pneumatic and covered conveyor architectures. CE marking under EU machinery directives shapes market access for European-built stackers and reclaimers entering Asian port projects. Stakeholders must weigh capex cycles against regulatory compliance deadlines as carbon-border adjustments begin affecting equipment sourcing decisions.
Market Dynamics
Automated conveyor deployments are fragmenting traditional equipment procurement patterns as mining operators in Australia and Chile prioritize throughput guarantees over upfront capital optimization. This shift compresses vendor margins toward lifecycle service contracts while elevating systems integrators with autonomous control capabilities.
Growth Catalysts
- EPA Emissions Standards:Open-belt transfer systems face mandated replacement deadlines across US mining corridors, accelerating enclosed pneumatic and covered conveyor architectures.
- Iron Ore Volume Concentration:China's inland port clusters continue expanding material throughput requirements, driving demand for high-capacity overland conveying systems.
- Autonomous Haulage Integration:Downstream processing equipment synchronization with driverless truck fleets is pulling capital toward integrated port-to-plant system investments.
Market Restraints
- Steel Input Volatility:Structural steel and specialized alloy pricing swings compress fabrication margins for conveyor OEMs with fixed-price contract exposure.
- European Supply Concentration:Critical drive component and advanced sensor sourcing clusters in Germany and Italy create vulnerability to single-source disruption.
- Pneumatic Energy Density Limits:Bulk density thresholds above 800 kg/m³ render pneumatic conveying economically unviable for heavy mineral concentrates.
Strategic Opportunities
- Brazilian Underpenetration:Vale's Carajás expansion creates demand for automated stacking and reclaiming systems with limited domestic supplier competition.
- EU Carbon Border Adjustment:CBAM implementation favors European-built equipment with verified embodied-carbon documentation for Asian port projects.
- Digital Twin Convergence:Physics-based simulation married to real-time sensor networks enables predictive maintenance contracts displacing traditional spare parts revenue.
Industry Challenges
- Control Systems Integration:Legacy SCADA architectures resist seamless interfacing with modern autonomous fleet management platforms, extending commissioning timelines.
- MEE Compliance Certification:China's Ministry of Ecology and Environment air-quality documentation requirements impose 12-18 month approval cycles for imported pneumatic systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bulk Material Handling Products and Technologies Market |
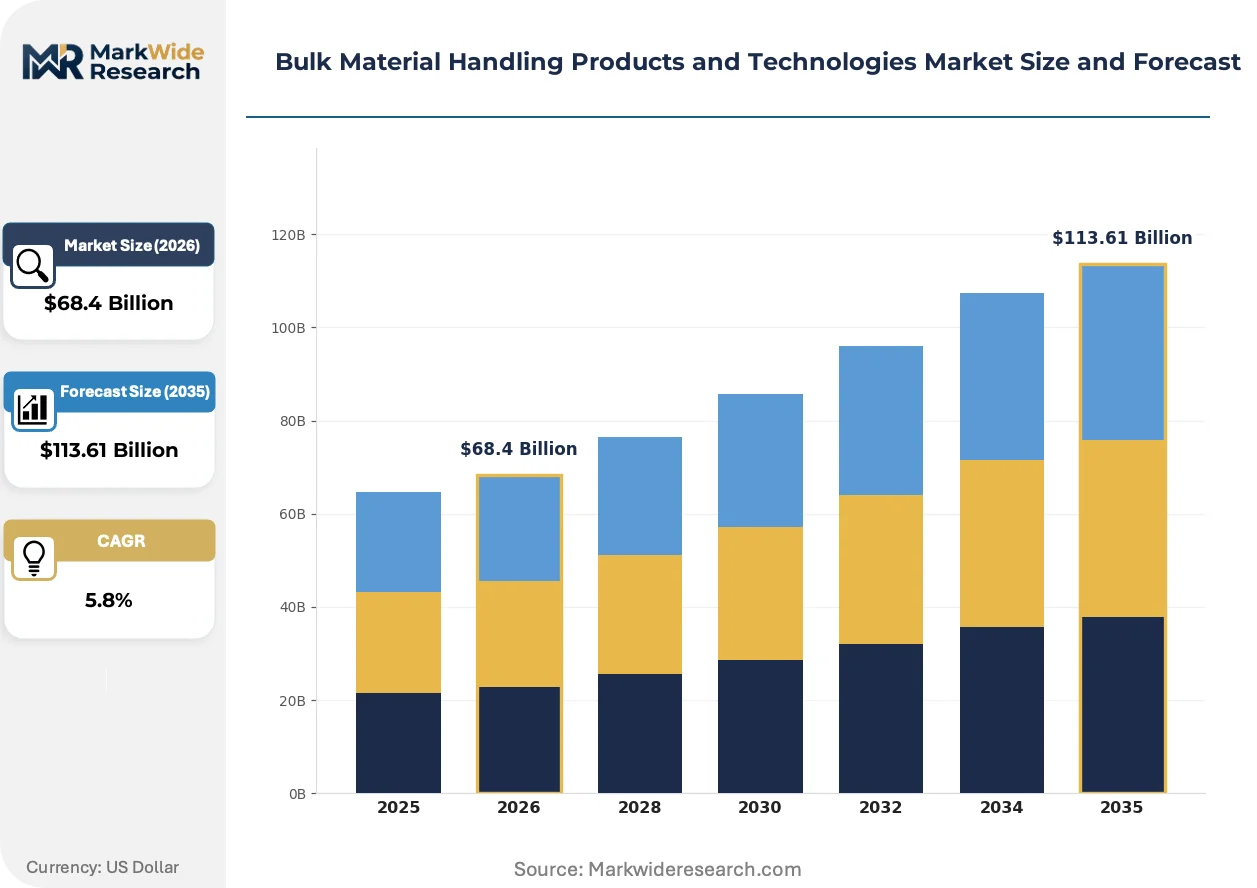
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $113.61 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Conveyors, Hoists, Cranes, Buckets Technology: Automated Systems, Robotic Handling, Pneumatic Conveying, Hydraulic Lifts End User: Manufacturing, Agriculture, Mining, Logistics Application: Storage Solutions, Transport Systems, Loading/Unloading, Waste Management |
| Companies Covered | Caterpillar Inc, thyssenkrupp AG, FLSmidth A/S, Metso Outotec, BEUMER Group, Komatsu Ltd, Siemens AG, Liebherr Group, ABB Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bulk Material Handling Products and Technologies Market Emerging Trajectories
Sensor fusion and edge computing architectures are compressing maintenance response windows from scheduled intervals to condition-triggered interventions. This transformation elevates data analytics capabilities above mechanical reliability as the primary vendor differentiator.
Digital twin technology is fragmenting traditional aftermarket service models. Mining operators in Western Australia now deploy virtual commissioning environments that replicate conveyor dynamics before physical installation. Caterpillar and Komatsu compete to embed these simulations within their autonomous haulage ecosystems, compressing rival independent software vendors into narrow specialized niches.
EU machinery directives under CE marking are reshaping equipment specification standards for Asian port projects. The F-Gas Regulation's phasedown of high-global-warming-potential refrigerants affects pneumatic system designs for temperature-sensitive bulk materials. European stacker and reclaimer manufacturers now lead with carbon-footprint documentation as a competitive wedge against lower-cost Asian fabricators.
Buyer consolidation among major mining houses is compressing vendor negotiation leverage. BHP and Rio Tinto now mandate outcome-based availability contracts rather than discrete equipment purchases, transferring operational risk to OEMs. This shift is most visible in Pilbara iron ore operations where integrated maintenance responsibility clauses now dominate tender evaluations.
Bulk Material Handling Products and Technologies Market Segmentation
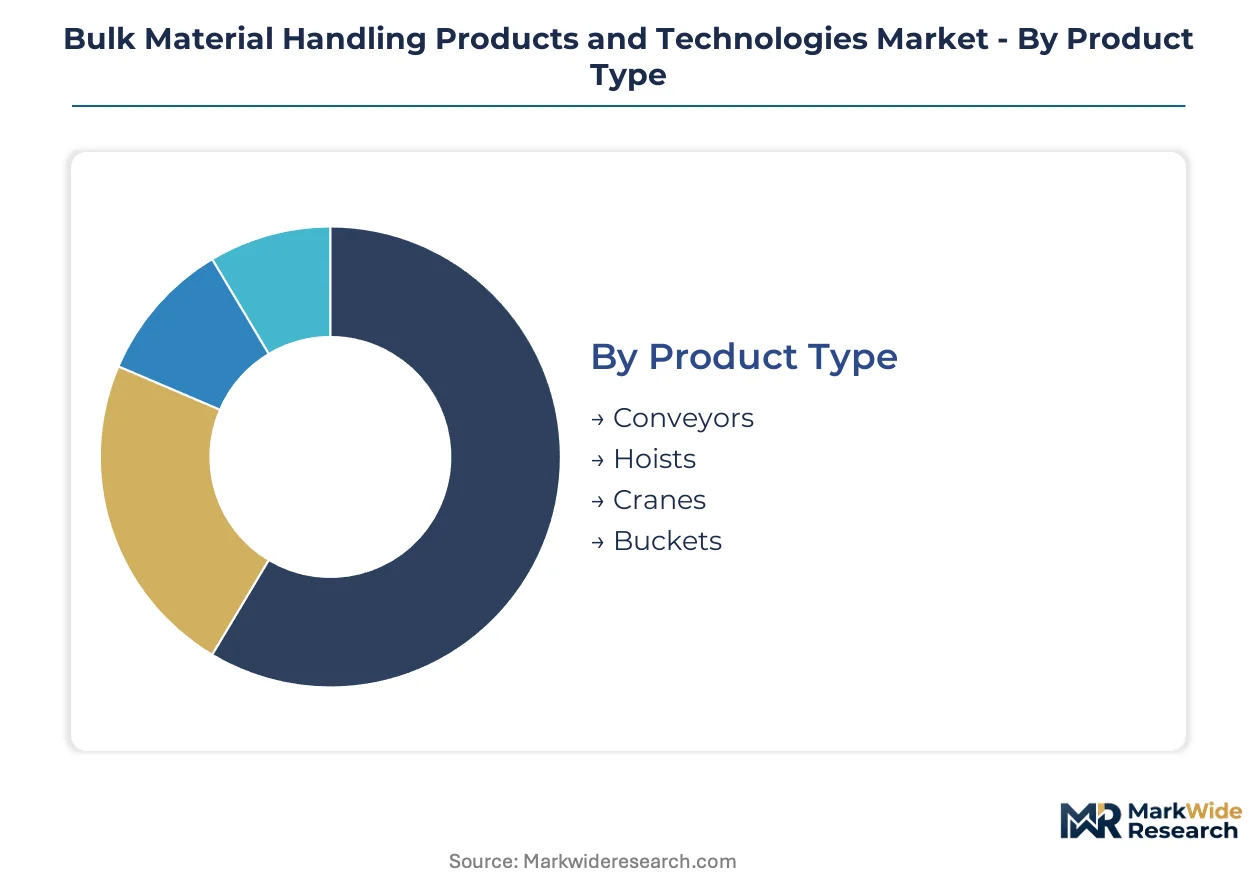
Segmentation in bulk material handling reveals how margin pools concentrate around automation intensity and regulatory compliance tiers. Equipment buyers now segment procurement by lifecycle cost rather than upfront capital, reshaping vendor competitive positioning across all four dimensions.
Product Type:
Margin pools have compressed to maintenance and retrofit services in mature mechanical equipment, while integrated systems command premium pricing through throughput guarantees.
- Conveyors:Belt and roller configurations engineered for continuous flow rates exceeding 10,000 tonnes per hour in mining corridors. Australian iron ore operators in the Pilbara region now specify covered architectures to meet EPA dust-emission mandates, displacing open-belt transfers.
- Hoists:Electromechanical lifting systems rated for heavy mineral concentrate handling in port terminal applications. Chinese inland port clusters drive specification upgrades as coal and iron ore volumes expand, though steel input volatility compresses fabrication margins for fixed-price contracts.
- Cranes:Gantry and bridge configurations dominate containerized bulk transfer at deep-water terminals.
- Buckets:Grab and clamshell designs serve grab ship unloaders in high-throughput grain and ore terminals.
The dominant share belongs to Conveyors, while Automated Systems integration is closing the gap fastest through lifecycle service contract expansion.
Technology:
Application context determines technology selection, with contamination control and labor cost thresholds driving divergence between pneumatic, hydraulic, and autonomous approaches.
- Automated Systems:Sensor networks and programmable logic controllers enable autonomous loading sequences without human intervention. Mining operators in Chile's Atacama operations deploy these systems to eliminate shift-change bottlenecks and reduce exposure to hazardous dust environments.
- Robotic Handling:Articulated arm configurations with force-feedback grippers sort irregular lump materials in hazardous zones. European heavy-industry contracts now specify these systems where MEE air-quality documentation and human exposure limits intersect.
- Pneumatic Conveying:Pressure-differential systems transfer food-grade and pharmaceutical powders under contamination control.
- Hydraulic Lifts:Cylinder-actuated platforms handle dense mineral concentrates above pneumatic density thresholds.
Automated Systems holds the installed base advantage, yet Robotic Handling is expanding most quickly into hazardous-material sorting applications.
End User:
Capital cycle timing and regulatory pressure intensity vary sharply across end-user categories, with mining and logistics leading replacement demand.
- Mining:Open-pit and underground extraction operations require continuous material flow from face to processing plant. Australian and Chilean operators now prioritize integrated port-to-plant systems that cut transfer losses, rotating capital away from discrete equipment purchases.
- Logistics:Port terminals and inland distribution hubs manage multimodal transfer points with high seasonality. China's coastal and inland port clusters are expanding pneumatic and covered conveyor deployments to handle rising coal and iron ore volumes under stricter MEE enforcement.
- Manufacturing:Process industries integrate handling equipment with continuous production lines.
- Agriculture:Grain elevators and fertilizer handling require seasonal surge capacity with dust control.
Mining commands the largest equipment spend, while Logistics is gaining share fastest through port automation mandates.
Application:
Functional role in the material flow determines system architecture, with transport and loading applications absorbing the majority of autonomous technology investment.
- Transport Systems:Overland conveying and pipeline networks move bulk materials between extraction, processing, and shipping points. Brazil's Carajás expansion creates demand for automated stacking and reclaiming systems with limited domestic supplier competition.
- Loading/Unloading:Ship-to-shore and rail-to-truck transfer equipment manages peak throughput windows. Western Australian mining houses now mandate outcome-based availability contracts for these systems, transferring operational risk to OEMs.
- Storage Solutions:Stacker-reclaimer combinations manage stockpile geometry for blending and inventory control.
- Waste Management:Tailings and byproduct handling systems face escalating containment and dust suppression requirements.
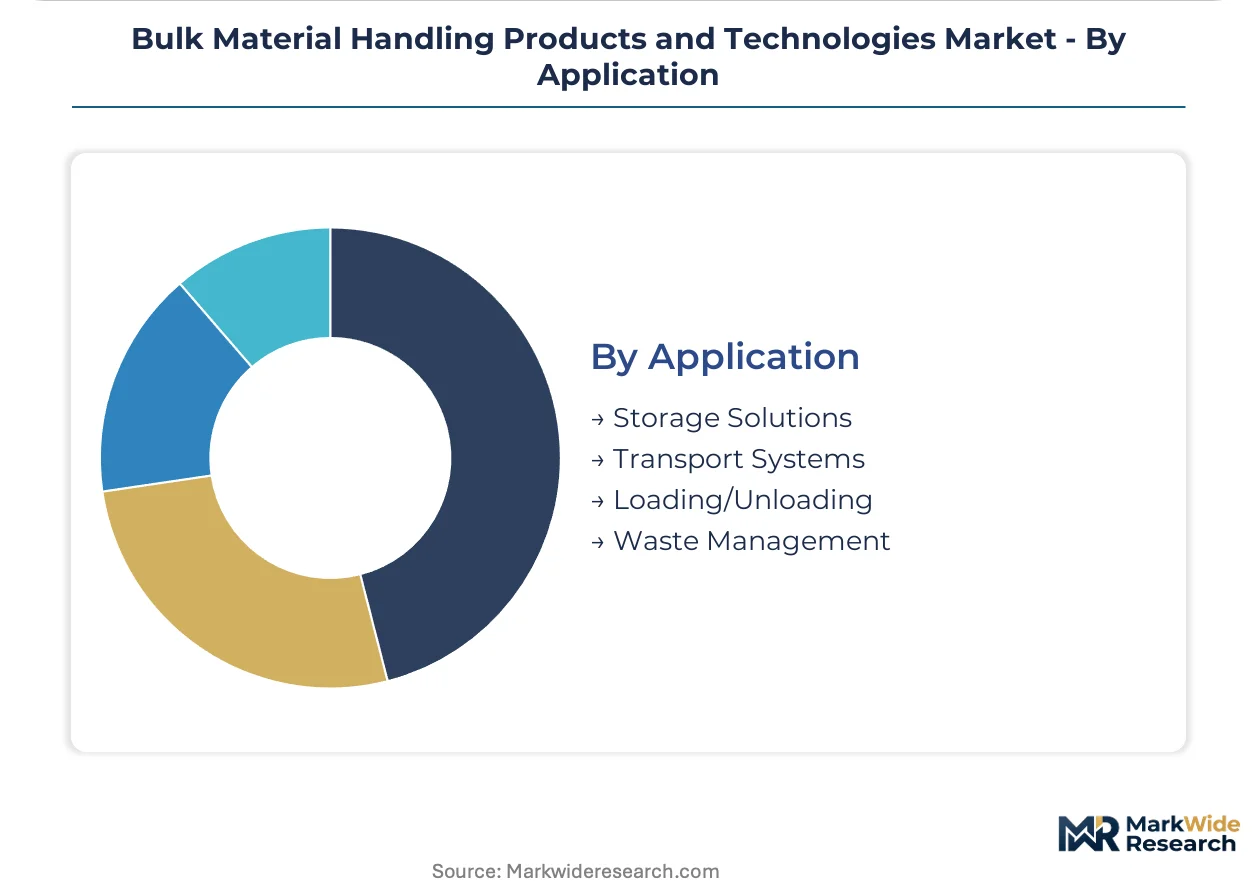
Transport Systems anchors capital allocation, though Loading/Unloading is climbing the fastest as autonomous fleet synchronization demands grow.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pilbara heavy-haul rail network and Port Hedland bulk export terminals anchor Australia's position as the infrastructure backbone for seaborne iron ore trade. Chile's Escondida copper concentrate pipeline and Antofagasta port linkages complete the South American corridor. China's Yangtze River inland waterway grid and German Rhine-Ruhr industrial belt round out the critical nodes.
Australia
BHP and Rio Tinto operate the world's densest autonomous haulage corridors across Western Australia's Pilbara region. EPA dust-emission standards mandate covered conveyor architectures for all new port-to-plant installations. The Karratha-to-Port Hedland rail spine now moves over 800 million tonnes annually, driving replacement demand for high-capacity stacking and reclaiming systems.
Chile
State-owned Codelco and Anglo American's Los Bronces expansion anchor copper concentrate throughput requirements in the Atacama Desert. MEE-equivalent air-quality documentation from Chile's environmental regulator SMA imposes extended certification cycles on imported pneumatic equipment. The Antofagasta port cluster serves as the primary export node, with limited domestic fabrication capacity forcing reliance on European and Australian system integrators.
China
Coal and iron ore volume concentration in Yangtze River Delta and Bohai Rim port clusters sustains demand for overland conveying systems rated above 10,000 tonnes per hour. MEE enforcement of GB air-quality standards accelerates replacement of open-belt transfers with enclosed pneumatic architectures. The Tangshan steel corridor and Qinhuangdao coal port represent the densest equipment deployment zones.
Germany
Thyssenkrupp's engineering heritage and Siemens' automation capabilities anchor European heavy-industry contracting for stacker-reclaimer systems. CE marking under EU machinery directives shapes specification standards for equipment exported to Asian port projects. The Ruhr industrial belt and Hamburg port complex concentrate domestic demand for integrated bulk handling solutions.
Brazil
Vale's Carajás iron ore expansion in Pará state creates demand for automated stacking and reclaiming systems with limited domestic supplier competition. ANVISA-equivalent industrial safety regulations govern equipment certification for mining corridor deployments. The Itaqui port terminal in Maranhão and the Carajás railway extension represent the primary infrastructure investment nodes.
Bulk Material Handling Products and Technologies Market Vendor Landscape
Concentration sits with diversified industrial conglomerates that bundle mechanical equipment with automation and lifecycle services. Three archetypes dominate: mining-focused OEMs with autonomous haulage integration capabilities, European engineering houses with port-to-plant systems expertise, and industrial automation specialists with control systems portfolios. Competitive moves center on outcome-based availability contracts that transfer operational risk to vendors, and vertical integration into predictive maintenance software.
Among diversified mining equipment OEMs, Caterpillar Inc and Komatsu Ltd exemplify the autonomous integration archetype, while thyssenkrupp AG occupies a position within the European engineering tier. These three anchors represent distinct strategic postures: Caterpillar leverages dealer network density for large-class haulage dominance, Komatsu competes on downstream processing synchronization, and thyssenkrupp anchors European heavy-industry contracts through conveying heritage. Siemens AG and ABB Ltd sit within the automation tier, supplying control systems that increasingly determine vendor selection criteria.
| Leading Market Players |
|---|
| Caterpillar Inc |
| thyssenkrupp AG |
| FLSmidth A/S |
| Metso Outotec |
| BEUMER Group |
| Komatsu Ltd |
| Siemens AG |
| Liebherr Group |
| ABB Ltd |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at German and Italian drive-component foundries shapes both supply concentration and price floors for conveyor OEMs, compressing margins when steel input volatility meets fixed-price contract exposure. Mining operators in Australia's Pilbara region now negotiate outcome-based availability contracts that transfer operational risk to vendors, elevating lifecycle service pricing above discrete equipment tags.
Pricing Analysis
Volume-discount tiering structures separate premium integrated systems with autonomous control capabilities from standard mechanical equipment and economy retrofit services. Price differentiation rests on CE marking certification for European-built stackers entering Asian port projects and after-sales service bundling that locks in maintenance revenue. Cost compression in standard conveyor tiers is intensifying because steel alloy pricing swings compress fabrication margins for fixed-price contracts. Small-scale mining operators in Brazil's Carajás corridor show highest price sensitivity, while BHP and Rio Tinto prioritize throughput guarantees over upfront capital optimization.
Supply Chain Analysis
Inventory lead times for advanced sensors and variable-frequency drives stretch 16-24 weeks, tethering project delivery schedules to German and Italian component clusters. Critical inputs draw from structural steel mills in China, specialized alloy foundries in Germany, and high-tensile cable manufacturers in South Korea. Single-source vulnerability concentrates in precision drive components where European engineering houses dominate. Distribution runs through Caterpillar and Komatsu dealer networks for large-class haulage, while systems integrators direct European-built port equipment through EPC contractors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The bulk material handling market sits in early-cycle recovery as mining capital expenditure rebounds from trough levels, with Australian iron ore throughput expansion and Brazilian greenfield projects pulling replacement demand forward.
For Market Incumbents: Shield installed base revenue through predictive maintenance software embedding that displaces independent service vendors. Deepen backward integration into sensor manufacturing to reduce exposure to German and Italian single-source disruption. Cement lifecycle service contracts with outcome-based availability clauses before competitor autonomous integration capabilities mature.
For New Entrants and Emerging Players: Lead with digital twin commissioning capabilities as a wedge against established mechanical OEMs lacking physics-based simulation expertise. Brazil's Carajás expansion presents the most penetrable geography given limited domestic supplier competition and Vale's automation mandates. Partner with Siemens or ABB for control systems credibility rather than building proprietary automation stacks.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors automation specialists with sensor fusion and edge computing portfolios over pure-play mechanical fabricators. Long-term viability across the projection horizon hinges on software-enabled service revenue streams that compound beyond equipment replacement cycles. Watch for inflection when mining operators in Chile's Atacama operations mandate autonomous fleet synchronization as standard tender requirement.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Reduces single-source dependency on German drive-component suppliers for conveyor OEMs. |
| Autonomous Fleet Synchronization Investment | Aligns downstream processing equipment with Komatsu and Caterpillar driverless truck deployments. |
| CE Marking Certification Acceleration | Unlocks European-built equipment access to MEE-compliant Asian port projects under carbon-border rules. |
| Predictive Maintenance Platform Launch | Captures lifecycle service revenue from BHP and Rio Tinto outcome-based availability contracts. |
| Brazilian Systems Integrator Joint Venture | Addresses Vale's Carajás automation demand where domestic supplier competition remains thin. |
Methodological Framework
Findings reconcile primary fieldwork against secondary review of customs trade databases, mining operator capex disclosures, and EU machinery directive filings. Primary interviews engaged maintenance directors at Pilbara iron ore operations, OEM procurement teams at Caterpillar and Komatsu, aftermarket service heads at thyssenkrupp, and plant engineers at Chinese inland port clusters. Secondary validation drew from EPA emissions enforcement records, MEE air-quality documentation requirements, and SEC 10-K equipment revenue segmentations. Bottom-up equipment unit economics triangulate against top-down mining capital expenditure flows.
Segmentation dimensions modeled span product type, technology tier, end-user vertical, and application function across the analysis window. CAGRs derive from equipment replacement cycle timing, regulatory compliance deadline clustering, and autonomous technology penetration curves. Industry-specific forecast inputs include iron ore volume trajectories at China's Yangtze River Delta ports and copper concentrate throughput at Chile's Antofagasta cluster.
Underlying assumptions cover sustained mining commodity price levels, MEE enforcement continuity, and EPA emissions standard adherence, with deviation risk concentrated in steel input volatility and European supply disruption. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Material Handling Equipment
Global Precision Gearboxes Market
Material Handling Equipment
Australia and New Zealand Industrial Fasteners Market
Material Handling Equipment
Automated Material Handling Systems Market
Material Handling Equipment
Modular Self-Contained Aisle and Racking Systems Market
Material Handling Equipment
Global Conveyor System Market
Material Handling Equipment
Port Equipment Market
Material Handling Equipment
Die Casting Market
Material Handling Equipment
Tree Milling Machine Market
Material Handling Equipment
Froth Flotation Equipment Market
Material Handling Equipment
Global Loaders Market
Material Handling Equipment
Fork Lift Attachments Market
Material Handling Equipment
Pipe Belt Conveyor Market
Material Handling Equipment
Stair Lifts and Climbing Devices Market
Material Handling Equipment
Portable Conveyor Belt Market
Material Handling Equipment
Rough Terrain Lift Truck Market
Material Handling Equipment
Hoist Sling Chains Assemblies Market