
 Skincare Market | 2026-2036
Skincare Market Size, Share, and Industry Trends Forecast 2026-2036
Skincare Market Intelligence
Korean contract manufacturers in Seoul and Incheon is broadening clean beauty formulation capacity for Western brands. L'Oréal S.A. leverages integrated R&D centers in France and the United States to accelerate biotechnology-derived actives. Beiersdorf AG anchors its competitive position through dermatological testing protocols and pharmacy channel dominance in Germany. Shiseido Company Limited differentiates via fermentation-based ingredient science and precision skincare systems developed in Yokohama.
Skincare encompasses topical formulations designed to cleanse, protect, and maintain epidermal barrier function, typically incorporating emollients, humectants, occlusives, and active compounds at concentrations calibrated for daily or therapeutic use. Manufacturing involves emulsion stabilization, pH balancing, and preservative efficacy testing under GMP conditions to ensure microbial safety and ingredient potency. Moisturizers and serums capture the largest margin pools due to premium pricing and repeat purchase frequency, while sunscreens face accelerating reformulation cycles as regulators tighten UV filter approvals. The natural and organic ingredient category is expanding fastest among ingredient types, though synthetic hyaluronic acid retains volume leadership due to cost-scaling advantages in mass-market channels.
FDA oversight in the United States distinguishes between cosmetics and drugs based on intended use claims, forcing brands to navigate separate approval pathways for anti-aging and acne treatment positioning. ECHA's REACH framework and the EU Green Deal constrain synthetic preservative and fragrance compound usage, redirecting R&D investment toward biodegradable alternatives. China's NMPA and SAMR enforce animal testing exemptions for imported cosmetics only under specific conditions, creating compliance complexity for brands seeking mainland market access. Stakeholders must monitor regulatory divergence between jurisdictions to optimize formulation platforms and avoid market entry delays.
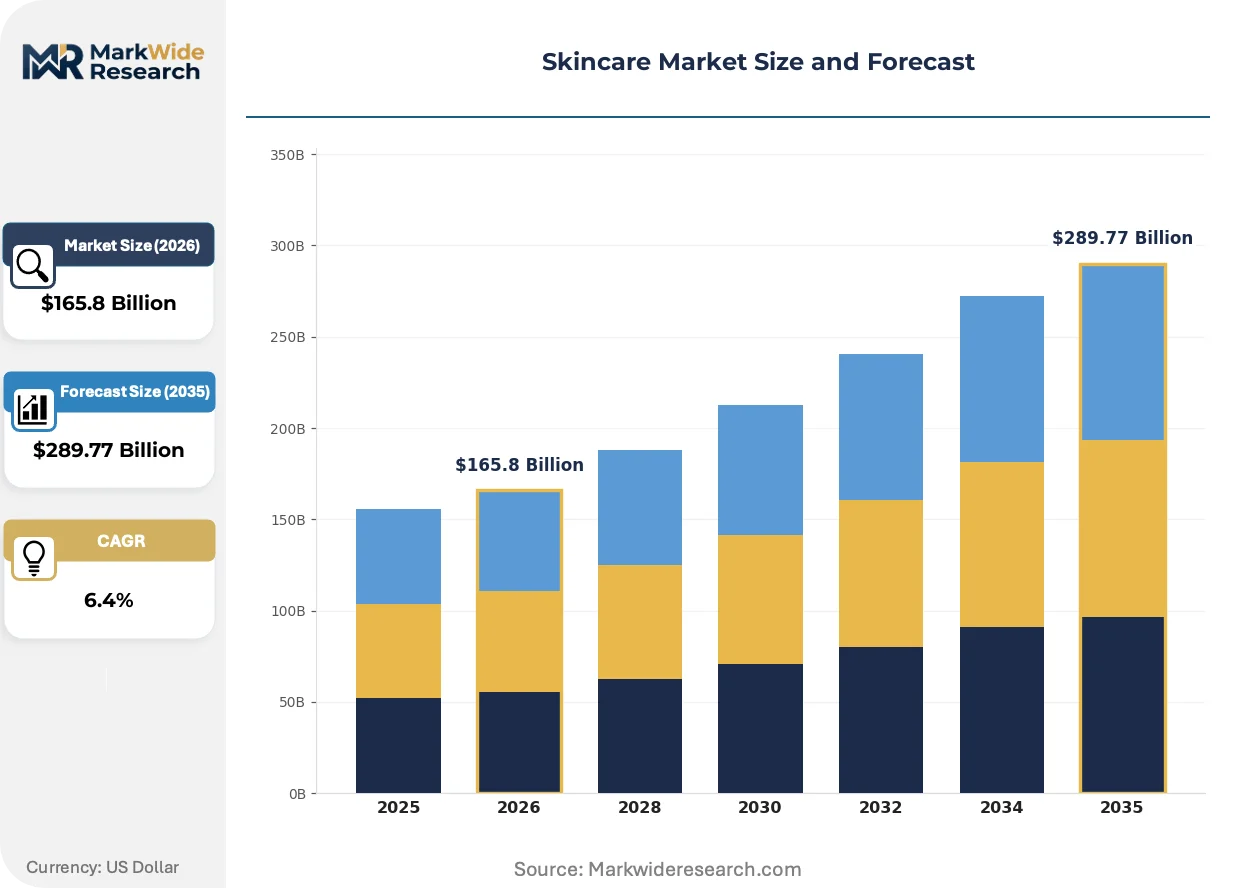
Market Dynamics
Biotechnology-derived actives and fermentation-based ingredient science are compressing formulation cycles while ECHA's REACH framework and the EU Green Deal force preservative system redesigns across Western supply chains.
Growth Catalysts
- Regulatory clarity in China:NMPA and SAMR animal testing exemptions under specific conditions unlock mainland market access for compliant Western brands.
- Medi-spa channel expansion:Dermatology clinics accelerate premium product uptake through prescription-adjacent positioning and clinical credibility transfer.
- Seoul-Incheon manufacturing cluster:Korean contract manufacturers scale clean beauty capacity for brands seeking REACH-compliant formulation alternatives.
Market Restraints
- Synthetic hyaluronic acid cost volatility:Mass-market margin compression limits pricing flexibility for volume-tier moisturizers and serums.
- UV filter approval bottlenecks:FDA and ECHA divergence on new UV active safety data extends sunscreen reformulation timelines.
- Preservative system concentration:REACH-constrained synthetic biocide suppliers reduce formulation options for water-based emulsions.
Strategic Opportunities
- Tier-one China cities:Underpenetrated precision skincare systems present white space for fermentation-based ingredient platforms.
- Biotechnology-convergence:R&D integration between French and US integrated centers accelerates novel active compound pipelines.
- Pharmacy channel dominance:German dermatological testing protocols create defensible positioning for clinically validated brands.
Industry Challenges
- Formulation chemist scarcity:GMP-qualified emulsion stabilization expertise concentrates in Seoul and Yokohama, constraining Western scale-up.
- Dual certification timelines:Parallel FDA cosmetic-drug distinction navigation and ECHA REACH compliance extend product launch windows.
- Legacy preservative system retrofitting:Biodegradable alternative integration requires pH balancing and microbial safety retesting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Skincare Market |
| Market Size in 2026 | $165.8 Billion |
| Market Size in 2035 | $289.77 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Moisturizers, Serums, Cleansers, Sunscreens Ingredient Type: Natural, Organic, Synthetic, Hyaluronic Acid Application: Daily Care, Anti-Aging, Acne Treatment, Sun Protection Customer Type: Men, Women, Teens, Professionals |
| Companies Covered | The Estée Lauder Companies Inc., Beiersdorf AG, L'Oréal S.A., Natura & Co., Kao Corporation, Unilever PLC, Shiseido Company Limited, Coty Inc., Procter & Gamble Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Skincare Market Strategic Shifts & Innovations
Active ingredient delivery mechanisms and regulatory disclosure mandates are restructuring competitive advantage around biotech sourcing transparency and clinical validation depth.
Fermentation-based ingredient science is absorbing R&D investment from synthetic chemistry platforms as brands seek REACH-compliant alternatives to traditional preservatives. L'Oréal's integrated centers and Shiseido's Yokohama facilities accelerate adoption timelines. This shift is compressing conventional active compound development cycles while expanding patentable molecule libraries.
ECHA's REACH framework and the EU Green Deal mandate biodegradable preservative alternatives, forcing reformulation of water-based emulsions and fragrance compounds. Industrial consequence includes raw material supplier consolidation around compliant biocide producers. Sunscreen and serum categories face the steepest compliance costs, with brands accelerating partnerships with Seoul-based contract manufacturers.
Clinical channel credibility transfer is displacing traditional retail discovery for premium moisturizers and anti-aging systems. Medi-spa and dermatology clinic recommendations now drive repeat purchase frequency previously captured by department store counters. This pattern concentrates in Seoul-Incheon and China's tier-one cities where pharmacy-anchored distribution retains stronger consumer trust.
Skincare Market Segmentation
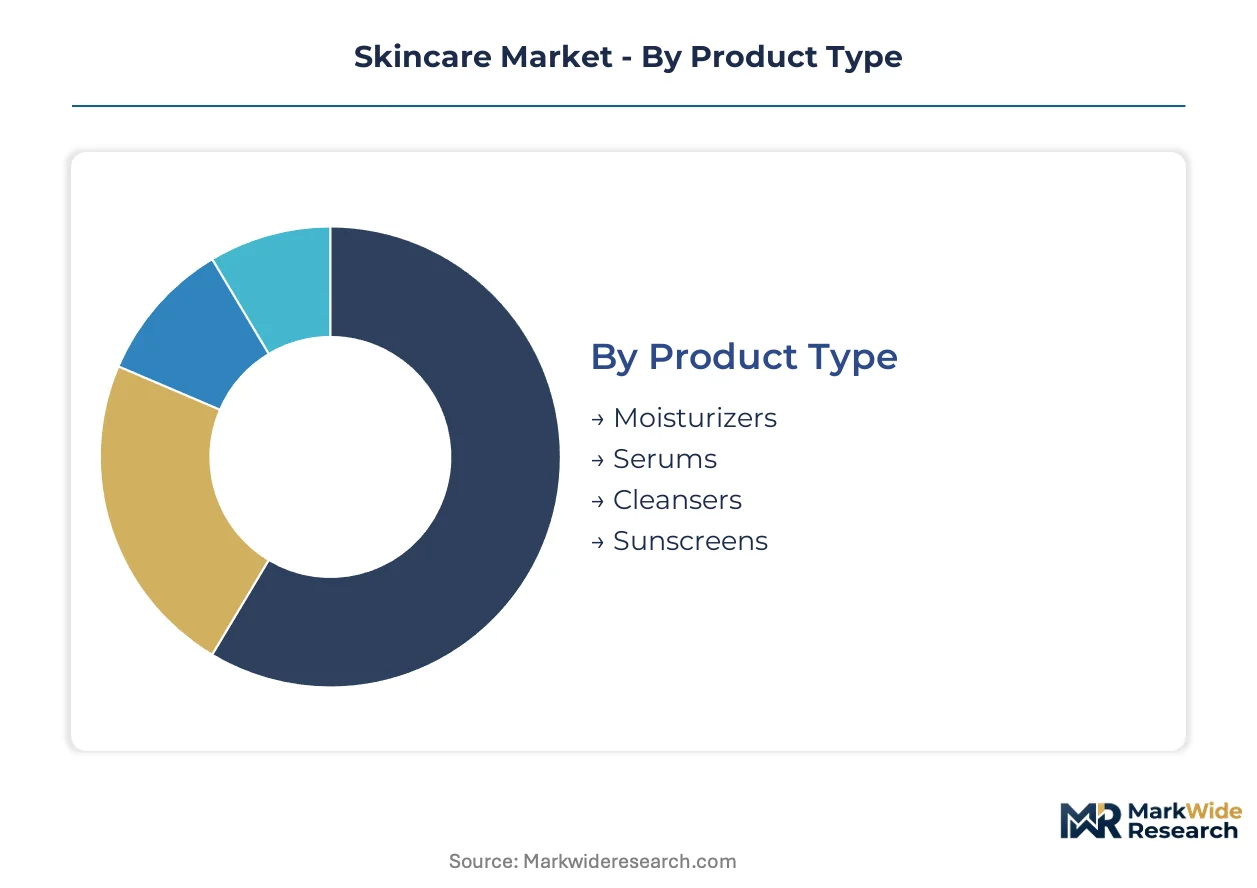
Skincare purchasing decisions pivot on formulation chemistry, clinical credibility, and channel accessibility. Distinct buyer profiles prioritize efficacy claims, clean ingredient sourcing, or dermatological endorsement, fragmenting demand across parallel segmentation axes.
Product Type:
Price tolerance and repeat purchase frequency separate mass-market staples from premium positioning tiers.
- Moisturizers:Emulsion-stabilized formulations combining humectants, emollients, and occlusives at pH-calibrated concentrations for barrier maintenance. Demand clusters in Seoul-Incheon contract manufacturing for Western brands seeking REACH-compliant clean beauty alternatives, with pharmacy channel dominance in Germany reinforcing clinical validation premiums.
- Serums:High-actives concentrates delivering targeted compounds like biotechnology-derived peptides or fermentation-based molecules in lightweight vehicles. Precision skincare systems developed in Yokohama capture tier-one China city demand, where fermentation-based ingredient science commands pricing premiums over synthetic alternatives.
- Cleansers:Surfactant-based or oil-based formulations for epidermal cleansing without barrier disruption.
- Sunscreens:UV filter systems facing reformulation delays from FDA-ECHA regulatory divergence on new active safety data requirements.
Volume sits with moisturizers; growth tilts toward serums.
Ingredient Type:
Regulatory constraint intensity and biodegradability mandates are redirecting R&D investment away from petrochemical platforms.
- Natural:Plant-derived extracts and botanical actives subject to batch-to-batch variability and supply chain traceability requirements. EU Green Deal disclosure mandates accelerate supplier consolidation around certified sustainable sources, with brands absorbing compliance cost premiums for mass-market positioning.
- Organic:Certified cultivation-standard ingredients meeting COSMOS or USDA specifications with restricted synthetic processing aids. German pharmacy channels anchor demand for clinically tested organic systems, where dermatological testing protocols create defensible brand positioning against conventional alternatives.
- Synthetic:Laboratory-engineered compounds offering batch consistency and cost-scaling advantages in high-volume channels.
- Hyaluronic Acid:Biopolymer retaining volume leadership through recombinant production cost efficiency despite mass-market margin compression risks.
Hyaluronic acid carries volume; organic ingredients are climbing the fastest.
Application:
Regulatory classification thresholds separate cosmetic positioning from drug-approval pathways with distinct commercial consequences.
- Daily Care:Maintenance formulations for cleansing, hydration, and basic protection without therapeutic claims. Korean contract manufacturers in Seoul and Incheon scale production for Western brands seeking clean beauty capacity expansion, with GMP-qualified expertise concentrating formulation chemistry talent.
- Anti-Aging:Retinoid, peptide, and antioxidant systems navigating FDA cosmetic-drug distinction based on intended-use claims. L'Oréal's integrated R&D centers in France and the United States accelerate biotechnology-derived active pipelines for this clinically positioned segment.
- Acne Treatment:Salicylic acid, benzoyl peroxide, and alternative actives requiring separate regulatory approval pathways in major jurisdictions.
- Sun Protection:UV filter systems facing accelerating reformulation cycles as ECHA REACH constraints tighten on synthetic preservative and fragrance compound usage.
Daily care holds volume; anti-aging shows steepest expansion trajectory.
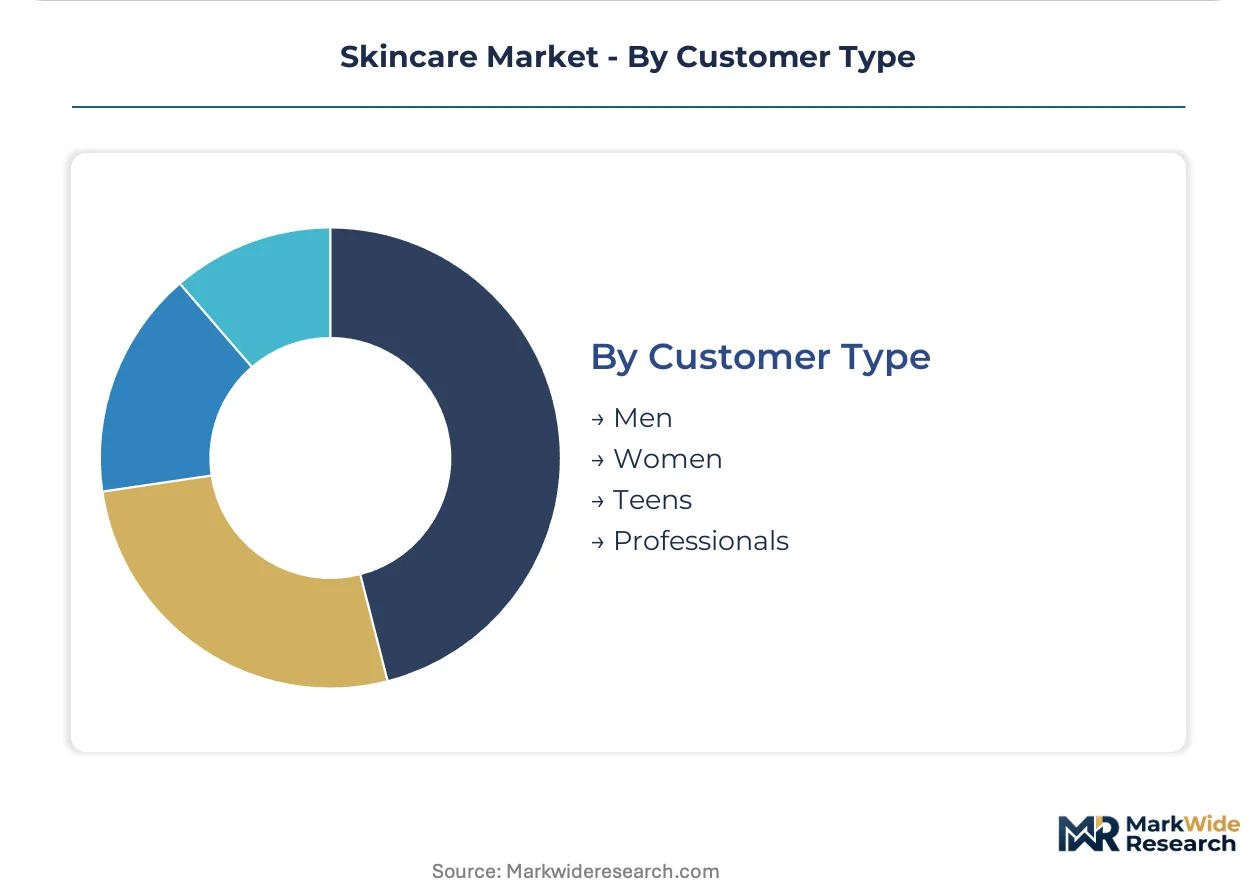
Customer Type:
Channel discovery patterns and clinical credibility transfer mechanisms vary sharply across demographic boundaries.
- Women:Core demographic driving premium moisturizer and serum repeat purchase frequency through medi-spa and dermatology clinic recommendations. China's tier-one cities concentrate underpenetrated precision skincare system demand, with pharmacy-anchored distribution retaining stronger consumer trust than department store counters.
- Men:Emerging segment attracted to simplified multi-function formulations and clinical channel positioning. Beiersdorf's dermatological testing protocols and German pharmacy dominance create template for male-focused brand extension with credibility transfer from established clinical platforms.
- Teens:Acne treatment and basic cleansing demand sensitive to price positioning and social media discovery.
- Professionals:Time-constrained buyers prioritizing efficacy-validated systems with minimal routine complexity.
Women anchor current volume; men represent the fastest-growing customer acquisition target.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul-Incheon anchors the fermentation-based ingredient supply chain for biotechnology-derived actives, while China's tier-one cities concentrate precision skincare demand. German pharmacy channels and US integrated R&D centers complete the geographic triad shaping competitive positioning.
United States
FDA cosmetic-drug distinction navigation and medi-spa channel expansion drive premium product uptake. The agency's separate approval pathways for anti-aging and acne treatment positioning force dual certification strategies. Greater Boston and Pacific Northwest clusters concentrate biotechnology-derived active R&D, with integrated centers accelerating novel compound pipelines.
Germany
Pharmacy channel dominance and dermatological testing protocols anchor clinically validated brand positioning. ECHA's REACH framework and the EU Green Deal constrain synthetic preservative usage, redirecting investment toward biodegradable alternatives. Bavaria and North Rhine-Westphalia host formulation chemistry expertise serving Western European clean beauty demand.
China
Tier-one city demand for precision skincare systems outpaces supply of fermentation-based ingredient platforms. NMPA and SAMR animal testing exemptions under specific conditions unlock mainland market access for compliant Western brands. Yangtze River Delta and Pearl River Delta clusters concentrate contract manufacturing capacity for domestic and imported brands.
South Korea
Seoul-Incheon manufacturing cluster scales clean beauty formulation capacity for Western brands seeking REACH-compliant alternatives. MFDS regulatory alignment with international standards accelerates export certification timelines. GMP-qualified emulsion stabilization expertise concentrates in the capital region, constraining Western scale-up capabilities.
Japan
Yokohama-based fermentation-based ingredient science commands pricing premiums in precision skincare systems. METI standards for biotechnology-derived actives create defensible IP positions for domestic innovators. Kanto region R&D facilities absorb investment shifting from synthetic chemistry platforms.
Skincare Market Key Industry Players
Global majors compete with regional champions across formulation chemistry expertise and channel access. The vendor base stratifies between integrated biotechnology players, pharmacy-anchored dermatological specialists, and contract manufacturing platforms. Three archetypes dominate: fermentation-science innovators, clinical-credibility brands, and clean-beauty scale operators. M&A activity concentrates on biotechnology capability acquisition, while capacity expansion targets Seoul-Incheon and Chinese tier-one city proximity.
Within the integrated biotechnology tier, L'Oréal S.A. and Shiseido Company Limited exemplify R&D-center-driven active compound development. Beiersdorf AG occupies a position anchoring pharmacy channel dominance through dermatological testing protocols. These three entities represent distinct geographic-strategic combinations: French-US integrated centers, Japanese fermentation science, and German clinical validation platforms.
| Leading Market Players |
|---|
| The Estée Lauder Companies Inc. |
| Beiersdorf AG |
| L'Oréal S.A. |
| Natura & Co. |
| Kao Corporation |
| Unilever PLC |
| Shiseido Company Limited |
| Coty Inc. |
| Procter & Gamble Company |
| Others |
Cost & Logistics Intelligence
Family-owned Korean contract manufacturers in Seoul and Incheon anchor supply-side discipline, connecting REACH-compliant clean beauty capacity expansion with premium pricing power for Western brands seeking formulation alternatives. Their concentrated GMP-qualified expertise limits Western scale-up options, reinforcing margin structures across moisturizer and serum categories.
Pricing Analysis
Extended clinical validation warranties bundled with dermatological testing protocols command 15-40% premiums over unbundled mass-market equivalents. Three-tier pricing structure across premium, standard, and economy levels separates pharmacy-anchored German brands with dermatological endorsement from Seoul-manufactured clean beauty alternatives and cost-scaled synthetic hyaluronic acid volume plays. Cost compression in mass-market moisturizers is intensifying because recombinant hyaluronic acid suppliers face margin pressure from Chinese tier-one city demand concentration. Professional channel buyers through medi-spa and dermatology clinics exhibit lowest price sensitivity, while teen segment acne treatment purchasers show highest elasticity.
Supply Chain Analysis
Dual-sourcing mandates from EU and US brands seeking REACH-compliant alternatives now require qualified backup suppliers across South Korea, Germany, and Japan. Raw material dependencies center on fermentation-derived biocides, biodegradable emulsion stabilizers, and UV filter actives subject to FDA-ECHA regulatory divergence. Single-source vulnerability concentrates in Seoul-Incheon's GMP-qualified formulation chemist pool, where talent scarcity constrains Western scale-up timelines. Distribution runs through pharmacy channels in Germany, medi-spa networks in the United States, and tier-one city precision skincare boutiques in China.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from REACH-mandated preservative system retrofits will force out mid-tier brands lacking biotechnology R&D scale or Seoul-Incheon manufacturing partnerships.
For Market Incumbents: Extend fermentation-based ingredient science capabilities through Yokohama or Seoul-Incheon R&D partnerships to defend against synthetic chemistry platform obsolescence. Lock in multi-year contracts with GMP-qualified contract manufacturers before formulation chemist scarcity worsens. Prioritize pharmacy channel control in Germany and medi-spa network expansion in the United States to capture clinical credibility transfer premiums. For New Entrants and Emerging Players: Dermatology clinic distribution partners in China's tier-one cities offer the most penetrable white space for precision skincare systems with fermentation-based positioning. Target male-focused simplified formulations leveraging German dermatological testing protocols as credibility anchor. Pursue direct-to-clinic sampling programs bypassing traditional retail discovery costs. For Investors and Strategic Acquirers: Distressed-cycle entries favor clean beauty contract manufacturers with Seoul-Incheon capacity and REACH-compliant certification pipelines. Five-to-ten year viability hinges on biotechnology-derived active compound IP positions rather than synthetic chemistry legacy assets. Watch NMPA animal testing exemption expansion as inflection signal for Western brand China market access acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Biotechnology R&D Center Integration | L'Oréal's France-US centers accelerate novel active pipelines ahead of synthetic chemistry obsolescence. |
| Clean Beauty Capacity Expansion | Seoul-Incheon contract manufacturers scale REACH-compliant formulation alternatives for Western brand demand. |
| Pharmacy Channel Dominance | Beiersdorf's German dermatological testing protocols create defensible positioning against retail-discovered competitors. |
| Precision Skincare System Launch | Shiseido's Yokohama fermentation science captures tier-one China city pricing premiums. |
| Medi-Spa Network Partnership | Clinical credibility transfer through US dermatology clinics displaces department store counter discovery. |
Research Approach
Multi-period observation of NMPA regulatory exemption patterns, REACH compliance cost trajectories, and Seoul-Incheon manufacturing capacity utilization anchored the trend analysis, supplemented by interviews with formulation chemists at Korean contract manufacturers, regulatory affairs leads at German pharmacy-anchored brands, medi-spa procurement directors in US metropolitan markets, and biotechnology R&D directors in French and Japanese integrated centers. Secondary validation drew from ECHA substance restriction updates, FDA UV filter approval dockets, MFDS export certification timelines, and customs trade data on hyaluronic acid feedstock flows. Bottom-up segment sizing triangulated against top-down market value reconstruction.
Segment-weighting across product type, ingredient category, application positioning, and customer demographic distributed value and volume estimates across the projection horizon. Modeled dimensions included emulsion complexity tier, active compound sourcing origin, regulatory pathway classification, and channel discovery mechanism. CAGRs derived from elasticity-adjusted demand curves incorporating professional channel penetration rates and clean beauty certification adoption slopes. Forecast inputs incorporated ECHA biocide restriction phase-in schedules and NMPA animal testing policy evolution scenarios.
Caveats apply where FDA-ECHA regulatory divergence on UV filter safety data or MFDS export certification backlog could materially shift the outlook. Forecasts assume stable REACH enforcement intensity and continued Seoul-Incheon manufacturing cluster capacity expansion. Deviation in China animal testing exemption scope or fermentation-based ingredient scale-up timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Anti Stretch Mark Products Market
Beauty & Personal Care
Facial Epilator Market
Beauty & Personal Care
Spain Dermocosmetics Market
Beauty & Personal Care
Germany Beauty Industry Market
Beauty & Personal Care
Body Firming Creams Market
Beauty & Personal Care
Hair Removal Wax Market
Beauty & Personal Care
Europe Cosmetics Market
Beauty & Personal Care
India Antibacterial Soap Market
Beauty & Personal Care
Middle East and Africa Hair Conditioner Market
Beauty & Personal Care
Personalized Beauty Devices Market
Beauty & Personal Care
North America Hair Removal Wax Market
Beauty & Personal Care
UK Sustainable Personal Care Market
Beauty & Personal Care
Nail Polish Remover Market
Beauty & Personal Care
Malaysia Aromatherapy Products Market
Beauty & Personal Care
UK Vegan Cosmetics Market
Beauty & Personal Care
Oil Control Shampoo Market