
 India Antibacterial Soap Market | 2026-2036
India Antibacterial Soap Market Size, Share, and Industry Trends Forecast 2026-2036
India Antibacterial Soap Market Insights
The capital-intensity divergence between integrated manufacturers and contract-dependent brands is reorganizing competitive tiers in India's antibacterial soap sector. Hindustan Unilever Limited leverages its extensive rural distribution network to sustain volume leadership across price points. Reckitt Benckiser India anchors its position through concentrated investment in germ-protection science and premium positioning. Jyothy Labs competes aggressively in value-tier segments with localized manufacturing and regional brand strength.
India antibacterial soap comprises cleansing formulations containing antimicrobial agents such as triclosan, triclocarban, or benzalkonium chloride, manufactured through saponification or synthetic detergent processes to reduce bacterial load on skin surfaces. Bar soap dominates mass-market volumes due to lower per-unit cost and established consumer habits, while liquid soap captures faster expansion in urban households and institutional channels seeking dispenser-compatible hygiene solutions. The distribution channel structure concentrates margin pools in supermarkets and online retail, where branded players extract premium pricing through bundled promotions and subscription models.
BIS formulation standards, CDSCO oversight of medicated soap claims, and FSSAI ingredient safety protocols collectively shape product development cycles and market access requirements for domestic manufacturers. Compliance costs favor larger entities with dedicated regulatory affairs capacity, narrowing the field for new entrants. Stakeholders must monitor evolving restrictions on synthetic antimicrobials and the pace of natural-extract substitution to align portfolio decisions with enforcement trajectories.
Market Dynamics
BIS certification mandates for antimicrobial formulations are compressing the supplier base and forcing manufacturers to rebuild sourcing relationships around compliant ingredient vendors. This regulatory pressure is redistributing margin pools toward integrated producers with captive laboratory capacity.
Growth Catalysts
- Urban sanitation campaigns:Municipal hygiene drives in Maharashtra and Gujarat are creating institutional procurement pipelines for dispenser-compatible liquid formats in schools and hospitals.
- CDSCO oversight clarity:Defined medicated soap claim boundaries are enabling brands to market germ-protection efficacy without crossing into pharmaceutical classification.
- Natural extract substitution:Neem and tulsi-based antimicrobial formulations are capturing shelf space as retailers respond to consumer preference shifts away from synthetic actives.
Market Restraints
- Palm oil price volatility:Saponification feedstock costs swing with Malaysian and Indonesian export policies, squeezing gross margins for bar soap specialists.
- Surfactant import concentration:Linear alkylbenzene sulfonate supply clusters in Gujarat's petrochemical corridor, exposing brands to single-state logistics disruptions.
- Triclosan phase-out friction:FSSAI ingredient safety protocols have restricted legacy antimicrobial agents without fully certifying replacement compounds, delaying reformulation cycles.
Strategic Opportunities
- Tier-2 city retail penetration:Kirana store digitization in Madhya Pradesh and Rajasthan is opening direct-to-retail distribution channels previously gated by wholesaler networks.
- Subscription commerce models:Online platforms are bundling liquid soap refills with household cleaning products, locking in recurring revenue from urban apartment complexes.
- PLI scheme alignment:Domestic manufacturing incentives for personal care chemicals are enabling backward integration into active ingredient synthesis.
Industry Challenges
- Formulation chemist scarcity:BIS-compliant antimicrobial stability testing requires specialized talent concentrated in Mumbai and Bangalore R&D clusters.
- Multi-regulator compliance timelines:Parallel CDSCO cosmetic notifications and FSSAI safety assessments extend product launch windows by eight to fourteen months.
- Legacy distributor resistance:Traditional stockist networks in Uttar Pradesh and Bihar obstruct direct-to-retail pilot programs that bypass established commission structures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India Antibacterial Soap Market |
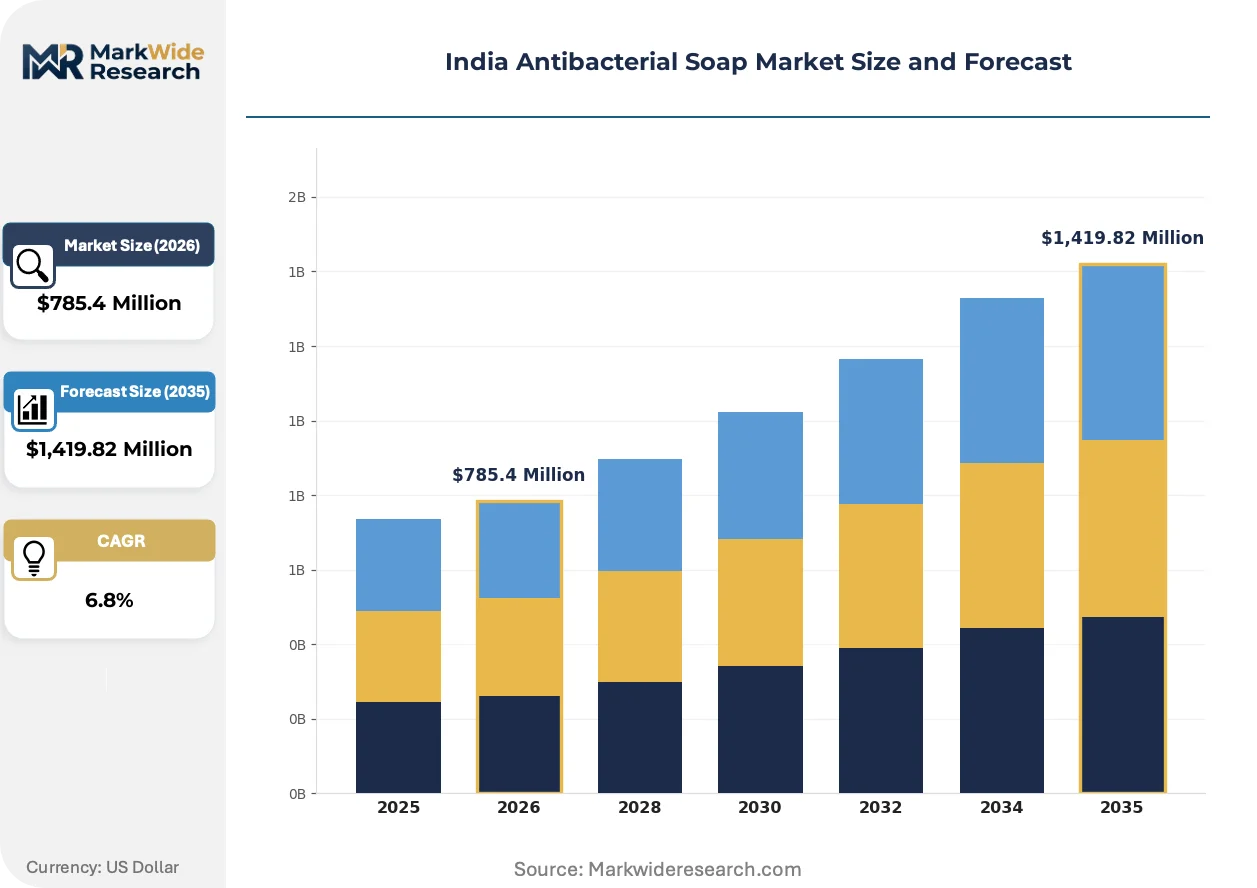
| Market Size in 2026 | $785.4 Million |
| Market Size in 2035 | $1,419.82 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Liquid Soap, Bar Soap, Foaming Soap, Gel Soap Distribution Channel: Online Retail, Supermarkets, Drugstores, Convenience Stores End User: Households, Healthcare Facilities, Hotels, Schools Ingredient Type: Natural Extracts, Synthetic Antibacterials, Essential Oils, Antimicrobial Agents |
| Companies Covered | Wipro Consumer Care & Lighting Ltd., Reckitt Benckiser India, Hindustan Unilever Limited, Dettol (Reckitt Benckiser), Johnson & Johnson Private Limited, ITC Limited, Jyothy Labs, Savlon (ITC Limited), Godrej Consumer Products Pvt. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India Antibacterial Soap Market Trends and Innovations
Antimicrobial soap formulation is diverging along two paths: synthetic agent refinement for institutional efficacy and botanical extract standardization for consumer-facing natural positioning. This bifurcation is reshaping R&D allocation and supplier relationships simultaneously.
Encapsulated essential oil delivery systems are fragmenting the traditional preservative-additive supply chain. These microsphere technologies enable time-release antimicrobial action from tea tree and eucalyptus extracts. Institutional buyers in hospital procurement are piloting these formats for surgical scrub compatibility. The technology is fragmenting incumbent chemical supplier relationships as fragrance houses and pharmaceutical excipient vendors enter formulation partnerships.
BIS formulation standards are tightening allowable preservative concentrations in rinse-off products. The regulation is forcing manufacturers to validate alternative antimicrobial mechanisms including pH modulation and chelation. Bar soap producers in Tamil Nadu and Karnataka are investing in in-house stability testing to maintain certification without third-party laboratory delays.
Quick-commerce platforms are compressing replenishment cycles for liquid soap in metropolitan households. Mumbai and Delhi consumers now expect two-hour delivery for personal care staples, displacing monthly supermarket stock-up trips. This pattern is most visible among dual-income apartment dwellers who prioritize convenience over unit economics in hygiene purchasing.
India Antibacterial Soap Market Segmentation
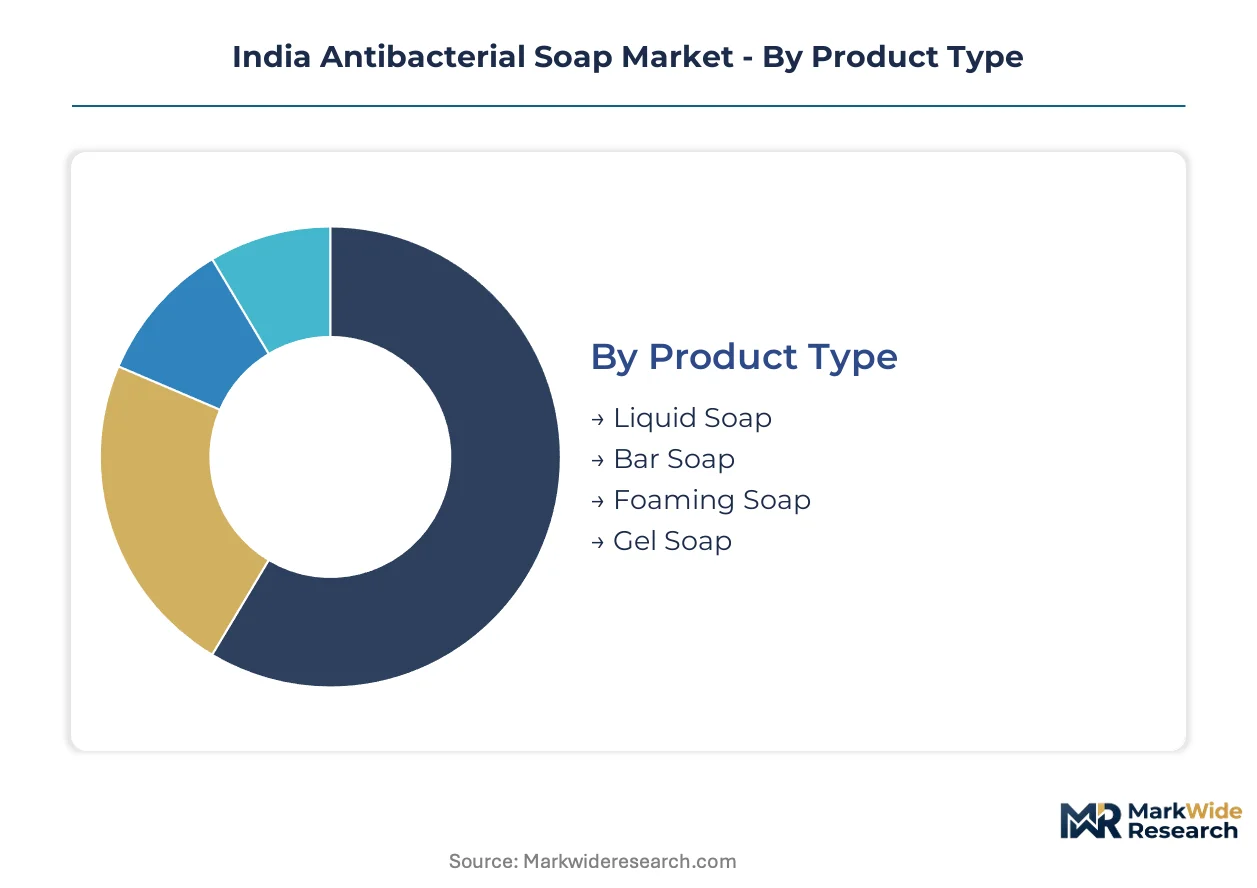
Segmentation in India's antibacterial soap market determines pricing power, regulatory pathway, and channel economics. Manufacturers configure product portfolios around format preferences that vary sharply between institutional buyers and household consumers.
Product Type:
Channel-mix dynamics channel bar formats through kirana networks while liquid and gel variants concentrate in modern trade and institutional procurement pipelines.
- Bar Soap:Saponified fatty acid formulations deliver lowest per-wash cost. Mass-market demand clusters in Maharashtra and Gujarat kirana stores, constrained by palm oil feedstock volatility squeezing margin.
- Liquid Soap:Synthetic detergent bases enable dispenser compatibility and controlled dosing. Urban households in Mumbai and Delhi apartment complexes drive expansion through quick-commerce replenishment cycles.
- Foaming Soap:Pre-aerated formulations reduce water consumption in high-traffic restrooms. Pilot adoption is visible in Gujarat municipal school sanitation contracts.
- Gel Soap:Thickened surfactant systems offer visual differentiation and cling properties. Premium positioning targets hotel amenity programs in Bangalore and Hyderabad hospitality clusters.
Bar soap dominates installed base across rural India. Liquid soap is where expansion concentrates in metropolitan and institutional channels.
Distribution Channel:
Margin pools concentrate in channels with branded pricing power and subscription lock-in potential, diverging from commodity throughput in traditional wholesale.
- Supermarkets:Modern trade formats extract premium through bundled promotions and visibility placement. Maharashtra and Gujarat retail penetration supports branded antibacterial positioning.
- Online Retail:E-commerce platforms enable subscription bundling with household cleaning categories. Urban apartment complexes in Delhi and Mumbai generate recurring refill revenue.
- Drugstores:Pharmacy channels validate medicated claims under CDSCO oversight. Healthcare-adjacent positioning supports price premiums for germ-protection formulations.
- Convenience Stores:Small-format retail captures impulse replenishment in transit corridors. Commission structures in Uttar Pradesh and Bihar obstruct direct-to-retail pilot programs.
Supermarkets anchor volume throughput for established brands. Online retail is climbing the fastest as quick-commerce platforms compress delivery windows.
End User:
Application context shapes formulation specification, with institutional buyers demanding batch certification and households responding to sensory and price cues.
- Households:Consumer purchasing prioritizes fragrance, skin-feel, and unit economics. Tier-2 city middle-income expansion in Madhya Pradesh and Rajasthan widens the addressable base.
- Healthcare Facilities:Hospital procurement mandates surgical scrub compatibility and microbial log-reduction documentation. Encapsulated essential oil delivery systems are piloting in Tamil Nadu medical clusters.
- Hotels:Amenity programs require bulk dispensing formats and brand-neutral packaging. Bangalore and Hyderabad hospitality supply chains favor gel and liquid presentations.
- Schools:Municipal sanitation campaigns in Maharashtra and Gujarat create institutional pipelines for dispenser-compatible liquid formats in educational facilities.
Households represent the deepest volume pool. Healthcare facilities command the steepest expansion trajectory as infection control protocols tighten.
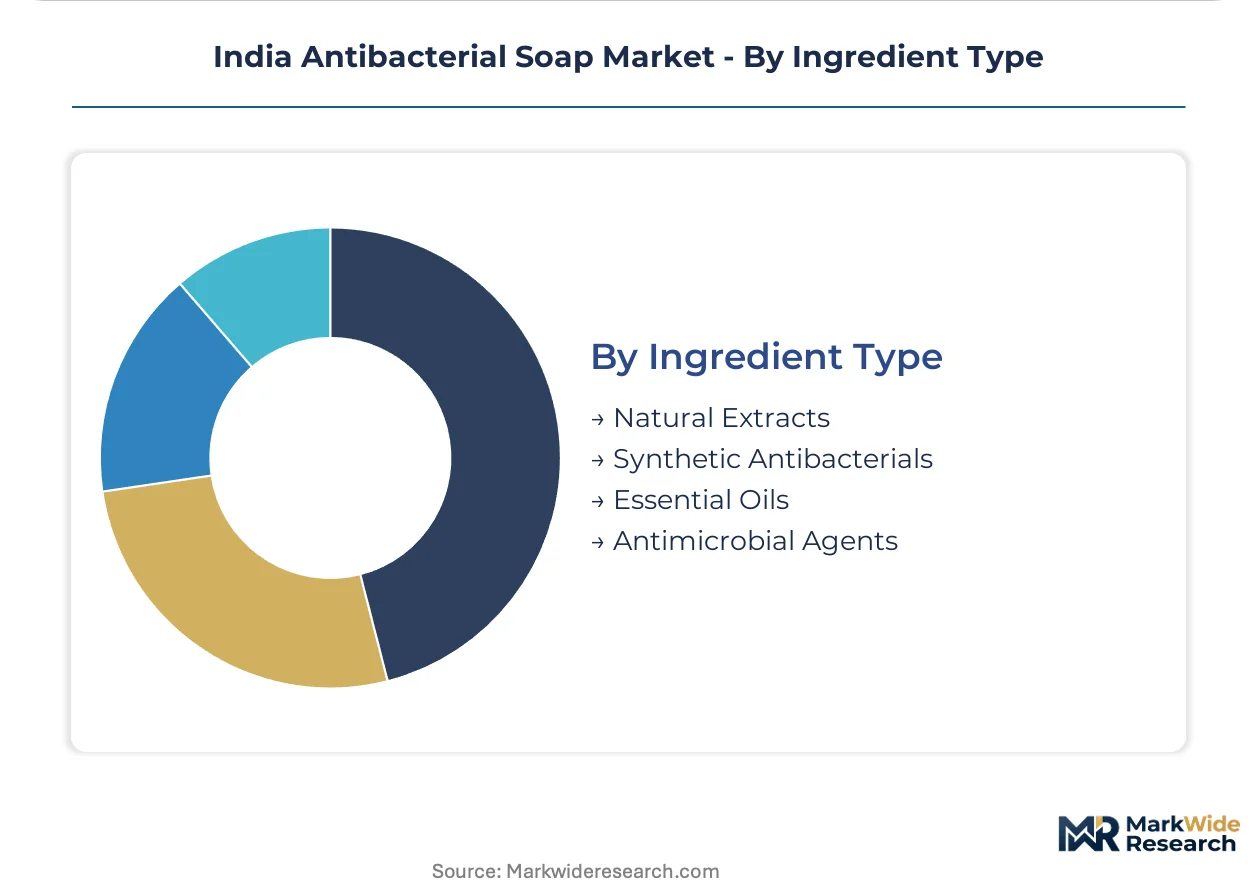
Ingredient Type:
Supply concentration in Gujarat's petrochemical corridor and Western Ghats botanical processing shapes sourcing economics and regulatory exposure.
- Natural Extracts:Neem and tulsi-based formulations respond to consumer preference shifts away from synthetic actives. Shelf space expansion in modern trade reflects retailer risk mitigation on FSSAI enforcement.
- Synthetic Antibacterials:Triclosan phase-out under FSSAI protocols has restricted legacy agents without fully certifying replacements. Reformulation cycles face eight-to-fourteen-month regulatory windows.
- Essential Oils:Tea tree and eucalyptus microsphere encapsulation enables time-release antimicrobial action. Fragrance houses and pharmaceutical excipient vendors are entering formulation partnerships.
- Antimicrobial Agents:Benzalkonium chloride and alternative actives require BIS stability validation. Compliance costs favor integrated producers with captive laboratory capacity in Mumbai and Bangalore.
Synthetic antibacterials retain institutional efficacy share. Natural extracts are gaining share fastest as BIS preservative concentration limits tighten and consumer sentiment shifts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Maharashtra and Gujarat concentrate dispenser-compatible liquid format adoption through municipal sanitation contracts, while southern states anchor bar soap volume through kirana network density and price-sensitive household purchasing.
Maharashtra
Mumbai's quick-commerce corridors drive two-hour liquid soap replenishment cycles among dual-income apartment dwellers. The state's urban sanitation campaigns create institutional procurement pipelines for schools and hospitals. Pune and Nagpur manufacturing clusters supply synthetic detergent bases to national brands.
Gujarat
Surat and Ahmedabad kirana networks sustain bar soap throughput through established wholesaler relationships. The state's petrochemical corridor concentrates linear alkylbenzene sulfonate supply, exposing brands to single-state logistics exposure. Vadodara formulators pilot foaming soap formats for municipal school contracts.
Karnataka
Bangalore hospitality clusters generate gel soap demand for hotel amenity programs. The state's R&D talent concentration supports BIS-compliant antimicrobial stability testing. Mysuru and Hubli distributors face legacy stockist resistance to direct-to-retail digitization pilots.
Tamil Nadu
Chennai medical clusters pilot encapsulated essential oil delivery systems for surgical scrub compatibility. Coimbatore bar soap producers invest in captive stability testing to avoid third-party laboratory delays. The state's neem processing infrastructure feeds natural extract substitution trends.
Delhi-NCR
Gurgaon and Noida apartment complexes anchor subscription commerce bundling of liquid soap refills with household cleaning products. The National Capital Region's retail density supports modern trade premium extraction through bundled promotions. Faridabad distributors navigate multi-regulator compliance timelines extending product launch windows.
India Antibacterial Soap Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with capital-intensity divergence reorganizing competitive tiers through captive laboratory capacity and rural distribution depth. Three archetypes dominate: diversified FMCG conglomerates with backward integration into active ingredient synthesis, mid-cap regional specialists with localized manufacturing footprints, and contract-dependent brands reliant on third-party formulators. Competitive moves concentrate on kirana store digitization partnerships and PLI scheme alignment for personal care chemical manufacturing.
Within the integrated conglomerate tier, Hindustan Unilever Limited and ITC Limited exemplify scale-driven positioning through extensive rural distribution networks and modern trade premium extraction. Reckitt Benckiser India occupies a position concentrated on germ-protection science investment and premium-tier positioning. Jyothy Labs represents the regional specialist archetype with value-tier segment focus and localized manufacturing strength in southern markets.
| Leading Market Players |
|---|
| Wipro Consumer Care & Lighting Ltd. |
| Reckitt Benckiser India |
| Hindustan Unilever Limited |
| Dettol (Reckitt Benckiser) |
| Johnson & Johnson Private Limited |
| ITC Limited |
| Jyothy Labs |
| Savlon (ITC Limited) |
| Godrej Consumer Products Pvt. Ltd. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day inventory cycles for palm oil feedstock in Maharashtra and Gujarat determine margin volatility for bar soap manufacturers while concentrating pricing power among integrated producers with captive storage capacity. BIS certification timelines stretching eight to fourteen months force brands to pre-position compliant ingredients, compressing working capital flexibility for contract-dependent players and widening cost spreads between integrated and outsourced production models.
Pricing Analysis
Long-term offtake contracts for linear alkylbenzene sulfonate from Gujarat's petrochemical corridor anchor pricing for liquid soap manufacturers, while spot market exposure for palm oil derivatives drives volatility in bar soap economics. Price differentiation rests on BIS certification tier and volume scale, with institutional buyers commanding discounts against retail premiums. Cost compression in value-tier bar formats is intensifying because palm oil import duties and Malaysian export policy swings feed directly into saponification costs. Tier-2 city kirana consumers exhibit highest price sensitivity, whereas Mumbai and Delhi apartment dwellers purchasing through quick-commerce platforms accept convenience premiums.
Supply Chain Analysis
Just-in-time inventory strategies dominate liquid soap production for quick-commerce replenishment, whereas bar soap specialists maintain strategic stockpiles of palm oil derivatives to hedge against Malaysian and Indonesian export volatility. Supply concentration centers on India for neem and tulsi botanical processing, Malaysia and Indonesia for palm oil feedstock, and Gujarat for synthetic surfactant production. Raw material dependencies encompass palm oil fatty acids, linear alkylbenzene sulfonate, and antimicrobial actives awaiting FSSAI replacement certification. Single-state logistics exposure in Gujarat's petrochemical corridor presents structural vulnerability. Distribution runs through kirana networks in Maharashtra and Gujarat for bar formats, with modern trade and quick-commerce channels capturing liquid soap margin pools.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
India's antibacterial soap market sits in early-cycle expansion as municipal sanitation campaigns in Maharashtra and Gujarat institutionalize dispenser-compatible liquid formats, creating procurement pipelines that outpace household penetration rates in comparable emerging markets.
For Market Incumbents: Secure BIS certification capacity through captive laboratory investment in Mumbai and Bangalore to compress eight-to-fourteen-month compliance timelines that threaten product launch velocity. Lock in backward integration into active ingredient synthesis under PLI scheme incentives before feedstock volatility squeezes contract manufacturers. Defend against natural extract substitution trends by accelerating encapsulated essential oil delivery partnerships with fragrance houses and pharmaceutical excipient vendors.
For New Entrants and Emerging Players: CDSCO cosmetic notification fast-tracks for germ-protection claims without pharmaceutical classification open immediate positioning opportunities against legacy brands burdened by triclosan phase-out friction. White-space concentration appears in tier-2 city kirana digitization across Madhya Pradesh and Rajasthan, where direct-to-retail channels bypass entrenched wholesaler commission structures. Subscription commerce bundling with household cleaning products offers the most penetrable go-to-market angle for urban apartment complexes in Delhi and Mumbai.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified FMCG conglomerates seeking to divest non-core personal care chemical assets with stranded regulatory compliance costs. Long-term viability favors integrated manufacturers with captive laboratory capacity and established BIS certification relationships over contract-dependent brands exposed to multi-regulator timeline extensions. Watch FSSAI certification velocity for synthetic antimicrobial replacements as the inflection signal distinguishing reformulation-capable assets from stranded legacy formulations.
| Strategic Initiative | Industry Significance |
|---|---|
| Kirana Store Digitization Partnership | Madhya Pradesh and Rajasthan direct-to-retail channels bypass Uttar Pradesh and Bihar stockist resistance. |
| Backward Integration into Active Ingredient Synthesis | PLI scheme alignment reduces exposure to Gujarat petrochemical corridor logistics disruptions. |
| Encapsulated Essential Oil Delivery Development | Tamil Nadu medical clusters pilot surgical scrub compatibility for hospital procurement pipelines. |
| Subscription Commerce Model Launch | Delhi and Mumbai apartment complexes generate recurring refill revenue through bundled household cleaning. |
| BIS Certification Capacity Expansion | Mumbai and Bangalore captive laboratories compress product launch windows against contract-dependent competitors. |
Research Methodology
Initial hypotheses were tested against primary input from brand managers at integrated FMCG conglomerates, category buyers at modern trade retailers, supply planners at contract manufacturing facilities, and regulatory affairs leads navigating CDSCO cosmetic notifications and FSSAI safety assessments. Secondary validation drew from BIS formulation standards documentation, CDSCO medicated soap claim guidelines, customs records tracking palm oil derivative imports, and Nielsen retail audit data for Maharashtra and Gujarat kirana networks. Bottom-up demand modeling across household, healthcare, hotel, and school end-use segments was triangulated against top-down value chain analysis.
Variance decomposition across the projection horizon isolates volume drivers from price-mix effects within product type, distribution channel, end user, and ingredient type segmentation dimensions. CAGRs were derived from segment-level growth trajectory analysis incorporating urban sanitation campaign procurement pipelines, tier-2 city middle-income expansion patterns, and natural extract substitution velocity. Industry-specific forecast inputs encompass BIS certification timeline distributions and quick-commerce platform penetration rates in metropolitan apartment complexes.
Underlying assumptions cover regulatory enforcement consistency for synthetic antimicrobial phase-outs, with deviation risk concentrated in FSSAI replacement compound certification delays and palm oil export policy volatility from Malaysia and Indonesia. Revision becomes warranted when BIS preservative concentration limits tighten beyond current formulation adaptation capacity or when PLI scheme incentives shift domestic manufacturing economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Organic Liquid Soaps Market
Beauty & Personal Care
BB Cushions Market
Beauty & Personal Care
Europe Halal Cosmetics Market
Beauty & Personal Care
Hair Thickener Serum Market
Beauty & Personal Care
South America Hair Conditioner Market
Beauty & Personal Care
Herbal Beauty Products Market
Beauty & Personal Care
Hair Wig Market
Beauty & Personal Care
Lip Care Products Market
Beauty & Personal Care
Beauty Oils Market
Beauty & Personal Care
Colombia Hair Care Market
Beauty & Personal Care
LAMEA Hair Removal Wax Market
Beauty & Personal Care
Asia Pacific Beauty Fridges Market
Beauty & Personal Care
Intimate Wash Care Products Market
Beauty & Personal Care
Deodorant and Antiperspirants Market
Beauty & Personal Care
Hair Color Spray Market
Beauty & Personal Care
Foaming Hand Soaps Market