
 Anti Stretch Mark Products Market | 2026-2036
Anti Stretch Mark Products Market Size, Share, and Industry Trends Forecast 2026-2036
Anti Stretch Mark Products Market Intelligence
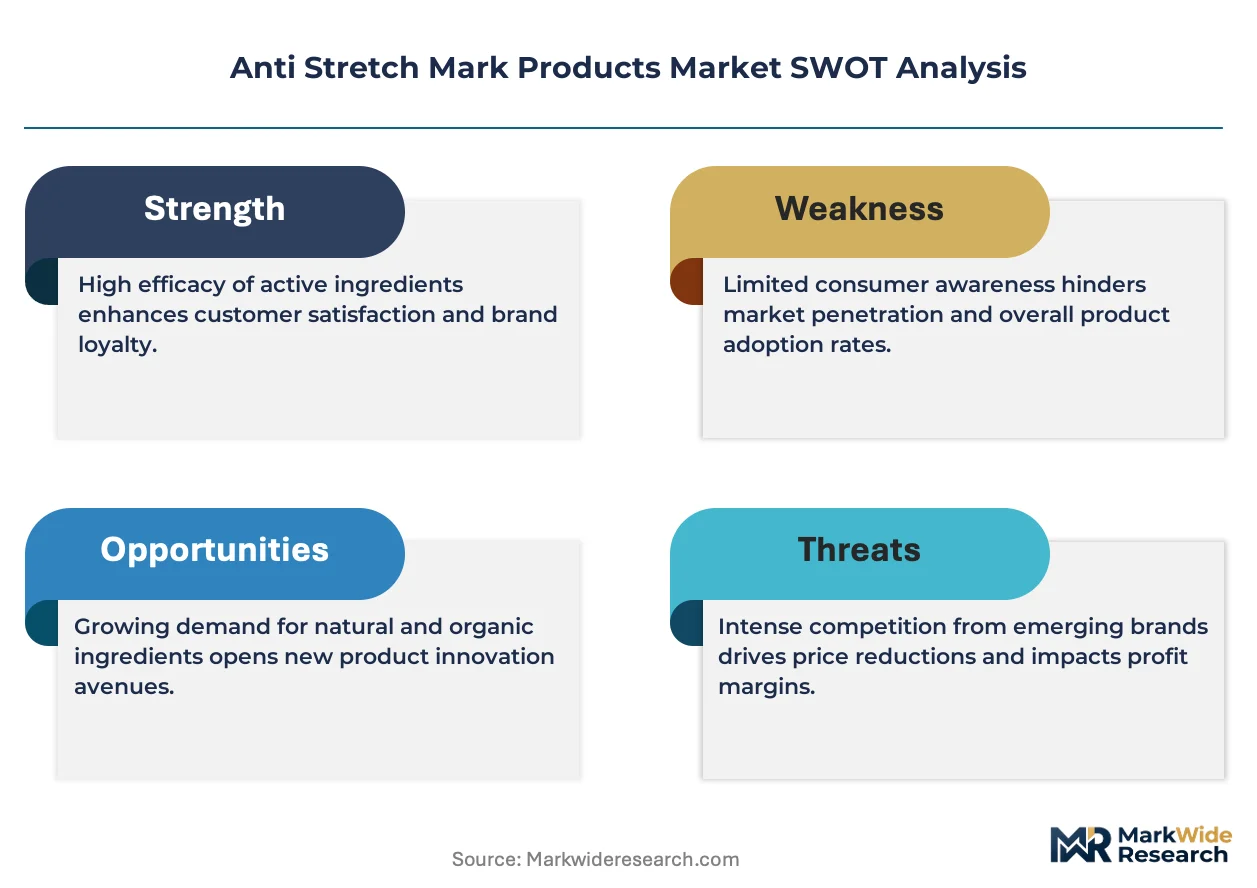
Buyer concentration among pregnant women is expanding as maternity clinics and prenatal care networks consolidate skincare recommendations into standardized protocols. L'Oréal S.A. leverages its dermatological science heritage to anchor premium positioning in clinical channels. Beiersdorf AG sustains mass-market reach through Nivea's trusted equity in maternity segments. Mustela specializes in perinatal formulations, competing on pediatrician endorsement density rather than advertising scale.
Anti stretch mark products comprise topical formulations—creams, oils, gels, and butters—engineered with emollients, peptides, and botanical extracts to improve dermal elasticity and reduce collagen fiber disruption. These products serve both preventive application during pregnancy and corrective use post-weight fluctuation or adolescent growth spurts. Creams dominate volume due to familiar texture and lower price positioning, while oils capture margin pools through premium natural ingredient positioning and ritual-driven consumption patterns. The ingredient type dimension splits between natural and synthetic pathways, with herbal extracts gaining traction among consumers seeking clean-label alternatives to chemical-based retinoid formulations.
The EU Cosmetics Regulation (EC) No 1223/2009 mandates safety assessments and ingredient disclosure that elevate compliance costs for new entrants. The U.S. FDA oversees cosmetic labeling claims, restricting therapeutic language that would trigger drug classification. India's CDSCO and BIS frameworks govern import quality standards for international brands entering the domestic market. Stakeholders must monitor regulatory divergence between jurisdictions where clean-label expectations tighten and those where cost-sensitive synthetic formulations still dominate purchasing decisions.
Market Dynamics
Maternity skincare protocols are professionalizing as prenatal clinics integrate stretch mark prevention into standardized patient care pathways, elevating formulation science requirements and channel access barriers for new entrants.
Growth Catalysts
- EU Cosmetics Regulation (EC) No 1223/2009:Safety assessment mandates are accelerating R&D investment in clinically validated formulations, filtering out undercapitalized competitors and rewarding dermatological science capabilities.
- Pregnant women segment professionalization:Prenatal care networks are consolidating skincare recommendations into protocol-driven dispensing, creating institutional demand pull for prescription-grade efficacy claims.
- Peptide engineering advances:Collagen-stimulating peptide complexes are replacing basic emollient formulations in premium positioning, enabling measurable elasticity improvement claims that command price premiums.
Market Restraints
- Shea butter and marula oil price volatility:Climate-induced harvest variability in West African and Southern African sourcing regions is compressing margins for natural-positioned brands dependent on fixed botanical supply contracts.
- FDA cosmetic-drug boundary enforcement:Therapeutic language restrictions on collagen repair and scar reduction claims are limiting marketing differentiation and forcing costly clinical trial investments for repositioning.
- Retinoid substitution threat:Prescription tretinoin formulations prescribed through dermatology channels are capturing corrective-use occasions from over-the-counter alternatives despite pregnancy contraindications.
Strategic Opportunities
- India CDSCO import pathway expansion:Streamlined quality standard recognition for EU-certified formulations is opening access to 25 million annual births and underdeveloped maternity skincare infrastructure.
- Telehealth prenatal platform integration:Virtual maternity care providers are adding skincare modules to subscription bundles, creating direct-to-patient dispensing channels bypassing traditional retail.
- Biometric skin elasticity monitoring convergence:Wearable dermal sensors paired with personalized formulation algorithms are enabling outcome-linked subscription models with retention advantages over static product sales.
Industry Challenges
- Cosmetic chemist talent scarcity:Formulation expertise bridging dermatological efficacy and cosmetic elegance is concentrated among senior professionals approaching retirement, constraining pipeline velocity for mid-tier brands.
- ISO 16128 natural origin certification timelines:Bureaucratic verification processes for clean-label claims are delaying product launches by 8-14 months, ceding first-mover advantage to established certificated portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Anti Stretch Mark Products Market |
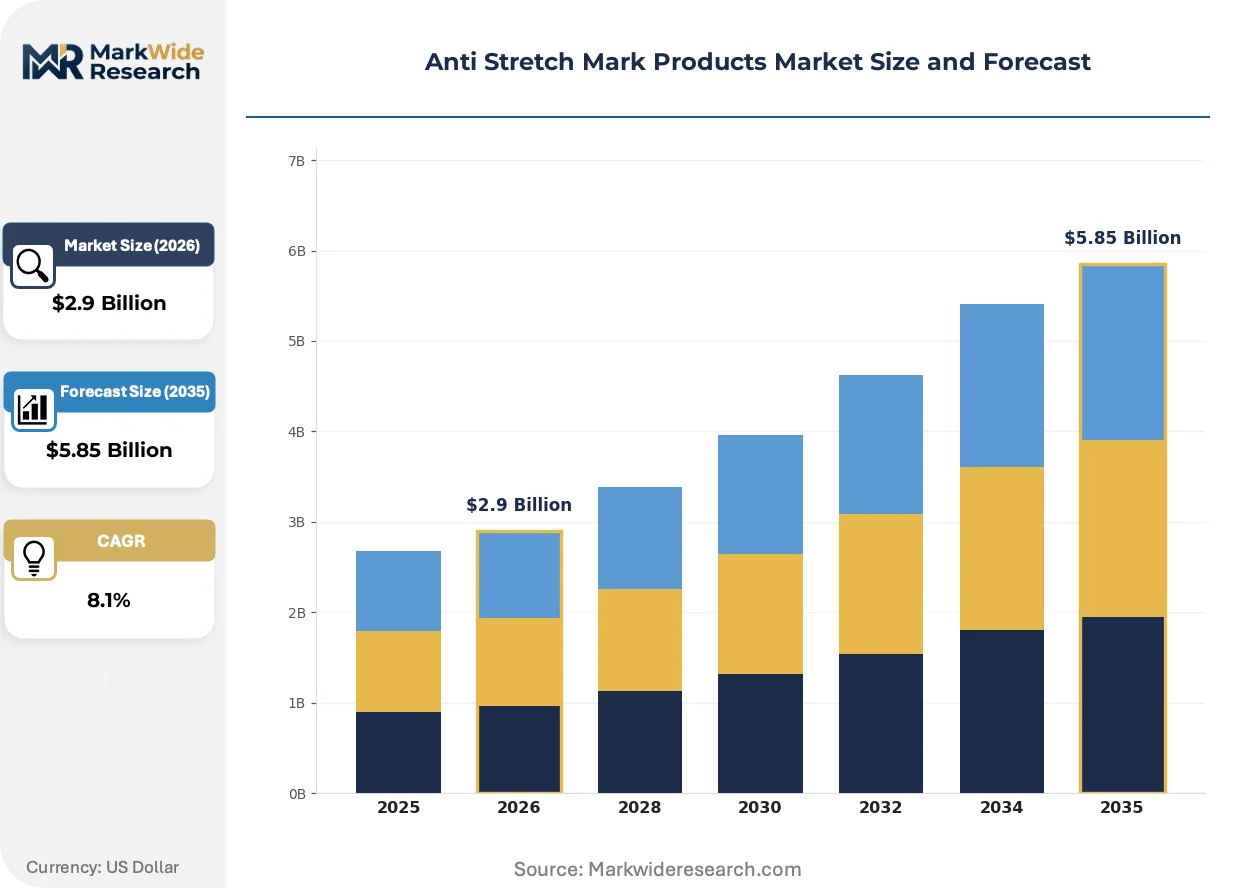
| Market Size in 2026 | $2.9 Billion |
| Market Size in 2035 | $5.85 Billion |
| CAGR (2026 – 2036) | 8.1% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Creams, Oils, Gels, Butters Ingredient Type: Natural, Synthetic, Herbal, Chemical Application Area: Abdomen, Thighs, Breasts, Hips End User: Pregnant Women, Bodybuilders, Adolescents, General Consumers |
| Companies Covered | L’Oréal S.A., Beiersdorf AG, Mustela, Bio Oil, Clarins, The Estée Lauder Companies Inc., Himalaya Global Holdings Ltd., Palmer’s, Weleda AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Anti Stretch Mark Products Market Strategic Shifts & Innovations
Formulation science is pivoting toward biomimetic approaches that replicate endogenous skin repair mechanisms, while distribution channels fragment between clinical endorsement pathways and algorithm-driven personalization platforms.
Microencapsulated retinoid alternatives are consolidating preventive efficacy positioning in pregnancy-safe segments. Formulators are adopting time-release delivery systems that stabilize bakuchiol and phyto-retinol compounds for dermal penetration comparable to conventional retinoids. Prenatal subscription services are accelerating adoption of these encapsulated formats, consolidating demand around brands with demonstrated tolerability data.
REACH microplastic restrictions are forcing reformulation of conventional gel and scrub delivery vehicles. The European Chemicals Agency's proposed ban on synthetic polymer microbeads in rinse-off cosmetics is extending to leave-on products, compelling substitution with biodegradable starch-based texturizers. Cream and butter formats are gaining share as formulators abandon polymer-dependent gel structures, compressing innovation timelines for texture-engineered products.
Algorithmic skin assessment tools are displacing static product recommendations in premium channels. Consumers are uploading pregnancy-week and skin-type data to receive customized oil-to-cream ratios and application protocols, bypassing generic shelf selection. This behavioral pivot is most visible in the United States, where direct-to-consumer brands are capturing maternity segment share through diagnostic-driven subscription models that institutionalize repurchase behavior before birth.
Anti Stretch Mark Products Market Segmentation
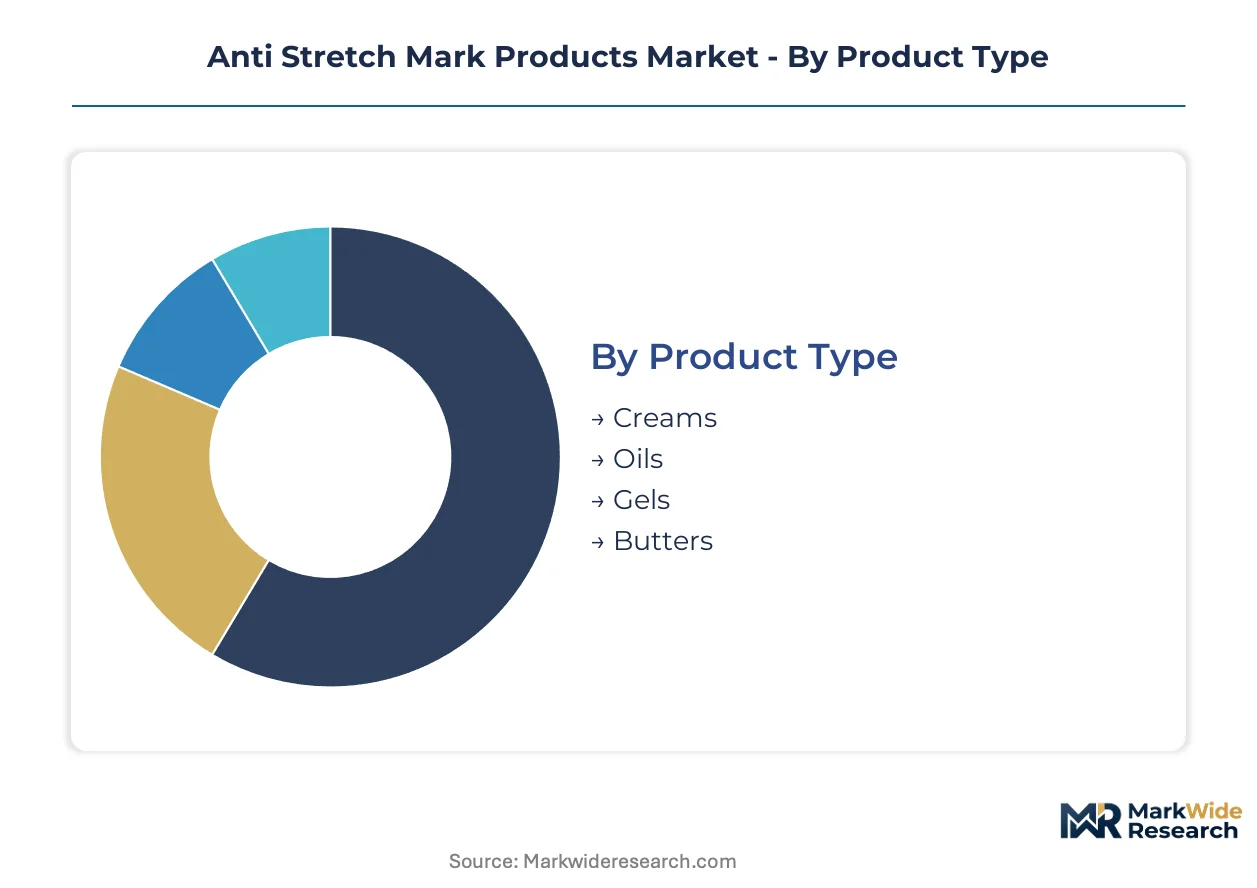
Segmentation in anti stretch mark products reflects divergent consumer rituals and physiological application needs. Formulators balance texture preferences against ingredient transparency demands while distribution channels fragment between clinical endorsement and algorithm-driven personalization platforms.
Product Type:
Texture standardization competes with ritual-driven customization across the moisturizing-to-treatment spectrum.
- Creams:Water-in-oil emulsions with medium viscosity dominate pharmacy and mass retail shelves. Familiar application rituals and accessible price positioning sustain volume leadership in United States maternity segments where prenatal clinic dispensing protocols favor recognizable formats.
- Oils:Lipid-dense formulations featuring marula, rosehip, or jojoba carrier systems command premium positioning through massage ritual associations. Direct-to-consumer channels in United States metropolitan markets capture margin pools via subscription bundling with pregnancy week-tracking applications.
- Gels:Hydroxyethylcellulose-thickened aqueous bases offer rapid absorption for consumers prioritizing convenience over sensorial experience.
- Butters:High-shea or cocoa butter solids target intensive overnight repair occasions with occlusive film-forming properties.
Leading the category by volume: Creams. Growing fastest: Oils.
Ingredient Type:
Clean-label certification costs stratify competitive positioning between legacy synthetic portfolios and emerging botanical alternatives.
- Natural:Plant-derived emollients and cold-pressed oils require ISO 16128 origin verification. EU Cosmetics Regulation (EC) No 1223/2009 safety assessment mandates elevate compliance investment, filtering out undercapitalized entrants from German and French pharmacy channels.
- Synthetic:Petrolatum-based occlusives and silicone elastomers deliver cost-efficient barrier function. India's CDSCO import quality standards recognize EU-certified synthetic formulations, opening access to maternity segments in Mumbai and Delhi metropolitan clusters.
- Herbal:Ayurvedic and traditional Chinese medicine extracts target ethnographic positioning in South Asian and East Asian diaspora communities.
- Chemical:Retinoid and peptide compounds face FDA cosmetic-drug boundary enforcement restricting therapeutic collagen repair language.
Natural ingredients command the steepest price premiums. Synthetic formulations retain the broadest geographic penetration.
Application Area:
Anatomical specificity drives formulation viscosity and packaging format decisions across body contour zones.
- Abdomen:High-surface-area applications during pregnancy require pump-dispensed formats for ergonomic reach. Prenatal subscription services in United States consolidate demand around abdomen-specific oil protocols with week-calibrated dispensing instructions.
- Thighs:Friction-prone zones demand rub-resistant film formers. Bodybuilder segments in Germany and United Kingdom drive corrective-use occasions for thigh-focused peptide formulations.
- Breasts:Sensitive tissue applications prioritize fragrance-free and nipple-safe certifications.
- Hips:Adolescent growth spurt and post-adolescent weight fluctuation occasions concentrate demand in mass-market channels.
Abdomen applications generate the highest per-user consumption volumes. Thigh-focused formulations are expanding most quickly among non-maternity corrective-use segments.
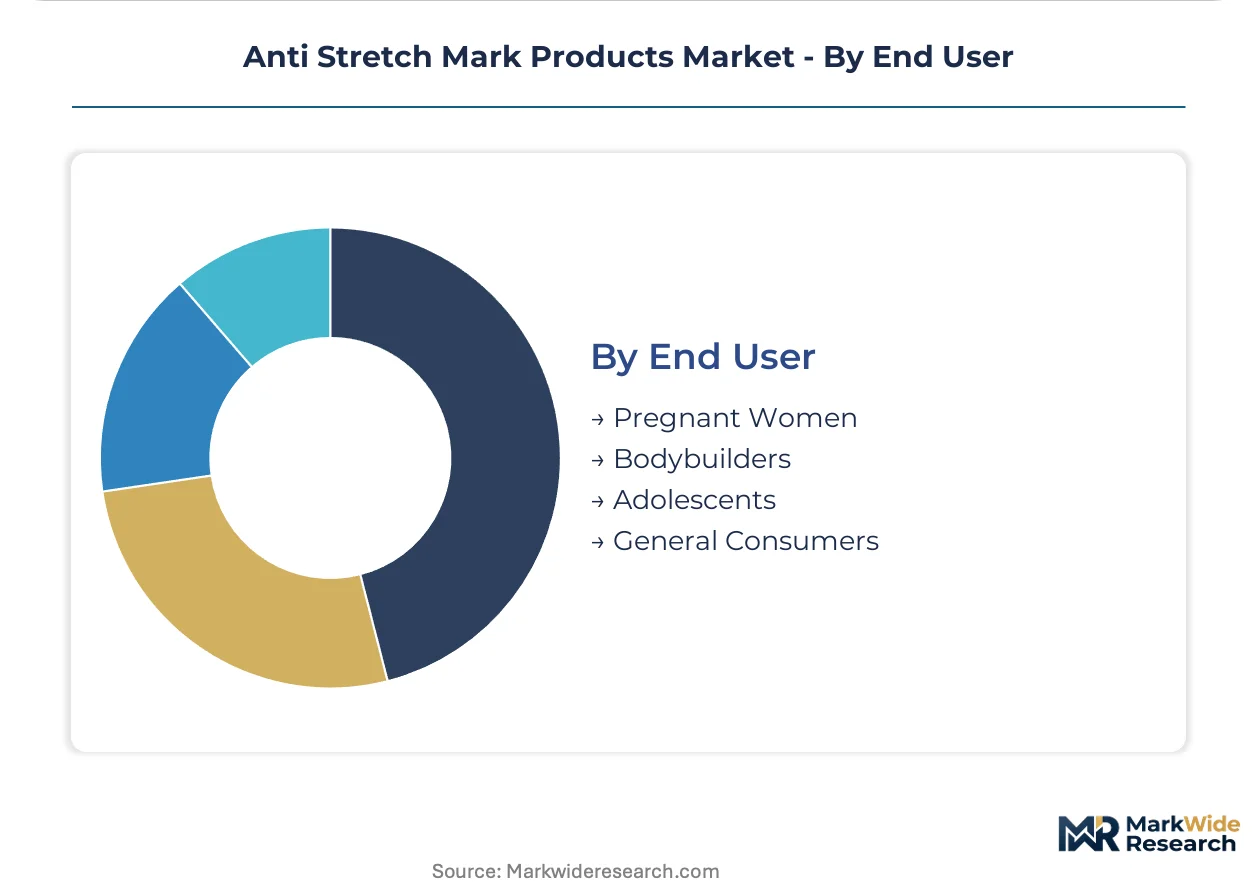
End User:
Demographic targeting fragments between institutional protocol integration and discretionary self-care purchasing.
- Pregnant Women:Protocol-driven dispensing through maternity clinics elevates efficacy claim requirements. United States prenatal care networks consolidate recommendations around dermatologist-endorsed brands with pregnancy safety databases.
- Bodybuilders:Rapid muscle hypertrophy creates dermal stress occasions distinct from pregnancy etiology. Specialty retail and gym-adjacent channels in United States and United Kingdom capture this performance-oriented segment.
- Adolescents:Growth spurt-related striae drive accessible price-tier demand in mass retail.
- General Consumers:Post-weight loss and aging-related elasticity concerns expand addressable market beyond acute physiological stress events.
Pregnant women anchor institutional channel volume. Bodybuilders represent the steepest expansion trajectory among non-traditional end-user categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pregnant women in the United States drive the highest per-capita consumption of anti stretch mark products, with institutional dispensing through prenatal clinics creating concentrated demand corridors. Regulatory divergence between jurisdictions shapes formulation strategies and channel access across major markets.
United States
FDA cosmetic-drug boundary enforcement restricts therapeutic collagen repair claims, forcing brands toward clinical trial investments for repositioning. Direct-to-consumer subscription models in metropolitan clusters like New York and Los Angeles capture maternity segment share through algorithmic skin assessment tools paired with personalized oil protocols.
Germany
EU Cosmetics Regulation (EC) No 1223/2009 safety assessment mandates elevate compliance costs, filtering undercapitalized entrants from pharmacy channels. The country's national pharmaceutical regulator maintains strict efficacy documentation requirements. Berlin and Munich anchor demand for peptide-engineered formulations targeting bodybuilder corrective-use segments.
France
Dermatologist endorsement density determines premium positioning in Paris and Lyon metropolitan pharmacy networks. ANSM oversight of cosmetic safety claims reinforces clinical validation requirements. Maternity skincare protocols professionalizing through prenatal clinic consolidation drive institutional demand for prescription-grade efficacy positioning.
India
CDSCO import quality standards and BIS frameworks govern EU-certified formulation recognition, opening access to 25 million annual births. Mumbai and Delhi metropolitan clusters concentrate demand for mass-market synthetic formulations, while Ayurvedic-positioned herbal extracts target ethnographic segments in diaspora communities.
United Kingdom
Post-Brexit regulatory alignment with EU Cosmetics Regulation maintains safety assessment continuity while creating divergence risk. London anchors premium oil subscription services integrating with telehealth prenatal platforms. Manchester and Birmingham mass retail channels sustain accessible price-tier demand for cream-format preventive applications.
Anti Stretch Mark Products Market Key Industry Players
United States and French producers anchor the premium dermatological tier; German and Swiss specialists hold mass-market pharmacy positioning. The vendor base stratifies across three tiers: multinational science-driven portfolios, regional natural-positioned brands, and private-label contract manufacturers. Two dominant competitive moves concentrate competitive dynamics: M&A activity targeting pediatrician endorsement networks, and vertical integration into shea butter and marula oil sourcing regions to secure botanical supply chains.
Within the science-driven multinational tier, L'Oréal S.A. and Beiersdorf AG occupy positions reflecting dermatological heritage and mass-market reach respectively. Mustela exemplifies the specialist archetype, competing through pediatrician endorsement density rather than advertising scale. These three anchors represent divergent strategic postures: one leverages clinical channel access, another sustains trusted equity in maternity segments, and the third concentrates perinatal formulation expertise.
| Leading Market Players |
|---|
| L'Oréal S.A. |
| Beiersdorf AG |
| Mustela |
| Bio Oil |
| Clarins |
| The Estée Lauder Companies Inc. |
| Himalaya Global Holdings Ltd. |
| Palmer's |
| Weleda AG |
| Others |
Cost & Logistics Intelligence
Pregnant women in prenatal care networks anchor pricing power for prescription-grade efficacy tiers, while cost-sensitive mass-market segments in India and Southeast Asia sustain economy positioning through synthetic formulation sourcing. This buyer concentration bifurcation rewards dermatological science capabilities in premium channels and penalizes undercapitalized natural-positioned brands facing shea butter and marula oil price volatility.
Pricing Analysis
Volume leadership in cream formats sustains accessible price positioning across United States pharmacy and mass retail channels, while oil subscriptions capture margin pools through premium natural ingredient positioning and ritual-driven consumption patterns. Three-tier pricing structure across premium peptide-engineered, standard botanical, and economy synthetic levels differentiates based on certification grade and clinical validation depth. Pricing pressure stems from climate-induced harvest variability in West African sourcing regions compressing margins for natural-positioned portfolios. Mass-market synthetic formulations in India demonstrate highest price sensitivity, while United States maternity segments show lowest sensitivity to premium positioning backed by dermatologist endorsement.
Supply Chain Analysis
Cosmetic chemist talent scarcity in France and Germany constrains formulation pipeline velocity as senior professionals approach retirement without adequate replacement pipelines. Manufacturing concentration centers on France for dermatological science capabilities, Germany for pharmacy-channel production, and India for cost-efficient synthetic formulation export. Raw material dependencies draw from West African shea butter harvests, Southern African marula oil regions, and Southeast Asian botanical extract suppliers. Single-source vulnerability in climate-exposed agricultural regions elevates supply risk for natural-positioned brands dependent on fixed botanical contracts. Distribution runs through prenatal clinic dispensing protocols in the United States, pharmacy networks in Germany and France, and mass retail channels in India.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The anti stretch mark products market is transitioning from basic emollient formulations toward biomimetic peptide engineering and microencapsulated retinoid alternatives, displacing legacy petrolatum-based portfolios that lack clinically validated elasticity improvement claims.
For Market Incumbents: Deepen pediatrician and dermatologist endorsement density to defend against prescription tretinoin substitution threats in corrective-use segments, while securing captive supply of shea butter and marula oil through backward integration into West African and Southern African sourcing regions. Prioritize ISO 16128 natural origin certification investment to accelerate clean-label product launches against bureaucratic verification timelines. For New Entrants and Emerging Players: Algorithmic skin assessment tools paired with personalized formulation protocols offer technology-first entry into United States direct-to-consumer maternity segments underserved by static product recommendations. Target telehealth prenatal platform integration as the most penetrable channel, bypassing traditional retail access barriers through subscription bundling with pregnancy week-tracking applications. For Investors and Strategic Acquirers: The window for entry favors specialist brands with demonstrated pediatrician endorsement networks and perinatal formulation expertise over mass-market synthetic portfolios facing margin compression. Monitor biometric skin elasticity monitoring convergence with wearable dermal sensors as the inflection indicator for outcome-linked subscription model viability over static product sales.| Strategic Initiative | Industry Significance |
|---|---|
| Pediatrician Endorsement Network Acquisition | Institutional demand pull from prenatal clinic dispensing protocols concentrates around endorsed brands in United States and French markets. |
| Backward Integration into Shea Butter Sourcing | Climate-induced harvest variability in West African regions rewards captive supply control for natural-positioned portfolios. |
| Telehealth Prenatal Platform Partnership | Virtual maternity care providers in United States metropolitan clusters enable direct-to-patient dispensing bypassing retail. |
| Microencapsulated Retinoid Alternative Launch | Pregnancy-safe bakuchiol and phyto-retinol formats capture preventive efficacy positioning from legacy emollient formulations. |
| ISO 16128 Certification Fast-Track | Bureaucratic verification timelines for clean-label claims delay launches by 8-14 months, rewarding pre-certified portfolios. |
Research Approach
Document review covered EU Cosmetics Regulation (EC) No 1223/2009 safety assessment filings, FDA cosmetic labeling guidance, and CDSCO import quality standards, complemented by interviews with dermatology brand managers, prenatal clinic procurement leads, cosmetic chemists, and pharmacy channel buyers. Secondary validation drew from customs trade data, retail audit databases, and clinical formulation journals. Bottom-up demand modeling across end-user segments triangulated against top-down market sizing from regulatory filings and industry association reports.
Cross-referencing historical elasticity improvement claim trends with expert panel input on peptide engineering adoption shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product type, ingredient pathway, application area, and end-user demographic. CAGRs were derived from growth rate convergence analysis across these segments. Industry-specific forecast inputs incorporated prenatal care network consolidation rates and telehealth platform expansion trajectories.
Forecast precision tightens around the base case; tail outcomes carry wider variance under regulatory divergence scenarios between EU safety assessment mandates and cost-sensitive synthetic formulation dominance in emerging markets. Forecasts reflect assumptions on maternity skincare protocol professionalization and climate stability in botanical sourcing regions. Material deviation in shea butter harvest yields or FDA cosmetic-drug boundary enforcement stringency warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Anti-Acne Facial Serum Market
Beauty & Personal Care
Over-Night Hair Treatment Products Market
Beauty & Personal Care
Colombia Beauty and Personal Care Products Market
Beauty & Personal Care
Global Personal Care Emollients Market
Beauty & Personal Care
Online Beauty and Personal Care Products Market
Beauty & Personal Care
Germany Cosmetics for Pregnancy Market
Beauty & Personal Care
Liquid Soap Market
Beauty & Personal Care
Depilatories Market
Beauty & Personal Care
Facial Make-Up Market
Beauty & Personal Care
Netherlands Sustainable Personal Care Market
Beauty & Personal Care
Japan Beauty Fridges Market
Beauty & Personal Care
Facial Epilator Market
Beauty & Personal Care
Japan Beauty and Personal Care Products Market
Beauty & Personal Care
UV Nail Gel Market
Beauty & Personal Care
Personal Care Contract Manufacturing Market
Beauty & Personal Care
Mass Beauty & Personal Care Products Market