
 Nail Polish Remover Market | 2026-2036
Nail Polish Remover Market Size, Share, and Industry Trends Forecast 2026-2036
Nail Polish Remover Market Outlook
Asset-light licensing and contract manufacturing is rewriting competitive dynamics in nail polish remover production. OPI leverages its salon-centric brand heritage to sustain premium positioning in professional channels. Coty Inc. anchors mass-market volume through broad retail partnerships across drugstore and grocery networks. Ella+Mila differentiates via clean-beauty certification, competing for shelf space in specialty beauty retailers focused on ingredient transparency.
Nail polish remover comprises solvent-based or solvent-free formulations designed to dissolve nitrocellulose film-formers and synthetic resins in cured lacquer, typically employing acetone, ethyl acetate, or methyl ethyl ketone at concentrations between 30% and 100% depending on product class. Its primary commercial purpose centers on enabling rapid, complete removal of decorative nail coatings without excessive mechanical abrasion or cuticle damage. Acetone formulations dominate professional salon procurement due to faster lacquer breakdown, while non-acetone and organic variants capture growing home-user preference amid ingredient-conscious purchasing. Pump and wipe packaging formats expand fastest in travel and convenience segments, though standard bottles retain the largest absolute volume share across distribution channels.
FDA oversight of cosmetic labeling and ingredient safety under the Federal Food, Drug, and Cosmetic Act shapes product claims and warning requirements for acetone-based removers sold in the United States. The EU REACH framework and associated CLP classification restrict volatile organic compound thresholds and mandate hazard communication for professional-grade solvent concentrations. California's Proposition 65 adds state-level disclosure obligations for reproductive toxicants present in certain remover chemistries. Stakeholders must monitor evolving state-level chemical restriction bills and clean-beauty certification standards to anticipate reformulation costs and channel access requirements.
Market Dynamics
Professional salon channel expansion is compressing at-home consumption share while EU REACH solvent restrictions force simultaneous reformulation across acetone and non-acetone product lines.
Growth Catalysts
- REACH-Driven Reformulation:EU ECHA restrictions on volatile organic compound thresholds push manufacturers toward ethyl acetate and bio-derived solvent alternatives. Professional-grade removers now require updated CLP hazard classifications.
- Salon Service Diversification:Nail care establishments in the United States extend service menus beyond basic manicures to include gel removal, dip powder dissolution, and nail art correction. Each service type demands specialized remover chemistries.
- Ingredient Transparency Certification:Clean-beauty standards from EWG Verified and Leaping Bunny create shelf-space access in specialty retailers. Reformulated products capture premium positioning through documented exclusion lists.
Market Restraints
- Acetone Feedstock Volatility:Propylene-derived acetone pricing fluctuates with petrochemical refinery output cycles. Remover manufacturers face margin compression when solvent costs spike without corresponding retail price elasticity.
- Single-Source Solvent Dependence:Industrial-grade ethyl acetate production concentrates in China and India. Geographic concentration creates supply vulnerability during regional logistics disruptions or export quota adjustments.
- Technical Performance Trade-offs:Non-acetone formulations dissolve nitrocellulose film-formers at slower rates than acetone equivalents. Professional technicians resist switching where service throughput determines revenue per appointment.
Strategic Opportunities
- Travel-Format Packaging Innovation:Pump-dispense and pre-saturated wipe formats address TSA liquid restrictions and gym-bag convenience needs. These SKUs command per-ounce premiums over standard bottles.
- Professional-Grade Bio-Solvent Convergence:Methyl soyate and terpene-based actives combined with enzymatic additives offer petroleum-free alternatives. Early adopters in California and New York metro salons test performance parity claims.
- State-Level Chemical Disclosure Mandates:California Proposition 65 enforcement creates competitive differentiation for brands with pre-existing reproductive toxicant screening. Compliant products secure preferential placement in state-regulated retail chains.
Industry Challenges
- Cosmetic Chemist Talent Scarcity:Formulation expertise bridging solvent chemistry and clean-beauty marketing claims remains concentrated among veteran professionals. Recruitment lags behind reformulation pipeline demands.
- Dual Certification Timelines:Simultaneous pursuit of USDA BioPreferred and EU Ecolabel approvals extends product launch cycles. Testing protocols for biodegradability and aquatic toxicity add six to twelve months to commercialization schedules.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nail Polish Remover Market |
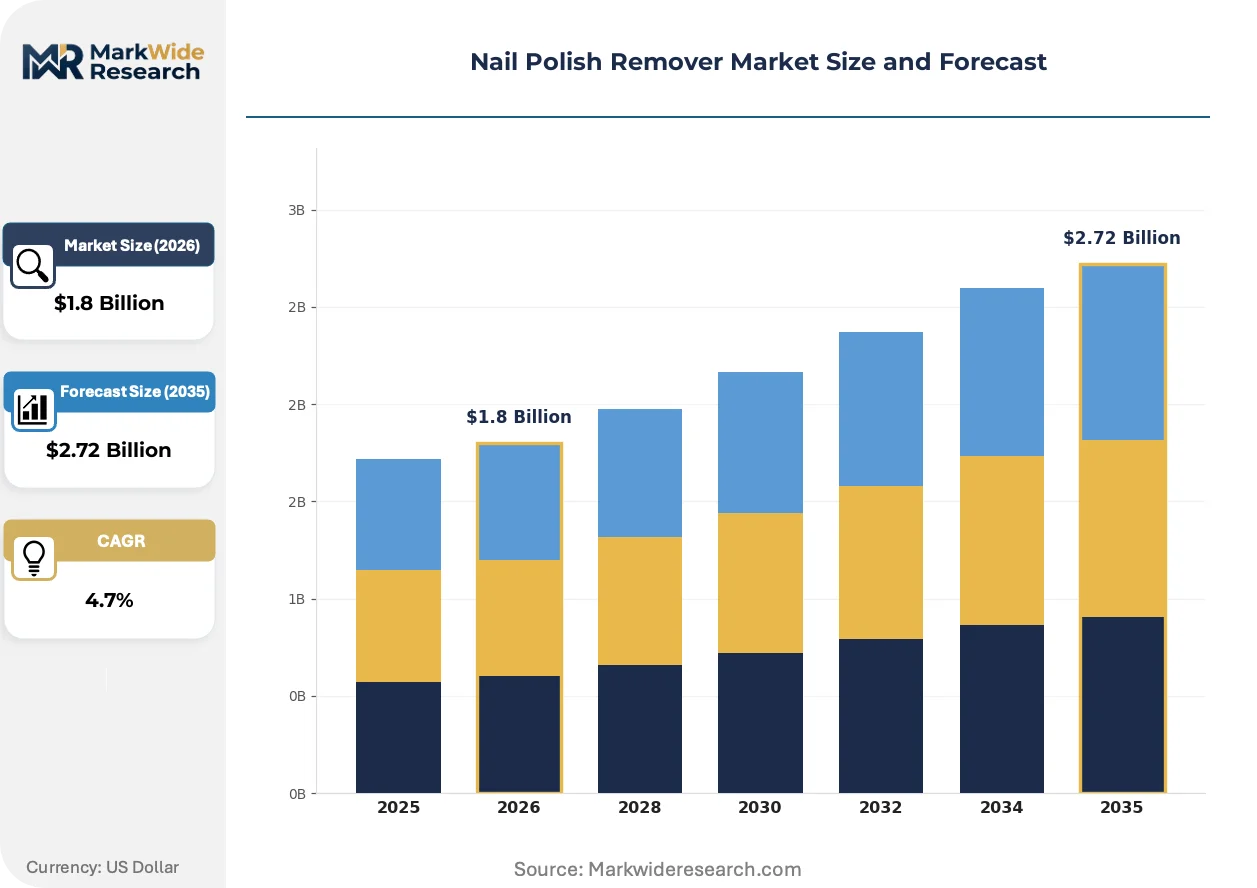
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acetone, Non-Acetone, Organic, Gel Packaging Type: Bottle, Wipe, Pump, Sachet End User: Professional Salons, Home Users, Retail Chains, E-commerce Distribution Channel: Online, Supermarkets, Beauty Supply Stores, Pharmacies |
| Companies Covered | L'Oréal, OPI, Procter & Gamble, Onyx Professional, Essie, Revlon, Sally Hansen, Ella+Mila, Coty Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nail Polish Remover Market Strategic Shifts
Water-based micellar technologies and enzymatic dissolution systems are fragmenting traditional solvent-dominated formulation paradigms while regulatory pressure accelerates ingredient disclosure granularity.
Micellar water removers employing surfactant-encapsulated oil phases are collapsing the performance gap with conventional acetone formulations. Home users in Germany and France adopt these systems for daily polish change routines without cuticle dehydration concerns. The technology compresses market share for standard non-acetone variants by delivering comparable removal speed with reduced surface damage.
EU REACH Annex XVII amendments restrict per- and polyfluoroalkyl substance residues in cosmetic-grade solvents. Remover manufacturers serving European professional channels must certify supply chain absence of PFAS contaminants. German salon distributors now require batch-level testing documentation before purchase order acceptance.
Subscription-based replenishment models displace conventional retail restocking for heavy-use professional accounts. United States salon chains consolidate procurement through direct-to-business platforms offering volume-tiered pricing and automated reorder triggers. This channel shift concentrates buyer power among multi-location operators while marginalizing independent distributor margins.
Nail Polish Remover Market Segmentation
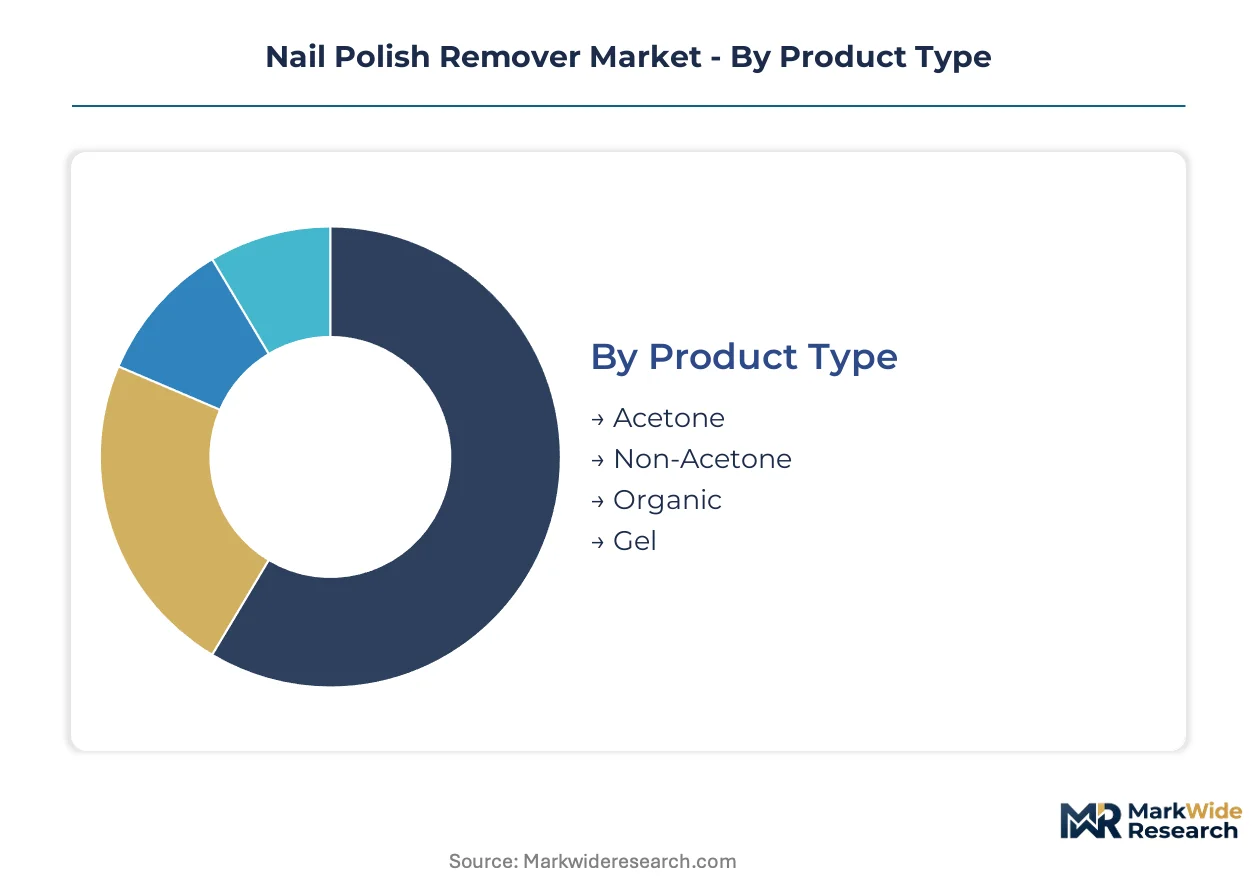
Segmentation in nail polish remover markets reveals how solvent chemistry, packaging convenience, and channel access fragment purchasing behavior across professional and consumer domains. Manufacturers align formulation portfolios and distribution investments to capture distinct usage occasions and regulatory risk profiles.
Product Type:
Mature solvent technologies coexist with emerging bio-derived alternatives as professional throughput demands and ingredient-conscious purchasing diverge.
- Acetone:This petroleum-derived ketone dissolves nitrocellulose film-formers at the fastest rate among commercial solvents. Professional salons in the United States specify acetone formulations for gel polish removal where appointment duration directly impacts technician revenue.
- Non-Acetone:Ethyl acetate and methyl ethyl ketone blends reduce cuticle dehydration while extending removal time. Home users in Germany and France select these variants for frequent polish changes without salon-grade ventilation systems.
- Organic:Plant-derived terpenes and methyl soyate formulations target clean-beauty certification requirements. These SKUs command shelf space in specialty retailers with documented exclusion lists.
- Gel:Higher solvent concentrations and extended soak protocols address cross-linked polymer structures in cured gel coatings. Nail care establishments specify dedicated gel removers to prevent service delays.
Acetone handles the majority of throughput; organic formulations are gaining share fastest as EWG Verified certification expands retail access.
Packaging Type:
Volume concentration in standard bottles contrasts with margin expansion in convenience formats serving mobile and travel use cases.
- Bottle:Standard cylindrical containers with screw-cap closures retain the largest absolute volume across all distribution channels. These formats optimize cost per ounce for high-frequency professional procurement.
- Wipe:Pre-saturated towelettes eliminate spill risk and TSA liquid restrictions for air travelers. Gym-bag and overnight-kit applications drive per-unit premium capture.
- Pump:Metered-dispense mechanisms reduce product waste in salon backbar environments. United States nail chains specify pump formats for inventory control and technician workflow efficiency.
- Sachet:Single-use foil pouches serve sample distribution and hospitality amenity programs. These units minimize counterfeit risk in emerging market retail.
Bottle formats dominate absolute volume; pump packaging climbs the fastest as salon chains consolidate procurement through direct-to-business platforms.
End User:
Professional service expansion is compressing at-home consumption share while e-commerce intermediaries reshape retail access patterns.
- Professional Salons:Licensed nail care establishments purchase concentrated formulations in institutional volumes. Service menu diversification into gel removal and dip powder dissolution drives specialized chemistry procurement.
- Home Users:Individual consumers select lower-concentration variants for occasional use with limited ventilation. Ingredient transparency claims influence purchase decisions in specialty beauty retail.
- Retail Chains:Multi-location drugstore and grocery operators negotiate national distribution agreements for mass-market SKUs. These buyers prioritize shelf-stable formulations with extended turnover periods.
- E-commerce:Direct-to-consumer platforms and marketplace aggregators capture replenishment purchasing for heavy-use accounts. Subscription models displace conventional restocking for professional buyers.
Professional salons absorb the largest volume; e-commerce shows the steepest expansion trajectory as automated reorder triggers concentrate buyer power.
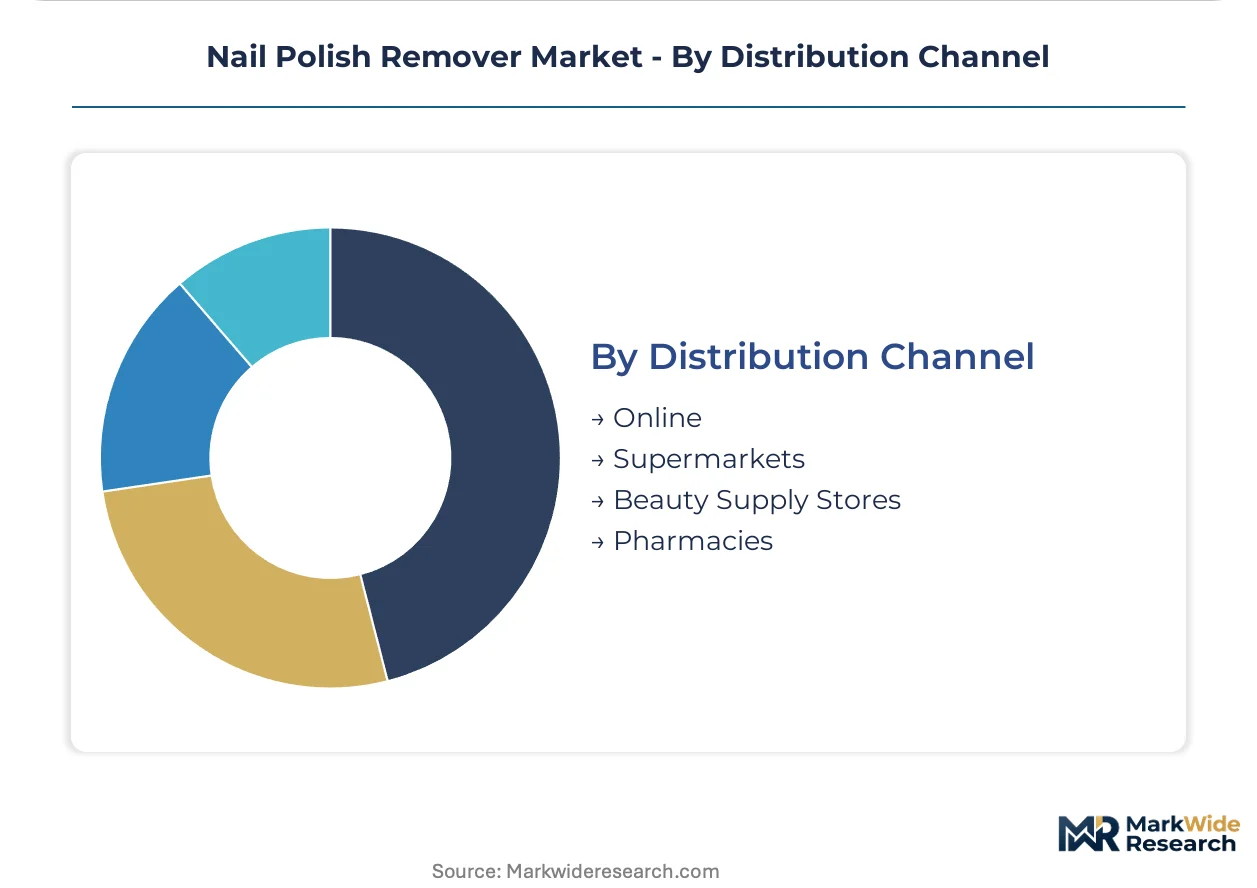
Distribution Channel:
Channel selection determines regulatory exposure and margin structure as state-level chemical disclosure mandates proliferate.
- Online:Brand-owned websites and third-party marketplaces bypass physical retail overhead while capturing detailed consumer preference data. California Proposition 65 compliance documentation becomes a conversion factor.
- Supermarkets:Mass-market grocery operators prioritize high-velocity SKUs with broad demographic appeal. These channels favor acetone formulations with established household recognition.
- Beauty Supply Stores:Specialty retailers serving licensed professionals stock concentrated salon-grade chemistries. Staff training requirements support technical product differentiation.
- Pharmacies:Drugstore chains integrate nail care into broader beauty and personal care assortments. These outlets emphasize dermatologist-tested claims for sensitive-skin positioning.
Beauty supply stores move the most professional-grade volume; online channels expand most quickly as direct-to-business platforms capture salon chain procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Professional nail care establishments concentrate procurement power in the United States, while ingredient-conscious home users fragment demand across Germany and France. Regulatory divergence between FDA cosmetic oversight and EU REACH solvent restrictions forces parallel formulation strategies.
United States
Licensed salon chains in New York and Los Angeles drive institutional-volume procurement of acetone-based removers for gel polish services. FDA labeling requirements under the Federal Food, Drug, and Cosmetic Act mandate hazard warnings for professional-grade solvent concentrations. California's Proposition 65 enforcement creates competitive differentiation for brands with pre-existing reproductive toxicant screening in Los Angeles-anchored retail networks.
Germany
Beauty retailers in Berlin and Munich stock micellar water removers for daily home-use polish changes without ventilation concerns. ECHA REACH Annex XVII amendments restrict volatile organic compound thresholds in cosmetic-grade solvents. Frankfurt-based salon distributors now require batch-level PFAS testing documentation before purchase order acceptance.
France
Parisian nail care establishments specify ethyl acetate blends for clients with sensitive cuticles seeking frequent color rotation. ANSM cosmetic safety guidelines align with EU CLP classification mandates for professional-grade hazard communication. Lyon specialty retailers capture clean-beauty positioning through EWG Verified certification requirements.
China
Industrial-grade ethyl acetate production concentrates in Jiangsu and Shandong provinces for downstream remover formulation. SAMR cosmetic registration rules govern ingredient disclosure for imported nail care products. Shanghai beauty supply distributors consolidate procurement for multi-location salon chains seeking automated reorder platforms.
United Kingdom
London nail technicians prioritize acetone formulations for appointment throughput in high-rent commercial districts. UK REACH retains EU-derived solvent restrictions post-Brexit with independent enforcement by the Health and Safety Executive. Manchester-based e-commerce platforms capture subscription-based replenishment for heavy-use professional accounts.
Nail Polish Remover Market Competitive Environment
Channel-controlling players compete with product-specialist players across fragmented shelf-space negotiations. The vendor base spans multinational beauty conglomerates with retail network leverage and independent clean-beauty specialists with certification-driven positioning. Three archetypes dominate: salon-heritage brands with professional credibility, mass-market volume suppliers with grocery and drugstore penetration, and clean-formulation specialists with specialty retail access. Competitive moves center on direct-to-business platform deployment for salon chain procurement and dual-certification pursuit for clean-beauty label access.
Within the salon-heritage tier, OPI occupies a position exemplifying professional-channel credibility, while Coty Inc. anchors mass-market volume through broad retail partnerships. Ella+Mila represents the clean-beauty specialist archetype, competing for shelf space in specialty retailers focused on ingredient transparency.
| Leading Market Players |
|---|
| L'Oréal |
| OPI |
| Procter & Gamble |
| Onyx Professional |
| Essie |
| Revlon |
| Sally Hansen |
| Ella+Mila |
| Coty Inc. |
| Others |
Value Chain & Pricing Dynamics
Jiangsu and Shandong provinces anchor industrial-grade ethyl acetate production capacity, and their refinery output cycles transmit directly into acetone-based remover pricing power for downstream formulators across Asia-Pacific and North American markets.
Pricing Analysis
Certification level creates the primary spread between professional salon-grade and mass-market retail SKUs, with EWG Verified and Leaping Bunny standards commanding shelf-space premiums in specialty beauty channels. Three-tier pricing structure across premium clean-beauty, standard professional, and economy household levels reflects ingredient transparency investments and ventilation-grade solvent concentrations. Pricing pressure stems from propylene feedstock volatility in acetone production, compressing margins for non-integrated formulators. Home users in drugstore channels exhibit highest price sensitivity, while United States salon chains prioritize throughput performance over per-unit cost.
Supply Chain Analysis
Upstream petrochemical feedstocks from propylene and ethanol derivatives concentrate manufacturing input costs in China, India, and United States Gulf Coast clusters. Acetone, ethyl acetate, and methyl ethyl ketone supply hinges on refinery co-product availability and regional export quota regimes. Single-source solvent vulnerability intensifies during logistics disruptions from Shanghai port congestion or Indian Ocean routing constraints. Distribution runs through beauty supply store networks for professional channels, with direct-to-business platforms capturing automated reorder volume from multi-location salon operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Formulation expertise bridging solvent chemistry and clean-beauty certification requirements remains concentrated among veteran cosmetic chemists, creating a talent bottleneck that constrains reformulation velocity for mid-tier manufacturers.
For Market Incumbents: Insulate professional channel relationships by embedding pump-dispense inventory systems directly into United States salon chain backbar operations. Pursue backward integration into bio-derived solvent supply through methyl soyate partnerships with agricultural processors. Defensive patent filings around enzymatic dissolution technologies will block emerging clean-beauty entrants from achieving performance parity claims. For New Entrants and Emerging Players: Establish a beachhead in travel-format packaging innovation where TSA compliance and gym-bag convenience command per-ounce premiums absent entrenched brand loyalty. Target micellar water remover segments in Germany and France where daily polish change routines favor gentle surfactant systems over acetone alternatives. Go-to-market positioning through specialty retailers with pre-existing EWG Verified shelf access accelerates trial conversion. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors clean-formulation specialists with dual-certification pipelines already navigating USDA BioPreferred and EU Ecolabel timelines. Long-term viability rests on brands capturing professional-grade performance claims without petroleum-derived actives. Monitor California Proposition 65 enforcement intensity as the inflection signal for reproductive toxicant screening becoming table stakes in regulated retail chains.| Strategic Initiative | Industry Significance |
|---|---|
| Bio-Solvent R&D Partnership | Methyl soyate and terpene collaborations with agricultural processors secure petroleum-free feedstock alternatives. |
| Direct-to-Business Platform Deployment | Automated reorder triggers for United States salon chains concentrate procurement power and displace distributor margins. |
| Dual Certification Investment | Simultaneous USDA BioPreferred and EU Ecolabel pursuit extends launch timelines but locks in specialty retail access. |
| Travel-Format SKU Expansion | Pump-dispense and pre-saturated wipe formats capture per-unit premiums in TSA-compliant convenience segments. |
| PFAS-Free Supply Chain Certification | Batch-level testing documentation satisfies Frankfurt distributor requirements under REACH Annex XVII amendments. |
Study Parameters
The analysis maps solvent-based, non-acetone, organic, and gel remover sub-sectors, each validated through cosmetic chemists, salon procurement managers, beauty supply distributors, and specialty retail category buyers. Primary fieldwork combined formulation laboratory interviews with secondary validation from FDA cosmetic labeling guidance, ECHA REACH Annex XVII amendments, customs trade data for ethyl acetate flows, and SEC filings from publicly traded beauty conglomerates. Bottom-up SKU-level volume estimates triangulated against top-down channel revenue assessments.
Assumptions held fixed include current EU REACH volatile organic compound thresholds and United States FDA cosmetic oversight frameworks, while solvent feedstock pricing and clean-beauty certification adoption rates varied across sensitivity scenarios. Segmentation dimensions modeled encompass solvent chemistry, packaging format, end-user type, and distribution channel. CAGRs derived from weighted average growth across professional salon service expansion and at-home consumption compression. Industry-specific inputs incorporated nail care service menu diversification rates and micellar technology adoption curves.
Macroeconomic conditions sit as an overlay; deviation in petrochemical refinery output cycles or trans-Pacific logistics costs would shift the trajectory. Forecasts reflect documented assumptions about regulatory stability and certification timeline completion. Cross-checking against EWG Verified product database growth rates and United States salon establishment counts is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Beauty & Personal Care
Russia Beauty and Personal Care Market
Beauty & Personal Care
Personal Care Wipes Market
Beauty & Personal Care
Asia-Pacific Perms and Relaxants Market
Beauty & Personal Care
Luxury Bath and Body Products Market
Beauty & Personal Care
Middle East and Africa Hair Styling Products Market
Beauty & Personal Care
Middle East Herbal Shampoo Market
Beauty & Personal Care
DIY Haircut Kits Market
Beauty & Personal Care
Beauty and Personal Care Surfactants Market
Beauty & Personal Care
Intensive Conditioner Market
Beauty & Personal Care
Over-Night Hair Treatment Products Market
Beauty & Personal Care
Emea Beauty Devices Market
Beauty & Personal Care
Wrinkle Release Spray Market
Beauty & Personal Care
Colombia Hair Care Market
Beauty & Personal Care
Japan Beauty Fridges Market
Beauty & Personal Care
Bangladesh Hair Oil Market
Beauty & Personal Care
Global Personal Care Emollients Market